
 Semiconductor Inspection System Market | 2026-2036
Semiconductor Inspection System Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Inspection System Market Intelligence
The EU Green Deal's focus on circular economy principles and electronic product passports is restructuring supply chain verification requirements for semiconductor manufacturers. KLA Corporation leverages its extensive portfolio of process control solutions to address these evolving inspection needs. Applied Materials differentiates through its integrated inspection and metrology platforms for advanced nodes. Lasertec Corporation specializes in actinic pattern inspection systems for EUV lithography masks.
Semiconductor inspection systems are automated platforms designed to detect and classify defects on silicon wafers, photomasks, and packaged chips. These systems utilize technologies like optical and electron beam imaging to identify anomalies as small as a few nanometers, ensuring manufacturing process integrity. Wafer inspection tools represent the largest product segment, driven by high-volume production at leading-edge foundries. Electron beam inspection technology is gaining share over traditional optical methods for its superior resolution in advanced failure analysis applications.
Equipment performance and interoperability are governed by SEMI standards, which are adopted globally by fabs and equipment suppliers. Additionally, export controls on advanced semiconductor technology, enforced by entities like the US Department of Commerce, and China's GB standards for electronics influence market access. Vendor selection increasingly hinges on a system's ability to integrate artificial intelligence for faster, more accurate defect classification.
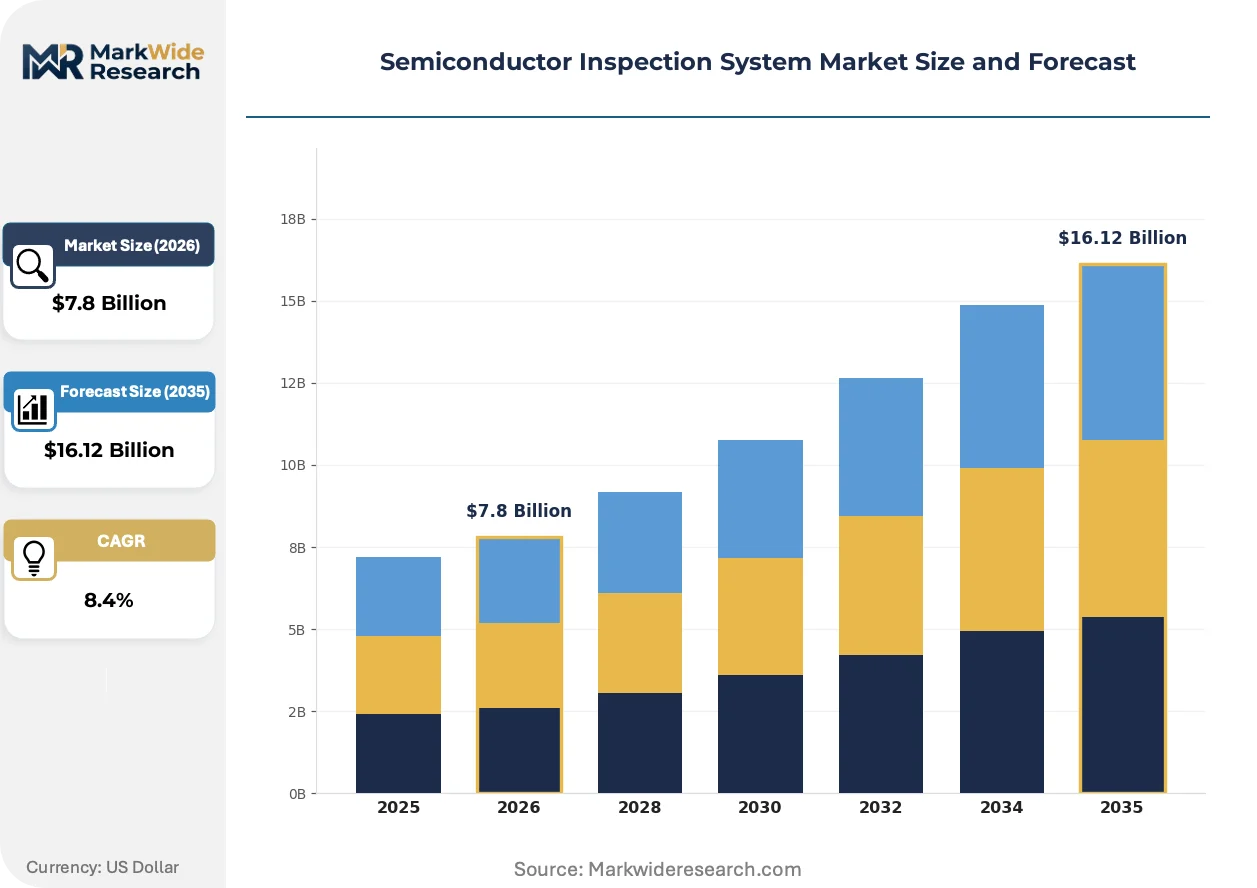
Market Dynamics
The transition to complex three-dimensional transistor architectures, such as Gate-All-Around (GAA), is the central force shaping the semiconductor inspection system market. This architectural shift demands unprecedented inspection precision to ensure yield and reliability for advanced logic and memory devices.
Growth Catalysts
- Advanced Packaging:The shift to 2.5D and 3D IC packaging for high-performance computing requires new inspection methods to verify through-silicon vias (TSVs) and micro-bumps, driving demand for specialized systems.
- Automotive Electronics:The proliferation of ADAS and in-vehicle infotainment systems, which rely on high-reliability semiconductors, is expanding the need for stringent wafer and die-level inspection to meet automotive safety standards.
- National Semiconductor Initiatives:Government-led programs like the US CHIPS Act and similar initiatives in Europe are stimulating domestic fab construction, creating a direct demand pipeline for new inspection equipment installations.
Market Restraints
- High Capital Expenditure:The immense cost of leading-edge inspection tools, particularly EUV mask and e-beam systems, presents a significant barrier to entry for smaller foundries and limits capacity expansion for even large players.
- Throughput vs. Resolution Trade-off:High-resolution e-beam inspection systems offer superior defect detection but suffer from slower throughput compared to optical methods, creating a persistent bottleneck in high-volume manufacturing.
- Export Controls:Restrictions on the sale of advanced semiconductor equipment to certain countries, enforced by entities like the US Department of Commerce, limit the total addressable market and create geopolitical complexities.
Strategic Opportunities
- AI and Machine Learning Integration:Embedding AI algorithms into inspection platforms for real-time, automated defect classification offers a significant opportunity to reduce manual review and accelerate yield learning cycles for fabs.
- Silicon Photonics Inspection:The growing silicon photonics market for data centers requires specialized inspection to detect defects in optical components like waveguides and modulators, opening a new application frontier.
- EU Electronic Product Passports:The EU Green Deal's mandate for product passports will create demand for inspection systems that can provide detailed traceability and material composition data, linking manufacturing data to circular economy goals.
Industry Challenges
- Specialized Skill Scarcity:A shortage of engineers and data scientists skilled in both semiconductor physics and advanced machine learning hinders the development and effective operation of next-generation, AI-driven inspection systems.
- Data Interoperability:Integrating data from diverse inspection and metrology tools into a unified factory-wide yield management system is a major challenge, often hindered by proprietary data formats and a lack of SEMI standard adherence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Inspection System Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Defect Review Systems, Wafer Inspection Tools, Mask Inspection Equipment, Metrology Systems, Electrical Testers Technology: Optical Inspection, Electron Beam Inspection, X-Ray Inspection, Acoustic Microscopy, Atomic Force Microscopy Application: Yield Management, Failure Analysis, Process Control, Quality Assurance, Packaging Inspection End User: Foundries, Chip Designers, OSAT Providers, Semiconductor fabs, Equipment Suppliers |
| Companies Covered | Hitachi High-Technologies, Onto Innovation, KLA Corporation, ViSCO Technologies, Lasertec Corporation, Applied Materials, Rudolph Technologies, Camtek, ASML Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Inspection System Market Strategic Shifts & Innovations
The market's evolution is defined by the fusion of advanced imaging hardware with sophisticated data analytics. This convergence is moving inspection from simple defect detection toward predictive process control, fundamentally altering how fabs manage manufacturing yield and quality.
Electron beam inspection provides unparalleled resolution for identifying nanometer-scale defects invisible to optical systems. Leading-edge foundries are adopting this technology for critical process steps in GAA and 3D NAND fabrication. This adoption is integrating e-beam data with optical inspection results, creating a hybrid metrology strategy that balances speed with precision for comprehensive process monitoring.
China’s GB standards for electronics and its dual carbon goals are influencing manufacturing practices within its domestic semiconductor industry. These national standards compel manufacturers to adopt inspection processes that not only ensure product quality but also monitor energy and material efficiency. The domestic equipment market is responding by developing systems tailored to these specific compliance and sustainability reporting requirements.
Foundries are shifting from one-time equipment purchases toward partnerships focused on yield-as-a-service. This model deemphasizes the standalone tool in favor of a continuous data stream and analytical support from the equipment vendor. This trend is most prominent in Taiwan and South Korea, where leading fabs use vendor expertise to accelerate ramp-up for new process nodes.
Semiconductor Inspection System Market Segmentation
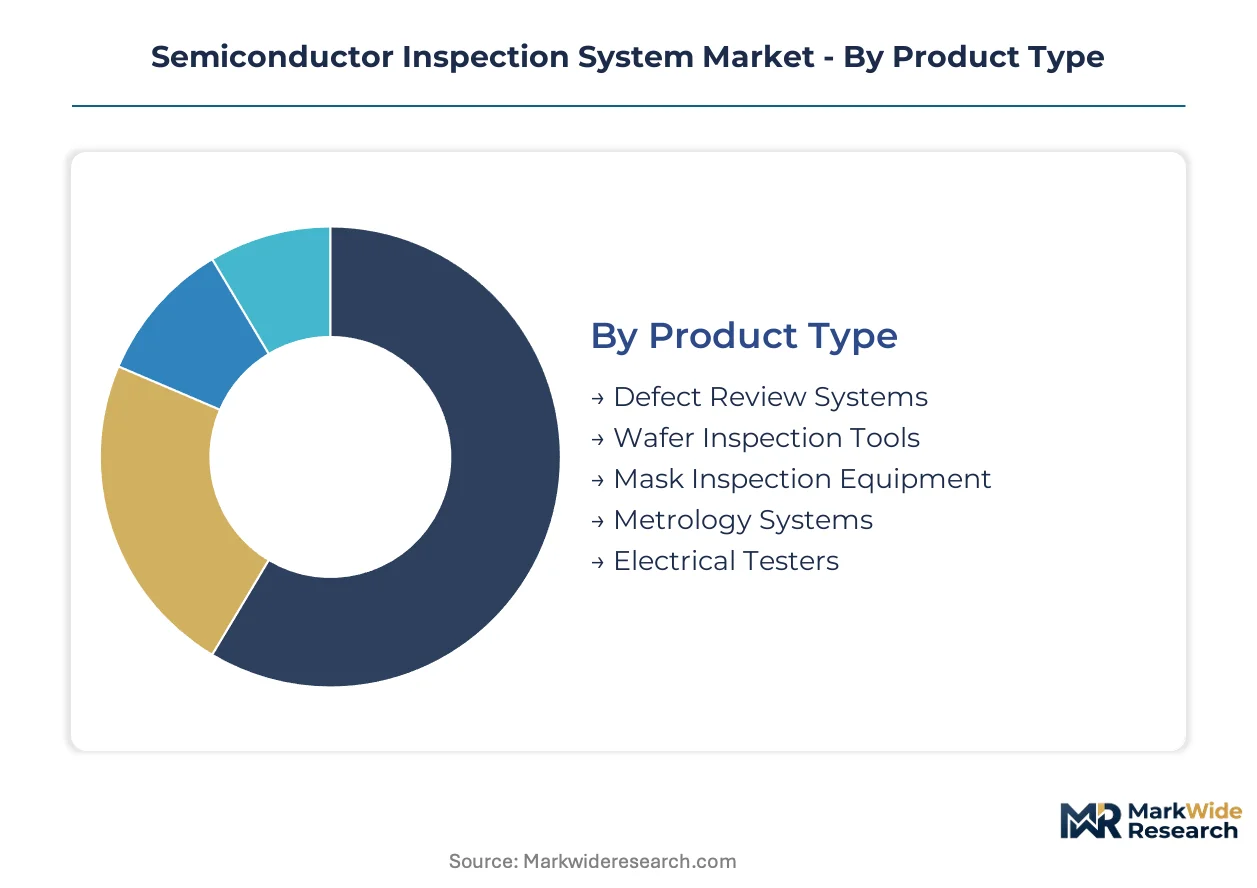
Understanding the market for semiconductor inspection systems requires detailed segmentation, reflecting the diverse technologies and applications driving device manufacturing. This granular breakdown clarifies where investment is concentrating and how technological advancements are reshaping demand across various industry participants. Each segment highlights specific operational needs and strategic priorities for semiconductor production.
Product Type:
The capital-intensive nature of semiconductor manufacturing dictates significant upfront investment in specialized inspection tools across product types.
- Defect Review Systems:These systems analyze defects identified by other inspection tools, providing detailed characterization for process improvement. Demand is strong in advanced foundries for rapid fault isolation.
- Wafer Inspection Tools:Automated platforms scan silicon wafers for defects during various fabrication stages, ensuring quality before further processing. High-volume production at leading-edge foundries in Taiwan and South Korea drives demand.
- Mask Inspection Equipment:Critical for verifying the integrity of photomasks used in lithography, these systems detect minute pattern errors. The transition to EUV lithography demands highly precise mask inspection, particularly from major mask shops.
- Metrology Systems:These tools measure critical dimensions and material properties on wafers and masks, ensuring process parameters are within specifications. They are essential for process control in advanced node development.
- Electrical Testers:These systems perform functional tests on finished chips or wafer dies, identifying electrical failures. They are crucial for final product quality assurance before packaging.
Most installed capacity flows through Wafer Inspection Tools. Expansion is steepest in Mask Inspection Equipment.
Technology:
Technological choices in inspection systems hinge on the trade-off between resolution, speed, and the specific defect types targeted.
- Optical Inspection:These systems use visible or UV light to detect defects on wafer surfaces, offering high throughput for large-area scanning. Foundries in the United States utilize optical methods for initial defect screening.
- Electron Beam Inspection:Utilizing electron beams for imaging, this technology provides unparalleled resolution for nanometer-scale defect detection and characterization. Advanced logic and memory fabs in South Korea adopt e-beam for critical process steps.
- X-Ray Inspection:This technology allows for non-destructive inspection of internal structures within packaged chips or wafers, detecting subsurface defects. It is used for advanced packaging inspection and failure analysis.
- Acoustic Microscopy:Acoustic waves are used to detect delamination, voids, and cracks within packaged devices, particularly in 3D ICs and advanced packaging. This method is critical for reliability testing.
- Atomic Force Microscopy:AFM provides ultra-high resolution 3D topographical imaging of wafer surfaces, enabling detailed characterization of nanoscale defects and surface roughness. It supports research and development in new materials.
The adoption trajectory is steepest for Electron Beam Inspection, while Optical Inspection maintains foundational importance.
Application:
The application of inspection systems directly impacts manufacturing yield, product reliability, and overall operational efficiency.
- Yield Management:This application integrates inspection data to identify root causes of yield loss and implement corrective actions, optimizing manufacturing processes. Foundries prioritize yield management to maximize output from complex processes.
- Failure Analysis:Inspection systems are crucial for investigating the physical causes of device malfunctions, guiding design improvements and process adjustments. Specialized labs and chip designers extensively use these tools.
- Process Control:Real-time monitoring and adjustment of manufacturing parameters based on inspection data ensure consistent product quality. This application is vital for maintaining tight tolerances in advanced semiconductor fabrication.
- Quality Assurance:Ensuring that semiconductor products meet specified performance and reliability standards before shipment falls under this application. It is a critical final step in the manufacturing workflow.
- Packaging Inspection:This application focuses on detecting defects in 2.5D and 3D IC packaging, including micro-bumps, TSVs, and interconnections. The growth of advanced packaging drives demand for these specialized inspection methods.
Yield Management remains the primary driver of inspection demand, with significant gains observed in Packaging Inspection.
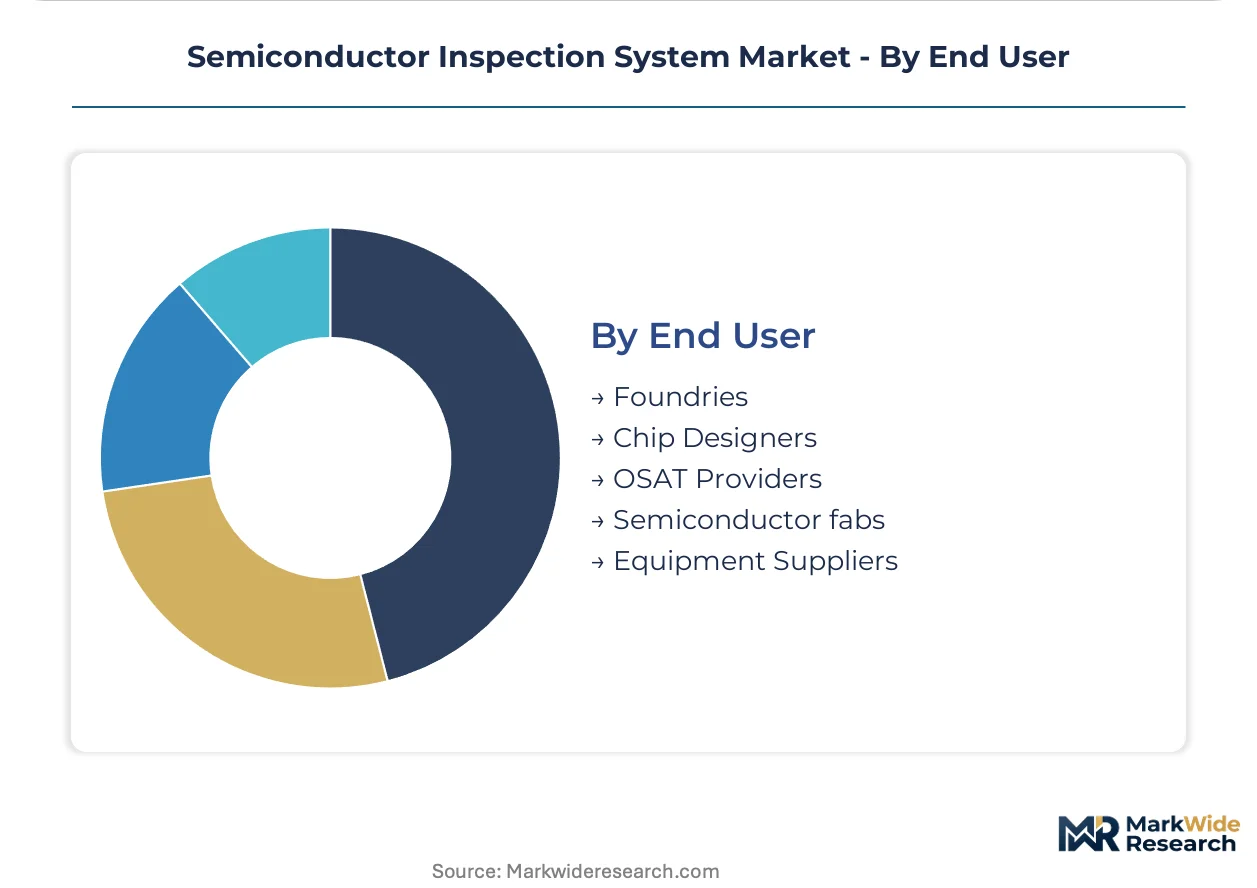
End User:
Different end-user segments leverage inspection systems based on their specific roles within the semiconductor supply chain.
- Foundries:These companies fabricate integrated circuits for other firms, requiring extensive inspection capabilities to ensure high yields and process consistency. Major foundries in Taiwan and the United States are primary purchasers.
- Chip Designers:Firms that design integrated circuits use inspection systems for early prototyping, failure analysis, and validating manufacturing processes. They rely on detailed defect data for design refinement.
- OSAT Providers:Outsourced Semiconductor Assembly and Test providers handle packaging and final testing of chips, requiring inspection tools for quality control at these stages. The shift to advanced packaging increases their inspection needs.
- Semiconductor fabs:Integrated device manufacturers (IDMs) that design, fabricate, and package their own chips require comprehensive inspection solutions across their entire production cycle. These fabs operate complex, vertically integrated facilities.
- Equipment Suppliers:Companies that manufacture and sell semiconductor equipment, including inspection systems, often use these tools internally for R&D and quality control of their own products. They drive innovation in inspection technology.
The largest procurement volumes originate from Foundries, with OSAT Providers showing accelerated equipment purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Talent concentration in advanced semiconductor manufacturing centers anchors demand for sophisticated inspection systems. These regions, characterized by dense fabrication ecosystems and continuous innovation cycles, drive the market's technological evolution. Government initiatives and private investments further solidify these areas as critical hubs for inspection equipment procurement.
Taiwan
High-volume production at leading-edge foundries, particularly those involved in Gate-All-Around (GAA) architectures, drives significant demand for inspection systems. National semiconductor initiatives support capacity expansion and advanced process development across the island. The Hsinchu Science Park remains a central hub, fostering collaboration between equipment vendors and major foundries for rapid technology adoption.
South Korea
Advanced logic and memory fabs in South Korea extensively adopt electron beam inspection for critical process steps, ensuring nanometer-scale defect detection. Government support for semiconductor R&D and manufacturing strengthens the domestic industry's inspection capabilities. Major manufacturing clusters in Gyeonggi Province, home to Samsung and SK Hynix, continuously invest in next-generation inspection tools.
United States
Domestic fab construction, spurred by the US CHIPS Act, creates a direct demand pipeline for new inspection equipment installations. Export controls on advanced semiconductor technology, enforced by the US Department of Commerce, influence market access and technology development. Key clusters like Silicon Valley and the growing Arizona semiconductor corridor attract significant investment in advanced inspection and metrology.
China
China's GB standards for electronics and its dual carbon goals are influencing manufacturing practices within its domestic semiconductor industry. National initiatives to bolster self-sufficiency in semiconductor production are stimulating local equipment development and procurement. Major manufacturing zones in the Yangtze River Delta and Pearl River Delta are expanding their inspection capabilities to meet stringent quality and sustainability requirements.
Germany
The EU Green Deal's focus on circular economy principles is restructuring supply chain verification requirements for semiconductor manufacturers in Germany. National semiconductor initiatives within Europe are stimulating domestic fab construction and R&D investment. The "Silicon Saxony" cluster in Dresden represents a key European hub for semiconductor manufacturing, driving demand for specialized inspection equipment for automotive and industrial applications.
Semiconductor Inspection System Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the semiconductor inspection system market. This market structure features a mix of highly specialized equipment manufacturers and broader technology conglomerates. Strategic archetypes include dedicated process control specialists, integrated metrology platform providers, and niche players focusing on specific inspection technologies.
Specialists in process control and advanced metrology, such as KLA Corporation, leverage extensive portfolios to address evolving inspection needs for advanced nodes. Applied Materials differentiates through its integrated inspection and metrology platforms, offering comprehensive solutions for fabrication facilities. Lasertec Corporation exemplifies a niche leader, specializing in actinic pattern inspection systems crucial for EUV lithography masks.
| Leading Market Players |
|---|
| Hitachi High-Technologies |
| Onto Innovation |
| KLA Corporation |
| ViSCO Technologies |
| Lasertec Corporation |
| Applied Materials |
| Rudolph Technologies |
| Camtek |
| ASML Holding |
| Others |
Cost & Logistics Intelligence
Silicon wafer pricing fluctuations directly influence the cost structure of semiconductor inspection systems. This cost variability cascades through the supply chain, impacting equipment manufacturers' pricing strategies for advanced tools.
Pricing Analysis
Semiconductor inspection system pricing often reflects a bundled hardware and software approach. The dominant pricing structure is contract-based long-term off-take, especially for leading-edge fabs. Customization level for specific process nodes and after-sales service agreements drive significant price differentiation. Pricing softness reflects intense competition from Chinese domestic suppliers and global market saturation for mature nodes. Smaller foundries and emerging players exhibit higher price sensitivity compared to major integrated device manufacturers.
Supply Chain Analysis
Dual-sourcing requirements for critical components mitigate risks in the semiconductor inspection system supply chain. The supply chain for advanced inspection systems concentrates in Taiwan, South Korea, and the United States. Key dependencies include specialized optical components, high-purity rare gases, and precision mechanical parts. Geopolitical tensions and export controls enforced by the US Department of Commerce present a significant structural risk. Distribution runs primarily through direct sales channels and long-term strategic partnerships with major foundries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The semiconductor inspection system market functions as a stable compounder, driven by the relentless demand for advanced process nodes. Continuous innovation in transistor architectures necessitates ongoing investment in sophisticated inspection capabilities.
For Market Incumbents: Anticipate the increasing complexity of GAA and 3D IC architectures by investing heavily in advanced R&D for next-generation e-beam and actinic inspection. Deepen vertical integration into critical component manufacturing to secure supply chains against geopolitical risks. Counter emerging competition from domestic Chinese equipment suppliers through superior technology and global service networks. Expand capacity in key fabrication centers like Taiwan and the United States, leveraging government initiatives such as the US CHIPS Act. For New Entrants and Emerging Players: Begin with specialized niche applications, such as silicon photonics inspection for data centers or advanced packaging verification. Target the growing demand for AI-driven defect classification software, offering platform-agnostic solutions. The OSAT providers segment offers a penetrable entry point due to accelerated equipment purchases. Partner with smaller foundries or R&D labs in Europe to establish initial market credibility and build a reference customer base. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized technology offers a clear competitive advantage in advanced nodes. This market offers long-term viability over a 5-10 year window, driven by continuous semiconductor scaling. Seek out mid-sized firms specializing in electron beam inspection or advanced AI/ML defect classification algorithms. The integration rate of AI for faster defect classification across major foundries will serve as a key inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Defect Classification Integration | Accelerates yield learning cycles for advanced logic devices. |
| EUV Mask Inspection System Development | Ensures pattern fidelity for next-generation lithography processes. |
| Advanced Packaging Inspection Solutions | Verifies integrity of micro-bumps and TSVs in 2.5D/3D ICs. |
| Global Service Network Expansion | Provides essential support to geographically dispersed fabrication facilities. |
| Compliance with EU Green Deal Standards | Addresses evolving supply chain verification requirements for European markets. |
Research Approach
Multiple input streams — primary interviews, industry reports, and company financials — were reconciled for this analysis. Primary research involved discussions with CTOs, procurement leads at major foundries, and R&D managers from equipment suppliers. Secondary data sources included SEC filings, academic publications on semiconductor physics, and trade association reports from SEMI. A triangulated approach combined bottom-up market sizing with top-down validation.
Data-stream reconciliation established the analytical framework for market projections. Segmentation dimensions modeled included product type, technology, application, and end-user, alongside regional adoption patterns. Compound Annual Growth Rates were derived from historical trends and projected technological advancements across the modeling period. Key forecast inputs included new fab construction announcements and semiconductor capital expenditure cycles.
Several conditions sit outside the modeled scope, including unforeseen geopolitical conflicts and rapid shifts in global economic policy. Forecasts reflect assumptions regarding technological roadmaps and stable supply chain dynamics. Deviation in major export control policies or material input costs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Temperature Detection Screen Market
Detection and Regulation Devices
Hydrogen Detection Transmitters Market
Detection and Regulation Devices
Global Gas Leak Detectors Market
Detection and Regulation Devices
Constant Current Regulator Market
Detection and Regulation Devices
Betavoltaic Device Market
Detection and Regulation Devices
Microwave Leakage Detector Market
Detection and Regulation Devices
EMEA Frequency Control and Timing Devices Market
Detection and Regulation Devices
Global Portable Gas Detector Market
Detection and Regulation Devices
Global Label-Free Detection Market
Detection and Regulation Devices
Photoionization Detectors Market
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
Middle East and Africa Trace Detection Market
Detection and Regulation Devices
Europe Gas Detectors Market
Detection and Regulation Devices
Global Gas Sensors Market
Detection and Regulation Devices
Semiconductor Leak Detectors Market
Detection and Regulation Devices
Temperature Modulation Devices Market