
 Radar Detector Market | 2026-2036
Radar Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Radar Detector Market Analysis
Modular bundling of GPS integration with laser detection is repositioning buyer choice toward all-in-one configurations. Escort Inc. leverages its brand strength in premium standalone units to sustain loyalty among repeat purchasers. Uniden America Corporation anchors its position through manufacturing scale across mid-tier wireless models. Cobra Electronics competes aggressively on price to occupy volume channels in online retail.
A radar detector is an electronic device that senses radio waves emitted by police speed-measurement equipment, typically operating across X, K, and Ka frequency bands with sensitivity thresholds measured in decibels. Its primary commercial purpose is alerting drivers to active speed enforcement, thereby reducing citation risk. Portable devices command the largest installed base due to low switching costs and universal vehicle compatibility, while integrated systems capture the highest margin pools through factory-fit installations. Bluetooth connectivity represents the fastest-expanding technology segment as smartphone pairing enables crowd-sourced alert networks.
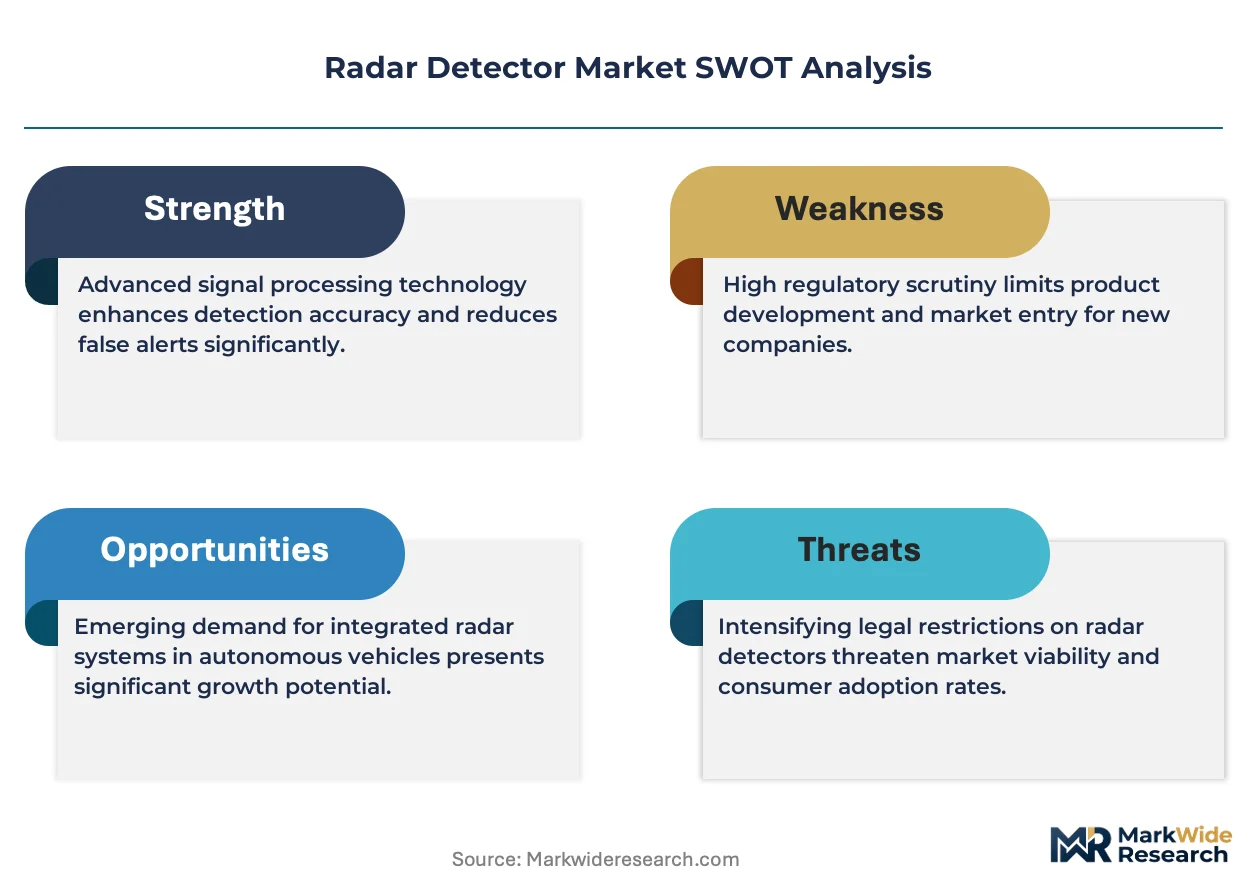
The FCC regulates radar detector emissions under Part 15 rules, limiting spurious radiated signals and mandating certification for lawful marketing in the United States. FDA oversight extends to laser-based eye safety standards that constrain detector design parameters. State-level prohibitions in Virginia and Washington, D.C. fragment addressable demand and complicate interstate distribution logistics. Stakeholders must monitor evolving municipal ordinances and spectrum reallocation debates to anticipate compliance burdens and geographic market-access constraints.
Market Dynamics
Bluetooth connectivity is consolidating aftermarket radar detectors into smartphone-integrated alert networks, compressing the addressable market for standalone hardware while expanding recurring service revenue pools for connected-device vendors.
Growth Catalysts
- Ka-band proliferation:Police departments across the United States are migrating speed-enforcement equipment toward Ka-band frequencies, compelling detector owners toward higher-sensitivity replacement cycles.
- FCC Part 15 certification:Streamlined equipment authorization procedures for unintentional radiators reduce time-to-market for new detector models, accelerating product refresh rates.
- Interstate corridor density:Variable speed-limit enforcement patterns along U.S. highway networks sustain replacement demand among long-haul commercial drivers and recreational vehicle operators.
Market Restraints
- State-level prohibitions:Virginia and Washington, D.C. maintain outright bans on detector possession and use, fragmenting distribution logistics and complicating interstate e-commerce fulfillment.
- Laser detection saturation:LIDAR-based speed enforcement achieves near-instantaneous target acquisition, rendering traditional radar detection insufficient and forcing costly dual-mode hardware upgrades.
- Semiconductor input volatility:RF front-end components and GaAs MMICs face supply concentration among specialty foundries, exposing detector manufacturers to input cost swings.
Strategic Opportunities
- Connected-vehicle integration:CAN bus interfacing and OBD-II data fusion enable detectors to access vehicle telemetry, opening premium subscription tiers for predictive enforcement mapping.
- Cloud-based alert networks:Real-time crowdsourced data aggregation from mobile applications creates network-effect moats that hardware-only competitors cannot replicate.
- Commercial fleet penetration:Logistics operators with self-insured vehicle pools represent an underpenetrated buyer segment seeking citation-risk reduction at enterprise scale.
Industry Challenges
- RF engineering talent scarcity:Specialist microwave circuit designers with millimeter-wave experience command premium compensation, constraining in-house R&D expansion.
- Certification timeline compression:FCC and FDA laser-safety testing protocols require 4-6 month validation cycles that lag behind consumer electronics launch velocities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radar Detector Market |
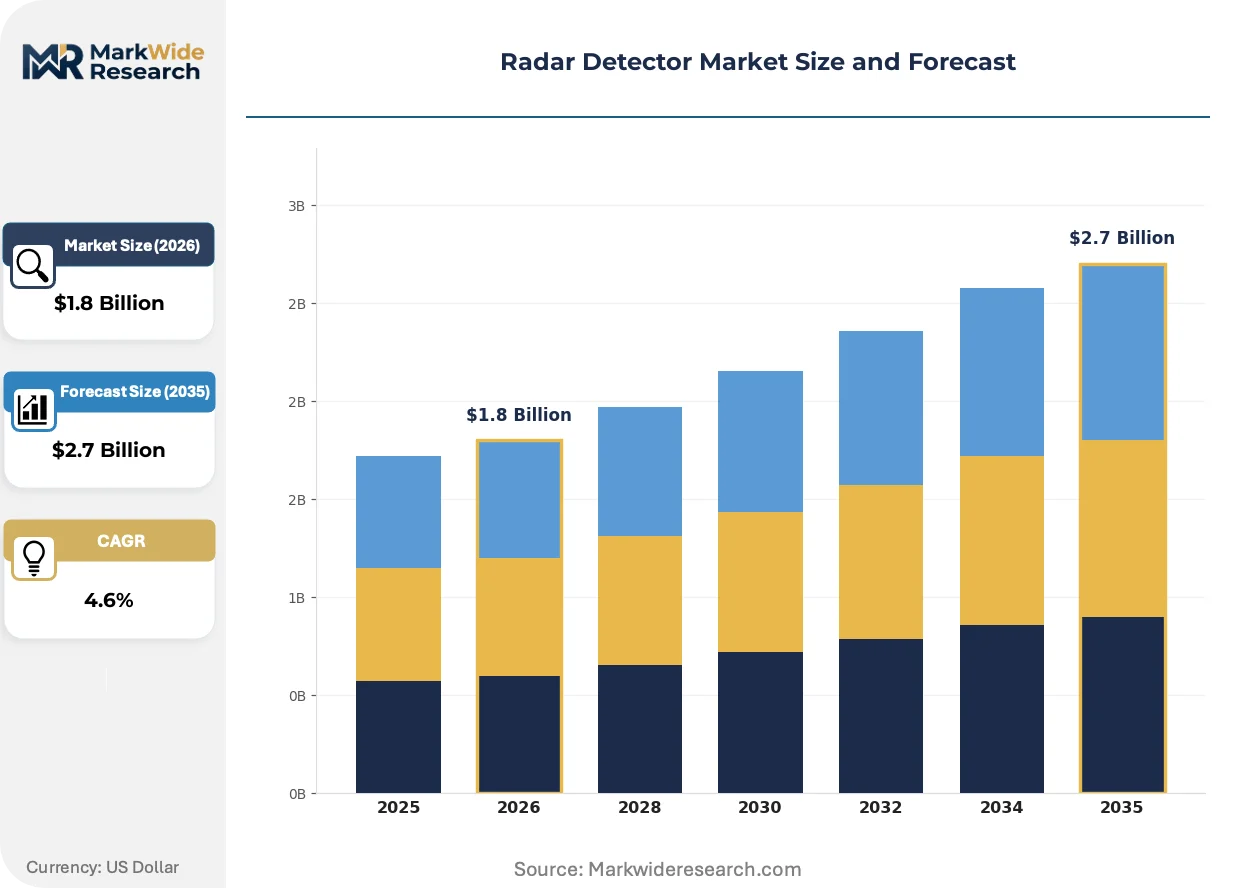
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Units, Integrated Systems, Portable Devices, Wireless Models Technology: Laser Detection, Radar Band, GPS Integration, Bluetooth Connectivity End User: Personal Vehicles, Commercial Trucks, Law Enforcement, Automotive Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Automotive Dealers, Direct Sales |
| Companies Covered | Escort Inc., Uniden America Corporation, Cobra Electronics, Beltronics, Cedar Electronics, Whistler Group, Radenso, K40 Electronics, Rocky Mountain Radar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radar Detector Market Emerging Trajectories
Sensor fusion and edge computing are redefining detector architecture, shifting competitive advantage from raw sensitivity specifications toward algorithmic false-alert suppression and contextual awareness.
Artificial intelligence-driven signal processing is consolidating false-alert filtering capabilities into neural-network classifiers that distinguish police radar from collision-avoidance systems and automatic door openers. Automotive enthusiasts and professional drivers are adopting these models at premium price points. The technology is consolidating the mid-tier market by obsoleting rule-based filtering hardware that cannot adapt to emerging radar signatures.
REACH substance restrictions in the European Union are constraining lead-based solder and specific flame retardants in printed circuit board assemblies, forcing detector manufacturers toward halogen-free laminate substrates. Industrial consequence includes elevated bill-of-materials costs and supplier qualification burdens. Premium-tier manufacturers with existing automotive-grade supply chains are absorbing these transitions more rapidly than price-focused competitors.
Fleet procurement departments are unbundling hardware acquisition from data-service subscriptions, treating detectors as connected-asset nodes rather than discrete electronics. Commercial vehicle leasing companies and long-haul trucking operators are displacing individual driver purchases with centralized equipment provisioning. This pattern is most visible across the United States interstate corridor network where citation costs scale with fleet size.
Radar Detector Market Segmentation
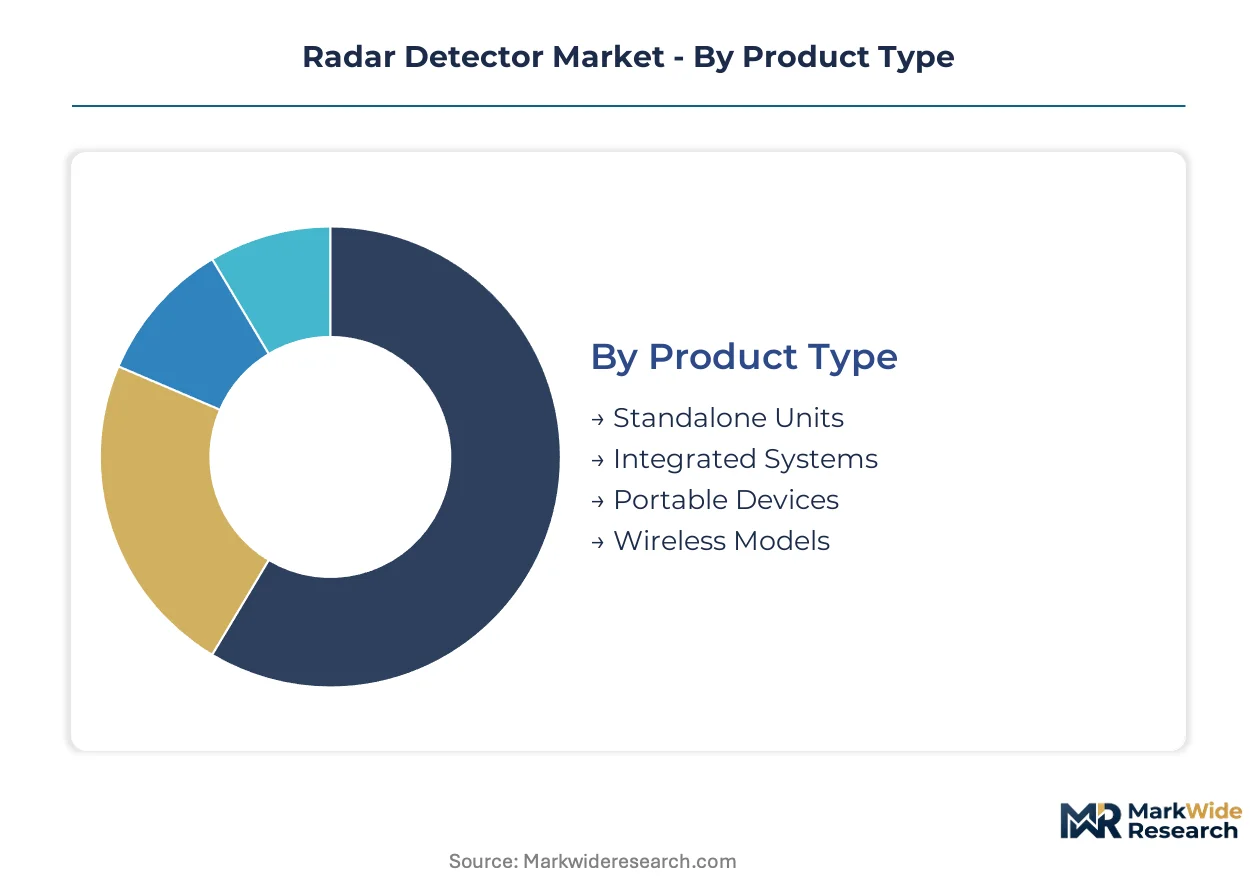
Radar detector segmentation reveals how hardware form factors, sensing technologies, and procurement channels align with distinct risk-tolerance profiles and enforcement exposure patterns. Manufacturers configure product portfolios across these dimensions to match replacement cycles, margin targets, and regulatory constraints.
Product Type:
Customization intensity varies from plug-and-play portability to permanent vehicle integration, with cost tiers and switching friction defining buyer commitment levels.
- Standalone Units:Self-contained devices mount via suction cup or visor clip, operating without vehicle system interfacing. Demand concentrates among automotive enthusiasts in the United States seeking high-sensitivity hardware with minimal installation complexity.
- Integrated Systems:Factory-fit or professionally installed units embed into dashboard architecture and vehicle electrical systems. Commercial fleet operators across long-haul interstate corridors favor these configurations for reduced theft risk and cleaner cabin aesthetics.
- Portable Devices:Battery-powered or cigarette-lighter adapters enable transfer between vehicles. Personal vehicle owners value universal compatibility and low switching costs.
- Wireless Models:Cord-free designs eliminate power cable routing through cabin trim. Urban drivers in jurisdictions with detector prohibitions prioritize discreet storage and rapid removal.
Most installed capacity flows through Portable Devices. Expansion is steepest in Integrated Systems.
Technology:
Performance differentiation tracks sensitivity thresholds, false-alert suppression algorithms, and network connectivity capabilities that reshape hardware refresh incentives.
- Laser Detection:Photodiode arrays sense 904nm LIDAR pulses used in speed enforcement, requiring line-of-sight orientation. Law enforcement agencies in Virginia and Washington, D.C. deploy LIDAR exclusively, constraining detector effectiveness where radar detection remains prohibited.
- Radar Band:Superheterodyne receivers scan X, K, and Ka frequencies with sensitivity measured in decibels. Ka-band sensitivity commands premium pricing as police departments migrate enforcement equipment toward higher frequencies.
- GPS Integration:Location databases flag fixed enforcement cameras and speed-limit transitions. European buyers under REACH compliance burdens favor these models for reduced false-alert fatigue.
- Bluetooth Connectivity:Smartphone pairing enables real-time alert crowdsourcing and firmware updates. This segment is expanding most quickly as subscription revenue models displace pure hardware economics.
Volume leadership sits with Radar Band hardware. Steepest expansion trajectory belongs to Bluetooth Connectivity.
End User:
Procurement authority and citation risk exposure separate individual drivers from institutional fleet managers with enterprise-scale risk mitigation budgets.
- Personal Vehicles:Individual owners purchase through retail channels with price sensitivity varying by driving frequency and prior citation history. Interstate corridor commuters in the United States sustain replacement demand.
- Commercial Trucks:Self-insured logistics operators and leasing companies provision equipment centrally. Long-haul operators across variable speed-limit jurisdictions absorb hardware costs against scaled citation exposure.
- Law Enforcement:Agencies procure counter-detection equipment and training systems to maintain enforcement effectiveness. Procurement runs through municipal and state government contracting channels.
- Automotive Enthusiasts:Hobbyist drivers demand premium specifications and early access to emerging detection capabilities. This segment tolerates highest price points for AI-driven false-alert suppression.
Personal Vehicles account for dominant installation base. Commercial Trucks are gaining share fastest as fleet digitization accelerates.
Distribution Channel:
Channel selection determines margin capture, customer education requirements, and regulatory compliance burden for interstate fulfillment.
- Online Retail:E-commerce platforms enable price comparison and customer review aggregation. Virginia and Washington, D.C. prohibitions complicate fulfillment logistics for national retailers.
- Specialty Stores:Dedicated automotive electronics retailers provide installation services and technical consultation. Enthusiast buyers seeking sensitivity benchmarking favor these channels.
- Automotive Dealers:New and used vehicle sales points offer factory-fit integration as add-on financing. Dealer networks capture highest-margin integrated system placements.
- Direct Sales:Manufacturer-owned channels control brand presentation and subscription service attachment. Premium-tier vendors deploy direct models to capture recurring revenue streams.
Transaction volume concentrates in Online Retail. Margin expansion is steepest in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radar detector manufacturing originated in the United States during the 1970s as microwave electronics firms adapted military surplus technology for civilian speed-enforcement detection. Interstate highway expansion and variable speed-limit enforcement patterns established North American demand patterns that later diffused to European and Asia-Pacific markets.
United States
Long-haul commercial drivers and recreational vehicle operators sustain replacement demand across interstate corridors with variable enforcement patterns. FCC Part 15 rules govern spurious radiated emissions and mandate certification timelines that shape product launch velocities. Ohio and Michigan host specialized RF engineering clusters where detector manufacturers source microwave circuit design talent.
Canada
Cross-border fleet operators absorb hardware costs against citation exposure along transcontinental highway networks linking major urban centers. Health Canada and PMRA maintain equipment safety standards that parallel FDA laser-safety protocols for LIDAR detection hardware. Ontario's automotive electronics supply chain feeds component sourcing for North American assembly operations.
Germany
Autobahn corridor logistics operators seek citation-risk reduction for self-insured commercial vehicle pools. KBA vehicle certification requirements and REACH substance restrictions constrain printed circuit board material selection. Bavaria's precision electronics manufacturing base supplies RF front-end components to detector assemblers.
United Kingdom
Fixed speed-camera density in metropolitan areas drives GPS-integrated detector adoption among commuter vehicle owners. DVLA enforcement data sharing patterns and GDPR privacy frameworks shape crowdsourced alert network architectures. Southeast England's automotive technology corridor hosts software development for AI-driven false-alert suppression algorithms.
Australia
Remote highway patrol patterns across vast interstate distances sustain demand for high-sensitivity Ka-band detection capabilities. TGA equipment standards and state-level motor vehicle regulations fragment distribution compliance requirements. Victoria's electronics manufacturing sector provides contract assembly services for Asia-Pacific market variants.
Radar Detector Market Vendor Landscape
Premium-margin players sit above commodity-margin players across sensitivity specification tiers and connectivity feature integration. The vendor base stratifies into three concentration levels: heritage microwave electronics firms with RF engineering depth, consumer electronics brands leveraging manufacturing scale, and specialist entrants focused on AI-driven signal processing. Two dominant competitive moves are consolidating aftermarket position: cloud-based alert network subscription services that displace pure hardware economics, and fleet procurement centralization that treats detectors as connected-asset nodes rather than discrete electronics.
Within the heritage RF engineering tier, Escort Inc. and Beltronics occupy positions anchored by brand recognition among automotive enthusiasts seeking premium standalone configurations. Uniden America Corporation exemplifies the manufacturing-scale archetype through mid-tier wireless model proliferation. Cobra Electronics represents the price-competitive volume channel strategy targeting online retail fulfillment. These three anchors illustrate how competitive positioning fragments across margin tiers rather than consolidating around unified technology platforms.
| Leading Market Players |
|---|
| Escort Inc. |
| Uniden America Corporation |
| Cobra Electronics |
| Beltronics |
| Cedar Electronics |
| Whistler Group |
| Radenso |
| K40 Electronics |
| Rocky Mountain Radar |
| Others |
Supply Flow & Price Mechanics
AI-driven signal processing migration is compressing component counts in premium detector architectures while concentrating RF front-end sourcing among GaAs MMIC specialists with millimeter-wave fabrication capabilities. This technological shift simultaneously elevates R&D amortization burdens for algorithmic development and reduces per-unit hardware costs for established manufacturers with captive chip supply relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Escort Inc.'s AI-enabled flagship models from Uniden's mid-tier wireless configurations and Cobra's entry-level online retail offerings. Price differentiation hinges on Ka-band sensitivity certification tiers and Bluetooth connectivity bundling with subscription alert networks. Cost compression in the economy tier is intensifying because Cobra Electronics' aggressive channel pricing forces margin concessions across volume-focused competitors. Fleet procurement departments exhibit lowest price sensitivity due to citation-risk pooling, while individual online retail buyers demonstrate highest elasticity to promotional discounting.
Supply Chain Analysis
Returns and refurbishment flows for portable detector units create secondary market channels that constrain pricing power for new hardware releases. Component sourcing concentrates in Taiwan for GaAs MMIC fabrication, China for printed circuit board assembly, and Germany for precision RF front-end components. Raw material dependencies span gallium arsenide substrates, halogen-free laminate substrates under REACH compliance, and 904nm photodiode arrays for LIDAR detection. Single-source vulnerability in specialty foundry capacity for millimeter-wave chips exposes manufacturers to allocation constraints during semiconductor demand surges. Distribution runs through direct-to-fleet contracting for integrated systems and e-commerce platforms for portable device fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the radar detector market rests on algorithmic differentiation displacing hardware cost competition, with AI-driven false-alert suppression commanding subscription attach rates that decouple revenue from unit shipment volatility.
For Market Incumbents: Anticipate cloud-based alert network saturation by deepening proprietary data moats through exclusive fleet partnerships that crowdsource enforcement location intelligence. Defensive consolidation should prioritize backward integration into GaAs MMIC design capabilities to secure RF front-end supply against foundry allocation shocks. Escort Inc. and Uniden America Corporation must monitor emerging AI entrants with neural-network classifier architectures that threaten to obsolete rule-based filtering hardware. For New Entrants and Emerging Players: Launch via direct-to-fleet distribution models targeting self-insured logistics operators with underpenetrated enterprise-scale provisioning needs. White-space concentration sits in commercial truck segments where centralized procurement patterns displace individual driver purchases. Most penetrable geography spans Ohio and Michigan interstate corridors where RF engineering talent clusters support rapid technical support scaling. Go-to-market positioning should emphasize OBD-II data fusion capabilities that incumbent heritage microwave electronics firms lack. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier wireless model manufacturers facing margin compression from Bluetooth connectivity commoditization. Long-term viability across the projection horizon favors vendors with recurring subscription revenue streams and fleet contract backlogs rather than pure hardware economics. Acquisition target archetypes include AI signal processing specialists with neural-network classifier IP and established cloud alert network user bases. Practitioners should monitor FCC spectrum reallocation debates and municipal LIDAR enforcement adoption curves for demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| AI Signal Processing Integration | Neural-network classifiers differentiate police radar from collision-avoidance systems, commanding premium pricing. |
| Cloud Alert Network Expansion | Real-time crowdsourced data aggregation creates network-effect moats against hardware-only competitors. |
| Fleet Direct Contracting | Centralized procurement by self-insured logistics operators displaces fragmented individual driver purchases. |
| GaAs MMIC Backward Integration | In-house millimeter-wave chip design secures supply allocation against specialty foundry concentration. |
| OBD-II Data Fusion Development | Vehicle telemetry access enables predictive enforcement mapping and premium subscription tiers. |
Methodological Framework
Direct dialogue with RF engineering directors at heritage microwave electronics firms, procurement leads at commercial fleet operators, FCC certification consultants, and specialty semiconductor foundry account managers grounded qualitative findings in operational reality. Secondary validation drew from FCC Part 15 equipment authorization databases, FDA laser-safety filing records, commercial vehicle registration data from interstate corridor states, and SEC filings from publicly traded consumer electronics parent companies. Bottom-up unit shipment estimates across portable, integrated, and wireless form factors triangulated against top-down addressable market sizing derived from citation-risk exposure modeling.
Bottom-up modeling aggregated replacement cycle assumptions, price-band migration patterns, and connectivity attach rates across the analysis window. Segmentation dimensions included product type, sensing technology, end-user procurement authority, and distribution channel margin capture. CAGRs were derived from installed base evolution and average selling price trajectory synthesis. Industry-specific forecast inputs incorporated Ka-band enforcement equipment migration rates from municipal procurement databases and Bluetooth connectivity adoption curves from smartphone pairing statistics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated LIDAR enforcement adoption or FCC spectrum reallocation decisions. Practitioners should monitor state-level detector prohibition enforcement intensity, specialty foundry capacity utilization reports, and fleet insurance premium adjustment patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Filter Panels Market
Detection and Regulation Devices
Limiter Diodes Market
Detection and Regulation Devices
Microwave Leakage Detector Market
Detection and Regulation Devices
Voltage Detector Market
Detection and Regulation Devices
Magnetic Crack Detectors Market
Detection and Regulation Devices
IR Detector Market
Detection and Regulation Devices
Duct Smoke Detectors Market
Detection and Regulation Devices
Global a-Si X-Ray Flat Panel Detectors Market
Detection and Regulation Devices
Europe Portable Gas Detector Market
Detection and Regulation Devices
US Pin and Sleeve Devices Market
Detection and Regulation Devices
Betavoltaic Device Market
Detection and Regulation Devices
EMEA Frequency Control and Timing Devices Market
Detection and Regulation Devices
Transient Voltage Suppressor Market
Detection and Regulation Devices
Vacuum Leak Detectors Market
Detection and Regulation Devices
Voltage Detection System Market
Detection and Regulation Devices
Infrared Detection Chip Market