
 Pea Protein Isolate Market | 2026-2036
Pea Protein Isolate Market Size, Share, and Industry Trends Forecast 2026-2036
Pea Protein Isolate Market Intelligence
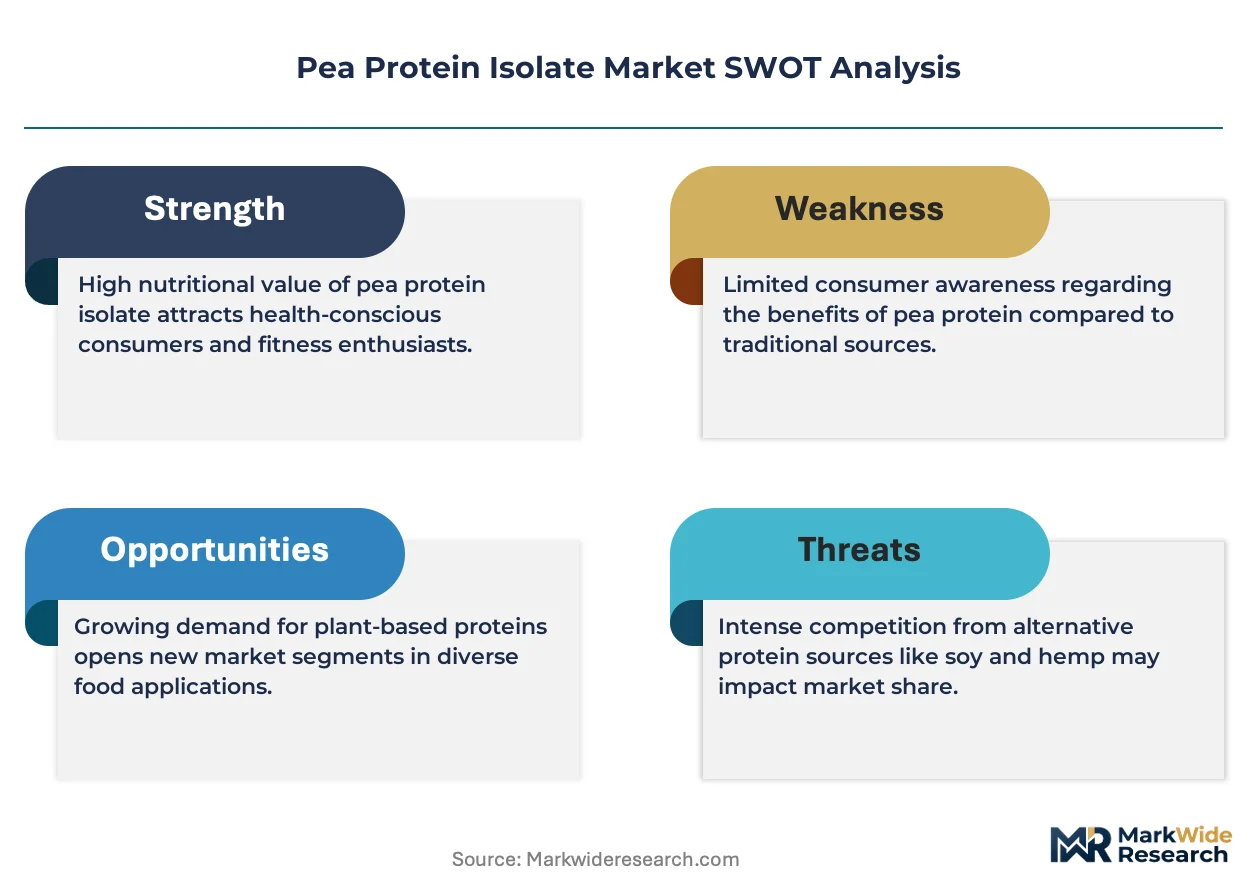
Consolidation among large-scale food and beverage manufacturers is hardening procurement requirements for pea protein isolate suppliers. This shift favors suppliers with extensive production capacity and consistent quality control. Roquette Frères leverages its significant manufacturing scale to serve multinational clients. Meanwhile, Ingredion Incorporated differentiates through its expertise in functional ingredient formulation and application support.
Pea protein isolate is a highly concentrated protein powder, typically containing over 85% protein, derived from yellow peas through a fractionation process. This process separates the protein from starch and fiber, resulting in a functional ingredient valued for its emulsifying and gelling properties. The sports nutrition segment continues to be a primary application, driving volume. However, textured pea protein formats are seeing rapid uptake in dairy alternatives, offering higher margins for producers.
Product safety and market access are governed by frameworks like the FDA's Generally Recognized as Safe (GRAS) notifications in the United States and EFSA's food safety standards in the European Union. These regulations, combined with non-GMO and organic certifications, define quality tiers and influence buyer specifications. Consequently, securing a stable supply of compliant raw peas becomes a critical strategic decision for processors.
Market Dynamics
Consolidation among food manufacturers is hardening procurement standards, favoring large-scale processors. This dynamic elevates the importance of consistent quality control and verifiable supply chains for pea protein isolate suppliers seeking to serve multinational clients.
Growth Catalysts
- Allergen Regulations:Stricter food labeling laws, including those from the FDA and EFSA, compel manufacturers to replace allergenic proteins like soy and whey, creating a direct substitution demand for pea protein.
- Sports Nutrition Demand:The sports nutrition sector's pivot towards plant-based diets provides a high-volume outlet for pea protein isolate, valued for its high protein content and amino acid profile.
- Clean Label Movement:Consumer preference for non-GMO and organic certified ingredients, particularly in developed markets like the United States, positions certified pea protein as a premium, clean-label input.
Market Restraints
- Raw Material Volatility:Dependence on yellow pea harvests, concentrated in specific agricultural regions, exposes processors to price fluctuations and supply disruptions from weather or geopolitical events.
- Sensory Profile:Unpleasant "beany" or earthy off-notes in some pea protein isolates present a technical hurdle, often requiring costly masking agents or further processing to achieve consumer acceptance.
- Soy Protein Competition:In applications where allergenicity is not the primary concern, lower-cost soy protein isolate remains a significant substitute, competing directly on price and functionality.
Strategic Opportunities
- Textured Protein Formats:Developing textured pea protein for meat and dairy analogue applications offers a pathway to higher-margin products, moving beyond the commodity powder market.
- Asia-Pacific Market Entry:Expanding into nascent plant-based markets in countries like China and India presents a significant volume growth opportunity as dietary patterns shift away from traditional animal proteins.
- Fractionation Technology:Investing in novel dry or wet fractionation techniques can yield isolates with superior solubility or gelling properties, creating differentiated, high-value product tiers.
Industry Challenges
- Capital Expenditure:The high upfront investment required to construct and certify a food-grade fractionation plant creates a significant barrier to entry for smaller firms.
- Certification Complexity:Navigating the array of required certifications, from GRAS notifications in the US to non-GMO and organic seals, adds significant administrative overhead and extends time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pea Protein Isolate Market |
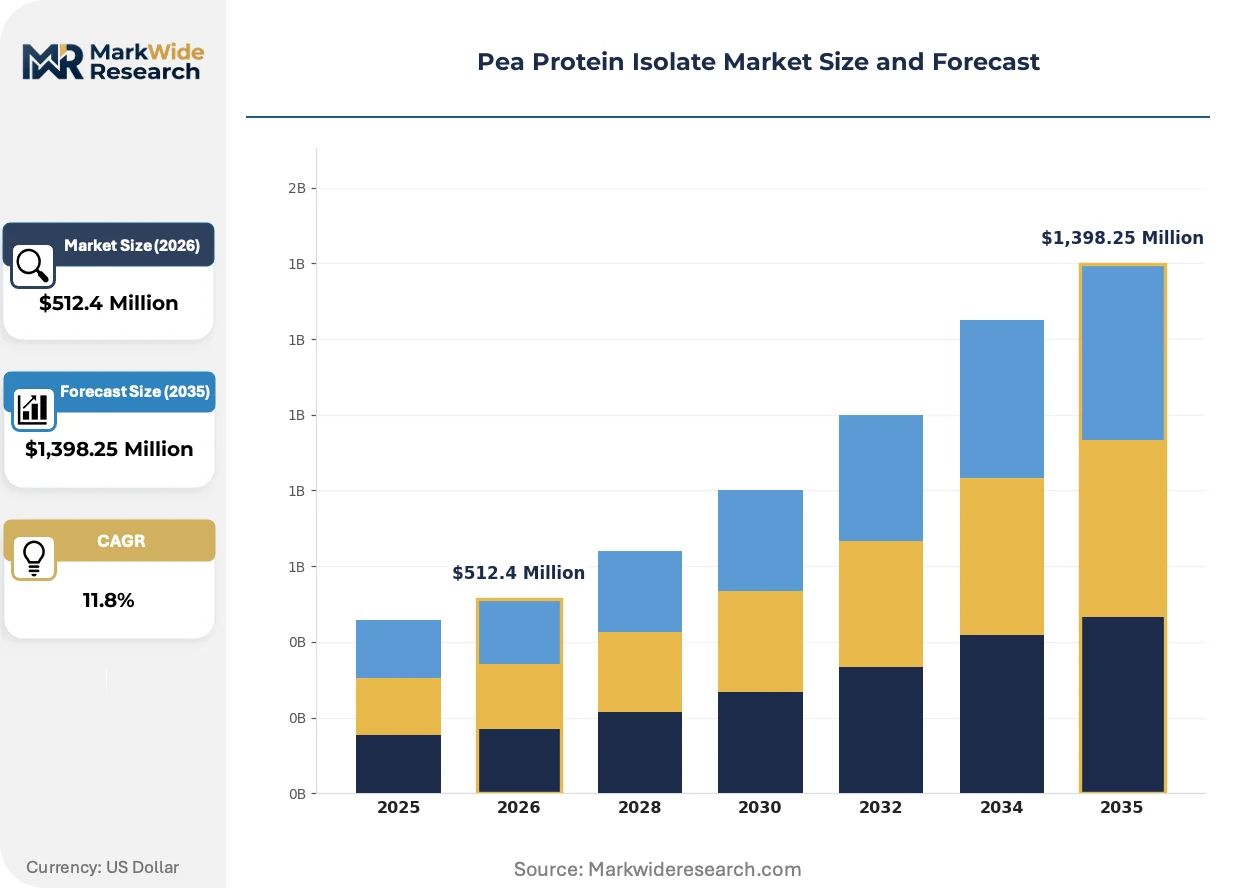
| Market Size in 2026 | $512.4 Million |
| Market Size in 2035 | $1,398.25 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured Pea Protein, Concentrated Pea Protein, Native Pea Protein, Fractionated Pea Protein, Acid-Extracted Pea Protein Application: Sports Nutrition, Infant Nutrition, Animal Feed, Functional Foods, Bakery Products, Dairy Alternatives End User: Food & Beverage Manufacturers, Nutraceutical Companies, Animal Feed Producers, Dietary Supplement Brands Packaging Type: Bulk Bags, Stand-up Pouches, Vacuum Sealed Bags, Paper Bags, Plastic Containers |
| Companies Covered | Ingredion Incorporated, Glanbia PLC, Cargill, Incorporated, Burcon NutraScience Corporation, Kerry Group PLC, Roquette Frères, The Scoular Company, Emsland Group, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pea Protein Isolate Market Strategic Shifts & Innovations
The market is evolving from supplying a bulk ingredient to providing a portfolio of functional solutions. This transition is driven by technological advancements in processing and a deeper understanding of how isolate properties impact final food product texture and stability.
Advanced fractionation and texturization processes are creating new classes of pea protein isolate with specific functional attributes. Food formulators in the dairy alternative and plant-based meat sectors are rapidly adopting these specialized ingredients. This innovation is decentralizing the market away from a single commodity-grade powder into a spectrum of application-specific, higher-value products.
European Union regulations mandating clear allergen labeling on food products are compelling manufacturers to reformulate away from ingredients like whey and soy. This regulatory pressure directly benefits non-allergenic plant proteins. The prepared meals and sports nutrition categories within the EU are most affected, accelerating their adoption of pea protein isolate as a default base ingredient.
A shift from transactional purchasing to strategic sourcing is altering buyer behavior. Large food and beverage conglomerates are bypassing distributors to secure long-term contracts directly with processors for supply stability and co-development. This pattern is most pronounced in North America, where supply chain resilience has become a core procurement priority.
Pea Protein Isolate Market Segmentation
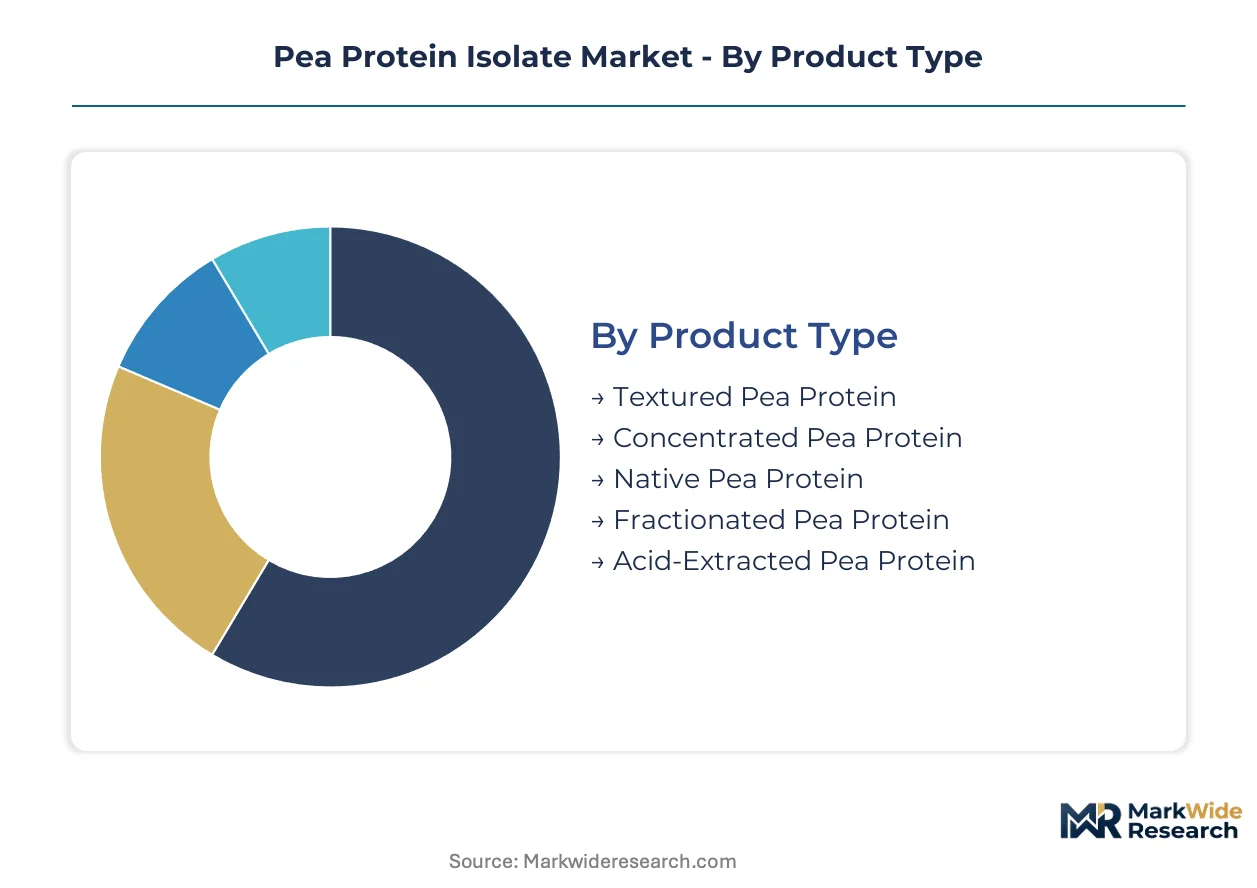
The pea protein isolate market is diverse, with segmentation crucial for understanding varied product formulations and end-user requirements. Each segment reflects distinct functional needs, processing methods, and target consumer groups, influencing supply chain dynamics.
Product Type:
The choice of pea protein isolate product type often differentiates buyers based on their desired functional properties and target product applications.
- Textured Pea Protein:This format undergoes extrusion to create a fibrous structure, mimicking meat textures. Demand is expanding rapidly in plant-based meat alternatives across North America and Europe, driven by evolving consumer diets.
- Native Pea Protein:This minimally processed form retains a high percentage of protein with good digestibility. It finds significant use in sports nutrition products in Germany and the United States, valued for its clean label appeal.
- Concentrated Pea Protein:Containing 70-80% protein, this less refined version serves as a cost-effective ingredient in animal feed formulations.
- Fractionated Pea Protein:This type involves separating protein from starch and fiber, often used for specific functional properties in food systems.
- Acid-Extracted Pea Protein:Produced using acid treatment, this isolate can offer unique solubility and emulsification characteristics for specialized food applications.
Volume sits with Native Pea Protein; growth tilts toward Textured Pea Protein.
Application:
The application segment for pea protein isolate often reflects varying cost-benefit considerations and formulation requirements for manufacturers.
- Sports Nutrition:This segment heavily utilizes pea protein isolate for its high protein content and amino acid profile, supporting muscle recovery and growth. Demand is robust in developed markets like the United States and Canada, driven by the plant-based fitness trend.
- Dairy Alternatives:Pea protein isolate provides essential protein and functional properties for plant-based milks, yogurts, and cheeses. European consumers are increasingly adopting these alternatives, leading to significant innovation in product development.
- Infant Nutrition:Pea protein isolate offers a hypoallergenic protein source for specialized infant formulas, particularly for babies with allergies.
- Animal Feed:This application leverages pea protein as a sustainable and nutritious protein supplement for livestock and aquaculture.
- Functional Foods:Pea protein isolate enhances the protein content and nutritional profile of various fortified food products, appealing to health-conscious consumers.
- Bakery Products:Incorporating pea protein isolate into baked goods improves nutritional value and can offer textural benefits in gluten-free formulations.
Sports Nutrition maintains significant market share, while Dairy Alternatives demonstrate the steepest expansion trajectory.
End User:
End-user categories for pea protein isolate are primarily distinguished by their purchasing volume and specific product development cycles.
- Food & Beverage Manufacturers:These large-scale entities integrate pea protein isolate into a wide array of products, from plant-based meats to fortified beverages. Their procurement needs emphasize consistent quality and large-volume supply from global processors.
- Dietary Supplement Brands:These companies formulate pea protein isolate into powders, bars, and capsules targeting health-conscious consumers and athletes. Product innovation often focuses on taste masking and advanced blending to meet specific nutritional claims.
- Nutraceutical Companies:These firms utilize pea protein isolate for its health benefits in products designed to support overall wellness and specific physiological functions.
- Animal Feed Producers:This end-user group incorporates pea protein isolate into livestock and pet feed formulations to enhance protein content and digestibility.
Food & Beverage Manufacturers represent the largest consumer base, with Dietary Supplement Brands exhibiting strong upward momentum.
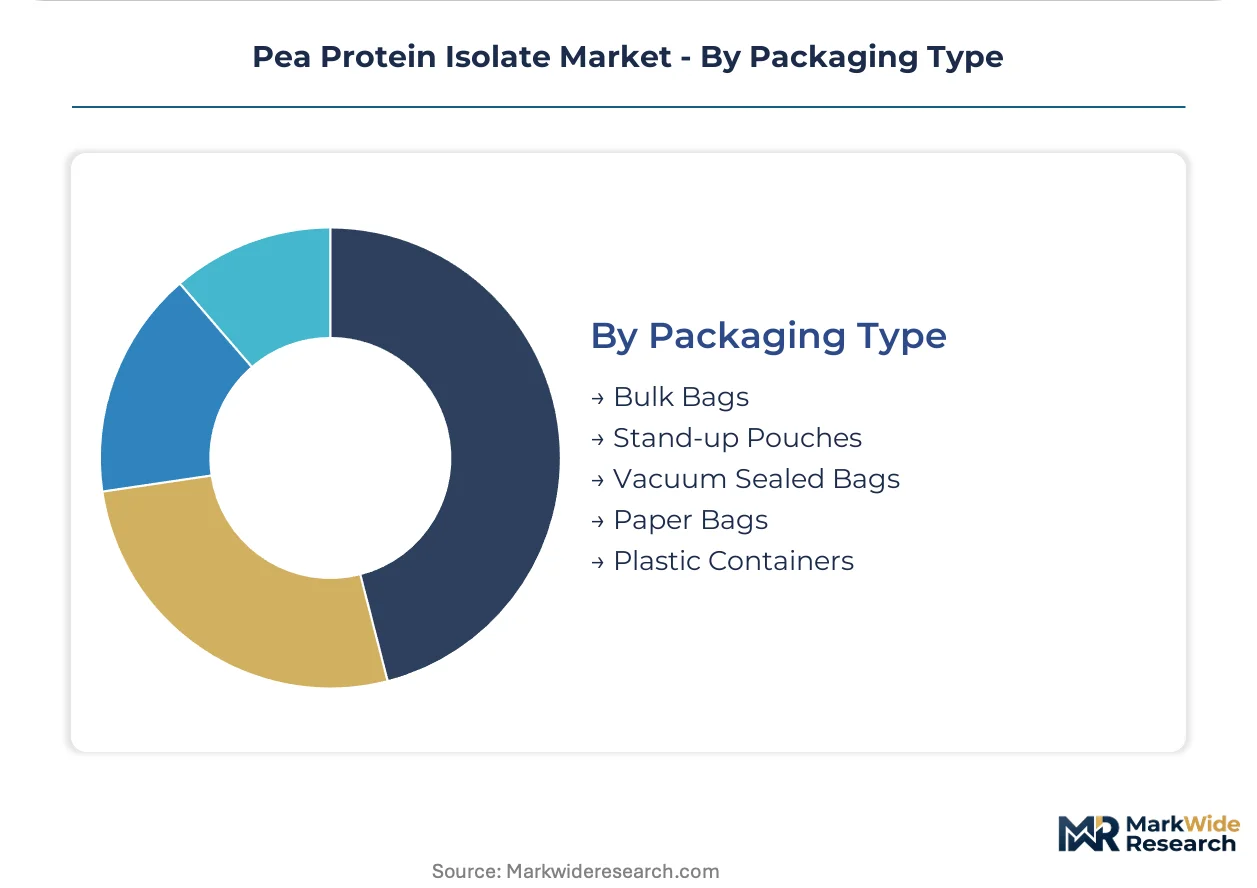
Packaging Type:
Packaging type for pea protein isolate is tailored to the specific customer type, ranging from industrial processors to direct-to-consumer brands.
- Bulk Bags:These large-format packages, typically 500kg to 1000kg, cater to industrial food and beverage manufacturers requiring high-volume ingredient delivery. They prioritize cost efficiency and ease of handling in large-scale production facilities.
- Stand-up Pouches:Often used for retail-ready consumer products, these packages offer convenience, resealability, and branding opportunities. They are particularly popular for sports nutrition and dietary supplement applications in North America.
- Vacuum Sealed Bags:This packaging type extends shelf life and protects pea protein isolate from moisture and oxidation, crucial for preserving product quality.
- Paper Bags:An economical and environmentally conscious option, paper bags are often used for lower-cost or bulk ingredients where moisture barrier requirements are less stringent.
- Plastic Containers:These rigid containers provide excellent product protection and are frequently used for smaller, premium-priced pea protein isolate products.
Bulk Bags dominate industrial procurement, while Stand-up Pouches are gaining traction in retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's robust yellow pea cultivation underpins a significant portion of global pea protein isolate supply, influencing market dynamics across diverse consumer regions. Demand concentration is particularly high in developed economies, driven by evolving dietary preferences and stringent food regulations. This global market sees varied growth patterns influenced by local regulatory frameworks and consumer trends.
United States
Sports nutrition and the clean label movement drive substantial demand for pea protein isolate in the United States. FDA regulations, including GRAS notifications, ensure product safety and market access for compliant ingredients. Major food manufacturers in California and the Midwest are reformulating products, integrating pea protein into plant-based meat and dairy alternatives.
Germany
German consumers increasingly seek plant-based dairy alternatives and functional foods, boosting pea protein isolate consumption. EFSA food safety standards dictate ingredient quality, accelerating reformulation efforts by manufacturers. Food and beverage innovators in Bavaria and North Rhine-Westphalia are developing new applications for specialized pea protein formats.
China
Emerging plant-based trends and a focus on protein diversification are fueling nascent demand for pea protein isolate in China. NMPA regulations govern food ingredient approvals, influencing processor investment and market entry strategies. Manufacturers in the Yangtze River Delta region are exploring textured pea protein for local meat analogue products.
Canada
Canadian pea growers provide a reliable raw material base, supporting domestic and export pea protein isolate production. Health Canada's food regulations ensure quality and labeling transparency for protein ingredients. Processors in Saskatchewan and Manitoba are expanding fractionation capabilities to meet rising global demand for native pea protein.
France
France, a significant pea-producing nation, benefits from European Union regulations that compel manufacturers to seek non-allergenic protein sources. This regulatory environment supports the local pea protein isolate industry. Companies in northern France, particularly around Lille, are investing in advanced fractionation technologies to develop high-value functional ingredients.
Pea Protein Isolate Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue functional ingredient specialization and application-specific solutions. The market structure exhibits a tiered approach, with large agricultural processors competing against specialized ingredient manufacturers. Strategic partnerships and capacity expansions are common competitive moves among participants.
Scale-driven players like Cargill, Incorporated and Roquette Frères anchor the bulk ingredient supply, leveraging extensive raw material sourcing and processing capabilities. Ingredion Incorporated, meanwhile, exemplifies a focus on functional ingredient formulation and application support, differentiating through technical expertise. These companies represent distinct strategic archetypes within the pea protein isolate market.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Glanbia PLC |
| Cargill, Incorporated |
| Burcon NutraScience Corporation |
| Kerry Group PLC |
| Roquette Frères |
| The Scoular Company |
| Emsland Group |
| DuPont |
| Others |
Cost & Logistics Intelligence
Food and beverage manufacturers' consolidation into larger entities directly influences the dominant pricing model for pea protein isolate, shifting towards contract-based long-term offtake agreements.
Pricing Analysis
Volume-driven segments often experience commodity spot pricing, while specialized functional properties command higher margins through contract-based agreements. Pricing stratifies across non-GMO and organic certification levels, and also by specific functional attributes like superior solubility. Pricing softness reflects intense competition from lower-cost soy protein isolate in many applications. Animal feed producers exhibit the highest price sensitivity, while infant nutrition and specialized functional food manufacturers demonstrate lower sensitivity.
Supply Chain Analysis
Certification and qualification gating, such as FDA GRAS notifications and EFSA standards, are crucial entry points into the pea protein isolate supply chain. Raw yellow peas are primarily sourced from agricultural regions in Canada and France, with emerging production in China. The supply chain relies on consistent harvests, exposing processors to commodity price volatility due to weather events. Distribution runs through direct long-term contracts with major food and beverage manufacturers, complemented by specialized ingredient distributors serving smaller formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pea protein isolate market is characterized by a vertical-integration race, with players actively pursuing upstream control over raw yellow pea sourcing. This strategy aims to secure consistent supply and quality amidst fluctuating agricultural yields.
For Market Incumbents: Lock in long-term raw material contracts with key pea growers in Canada to mitigate supply volatility. Expanding advanced fractionation capacity allows for the development of specialized functional isolates, addressing sensory profile challenges like "beany" off-notes. This defends against lower-cost soy protein competition and reinforces market position through premium, certified offerings.
For New Entrants and Emerging Players: Direct-to-consumer e-commerce channels offer a viable entry point for niche, high-value pea protein products. Target underpenetrated Asia-Pacific plant-based markets, particularly China's textured pea protein segment for meat analogues. Focus on co-development partnerships with local food startups to tailor formulations to regional tastes and regulatory requirements, driving rapid adoption.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to consolidate fragmented processing capabilities over the next 5-10 years. Target mid-sized processors possessing proprietary fractionation technologies or established raw material sourcing networks in regions like France. A significant signal to watch is an acceleration of M&A activity within the broader plant-based ingredient sector, indicating heightened consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Roquette Frères' investment in new facilities ensures consistent supply for multinational clients. |
| Proprietary Fractionation R&D | Ingredion Incorporated differentiates its offerings with superior functional properties for dairy alternatives. |
| Long-term Raw Material Contracts | Cargill, Incorporated secures stable yellow pea supply, reducing price volatility for its protein isolates. |
| Non-GMO/Organic Certification Pursuit | Emsland Group gains market access and premium pricing in developed economies like Germany. |
| Asia-Pacific Market Entry | The Scoular Company establishes distribution networks to capitalize on China's emerging plant-based demand. |
Research Approach
Independent corroboration across primary interviews with procurement leads, R&D directors, and food formulators, alongside secondary validation from FDA GRAS notices and EFSA scientific opinions, underwrites the qualitative findings. This approach integrates insights from industry stakeholders with data from customs trade records and company annual reports. Both bottom-up and top-down triangulation methods were employed to ensure data accuracy and market scope definition.
The forecast window was anchored to a three-year historical reference period, establishing baseline growth rates for quantitative modeling across the projection horizon. Segmentation dimensions modeled include product type, application, end-user, packaging type, and regional regulatory frameworks. Compound Annual Growth Rates (CAGRs) were derived from historical growth patterns and projected market accelerators. Key forecast inputs include raw pea harvest yields and the rate of plant-based food innovation.
The model holds under conditions of a stable regulatory environment and predictable agricultural cycles; deviation in raw material availability or unexpected regulatory shifts would alter projections. Forecasts reflect assumptions regarding current consumer trends and competitive dynamics. A model refresh is warranted upon material change in global trade policies or protein ingredient technology.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Global Isolate Organic Soy Protein Market
Plant Based Food
Vegan Pasta Market
Plant Based Food
China Rice Protein Market
Plant Based Food
Global Plant Based Food Market
Plant Based Food
Asia-Pacific Rice Protein Market
Plant Based Food
Germany Plant Protein Market
Plant Based Food
Europe Plant-Based Food Market
Plant Based Food
Vegan Meals Market
Plant Based Food
Dandelion Root Extract Market
Plant Based Food
Plant Based Pork Market
Plant Based Food
Plant Based Meal Kit Market
Plant Based Food
Global Chaga Mushroom-Based Products Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
Plant-Based Frozen Dessert Market
Plant Based Food
Plant-Based Chorizo Market
Plant Based Food
Plant-Based Food and Beverages Market