
 Vegan Pasta Market | 2026-2036
Vegan Pasta Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Pasta Market Analysis
The gap between artisanal legume-based formulations and mass-market wheat-alternative lines is recalibrating how manufacturers allocate production capacity. Barilla Group leverages its Italian milling heritage to sustain premium positioning in whole wheat and legume blends. Banza Inc. competes on chickpea protein density while Tolerant Organics specializes in single-ingredient organic lentil and pea pastas with limited distribution footprints.
Vegan pasta denotes durum wheat alternatives or legume-derived noodles formulated without eggs, dairy, or animal derivatives, typically achieving protein content of 11-25 grams per serving through chickpea, lentil, or pea flour bases. The primary commercial purpose is serving retail and foodservice channels seeking to satisfy plant-based dietary protocols without sacrificing macronutrient density. Spaghetti and penne SKUs anchor volume throughput in conventional supermarkets, while quinoa and legume ingredient sources command margin premiums in health stores and specialty retail. Online retail distribution is expanding fastest among channels, though supermarkets still occupy the dominant shelf position for box-packaged formats.
The EU Green Deal and F-Gas Regulation shape processing equipment standards and packaging sustainability mandates across European manufacturing. The FDA's Food Safety Modernization Act and USDA organic certification requirements govern ingredient traceability and label claims in the United States. Stakeholders must monitor evolving protein content thresholds as clean-label standards tighten and retail buyers recalibrate assortment criteria around nutritional density rather than ingredient novelty alone.
Market Dynamics
Legume flour processing capacity is consolidating around specialized extrusion facilities that can achieve protein retention above 20% while maintaining al dente texture, creating a technical moat between artisanal formulators and commodity wheat-alternative producers.
Growth Catalysts
- EU Green Deal sustainable food system targets:Mandatory farm-to-fork traceability requirements are accelerating certified organic ingredient procurement across German and Italian manufacturing bases.
- Foodservice channel expansion:North American urban restaurant operators are dedicating permanent menu sections to plant-based pasta dishes, driving bulk procurement contracts for chickpea and lentil SKUs.
- Chickpea protein density standards:Clean-label retail buyers are recalibrating shelf placement criteria around macronutrient thresholds rather than ingredient novelty alone.
Market Restraints
- Pulse crop price volatility:Canadian and Australian lentil harvest fluctuations transmit directly into raw material cost instability for single-ingredient organic lines.
- Extrusion equipment concentration:Italian and Swiss machinery suppliers control 80% of high-shear pasta extrusion technology, creating supply bottleneck risks.
- Texture-performance tradeoffs:Legume-only formulations without wheat blending struggle to achieve consumer-acceptable cooking tolerance windows above 12 minutes.
Strategic Opportunities
- India urban retail penetration:Tier-1 metropolitan health stores remain underpenetrated by imported legume pasta brands despite rising plant-based protein demand.
- Quinoa-konjac hybrid formats:Converging ancient grain and soluble fiber technologies enable ultra-low glycemic index positioning for diabetic dietary protocols.
- Direct-to-subscription channels:Customizable monthly pasta boxes with rotating legume bases bypass conventional supermarket slotting fee structures.
Industry Challenges
- Food technologist scarcity:Formulation chemists with dual expertise in pulse protein chemistry and traditional durum rheology command premium salaries that strain mid-cap R&D budgets.
- USDA organic certification timelines:Ingredient traceability documentation requirements now extend 18-24 months for multi-origin legume supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Pasta Market |
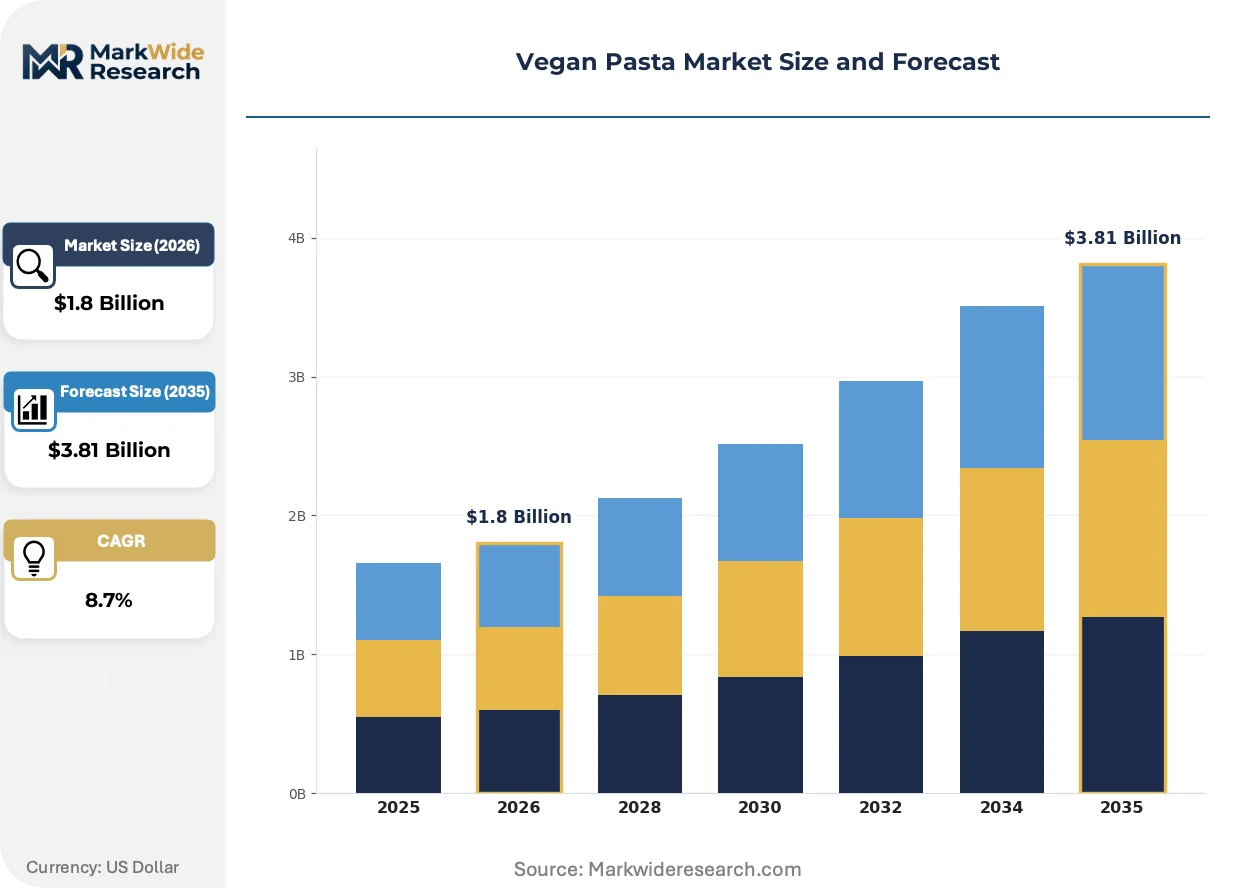
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spaghetti, Fusilli, Penne, Lasagna Ingredient Source: Legumes, Whole Wheat, Rice, Quinoa Packaging Type: Box, Bag, Jar, Vacuum Seal Distribution Channel: Supermarkets, Online Retail, Health Stores, Specialty Stores |
| Companies Covered | DeLallo Company, Tolerant Organics, Barilla Group, Bionaturae LLC, Windmill Organics, Nestlé S.A., Banza Inc., TreeHouse Foods Inc., F.lli De Cecco di Filippo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Pasta Market Emerging Trajectories
Extrusion technology and packaging sustainability mandates are compressing production batch sizes while fragmenting distribution channels, forcing manufacturers to choose between scale efficiency and SKU proliferation strategies.
High-pressure cold extrusion systems are modularizing production workflows for regional pasta manufacturers. Mid-scale Italian and Spanish producers are adopting these units to switch between chickpea, lentil, and fava bean formulations within single production cycles. This flexibility is compressing minimum viable batch sizes from 10-ton runs to sub-ton lots, enabling private-label customization for specialty retail chains.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in industrial cooling systems that stabilize pasta dough temperature during extrusion. European manufacturers face retrofit deadlines that favor ammonia-based or CO2 refrigeration alternatives with higher upfront capital requirements. German and Dutch processing facilities are responding fastest, driven by national implementation schedules that precede EU-wide mandates.
Retail buyers are consolidating supplier relationships around vertically integrated pulse processors that control milling, extrusion, and packaging under single facility roofs. This procurement compression is displacing fragmented ingredient-trader networks that previously supplied independent pasta brands. The shift is most visible in German supermarket chains, where direct sourcing contracts with Canadian and Turkish pulse processors now dominate shelf-stable pasta procurement.
Vegan Pasta Market Segmentation
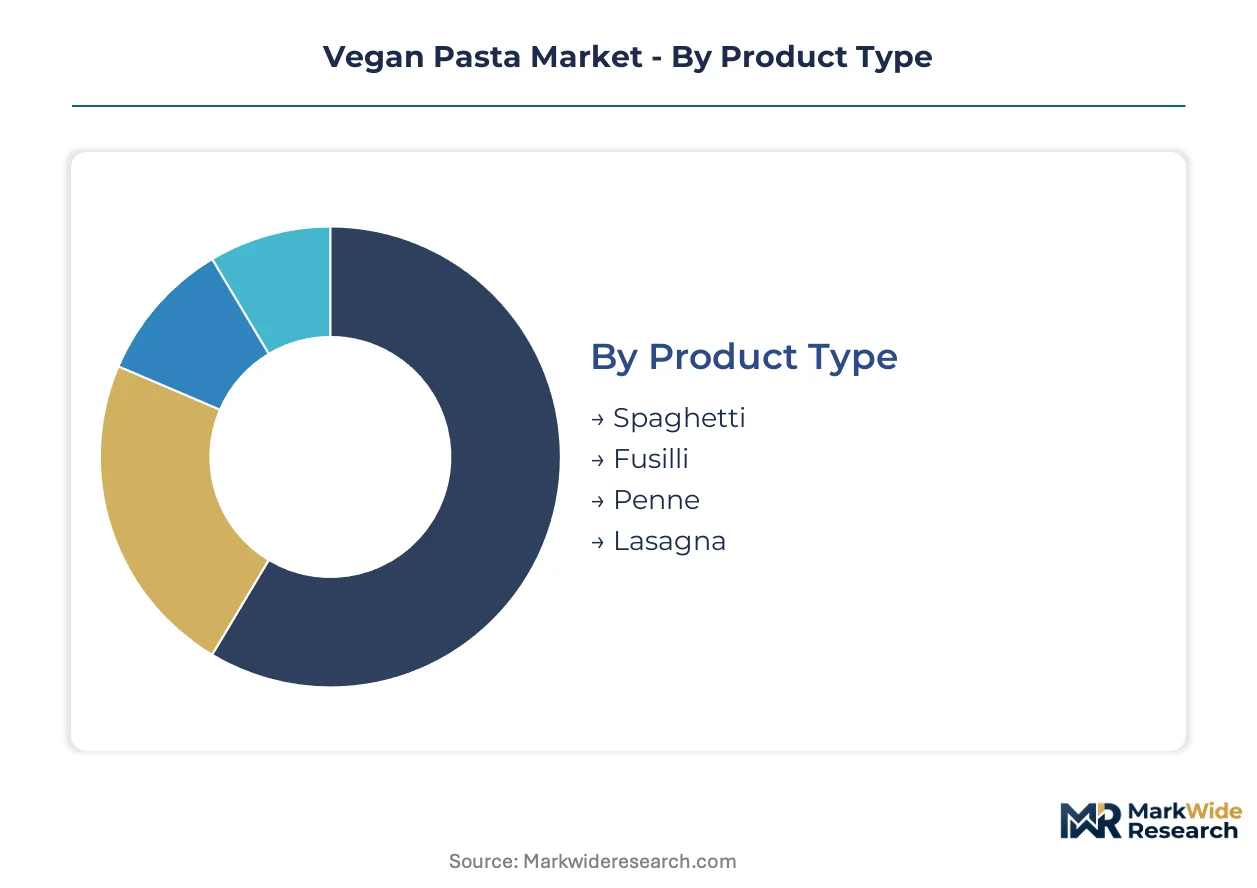
Vegan pasta manufacturers must navigate divergent certification requirements across product formats and ingredient bases. Segmentation reveals where USDA organic, EU organic, and gluten-free claims concentrate regulatory burden and margin opportunity.
Product Type:
Long-format noodles carry stricter durum wheat-alternative labeling requirements under FDA and EFSA guidelines, while short cuts face different texture-performance thresholds for protein retention claims.
- Spaghetti:Long-strand extrusion demands specialized high-shear equipment to prevent legume-based breakage during drying. German and Italian retail chains anchor procurement volumes for this format, driven by foodservice operators seeking familiar plate presentations for plant-based menu conversions.
- Penne:Ridged tubular geometry maximizes sauce adhesion in chickpea and lentil formulations, making it the preferred format for premium health store positioning. North American urban supermarkets have expanded facings for this SKU as clean-label buyers prioritize protein density over wheat mimicry.
- Fusilli:Helical shapes suit cold pasta salad applications in deli counters and prepared foods sections.
- Lasagna:Sheet formats require precise moisture control during extrusion to prevent brittleness in legume-only recipes.
Spaghetti sits at the top of the volume ranking, with penne climbing the fastest.
Ingredient Source:
Raw material certification timelines stretch procurement cycles unevenly across plant bases, with multi-origin legume supply chains demanding 18-24 month traceability documentation under USDA organic rules.
- Legumes:Chickpea, lentil, and pea flours achieve 20-25 grams protein per serving through specialized extrusion that preserves albumin structure. Canadian and Turkish pulse processors have secured direct contracts with German supermarket chains, bypassing fragmented ingredient-trader networks.
- Whole Wheat:Semolina alternatives without egg binders rely on modified gluten networks for texture, occupying mid-tier price positioning in conventional retail. Italian milling heritage underpins premium claims for this segment.
- Quinoa:Ancient grain positioning commands margin premiums in specialty channels despite smaller production scale.
- Rice:Neutral flavor profile suits allergen-free formulations but requires protein fortification to meet clean-label density thresholds.
Legumes dominate current shelf space allocation, with quinoa expanding most quickly in health store channels.
Packaging Type:
Sustainability mandates under the EU Green Deal and F-Gas Regulation are reshaping material specifications and cooling system requirements across format types.
- Box:Recycled cardboard with vegetable-based inks satisfies supermarket ESG procurement criteria and occupies dominant shelf positioning for shelf-stable formats. German retailers have accelerated plastic-reduction timelines that favor this packaging for legume-based lines.
- Vacuum Seal:Extended shelf life enables direct-to-subscription channel economics with reduced spoilage risk in humid climates. This format gains traction in Indian tier-1 metropolitan health stores where imported brand penetration remains limited.
- Bag:Flexible packaging reduces shipping cube but struggles with premium perception in specialty retail.
- Jar:Glass containers support premium positioning for fresh-refrigerated formats in urban foodservice.
Box packaging maintains volume leadership, with vacuum seal formats gaining share fastest in online retail.
Distribution Channel:
Slotting fee structures and buyer consolidation patterns create divergent margin profiles across channel types, with vertical integration favoring direct relationships over fragmented networks.
- Supermarkets:Conventional grocery occupies dominant shelf position for box-packaged formats, with buyers recalibrating assortment criteria around protein content thresholds rather than ingredient novelty. North American chains have expanded permanent plant-based pasta sections.
- Online Retail:Customizable subscription boxes with rotating legume bases bypass conventional slotting fees and enable data-driven flavor testing. This channel shows steepest expansion trajectory as direct-to-consumer logistics mature.
- Health Stores:Curated assortments prioritize single-ingredient organic lentil and pea pastas with limited distribution footprints.
- Specialty Stores:Italian and Mediterranean importers sustain premium positioning for artisanal whole wheat and legume blends.
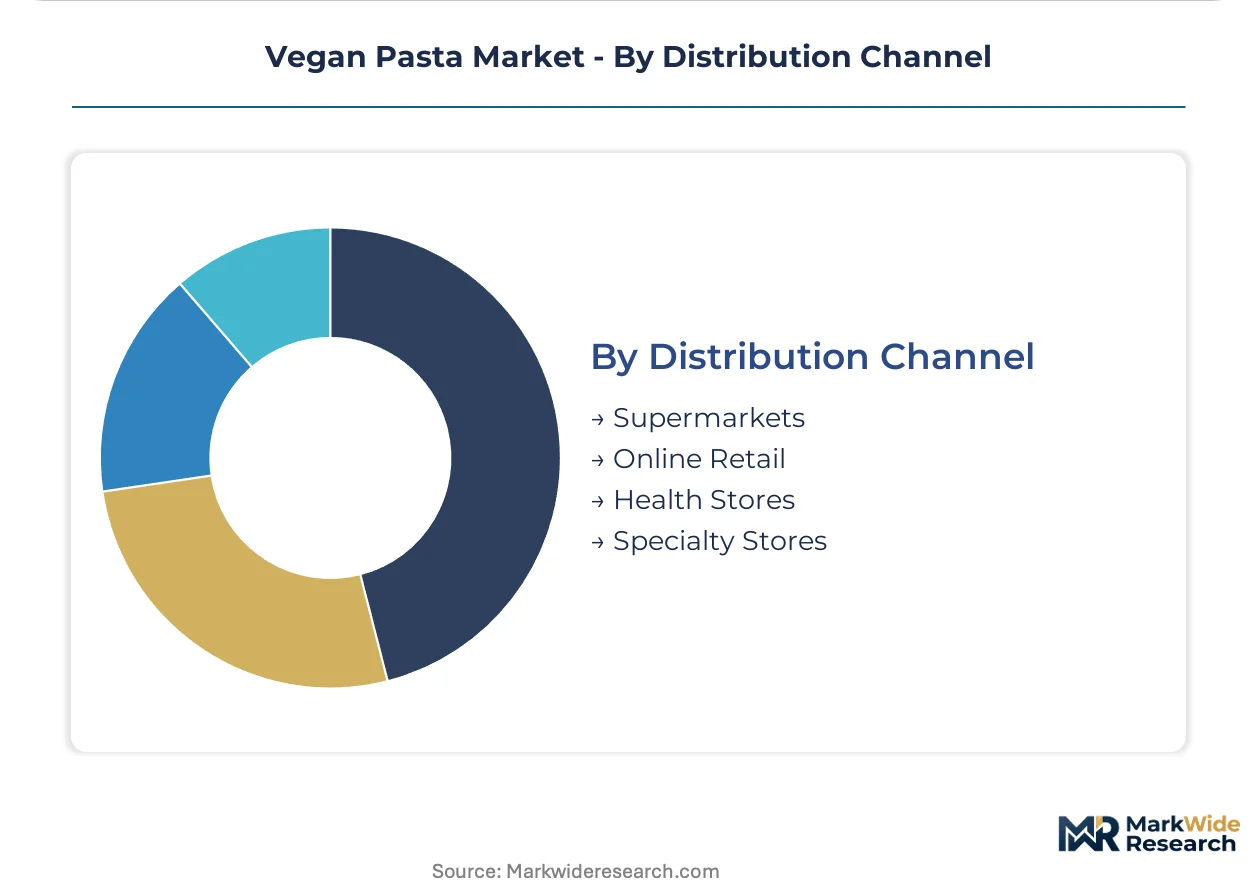
Supermarkets anchor current volume, with online retail climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian food technologists and German supply chain engineers anchor the industry's technical workforce concentration. Their expertise in durum rheology and pulse protein chemistry underpins regional manufacturing advantages. Migration patterns favor Emilia-Romagna and Baden-Württemberg as talent magnets.
Germany
Retail buyers at Edeka and REWE chains recalibrated shelf placement criteria around protein density thresholds. The EU Green Deal's farm-to-fork traceability mandates accelerate certified organic procurement timelines. Pulse processing clusters in Lower Saxony secure direct contracts with Canadian lentil suppliers, bypassing fragmented trader networks.
Italy
Barilla Group and De Cecco sustain premium positioning through milling heritage and high-shear extrusion capabilities. EFSA guidelines on durum wheat-alternative labeling shape formulation disclosure requirements. Emilia-Romagna manufacturers dominate spaghetti and penne production for German supermarket private-label programs.
United States
Urban foodservice operators in New York and Los Angeles dedicate permanent menu sections to plant-based pasta dishes. FDA Food Safety Modernization Act rules govern ingredient traceability for multi-origin legume supply chains. Chickpea-dense formulations from midwestern extrusion facilities supply bulk procurement contracts for restaurant chains.
Canada
Pulse crop processors in Saskatchewan and Manitoba face price volatility from Australian harvest fluctuations transmitting into raw material costs. Canadian Food Inspection Agency organic certification timelines extend documentation requirements for export-bound legume flour. Prairie milling clusters supply German and Italian manufacturers with single-ingredient organic lentil bases.
India
Tier-1 metropolitan health stores in Mumbai and Bangalore remain underpenetrated by imported legume pasta brands despite rising plant-based protein demand. FSSAI labeling standards for gluten-free claims create compliance friction for foreign entrants. Domestic quinoa-konjac hybrid development in Karnataka targets diabetic dietary protocols with ultra-low glycemic index positioning.
Vegan Pasta Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent scale thresholds. Italian milling conglomerates and North American pulse specialists occupy distinct tiers, with mid-cap organic formulators squeezed between them. Three archetypes dominate: heritage millers leveraging regional brand equity, chickpea-protein disruptors competing on macronutrient density, and single-ingredient organic specialists with limited distribution footprints. Capacity expansion and direct-to-retail procurement compression represent the dominant competitive vectors.
Among heritage-anchored Italian producers, Barilla Group and F.lli De Cecco di Filippo S.p.A. exemplify milling-centric positioning sustained through extrusion technology control and supermarket shelf-space dominance. Banza Inc. represents the North American protein-density disruptor archetype, while Tolerant Organics occupies the single-ingredient organic specialist tier with constrained geographic reach. These three entities illustrate how technical moats in pulse protein retention and al dente texture achievement separate scalable competitors from artisanal formulators.
| Leading Market Players |
|---|
| DeLallo Company |
| Tolerant Organics |
| Barilla Group |
| Bionaturae LLC |
| Windmill Organics |
| Nestlé S.A. |
| Banza Inc. |
| TreeHouse Foods Inc. |
| F.lli De Cecco di Filippo S.p.A. |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's farm-to-fork traceability mandates gate qualified supply for premium-tier vegan pasta, compressing procurement timelines for certified organic legume bases while elevating price floors for compliant manufacturers. Retail buyers at German chains now demand 18-24 month documentation cycles that disqualify fragmented trader networks from shelf placement.
Pricing Analysis
Certification-bundled versus unbundled ingredient sourcing splits pricing tiers across the vegan pasta landscape. Three-tier pricing structure across premium, standard, and economy levels reflects USDA organic certification status and protein retention thresholds above 20%. Price differentiation hinges on single-origin traceability and high-shear extrusion capability. Cost compression in mid-tier whole wheat alternatives is intensifying because Italian milling conglomerates are absorbing slotting fee burdens to defend supermarket facings. Foodservice operators show lowest price sensitivity, while conventional retail buyers in North American urban centers negotiate hardest on volume contracts.
Supply Chain Analysis
Regional distribution centers in Lower Saxony and Emilia-Romagna anchor hub-and-spoke patterns for European vegan pasta fulfillment. Manufacturing concentrates in Italy, Germany, and Canada, with prairie milling clusters in Saskatchewan feeding German supermarket private-label programs. Raw material flows draw from Turkish lentil processors, Canadian pea flour mills, and Australian pulse traders. Single-source vulnerability concentrates in Italian and Swiss high-shear extrusion equipment suppliers controlling 80% of specialized machinery. Distribution runs through vertically integrated pulse processors that consolidated milling, extrusion, and packaging under single facility roofs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between German retail procurement compression and Indian tier-1 metropolitan underpenetration, where FSSAI compliance costs for foreign entrants run substantially below EU organic certification timelines.
For Market Incumbents: Deploy backward integration into Canadian pulse milling to secure 18-24 month traceability documentation ahead of USDA organic deadlines. Barilla Group and De Cecco should expand high-shear extrusion capacity in Emilia-Romagna to capture German private-label contract shifts away from fragmented ingredient traders. Certification investment in EU organic tiers defends margin position against chickpea-protein disruptors competing on macronutrient density alone. For New Entrants and Emerging Players: The EU F-Gas Regulation in Germany opens a window for ammonia-based refrigeration retrofit partnerships with Dutch processing facilities seeking compliance ahead of EU-wide mandates. Target Mumbai and Bangalore health stores with vacuum-sealed formats that bypass humid-climate spoilage risks. Direct-to-subscription channels with rotating legume bases offer the cleanest go-to-market angle, circumventing supermarket slotting fee structures entirely. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap organic formulators because procurement compression at German retail chains is displacing independent brands faster than they can self-integrate. Acquire single-ingredient organic specialists with captive Canadian or Turkish pulse supply contracts. Watch for inflection when Canadian harvest volatility transmits into sustained lentil price premiums that force consolidation among unhedged artisanal producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulse Milling | Captive supply of Canadian lentil flour secures 18-24 month USDA organic traceability documentation. |
| High-Shear Extrusion Capacity Expansion | Emilia-Romagna facility additions capture German supermarket private-label contract migration. |
| Ammonia Refrigeration Retrofit Partnership | Dutch processing compliance with EU F-Gas Regulation ahead of continental deadlines. |
| Direct-to-Subscription Channel Launch | Rotating legume bases bypass conventional supermarket slotting fee structures. |
| Single-Ingredient Organic Specialist Acquisition | Turkish and Canadian pulse supply contracts accelerate procurement compression timelines. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Italian food technologists, German supply chain engineers, North American foodservice procurement directors, Canadian pulse processors, and Indian health store category managers with secondary validation. Trade data from customs records, EU organic certification databases, FSSAI filing registries, and supermarket shelf-audit datasets anchored volume estimates. Bottom-up facility capacity assessments and top-down retail velocity figures were triangulated against ingredient flow documentation.
Segment-weighting across product type, ingredient source, packaging format, and distribution channel dimensions shaped the analytical framework over the projection horizon. Spaghetti and penne SKUs received volume-weighted treatment reflecting German and Italian retail procurement patterns. CAGRs were derived from protein density threshold trajectories and clean-label buyer recalibration trends. Pulse crop price volatility indices and extrusion equipment utilization rates fed industry-specific forecast inputs.
Revisions become necessary when Canadian or Australian harvest fluctuations transmit into sustained raw material cost instability, when EU F-Gas Regulation implementation timelines accelerate, or when FDA protein content disclosure requirements tighten. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Dandelion Root Extract Market
Plant Based Food
South America Soy Beverages Market
Plant Based Food
Vegan Tortillas Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Global Plant Protein Market
Plant Based Food
Vegan Chocolate Market
Plant Based Food
Oat Protein Market
Plant Based Food
Vegan Dips Market
Plant Based Food
Plant-Based Meatballs Market
Plant Based Food
United Kingdom Plant Protein Market
Plant Based Food
Plant Based Protein Market
Plant Based Food
Flax-Based Protein Market
Plant Based Food
Vegan Protein Foods Market
Plant Based Food
Oat-Based Cereals Market
Plant Based Food
Plant-Based Margarine Market
Plant Based Food
Plant-Based Food and Beverages Market