
 Vegan Meals Market | 2026-2036
Vegan Meals Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Meals Market Analytics
North American production capacity for plant-protein extrusion is reshaping supply dynamics across the vegan meals sector. Beyond Meat leverages its domestic manufacturing footprint to sustain price competitiveness in retail frozen aisles. Impossible Foods anchors its position through heme-fermentation technology leadership. Amy's Kitchen differentiates via certified organic supply chains and frozen entree specialization.
Vegan meals comprise prepared food products containing no animal-derived ingredients, typically formulated with protein isolates from soy, pea, or wheat gluten and processed through high-moisture extrusion or fermentation to replicate meat textures. These products serve retail consumers and foodservice operators seeking alternatives to animal-based proteins. Frozen meals currently occupy the largest margin pool due to premium pricing and extended shelf stability. Meal kits represent the fastest-growing product type as direct-to-consumer subscription models expand. Online retailers are displacing conventional supermarkets for initial trial purchases among flexitarian consumers.
The FDA governs labeling standards for plant-based protein claims in the United States, while the USDA oversees organic certification requirements that many vegan meal producers pursue. In Europe, EFSA evaluates novel protein safety and the EU Green Deal shapes agricultural sourcing mandates for climate disclosures. Stakeholders must monitor evolving allergen thresholds for pea and mung bean proteins as formulation diversity expands beyond legacy soy bases.
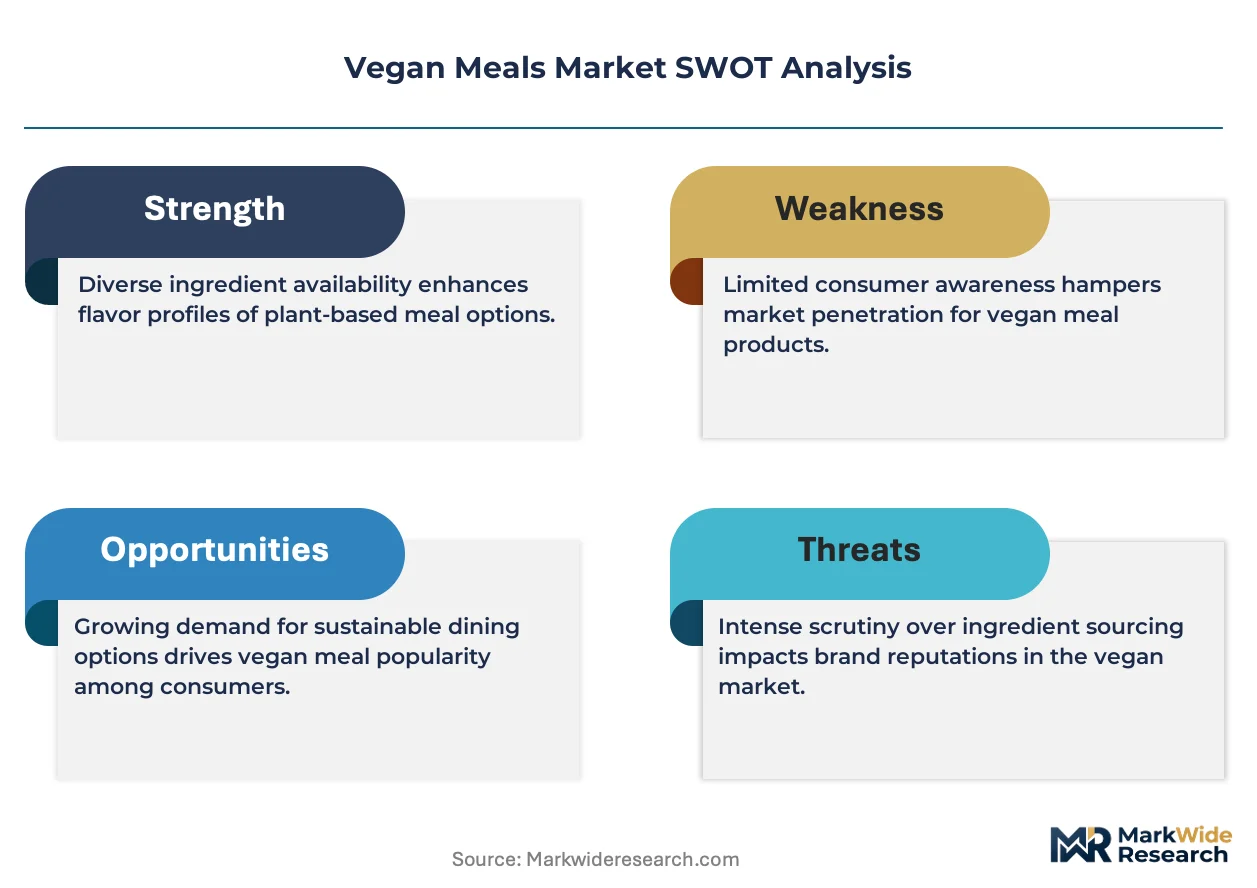
Market Dynamics
High-moisture extrusion capacity concentration in the United States and Germany is redrawing competitive boundaries as legacy soy-isolate supply chains face displacement by pea and mung bean protein networks.
Growth Catalysts
- EU Green Deal sourcing mandates:Climate disclosure requirements for agricultural inputs are compelling food manufacturers to reformulate with traceable plant proteins, accelerating certified supply chain development across European retail.
- Quick-service restaurant expansion:North American chains are embedding plant-based entrees into permanent menu architecture, creating institutional demand pull that stabilizes volume commitments for extrusion facilities.
- Heme-fermentation maturation:Precision fermentation infrastructure is achieving cost parity with conventional flavor systems, enabling sensory replication that converts skeptical flexitarian households.
Market Restraints
- Pea protein price volatility:Concentrated cultivation in Canada and France exposes formulations to weather-driven input cost swings that compress margin structures for mid-tier producers.
- EFSA novel protein evaluation timelines:Extended safety assessment windows for emerging protein sources delay product launches by 18-36 months, freezing formulation pipelines.
- Conventional frozen meal substitution:Price-sensitive retail segments retain loyalty to legacy vegetarian options that undercut premium-positioned vegan alternatives on shelf.
Strategic Opportunities
- German retail shelf expansion:Major supermarket chains have doubled refrigerated vegan protein space, creating physical distribution access that supports brand-building investments.
- Direct-to-consumer meal kit channels:Subscription models bypass conventional retail slotting fees while capturing trial behavior among urban flexitarian households.
- USDA organic certification differentiation:Certified organic supply chains command pricing premiums in frozen entree segments where ingredient provenance drives purchase decisions.
Industry Challenges
- Extrusion engineering talent scarcity:Specialized high-moisture extrusion expertise concentrates within a narrow pool of equipment manufacturers and research institutions, constraining facility expansion timelines.
- Allergen threshold harmonization:Divergent regulatory thresholds for pea and mung bean protein labeling across jurisdictions complicate unified product specifications for multinational portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Meals Market |
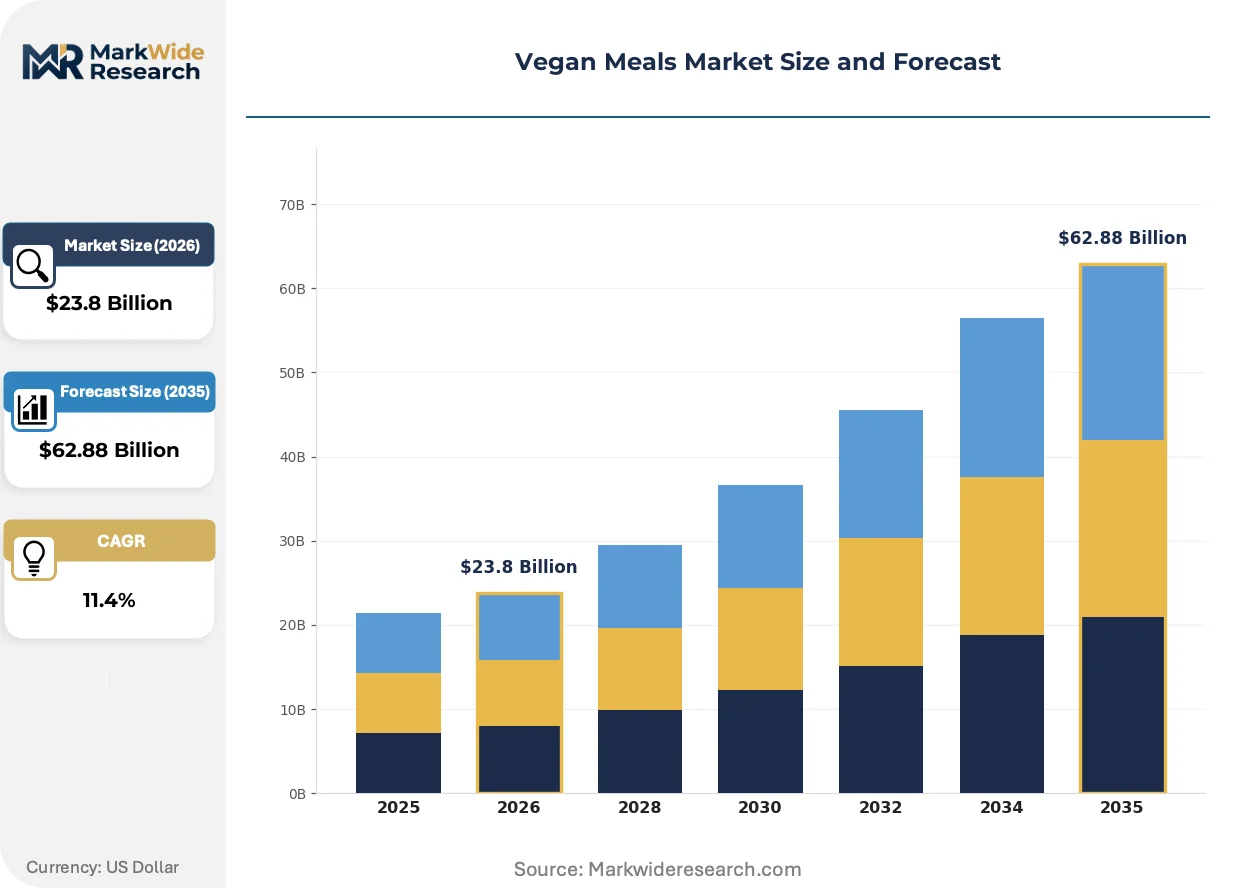
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $62.88 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Meals, Snacks, Sauces, Meal Kits Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Food Service Target Consumer: Health Conscious, Environmentally Friendly, Ethically Minded, Flexitarians Cuisine Type: Italian, Asian, Mediterranean, Mexican |
| Companies Covered | Amy's Kitchen, Beyond Meat, Danone S.A., Hain Celestial Group, SunOpta, Daiya Foods, Tofutti Brands, Impossible Foods, Conagra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Meals Market Evolving Landscape
Precision fermentation and advanced extrusion architectures are compressing the sensory gap between plant-based and animal-derived proteins while regulatory frameworks accelerate supply chain transparency mandates.
Whole-cut muscle analogs produced through directional fiber alignment technology are rendering obsolete the ground-meat format dominance that defined early vegan meal categories. Foodservice operators in the United Kingdom and Netherlands are piloting these structures for center-plate positioning. The shift is compressing R&D timelines as texture parity becomes the baseline expectation rather than premium positioning.
The EU Green Deal's Farm to Fork Strategy is tightening environmental labeling requirements that force disclosure of agricultural sourcing emissions and water intensity. German and French retailers are demanding blockchain-traceable ingredient documentation from suppliers. Frozen meal producers are responding by consolidating procurement around certified low-carbon protein sources that satisfy audit protocols.
Flexitarian consumers are fragmenting trial behavior across digital channels rather than committing to supermarket aisle exploration. Online retailers in urban United States markets are capturing initial purchase decisions through algorithmic recommendation engines that displace traditional brand loyalty. Subscription meal kit services in California and New York metropolitan clusters are converting these trials into recurring revenue through portion-controlled convenience positioning.
Vegan Meals Market Segmentation
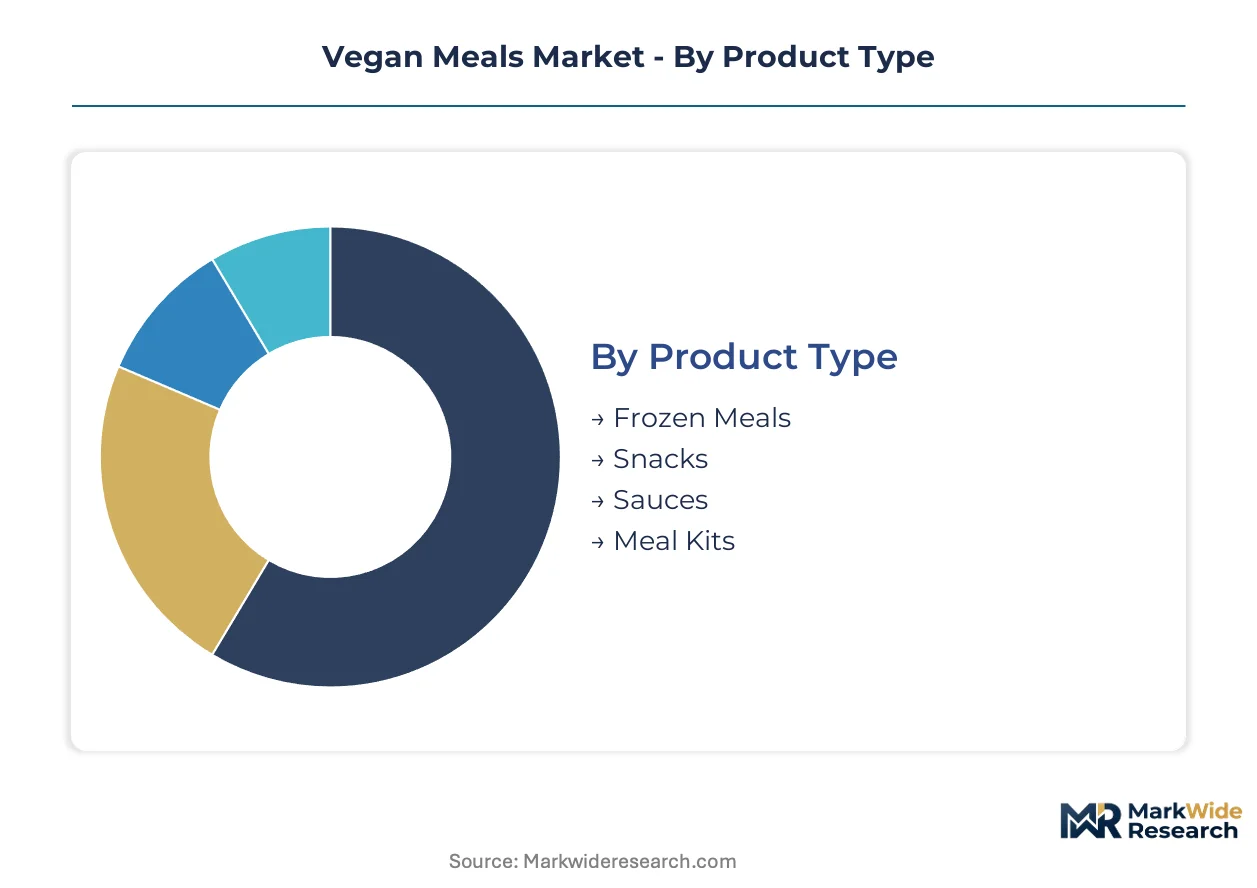
Segmentation in the vegan meals sector reveals how formulation technology, channel access, and consumer motivation intersect to determine margin capture. Manufacturers must align extrusion capabilities with distribution economics and certification requirements to optimize portfolio positioning.
Product Type:
Cost tier differentiation separates premium-positioned formats from mass-market alternatives, with processing complexity and shelf stability driving margin structures across each category.
- Frozen Meals:High-moisture extrusion products packaged for extended retail distribution. Demand concentrates in German supermarket chains where refrigerated shelf space expansion supports premium pricing for whole-cut muscle analogs.
- Meal Kits:Portion-controlled ingredient bundles delivered through subscription models. Direct-to-consumer channels in California and New York metropolitan clusters capture trial behavior among urban flexitarian households seeking convenience without supermarket navigation.
- Snacks:Shelf-stable protein isolates formulated for grab-and-positioning in convenience retail.
- Sauces:Fermentation-derived flavor systems packaged as complementary meal components.
Frozen meals command the established base. The steepest expansion runs through meal kits.
Distribution Channel:
Application context determines channel viability, with institutional foodservice contracts requiring volume scale that diverges from retail trial economics.
- Online Retailers:Algorithmic recommendation engines displace traditional brand loyalty in initial purchase decisions. Urban United States markets show concentrated activity where flexitarian consumers fragment trial behavior across digital platforms rather than committing to supermarket aisle exploration.
- Food Service:Quick-service restaurant chains embed plant-based entrees into permanent menu architecture. North American institutional demand stabilizes volume commitments for extrusion facilities seeking production certainty.
- Supermarkets:Conventional retail slotting fees burden new entrants competing for freezer aisle positioning.
- Health Food Stores:Certified organic supply chains find concentrated demand among provenance-driven purchasers.
Supermarkets retain the volume foundation. Online retailers are climbing the fastest as trial migration accelerates.
Target Consumer:
Customer type segmentation isolates purchasing motivation, with ethical positioning commanding pricing premiums that health-functional claims cannot sustain.
- Flexitarians:Households reducing animal protein without eliminating it entirely. Algorithm-driven discovery in United States urban markets converts these consumers through convenience-positioned meal kits that bypass ideological commitment requirements.
- Environmentally Friendly:Purchasers prioritizing carbon footprint disclosure and blockchain-traceable sourcing. EU Green Deal climate labeling mandates in Germany and France concentrate demand for certified low-carbon protein documentation.
- Health Conscious:Consumers responding to nutritional density claims and allergen management.
- Ethically Minded:Buyers motivated by animal welfare certification and supply chain transparency.
Health-conscious consumers provide the volume anchor. Environmentally motivated purchasers are expanding most quickly as disclosure requirements tighten.
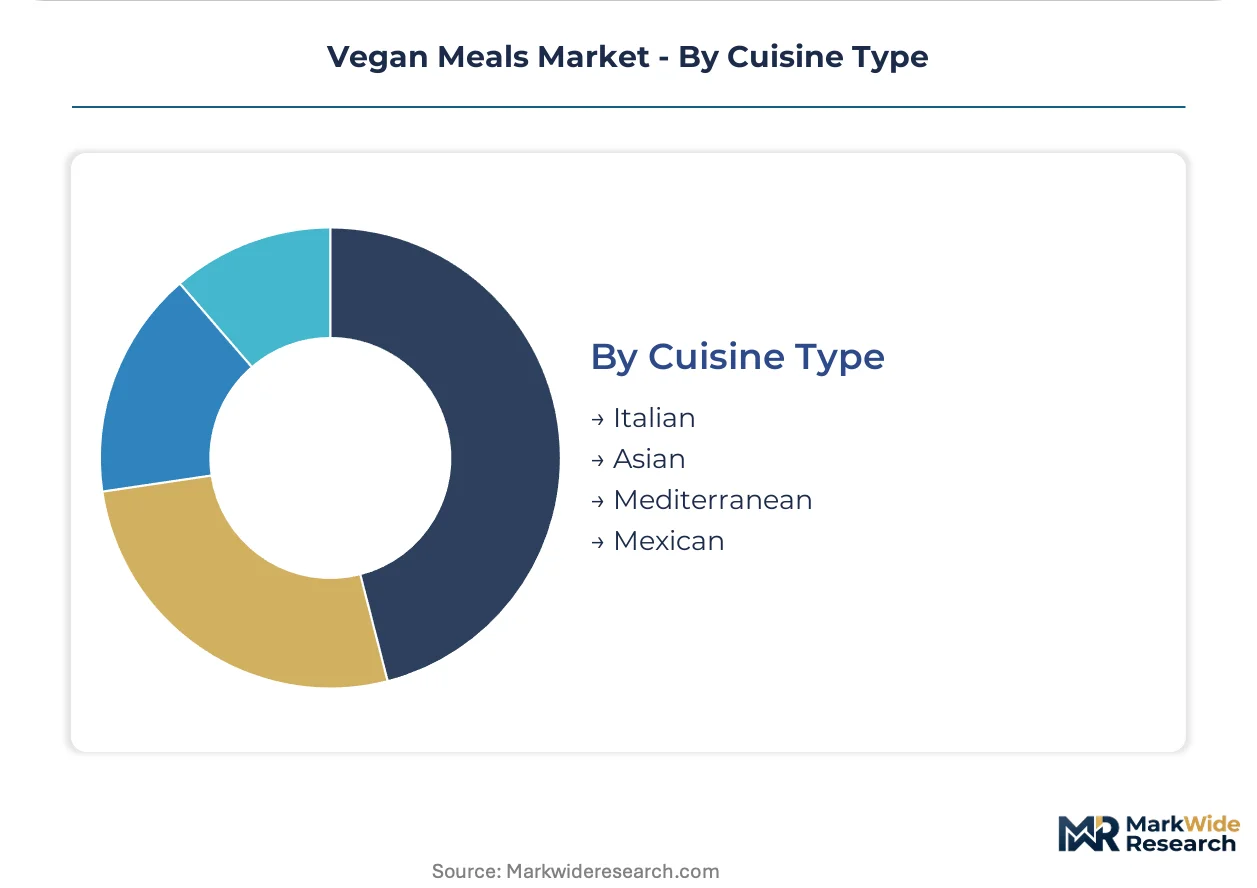
Cuisine Type:
Geographic flavor profiles align with established plant-protein formulation strengths, with extrusion technology adapting to regional texture expectations.
- Asian:Mung bean and soy isolate formulations replicate traditional protein textures. Demand concentrates in metropolitan clusters where fermentation-derived flavor systems achieve sensory parity with conventional preparations.
- Mediterranean:Chickpea and wheat gluten bases align with established regional ingredient familiarity. European retail expansion supports brand-building investments as shelf space allocation shifts toward refrigerated protein alternatives.
- Italian:Tomato-forward formulations leverage existing supply chain infrastructure for sauce integration.
- Mexican:Spice-forward flavor masking accommodates textural variance in emerging protein isolates.
Mediterranean offerings hold the established position. Asian cuisine formats are gaining share fastest as precision fermentation matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA labeling standards for plant-based protein claims anchor the United States regulatory environment, while EFSA novel protein safety assessments and EU Green Deal sourcing mandates reshape European formulation requirements. National regulators across Germany, France, and the United Kingdom are tightening climate disclosure protocols for agricultural inputs.
United States
Quick-service restaurant chains embed plant-based entrees into permanent menu architecture, creating institutional demand pull for extrusion facilities. The FDA governs labeling standards for plant-based protein claims while the USDA oversees organic certification requirements. California and New York metropolitan clusters concentrate direct-to-consumer meal kit subscription activity among urban flexitarian households.
Germany
Major supermarket chains have doubled refrigerated vegan protein shelf space, creating physical distribution access for premium-positioned whole-cut muscle analogs. The EU Green Deal's Farm to Fork Strategy tightens environmental labeling requirements for food products. Berlin and Hamburg anchor retail expansion as blockchain-traceable ingredient documentation becomes mandatory for supplier qualification.
France
Pea protein cultivation concentration exposes formulations to weather-driven input cost swings that compress margin structures. EFSA evaluates novel protein safety with extended assessment windows that delay product launches. Paris and Lyon metropolitan areas concentrate foodservice pilot programs for directional fiber alignment technology in center-plate positioning.
United Kingdom
Foodservice operators pilot whole-cut muscle analogs produced through directional fiber alignment technology for center-plate positioning. The EU Green Deal shapes agricultural sourcing mandates for climate disclosures despite post-Brexit regulatory divergence. London anchors algorithmic recommendation engine deployment among online retailers capturing initial purchase decisions from flexitarian consumers.
Canada
Pea protein cultivation concentration in prairie provinces exposes North American formulations to weather-driven supply volatility. Health Canada and PMRA evaluate novel ingredient safety for plant-protein isolates entering retail distribution. Ontario and British Columbia concentrate high-moisture extrusion capacity expansion as legacy soy-isolate supply chains face displacement.
Vegan Meals Market Competitive Landscape
Precision-fermentation specialists and high-moisture extrusion operators split the market between sensory-replication technology and manufacturing-scale production. The vendor base concentrates around three strategic archetypes: heme-fermentation technology leaders, certified organic supply chain specialists, and direct-to-consumer subscription model operators. Competitive moves center on strategic partnerships with quick-service restaurant chains and backward integration into captive protein isolate supply.
Within the precision-fermentation tier, Impossible Foods exemplifies heme-fermentation technology leadership, while Beyond Meat occupies a position as a domestic manufacturing footprint anchor. Amy's Kitchen represents the certified organic supply chain specialist archetype. These three companies illustrate how formulation technology differentiation and distribution channel access determine competitive positioning across frozen retail and foodservice segments.
| Leading Market Players |
|---|
| Amy's Kitchen |
| Beyond Meat |
| Danone S.A. |
| Hain Celestial Group |
| SunOpta |
| Daiya Foods |
| Tofutti Brands |
| Impossible Foods |
| Conagra |
| Others |
Value Network & Pricing Analysis
Canadian pea protein cultivation concentration in prairie provinces funnels margin capture toward extrusion facility operators in Ontario and British Columbia, while weather-driven input volatility compresses returns for mid-tier frozen meal producers lacking long-term offtake agreements.
Pricing Analysis
United States retail pricing for frozen vegan meals commands a premium over European shelf equivalents, reflecting USDA organic certification tiering and extended cold-chain logistics costs. Three-tier pricing structure across premium, standard, and economy levels separates certified organic whole-cut analogs from conventional extruded formats. Cost compression in the standard tier is intensifying because pea protein price swings transmit directly into formulation budgets. Flexitarian households in California metropolitan clusters show least price sensitivity, while mass-market supermarket segments in the Midwest retain loyalty to legacy vegetarian options.
Supply Chain Analysis
Extended payment terms from German supermarket chains now reach ninety days, forcing protein isolate suppliers to absorb working capital strain or seek supply-chain finance facilities. Raw material sourcing draws from Canadian pea cultivation, French mung bean networks, and domestic soy processing in the United States. Single-source vulnerability concentrates in high-moisture extrusion equipment manufacturers based in Germany and the United States. Distribution runs through direct-to-consumer subscription channels in coastal metropolitan clusters alongside conventional retail freezer aisles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from precision-fermentation entrants achieving cost parity with conventional flavor systems, eroding the sensory differentiation that once protected extrusion-based market positions.
For Market Incumbents: Entrench position through backward integration into captive pea protein cultivation in Canadian prairie provinces and accelerated heme-fermentation R&D investment. Lock in multi-year quick-service restaurant contracts to stabilize volume commitments against emerging precision-fermentation competitors. USDA organic certification renewal cycles present a defensive moat against mid-tier private-label encroachment. For New Entrants and Emerging Players: Direct-to-consumer meal kit subscriptions in New York and California metropolitan clusters represent the most penetrable entry point, bypassing retail slotting fees that burden freezer aisle competition. Blockchain-traceable ingredient documentation for EU Green Deal compliance opens German supermarket shelf access where refrigerated space has doubled. Target flexitarian households seeking convenience without ideological commitment through algorithmic discovery platforms. For Investors and Strategic Acquirers: Capital is best deployed toward precision-fermentation technology leaders with validated sensory replication and contracted quick-service restaurant pilots. Long-term viability hinges on achieving cost parity with extrusion-based production across the projection horizon. Watch for EFSA novel protein approval acceleration as the inflection signal indicating formulation pipeline thaw.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Protein Isolate Supply | Captive pea and mung bean sourcing insulates margins from Canadian weather volatility. |
| Precision Fermentation Scale-Up | Heme-fermentation cost parity converts skeptical flexitarian households in United States urban markets. |
| EU Green Deal Compliance Certification | Blockchain-traceable documentation unlocks German supermarket shelf expansion for premium positioning. |
| Quick-Service Restaurant Partnership | Institutional volume commitments stabilize utilization rates for high-moisture extrusion facilities. |
| Direct-to-Consumer Channel Launch | Subscription models capture trial behavior among California and New York metropolitan flexitarians. |
Research Methodology
Desk research of FDA labeling guidance documents, EFSA novel protein safety assessments, and EU Green Deal regulatory filings preceded structured interviews with high-moisture extrusion equipment manufacturers, plant-based protein procurement leads at quick-service restaurant chains, and category buyers at German supermarket chains. Secondary validation drew from USDA organic certification databases, Canadian agricultural statistics, and trade flow records for pea protein isolates. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Assumptions held fixed include EFSA evaluation timelines for novel proteins and EU climate disclosure implementation schedules, while pea protein price volatility and quick-service restaurant adoption curves were varied across scenarios. Segmentation dimensions modeled encompass product type, distribution channel, target consumer motivation, and cuisine format. CAGRs were derived from regression analysis of historical expansion patterns and elasticity estimates for flexitarian trial conversion. Forecast inputs incorporated extrusion capacity buildout timelines and precision fermentation cost curves.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, trade tariff regimes, or consumer disposable income trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory approval timelines and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
Plant Based Pasta Market
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Vegan Flour Market
Plant Based Food
Dandelion Root Extract Market
Plant Based Food
India Pea Protein Market
Plant Based Food
Europe Plant-Based Food and Beverage Market
Plant Based Food
Oat-Based Cereals Market
Plant Based Food
United Kingdom Plant Protein Market
Plant Based Food
Plant Based Collagen Market
Plant Based Food
Plant-Based Flour Market
Plant Based Food
Middle East and Africa Plant-Based Egg Market
Plant Based Food
North America Tofu Market
Plant Based Food
Fermented Plant-Based Food Market
Plant Based Food
Vegan Chocolate Market
Plant Based Food
Plant-Based Nuggets Market