
 Plant Based Meal Kit Market | 2026-2036
Plant Based Meal Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Meal Kit Market Analytics
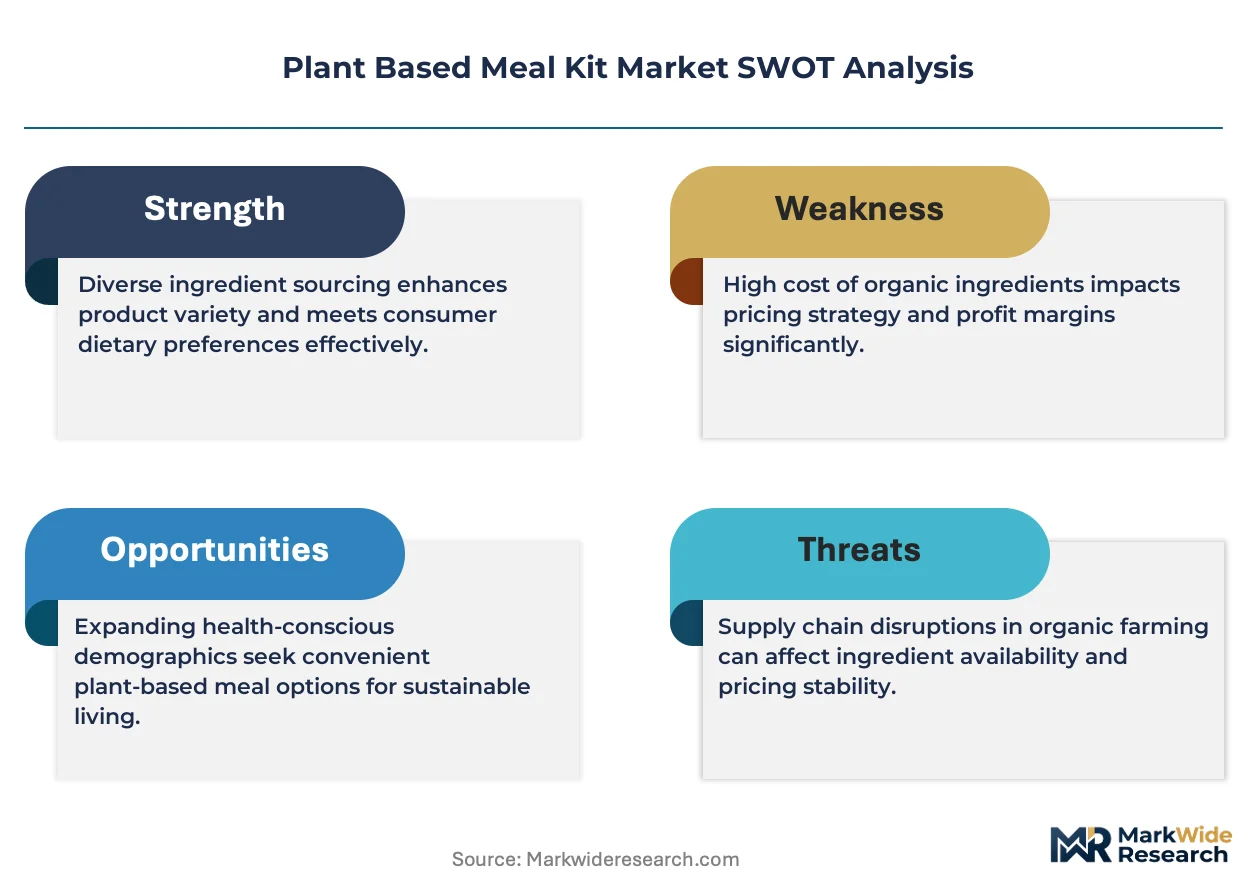
The capital-intensity divergence between in-house culinary development and third-party recipe outsourcing is bifurcating competitive posture across the industry. Purple Carrot sustains its position through dedicated vegan recipe laboratories and proprietary chef networks. HelloFresh leverages its continental fulfillment infrastructure to anchor cost efficiency in ready-to-cook assembly. Green Chef differentiates through certified organic ingredient procurement and allergen-controlled production protocols.
Plant based meal kits constitute pre-portioned ingredient bundles and fully prepared plant-derived meals designed for residential or light commercial preparation, typically requiring refrigeration and delivering within a seven-day consumption window to preserve nutritional integrity and flavor profiles. The category serves time-constrained consumers seeking reduced food waste and structured dietary adherence without conventional animal protein dependence. Ready-to-cook kits dominate volume throughput due to lower per-unit logistics cost and extended shelf stability, while ready-to-eat kits capture premium margin pools among urban professionals with minimal kitchen access. Online retail channels control subscriber acquisition economics, though supermarkets increasingly occupy fulfillment partnerships as click-and-collect infrastructure matures.
The FDA oversees allergen labeling and nutritional disclosure requirements that shape product formulation transparency across domestic supply chains, while the USDA administers organic certification pathways that influence ingredient sourcing premiums and supplier qualification. The EU Green Deal and REACH frameworks govern cross-border ingredient sustainability claims and packaging material restrictions for European market participants. Stakeholders must monitor evolving carbon accounting mandates and state-level extended producer responsibility laws that will determine which fulfillment models retain structural viability.
Market Dynamics
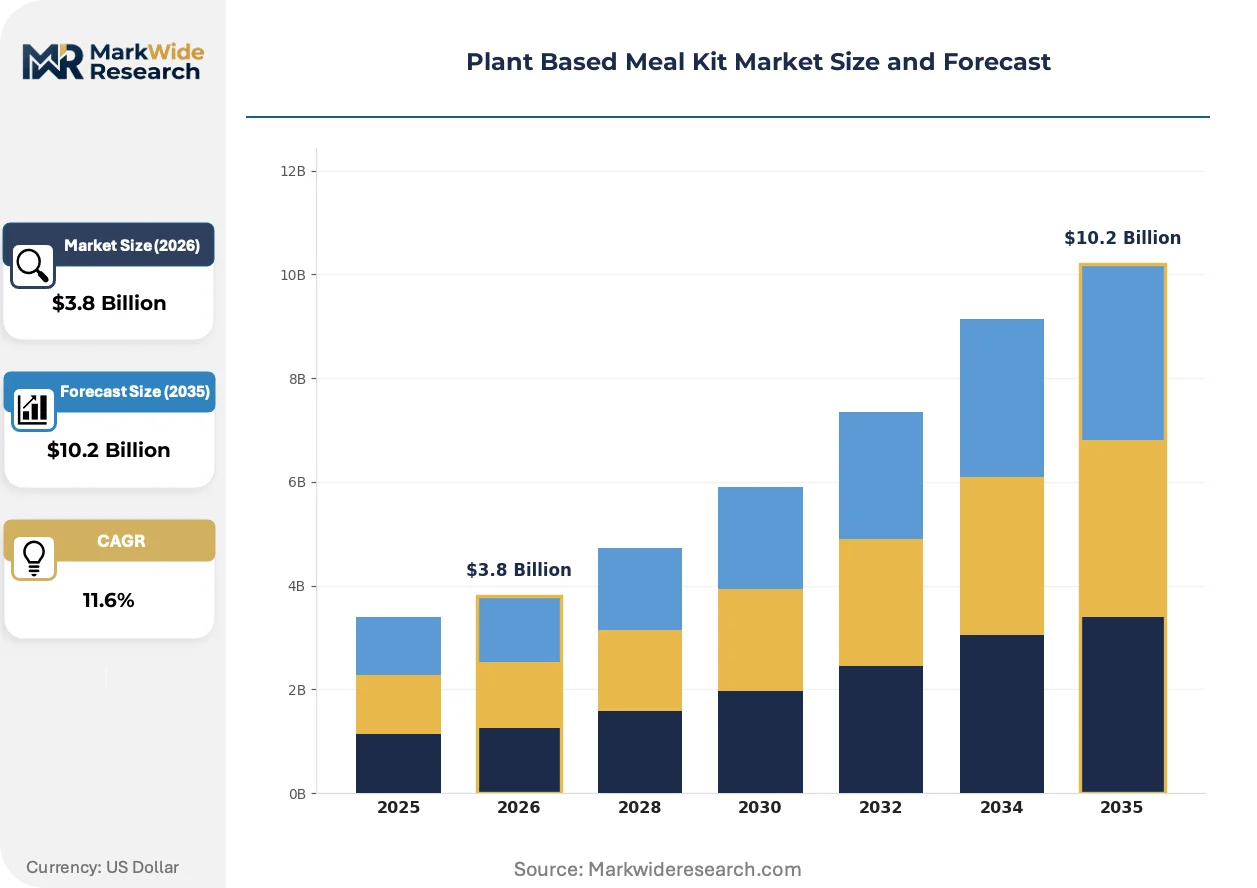
Subscription density in the United States is concentrating fulfillment infrastructure around direct-to-consumer cold chain networks, while the EU Green Deal is forcing ingredient sourcing transparency that raises compliance costs for cross-border suppliers.
Growth Catalysts
- EU Green Deal procurement standards:European supply chains must document carbon intensity across agricultural inputs, creating certified demand for regenerative-sourced legumes and grains that command sourcing premiums.
- Flexitarian household penetration:Urban centers in the United States show the deepest subscription density as time-constrained consumers seek structured dietary adherence without full vegan commitment.
- Refrigerated last-mile technology:Seven-day cold chain preservation systems now enable wider delivery radii from central kitchens, expanding addressable households beyond traditional metro corridors.
Market Restraints
- Perishable input cost volatility:Organic produce and specialty plant proteins face weather-driven price swings that compress margin predictability for ready-to-cook assembly models.
- Supplier concentration in organic certification:USDA-accredited organic ingredient sources cluster in California and the Pacific Northwest, creating geographic vulnerability to climate disruption.
- Technical limitation in extended shelf stability:Clean-label preservation without synthetic additives constrains ready-to-eat kit distribution to premium courier networks.
Strategic Opportunities
- Underpenetrated secondary United States metros:Cities with populations between 500,000 and 2 million lack dedicated plant-based meal kit fulfillment nodes, representing white space for regional hub deployment.
- Supermarket click-and-collect partnerships:Grocery chains are building refrigerated pickup infrastructure that can absorb last-mile costs from pure-play subscription models.
- IRA clean energy incentives:Domestic solar-powered cold storage facilities qualify for tax credits that reduce per-unit refrigeration overhead in southwestern United States distribution centers.
Industry Challenges
- Culinary R&D talent scarcity:Recipe development for allergen-controlled, certified organic menus requires hybrid food science and chef training that outpaces current vocational pipeline output.
- Capex intensity in captive production:In-house culinary laboratories and proprietary chef networks demand facility investments that strain mid-tier operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Meal Kit Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Cook Kits, Ready-to-Eat Kits, Snack Kits, Specialty Kits Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Customer Segment: Vegetarians, Vegans, Health-Conscious Consumers, Environmental Advocates Meal Type: Breakfast, Lunch, Dinner, Snacks |
| Companies Covered | Purple Carrot, Green Chef, HelloFresh, Blue Apron, Home Chef, Fresh n' Lean, Sun Basket, Sakara Life, Daily Harvest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Meal Kit Market Evolving Landscape
Active packaging technologies and carbon accounting protocols are restructuring how plant-based meal kits demonstrate value beyond convenience, shifting competitive differentiation toward verifiable sustainability claims.
Modified atmosphere packaging with plant-derived oxygen scavengers is bifurcating shelf-life extension strategies. Premium ready-to-eat kits in the United States are adopting cellulose-based barrier films that extend consumption windows to ten days. This technology is compressing the advantage of frozen alternatives while enabling broader distribution radii from single production facilities.
The EU Green Deal's carbon border adjustment mechanism is reshaping cross-border ingredient sourcing. European suppliers must now provide lifecycle emissions documentation for imported specialty proteins and exotic produce. Ready-to-cook kit assemblers with continental European fulfillment footprints are consolidating supplier bases to reduce documentation complexity and customs friction.
Subscription fatigue among urban professionals is fragmenting commitment patterns. Single-purchase trial formats through supermarket partnerships are displacing annual commitments in the United States coastal metros. This behavioral shift is most visible in New York and San Francisco, where flexible cancellation policies now drive acquisition economics more than price discounting.
Plant Based Meal Kit Market Segmentation
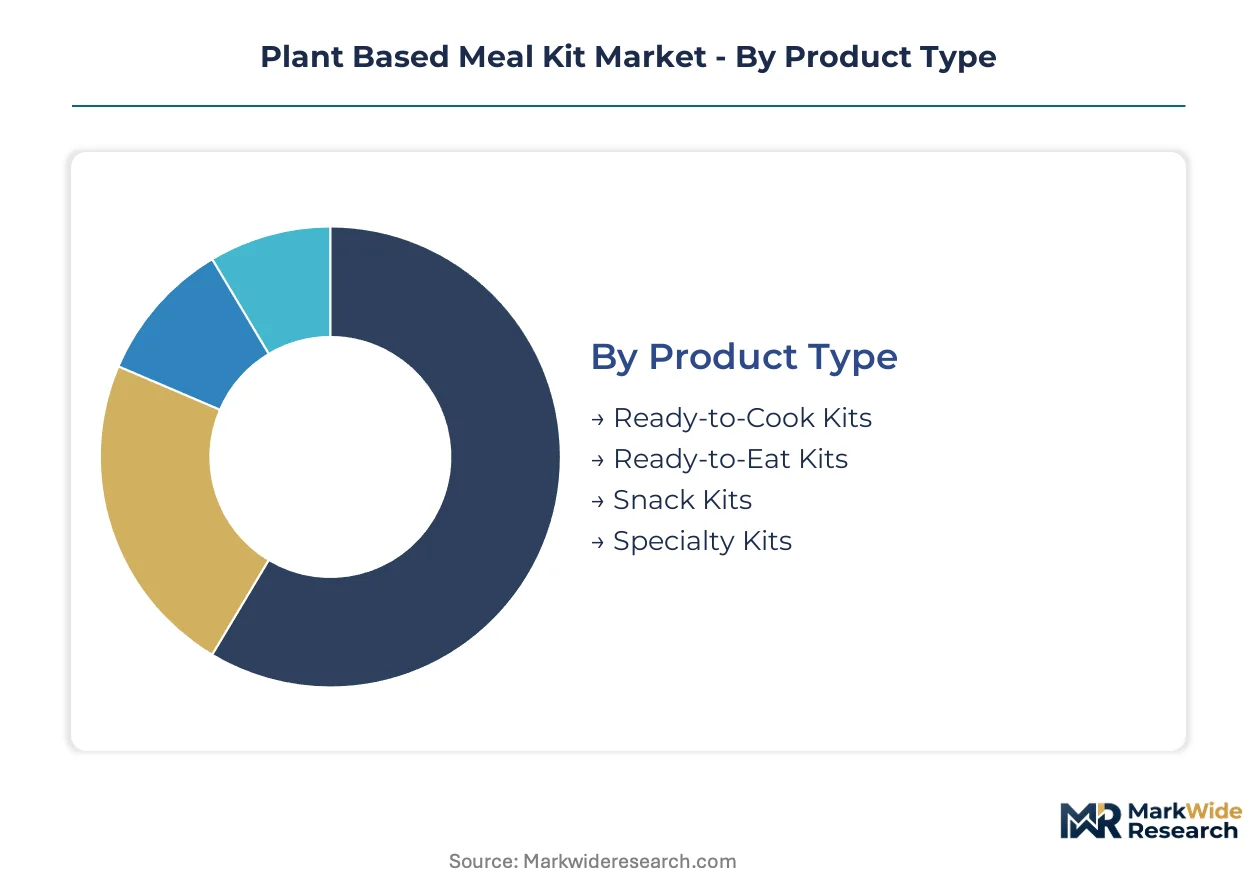
Plant-based meal kit segmentation reveals divergent margin profiles across preparation intensity and channel economics. Understanding which segments face substitution pressure from restaurant delivery and grocery prepared foods is essential for capacity planning and pricing architecture.
Product Type:
Ready-to-eat formats confront the most acute substitution threat from ghost kitchen delivery and supermarket prepared meals, while ready-to-cook kits defend position through waste reduction and portion control value propositions.
- Ready-to-Cook Kits:Pre-portioned fresh ingredients requiring residential preparation with recipe cards and timing instructions. Demand concentrates in United States suburban households where time constraints meet cooking intent, though perishable input volatility compresses margin predictability.
- Ready-to-Eat Kits:Fully prepared plant-derived meals demanding only reheating, typically packaged in modified atmosphere containers. Urban professionals in dense metros with minimal kitchen access drive adoption, with seven-day shelf stability constraining distribution radius from central production.
- Snack Kits:Assembled plant-based nibbles and mini-meals for between-meal consumption. Office workers and fitness-oriented consumers in coastal United States cities sustain trial rates.
- Specialty Kits:Niche formulations targeting allergen avoidance or athletic performance macros. CrossFit communities and registered dietitian referral networks in Texas and Florida generate concentrated demand.
Ready-to-cook kits anchor the volume base while ready-to-eat kits gain share at the steepest rate.
Distribution Channel:
Channel economics stratify sharply by customer acquisition cost and fulfillment overhead, with pure-play subscription models facing margin pressure from grocery partnership alternatives.
- Online Retail:Direct-to-consumer subscription platforms with automated reorder algorithms and preference learning. United States metro corridors with established cold chain density sustain lowest per-unit delivery costs.
- Supermarkets:Click-and-collect and in-store refrigerated pickup points. Kroger and Whole Foods Market partnerships in California and New York are absorbing last-mile economics from standalone operators.
- Specialty Stores:Independent grocers and natural food retailers with curated plant-forward assortments. Pacific Northwest co-ops and Midwestern health food chains maintain regional relevance.
- Direct Sales:Corporate wellness programs and institutional procurement channels. Silicon Valley tech campuses and university dining contracts in Massachusetts represent concentrated B2B opportunity.
Online retail commands subscriber economics while supermarket partnerships expand most quickly as refrigerated pickup infrastructure matures.
Customer Segment:
Flexitarian-adjacent health-conscious consumers present the largest addressable pool, while committed vegans deliver highest lifetime value through subscription persistence.
- Health-Conscious Consumers:Flexitarian households seeking structured dietary improvement without full protein-source elimination. This cohort dominates United States subscription volume, particularly in Denver and Austin where fitness culture intersects with environmental awareness.
- Vegans:Strict plant-based adherents requiring certified animal-free supply chains. Loyalty rates exceed other segments, with concentrated demand in Portland and Los Angeles where dedicated vegan culinary infrastructure is deepest.
- Vegetarians:Lacto-ovo adherents accepting dairy and eggs but avoiding meat. Older demographic skew in Midwestern United States cities sustains steady if slower-growing demand.
- Environmental Advocates:Climate-motivated purchasers prioritizing carbon-accounted sourcing and regenerative agriculture claims. EU Green Deal alignment drives premium willingness in European markets, with emerging presence in United States coastal metros.
Health-conscious consumers provide the volume foundation while environmental advocates climb the fastest as carbon labeling becomes standard.
Meal Type:
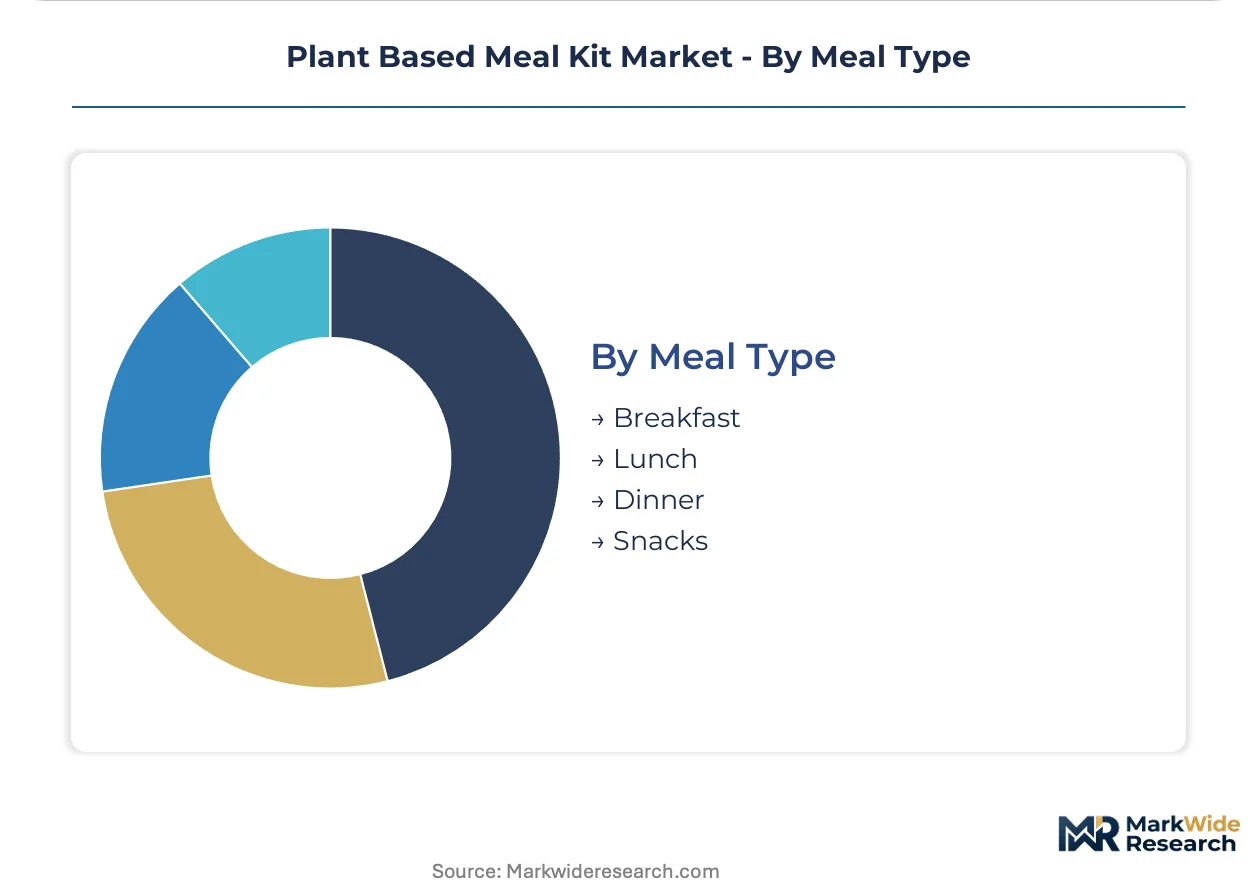
Dinner occasions capture the greatest share of consumer meal kit spending, though breakfast formats face less competition from restaurant alternatives.
- Dinner:Multi-component evening meals with protein, starch, and vegetable balance. Family households in United States suburbs sustain highest weekly order frequency, with recipe complexity driving culinary R&D investment concentration.
- Breakfast:Morning-oriented kits featuring plant-based proteins and whole grains. Urban professionals in Chicago and Seattle show strongest adoption, with lower per-meal price points enabling trial conversion.
- Lunch:Midday meal solutions targeting workplace consumption. Corporate subscription programs and individual office workers in Manhattan and San Francisco drive demand.
- Snacks:Mini-meal and grazing formats for between-occasion consumption. Fitness enthusiasts and remote workers in Sun Belt metros sustain growth.
Dinner commands the revenue base while breakfast gains share at the steepest rate as morning routine automation demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States coastal metros where subscription density sustains premium capture, while European markets face margin compression from EU Green Deal compliance documentation costs that suppliers must absorb.
United States
Subscription density in Denver and Austin drives recurring revenue stability as fitness-conscious flexitarian households prioritize structured meal planning. The USDA organic certification pathway shapes supplier qualification standards across domestic supply chains. Cold chain fulfillment nodes cluster in California's Central Valley and the Pacific Northwest, where regenerative-sourced legumes command sourcing premiums from certified organic producers.
Germany
Environmental advocates in Berlin and Hamburg sustain demand for carbon-accounted meal kits with documented lifecycle emissions. The EU Green Deal's carbon border adjustment mechanism forces importers to provide agricultural input documentation for specialty proteins. Bavarian organic producers are consolidating supplier relationships with ready-to-cook assemblers to reduce customs friction and certification complexity.
United Kingdom
Urban professionals in London and Manchester drive ready-to-eat adoption where minimal kitchen access favors ten-day shelf stability formats. REACH frameworks govern packaging material restrictions and chemical safety disclosures for modified atmosphere containers. Midlands-based fulfillment hubs are expanding refrigerated last-mile radii to capture secondary city households previously outside seven-day delivery windows.
France
Flexitarian penetration in Paris and Lyon sustains demand for premium recipe complexity without full vegan commitment. EFSA nutritional disclosure requirements shape product formulation transparency for allergen-controlled menus. Île-de-France culinary R&D clusters are deepening chef training pipelines to address hybrid food science talent scarcity affecting recipe development timelines.
Canada
Health-conscious consumers in Toronto and Vancouver anchor subscription growth where environmental awareness intersects with time-constrained professional lifestyles. Health Canada oversees allergen labeling standards that parallel FDA requirements while maintaining distinct bilingual disclosure mandates. British Columbia's organic certification infrastructure supports Pacific Northwest supplier integration across cross-border fulfillment networks.
Plant Based Meal Kit Market Competitive Landscape
Concentration sits with vertically integrated culinary laboratories that control recipe development and proprietary chef networks. The vendor base stratifies across three tiers: pure-play plant-based specialists with dedicated vegan infrastructure, diversified meal kit platforms leveraging continental fulfillment scale, and supermarket-affiliated brands absorbing last-mile costs through click-and-collect partnerships. Dominant competitive moves include strategic partnerships with grocery chains and geographic expansion into underpenetrated secondary metros.
Within the pure-play specialist tier, Purple Carrot exemplifies dedicated vegan recipe development through captive culinary infrastructure. Among diversified platforms, HelloFresh occupies a position representing continental fulfillment scale advantages in ready-to-cook assembly. Green Chef anchors the certified organic differentiation vector with allergen-controlled production protocols. These three companies collectively represent the strategic archetypes reshaping competitive posture: proprietary culinary development, logistics-scale efficiency, and certification-premium positioning.
| Leading Market Players |
|---|
| Purple Carrot |
| Green Chef |
| HelloFresh |
| Blue Apron |
| Home Chef |
| Fresh n' Lean |
| Sun Basket |
| Sakara Life |
| Daily Harvest |
| Others |
Value Network & Pricing Analysis
Central kitchen utilization rates above seventy percent in United States coastal metros compress per-unit fixed costs and establish price floors that secondary-market entrants struggle to match without equivalent throughput density. This scale concentration simultaneously locks in supplier preferential pricing for certified organic inputs and regenerative-sourced legumes, creating a feedback loop where volume concentration reinforces procurement leverage.
Pricing Analysis
The customization-premium spread between configured-to-order specialty kits and standard ready-to-cook bundles runs three-to-one in United States subscription markets. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and geographic delivery cost differentials. Pricing pressure stems from supermarket click-and-collect partnerships absorbing last-mile overhead and compressing pure-play subscription margins. Health-conscious flexitarian households show highest price sensitivity, while committed vegan segments accept premium capture for certified animal-free supply chains.
Supply Chain Analysis
Seven-day inventory turns for fresh produce inputs and fourteen-day lead times for specialty plant proteins constrain production planning flexibility across North American fulfillment networks. Agricultural inputs concentrate in California's Central Valley, the Pacific Northwest, and Midwestern organic corridors. Cold chain logistics draw from refrigerated transport fleets and modular packaging with plant-derived oxygen scavengers. Single-source vulnerability in USDA-accredited organic certification creates geographic exposure to climate disruption. Distribution runs through direct-to-consumer subscription platforms, supermarket click-and-collect nodes, and corporate wellness procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid food science and chef training pipelines lag recipe development demand across the industry, constraining menu innovation velocity and forcing compensation premiums that compress mid-tier operator economics. This talent scarcity situates culinary R&D infrastructure as the decisive competitive moat.
For Market Incumbents: Secure captive culinary laboratories and proprietary chef networks before talent scarcity intensifies wage inflation. Defend against supermarket-affiliated brands by deepening direct-to-consumer cold chain density in underpenetrated secondary metros. Prioritize USDA organic certification investment to maintain supplier preferential access as accredited sources face climate-driven yield volatility. For New Entrants and Emerging Players: USDA organic certification fast-track programs offer regulatory arbitrage against established players with legacy compliance burdens. Secondary United States metros between five hundred thousand and two million population present white space with minimal incumbent fulfillment infrastructure. Corporate wellness procurement channels provide B2B entry with lower customer acquisition costs than consumer subscription markets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated operators with in-house recipe development and controlled supply chains over asset-light platform models. Five-to-ten year viability hinges on carbon accounting infrastructure and regenerative sourcing documentation capabilities. The signal to watch is EU Green Deal carbon border adjustment enforcement intensity, which will determine which continental European fulfillment footprints retain structural advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Organic Procurement Consolidation | USDA-accredited supplier relationships reduce documentation friction and secure regenerative-sourced legume access. |
| Refrigerated Last-Mile Infrastructure Expansion | Solar-powered cold storage in southwestern distribution centers qualifies for IRA clean energy tax credits. |
| Supermarket Click-and-Collect Partnership | Kroger and Whole Foods Market refrigerated pickup nodes absorb per-unit delivery economics from pure-play subscriptions. |
| Corporate Wellness Channel Development | Silicon Valley tech campuses and university dining contracts offer concentrated B2B volume with lower churn. |
| Modified Atmosphere Packaging Adoption | Cellulose-based barrier films extend ready-to-eat kit shelf stability to ten days, compressing frozen alternatives. |
Research Methodology
Initial hypotheses were tested against primary input from culinary R&D directors, cold chain logistics managers, supermarket category buyers, and corporate wellness procurement officers and refined through secondary validation. FDA nutritional disclosure filings, USDA organic certification databases, EU Green Deal implementation guidance, and refrigerated transport customs records anchored quantitative baselines. Bottom-up subscriber volume modeling and top-down addressable household estimation were triangulated against channel partner inventory data.
Variance decomposition across product type, distribution channel, customer segment, and meal occasion dimensions structured the analytical framework. CAGRs were derived from segmented growth rate aggregation and cross-validated against macroeconomic consumption elasticity assumptions. Industry-specific forecast inputs included flexitarian household penetration curves and refrigerated last-mile technology adoption rates across United States metro corridors.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable organic certification supply; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Black Rice Protein Market
Plant Based Food
Plant Based Pork Market
Plant Based Food
Vegan Flavor Market
Plant Based Food
Fava Bean Protein Market
Plant Based Food
Plant-Based Frozen Dessert Market
Plant Based Food
USA Plant-Based Creamers Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
Asia-Pacific Pea Protein Market
Plant Based Food
India Meat Substitutes Market
Plant Based Food
Pea Protein Isolate Market
Plant Based Food
Vegan Dips Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Chicory Roots Market
Plant Based Food
Plant-Based Chorizo Market
Plant Based Food
Plant Based Eggs Market
Plant Based Food
Plant-Based Hot Dogs Market