
 Plant Based Pork Market | 2026-2036
Plant Based Pork Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Pork Market Outlook
Consolidation among North American quick-service chains is repositioning procurement power toward a handful of national buyers that now dictate formulation standards and volume commitments. Beyond Meat leverages its extrusion technology leadership to supply these concentrated buyers with texturally precise ground pork alternatives. Impossible Foods anchors its competitive stance through heme-based flavor science that narrows the sensory gap with conventional pork. Maple Leaf Foods sustains its position through integrated plant-protein supply chains spanning pea and soy processing.
Plant-based pork denotes protein-rich food products engineered from isolated plant proteins, binders, and lipid systems to replicate the organoleptic properties of conventional porcine muscle tissue, typically achieving 15-20 grams of protein per serving through high-moisture extrusion or shear-cell processing. These products serve industrial food manufacturers and food service operators seeking to reduce reliance on animal agriculture while maintaining menu versatility. Ground pork and sausages dominate current revenue pools due to their compatibility with existing manufacturing equipment and consumer familiarity in tacos, pasta sauces, and breakfast applications. Pea protein formulations command premium positioning among allergen-conscious shoppers, while soy protein variants occupy mainstream price tiers through established supply infrastructure. Mycoprotein remains a niche ingredient type with concentrated adoption among flexitarian households seeking fiber-enhanced nutritional profiles.
The FDA oversees labeling integrity for plant-based meat products in the United States, while USDA-FSIS jurisdiction intersects where products enter retail channels with meat-adjacent nomenclature, creating compliance complexity for cross-border formulations. The EU's Farm to Fork Strategy under the European Green Deal imposes sustainability disclosure requirements that advantage plant-based pork producers with verified carbon footprint data. Stakeholders must monitor evolving nomenclature rulings and procurement mandates from institutional food service buyers, as these decisions will determine which ingredient technologies and distribution channels capture disproportionate growth.
Market Dynamics
Consolidation among North American quick-service chains concentrates procurement power into a handful of national buyers now dictating formulation standards and volume commitments to plant-based pork suppliers.
Growth Catalysts
- EU Farm to Fork Strategy:Sustainability disclosure requirements under the European Green Deal advantage producers with verified carbon footprint data, creating procurement preference among institutional food service buyers.
- High-moisture extrusion:This processing technology enables textural precision in ground pork alternatives, allowing food manufacturers to replicate conventional porcine muscle tissue without retooling entire production lines.
- Quick-service chain expansion:Taco Bell, Chipotle, and similar operators across the United States are widening plant-based menu placements as consumer palates shift toward alternative proteins.
Market Restraints
- Pea protein input costs:Volatility in yellow pea concentrate pricing constrains margin expansion for allergen-conscious formulations targeting premium positioning.
- FDA-USDA jurisdictional overlap:Labeling compliance complexity increases where products enter retail channels with meat-adjacent nomenclature, creating cross-border formulation friction.
- Heme supply concentration:Flavor science dependent on soy leghemoglobin remains bottlenecked by limited fermentation capacity and intellectual property control.
Strategic Opportunities
- Institutional procurement mandates:K-12 school districts and hospital systems in the United States are establishing plant-forward purchasing requirements that open volume contracts.
- Mycoprotein-fiber convergence:Combining fungal protein with enhanced fiber systems targets flexitarian households seeking nutritional density beyond basic protein replication.
- Shear-cell processing:This emerging technology reduces energy intensity versus extrusion, enabling distributed production models closer to population centers.
Industry Challenges
- Food technologist scarcity:Formulation expertise spanning lipid systems, protein chemistry, and sensory science remains concentrated among a handful of specialized practitioners.
- Clean-label certification timelines:Non-GMO Project and similar third-party verifications require 12-18 month validation cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Pork Market |
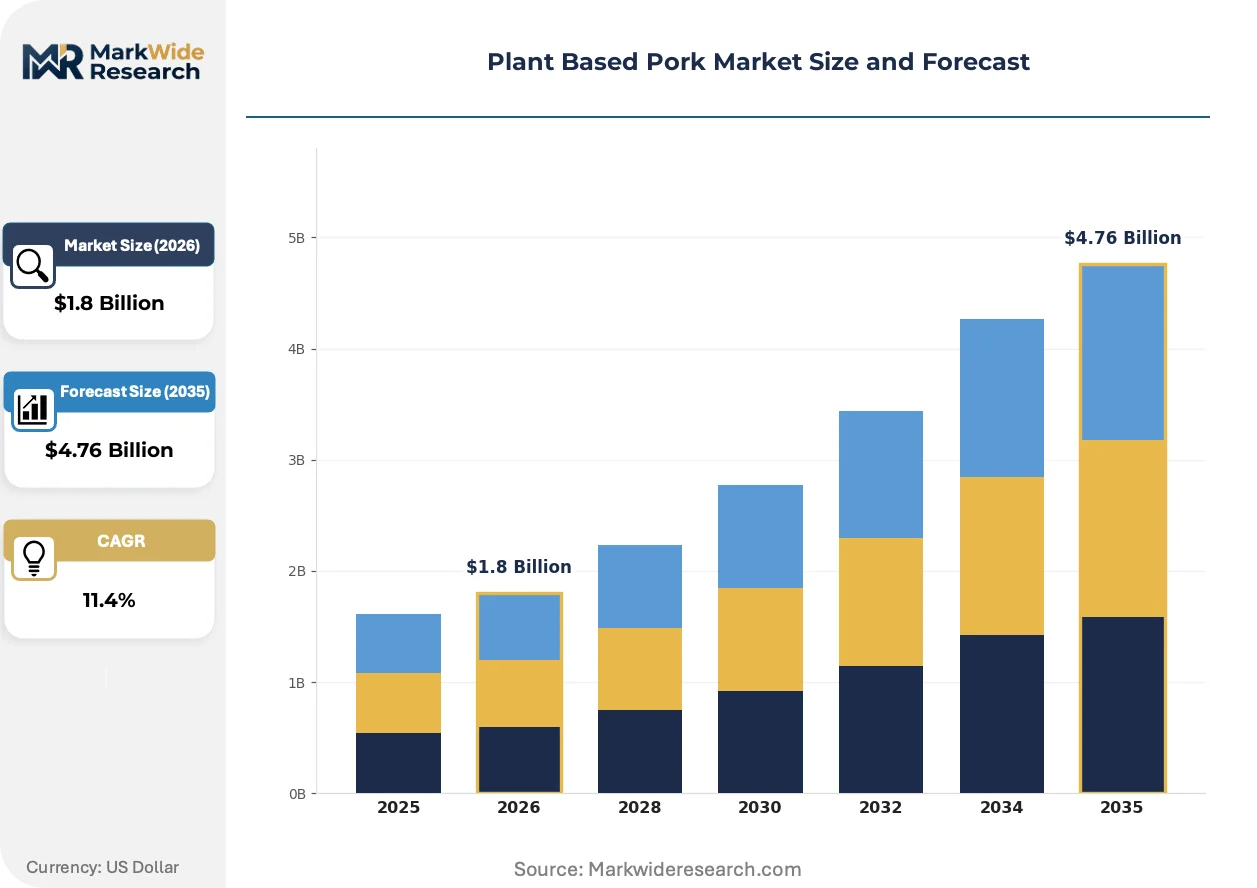
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
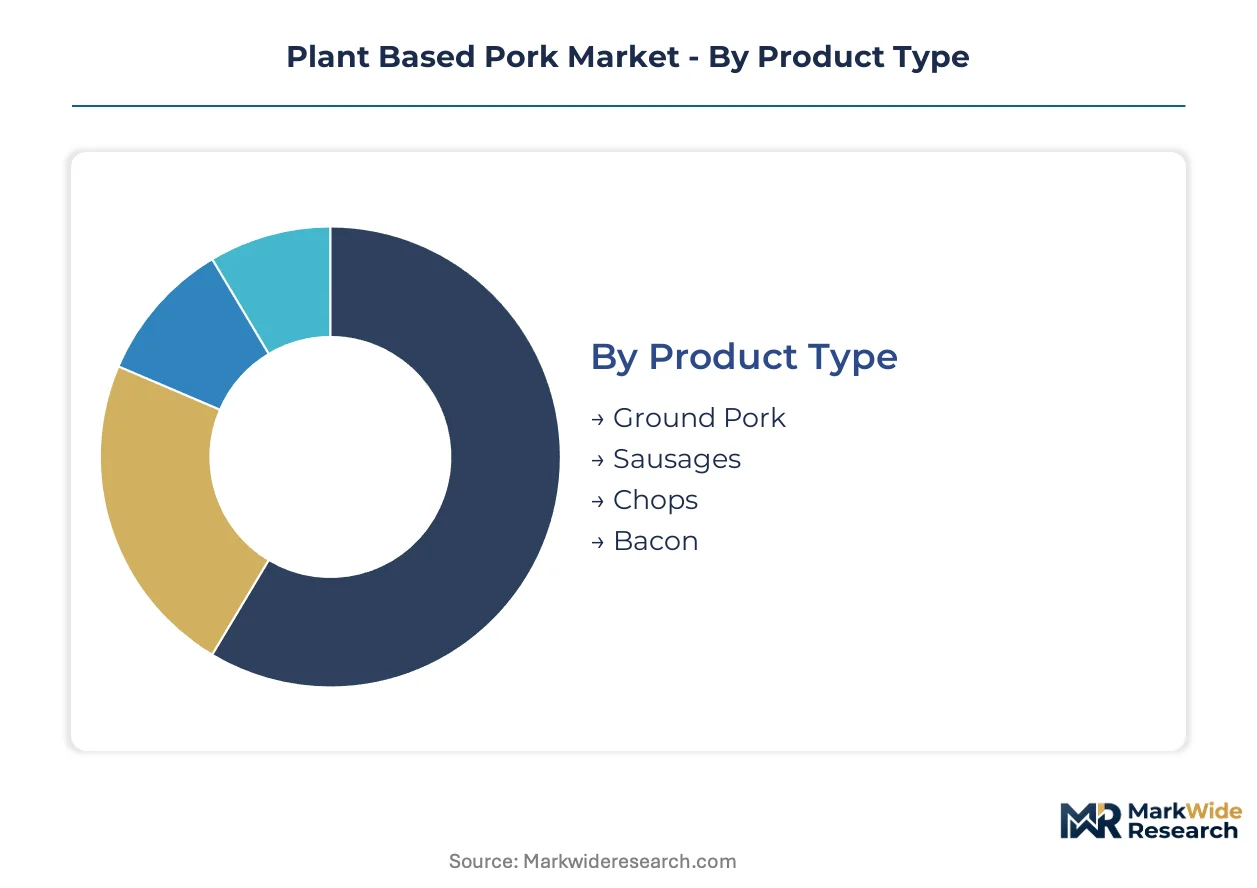
| Segmentation | Product Type: Ground Pork, Sausages, Chops, Bacon Ingredient Type: Pea Protein, Soy Protein, Wheat Gluten, Mycoprotein Distribution Channel: Supermarkets, Online Stores, Food Service, Specialty Stores End User: Vegetarians, Flexitarians, Health-Conscious Consumers, Chefs |
| Companies Covered | Beyond Meat, Impossible Foods, Maple Leaf Foods, Conagra, Tofurky, Quorn Foods, Omni Foods, Lightlife Foods, Field Roast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Pork Market Strategic Shifts
Active reformulation of lipid systems and protein texturization methods is compressing the sensory gap with conventional pork while regulatory frameworks evolve to accommodate novel production claims.
High-moisture extrusion technology is overtaking traditional low-moisture processes as the dominant manufacturing pathway for ground pork alternatives. Quick-service chains and industrial food manufacturers are adopting these systems at accelerated pace to achieve fibrous, chewable textures previously unattainable with legacy equipment. This shift is overtaking older capital investments and forcing equipment suppliers to retool their installed base toward twin-screw configurations with precise temperature control zones.
The FDA's evolving guidance on cell-cultured and plant-based meat labeling is reshaping how brands communicate protein origin to shoppers. Industrial consequence includes reformulation of packaging claims and front-of-package nomenclature to preempt state-level litigation risk. Ground pork and sausage categories face the most acute compliance pressure, with manufacturers responding through dual-SKU strategies that segregate retail and food service labeling.
Buyer concentration among national quick-service chains is compressing supplier negotiation cycles and standardizing formulation specifications across regional markets. Food service distributors are losing leverage as direct procurement relationships between plant-based pork manufacturers and chain headquarters consolidate volume commitments. This pattern is most visible in the United States, where Aramark, Compass Group, and similar institutional operators are establishing centralized alternative protein sourcing desks.
Plant Based Pork Market Segmentation
Plant-based pork manufacturers engineer distinct formulations and channel strategies to match divergent consumption occasions and protein sourcing priorities across retail and food service environments. Segmentation discipline determines which texturization technologies and lipid systems warrant capital deployment.
Product Type:
Extrusion and shear-cell processing capabilities dictate which muscle-cut replications achieve commercial scale versus remaining niche prototypes.
- Ground Pork:High-moisture extrusion produces fibrous textures compatible with existing taco and pasta sauce manufacturing lines. Demand concentrates in United States quick-service chains where Taco Bell and Chipotle specify precise crumble geometries for operational consistency.
- Sausages:Encapsulated fat systems and alginate casings replicate snap and juiciness for breakfast and grilling applications. German and Dutch retail channels show concentrated adoption where EU Green Deal sustainability disclosures advantage verified low-carbon formulations.
- Chops:Structured protein layers mimic muscle fiber orientation for center-plate positioning.
- Bacon:Precision-controlled lipid marbling and smoke flavoring targets premium breakfast and burger topping applications.
Mature deployment sits with Ground Pork. Newer deployment is concentrated in Bacon.
Ingredient Type:
Protein isolation costs and allergen labeling requirements segment the supply base between commodity-scale inputs and specialty concentrates.
- Pea Protein:Yellow pea concentrate achieves 80-85% protein content with favorable amino acid scoring for allergen-conscious positioning. Premium retail shelves in United States and Canadian supermarkets allocate disproportionate space to non-GMO verified variants despite input cost volatility.
- Soy Protein:Established crushing infrastructure across Midwestern United States and Brazilian interior delivers cost-competitive isolates with complete amino acid profiles. Mainstream price tiers depend on this supply base for volume production.
- Wheat Gluten:Seitan-derived textures provide chew density for Asian-market formulations and European artisanal production.
- Mycoprotein:Fusarium venenatum fermentation yields fiber-enhanced nutritional profiles with lower land-use intensity.
Volume concentration favors Soy Protein. Steepest expansion trajectory belongs to Mycoprotein.
Distribution Channel:
Channel selection determines packaging format, shelf-life requirements, and the regulatory jurisdiction governing label claims.
- Supermarkets:Refrigerated and frozen case placement demands 30-45 day distribution windows and front-of-package compliance with FDA and USDA-FSIS overlapping jurisdiction. United States retail shelf expansion for alternative proteins has widened considerably in conventional grocers beyond natural channel confines.
- Food Service:Direct procurement relationships with Aramark, Compass Group, and national quick-service headquarters consolidate volume commitments and standardize formulation specifications. Frozen bulk formats predominate for operational efficiency.
- Online Stores:Direct-to-consumer fulfillment enables subscription models and limited-edition flavor trials.
- Specialty Stores:Natural channel placement targets clean-label seekers with third-party certifications.
Margin capture is strongest in Food Service. Penetration depth is greatest in Supermarkets.
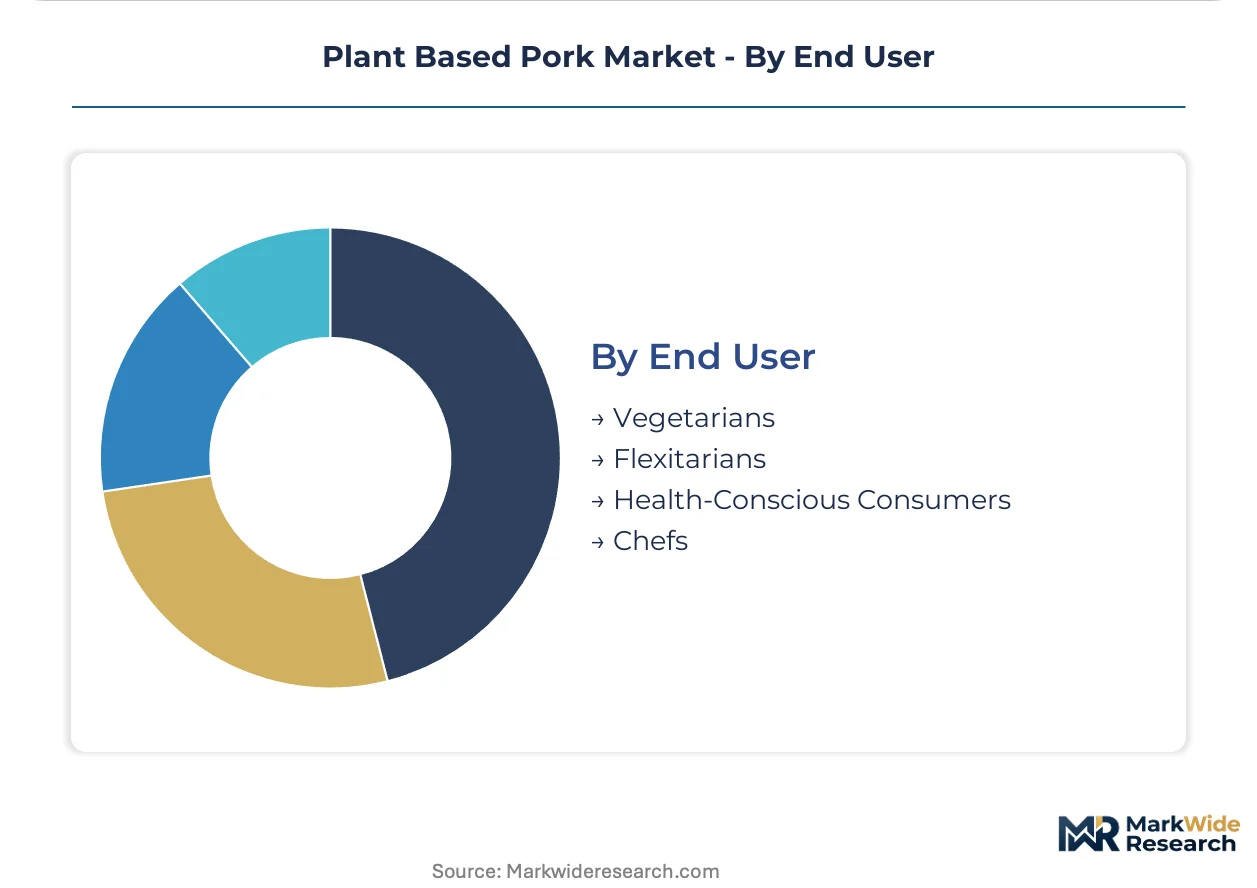
End User:
Consumption motivation—ethical restriction versus health optimization versus culinary experimentation—shapes product positioning and communication strategy.
- Flexitarians:Protein-seeking households reducing animal meat frequency without elimination drive mainstream volume. This segment commands the broadest SKU distribution across United States retail and food service channels as manufacturers target the largest addressable protein-reduction cohort.
- Health-Conscious Consumers:Saturated fat and sodium scrutiny motivates reformulation toward clean-label ingredient decks. K-12 school districts and hospital systems in the United States establish plant-forward procurement mandates that open institutional volume contracts.
- Vegetarians:Longstanding meat avoidance creates demand for sensory-faithful replication rather than vegetable-forward alternatives.
- Chefs:Menu innovation and cross-utilization potential drive premium ingredient specifications.
Volume leadership resides with Flexitarians. Fastest value-per-unit growth sits with Chefs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yellow pea cultivation across the Canadian prairies and Midwestern United States supplies the protein concentrates that anchor North American formulation capacity. This feedstock geography shapes where extrusion facilities cluster and which regions capture value from plant-based pork manufacturing.
United States
Quick-service chains including Taco Bell and Chipotle specify precise crumble geometries for operational consistency in ground pork alternatives. FDA and USDA-FSIS overlapping jurisdiction creates labeling compliance complexity where products enter retail channels with meat-adjacent nomenclature. Chicago and Los Angeles metropolitan areas concentrate food service distribution infrastructure for institutional procurement.
Germany
Retail channels show concentrated adoption of plant-based sausages where EU Green Deal sustainability disclosures advantage verified low-carbon formulations. The Farm to Fork Strategy under the European Green Deal imposes sustainability disclosure requirements that reshape procurement standards. Berlin and Hamburg anchor food manufacturing clusters with specialized extrusion equipment installations.
United Kingdom
Flexitarian households seeking fiber-enhanced nutritional profiles drive mycoprotein adoption in premium retail positioning. EFSA and national regulators enforce strict novel food authorization pathways for fermentation-derived proteins. The East Midlands and Greater London concentrate R&D facilities for alternative protein texturization.
Canada
Prairie provinces supply yellow pea concentrates that achieve 80-85% protein content for allergen-conscious positioning. Health Canada oversees labeling integrity while provincial agriculture departments promote plant-protein processing investments. Saskatchewan and Manitoba anchor crushing infrastructure that feeds cross-border formulation facilities.
Netherlands
Shear-cell processing research accelerates as food technologists seek energy intensity reductions versus traditional extrusion. ECHA and national environmental agencies regulate industrial fermentation emissions from heme production facilities. The Eindhoven Region and Wageningen cluster concentrate alternative protein innovation infrastructure.
Plant Based Pork Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue mycoprotein and shear-cell processing niches to differentiate positioning. The market structure reflects consolidation among national quick-service buyers that compress supplier negotiation cycles and standardize formulation specifications. Three archetypes dominate: extrusion technology specialists, heme-based flavor science developers, and integrated plant-protein processors with captive supply chains. Competitive moves concentrate on direct procurement relationships with chain headquarters and technology licensing for distributed production models.
Within the extrusion-specialist tier, Beyond Meat and Impossible Foods exemplify technology-led positioning, while Maple Leaf Foods anchors the integrated-processor archetype with upstream control over pea and soy processing infrastructure. These three companies represent distinct strategic pathways—equipment-based scale, molecular flavor replication, and supply chain verticality—that define how suppliers respond to buyer concentration among North American food service operators.
| Leading Market Players |
|---|
| Beyond Meat |
| Impossible Foods |
| Maple Leaf Foods |
| Conagra |
| Tofurky |
| Quorn Foods |
| Omni Foods |
| Lightlife Foods |
| Field Roast |
| Others |
Value Chain & Pricing Dynamics
Captive integration into yellow pea crushing infrastructure anchors both supply security and pricing power for North American plant-based pork manufacturers. This upstream control over protein concentrate sourcing buffers margin compression from volatile commodity markets while positioning integrated processors to dictate terms to fragmented ingredient buyers.
Pricing Analysis
Service-bundling separates formulation support from base ingredient supply, with extrusion technology licensing and sensory consulting packaged as premium add-ons. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with Non-GMO Project verification commanding shelf price premiums. Cost compression in mainstream soy-based tiers is intensifying because Brazilian crushing capacity expansion feeds oversupply dynamics. Quick-service chain procurement desks exhibit lowest price sensitivity due to operational standardization requirements, while independent food service distributors face margin erosion from direct manufacturer relationships.
Supply Chain Analysis
Single-source vulnerability sits with heme fermentation capacity concentrated among limited biotechnology facilities. Yellow pea concentrate draws from Canadian prairie crushing infrastructure, Midwestern United States processing hubs, and emerging Ukrainian supply alternatives. Soy protein isolate rests on established Brazilian and Argentine oilseed crushing networks. Regulatory restriction risk looms where FDA-USDA jurisdictional overlap complicates cross-border label compliance for meat-adjacent nomenclature. Distribution runs through frozen bulk logistics networks serving institutional food service operators, with refrigerated retail case placement requiring shorter distribution windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-moisture extrusion technology is displacing legacy low-moisture processing equipment across plant-based pork manufacturing, compressing capital replacement cycles and reshaping supplier competitive dynamics.
For Market Incumbents: Anticipate margin pressure from emerging shear-cell processing entrants by locking multi-year volume commitments with concentrated quick-service chain buyers. Prioritize backward integration into pea protein crushing to defend input cost position against yellow pea concentrate volatility.
For New Entrants and Emerging Players: Capture institutional procurement mandates from K-12 school districts and hospital systems seeking plant-forward volume contracts with verified carbon footprint disclosures. Penetrate mycoprotein-fiber convergence formulations targeting flexitarian households through direct-to-consumer subscription models.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated food conglomerates seeking extrusion technology capabilities and established food service distribution relationships. Five-to-ten year viability hinges on regulatory clarity around cell-cultured and plant-based meat labeling convergence. Monitor FDA guidance evolution as inflection indicator for packaging claim reformulation costs.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Moisture Extrusion Capacity Expansion | Twin-screw extrusion installations enable textural precision for quick-service chain specifications. |
| Heme Fermentation Scale-Up | Soy leghemoglobin production expansion narrows sensory gaps with conventional pork flavor profiles. |
| Direct Procurement Relationship Consolidation | Aramark and Compass Group centralized sourcing desks compress distributor leverage. |
| Clean-Label Certification Investment | Non-GMO Project verification opens premium retail shelf placement in United States supermarkets. |
| Shear-Cell Processing R&D Partnership | Wageningen University collaboration reduces energy intensity versus traditional extrusion methods. |
Study Parameters
SEC 10-K filings, FDA guidance documents, and EU Farm to Fork Strategy disclosures formed the secondary backbone, supplemented by customs records tracking yellow pea concentrate trade flows. Food technology R&D directors, quick-service chain procurement managers, and institutional food service operators provided primary perspective, with extrusion equipment suppliers and lipid systems formulators contributing technical validation. Bottom-up volume modeling triangulated against top-down protein ingredient demand estimates.
Historical trendline analysis across protein isolate pricing and extrusion equipment deployment informed projection parameters. Segmentation modeling spanned product type, ingredient source, distribution channel, and end-user motivation dimensions throughout the forecast period. CAGRs derived from elasticity-adjusted demand curves incorporating quick-service chain menu expansion rates and regulatory compliance cost trajectories.
The model holds under stable FDA-USDA jurisdictional boundaries; deviation in labeling preemption rulings or state-level litigation outcomes would shift channel profitability. Forecasts reflect assumptions regarding pea protein input cost normalization and heme fermentation capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Pea Protein Market
Plant Based Food
Vegan Chocolate Market
Plant Based Food
India Meat Substitutes Market
Plant Based Food
Burdock Root Extract Market
Plant Based Food
Africa Soy Beverages Market
Plant Based Food
South America Soy Beverages Market
Plant Based Food
Plant Based Meal Kit Market
Plant Based Food
Fava Bean Protein Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
Meatless Meat Market
Plant Based Food
Vegan Tortillas Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Vegan Food Market
Plant Based Food
Indoor Leafy Green Precision Nutrition Program Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
Global Tofu Market