
 Organic Snack Food Market | 2026-2036
Organic Snack Food Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Snack Food Market Analytics
Private-label organic assortment expansion is reshaping margin distribution between branded incumbents and retailer-controlled lines. General Mills Inc. sustains shelf dominance through backward integration into organic grain sourcing. Danone differentiates via its specialized dairy-free and plant-based snack sub-portfolio. SunOpta Inc. anchors North American supply with its integrated organic ingredient processing infrastructure.
Organic snack food denotes edibles manufactured from certified organic agricultural inputs, processed without synthetic preservatives or artificial additives, and validated through third-party accreditation against standards such as USDA Organic or EU Organic. These products serve commercial purposes spanning immediate consumption convenience, dietary restriction accommodation, and traceability-assured nutrition. Granola bars and nut-based formulations capture the largest revenue pools, while fruit-based ingredient sourcing registers the fastest volume trajectory. Pouch packaging commands premium placement in convenience retail, though bag formats retain cost-sensitive household penetration.
USDA Organic certification governs domestic market access in the United States, while EFSA and EU Organic Regulation shape formulation standards across European markets, with both frameworks intensifying scrutiny of supply chain integrity and label claims. Compliance costs favor scaled operators with dedicated regulatory affairs functions. Stakeholders must monitor evolving state-level extended producer responsibility mandates for snack packaging and assess whether captive organic ingredient supply or flexible contract sourcing better preserves margin under tightening traceability requirements.
Market Dynamics
Clean-label certification requirements and EU Green Deal packaging mandates are compressing formulation cycles while rerouting capital toward captive organic ingredient supply and compostable material R&D.
Growth Catalysts
- EU Farm-to-Fork Strategy:Binding pesticide residue limits and waste-reduction targets are accelerating certified organic acreage conversion across member states.
- Plant protein texturization:Extrusion and fermentation advances are expanding dairy-free snack palatability into mainstream convenience retail.
- Millennial household penetration:Subscription direct-to-consumer models in the United States are capturing repeat purchase velocity previously concentrated in club channels.
Market Restraints
- Organic grain input volatility:Weather-dependent yields and limited certified acreage create margin pressure during drought cycles in the US Midwest and Canadian prairies.
- Supply concentration in North American processing:Mid-scale organic ingredient tolling capacity clusters in Minnesota and Ontario, creating bottleneck risk during peak harvest windows.
- Extended producer responsibility mandates:State-level packaging fee structures in California and Oregon are raising unit economics for multi-layer pouch formats.
Strategic Opportunities
- Underpenetrated German convenience retail:Discounter channel organic snack assortment remains narrow relative to UK and US penetration, creating shelf space for certified entrants.
- Regenerative agriculture certification:USDA's emerging soil health standards offer premium positioning beyond baseline organic for climate-conscious buyers.
- AI-driven demand forecasting:Machine learning inventory optimization is virtualizing working capital requirements for perishable ingredient procurement.
Industry Challenges
- Organic certification timeline compression:Three-year land conversion requirements and auditor backlog are delaying new product launches.
- Legacy ERP integration with traceability platforms:Blockchain and batch-tracking systems require middleware investment that mid-scale co-packers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Snack Food Market |
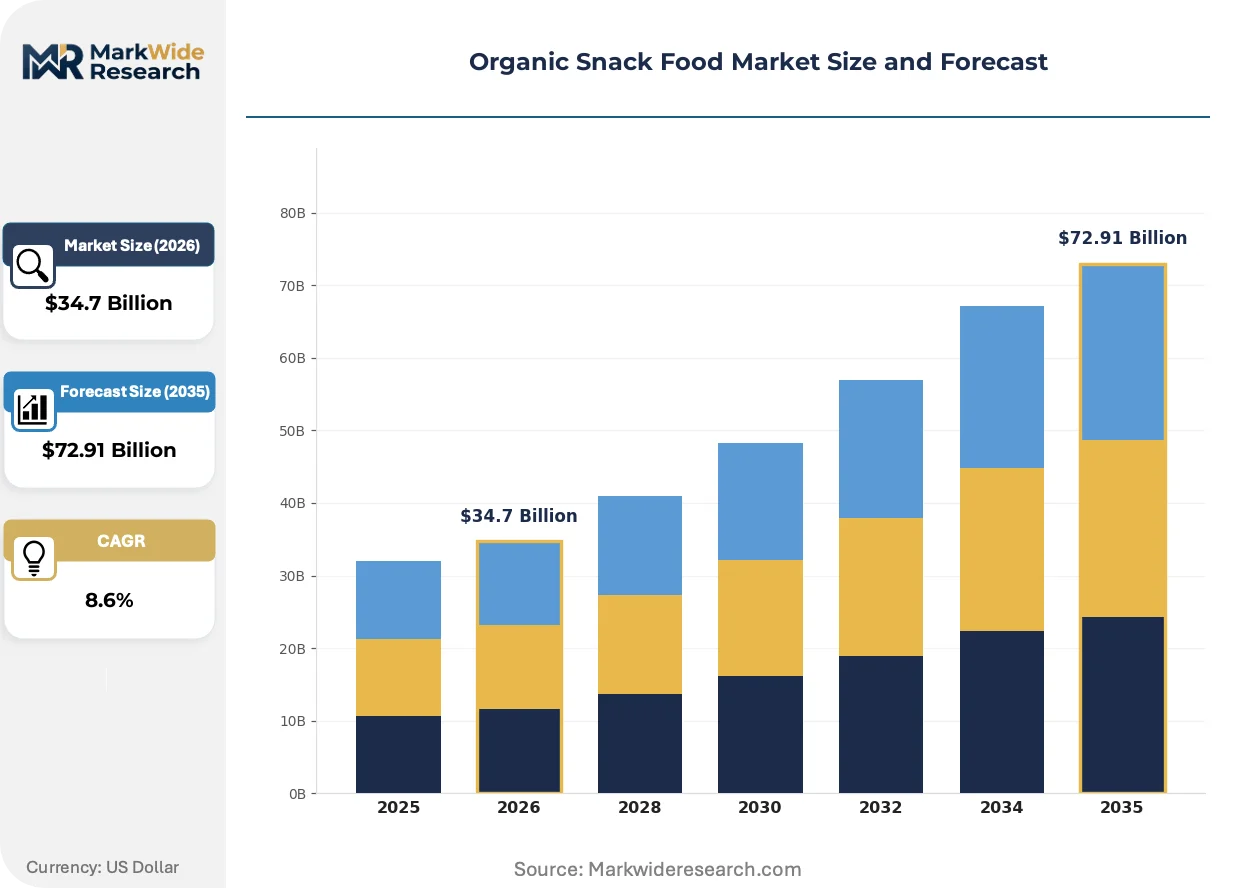
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Dried Fruits, Nuts, Seed Mixes Ingredient Source: Gluten-Free, Whole Grain, Nut-Based, Fruit-Based Packaging Type: Bags, Pouches, Boxes, Tubs Customer Type: Health-Conscious Consumers, Athletes, Families, On-the-Go Professionals |
| Companies Covered | General Mills Inc., Hain Celestial Group, Danone, Conagra Brands Inc., Frito-Lay Inc., Made in Nature, SunOpta Inc., Navitas Organics, Kellogg’s, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Snack Food Market Evolving Landscape
Digital traceability infrastructure and bio-based packaging chemistry are converging to redefine supply chain transparency and shelf-life performance in organic snack manufacturing.
Blockchain-enabled batch tracking is virtualizing audit costs for multi-ingredient supply chains. Large retailers in France and the Netherlands are mandating farm-level QR code disclosure for private-label organic lines. This compression of verification overhead is favoring operators with integrated ingredient sourcing over contract-dependent competitors.
EFSA's tightening scrutiny of novel packaging migration limits is accelerating compostable film R&D. The EU Single-Use Plastics Directive is banning conventional flexible packaging for certain formats by 2030. Snack brands are responding with pilot deployments of cellulose-based barriers in the UK and Nordic markets.
Clean-label preference is fragmenting buyer concentration across channels. Direct-to-consumer subscription platforms are displacing traditional distributor relationships for specialty organic SKUs. This channel rotation is most pronounced in coastal US metropolitan markets and London commuter corridors.
Organic Snack Food Market Segmentation
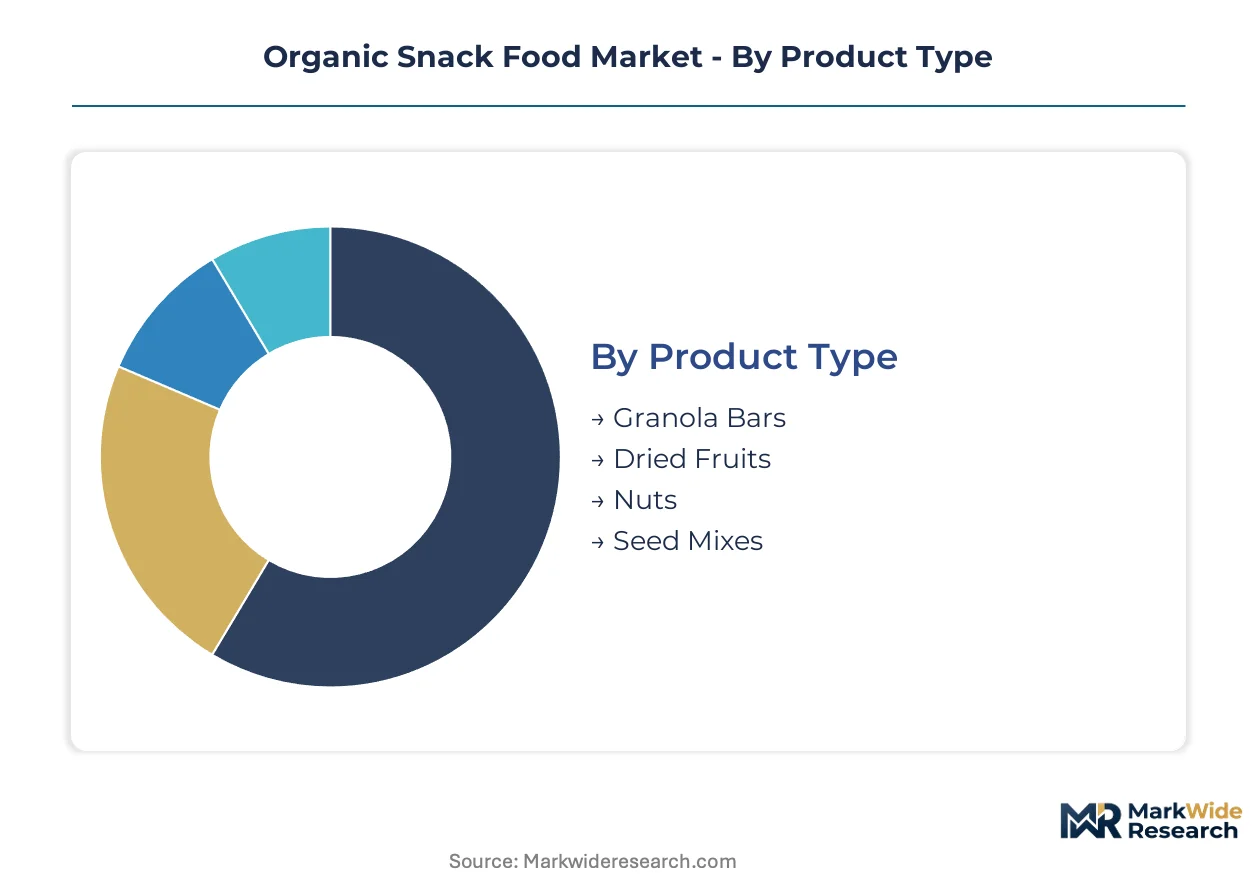
Organic snack food segmentation reveals divergent velocity profiles across product formats and buyer cohorts. Cycle time compression in perishable ingredient sourcing creates distinct inventory risk profiles between ambient-stable and moisture-sensitive formats.
Product Type:
Granola bars turn inventory fastest among shelf-stable formats, while dried fruits face extended procurement windows tied to harvest seasonality. Nuts occupy the middle ground with annual crop cycles but multi-year storage viability.
- Granola Bars:Compressed oat and sweetener supply chains enable rapid formulation pivots. US club channel velocity and direct-to-consumer subscription renewal rates concentrate demand for portable breakfast-replacement formats.
- Dried Fruits:Moisture-controlled dehydration extends shelf life but binds working capital through pre-harvest contracting. California Central Valley sourcing clusters expose margins to irrigation allocation volatility under state water regulations.
- Nuts:Almond and cashew varieties dominate premium positioning with protein density credentials. Bulk ingredient procurement from California and Vietnam shapes cost structures.
- Seed Mixes:Pumpkin and sunflower blends target mineral-conscious buyers with zinc and magnesium claims. Smaller batch sizes accommodate regional organic certification preferences.
Granola bars dominate installed base. Dried fruits are where expansion concentrates.
Ingredient Source:
Cost tier stratification separates commodity organic inputs from specialty-free-from premiums. Whole grain formulations anchor mainstream price points while allergen-free variants command manufacturing complexity premiums.
- Gluten-Free:Oat purity protocols and dedicated facility requirements inflate unit costs. Celiac and non-celiac gluten sensitivity diagnosis rates in US metropolitan markets sustain specialty retail placement.
- Whole Grain:USDA whole grain stamp eligibility drives school and institutional channel access. Midwest organic corn and wheat sourcing networks support volume scale.
- Nut-Based:Protein content and satiety claims resonate with athletic and weight-management segments. California almond processor concentration creates supply bottleneck risk during drought years.
- Fruit-Based:No-added-sugar positioning aligns with pediatric nutrition preferences. Pacific Northwest organic berry and apple sourcing registers steepest expansion trajectory among ingredient categories.
Whole grain commands volume leadership. Fruit-based is gaining share fastest.
Packaging Type:
Customer mobility patterns dictate format selection with single-serve portability driving pouch adoption against household-scale bag retention.
- Bags:Multi-serve capacity retains price-sensitive household penetration. Conventional flexible film faces California extended producer responsibility fee pressure.
- Pouches:Resealable zipper and spout innovations capture convenience retail premium placement. EU Single-Use Plastics Directive compliance costs accelerate compostable film migration.
- Boxes:Rigidity protects fragile formats in e-commerce fulfillment. Amazon and specialty retailer private-label expansion favors corrugated overwrap.
- Tubs:Reusability appeals to zero-waste demographic in UK and German urban markets. Higher freight cost per unit limits geographic radius.
Bags dominate installed base. Pouches are where expansion concentrates.
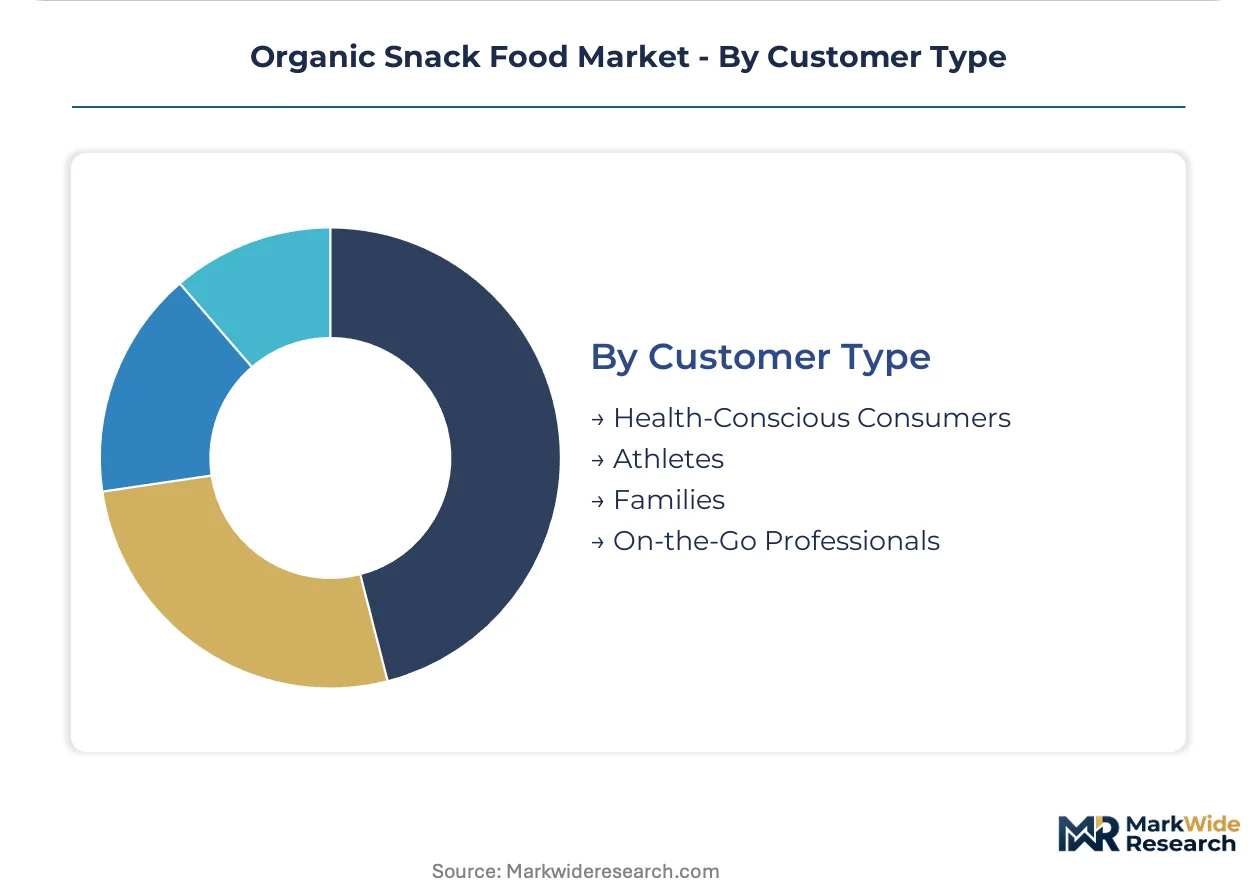
Customer Type:
Application intensity separates habitual daily consumption from occasion-based purchase with subscription models capturing the former and impulse retail the latter.
- Health-Conscious Consumers:Clean-label literacy and third-party certification scrutiny drive premium tolerance. Coastal US and London metropolitan clusters concentrate this cohort.
- Athletes:Macronutrient ratio precision and electrolyte fortification requirements shape product development. Sports specialty retail and gym channel placement dominate.
- Families:Pediatric portion sizing and allergen labeling transparency govern purchase decisions. Club channel multi-pack formats align with household inventory economics.
- On-the-Go Professionals:Transit-friendly consumption and desk-drawer storability prioritize shelf stability and odor containment. Urban commuter corridor convenience retail captures this segment.
Health-conscious consumers dominate installed base. On-the-go professionals are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. US households favor subscription-based direct-to-consumer models for repeat purchases, while European buyers prioritize discounter channel accessibility and farm-level traceability disclosure. Asian markets remain nascent, with urban coastal clusters driving initial premium adoption.
United States
Specialty retail and club channels concentrate demand for portable breakfast-replacement formats. USDA Organic certification governs domestic market access, with state-level extended producer responsibility mandates in California and Oregon raising unit economics for flexible packaging. Minneapolis-St. Paul anchors North American organic grain processing infrastructure.
Germany
Discounter channel organic snack assortment remains narrow relative to UK penetration, creating shelf space for certified entrants. EFSA and EU Organic Regulation shape formulation standards, with the EU Green Deal's Farm-to-Fork Strategy tightening pesticide residue limits. Berlin and Hamburg urban clusters drive zero-waste reusable packaging adoption.
France
Large retailers mandate farm-level QR code disclosure for private-label organic lines, compressing verification overhead. ANSM and CNIL oversee complementary health and data frameworks affecting direct-to-consumer platforms. Paris metropolitan demand clusters most intensely for clean-label pediatric nutrition formats.
United Kingdom
London commuter corridors exhibit the most pronounced channel rotation toward subscription platforms for specialty SKUs. EU Single-Use Plastics Directive compliance costs accelerate compostable film migration in pilot deployments. The Midlands and Northern England host emerging cellulose-based barrier manufacturing trials.
Canada
Health Canada and PMRA govern organic claim substantiation and pesticide residue monitoring. Toronto and Vancouver metropolitan areas concentrate health-conscious buyer cohorts with premium tolerance for allergen-free variants. Prairie provinces in Manitoba and Saskatchewan supply organic grain inputs subject to drought cycle volatility.
Organic Snack Food Market Competitive Landscape
Capability concentration sits with integrated ingredient processors; scale advantage sits with diversified food conglomerates. The market structures around three tiers: multinational packaged food operators with backward integration into organic grain sourcing, mid-scale specialists with dedicated facility certifications, and private-label lines controlled by retail chains. Dominant competitive moves include captive supply chain construction and compostable packaging R&D partnerships.
Within the integrated processing tier, SunOpta Inc. anchors North American supply infrastructure, while General Mills Inc. exemplifies scale-driven shelf dominance through upstream control over organic grain networks. Danone occupies a position representing specialized dairy-free and plant-based sub-portfolio differentiation.
| Leading Market Players |
|---|
| General Mills Inc. |
| Hain Celestial Group |
| Danone |
| Conagra Brands Inc. |
| Frito-Lay Inc. |
| Made in Nature |
| SunOpta Inc. |
| Navitas Organics |
| Kellogg's |
| Others |
Value Network & Pricing Analysis
Minneapolis-St. Paul anchors North American organic grain processing capacity, and tolling bottlenecks during peak harvest windows translate directly into margin compression for mid-scale brands lacking captive supply. This geographic concentration of certified organic milling infrastructure creates asymmetric pricing power for integrated operators who can guarantee throughput certainty to retail buyers.
Pricing Analysis
Long-term offtake contracts with California and Pacific Northwest organic growers dominate procurement strategy, insulating volume players from spot-market volatility in almond and berry inputs. Price differentiation rests on USDA Organic certification tier and dedicated gluten-free facility status, with the latter commanding manufacturing complexity premiums. Pricing pressure stems from drought-driven organic grain input volatility in the US Midwest and Canadian prairies. Club-channel families exhibit highest price sensitivity, while health-conscious coastal metropolitan buyers tolerate premium positioning for traceability-assured SKUs.
Supply Chain Analysis
Upstream feedstock dependencies center on California almonds, Vietnam cashews, and Pacific Northwest organic berries, with each sourcing corridor exposing margins to distinct climate and trade risks. Organic certification timeline compression and auditor backlog in the US and EU create supply chain risk through delayed new product launches. Distribution runs through club channels and direct-to-consumer subscription platforms, with the latter displacing traditional distributor relationships for specialty SKUs in coastal US and London metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from private-label organic lines controlled by retail chains, which are compressing branded shelf space through margin-advantaged assortment expansion.
For Market Incumbents: Harden supply chain resilience through backward integration into organic grain sourcing networks in the US Midwest and Canadian prairies. Deepen captive processing capacity to offset tolling bottleneck risk during peak harvest windows. This defensive posture neutralizes private-label encroachment by guaranteeing traceability credentials that contract-dependent competitors cannot match. For New Entrants and Emerging Players: Establish a beachhead in German discounter channels, where organic snack assortment remains narrow relative to UK and US penetration. Target fruit-based ingredient formulations, which register the fastest volume trajectory among input categories. Lead with compostable packaging pilot deployments to satisfy EU Single-Use Plastics Directive compliance ahead of incumbent migration timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated organic ingredient processors with dedicated regulatory affairs functions over contract-dependent assemblers. Acquisition targets should demonstrate captive supply chain construction and established third-party certification infrastructure. The signal to monitor is state-level extended producer responsibility mandate expansion beyond California and Oregon, which would accelerate working capital requirements for packaging compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Organic Ingredient Supply | Backward integration into US Midwest grain networks insulates margin from drought-driven spot volatility. |
| Compostable Packaging R&D Partnership | Cellulose-based barrier pilots in UK and Nordic markets anticipate EU Single-Use Plastics Directive deadlines. |
| Direct-to-Consumer Subscription Launch | Coastal US metropolitan demand clusters favor repeat purchase velocity over traditional club-channel concentration. |
| Regenerative Agriculture Certification | USDA soil health standards offer premium positioning beyond baseline organic for climate-conscious buyer segments. |
| AI-Driven Demand Forecasting Deployment | Machine learning inventory optimization reduces working capital requirements for perishable ingredient procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of USDA organic certification databases, EU Farm-to-Fork Strategy documentation, and retail audit data from Nielsen and Circana. Category buyers at specialty retailers, supply planners at integrated processors, regulatory affairs leads at branded operators, and channel sales heads at direct-to-consumer platforms provided qualitative input. Bottom-up SKU-level demand modeling triangulates against top-down macro consumption trend analysis.
Forecast inputs include organic acreage conversion rates under EU Green Deal mandates, plant protein texturization technology maturation curves, and generational purchasing pattern shifts among Millennial and Gen Z households. Segmentation dimensions span product format, ingredient source, packaging type, and customer archetype. CAGRs derive from regression analysis of historical velocity data projected across the modeling period.
Macroeconomic conditions sit as an overlay; deviation in organic grain commodity prices, irrigation allocation regulations in California, or EU packaging compliance cost trajectories would shift the trajectory. Cross-checking against USDA National Agricultural Statistics Service acreage reports and EFSA pesticide residue monitoring data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Europe Snack Pellets Market
Snacks
North America Baked Chips Market
Snacks
Thailand Snack Bar Market
Snacks
France Energy Bar Market
Snacks
Fiber Bars Market
Snacks
UAE Snack Bar Market
Snacks
Low Calorie Cookies Market
Snacks
Mushroom Based Jerky Market
Snacks
Plant-Based Snacks Market
Snacks
Low-Fat Tortillas Market
Snacks
Snack Products Market
Snacks
South Africa Savory Snacks Market
Snacks
Forti Flakes Market
Snacks
Low-Calorie Savoury Snacks Market
Snacks
Peanut Butter Keto Snacks Market
Snacks
Europe Snack Bar Market