
 Europe Pea Starch Market | 2026-2036
Europe Pea Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pea Starch Market Foresight
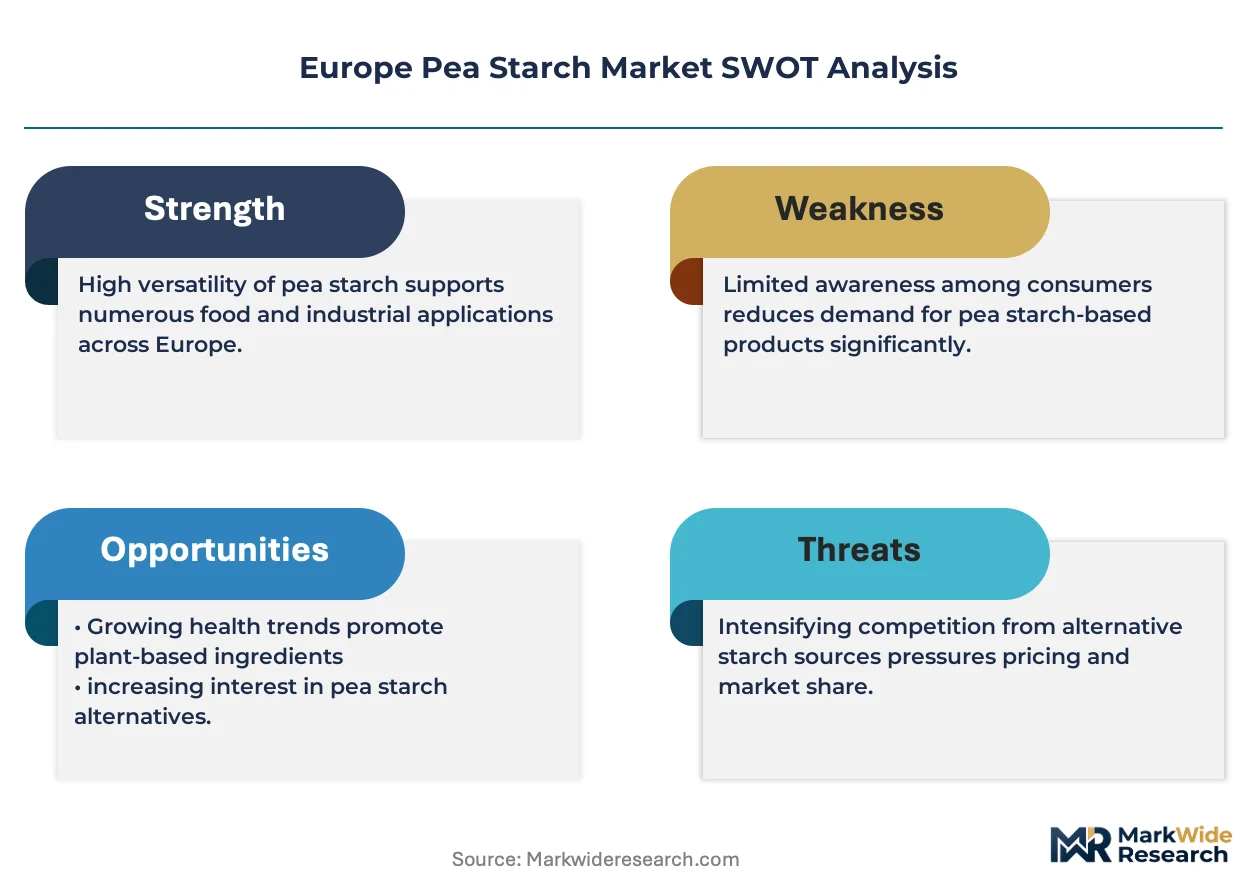
Ingredient customization revenue is reconfiguring margin pools away from commodity native starch toward modified and instant starch solutions. Roquette Frères anchors its position through deep European manufacturing scale and proprietary fractionation technology. Cosucra Groupe Warcoing differentiates via vertical integration from field to functional ingredient, controlling its organic pea supply chain. Emsland Group competes through specialized modified starch portfolios tailored to high-performance food and industrial applications.
Pea starch is the carbohydrate fraction extracted from Pisum sativum seeds, typically comprising 35-45% amylose and 55-65% amylopectin with gelatinization temperatures ranging from 60°C to 70°C depending on botanical variety and processing method. Manufacturers deploy it primarily as a gelling agent, thickener, and film-former across food systems and select industrial processes. Modified starch commands the dominant margin pool due to its engineered functionality for heat-shear stability and freeze-thaw resistance. Native starch maintains volume leadership in cost-sensitive applications such as paper sizing and basic food binding, while organic starch captures premium positioning among clean-label food manufacturers seeking non-GMO and allergen-free credentials.
EMA food additive evaluations, EU Green Deal sustainability benchmarks, and REACH chemical registration requirements collectively shape product formulation standards and raw material traceability obligations for pea starch suppliers operating across Europe. The EU F-Gas Regulation and broader decarbonization mandates are pressuring processing facilities to adopt energy-efficient wet-milling and drying technologies. Stakeholders must monitor how evolving EFSA health claims guidance and national carbon border adjustments will redraw competitive boundaries between European pea processors and imported alternatives.
Market Dynamics
The EU Green Deal and Farm-to-Fork Strategy are compressing formulation timelines for food manufacturers, forcing rapid substitution of synthetic additives with clean-label alternatives like pea starch across plant-based product lines.
Growth Catalysts
- EU Green Deal sustainability benchmarks:Mandatory carbon footprint disclosures for food ingredients are accelerating pea starch adoption as processors seek low-input crop credentials.
- Belgium and Netherlands processing clusters:Concentrated wet-milling infrastructure near port logistics reduces raw material transit losses and enables just-in-time ingredient supply.
- Clean-label texturizer demand:Plant-based meat and dairy formulators specify native and modified pea starch to replace methylcellulose and synthetic gums in binding applications.
Market Restraints
- Yellow pea input cost volatility:Weather-driven yield fluctuations in France and Baltic growing regions create margin compression for fractionators without captive supply.
- Modified starch technical limitations:Heat-shear stability gaps versus potato and tapioca derivatives restrict penetration into ultra-high-temperature processed sauces.
- REACH chemical registration friction:Novel modification chemistries face extended ECHA evaluation timelines, delaying new product commercialization by 18-24 months.
Strategic Opportunities
- Spain and Portugal underpenetration:Limited local fractionation capacity creates import substitution potential for suppliers with Iberian distribution partnerships.
- Biodegradable packaging films:Pea starch film-forming properties converge with mechanical pulp processing to replace petroleum-based barrier coatings in paperboard.
- CSRD supply chain disclosure rules:Mandatory Scope 3 emissions reporting positions vertically integrated organic pea processors for premium procurement contracts.
Industry Challenges
- Fractionation engineering talent scarcity:Specialized wet-milling process engineers command premium compensation in Belgium and northern France, constraining facility expansion timelines.
- Organic certification audit complexity:Multi-year field-to-facility traceability requirements under EU organic regulation create working capital intensity for supply chain operators.
- Retrofitting legacy spray-dryers:Energy-intensive drying infrastructure at established potato starch plants requires substantial capex to handle pea starch's distinct gelatinization profile.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pea Starch Market |
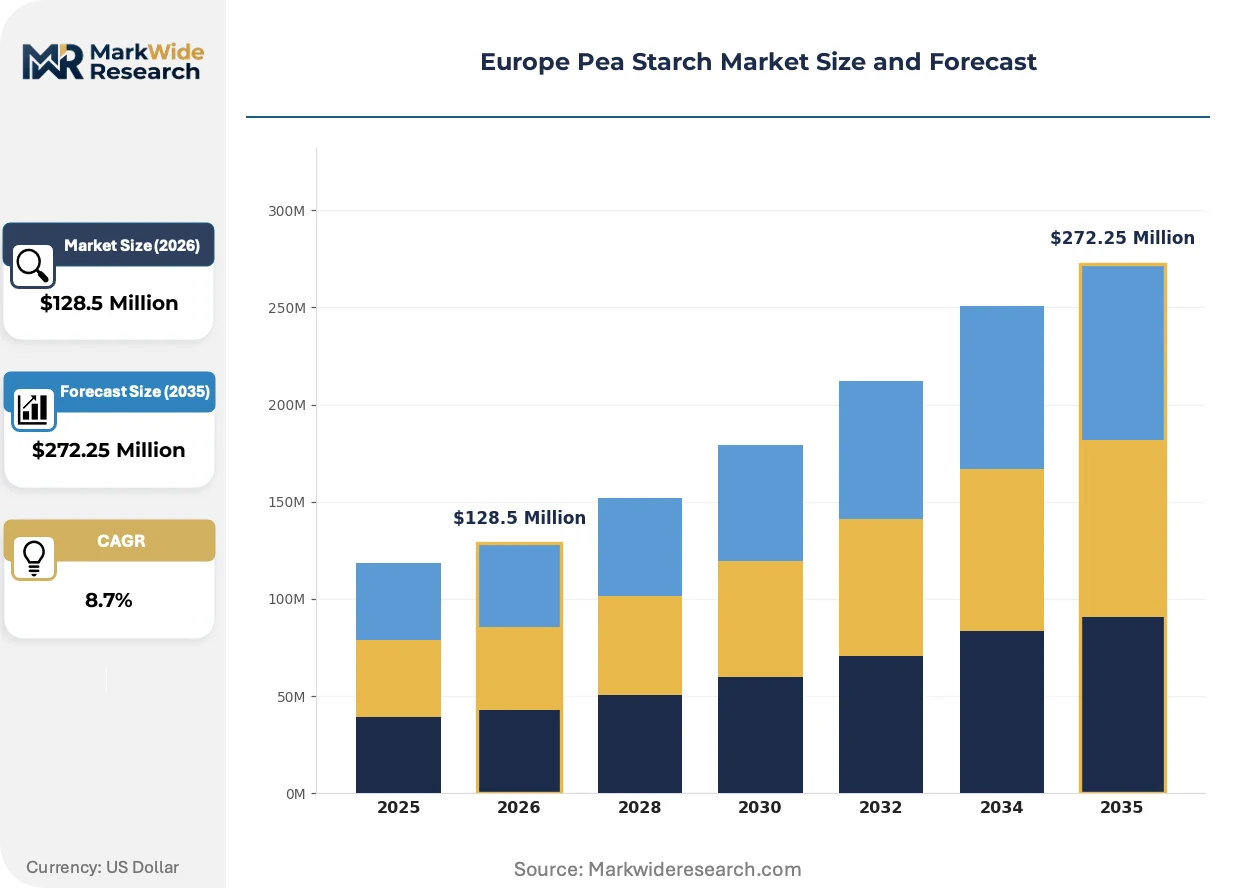
| Market Size in 2026 | $128.5 Million |
| Market Size in 2035 | $272.25 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Modified Starch, Instant Starch, Organic Starch Application: Food & Beverages, Personal Care, Textile, Paper & Packaging End User: Food Manufacturers, Cosmetics Companies, Textile Producers, Paper Mills Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Cosucra Groupe Warcoing, Meelunie B.V., Roquette Frères, Tate & Lyle, Vestkorn Milling AS, Emsland Group, Cargill, Avebe, Ingredion Incorporated, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pea Starch Market Shifts & Advancements
Pea starch functionality engineering is diverging along two paths: instant dissolution systems for beverage applications and high-amylose variants for thermoformed packaging. These parallel trajectories are fragmenting R&D investment and reshaping processor specialization.
Modified pea starch is migrating from commodity food thickeners toward engineered solutions for plant-based seafood analogues. High-moisture extrusion operators in Germany and the Netherlands specify cross-linked variants for fibrous texture replication. The technology is compressing price premiums for methylcellulose while expanding addressable volume in alternative protein formulations.
EU F-Gas Regulation phase-down schedules are forcing wet-milling facilities to abandon hydrofluorocarbon-based cooling systems. Refrigeration retrofits at starch processing plants in northern France are redirecting capital from capacity expansion toward compliance. Modified starch production lines with heat-recovery integration are capturing operational cost advantages under tightening emissions trading scheme allocations.
Clean-label procurement mandates from retail private-label divisions are displacing multi-ingredient stabilizer blends with single-source pea starch solutions. Discounters in Germany and supermarket chains in France now specify allergen-free, single-ingredient texturizers for own-brand plant-based ranges. This specification tightening concentrates volume with fractionators offering certified organic and non-GMO credential bundles.
Europe Pea Starch Market Segmentation
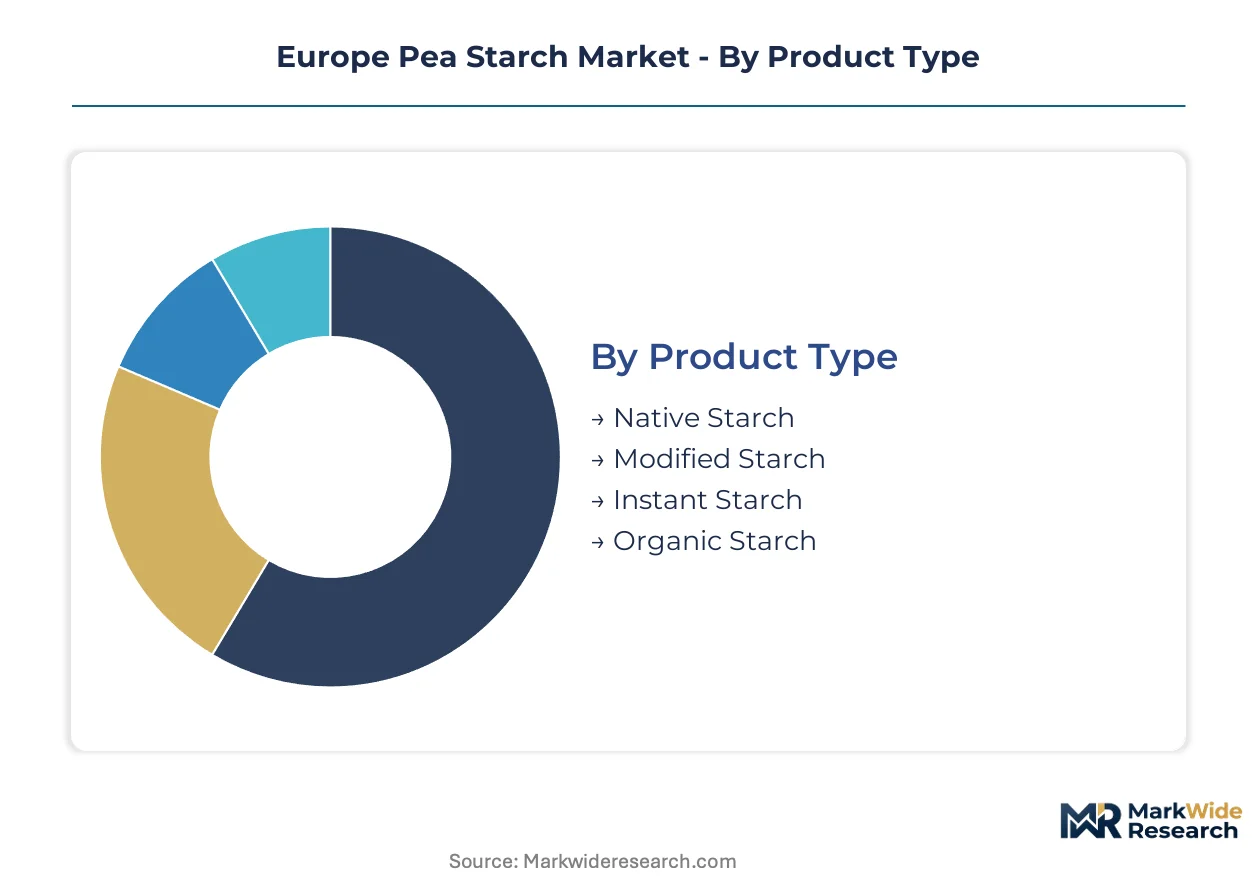
Pea starch segmentation in Europe reflects divergent technical requirements across food systems, industrial processes, and regulatory compliance tiers. Understanding these divides enables suppliers to align fractionation investments with margin concentration points and procurement specification trends.
Product Type:
Mature modified starch solutions coexist with emerging instant and organic variants as formulators balance performance demands against clean-label procurement mandates.
- Native Starch:Extracted through standard wet-milling without chemical alteration, retaining 35-45% amylose content and gelatinization temperatures of 60-70°C. Cost-sensitive paper mills in northern France and basic food binders specify this grade for volume applications where functional precision is secondary to input economics.
- Modified Starch:Engineered through cross-linking, acetylation, or oxidation to deliver heat-shear stability and freeze-thaw resistance. Plant-based meat extrusion operators in Germany and the Netherlands command premium positioning for cross-linked variants that replicate fibrous textures in high-moisture analogues.
- Instant Starch:Pre-gelatinized for cold-water solubility, targeting beverage emulsions and instant soup applications. Ready-meal manufacturers specify this grade to eliminate hydration steps in production lines.
- Organic Starch:Certified under EU organic regulation with full field-to-facility traceability. Retail private-label divisions in France and Germany specify this grade for allergen-free, non-GMO credential bundles in premium plant-based ranges.
Modified starch retains volume leadership; organic starch holds the steepest expansion curve.
Application:
Application demand stratifies across performance tiers, with food systems commanding formulation complexity and industrial segments prioritizing cost efficiency.
- Food & Beverages:Dominates value capture through gelling, thickening, and film-forming functions in plant-based dairy, meat analogues, and gluten-free bakery. Clean-label mandates from E.Leclerc and Carrefour private-label divisions are displacing multi-ingredient stabilizer blends with single-source pea starch solutions.
- Personal Care:Absorbs high-purity organic grades for powder formulations and natural emulsions. Cosmetic manufacturers in Belgium specify allergen-free texturizers for sensitive-skin product lines.
- Textile:Deploys native starch for warp sizing in linen and cotton processing. Portuguese textile clusters import modified variants for synthetic fiber finishing where petroleum-based alternatives face sustainability scrutiny.
- Paper & Packaging:Utilizes native starch for surface sizing and biodegradable barrier coatings. Mechanical pulp processors in Sweden and Finland are evaluating pea starch film-formers to replace petroleum-based coatings in paperboard.
Food and beverages retains volume leadership; paper and packaging holds the steepest expansion curve.
End User:
End-user procurement patterns diverge between integrated multinationals with captive technical teams and specialized processors dependent on distributor technical support.
- Food Manufacturers:Span multinational plant-based protein specialists to regional bakery cooperatives. High-moisture extrusion operators in the Netherlands specify cross-linked modified starch for fibrous texture replication.
- Cosmetics Companies:Concentrate in France and Switzerland, demanding certified organic grades with batch-level allergen documentation.
- Textile Producers:Cluster in Portugal and northern Italy, sourcing native starch for traditional warp sizing applications.
- Paper Mills:Concentrate in Nordic and Baltic regions, evaluating pea starch barrier coatings under EU Green Deal circular economy benchmarks.
Food manufacturers retain volume leadership; paper mills hold the steepest expansion curve.
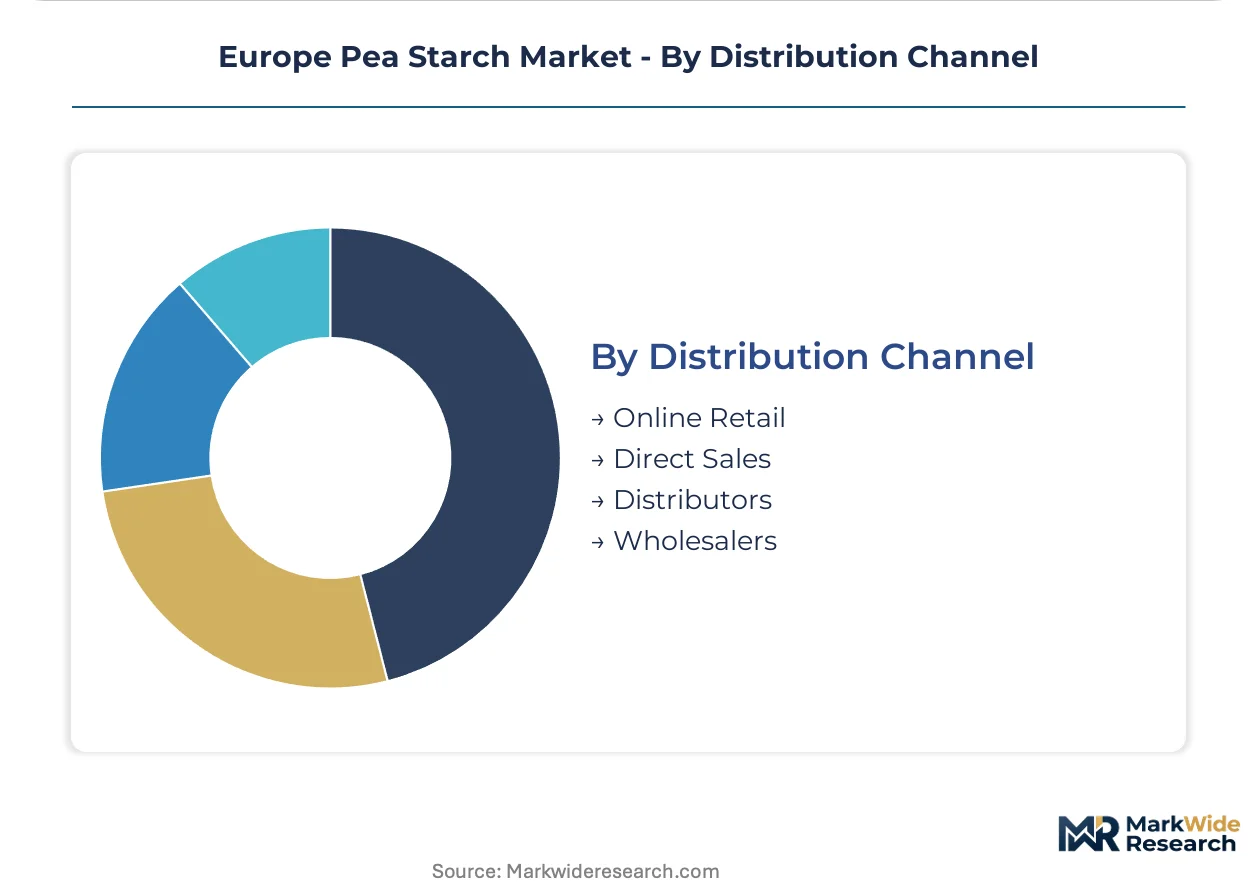
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to fractionation infrastructure.
- Direct Sales:Dominates large-volume contracts between fractionators and multinational food manufacturers. Roquette Frères and Cosucra Groupe Warcoing maintain dedicated technical service teams for plant-based formulation partners.
- Distributors:Capture mid-tier processors requiring smaller lot sizes and just-in-time delivery. Benelux-based ingredient distributors warehouse modified starch variants for German and French compounders.
- Wholesalers:Serve paper mills and textile producers with standardized native starch grades where technical consultation is minimal.
- Online Retail:Emerging channel for organic starch in artisanal food and cosmetic micro-producers, constrained by bulk packaging economics.
Direct sales retains volume leadership; online retail holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across European procurement zones. Benelux buyers absorb premium modified starch for plant-based extrusion, while Baltic paper mills drive hard on native starch input costs. Mediterranean markets remain underpenetrated, creating arbitrage windows for distributors with Iberian warehousing.
France
Plant-based meat formulators in Hauts-de-France specify cross-linked modified starch for high-moisture extrusion systems. The EU Green Deal Farm-to-Fork Strategy mandates carbon footprint disclosures that favor domestic yellow pea sourcing over Baltic imports. Roquette Frères operates fractionation facilities in Lestrem with proprietary wet-milling technology serving E.Leclerc and Carrefour private-label divisions.
Belgium
Cosmetics manufacturers in Brussels and Liège procure certified organic grades for sensitive-skin powder formulations. REACH chemical registration requirements under ECHA jurisdiction delay novel modification chemistries by 18-24 months. The Port of Antwerp wet-milling cluster enables just-in-time supply to German compounders with reduced transit losses.
Netherlands
High-moisture extrusion operators in Gelderland and Overijssel command cross-linked variants for fibrous texture replication in seafood analogues. The EU F-Gas Regulation phase-down forces refrigeration retrofits at starch processing facilities, redirecting capital from capacity expansion. Emsland Group maintains modified starch technical service teams for plant-based protein specialists in the Amsterdam-Rotterdam corridor.
Germany
Discount retail private-label divisions in Bavaria and North Rhine-Westphalia specify single-ingredient allergen-free texturizers for own-brand plant-based ranges. The CSRD supply chain disclosure rules position vertically integrated organic processors for premium procurement contracts. Ingredient distributors in Hamburg warehouse modified starch variants for mid-tier compounders requiring smaller lot sizes.
Spain
Textile producers in Catalonia import modified variants for synthetic fiber finishing where petroleum-based alternatives face sustainability scrutiny. Limited local fractionation capacity creates import substitution potential for suppliers with Iberian distribution partnerships. Barcelona-based mechanical pulp processors evaluate pea starch film-formers under EU Green Deal circular economy benchmarks.
Europe Pea Starch Market Competitive Landscape
Capability concentration sits with fractionators commanding proprietary wet-milling technology; scale advantage sits with diversified ingredient conglomerates with multi-crop portfolios. The vendor base stratifies across three tiers: integrated specialists with captive organic supply chains, regional modified starch engineers, and commodity traders sourcing Baltic native grades. Dominant competitive moves include backward integration into yellow pea cultivation and strategic partnerships with plant-based protein extrusion operators.
Within the integrated specialist tier, Cosucra Groupe Warcoing and Roquette Frères exemplify divergent approaches to supply chain control. Cosucra represents the archetype of field-to-functional-ingredient verticality, while Roquette occupies a position emphasizing European manufacturing scale and proprietary fractionation technology. Emsland Group sits within the specialized modified starch engineering segment, serving high-performance food and industrial applications.
| Leading Market Players |
|---|
| Cosucra Groupe Warcoing |
| Meelunie B.V. |
| Roquette Frères |
| Tate & Lyle |
| Vestkorn Milling AS |
| Emsland Group |
| Cargill |
| Avebe |
| Ingredion Incorporated |
| Others |
Supply & Pricing Matrix
The Port of Antwerp wet-milling cluster concentrates European fractionation capacity, translating just-in-time logistics advantages into pricing power over German and French compounders dependent on modified starch supply security.
Pricing Analysis
Ingredient customization revenue drives lifetime value across European pea starch portfolios. Three-tier pricing structure across premium organic, performance modified, and economy native levels stratifies procurement contracts. Price differentiation rests on certification grade and volume scale, with CSRD disclosure requirements pushing premiums for vertically integrated organic supply. Cost compression in standard modified grades is intensifying because Baltic yellow pea input volatility compresses fractionator margins. Baltic paper mills exhibit highest price sensitivity, while Dutch high-moisture extrusion operators absorb premiums for cross-linked variants.
Supply Chain Analysis
REACH chemical registration requirements under ECHA jurisdiction function as de facto export controls, delaying novel modification chemistries and limiting flows of innovative starch variants into European food systems. Supply concentrates in France, Belgium, and the Netherlands, with Baltic regions feeding native grade inputs. The chain draws from yellow pea cultivation, wet-milling infrastructure, and spray-drying capacity. Single-source vulnerability sits with specialized fractionation engineering talent concentrated in northern France. Distribution runs through direct sales for multinational food manufacturers, with Benelux distributors capturing mid-tier compounder demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pea starch procurement is shifting toward service-attach models where technical formulation support and certified organic traceability generate recurring revenue expanding faster than commodity native starch volume.
For Market Incumbents: Pre-empt margin erosion from Baltic commodity traders by deepening backward integration into organic yellow pea cultivation in Hauts-de-France and accelerating proprietary instant starch R&D for beverage applications. Captive supply of certified organic raw material secures CSRD-compliant procurement contracts from E.Leclerc and Carrefour private-label divisions. Capacity addition in Iberian distribution partnerships defends against import substitution threats in Spain and Portugal. For New Entrants and Emerging Players: Iberian underpenetration offers white-space expansion for suppliers establishing Barcelona-based warehousing and technical service capabilities. Target biodegradable packaging film applications in Swedish and Finnish mechanical pulp processing, where EU Green Deal circular economy benchmarks displace petroleum-based barrier coatings. Lead with organic certification bundles and allergen-free documentation to capture artisanal cosmetic micro-producers in France and Switzerland. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fractionators with captive organic supply chains and dedicated technical service teams for plant-based protein extrusion operators. Long-term viability across the analysis window favors processors with heat-recovery integrated modified starch lines and established E.Leclerc or Carrefour supply relationships. Monitor EFSA health claims guidance evolution as inflection indicator for clean-label texturizer specification tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captive yellow pea supply secures CSRD-compliant procurement contracts from major French retailers. |
| Heat-Recovery Technology Retrofit | EU F-Gas Regulation compliance redirects capital while capturing operational cost advantages under emissions trading. |
| Iberian Distribution Partnership | Barcelona-based warehousing addresses Spain and Portugal import substitution potential for underpenetrated markets. |
| Instant Starch R&D Expansion | Pre-gelatinized variants target beverage emulsion applications with cold-water solubility specifications. |
| Biodegradable Film-Former Development | Pea starch barrier coatings align with EU Green Deal circular economy benchmarks in Nordic paperboard. |
Research Methodology
Desk research of EU regulatory filings, trade customs data, and EFSA guidance documents preceded structured interviews with fractionation plant managers, procurement leads at Dutch high-moisture extrusion operators, technical R&D directors at Belgian cosmetics manufacturers, and distribution channel partners across Benelux. Secondary validation drew from SEC filings of diversified ingredient conglomerates, Cefic chemical industry reports, and national carbon border adjustment proposals. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and end-user segments.
Assumptions held fixed include EU Green Deal Farm-to-Fork Strategy implementation timelines and REACH registration requirement stability, while input cost volatility and EFSA health claims evolution were modeled as scenario variables. Segmentation dimensions spanned product grade tier, end-use industry, and regional processing hub concentration. CAGRs were derived from trend extrapolation validated against primary interview forward guidance, with pea protein co-product economics and modified starch functionality premiums as key forecast inputs across the projection horizon.
Practitioners should monitor EFSA health claims guidance publication and national carbon border adjustment implementation for early signals of specification or sourcing disruption. Forecasts reflect these documented assumptions. Material shifts in EU organic certification audit complexity or Baltic yellow pea yield patterns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Spelt Flour Market
Ingredients
Volatile Fatty Acids Market
Ingredients
Global Autolyzed Yeast Extract Market
Ingredients
Corn-Based Ingredients Market
Ingredients
Yeast and Yeast Extract Market
Ingredients
Instant Dry Yeast Market
Ingredients
Shortening Powder Market
Ingredients
Vegetable Glycerin Market
Ingredients
North America Feed Yeast Market
Ingredients
Phytogenic Market
Ingredients
Asia-Pacific Carrageenan Market
Ingredients
Corn Steep Liquor Market
Ingredients
Millet Protein Market
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
Passion Fruit Powder Market
Ingredients
Hexane-Free Protein Market