
 Protein Powder Market | 2026-2036
Protein Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Powder Market Analysis
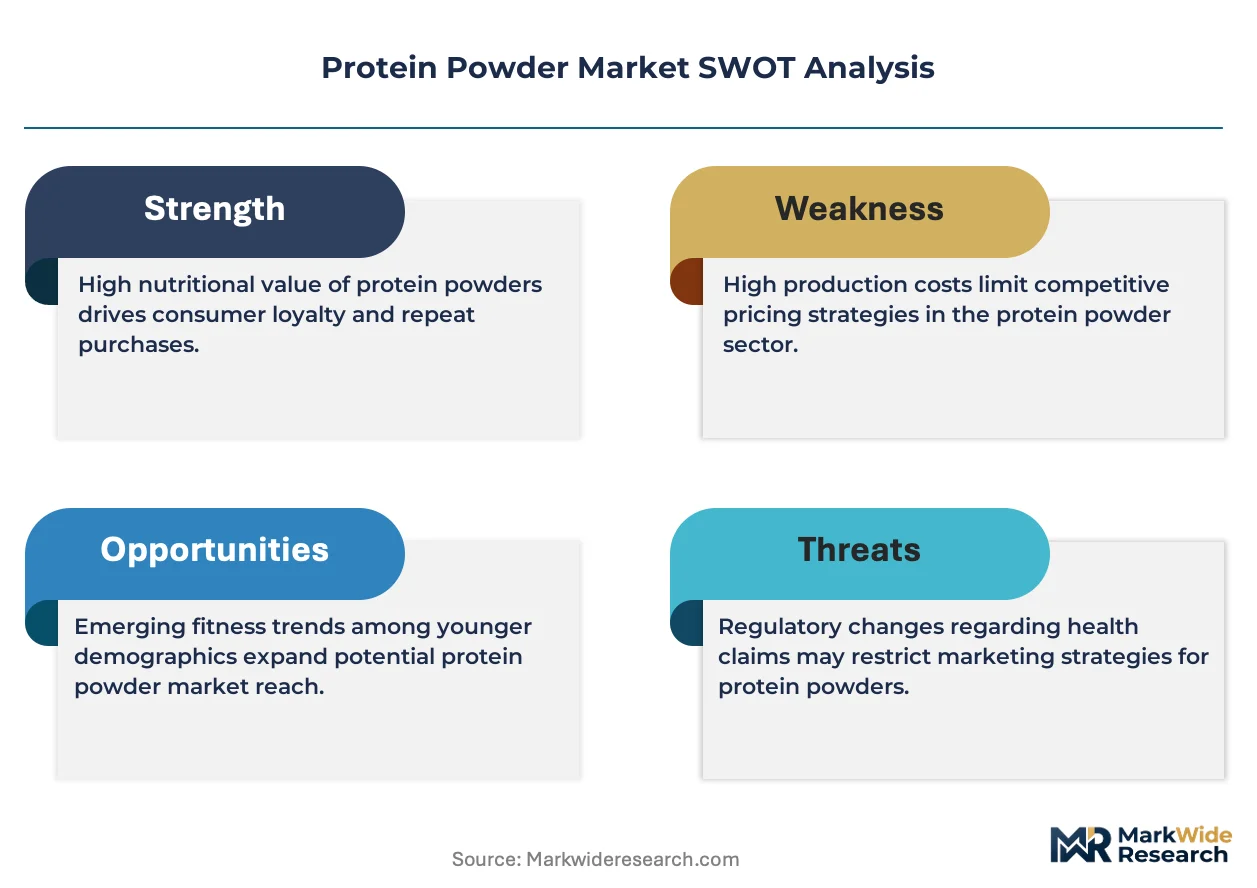
CE marking under the EU's evolving food supplement directives is recalibrating the cost-of-entry calculus for protein powder manufacturers seeking European market access. Weider Global Nutrition LLC leverages its long-standing distribution infrastructure to sustain shelf presence across mass retail and specialty channels. Transparent Labs differentiates through third-party testing protocols and transparent sourcing disclosures that resonate with ingredient-conscious buyers. Nutrafill LLC specializes in private-label and white-label manufacturing, occupying a critical middle tier between branded players and contract producers.
Protein powder refers to concentrated or isolated protein derived from animal or plant sources, processed through filtration, enzymatic hydrolysis, or ion exchange to achieve protein contents ranging from 70% to 90% by dry weight, formulated for muscle protein synthesis support and dietary supplementation. Whey protein dominates value generation due to its complete amino acid profile and rapid absorption kinetics, while pea protein is expanding fastest among plant-based alternatives as allergen-free positioning captures flexitarian households. The powder form retains the largest volume share, though ready-to-drink formats are capturing incremental margin pools through convenience premiums in gym and convenience retail channels.
The FDA exercises post-market surveillance over dietary supplements through adverse event reporting and current Good Manufacturing Practice enforcement, while the USDA oversees organic certification claims that command price premiums in natural retail. EFSA's health claim authorization process in Europe restricts permissible marketing language, forcing reformulation and evidence investment for products targeting EU consumers. Stakeholders must monitor regulatory divergence between jurisdictions and decide whether to pursue harmonized global formulations or region-specific product architectures.
Market Dynamics
The protein powder market is bifurcating between legacy whey-dominant supply chains and emerging plant-protein infrastructure, with clean-label certification requirements from FDA and EFSA forcing simultaneous reformulation and documentation investments that favor scaled manufacturers over artisan entrants.
Growth Catalysts
- Clean-label mandates:FDA's evolving dietary supplement enforcement posture is accelerating third-party testing adoption. Manufacturers investing in transparent sourcing protocols capture premium shelf positioning in natural retail channels.
- Gym culture maturation:Direct-to-consumer subscription models in the United States are compressing traditional wholesale margins. Fitness enthusiasts now expect personalized flavor profiles and delivery cadences.
- Flexitarian household expansion:Pea protein extraction technology is automating allergen-free formulation at scale. Flexitarian buyers in Germany and the United Kingdom are displacing soy-dominant legacy SKUs.
Market Restraints
- Milk powder price volatility:Whey protein concentrate costs track global dairy commodity swings. New Zealand and EU dairy policy shifts transmit directly into margin pressure for animal-protein formulators.
- Supply concentration risk:Ion-exchange resin production for protein isolation concentrates among three specialty chemical suppliers. Any disruption to German or Japanese resin manufacturing cascades through filtration capacity.
- EFSA health claim restrictions:The European Food Safety Authority's evidence thresholds for muscle-protein-synthesis marketing language force costly clinical trials. Smaller EU entrants lack capital to build authorized claim portfolios.
Strategic Opportunities
- Underpenetrated Indian market:FSSAI's evolving protein-supplement classification creates first-mover advantage for compliant foreign entrants. Urban gym penetration in Mumbai and Bangalore remains below US saturation levels.
- Cell-cultured protein convergence:Precision fermentation technology is converging with traditional powder processing. Hybrid formulations blending dairy and fermented proteins offer novel amino acid completeness.
- Convenience retail channel expansion:Ready-to-drink protein formats are capturing incremental margin pools in Japanese konbini chains. Powder-to-bottle single-serve packaging reduces consumer preparation friction.
Industry Challenges
- Formulation talent scarcity:Food scientists with dual expertise in sports nutrition and clean-label stabilization command premium compensation. Recruitment pipelines from university programs lag industry demand.
- Organic certification timelines:USDA organic approval for protein sourcing requires 18-24 month documentation cycles. Brands launching certified SKUs face working capital strain during qualification periods.
- Cross-border formulation complexity:Divergent maximum-permitted-protein claims between FDA and EFSA jurisdictions force SKU proliferation. Harmonized global architectures remain economically elusive.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Powder Market |
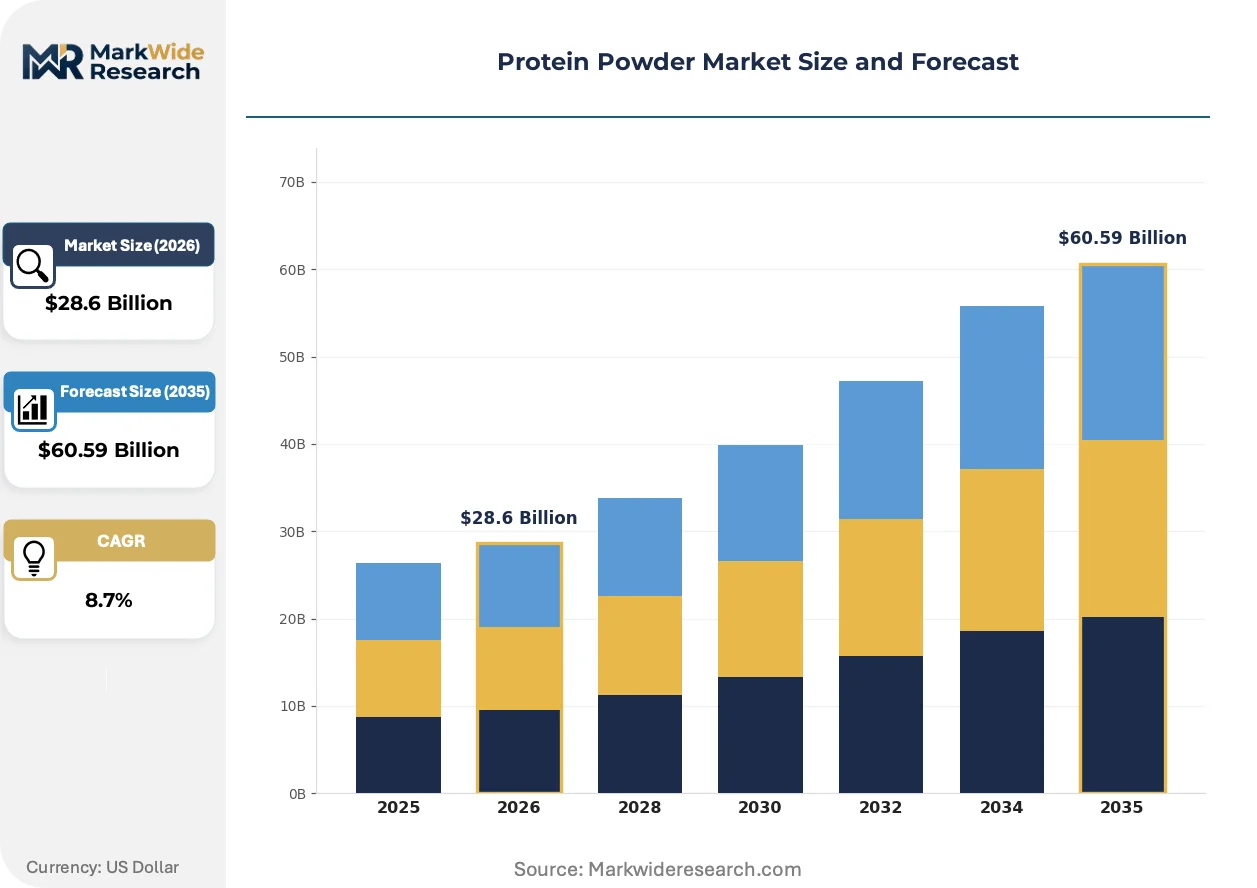
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Soy Protein, Pea Protein End User: Athletes, Fitness Enthusiasts, Bodybuilders, General Consumers Form: Powder, Ready-to-Drink, Bars, Capsules Distribution Channel: Online Retail, Health Stores, Gyms, Supermarkets |
| Companies Covered | Weider Global Nutrition LLC, Eagle Labs, Inc, ABS Corporation, Transparent Labs, WB Blends, Handian Nutrition, Nutrafill LLC, Swolverine, The Green Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Powder Market Emerging Trajectories
Protein powder manufacturing is experiencing simultaneous pressure from automation investments, regulatory documentation burdens, and channel fragmentation that rewards agile formulation over static product lines.
Membrane filtration technology is automating protein concentration and isolation workflows. Mid-sized manufacturers in the Netherlands and California are adopting ceramic microfiltration systems to reduce enzymatic processing steps. This automation is compressing batch-to-batch variation and enabling real-time quality monitoring that satisfies third-party audit requirements.
REACH regulation updates in the European Union are tightening disclosure obligations for processing aids and residual solvents in protein isolation. Manufacturers exporting to EU member states must now document supply chain chemical footprints through extended safety data sheets. Plant-protein suppliers with organic certification are responding fastest due to pre-existing documentation infrastructure.
Subscription-based replenishment models are displacing traditional retail replenishment cycles in the United States. Direct-to-consumer brands capture lifetime value through personalized flavor rotation and workout-calendar integration. This behavioral shift is most visible among CrossFit-affiliated consumers in Texas and Florida who prioritize convenience over in-store discovery.
Protein Powder Market Segmentation
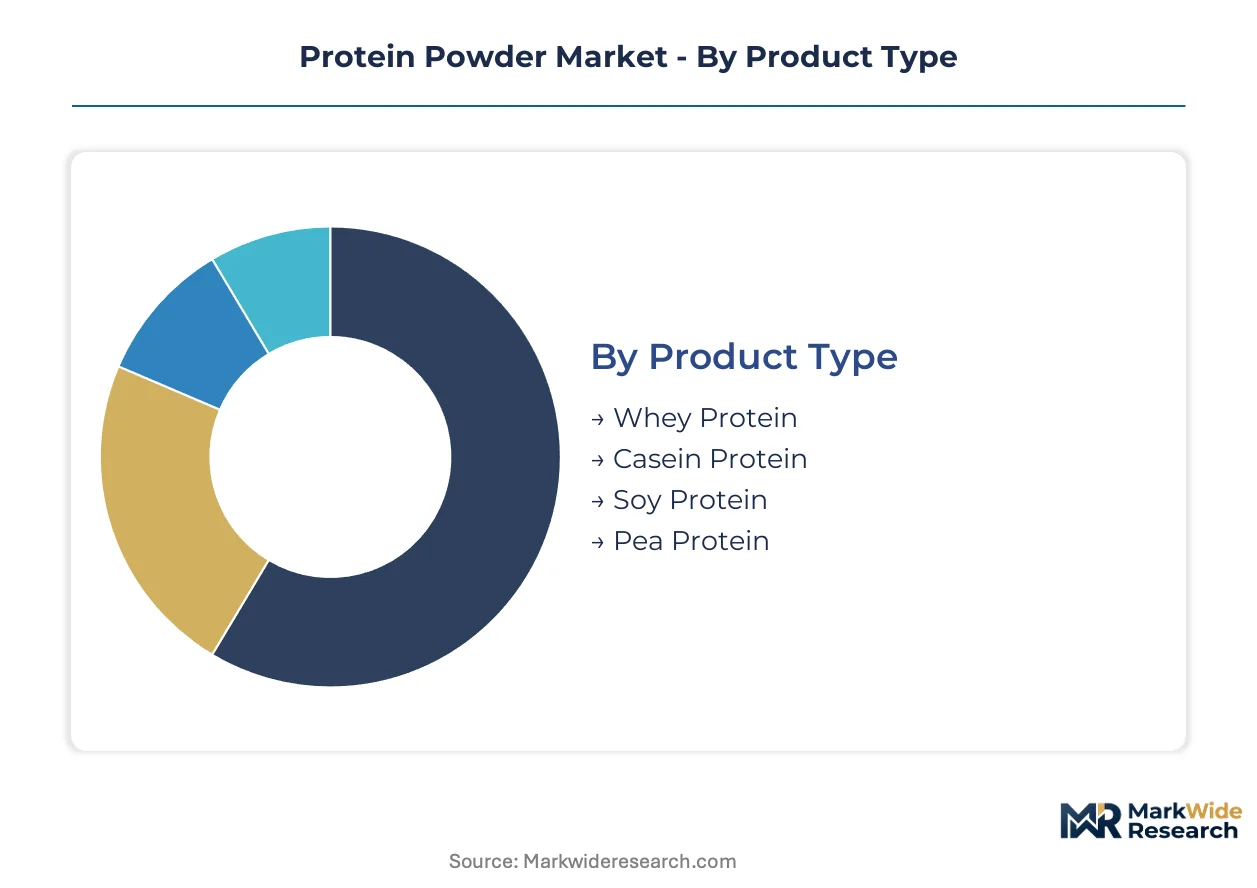
Protein powder segmentation reveals how regulatory requirements fragment across product architectures. FDA dietary supplement enforcement and EFSA health claim authorization create divergent compliance burdens that reshape which segments manufacturers prioritize.
Product Type:
FDA's evolving cGMP enforcement and EFSA's evidence thresholds for muscle-protein-synthesis claims impose asymmetric compliance costs across protein sources. Animal-derived proteins face dairy commodity volatility documentation, while plant proteins navigate novel food ingredient pathways.
- Whey Protein:Concentrates and isolates derived from cheese manufacturing byproducts achieve 70-90% protein content through ultrafiltration and ion exchange. Demand concentrates among CrossFit-affiliated consumers in Texas and Florida who prioritize rapid absorption kinetics for post-workout recovery. FDA's dairy facility registration requirements add traceability layers that favor established processors.
- Pea Protein:Yellow split pea isolates processed through dry fractionation and wet extraction achieve amino acid profiles approaching dairy completeness. Flexitarian households in Germany and the United Kingdom displace soy-dominant legacy SKUs as allergen-free positioning captures clean-label premiums. EFSA's novel food consultations delay EU market entry for innovative extraction methods.
- Casein Protein:Micellar structures from milk curd provide slow-release amino acid delivery overnight.
- Soy Protein:Isolate and concentrate forms face declining preference among ingredient-conscious buyers despite cost advantages.
Leading the category by volume: Whey Protein. Expanding most quickly: Pea Protein.
End User:
Customer archetypes diverge sharply in purchasing cadence and channel preference. Subscription models and personalized flavor rotation capture lifetime value differently across engagement levels.
- Fitness Enthusiasts:Recreational gym-goers purchasing 2-4 servings weekly drive powder volume through direct-to-consumer channels. Mumbai and Bangalore urban professionals adopt protein supplementation as gym penetration deepens below US saturation benchmarks. Personalized delivery cadences and workout-calendar integration sustain retention.
- Athletes:Competitive and collegiate performers require batch-tested certifications for anti-doping compliance. Third-party testing protocols from NSF Certified for Sport and Informed Sport command premium positioning. Procurement concentrates through specialty retailers and team nutrition partnerships.
- Bodybuilders:High-volume consumers prioritize cost-per-gram protein efficiency over flavor innovation.
- General Consumers:Wellness-oriented buyers entering the category through convenience retail and mass-market discovery.
Highest revenue per capita: Athletes. Broadest addressable base: General Consumers.
Form:
Manufacturing capital intensity and margin architecture vary dramatically across physical formats. Powder production leverages existing dairy and grain processing infrastructure, while liquid formats require aseptic filling investments.
- Powder:Dry-blended concentrates and isolates packaged in multi-serve containers dominate manufacturing scale economics. Ceramic microfiltration adoption in Netherlands and California facilities reduces batch-to-batch variation. Shelf stability enables global distribution without cold chain dependencies.
- Ready-to-Drink:UHT-processed beverages in single-serve bottles capture convenience premiums in Japanese konbini chains and US gym coolers. Powder-to-bottle packaging innovations reduce preparation friction for time-constrained consumers. Aseptic filling capacity constraints limit new entrant participation.
- Bars:Extruded and cold-pressed formats compete in broader snack replacement occasions.
- Capsules:Encapsulated isolates serve precision-dosing preferences in clinical and travel contexts.
Dominant volume share: Powder. Steepest margin expansion: Ready-to-Drink.
Distribution Channel:
Channel economics reflect working capital requirements and customer acquisition cost structures. Direct relationships compress wholesale margins while demanding fulfillment infrastructure investment.
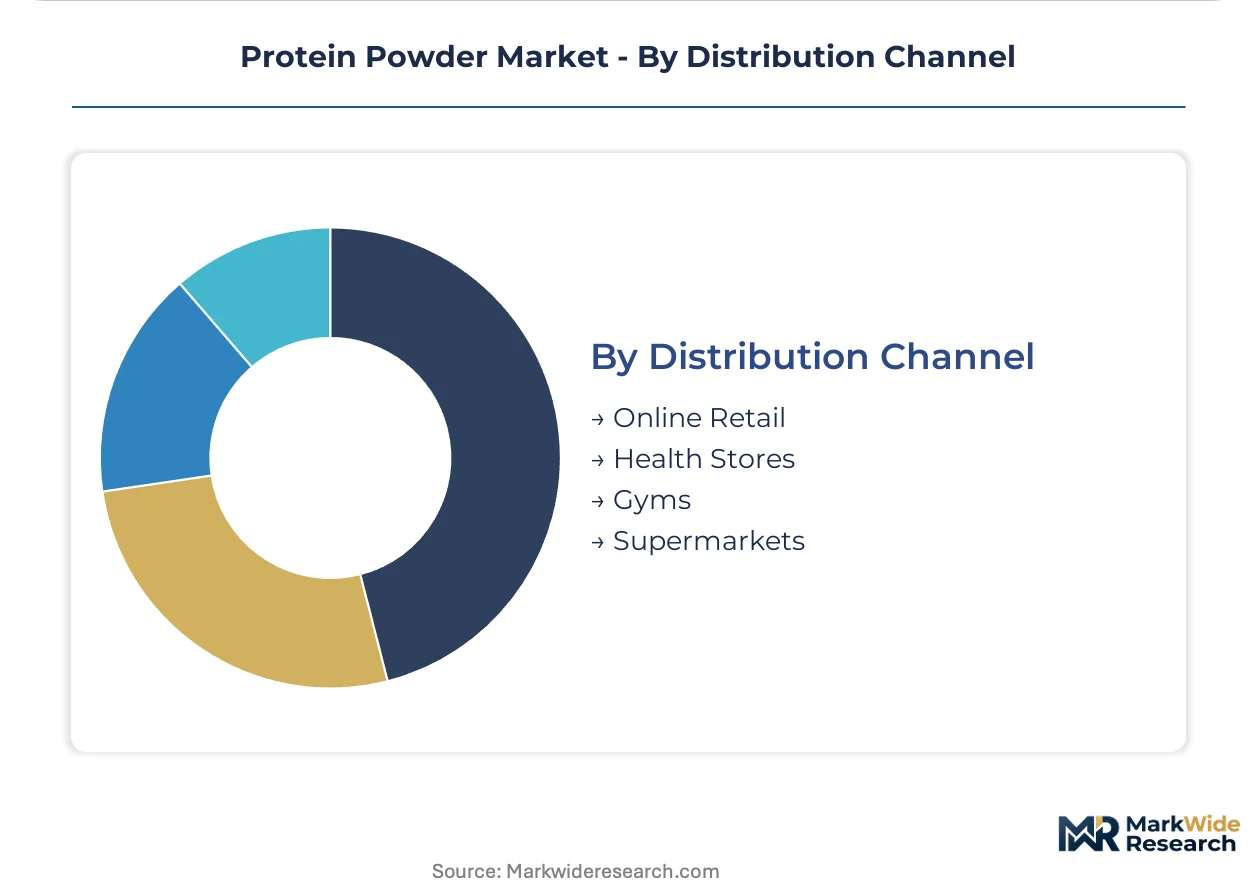
- Online Retail:Subscription-based replenishment models displace traditional retail cycles through personalized flavor rotation. Texas and Florida CrossFit communities demonstrate highest direct-to-consumer conversion rates. Lifetime value capture depends on churn management and workout-calendar integration.
- Health Stores:Natural retail channels command organic certification premiums and transparent sourcing disclosures. USDA organic approval documentation requirements strain working capital during 18-24 month qualification periods. Staff education investments sustain premium positioning.
- Gyms:On-site vending and pro-shop placement captures impulse consumption at point of exertion.
- Supermarkets:Mass retail placement requires slotting fee negotiations and promotional calendar alignment.
Highest growth trajectory: Online Retail. Maintaining premium positioning: Health Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where gym culture and direct-to-consumer channels have matured fastest. Protein powder consumption patterns diverge sharply across regulatory jurisdictions, with FDA enforcement, EFSA health claim restrictions, and FSSAI classification schemes reshaping market entry economics.
United States
Fitness enthusiasts in Texas and Florida drive powder volume through personalized subscription models. FDA's evolving cGMP enforcement accelerates third-party testing adoption among new entrants. CrossFit-affiliated communities in Dallas and Miami demonstrate the highest direct-to-consumer conversion rates for flavor-rotation services.
Germany
Flexitarian households in Berlin and Munich displace soy-dominant SKUs with allergen-free pea protein alternatives. EFSA's novel food consultations delay EU market entry for innovative extraction methods. The Bavarian industrial corridor hosts ceramic microfiltration equipment suppliers serving Central European processors.
India
Urban professionals in Mumbai and Bangalore adopt protein supplementation as gym penetration deepens below US benchmarks. FSSAI's evolving protein-supplement classification creates first-mover advantage for compliant foreign entrants. Maharashtra's warehousing clusters enable direct-to-consumer fulfillment for international brands.
United Kingdom
Clean-label buyers in London and Manchester command transparent sourcing disclosures and organic certification premiums. REACH regulation updates tighten disclosure obligations for processing aids in protein isolation. The Midlands logistics hub supports pan-European distribution for brands qualifying EFSA health claims.
Japan
Convenience-seeking consumers in Tokyo and Osaka capture ready-to-drink premiums through konbini chain distribution. METI standards for functional food claims constrain permissible marketing language for muscle-protein-synthesis positioning. The Kanto manufacturing belt concentrates aseptic filling capacity for liquid format production.
Protein Powder Market Vendor Landscape
United States producers anchor the premium tier with direct-to-consumer infrastructure; European specialists hold regulatory compliance advantages. The vendor base fragments across branded manufacturers, private-label contractors, and ingredient technology providers. Three archetypes dominate: legacy distributors with mass retail shelf presence, transparency-focused challengers with third-party testing protocols, and white-label manufacturers occupying the middle tier between branded players and contract producers. Competitive moves concentrate on subscription platform development and clean-label certification acquisition.
Within the transparency-focused tier, Transparent Labs exemplifies third-party testing protocols and sourcing disclosure standards that resonate with ingredient-conscious buyers. Weider Global Nutrition LLC occupies a position among legacy distributors leveraging long-standing infrastructure across mass retail and specialty channels. Nutrafill LLC sits within the white-label manufacturing archetype, bridging branded players and contract producers in private-label supply chains.
| Leading Market Players |
|---|
| Weider Global Nutrition LLC |
| Eagle Labs, Inc |
| ABS Corporation |
| Transparent Labs |
| WB Blends |
| Handian Nutrition |
| Nutrafill LLC |
| Swolverine |
| The Green Labs |
| Others |
Supply Flow & Price Mechanics
Fitness enthusiasts in Texas and Florida drive subscription-based purchasing that anchors the dominant pricing model around recurring replenishment rather than spot transactions. This buyer concentration compresses wholesale margins while rewarding direct-to-consumer brands with predictable revenue streams and customer lifetime value capture.
Pricing Analysis
Short lead-time premiums command shelf positioning in health stores and gym pro-shops where immediate consumption needs override price sensitivity. Three-tier pricing structure across premium, standard, and economy levels separates NSF Certified for Sport formulations from conventional third-party tested SKUs and unverified commodity powders. Cost compression in economy whey tiers is intensifying because New Zealand dairy commodity swings transmit directly into margin pressure. General consumers entering through mass retail demonstrate highest price sensitivity, while competitive athletes purchasing batch-tested certifications show least elasticity.
Supply Chain Analysis
Direct-to-consumer channels handle subscription buyer demand through fulfillment infrastructure concentrated in Texas and Florida distribution clusters. Raw material sourcing draws from New Zealand and EU dairy cooperatives for whey isolates, while yellow split pea protein concentrates increasingly feed from Canadian and Chinese dry fractionation facilities. Single-source vulnerability concentrates in German and Japanese ion-exchange resin suppliers whose disruption would cascade through protein isolation capacity. Distribution runs through direct-to-consumer platforms, natural retail channels, and gym pro-shops with divergent working capital requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Upstream control over organic certification documentation and captive pea protein extraction capacity has become the decisive vertical-integration race as clean-label mandates harden compliance thresholds.
For Market Incumbents: Anchor shelf presence through backward integration into ceramic microfiltration equipment and captive organic certification pipelines. Defend against transparency-focused challengers by accelerating third-party testing protocol adoption ahead of FDA cGMP enforcement evolution. Prioritize direct-to-consumer subscription platform investments in Texas and Florida metro clusters where CrossFit-affiliated conversion rates peak. For New Entrants and Emerging Players: Enter via FSSAI-compliant formulations targeting Mumbai and Bangalore urban professionals where gym penetration remains below saturation benchmarks. Exploit white-space in allergen-free pea protein SKUs for flexitarian households in Germany and the United Kingdom. Pursue white-label manufacturing partnerships with Nutrafill LLC archetypes to bypass capital-intensive filtration infrastructure. For Investors and Strategic Acquirers: The window for entry favors mid-tier private-label manufacturers with pre-existing organic certification documentation infrastructure. Long-term viability hinges on acquisition targets possessing REACH-compliant supply chain disclosure systems and EFSA health claim authorization portfolios. Monitor ceramic microfiltration equipment order backlogs from Netherlands and California suppliers as inflection indicators for automation-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Certification | USDA approval timelines strain working capital during 18-24 month qualification cycles. |
| Ceramic Microfiltration Equipment Deployment | Netherlands and California facilities reduce batch-to-batch variation for third-party audit compliance. |
| Direct-to-Consumer Subscription Platform Launch | Texas and Florida CrossFit communities demonstrate highest flavor-rotation service conversion rates. |
| EFSA Health Claim Authorization Investment | Clinical trial evidence thresholds restrict permissible muscle-protein-synthesis marketing language in EU markets. |
| Pea Protein Extraction Capacity Expansion | Yellow split pea isolate automation captures flexitarian household displacement of soy-dominant legacy SKUs. |
Methodological Framework
SEC 10-K filings, customs and trade data, and FDA cGMP enforcement records formed the secondary backbone for supply chain and regulatory trajectory assessment. Primary interviews with sports nutrition formulators, natural retail category buyers, and gym pro-shop procurement managers combined with secondary validation through EFSA novel food consultation databases and FSSAI classification circulars. Bottom-up and top-down triangulation reconciled manufacturer capacity disclosures with channel shipment patterns.
Bottom-up modeling built from individual SKU pricing architectures and volume flows across whey, pea, casein, and soy protein segments, while top-down validation cross-checked against dairy commodity futures and plant-protein ingredient trade flows. Segmentation dimensions spanned protein source, end-user archetype, physical form, and distribution channel across the projection horizon. CAGRs derived from regression analysis against gym penetration indices and direct-to-consumer subscription adoption curves, with sensitivity testing around New Zealand milk powder price volatility assumptions.
Revisions become necessary when FSSAI classification schemes shift protein-supplement regulatory status, EFSA health claim authorization thresholds tighten, or ion-exchange resin supply disruptions materialize. Forecasts reflect assumptions about clean-label mandate enforcement intensity and flexitarian household expansion trajectories. Practitioners should monitor ceramic microfiltration equipment order backlogs and organic certification approval timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Austria Protein Supplements Market
Nutritional Supplements
Tongkat Ali Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
Vegan Collagen Powder Market
Nutritional Supplements
Bone Supplements Market
Nutritional Supplements
Ready-To-Use Therapeutic Food Market
Nutritional Supplements
Electrolyte Powder Market
Nutritional Supplements
Choline Supplement Market
Nutritional Supplements
Latin America Herbal Supplements Market
Nutritional Supplements
Europe Feed Prebiotics Market
Nutritional Supplements
Europe Nutraceutical Market
Nutritional Supplements
Nutraceutical Gummies Market
Nutritional Supplements
Australia Collagen Peptides Market
Nutritional Supplements
North America Saffron Supplements Market
Nutritional Supplements
Bone Meal Supplement Market
Nutritional Supplements
Health Supplements Market