
 Soy Protein Isolate Market | 2026-2036
Soy Protein Isolate Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Protein Isolate Market Analysis
Market Context
Plant protein processing expertise is reorganizing competitive dynamics as enzyme engineering and extrusion technology talent becomes scarce across the industry. Archer Daniels Midland Company leverages its integrated oilseed crush network to secure raw material flow across multiple continents. Cargill, Incorporated sustains a broad formulation portfolio spanning meat alternatives, bakery, and beverage applications. Kerry Group plc differentiates through customized protein systems that address texture and flavor challenges in finished goods.
Product Definition and Segment Structure
Soy protein isolate is a highly refined protein powder containing approximately 90% protein content by weight, produced through aqueous extraction and isoelectric precipitation from defatted soy flour for use as a functional ingredient in food systems. Conventional soy protein dominates volume flows due to established supply chains and cost structures, while organic soy protein captures expanding premium positioning as clean-label requirements tighten across retail channels. The food and beverage application segment anchors value generation, whereas dietary supplements represent the fastest-growing demand pool as sports nutrition brands reformulate with plant-derived alternatives.
Regulatory Environment and Outlook
The FDA governs protein content claims and allergen labeling requirements in the United States, while the EFSA evaluates novel food applications and health claim substantiation across European markets, with China's SAMR enforcing GB standards for plant protein quality and safety. These frameworks collectively determine market access conditions, product positioning strategies, and reformulation investment priorities for ingredient suppliers and finished goods manufacturers alike. Stakeholders must monitor evolving allergen threshold regulations and emerging carbon footprint disclosure mandates that will reshape sourcing decisions and competitive positioning.
Market Dynamics
Enzyme engineering and extrusion technology talent scarcity is compressing plant protein processing capacity as food manufacturers race to scale meat analogue production. This bottleneck is reorganizing competitive dynamics across ingredient supply chains and forcing capital allocation toward captive bioprocessing capabilities.
Growth Catalysts
- GB Standards Compliance:China's SAMR enforcement of updated plant protein quality benchmarks is accelerating domestic processor capacity expansion for soy-derived ingredients.
- Meat Analogue Formulation:Food and beverage manufacturers are accelerating soy protein incorporation into plant-based meat alternatives as texture-matching technologies mature.
- Sports Nutrition Pivot:Dietary supplement brands are reformulating with plant-derived alternatives, anchoring the fastest-growing demand pool for high-purity isolates.
Market Restraints
- Allergen Labeling Friction:FDA requirements for soy allergen disclosure create reformulation costs for finished goods manufacturers targeting clean-label positioning.
- Input Cost Volatility:Defatted soy flour supply swings with global oilseed crush margins, compressing isolate producer margins during commodity spikes.
- Technical Limitation:Isoelectric precipitation yields plateau against target protein purity thresholds above 90%, constraining unit economics at scale.
Strategic Opportunities
- Functional Beverage White Space:Beverage applications for high-solubility isolates remain underdeveloped relative to powder formats, offering formulation partnership potential.
- EU Green Deal Tailwind:Carbon footprint disclosure mandates are reshaping sourcing decisions, favoring deforestation-certified soy supply chains with traceability infrastructure.
- Enzyme Engineering Convergence:Cell-free protein synthesis and precision fermentation are converging with traditional isolate production, enabling hybrid ingredient platforms.
Industry Challenges
- Extrusion Specialist Scarcity:Food science talent with high-moisture extrusion expertise commands premium compensation, inflating R&D overhead for texture development.
- Certification Timeline Compression:EFSA novel food applications and health claim substantiation cycles extend 18-24 months, delaying European market entry for new isolate variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Protein Isolate Market |
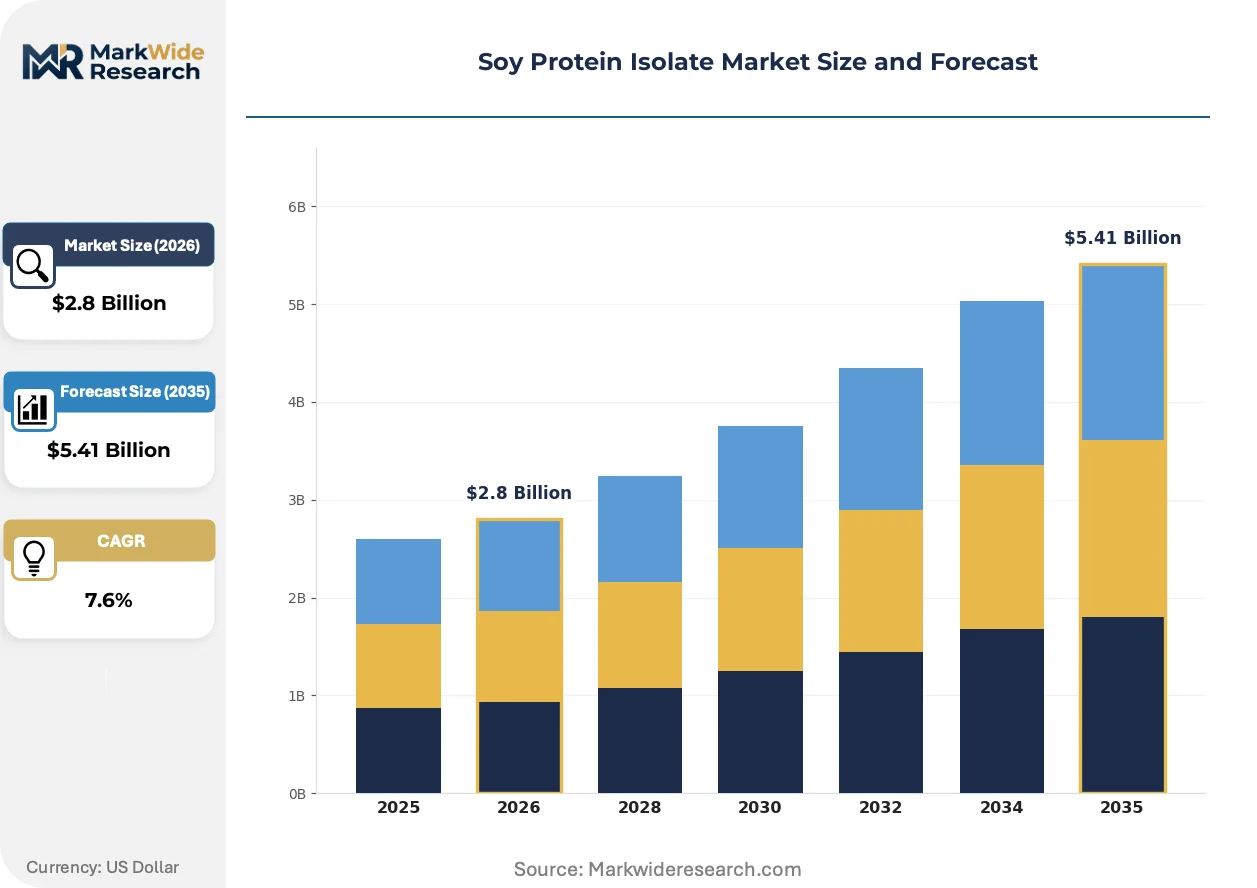
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Soy Protein, Conventional Soy Protein, Isolated Soy Protein, Hydrolyzed Soy Protein Application: Food & Beverage, Dietary Supplements, Animal Feed, Personal Care Form: Powder, Granules, Protein Bars, Ready-to-Drink End User: Health Enthusiasts, Fitness Trainers, Vegetarians, Manufacturers |
| Companies Covered | Kerry Group plc, Wilmar International Limited, Archer Daniels Midland Company, CHS Inc., Fuji Oil Holdings, Cargill, Incorporated, Bunge Limited, Crown Soya Protein Group, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Protein Isolate Market Emerging Trajectories
Processing technology and regulatory disclosure requirements are reshaping how soy protein isolate moves from commodity ingredient to differentiated functional system. These shifts are compressing traditional supply relationships while opening new value-capture mechanisms.
High-moisture extrusion is bifurcating the texture solutions landscape as meat analogue producers demand fibrous structures indistinguishable from animal muscle. Bakery and beverage formulators are adopting the same extrusion platforms at slower rates due to solubility constraints. This technology divergence is compressing margins for commodity isolate suppliers while enabling premium pricing for extrusion-ready protein systems.
EFSA's evolving novel food guidance is forcing ingredient suppliers to front-load clinical substantiation investments before European commercialization. The industrial consequence is a two-tier market where established players with existing dossiers defend shelf space while new entrants face extended capital lockup. Sports nutrition applications in Germany and France are most affected, with brands accelerating reformulation around pre-approved protein sources.
Direct procurement relationships between finished goods manufacturers and crush facilities are displacing traditional ingredient distributor intermediaries. Large meat analogue producers in the Netherlands and plant-based dairy brands in Spain are negotiating long-term offtake agreements for identity-preserved soy. This channel consolidation is most visible in North European markets where sustainability certification commands procurement priority over spot pricing.
Soy Protein Isolate Market Segmentation
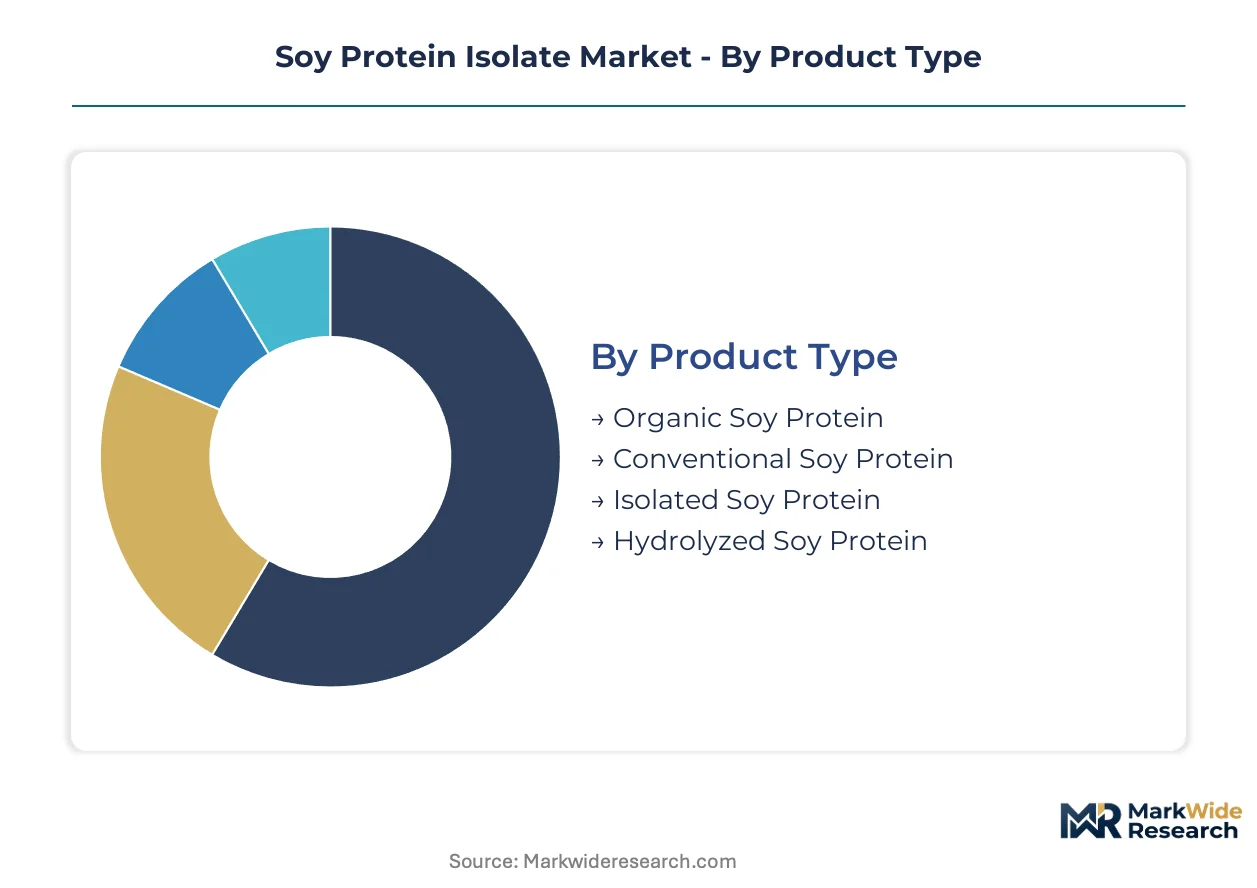
Segmentation in soy protein isolate reveals how purification grades, application requirements, and delivery formats split procurement patterns across domestic food processors and export-oriented ingredient traders. These divisions determine margin capture, certification burdens, and supply chain configuration for producers.
Product Type:
Domestic consumption concentrates in conventional isolates with established crushing infrastructure, while organic and hydrolyzed variants flow disproportionately to export markets demanding premium positioning or specialized nutrition applications.
- Conventional Soy Protein:Standard-grade isolate produced through conventional solvent extraction maintains approximately 90% protein purity. Demand concentrates in Chinese domestic meat analogue facilities expanding capacity for plant-based alternatives, driven by SAMR's updated GB standards enforcement.
- Organic Soy Protein:Certified organic isolate commands premium positioning through deforestation-free supply chains with full traceability. European procurement teams in the Netherlands and Germany prioritize this grade for retail-facing clean-label products under EU Green Deal carbon disclosure mandates.
- Isolated Soy Protein:Highly refined functional ingredient with minimum 90% protein content designed for texturization and emulsification. Food manufacturers in Spain leverage this grade for dairy alternative formulations requiring neutral flavor profiles.
- Hydrolyzed Soy Protein:Enzymatically pre-digested isolate with reduced molecular weight for enhanced bioavailability. Sports nutrition brands in France reformulate around this variant for rapid amino acid absorption.
Conventional soy protein holds the largest share; momentum sits with organic soy protein.
Application:
Cost tier stratification separates commodity-volume food manufacturing from premium-priced supplement positioning, with feed and personal care occupying intermediate value bands.
- Food & Beverage:Largest-volume application encompassing meat analogues, bakery systems, and beverage fortification. Kerry Group plc and similar formulators in Ireland develop customized protein systems addressing texture challenges in finished goods for European retail chains.
- Dietary Supplements:High-purity isolate for sports nutrition powders and capsules. German and French brands accelerate reformulation with plant-derived alternatives, expanding most quickly as whey protein substitution accelerates.
- Animal Feed:Standard-grade isolate for aquaculture and pet nutrition applications. Chinese aquafeed processors integrate soy protein as fishmeal replacement in coastal provinces.
- Personal Care:Cosmetic-grade isolate for hair conditioning and skin care formulations. Korean beauty manufacturers incorporate hydrolyzed variants for molecular weight compatibility.
Food and beverage anchors volume generation; dietary supplements gain share fastest.
Form:
Volume concentration favors powder formats with established handling infrastructure, while ready-to-drink and protein bar segments demand differentiated solubility and binding specifications.
- Powder:Dominant format for bulk ingredient distribution and consumer reconstitution. North American contract manufacturers maintain extensive powder blending capacity for private-label sports nutrition brands.
- Granules:Intermediate particle size for improved dispersibility in instant beverage applications. Japanese food companies prefer this format for miso and soup base production.
- Protein Bars:Texturized isolate systems requiring specific water-binding and extrusion compatibility. Brazilian snack manufacturers source extrusion-ready isolates for growing plant-based bar portfolios.
- Ready-to-Drink:High-solubility isolate for beverage emulsion stability. This format climbs the fastest as functional beverage white space attracts formulation partnership investment.
Powder commands procurement volume; ready-to-drink shows steepest expansion trajectory.
End User:
Customer type splits between direct manufacturing procurement with technical specification requirements and consumer-facing brands targeting named lifestyle segments.
- Manufacturers:Industrial buyers including meat analogue producers, bakery formulators, and beverage compounders. Dutch and Spanish finished goods manufacturers negotiate direct offtake agreements with crush facilities, displacing traditional distributor intermediaries.
- Health Enthusiasts:Consumer segment prioritizing clean-label and organic certifications. Premium retail channels in Germany stock isolates targeting this demographic with sustainability credentials.
- Fitness Trainers:Professional influencers driving sports nutrition brand selection. Social media recommendation patterns in France accelerate isolate adoption among recreational athletes.
- Vegetarians:Lifestyle-based consumers seeking complete protein alternatives. Indian vegetarian populations represent emerging demand as domestic processing capacity scales.
Manufacturers represent the largest procurement block; health enthusiasts drive premium tier expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes soy protein isolate primarily for meat analogue manufacturing, whereas European buyers prioritize organic-certified grades for clean-label retail positioning, and North American demand concentrates in sports nutrition powders.
China
Domestic meat analogue facilities drive volume consumption as food processors expand capacity for plant-based alternatives. SAMR enforces updated GB standards for plant protein quality and safety, accelerating processor investment. Shandong Peninsula clusters house expanding crush-to-isolate operations serving coastal food manufacturers.
United States
Sports nutrition brands reformulate around high-purity isolates for whey protein substitution in powder and ready-to-drink formats. FDA allergen labeling requirements for soy disclosure create reformulation overhead for clean-label positioning. Midwest oilseed crush facilities in Illinois and Iowa negotiate direct offtake agreements with finished goods manufacturers.
Germany
Retail-facing clean-label products prioritize organic and deforestation-certified isolates under EU Green Deal carbon disclosure mandates. EFSA novel food application cycles extend 18-24 months, delaying new isolate variant entry. Cologne-Düsseldorf corridor hosts formulation partnerships between ingredient suppliers and plant-based dairy brands.
Netherlands
Large meat analogue producers negotiate long-term identity-preserved soy contracts with sustainability certification priority over spot pricing. EU Green Deal traceability infrastructure favors deforestation-free supply chains. Rotterdam-Antwerp logistics cluster enables direct procurement relationships displacing traditional distributor intermediaries.
India
Domestic vegetarian populations represent emerging isolate demand as food processing capacity scales for bakery and beverage fortification. FSSAI plant protein quality standards guide domestic ingredient safety benchmarks. Maharashtra and Gujarat crush facilities expand aqueous extraction infrastructure for regional food manufacturers.
Soy Protein Isolate Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier controlling upstream oilseed crush and downstream formulation capabilities while specialists concentrate on customized protein systems and regional distribution. The market structure rewards backward integration into raw material security and captive bioprocessing capacity. Two dominant archetypes emerge: integrated agribusiness conglomerates with continental supply networks, and formulation-focused specialists addressing texture and flavor challenges. Competitive moves center on direct procurement relationships with crush facilities and strategic partnerships for extrusion-ready protein systems.
Among integrated agribusiness players, Archer Daniels Midland Company exemplifies the crush-to-ingredient archetype with multi-continent oilseed network control, while Cargill, Incorporated occupies a position spanning meat alternatives, bakery, and beverage applications. Kerry Group plc represents the formulation specialist tier, anchoring customized protein system development for European retail chains. These three companies illustrate how competitive positioning splits between raw material security and technical formulation capabilities.
| Leading Market Players |
|---|
| Kerry Group plc |
| Wilmar International Limited |
| Archer Daniels Midland Company |
| CHS Inc. |
| Fuji Oil Holdings |
| Cargill, Incorporated |
| Bunge Limited |
| Crown Soya Protein Group |
| DuPont de Nemours, Inc. |
| Others |
Supply Flow & Price Mechanics
Whey protein substitution by soy isolates in sports nutrition powders simultaneously relocates procurement gravity toward Midwest oilseed crush facilities and compresses margin capture for non-integrated ingredient traders lacking direct crusher relationships. This displacement dynamic rewards manufacturers with backward integration into oilseed processing while spot-market buyers absorb volatility from defatted soy flour supply swings.
Pricing Analysis
Long-term offtake agreements between Dutch meat analogue producers and crush facilities anchor pricing stability, while spot transactions for standard-grade isolate fluctuate with global oilseed margins. Three-tier pricing structure across premium organic, standard conventional, and economy feed-grade isolates differentiates by certification level and volume scale. Pricing pressure stems from isoelectric precipitation yield plateaus constraining unit economics at 90%-plus purity thresholds. Feed-grade buyers exhibit highest price sensitivity, whereas sports nutrition brands prioritize solubility performance over per-kilogram cost.
Supply Chain Analysis
Strategic stockpiling of identity-preserved soybeans by Netherlands-based meat analogue producers contrasts with just-in-time powder handling by North American contract manufacturers serving private-label sports nutrition brands. Raw material flows concentrate through crushing operations in China, the United States, and Brazil, with aqueous extraction capacity expanding fastest in Shandong Province and Maharashtra state. Downstream distribution runs through direct procurement relationships displacing traditional ingredient distributors in Northern European markets, though single-source vulnerability persists for organic-certified supply chains dependent on deforestation-free South American origin verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: EFSA novel food dossiers and FDA allergen compliance frameworks lock up 18-24 month approval cycles that new entrants cannot accelerate, cementing incumbent shelf-space control.
For Market Incumbents: Fortify captive bioprocessing capacity through enzyme engineering talent acquisition and high-moisture extrusion infrastructure investment. Defend margin position against precision fermentation substitutes by accelerating hybrid ingredient platform development. Prioritize GB standards pre-certification for Chinese market access ahead of domestic processor capacity saturation.
For New Entrants and Emerging Players: Lead with functional beverage formulation partnerships targeting solubility-optimized isolate grades where incumbent penetration remains shallow. Target Brazilian and Indian geographies where direct procurement relationships with crush facilities remain underdeveloped relative to European and North American markets. Anchor go-to-market strategy through sports nutrition brand white-label supply agreements bypassing EFSA novel food timeline barriers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated crush-to-ingredient conglomerates with multi-continent oilseed network control. Long-term viability across the five-to-ten year window hinges on carbon footprint traceability infrastructure compliance with EU Green Deal mandates. Acquisition target archetype: regional specialists with established EFSA dossiers and extrusion-ready protein system capabilities. Signal to watch: SAMR enforcement intensity against domestic Chinese processors as overcapacity indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crush | Archer Daniels Midland and Cargill secure raw material flow across Illinois, Iowa, and Brazilian facilities. |
| High-Moisture Extrusion Capacity Buildout | Kerry Group plc addresses texture challenges in European meat analogue formulations for retail chains. |
| EFSA Novel Food Dossier Investment | Pre-approved protein sources accelerate German and French sports nutrition brand reformulation timelines. |
| Direct Procurement Relationship Formation | Dutch and Spanish manufacturers negotiate long-term identity-preserved soy contracts displacing distributors. |
| Carbon Footprint Traceability Infrastructure | Netherlands-based producers meet EU Green Deal mandates through deforestation-certified supply chain verification. |
Methodological Framework
A spread of perspectives from oilseed crush facility managers, food formulation R&D directors, sports nutrition brand procurement leads, and EU regulatory affairs specialists converged on the working assumptions underpinning volume and value estimates. Primary interview intelligence combined with secondary validation from FDA guidance documents, EFSA novel food registers, SAMR GB standards publications, and customs trade flow records. Bottom-up capacity utilization modeling and top-down protein substitution trend analysis triangulated on segment-level projections.
Segmentation dimensions modeled span purification grade tier, application requirement intensity, delivery format solubility specifications, and end-user procurement archetype across the projection horizon. CAGRs derived from weighted average of historical capacity expansion patterns and forward-looking enzyme engineering adoption curves. Industry-specific forecast inputs include high-moisture extrusion technology diffusion rates and EFSA health claim substantiation cycle durations.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement intensity or SAMR capacity expansion approval continuity would require recalibration. Forecasts reflect documented assumptions regarding oilseed crush margin stability and allergen labeling regulatory persistence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Bouillon Cubes Market
Ingredients
Encapsulated Salt Market
Ingredients
Campesterol Market
Ingredients
Thinned Starch Market
Ingredients
White Wheat Malt Market
Ingredients
Guar Gum Market
Ingredients
Sugar Beet Pectin Market
Ingredients
Freeze-Dried Pea Isolates Market
Ingredients
Cheese Ingredients Market
Ingredients
Chickpea Fiber Market
Ingredients
Anti-Aging Ingredients Market
Ingredients
Phytosterols Market
Ingredients
Mirepoix Market
Ingredients
Blue Light Protection Ingredients Market
Ingredients
Zero-Calorie Oil Market
Ingredients
Agar Agar Flakes Market