
 Vegan Cookies Market | 2026-2036
Vegan Cookies Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Cookies Market Analytics
Buyer concentration across mainstream grocery is realigning as Walmart, Kroger, and Target expand dedicated plant-based sections, pulling volume from legacy natural-channel gatekeepers. Lenny & Larry's leverages its sports-nutrition heritage to anchor protein-forward cookie positioning in fitness retail. Simple Mills competes through grain-free formulation specialization that commands premium placement in Whole Foods and Sprouts. Partake Foods extends its allergen-free credentials into school-safe and institutional channels.
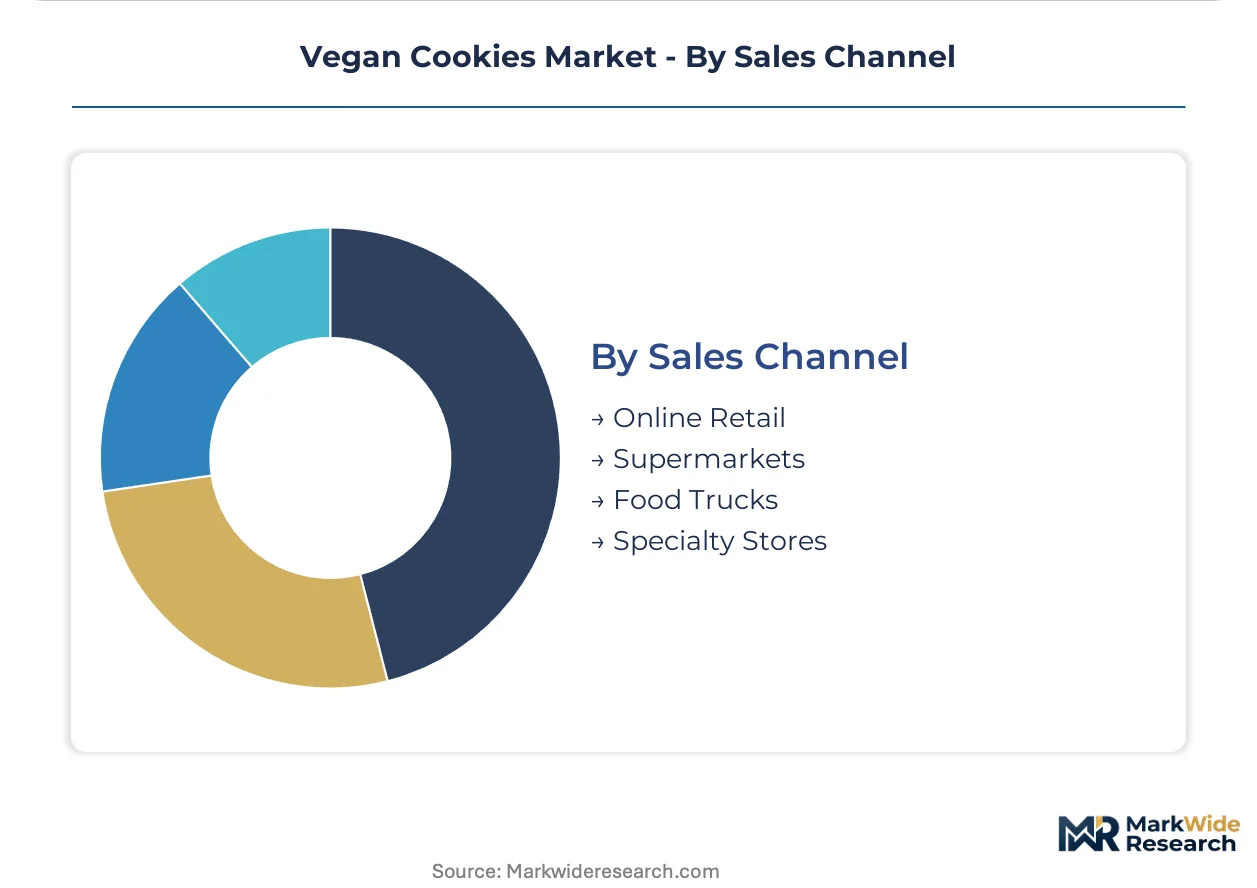
Vegan cookies are baked goods containing no animal-derived ingredients—eggs replaced by flax or aquafaba, butter by coconut or shea oil—formulated to match conventional textures at moisture contents of 12-18%. Their commercial purpose centers on serving dairy-free, egg-free consumers without sensory compromise. Choco Chip and Peanut Butter variants dominate household purchase frequency, while Oatmeal Raisin occupies a smaller but loyal breakfast-adjacent niche. Online Retail and Supermarkets together capture the bulk of volume, though Specialty Stores sustain higher per-unit margins through curated discovery experiences.
FDA standards for vegan labeling and USDA Organic certification both shape permissible ingredient sourcing and front-of-package claims. The EU Green Deal's deforestation-free supply chain requirements affect cocoa and palm oil inputs for exporters serving European buyers. Stakeholders must monitor evolving allergen thresholds and clean-label enforcement, as regulatory divergence between North American and European frameworks complicates unified product development.
Market Dynamics
Mainstream grocery retailers are consolidating shelf space allocation power, forcing vegan cookie brands to reformulate for mass-market price points while maintaining clean-label credentials that secured their initial natural-channel placement.
Growth Catalysts
- Plant-Based Dietary Guidelines:USDA's updated nutrition standards in school meal programs are expanding institutional procurement windows for allergen-free vegan baked goods, creating volume anchors beyond retail.
- Precision Fermentation:Cultured proteins and fats from Perfect Day and Motif FoodWorks are reducing reliance on commodity crop inputs while improving texture parity with conventional cookies.
- United States:Walmart's dedicated plant-based aisle expansions in 2,800 stores are normalizing vegan cookies as basket staples rather than specialty purchases, pulling trial from coastal early adopters to heartland markets.
Market Restraints
- Cocoa Supply Concentration:West African origin dependence exposes margins to Côte d'Ivoire and Ghana weather volatility and EU Green Deal deforestation enforcement timelines.
- Technical Limitation:Egg replacer performance gaps in high-moisture formulations limit soft-baked texture replication, constraining product architecture to crunchy formats in budget tiers.
- Substitution Threat:Date-sweetened fruit bars and nut-based energy bites are capturing the same snacking occasions with simpler ingredient decks and lower processing costs.
Strategic Opportunities
- India:FSSAI's vegan certification framework and urban dairy-aversion trends in Mumbai and Bangalore create first-mover potential before multinational brand saturation.
- Direct-to-Consumer Subscriptions:Curated monthly boxes bypass slotting fee barriers while building recurring revenue and first-party data for flavor innovation.
- Convergence of Upcycling and Clean Label:Spent grain from craft brewing and oat milk production streams are supplying fiber-rich, story-driven ingredients that command premium positioning.
Industry Challenges
- Allergen Cross-Contamination Protocols:Dedicated production line requirements for school-safe certification strain capital deployment timelines for mid-scale bakeries.
- Reformulation Cycle Compression:FDA's evolving vegan claim standards and state-level truth-in-labeling lawsuits are forcing repeated package redesigns and supply chain requalification.
- Specialized Workforce Scarcity:Plant-based baking technologists with simultaneous expertise in sensory science and scale-up manufacturing command compensation premiums that erode startup runway.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Cookies Market |
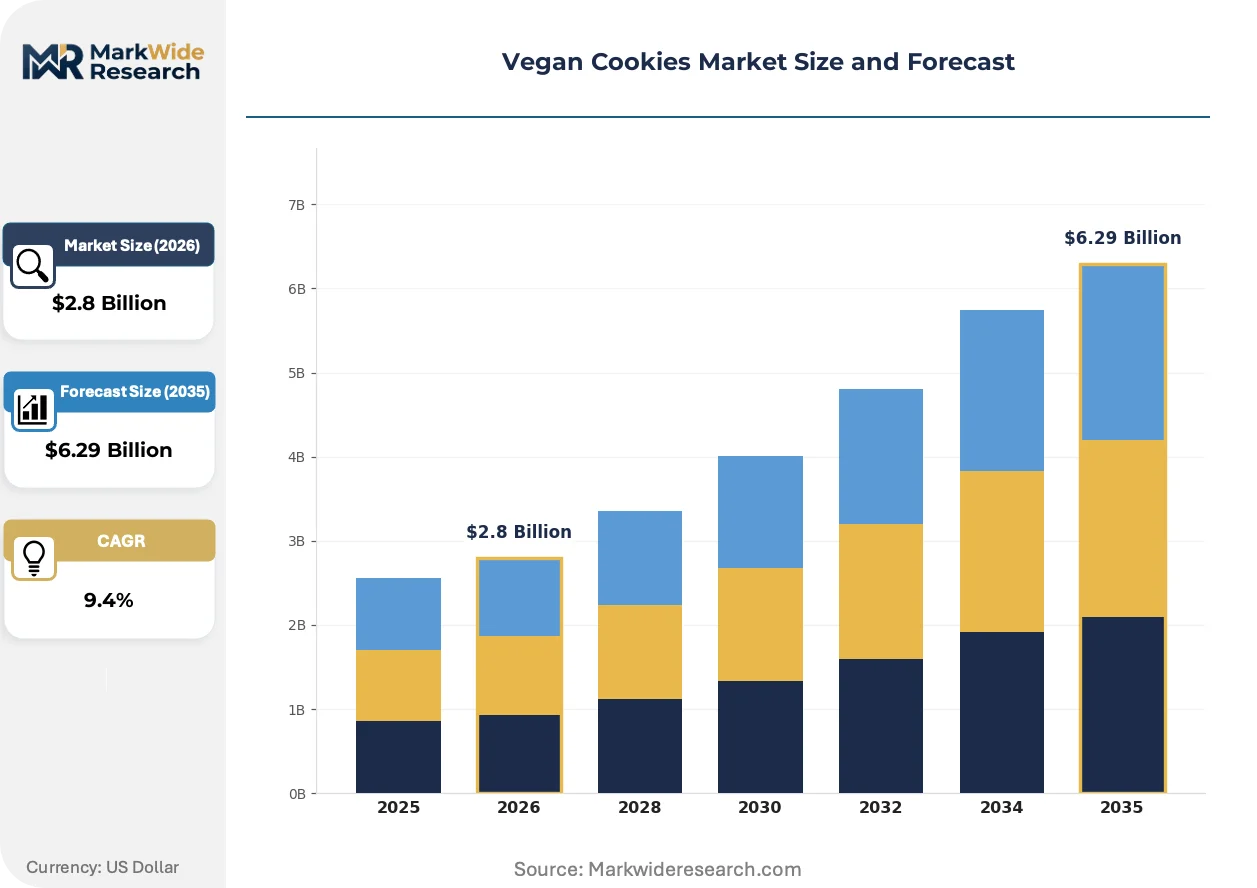
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Choco Chip, Oatmeal Raisin, Peanut Butter, Almond Joy Ingredient Source: Organic, Non-GMO, Gluten-Free, All-Natural End User: Households, Cafes, Restaurants, Health Stores Sales Channel: Online Retail, Supermarkets, Food Trucks, Specialty Stores |
| Companies Covered | Lenny & Larry's, Maxine's Heavenly, Alternative Baking Co., Simple Mills, Enjoy Life Foods, Divvies LLC, Partake Foods, Maya's Cookies, Emmy's Organics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Cookies Market Evolving Landscape
Formulation science and channel economics are diverging sharply as mass-market penetration demands cost engineering that threatens the premium positioning built on artisan credentials.
Precision fermentation-derived whey and casein analogs are modularizing protein functionality across cookie categories previously constrained by pea and rice protein grittiness. Sports-nutrition brands are adopting these inputs fastest, collapsing the historical separation between fitness-oriented protein cookies and indulgent snacking formats. This convergence is compressing R&D cycles as ingredient suppliers bundle texture systems with finished-goods co-manufacturing.
EU Green Deal deforestation-free supply chain regulations are forcing cocoa and palm oil traceability investments that reshape procurement relationships. Exporters serving European buyers must demonstrate geolocation-verified sourcing by compliance deadlines, accelerating vertical integration into plantation-level partnerships. Mid-sized brands without direct origin relationships are exiting European distribution to avoid liability exposure.
Subscription-based replenishment models are displacing impulse-driven supermarket purchases among core vegan households. Direct channels capture higher lifetime value through personalization algorithms while specialty stores pivot toward discovery-oriented limited releases. This bifurcation is most visible in coastal United States markets where digital-native brands now command household penetration rates previously reserved for legacy natural-channel stalwarts.
Vegan Cookies Market Segmentation
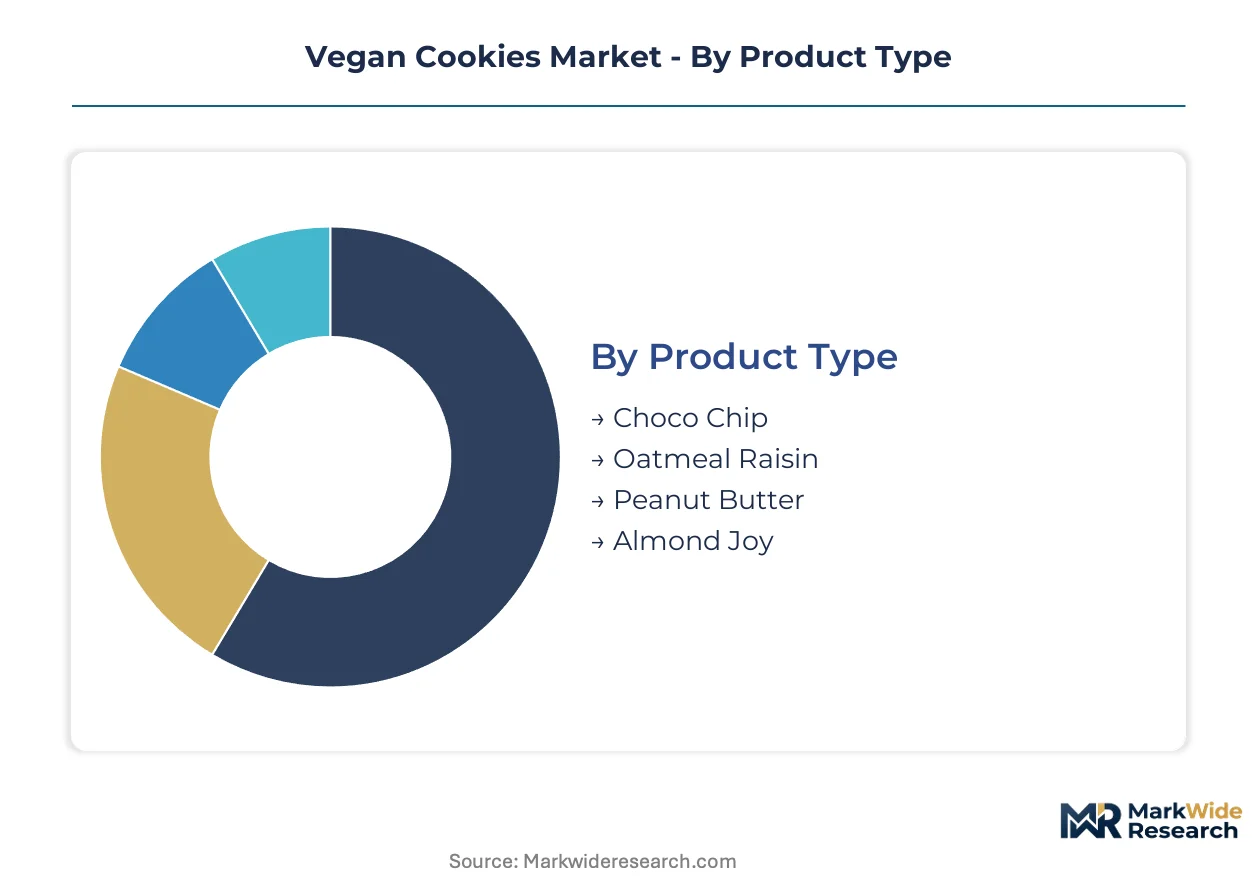
Vegan cookie segmentation reveals how formulation choices, procurement channels, and consumption contexts fragment addressable demand. Each dimension carries distinct margin profiles and regulatory exposure that shape portfolio architecture.
Product Type:
Flavor positioning determines whether vegan cookies compete as indulgence replacements or functional snacks, with texture engineering requirements varying sharply across the spectrum.
- Choco Chip:Dominant household purchase driver requiring cocoa butter and chocolate chunk reformulation to replicate melt characteristics without dairy fat. Walmart's dedicated plant-based aisle expansions normalize this variant as a basket staple across heartland markets.
- Peanut Butter:Protein-forward positioning leverages existing sports-nutrition consumer familiarity, with dense textures masking egg replacer limitations. Lenny & Larry's anchors this segment in fitness retail through heritage positioning.
- Oatmeal Raisin:Breakfast-adjacent niche sustained by loyal repeat purchasers seeking lower-sugar alternatives.
- Almond Joy:Coconut-almond combinations command premium placement in specialty discovery channels.
Choco Chip leads volumes today; Peanut Butter is gaining share fastest.
Ingredient Source:
Certification tiers stratify pricing power and shelf placement, with multi-credential products capturing the highest margins in natural-channel gatekeeping positions.
- Organic:USDA certification mandates supply chain documentation that constrains sourcing flexibility while securing Whole Foods and Sprouts placement. EU Green Deal deforestation-free requirements add traceability costs for cocoa inputs.
- Gluten-Free:Grain-free formulations from Simple Mills demonstrate that allergen-free credentials unlock school-safe and institutional procurement windows beyond retail.
- Non-GMO:Verification through third-party certifiers supports clean-label claims without organic price premiums.
- All-Natural:Minimal processing positioning competes with date-sweetened fruit bars on ingredient simplicity.
Organic commands the highest per-unit margins; Gluten-Free expands most quickly through institutional channels.
End User:
Consumption context determines pack size, distribution format, and formulation stability requirements, with away-from-home occasions demanding longer shelf life.
- Households:Core volume driver purchasing multipacks through supermarkets and online replenishment subscriptions. Partake Foods extends allergen-free credentials into school-lunchbox occasions.
- Cafes:Single-serve display cases require individually wrapped formats with moisture barriers.
- Restaurants:Dessert menu placement demands plate-ready presentation and portion consistency.
- Health Stores:Curated discovery environment sustains higher margins for limited-release and local brands.
Households anchor absolute volumes; Cafes show the steepest expansion trajectory as coffee chains add plant-based options.
Sales Channel:
Channel economics diverge sharply between high-frequency replenishment models and impulse-driven discovery formats, with slotting fee structures determining viable brand scale.
- Online Retail:Direct-to-consumer subscriptions bypass slotting barriers while building first-party data for flavor innovation. Digital-native brands now command household penetration rates previously reserved for legacy natural-channel stalwarts.
- Supermarkets:Mainstream grocery consolidation forces reformulation for mass-market price points while maintaining clean-label credentials.
- Specialty Stores:Curated discovery experiences sustain higher per-unit margins through limited assortment and educated staff.
- Food Trucks:Mobile vending requires ambient-stable formats with grab-and-go packaging.
Supermarkets capture the bulk of absolute volume; Online Retail climbs the fastest as subscription models displace impulse purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States vegan cookie penetration outpaces Germany by a factor of three in per-capita spend, yet both markets face tightening regulatory scrutiny over ingredient provenance and labeling precision.
United States
Walmart's dedicated plant-based aisle expansions across 2,800 stores normalize vegan cookies as basket staples rather than coastal specialty purchases. FDA labeling guidelines for vegan claims tighten formulation standards and front-of-package assertions. Austin and Los Angeles anchor innovation clusters where direct-to-consumer subscription brands command household penetration rates previously reserved for legacy natural-channel stalwarts.
Germany
EU Green Deal deforestation-free supply chain requirements reshape cocoa and palm oil procurement for exporters serving German retail. EFSA clean-label enforcement and national organic certification (Bio-Siegel) constrain permissible ingredient sourcing. Berlin and Hamburg concentrate alternative protein baking technology development, with precision fermentation startups supplying modular texture systems to regional co-manufacturers.
United Kingdom
Supermarket private-label expansion into plant-based bakery compresses branded shelf space while elevating price competition. FSA allergen threshold protocols and Natasha's Law ingredient disclosure requirements increase compliance burdens. London and Manchester host the densest specialty retail networks, with curated discovery formats sustaining premium placement for limited-release vegan cookie lines.
India
FSSAI's vegan certification framework and urban dairy-aversion trends in Mumbai and Bangalore create first-mover potential before multinational brand saturation. PLI scheme incentives for food processing infrastructure reduce capital deployment barriers for domestic bakery scale-up. Pune and Hyderabad emerge as contract manufacturing hubs serving both domestic demand and Middle East export markets.
France
ANSM and DGCCRF joint enforcement of clean-label claims limits permissible processing aids in artisan-positioned vegan cookies. EU Green Deal traceability mandates accelerate vertical integration into West African cocoa origin relationships. Paris and Lyon concentrate premium channel distribution, with specialty pâtisserie partnerships driving limited-edition collaboration releases.
Vegan Cookies Market Competitive Landscape
United States producers anchor the mass-market tier; European specialists hold premium positioning through stricter certification credentials. The vendor base stratifies across three functional layers: sports-nutrition heritage brands, grain-free formulation specialists, and allergen-free institutional suppliers. Strategic moves concentrate on co-manufacturing partnerships for capacity flexibility and subscription infrastructure for recurring revenue capture.
Within the sports-nutrition heritage tier, Lenny & Larry's exemplifies protein-forward cookie positioning anchored in fitness retail channels. Simple Mills represents grain-free formulation specialization commanding premium placement in natural-channel gatekeepers. Partake Foods occupies the allergen-free institutional vector, extending credentials into school-safe and procurement-heavy channels. These three archetypes illustrate how divergent formulation strategies yield distinct shelf access and margin profiles without direct segment overlap.
| Leading Market Players |
|---|
| Lenny & Larry's |
| Maxine's Heavenly |
| Alternative Baking Co. |
| Simple Mills |
| Enjoy Life Foods |
| Divvies LLC |
| Partake Foods |
| Maya's Cookies |
| Emmy's Organics |
| Others |
Value Network & Pricing Analysis
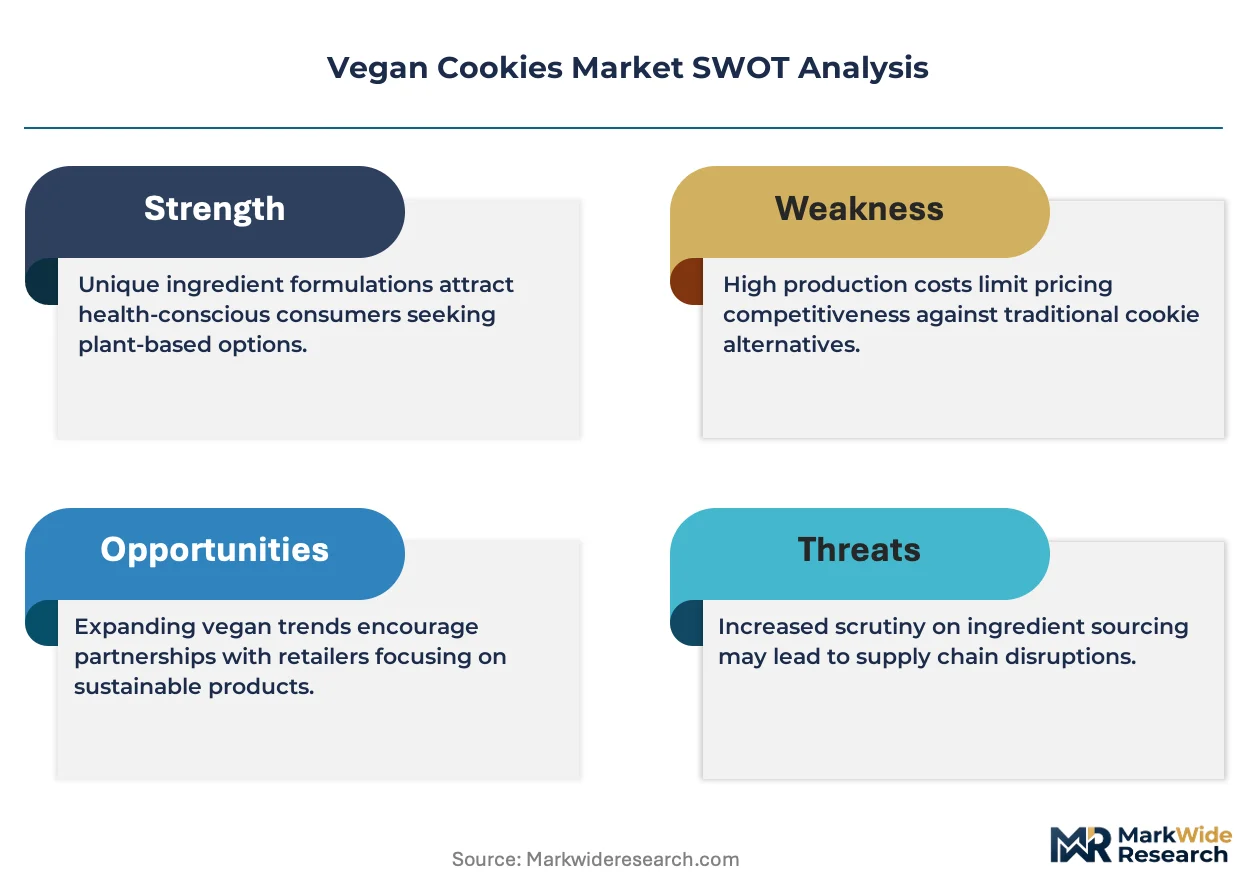
Cocoa butter and shea oil inputs travel from West African plantations through EU Green Deal traceability checkpoints before reaching three-tier pricing structures across premium, standard, and economy levels. Mass-market buyers like Walmart extract volume discounts that compress margins for mid-tier brands lacking backward integration into origin relationships.
Pricing Analysis
Capacity additions in contract manufacturing hubs are reshaping price floors for private-label vegan cookies. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified products from Non-GMO verified and conventional clean-label tiers. Cost compression in the economy tier is intensifying because slotting fee burdens at mainstream grocers force reformulation to commodity crop inputs. Household segment buyers show highest price sensitivity; specialty channel purchasers tolerate premiums for multi-credential certification stacks.
Supply Chain Analysis
Dual-sourcing mandates from European retailers require geolocation-verified cocoa from both Côte d'Ivoire and Ghana plus secondary Malaysian palm oil qualification. West African origin dependence creates single-source vulnerability to weather volatility and EU deforestation enforcement timelines. Distribution runs through co-manufacturer networks in the United States and Germany before final retail placement. Brands without captive supply of precision fermentation-derived fats face input cost instability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA vegan claim tightening and EU Green Deal traceability mandates continuously reshape formulation costs and competitive moats.
For Market Incumbents: Hedge against precision fermentation disruption by securing exclusive supply agreements with Perfect Day or Motif FoodWorks before ingredient suppliers bundle texture systems with co-manufacturing. Defend shelf position through backward integration into West African cocoa origin relationships that satisfy EU geolocation verification. Channel control through dedicated plant-based aisle partnerships at Kroger and Target anchors volume against private-label encroachment. For New Entrants and Emerging Players: Precision fermentation-derived whey analogs offer technology-first wedge into sports-nutrition cookie formats where texture parity commands premium pricing. Target India's FSSAI certification window in Mumbai and Bangalore before multinational saturation erodes first-mover margins. Direct-to-consumer subscription models bypass slotting fee barriers while building recurring revenue and flavor innovation data. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale bakeries strain under dedicated allergen-free production line capital requirements. Five-to-ten year viability favors brands with simultaneous organic certification, precision fermentation ingredient access, and subscription infrastructure. Watch for EU Green Deal enforcement acceleration as inflection indicator triggering exit of non-compliant exporters from European distribution.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Cultured fat access from Motif FoodWorks collapses texture parity gaps with conventional cookies. |
| EU Traceability Certification | Geolocation-verified cocoa sourcing secures placement with German and French retail buyers. |
| Subscription Infrastructure Buildout | Direct channels capture higher lifetime value through personalization algorithms in coastal US markets. |
| School-Safe Production Investment | Dedicated allergen-free lines unlock USDA school meal procurement windows beyond retail. |
| India FSSAI First-Mover Positioning | Urban dairy-aversion trends in Bangalore create volume anchors before multinational saturation. |
Research Methodology
Coverage spans the United States, Germany, United Kingdom, India, and France, with primary inputs from each market's stakeholder base. The analysis combines interviews with brand managers, category buyers at Walmart and Kroger, plant-based baking technologists, and supply chain directors with secondary validation through FDA labeling guidance documents, EU Green Deal regulatory texts, FSSAI certification frameworks, and Nielsen retail audit data. Bottom-up volume triangulation across product type, ingredient source, and sales channel dimensions converges with top-down macroeconomic anchoring.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon. The analytical framework models flavor variant, certification tier, end-user context, and channel format as core segmentation dimensions, with precision fermentation adoption velocity as an industry-specific overlay. CAGRs derive from regression against historical penetration curves in adjacent plant-based categories, adjusted for regulatory milestone timing and retail shelf space expansion trajectories.
The model holds under continued FDA vegan claim enforcement and EU deforestation regulation implementation; deviation in cocoa supply disruption severity or precision fermentation cost reduction speed would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
South America Meat Substitute Market
Plant Based Food
Flax-Based Protein Market
Plant Based Food
North America Rice Protein Market
Plant Based Food
Faba Bean Protein Market
Plant Based Food
Enzyme-Based Plant Protein Market
Plant Based Food
US Plant-Based Meat Market
Plant Based Food
Meatless Meat Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Organic Rice Protein Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Fermented Plant Protein Market
Plant Based Food
Yucca Extract Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Plant Based Ice Cream Market
Plant Based Food
Plant-Based Flour Market
Plant Based Food
Global Vegan Fast Foods Market