
 Global Isolate Organic Soy Protein Market | 2026-2036
Global Isolate Organic Soy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Global Isolate Organic Soy Protein Market Foresight
Precision fermentation and enzymatic extraction is tilting production economics toward higher-purity isolates with lower antinutrient profiles. Archer Daniels Midland Company leverages its North American oilseed crush network to secure non-GMO organic bean supply. Cargill, Incorporated anchors its position through backward integration into certified organic farming cooperatives. Puris competes on domestic U.S. sourcing, eliminating transoceanic organic certification complexity.
Isolate organic soy protein denotes a defatted, water-extracted fraction containing minimum ninety percent protein by dry weight, processed exclusively from certified organic soybeans without synthetic solvents. Manufacturers deploy alkaline extraction followed by isoelectric precipitation to achieve functional gelling and emulsification properties for meat analogues and dairy replacements. Organic soy protein isolate powder leads value generation due to its neutral flavor profile and superior dispersibility in beverage matrices. Meat alternatives represent the fastest-expanding application channel, driven by flexitarian protein diversification across retail and foodservice.
The USDA National Organic Program governs certification integrity for U.S.-bound shipments, while EFSA and EU Organic Regulation enforce strict contaminant thresholds and traceability mandates for European market access. China's SAMR and GB standards impose additional testing protocols on imported organic protein isolates, lengthening approval timelines but filtering substandard suppliers. Stakeholders must monitor evolving divergence between U.S. and EU organic equivalence agreements, as fragmentation in mutual recognition would force parallel certification investments and reshape competitive cost structures.
Market Dynamics
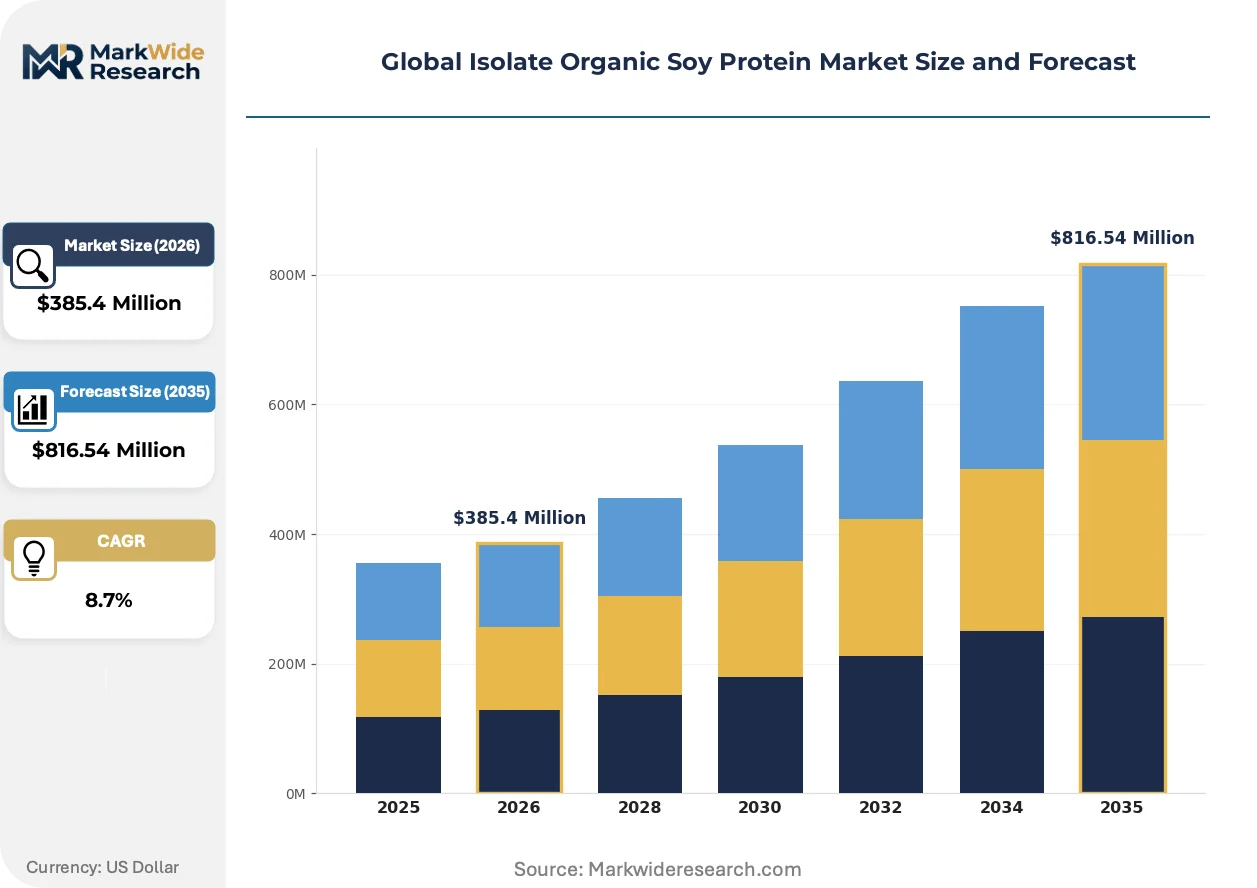
Precision fermentation and enzymatic extraction are compressing production costs for high-purity isolates while the EU Green Deal and USDA National Organic Program impose divergent certification burdens on multinational suppliers.
Growth Catalysts
- EU Green Deal clean-label mandates:Brussels is tightening contaminant thresholds and traceability requirements, forcing reformulation across meat analogue and dairy replacement categories toward certified organic isolates.
- Sports nutrition procurement acceleration:Functional beverage and powder brands are specifying organic isolate grades for amino acid completeness and neutral flavor profiles in high-protein formulations.
- German organic food processing concentration:Bavarian and Baden-Württemberg ingredient clusters command premium sourcing contracts, pulling supply toward EU-certified production networks.
Market Restraints
- Organic soybean input cost volatility:Weather-driven yield fluctuations in Argentina and Brazil transmit directly to isolate margins, with limited hedging instruments for non-GMO organic grades.
- China SAMR approval timelines:Extended GB standards testing protocols for imported organic protein isolates filter substandard suppliers but lengthen working capital cycles for exporters.
- Pea and fava protein substitution:Allergen-free positioning and comparable emulsification properties in these legume isolates capture flexitarian consumers seeking soy avoidance.
Strategic Opportunities
- India FSSAI organic recognition expansion:Emerging domestic certification infrastructure and PLI scheme incentives for food processing create first-mover positioning for isolate suppliers establishing local crushing partnerships.
- Cell-cultured meat hybrid applications:Scaffold and medium formulations requiring high-purity organic protein fractions open technical collaboration channels with cultivated protein startups.
- Direct-to-manufacturer platform distribution:B2B ingredient marketplaces are compressing traditional distributor layers, enabling smaller organic processors to access mid-sized meat analogue brands directly.
Industry Challenges
- Organic equivalency agreement fragmentation:Diverging U.S.-EU mutual recognition protocols force parallel certification investments, duplicating audit costs and documentation burdens for cross-Atlantic suppliers.
- Isoelectric precipitation capex intensity:Alkaline extraction and precipitation infrastructure requires stainless steel vessels and wastewater treatment systems that strain balance sheets of mid-scale organic processors.
- Enzymatic process engineering talent scarcity:Limited pools of protein chemists with both organic certification knowledge and industrial bioprocessing experience constrain scale-up timelines for precision fermentation ventures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Isolate Organic Soy Protein Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured Organic Soy Protein, Organic Soy Protein Isolate Powder, Organic Soy Protein Concentrate, Organic Soy Protein Hydrolysate Application: Sports Nutrition, Functional Foods, Infant Formula, Animal Feed, Beverages, Meat Alternatives End User: Food Manufacturers, Nutraceutical Companies, Animal Nutrition Firms, Beverage Producers, Dietary Supplement Brands Packaging Type: Bulk Bags, Pouches, Tins, Sachets, Drums |
| Companies Covered | SunOpta, Inc., Foodchem International Corporation, Archer Daniels Midland Company, Devansoy Inc., Puris, Cargill, Incorporated, The Scoular Company, Chaitanya Agro Biotech Pvt. Ltd., DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Isolate Organic Soy Protein Market Shifts & Advancements
Bioprocessing advances and regulatory fragmentation are simultaneously lowering purity thresholds and raising compliance barriers, reshaping how organic isolate suppliers compete on cost, certification, and functional performance.
Membrane filtration coupled with precision fermentation is rendering obsolete traditional solvent-based extraction for premium isolate grades. Meat analogue manufacturers in the Netherlands and Denmark are adopting these enzymatic routes at pilot scale. The technology is rendering obsolete legacy hexane-extracted isolates in clean-label contract manufacturing.
REACH and EU F-Gas Regulation amendments are tightening solvent recovery and emissions accounting for organic protein processors operating within the European Economic Area. Industrial consequence includes mandatory third-party verification of extraction solvent circularity. German and French isolate importers are responding by sourcing exclusively from EU-registered organic crush facilities with closed-loop systems.
Ingredient verification protocols are migrating from paper-based organic certificates to blockchain-anchored supply chain records. Foodservice distributors and retail private-label buyers are mandating real-time traceability dashboards as contract preconditions. This behavioral pivot is most visible in Scandinavian markets, where Coop and ICA Group procurement teams penalize suppliers lacking digitized farm-to-fork documentation.
Global Isolate Organic Soy Protein Market Segmentation
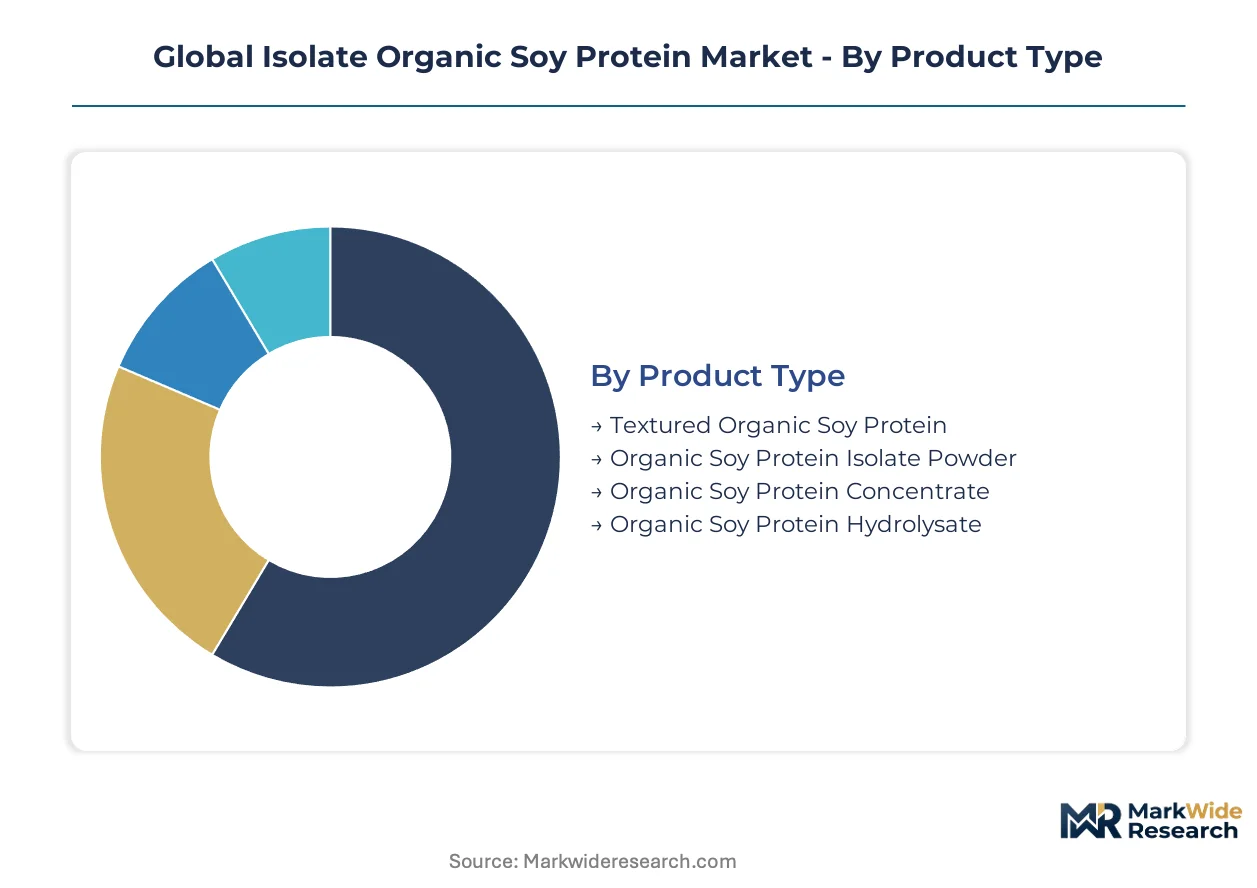
Segmentation in organic soy protein isolates reveals how functional specifications and certification tiers fragment procurement patterns across food manufacturing. Buyers sort supply by protein purity thresholds, solubility indices, and organic traceability depth rather than commodity pricing alone.
Product Type:
Inventory velocity varies dramatically across these grades, with powder formats turning fastest in beverage applications while textured variants sit longer in meat analogue processor warehouses.
- Organic Soy Protein Isolate Powder:Minimum ninety percent protein by dry weight with neutral flavor and superior dispersibility. Demand concentrates in German sports nutrition contract manufacturers seeking instantized grades for RTD protein beverages, constrained by EU Organic Regulation contaminant thresholds that filter lower-purity imports.
- Textured Organic Soy Protein:Extruded fibrous structures rehydrating to meat-like bite. Bavarian and Dutch meat analogue producers specify these for clean-label burger patties, driven by flexitarian retail expansion across German and French supermarkets.
- Organic Soy Protein Concentrate:Seventy percent protein fraction retaining more native fiber and carbohydrate. Japanese functional food processors favor this grade for fermented soy applications.
- Organic Soy Protein Hydrolysate:Enzymatically predigested peptides for hypoallergenic positioning. Infant formula specialists in Switzerland and the Netherlands source this for premium organic neonatal nutrition lines.
Organic Soy Protein Isolate Powder dominates installed base. Textured Organic Soy Protein is where expansion concentrates.
Application:
Margin structures diverge sharply across these channels, with beverage and sports nutrition commanding certification premiums while animal feed operates on volume-driven cost tiers.
- Meat Alternatives:Fastest-climbing application channel as flexitarian protein diversification accelerates across German, Dutch, and Danish retail and foodservice. Clean-label contract manufacturers in the Netherlands adopt enzymatic extraction routes at pilot scale to meet EFSA purity mandates.
- Sports Nutrition:Functional beverage and powder brands specify organic isolate grades for amino acid completeness. Procurement teams at Scandinavian distributors now mandate blockchain-anchored supply chain records as contract preconditions.
- Functional Foods:Fermented and baked applications leveraging gelling and emulsification properties. Japanese and South Korean processors lead formulation innovation.
- Beverages:RTD protein drinks requiring instantized, neutral-flavor isolates with minimal sedimentation.
- Infant Formula:Hypoallergenic organic hydrolysates for premium neonatal nutrition lines in Switzerland and the Netherlands.
- Animal Feed:Volume-driven organic protein fortification for aquaculture and pet nutrition segments.
Sports Nutrition captures the steepest premium pricing. Meat Alternatives is gaining share fastest.
End User:
Customer sophistication tiers separate those with in-house protein chemistry capabilities from brands outsourcing formulation entirely.
- Food Manufacturers:Meat analogue and dairy replacement specialists with dedicated protein application labs. German organic food processing clusters in Bavaria and Baden-Württemberg command premium sourcing contracts with closed-loop extraction verification.
- Dietary Supplement Brands:Sports nutrition marketers specifying organic isolate grades for amino acid panel completeness. These buyers increasingly source through B2B ingredient marketplaces that compress traditional distributor layers.
- Nutraceutical Companies:Clinical nutrition and medical food formulators requiring batch-level organic certification documentation.
- Beverage Producers:RTD and plant-based milk brands prioritizing dispersibility and neutral flavor profiles.
- Animal Nutrition Firms:Pet food and aquaculture feed compounders operating on cost-optimized procurement with lower purity tolerance.
Food Manufacturers anchor volume commitment. Dietary Supplement Brands is where procurement innovation concentrates.
Packaging Type:
Logistics economics and contamination risk shape format selection, with bulk dominating ingredient trade and sachets serving sampling and premium direct-to-consumer channels.
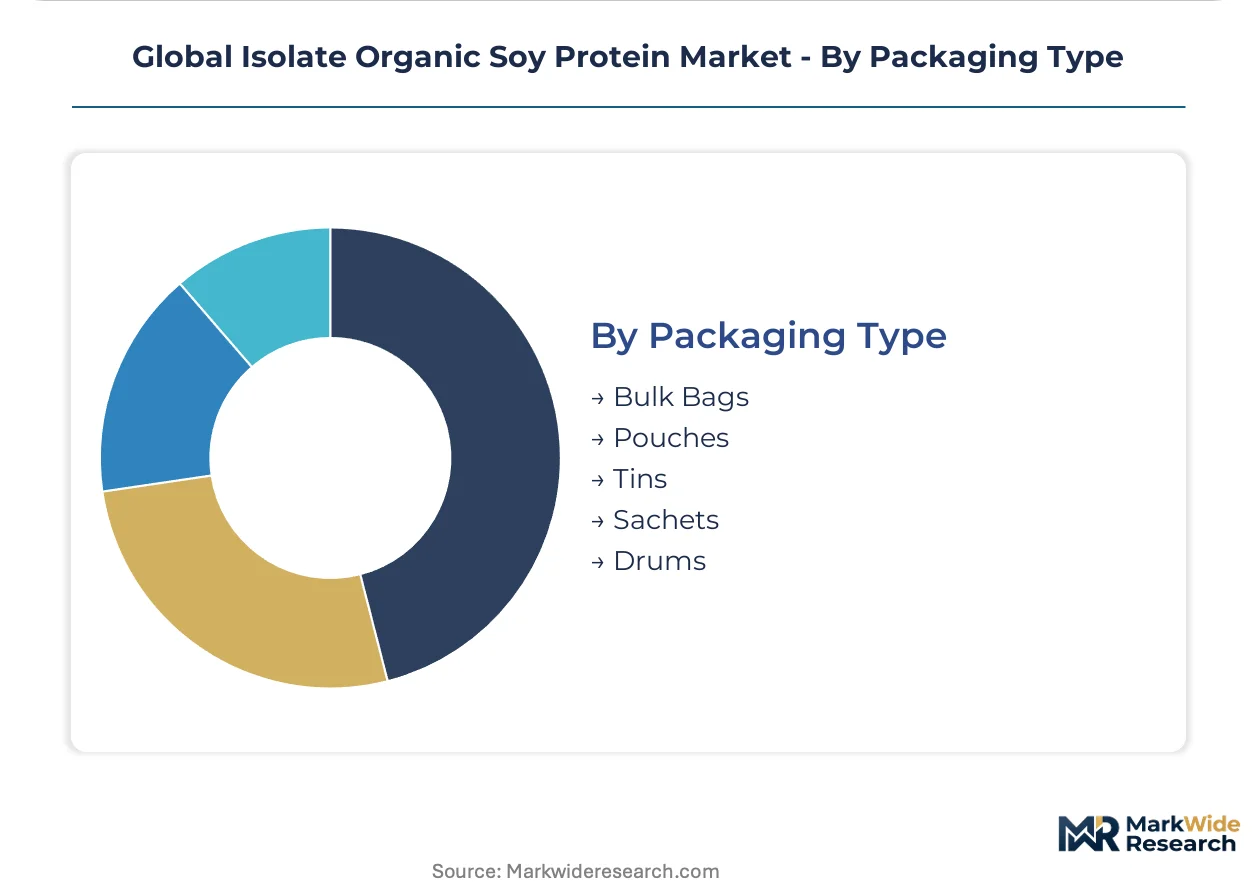
- Bulk Bags:One-tonne flexible intermediate bulk containers for organic crush facilities and toll processors. German and French isolate importers source exclusively from EU-registered facilities with closed-loop solvent recovery systems per REACH amendments.
- Sachets:Single-serve retail sampling formats for sports nutrition brand marketing campaigns. Scandinavian markets show strongest uptake through Coop and ICA Group procurement channels.
- Pouches:Mid-scale foodservice and small-batch manufacturing quantities.
- Drums:Stainless steel or fiber containers for hygroscopic isolate storage.
- Tins:Premium retail presentation formats for organic protein powders.
Bulk Bags dominate throughput volume. Sachets is climbing fastest on sampling demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina and Brazil export organic soybeans to German crushing facilities, establishing a transatlantic trade corridor that channels South American raw material into EU-certified isolate production for Bavarian meat analogue processors.
Germany
Bavarian and Baden-Württemberg organic food processing clusters command premium sourcing contracts for meat analogue and dairy replacement applications. The EU Green Deal mandates tightening contaminant thresholds through EFSA protocols, forcing reformulation toward certified organic isolates. Stuttgart-based ingredient distributors now require blockchain-anchored supply chain records as contract preconditions.
United States
Sports nutrition brands in California and Colorado accelerate procurement of organic isolate grades for amino acid completeness in functional beverages. The USDA National Organic Program governs certification integrity for domestic shipments, while state-level clean-label standards in Oregon and Washington impose additional verification layers. Iowa and Illinois organic crush facilities leverage backward integration into certified farming cooperatives.
Netherlands
Meat analogue manufacturers in the Netherlands adopt enzymatic extraction routes at pilot scale to meet EFSA purity mandates for clean-label burger patties. REACH and EU F-Gas Regulation amendments tighten solvent recovery accounting, pushing Dutch importers toward EU-registered organic crush facilities with closed-loop systems. Rotterdam serves as the primary entry point for South American organic bean shipments.
India
Emerging domestic certification infrastructure under FSSAI organic recognition and PLI scheme incentives for food processing create first-mover positioning for isolate suppliers. Maharashtra and Gujarat organic farming cooperatives are establishing local crushing partnerships to bypass transoceanic certification complexity. Mumbai-based ingredient distributors are compressing traditional supply layers through B2B marketplace platforms.
Switzerland
Infant formula specialists in Basel and Zurich source organic soy protein hydrolysates for premium neonatal nutrition lines, prioritizing hypoallergenic positioning. Swissmedic enforces strict batch-level organic certification documentation for imported protein isolates. The Lake Geneva corridor concentrates formulation R&D for clinical nutrition applications.
Global Isolate Organic Soy Protein Market Competitive Landscape
On the supply side, the industry is consolidating around agricultural trading houses with captive oilseed crush networks and specialized organic processors with certified farming partnerships. Three strategic archetypes dominate: North American agribusiness conglomerates with backward integration into organic bean supply, European ingredient specialists with enzymatic extraction capabilities, and domestic-focused U.S. processors eliminating transoceanic certification complexity. Competitive moves concentrate on capacity expansion in EU-registered facilities and strategic partnerships with meat analogue startups for technical collaboration.
Within the agribusiness tier, Archer Daniels Midland Company and Cargill, Incorporated anchor positions through upstream control over non-GMO organic bean supply chains. Puris occupies a distinct geography-first position, representing the domestic-sourcing archetype that eliminates transoceanic organic certification complexity for U.S. manufacturers. These three exemplify how scale, integration depth, and certification strategy separate market participants.
| Leading Market Players |
|---|
| SunOpta, Inc. |
| Foodchem International Corporation |
| Archer Daniels Midland Company |
| Devansoy Inc. |
| Puris |
| Cargill, Incorporated |
| The Scoular Company |
| Chaitanya Agro Biotech Pvt. Ltd. |
| DuPont de Nemours, Inc. |
| Others |
Supply & Pricing Matrix
Argentine and Brazilian organic soybean harvests concentrate upstream supply leverage, transmitting weather-driven volatility directly to German meat analogue processors who command premium pricing for EFSA-compliant isolates. This geographic tethering concentrates margin capture at the crush facility level while downstream brands absorb certification cost inflation.
Pricing Analysis
Hexane-extracted isolates trade at standard tiers while enzymatic precision-fermentation grades capture premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates EU-certified organic isolates with blockchain traceability from conventional organic grades and commodity non-certified supply. Cost compression in standard tiers is intensifying because pea and fava protein substitution erodes soy volume commitments. Animal nutrition firms exhibit highest price sensitivity; infant formula specialists in Switzerland demonstrate lowest sensitivity due to hypoallergenic specification rigidity.
Supply Chain Analysis
Extended payment terms from Bavarian meat analogue processors strain working capital for mid-scale organic crush facilities in Argentina, Brazil, and India. Raw material dependencies center on certified organic soybean supply, enzymatic processing inputs, and stainless steel extraction infrastructure. Single-source vulnerability concentrates in EU-registered crush facilities with closed-loop solvent systems. Distribution runs through Rotterdam as primary entry point for South American organic bean shipments, then radiates to German processing clusters and Dutch meat analogue manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation and enzymatic extraction are disrupting legacy extraction economics, while EU Green Deal contaminant mandates force parallel certification investments that fragment competitive cost structures.
For Market Incumbents: Harden organic equivalency protocol compliance across USDA National Organic Program and EU Organic Regulation frameworks to preempt audit duplication costs. Expand captive crushing capacity in EU-registered facilities with closed-loop solvent recovery per REACH amendments, neutralizing tariff exposure on South American organic bean imports. For New Entrants and Emerging Players: Maharashtra and Gujarat organic farming cooperatives in India represent the most penetrable entry point for bypassing transoceanic certification complexity. FSSAI organic recognition expansion and PLI scheme incentives create first-mover positioning through local crushing partnerships. B2B ingredient marketplace distribution compresses traditional supply layers for direct access to mid-sized meat analogue brands. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European ingredient specialists possessing enzymatic extraction capabilities but limited organic farming integration. Five-to-ten year viability hinges on backward integration into certified cooperatives or precision fermentation scale-up execution. Monitor divergence between U.S.-EU organic equivalence agreements as inflection signal for parallel certification investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Farming Cooperatives | Cargill anchors position through upstream control over non-GMO organic bean supply chains. |
| Enzymatic Extraction Route Adoption at Pilot Scale | Dutch meat analogue manufacturers adopt precision fermentation to meet EFSA purity mandates. |
| Blockchain-Anchored Supply Chain Documentation | Scandinavian Coop and ICA Group procurement teams mandate real-time traceability dashboards. |
| EU-Registered Crush Facility Capacity Expansion | German and French importers source exclusively from facilities with closed-loop solvent systems. |
| B2B Ingredient Marketplace Platform Launch | Mumbai-based distributors compress traditional supply layers for direct manufacturer access. |
Research Methodology
A spread of perspectives from organic crush facility operators, meat analogue R&D directors, sports nutrition procurement leads, and EU regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through USDA National Organic Program filings, EFSA contaminant threshold databases, EU Organic Regulation equivalence agreements, and customs trade records. Bottom-up volume modeling triangulated against top-down protein isolate demand estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product purity tier, application channel, end-user sophistication level, and regional regulatory cluster. CAGRs were derived from growth driver elasticity analysis against baseline penetration rates. Industry-specific inputs incorporated organic soybean yield volatility patterns and enzymatic process engineering talent availability constraints.
Practitioners should monitor organic equivalency agreement negotiations, precision fermentation scale-up milestones, and EU F-Gas Regulation enforcement intensity for early signals. Forecasts reflect documented assumptions on certification cost trajectories and substitution elasticity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Bacon Market
Plant Based Food
Plant Based Pasta Market
Plant Based Food
Global Plant Based Milk Market
Plant Based Food
Indonesia Plant-Based Food and Beverages Market
Plant Based Food
Vegan Margarine Market
Plant Based Food
Black Rice Protein Market
Plant Based Food
West Africa Plant Based Product Market
Plant Based Food
Rhubarb Root Extract Market
Plant Based Food
Plant-Based Meatballs Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Plant-Based Flour Market
Plant Based Food
Europe Plant-Based Meal Kit Market
Plant Based Food
New Jersey Vegan Products Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
US Plant-Based Meat Market
Plant Based Food
North America Tofu Market