
 Asia-Pacific Rice Protein Market | 2026-2036
Asia-Pacific Rice Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Rice Protein Market Outlook
Multi-source procurement of organic brown rice is expanding across the Asia-Pacific rice protein value chain as buyers reduce dependency on single-origin supply. Shafi Gluco Chem leverages its vertically integrated starch and protein operations in Pakistan to sustain cost advantages in concentrate grades. Axiom Foods anchors North American export demand through its organic certification stack, while Jiangxi Golden Agriculture Biotech dominates domestic Chinese supply with in-house enzymatic extraction capabilities.
Rice protein comprises the albumin and glutelin fractions extracted from brown or white rice through aqueous enzymatic hydrolysis, typically yielding protein contents ranging from 50% in concentrates to over 80% in isolates with balanced amino-acid profiles excluding lysine. The ingredient serves as a hypoallergenic alternative to soy and dairy proteins in clean-label formulations across food and beverage applications. Isolate grades command the deepest margin pools due to solubility requirements in ready-to-drink beverages, while hydrolysate output is accelerating fastest among fitness-oriented dietary supplements seeking rapid absorption claims. Food and beverage applications occupy the volume base, though cosmetics-grade textured proteins remain a nascent specialty segment with limited supplier competition.
FSSAI in India enforces protein-content labeling and contaminant thresholds that shape import acceptance criteria for rice protein destined for domestic supplement brands. China's SAMR and NMPA jointly regulate novel food ingredient registrations, creating compliance gates for hydrolysate entrants seeking health-food blue-hat certification. Australia's TGA and FSANZ standards influence export-oriented manufacturers across Southeast Asia. Stakeholders must monitor divergence between allergen-free certification schemes as retail buyers in Japan and South Korea impose distinct vendor-qualification protocols that fragment market-access requirements.
Market Dynamics
FSSAI protein-labeling enforcement in India is compressing supplier qualification timelines across the Asia-Pacific rice protein value chain, forcing manufacturers to accelerate third-party certification investments before the 2026 compliance window closes.
Growth Catalysts
- Enzymatic extraction efficiency gains:In-house enzymatic capabilities at Chinese contract manufacturers are reducing isolate production costs by 15-20% versus solvent-based alternatives, unlocking price-competitive supply for Australian sports nutrition brands.
- Japan's allergen-free retail protocols:Major Japanese supermarket chains now mandate vendor-specific allergen-free certification stacks, creating procurement preference for rice protein over soy and dairy alternatives in clean-label formulations.
- South Korea's functional food registration pathway:MFDS streamlined health-functional food approvals for plant proteins are accelerating market entry timelines for hydrolysate grades targeting fitness applications.
Market Restraints
- Single-origin supply concentration:Premium organic brown rice procurement remains concentrated in Pakistan's Sindh and Punjab provinces, exposing buyers to monsoon-driven crop volatility and quality inconsistency.
- Lysine deficiency technical ceiling:Rice protein's incomplete amino acid profile requires costly blending with pea or pumpkin seed proteins to achieve complete protein claims, compressing margin structures for isolate-grade suppliers.
- China's dual-registration burden:SAMR novel food ingredient registration combined with NMPA health-food blue-hat certification creates 18-24 month approval timelines that deter hydrolysate market entrants.
Strategic Opportunities
- Vietnam's underpenetrated processing base:Limited domestic enzymatic extraction capacity creates first-mover advantage for contract manufacturers establishing operations in Ho Chi Minh City's industrial zones to serve ASEAN export demand.
- Cosmetics-grade textured proteins:Biodegradable film and personal care applications represent nascent demand with limited supplier competition and 40-60% price premiums over food-grade concentrates.
- Australia's TGA-export halo:TGA-registered manufacturing facilities gain automatic qualification for Southeast Asian markets, creating regulatory arbitrage opportunities for Australian-based processors serving Thai and Indonesian brands.
Industry Challenges
- Enzymology talent scarcity:Commercial-scale enzymatic extraction requires specialized protein biochemists and process engineers in short supply across China's Shandong and Jiangsu manufacturing clusters.
- Multi-jurisdiction certification stacking:Simultaneous pursuit of organic, non-GMO, allergen-free, and halal certifications for export-oriented production creates 12-18 month timeline compression risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Rice Protein Market |
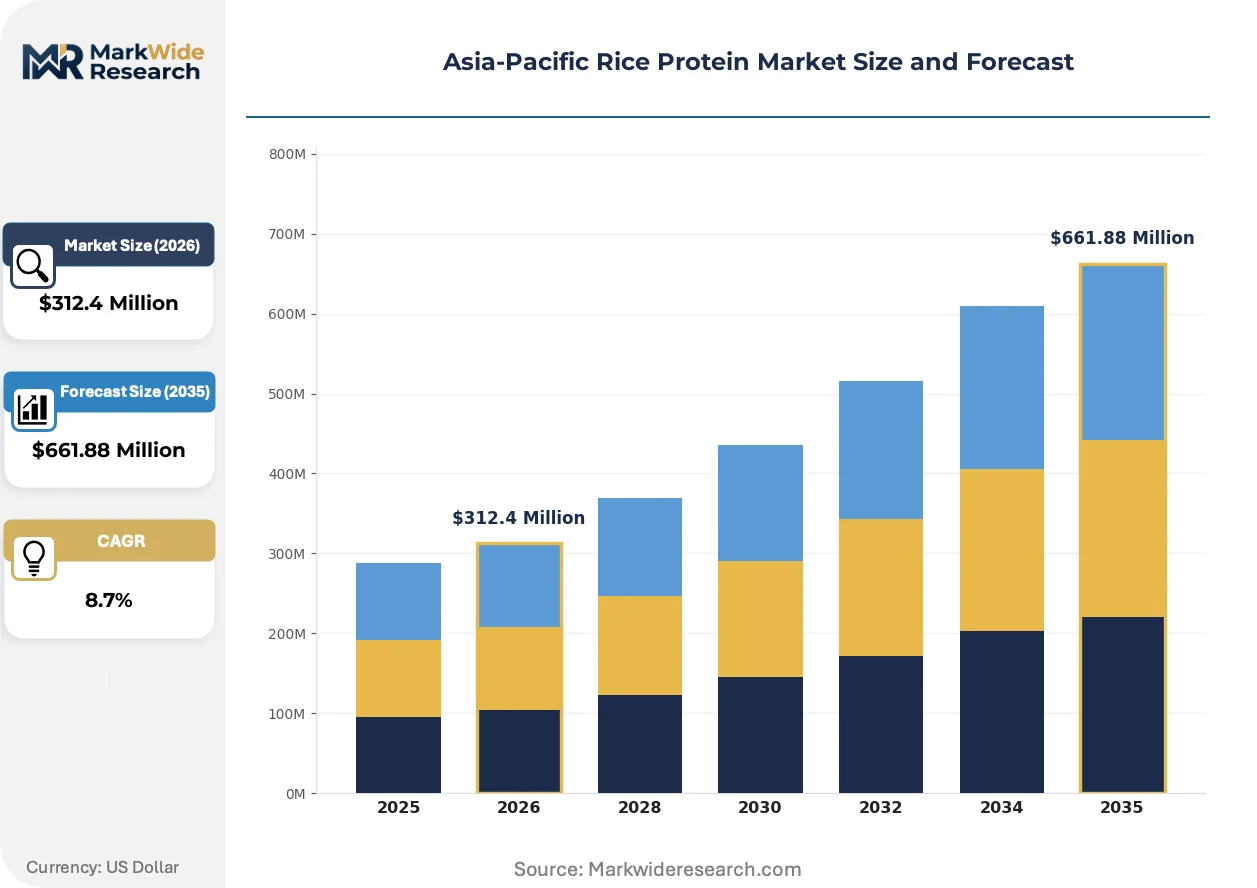
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Hydrolysate, Textured Application: Food & Beverages, Dietary Supplements, Animal Feed, Cosmetics Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Stores End User: Fitness Enthusiasts, Vegans, Athletes, General Consumers |
| Companies Covered | Shafi Gluco Chem Pvt. Ltd., Habib-ADM Ltd., Axiom Foods Inc., Jiangxi Golden Agriculture Biotech Co. Ltd., Gulshan Polyols Ltd., Bioway (Xi'an) Organic Ingredients Co. Ltd., Shaanxi Fuheng (FH) Biotechnology Co. Ltd., Wuxi Jinnong Biotechnology, Golden Grain Group Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Rice Protein Market Strategic Shifts
Process intensification and regulatory convergence are reshaping competitive positioning across the Asia-Pacific rice protein landscape, with enzymatic extraction advances and certification harmonization emerging as decisive capability differentiators.
Membrane filtration technology is expanding into commercial isolate production, replacing traditional acid-precipitation methods with gentler protein recovery that preserves functional properties. Australian ready-to-drink beverage manufacturers are adopting membrane-processed isolates at 25-30% volume growth rates for 2024-2025 procurement cycles. This shift is expanding into premium pricing tiers previously reserved for dairy and pea protein isolates, compressing the historical quality gap between rice and alternative plant proteins.
FSSAI's 2024 protein-content labeling amendments mandate third-party analytical verification for all imported protein ingredients above 50% concentration, with specific heavy-metal and microbial thresholds aligned to Codex Alimentarius standards. Indian contract manufacturers serving domestic supplement brands are responding by pre-qualifying suppliers against FSSAI, TGA, and MFDS requirements simultaneously. The regulatory friction most acutely affects concentrate-grade imports from Pakistan and Myanmar, where analytical infrastructure gaps create documentation delays.
Direct-procurement relationships between Australian sports nutrition brands and Chinese enzymatic processors are displacing traditional trader-mediated supply chains, with volume commitments replacing spot-market purchasing. This channel restructuring concentrates contract volume with Jiangsu and Shandong manufacturers holding multi-certification stacks. The behavioral shift is most visible in Melbourne and Sydney-headquartered brands targeting export markets across Southeast Asia, where supply-chain transparency requirements from Japanese and South Korean retail buyers mandate processor-level traceability.
Asia-Pacific Rice Protein Market Segmentation
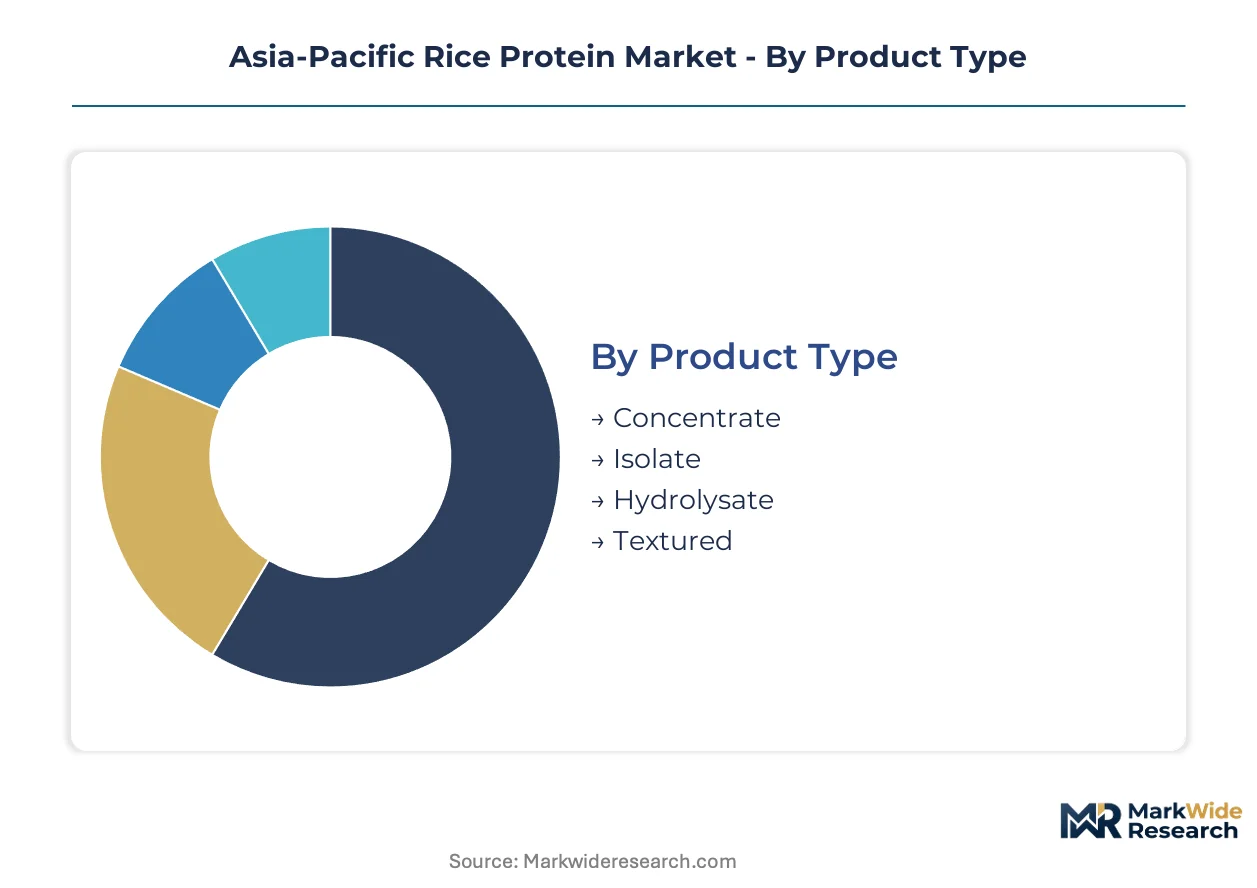
Rice protein suppliers configure their production assets and certification stacks around discrete segment requirements. Product grade determines extraction technology investment, while application verticals dictate regulatory compliance pathways across FSSAI, TGA, and MFDS jurisdictions.
Product Type:
Integration depth varies sharply across grades: isolates and hydrolysates demand dedicated enzymatic lines and separate allergen-free protocols, while concentrates and textured proteins flow through shared infrastructure with starch co-products.
- Concentrate:Protein content ranges from 50-70% with retained fiber and carbohydrate fractions from brown rice. Australian sports nutrition brands procure concentrate grades for powder blends where solubility requirements remain moderate.
- Isolate:Enzymatic extraction yields protein content exceeding 80% with neutral flavor profiles and enhanced solubility. Japanese ready-to-drink beverage manufacturers specify isolate grades for clean-label formulations requiring transparent dissolution.
- Hydrolysate:Pre-digested peptide fractions accelerate absorption claims for fitness applications. South Korea's MFDS streamlined approvals are compressing market entry timelines for hydrolysate entrants.
- Textured:Extruded protein structures serve meat analog and cosmetic film applications with limited supplier competition.
Volume placements concentrate in Concentrate; the faster expansion belongs to Isolate.
Application:
Cost tier separation drives procurement behavior: premium-positioned applications command certified-organic isolates, while mass-market formulations absorb standard-grade concentrates.
- Food & Beverages:Plant-based dairy alternatives and baked goods absorb rice protein for hypoallergenic positioning. China's Shandong province contract manufacturers supply export-oriented brands with FSSC 22000-certified isolates.
- Dietary Supplements:Sports nutrition powders and meal replacements represent the deepest margin pool. Australian brands accelerate direct procurement from Jiangsu enzymatic processors to satisfy TGA export requirements.
- Animal Feed:Pet food formulations leverage rice protein for allergen-free claims in premium positioning.
- Cosmetics:Biodegradable films and personal care applications command 40-60% price premiums with nascent demand concentration.
Revenue concentration sits with Dietary Supplements; Cosmetics applications are climbing the fastest.
Distribution Channel:
Customer type fragmentation shapes channel strategy: institutional buyers favor direct processor relationships, while fragmented end-users flow through retail intermediaries.
- Online Retail:Direct-to-consumer sports nutrition brands in Australia and Japan bypass traditional distribution. Melbourne-headquartered companies utilize proprietary e-commerce platforms with processor-level traceability documentation.
- Supermarkets:Major Japanese chains mandate vendor-specific allergen-free certification stacks, filtering supplier eligibility. Clean-label positioning in Tokyo and Osaka retail networks favors rice protein over soy alternatives.
- Health Stores:Specialty retailers in South Korea and Thailand stock premium isolate grades with MFDS or TGA registration marks.
- Specialty Stores:Vegan and organic-focused independents in Sydney and Mumbai concentrate procurement on certified-organic concentrates.
Transaction volume flows through Supermarkets; Online Retail channels are gaining share fastest.
End User:
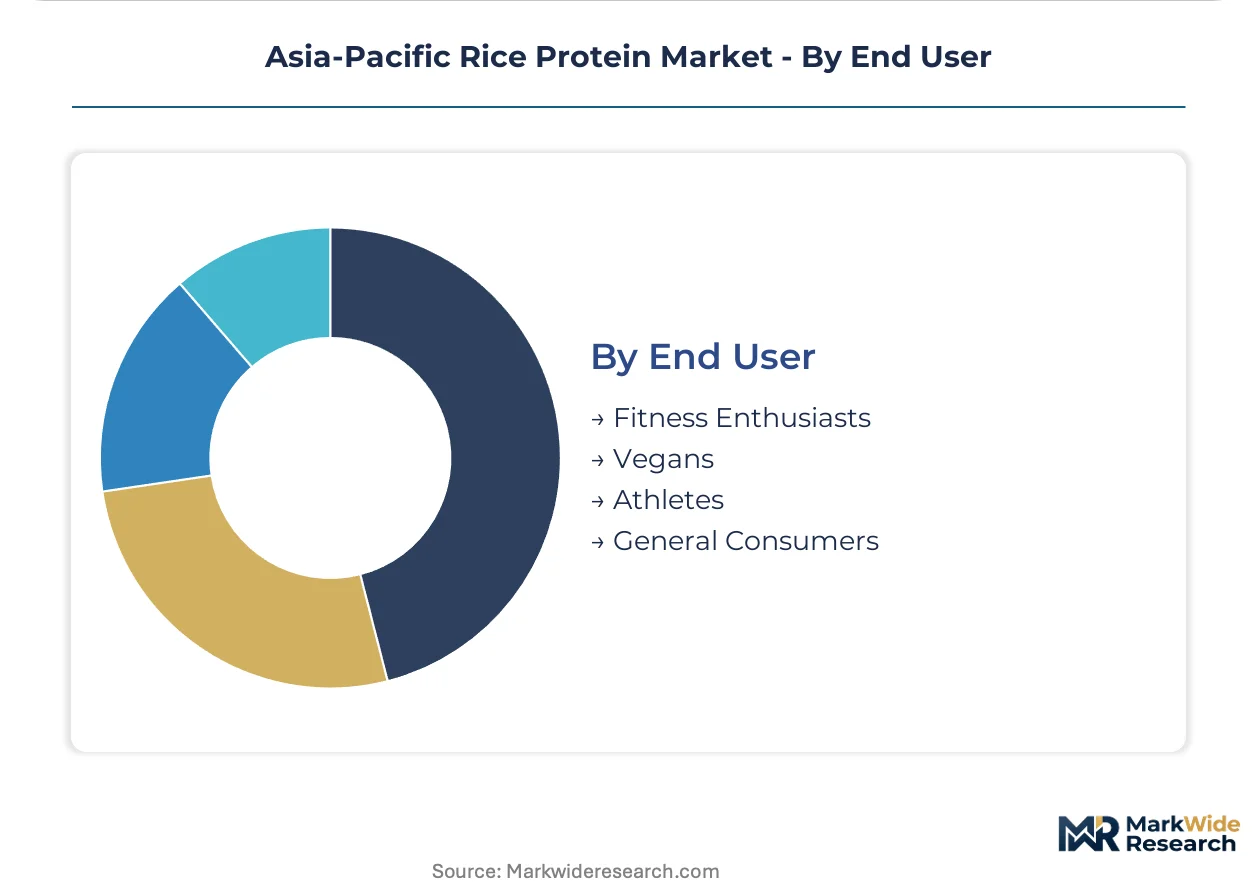
Supply concentration aligns with certification intensity: athlete and fitness segments demand analytical verification stacks that general consumer applications bypass.
- Fitness Enthusiasts:Rapid-absorption hydrolysate grades target post-workout recovery positioning. South Korean brands leverage MFDS functional food registrations to compress claim substantiation timelines.
- Vegans:Ethical positioning drives preference for certified-organic, non-GMO isolates with full supply chain transparency. Japanese retail protocols mandate processor-level documentation.
- Athletes:Competitive and professional segments require batch-tested isolates with contaminant thresholds aligned to TGA or WADA standards.
- General Consumers:Mainstream adoption flows through food and beverage applications where hypoallergenic claims support clean-label marketing.
Procurement scale concentrates with General Consumers; Athlete segments are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diet-side procurement concentrates in eastern China's enzymatic processing clusters and Australia's direct-import channels, with regulatory divergence across FSSAI, TGA, and MFDS jurisdictions fragmenting supplier qualification requirements.
China
Shandong and Jiangsu provinces host the dominant contract manufacturing base for rice protein isolates, with enzymatic extraction capabilities reducing production costs versus solvent-based alternatives. SAMR and NMPA jointly enforce dual-registration requirements for novel food ingredients and health-food blue-hat certification, creating 18-24 month approval timelines that deter hydrolysate market entrants. Jiangxi Golden Agriculture Biotech anchors domestic supply through in-house enzymatic extraction capabilities serving export-oriented supplement brands.
India
FSSAI's 2024 protein-content labeling amendments mandate third-party analytical verification for imported protein ingredients above 50% concentration, compressing supplier qualification timelines before the 2026 compliance window closes. Heavy-metal and microbial thresholds aligned to Codex Alimentarius standards most acutely affect concentrate-grade imports from Pakistan and Myanmar, where analytical infrastructure gaps create documentation delays. Domestic contract manufacturers serving supplement brands are pre-qualifying suppliers against FSSAI, TGA, and MFDS requirements simultaneously.
Japan
Major supermarket chains mandate vendor-specific allergen-free certification stacks, creating procurement preference for rice protein over soy and dairy alternatives in clean-label formulations. METI standards influence export-oriented manufacturers across Southeast Asia through technical harmonization pressures. Tokyo and Osaka retail networks filter supplier eligibility through processor-level traceability documentation that Melbourne-headquartered brands must satisfy for Southeast Asian export markets.
Australia
TGA-registered manufacturing facilities gain automatic qualification for Southeast Asian markets, creating regulatory arbitrage opportunities for Australian-based processors serving Thai and Indonesian brands. Direct-procurement relationships between Melbourne and Sydney-headquartered sports nutrition brands and Chinese enzymatic processors are displacing traditional trader-mediated supply chains. Volume commitments replace spot-market purchasing as supply-chain transparency requirements from Japanese and South Korean retail buyers mandate processor-level traceability.
South Korea
MFDS streamlined health-functional food approvals for plant proteins are accelerating market entry timelines for hydrolysate grades targeting fitness applications. Rapid-absorption hydrolysate grades target post-workout recovery positioning for fitness enthusiasts, with batch-tested isolates requiring contaminant thresholds aligned to TGA or WADA standards for competitive segments. Specialty retailers in Seoul and Busan stock premium isolate grades with MFDS registration marks that signal analytical verification to athlete and vegan consumer segments.
Asia-Pacific Rice Protein Market Competitive Environment
Capacity expansion dominates the current landscape as enzymatic extraction investments concentrate contract volume with multi-certification processors. The vendor base stratifies across three tiers: vertically integrated agricultural processors controlling upstream brown rice supply, specialized enzymatic extraction firms serving export-oriented brands, and regional traders mediating spot-market transactions. Strategic archetypes include certification-stack aggregators, enzymology-capability specialists, and backward-integrated agricultural processors. Geographic expansion and technology licensing represent the dominant competitive moves, with players establishing enzymatic processing capabilities in Vietnam's underpenetrated industrial zones.
Within the vertically integrated tier, Shafi Gluco Chem leverages its Pakistan-based starch and protein operations to sustain cost advantages in concentrate grades. Axiom Foods anchors North American export demand through its organic certification stack, while Jiangxi Golden Agriculture Biotech dominates domestic Chinese supply with in-house enzymatic extraction capabilities. These three exemplify how geographic positioning and certification depth determine competitive access to premium pricing tiers across FSSAI, TGA, and MFDS jurisdictions.
| Leading Market Players |
|---|
| Shafi Gluco Chem Pvt. Ltd. |
| Habib-ADM Ltd. |
| Axiom Foods Inc. |
| Jiangxi Golden Agriculture Biotech Co. Ltd. |
| Gulshan Polyols Ltd. |
| Bioway (Xi'an) Organic Ingredients Co. Ltd. |
| Shaanxi Fuheng (FH) Biotechnology Co. Ltd. |
| Wuxi Jinnong Biotechnology |
| Golden Grain Group Ltd. |
| Others |
Value Chain & Pricing Dynamics
Enzymology talent scarcity in China's Shandong and Jiangsu provinces widens labor-cost differentials between enzymatic isolate producers and solvent-based concentrate manufacturers, compressing pricing-tier spreads as certified processors command 15-20% production cost advantages.
Pricing Analysis
Certification-bundling separates quoted prices: FSSC 22000 and organic verification are typically included in isolate premiums, while third-party allergen-free testing and batch-specific analytical reports are unbundled add-ons. Three-tier pricing structure across premium, standard, and economy levels reflects protein content grade and certification stack depth. Pricing pressure stems from enzymatic efficiency gains at Chinese contract manufacturers passing cost reductions to Australian sports nutrition brands. Powder-blend manufacturers show highest price sensitivity; ready-to-drink beverage formulators absorb premiums for solubility-assured isolates.
Supply Chain Analysis
Premium organic brown rice procurement rests on Pakistan's Sindh and Punjab provinces, with enzymatic extraction capacity concentrating in China's Shandong and Jiangsu manufacturing clusters. Raw material dependencies span brown rice supply, commercial enzyme formulations, and membrane filtration equipment. Single-origin crop concentration exposes buyers to monsoon-driven quality volatility and documentation gaps. Distribution runs through direct-procurement relationships displacing trader-mediated spot markets, with Australian brands securing volume commitments from Chinese enzymatic processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market is becoming a vertical-integration race, with players pursuing backward control over organic brown rice supply to defend margin structures against certification-cost inflation.
For Market Incumbents: Hedge against enzymology talent scarcity by securing exclusive contracting arrangements with protein biochemist programs at Jiangsu and Shandong technical universities. Defend market position through captive brown rice procurement in Pakistan's Sindh province, reducing exposure to monsoon-driven supply interruptions that disrupt concentrate-grade output.
For New Entrants and Emerging Players: Cosmetics-grade textured protein buyers represent an underserved buyer archetype with 40-60% price premiums and limited supplier competition. Establish enzymatic extraction operations in Vietnam's Ho Chi Minh City industrial zones to capture ASEAN export demand flowing through Australian TGA-registered channels. Lead with biodegradable film applications to bypass food-grade certification stacking requirements.
For Investors and Strategic Acquirers: Re-rating potential sits with multi-certification processors given FSSAI's 2026 compliance window compressing supplier qualification timelines. Long-term viability favors assets with simultaneous organic, non-GMO, and halal certification stacks serving Japanese retail protocols. Watch MFDS hydrolysate approval velocity as inflection indicator for fitness-application market entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Capacity Expansion | Chinese processors in Shandong reduce isolate production costs versus solvent alternatives, unlocking Australian sports nutrition procurement. |
| Backward Integration into Brown Rice Supply | Pakistan-based operations secure organic premium positioning while mitigating monsoon-driven crop volatility exposure. |
| Multi-Jurisdiction Certification Stacking | Simultaneous FSSAI, TGA, and MFDS pre-qualification compresses supplier timelines before Indian compliance deadlines. |
| Cosmetics-Grade Textured Protein Development | Biodegradable film applications command 40-60% premiums with limited supplier competition in personal care segments. |
| Vietnam Manufacturing Footprint Establishment | Ho Chi Minh City enzymatic processing captures ASEAN export demand with first-mover advantage in underpenetrated base. |
Study Parameters
Trade databases, regulatory filings from FSSAI and SAMR, and customs export records formed the secondary backbone, cross-referenced with primary interviews across enzymatic extraction plant managers, sports nutrition brand procurement leads, and third-party certification auditors. Bottom-up and top-down triangulation validated volume estimates against contract manufacturer disclosed capacities and import documentation patterns.
Bottom-up modeling anchored projections, segmenting by product grade, application vertical, and regulatory jurisdiction cluster across the analysis window. CAGRs derived from enzymatic capacity expansion timelines, certification adoption curves, and direct-procurement relationship formation rates in Australian and Japanese buyer bases.
Revisions become necessary when FSSAI enforcement intensity shifts, enzymology labor markets tighten beyond current scarcity levels, or Japanese retail allergen-free protocols expand vendor-qualification requirements. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Flour Market
Plant Based Food
Middle East Plant Protein Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Italy Plant Protein Market
Plant Based Food
Meat Substitutes Market
Plant Based Food
Enzyme-Based Plant Protein Market
Plant Based Food
Singapore Plant-Based Food and Beverages Market
Plant Based Food
Yucca Extract Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
Fermented Plant-Based Ingredient Market
Plant Based Food
Canada Plant Protein Market
Plant Based Food
Vegan Steak Market
Plant Based Food
Plant-Based Food Ingredients Market
Plant Based Food
Plant Chocolate Protein Powder Market
Plant Based Food
United States Pea Protein Market