
 Global Chaga Mushroom-Based Products Market | 2026-2036
Global Chaga Mushroom-Based Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chaga Mushroom-Based Products Market Analysis
USDA Organic certification is bifurcating the competitive landscape into qualified suppliers and excluded commodity traders. Sayan Health leverages its Siberian wild-harvesting network to control premium raw material flows. Om Mushroom Superfood sustains R&D intensity across dual-extraction protocols that standardize beta-glucan content. Fungi Perfecti LLC anchors its position through mycologist-led education platforms that build practitioner channel loyalty.
Global Chaga Mushroom-Based Products encompass formulations derived from Inonotus obliquus, a parasitic fungus harvested from birch trees in boreal climates, typically processed through hot-water or dual-extraction methods to concentrate betulinic acid and polysaccharides for immune-support and adaptogenic applications. Extracts command the deepest margin pools due to concentration ratios and clinical positioning, while capsules dominate volume through pharmacy and practitioner channels. E-commerce represents the fastest-growing distribution channel as direct-to-consumer brands bypass traditional retail markups.
FDA dietary supplement regulations govern structure-function claims and cGMP compliance for US-market entrants, while EFSA novel food assessments delay European product launches pending toxicology dossiers. China's SAMR and NMPA frameworks impose additional export hurdles for finished goods entering Asia-Pacific wellness markets. Stakeholders must monitor evolving extraction-method patents and geographic indication movements that could reshape raw material access and pricing power.
Market Dynamics
Dual-extraction standardization is compressing quality variance and forcing raw material suppliers into certification-heavy procurement relationships with finished goods manufacturers.
Growth Catalysts
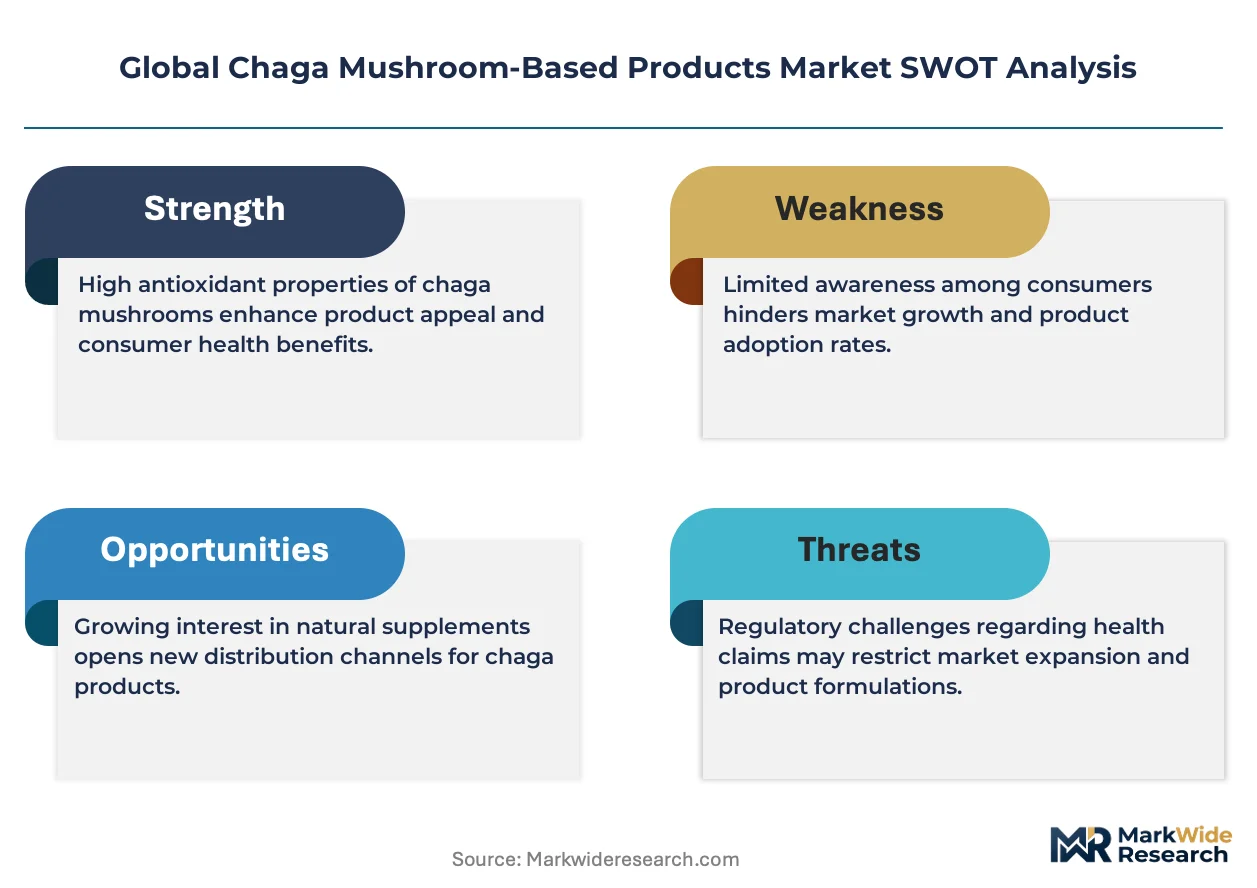
- EU Novel Food Regulation pathways:EFSA toxicology dossier approvals are creating first-mover advantages for compliant entrants in European functional beverage channels.
- Siberian wild-harvesting corridors:Birch forest concentration in Irkutsk and Krasnoyarsk regions supplies authenticated Inonotus obliquus to premium extractors.
- Practitioner channel expansion:Integrative medicine clinics in the United States are prescribing chaga tinctures for immune-modulation protocols.
Market Restraints
- Birch bark input volatility:Boreal forest harvesting permits fluctuate with Russian federal land-use policies.
- Wild supply concentration:Authentic chaga growth requires specific birch host conditions found only in subarctic zones.
- EFSA novel food friction:Eighteen-to-twenty-four month assessment timelines delay European product launches versus North American market entry.
Strategic Opportunities
- South Korean functional food white space:MFDS health functional food registration pathways remain underutilized by Western chaga brands.
- Hot-water plus ethanol dual-extraction convergence:Standardized beta-glucan and betulinic acid profiles enable clinical positioning.
- Direct-to-consumer subscription models:E-commerce platforms bypass pharmacy retail markups and capture recurring revenue.
Industry Challenges
- Mycologist talent scarcity:Fungal identification expertise for wild-harvest authentication commands premium compensation.
- USDA Organic certification timelines:Three-year transition periods for cultivated chaga operations strain working capital.
- Extraction method patent thickets:Proprietary ultrasonic and supercritical CO2 processes create licensing complexity for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chaga Mushroom-Based Products Market |
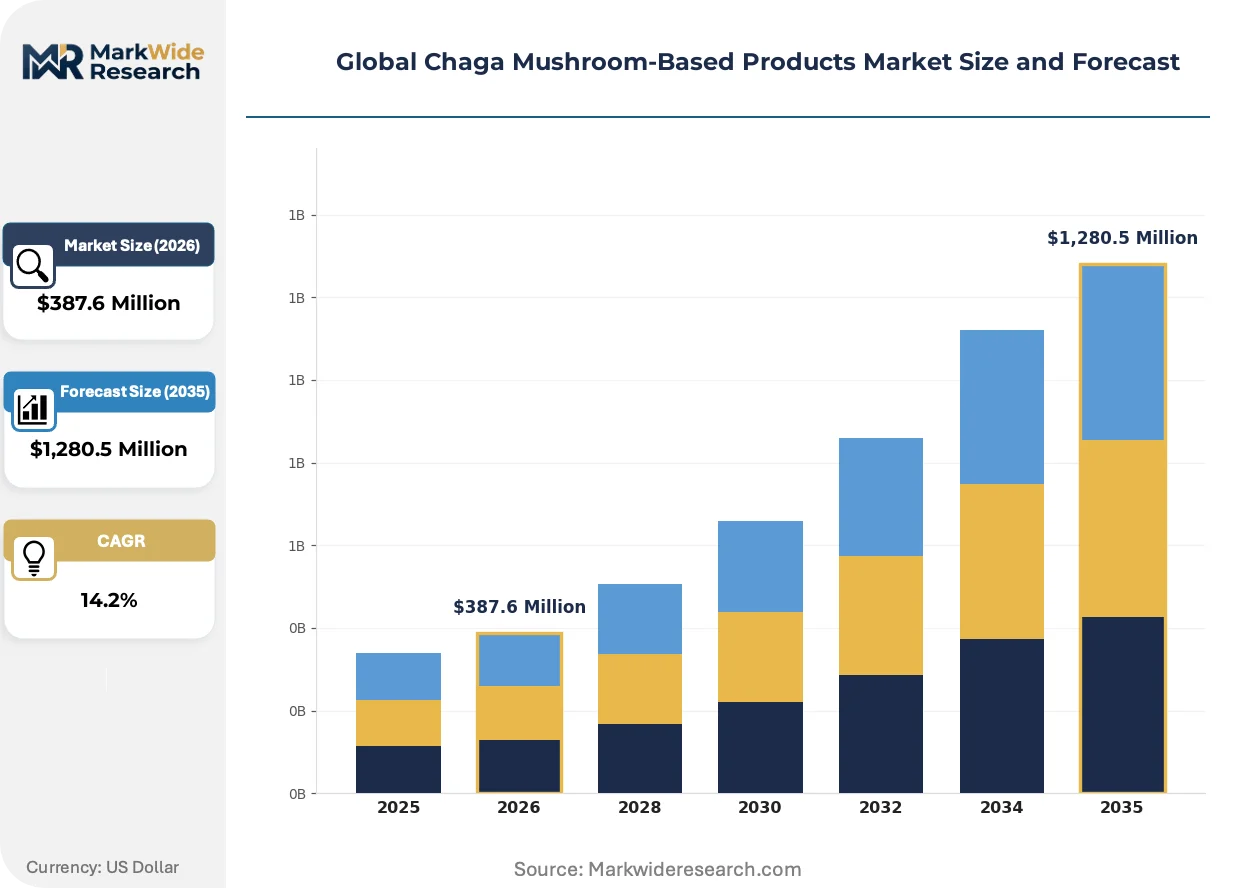
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracts, Powder, Teas, Capsules End User: Retail Consumers, Health Food Stores, Wellness Centers, Online Retail Distribution Channel: Direct Sales, E-commerce, Specialty Stores, Supermarkets Form: Solid, Liquid, Dry, Brewed |
| Companies Covered | Sayan Health, Om Mushroom Superfood, Fungi Perfecti LLC, Host Defense, Four Sigmatic, Annanda Chaga Mushrooms, Aloha Medicinals, Real Mushrooms, Baikal Herbs Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chaga Mushroom-Based Products Market Emerging Trajectories
Biomarker-verified sourcing is replacing origin claims as the primary quality signal, while extraction technology races concentrate betulinic acid yields and regulatory compliance automation accelerates market access.
Ultrasonic-assisted extraction is fragmenting competitive positioning among mid-tier processors. Functional beverage manufacturers in Canada and the United States are adopting this method to achieve higher polysaccharide concentration ratios than conventional hot-water techniques. The technology is fragmenting margin structures by enabling smaller producers to match large-scale extractors on standardized potency claims without captive Siberian sourcing networks.
REACH substance registration requirements for novel fungal extracts are tightening entry barriers for European market participants. ECHA dossier preparation costs and testing timelines favor established suppliers with dedicated regulatory affairs functions. Small-batch artisan producers in Nordic countries are responding by partnering with contract laboratories for shared toxicology data packages.
Subscription-based replenishment models are displacing one-time retail purchases in direct-to-consumer channels. Wellness-focused buyers in Germany and Australia are locking into quarterly delivery cycles for chaga powders and tinctures. This behavioral shift is most visible among urban professionals aged 35-50 who prioritize convenience and dosage consistency over pharmacy counter availability.
Global Chaga Mushroom-Based Products Market Segmentation
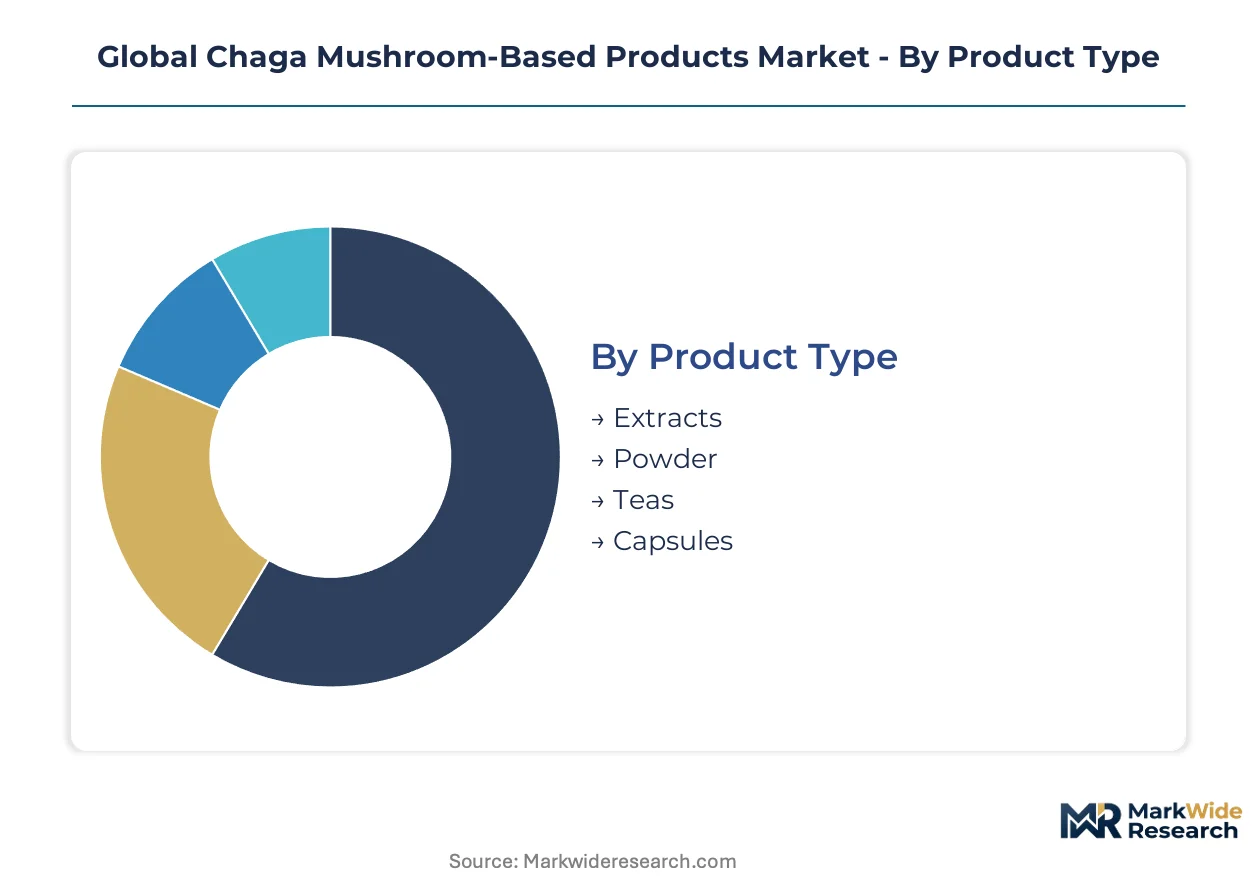
Product format determines regulatory pathway complexity and margin structure in chaga commerce. Extraction method and concentration ratios differentiate compliance requirements across jurisdictions, while distribution channel selection shapes customer acquisition economics and brand positioning.
Product Type:
FDA structure-function claims and EFSA novel food assessments create divergent approval timelines across concentration tiers.
- Extracts:Dual-extraction concentrates standardize beta-glucan and betulinic acid ratios for practitioner channel positioning. Demand concentrates in North American integrative medicine clinics where cGMP compliance enables insurance-adjacent reimbursement discussions.
- Powder:Single-ingredient bulk formats serve functional beverage manufacturers and private-label brands seeking formulation flexibility. Siberian wild-harvested material commands premium positioning against cultivated alternatives in German and Australian direct-to-consumer channels.
- Teas:Whole chunk and cut-and-sift formats appeal to traditional preparation methods in Russian and Korean heritage markets.
- Capsules:Pre-dosed convenience formats dominate pharmacy retail and practitioner dispensing protocols.
Established volume favors capsules; emerging adoption favors extracts.
End User:
Customer acquisition cost tiers separate recurring subscription buyers from one-time retail purchasers.
- Retail Consumers:Direct-to-subscription models capture urban professionals aged 35-50 through quarterly replenishment cycles bypassing pharmacy markups.
- Health Food Stores:Staff-education-dependent velocity requires branded merchandising support and mycologist-led training materials.
- Wellness Centers:Clinical positioning demands third-party lab verification and batch-specific biomarker documentation for protocol integration.
- Online Retail:Marketplace algorithms favor review velocity and USDA Organic certification badges for search ranking.
Revenue concentration sits with retail consumers; margin expansion favors wellness centers.
Distribution Channel:
Geographic reach and regulatory burden trade off across channel architectures.
- Direct Sales:Practitioner and spa networks enable premium pricing through relationship-based consultation models.
- E-commerce:Subscription infrastructure captures lifetime value in Germany and Australia where convenience prioritization displaces pharmacy loyalty.
- Specialty Stores:Curated assortment environments in Canada and United States reward origin storytelling and wild-harvest authentication.
- Supermarkets:Mass retail placement demands price compression and conventional cultivation sourcing to hit velocity thresholds.
Volume scale favors supermarkets; customer lifetime value expansion favors e-commerce.
Form:
Stability requirements and extraction completeness define supply chain configuration.
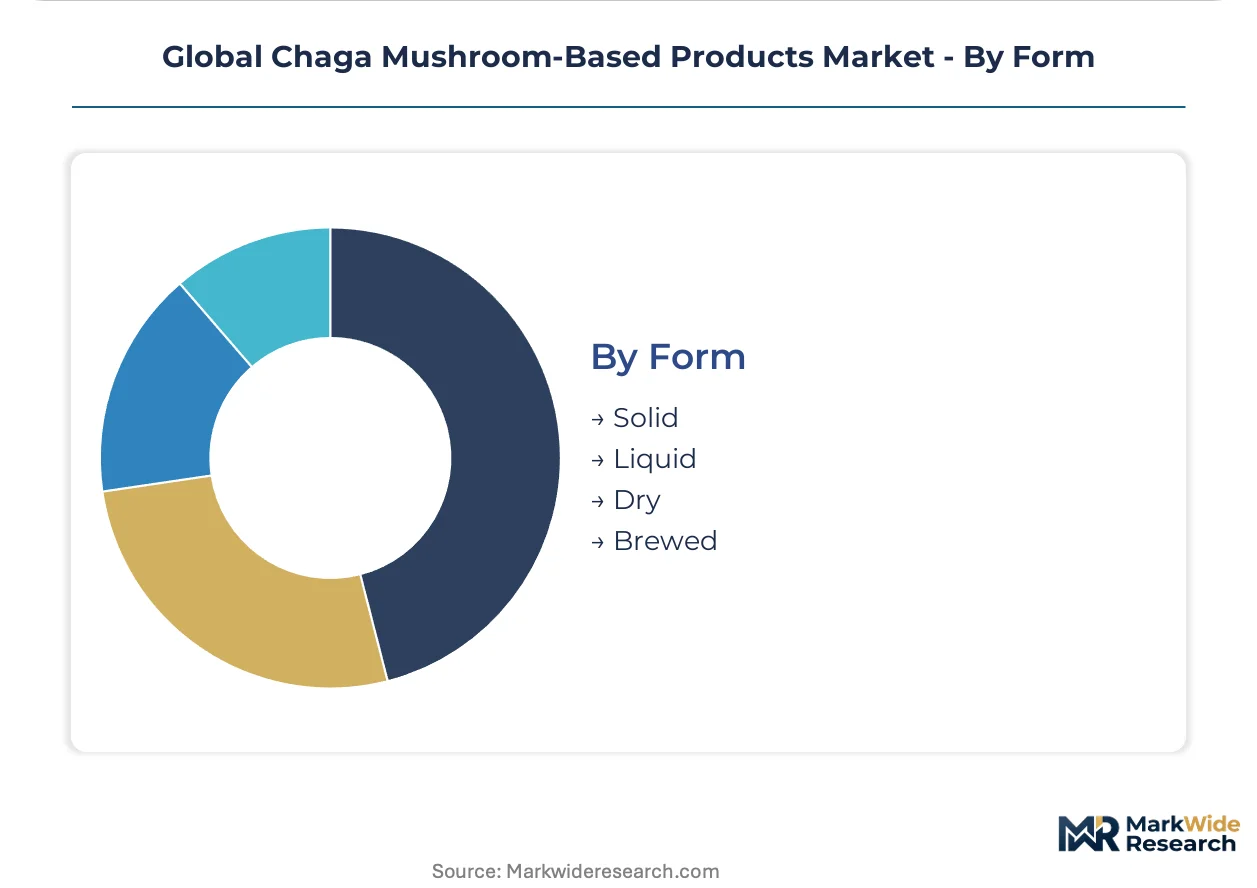
- Solid:Freeze-dried chunks and granules preserve raw matrix complexity for traditional decoction methods in heritage consumer segments.
- Liquid:Tinctures and glycerites enable rapid absorption claims and portable dosing for travel and workplace consumption.
- Dry:Spray-dried and freeze-dried powders optimize shipping economics and shelf stability for bulk ingredient trade.
- Brewed:Ready-to-drink formulations require hot-fill processing and aseptic packaging for convenience positioning.
Supply chain efficiency favors dry formats; experience differentiation favors brewed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Novel Food Regulation compliance timelines are accelerating investment in toxicology dossier preparation across European entrants. North American procurement networks are consolidating around USDA Organic certified Siberian supply corridors. Asia-Pacific functional food registrations remain underpenetrated by Western extractors despite MFDS pathway clarity.
United States
FDA cGMP compliance requirements and practitioner channel expansion are driving dual-extraction standardization investments. Structure-function claim substantiation protocols govern immune-modulation positioning in integrative medicine clinics. Pacific Northwest wild-harvesting territories in Oregon and Washington supply authenticated raw material to premium extractors serving West Coast wellness centers.
Germany
EFSA novel food assessment backlogs are compressing first-mover advantages for compliant entrants in functional beverage channels. REACH substance registration requirements for fungal extracts favor established suppliers with dedicated regulatory affairs functions. Berlin and Hamburg host contract laboratory networks supporting shared toxicology data packages for small-batch Nordic producers.
China
SAMR and NMPA export frameworks are imposing additional documentation hurdles for finished goods entering domestic wellness markets. Traditional medicine heritage consumption sustains demand for whole chunk decoction formats in northern provinces. Heilongjiang and Jilin provinces maintain wild-harvesting operations supplying both domestic TCM practitioners and export-oriented extractors.
South Korea
MFDS health functional food registration pathways remain underutilized by Western chaga brands despite clear regulatory guidance. Urban professional demand for adaptogenic convenience formats is displacing traditional pharmacy purchasing. Seoul metropolitan area distribution networks are integrating subscription-based replenishment models for premium extract powders.
Canada
Health Canada Natural and Non-prescription Health Products Directorate licensing timelines shape product launch sequencing for North American brands. Functional beverage manufacturers in British Columbia and Ontario are adopting ultrasonic-assisted extraction to achieve competitive polysaccharide concentration ratios. Vancouver and Toronto wellness retail clusters reward origin storytelling and wild-harvest authentication badges.
Global Chaga Mushroom-Based Products Market Vendor Landscape
Player mix skews toward vertically integrated wild-harvest specialists and R&D-intensive dual-extraction processors. Market structure concentrates margin capture among Siberian corridor controllers and clinical-positioning brands with practitioner channel loyalty. Two strategic archetypes dominate: geography-anchored raw material gatekeepers and protocol-standardizing formulation scientists. Competitive moves center on certification-heavy procurement relationships and extraction method patent licensing.
Within the wild-harvest specialist tier, Sayan Health and Baikal Herbs Ltd. exemplify geography-anchored raw material control through Siberian sourcing network ownership. Om Mushroom Superfood occupies a position representing R&D-intensive dual-extraction standardization, while Fungi Perfecti LLC anchors the practitioner education archetype through mycologist-led platform development. These three entities collectively illustrate the competitive fault lines separating raw material access, clinical credibility, and direct-to-consumer scale.
| Leading Market Players |
|---|
| Sayan Health |
| Om Mushroom Superfood |
| Fungi Perfecti LLC |
| Host Defense |
| Four Sigmatic |
| Annanda Chaga Mushrooms |
| Aloha Medicinals |
| Real Mushrooms |
| Baikal Herbs Ltd. |
| Others |
Supply Flow & Price Mechanics
Ultrasonic-assisted extraction adoption is displacing conventional hot-water methods and simultaneously redrawing procurement geography toward Canadian and United States processors while compressing margin premiums previously captured by Siberian-sourced dual-extraction specialists.
Pricing Analysis
Certification level creates the primary spread between USDA Organic wild-harvested extracts and conventional cultivated alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects extraction completeness, beta-glucan standardization, and biomarker verification depth. Cost compression in mid-tier concentrates is intensifying because ultrasonic technology democratizes polysaccharide concentration ratios. Functional beverage manufacturers exhibit highest price sensitivity; integrative medicine clinics show lowest sensitivity due to protocol-driven reimbursement positioning.
Supply Chain Analysis
Russia and Canada anchor authenticated wild-harvesting corridors for Inonotus obliquus, while China and South Korea sustain cultivated alternative supply. Birch bark substrate quality, extraction solvent purity, and freeze-drying infrastructure capacity constitute critical input dependencies. Single-source vulnerability concentrates in Irkutsk region permitting volatility under Russian federal land-use policy shifts. Distribution runs through direct-to-consumer subscription platforms and practitioner dispensing networks, bypassing conventional pharmacy retail markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual-extraction patent thickets and EFSA novel food automation are accelerating market access disruption, compressing launch timelines for compliant entrants while raising barriers for artisan producers lacking regulatory affairs infrastructure.
For Market Incumbents: Shield premium positioning by deepening captive Siberian sourcing relationships and accelerating USDA Organic certification coverage across cultivated operations. Ultrasonic-assisted extraction entrants threaten mid-tier margin pools; respond with biomarker-verified sourcing documentation that artisan competitors cannot replicate without mycologist talent investment. For New Entrants and Emerging Players: MFDS health functional food registration fast-tracks in South Korea offer underpenetrated white space for Western extractors seeking Asia-Pacific footholds. Target Seoul metropolitan subscription channels with adaptogenic convenience formats displacing traditional pharmacy purchasing. Lead with clinical batch documentation enabling wellness center protocol integration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dual-extraction processors holding EFSA-compliant dossier libraries and practitioner channel contracts. Five-to-ten year viability hinges on extraction method patent licensing revenue streams and geographic indication movements reshaping raw material access. Signal to monitor: ECHA REACH substance registration cost escalation favoring consolidated regulatory affairs functions over small-batch Nordic partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Automation | Compresses eighteen-to-twenty-four month assessment timelines for European functional beverage entrants. |
| Siberian Sourcing Network Consolidation | Captures authenticated Irkutsk and Krasnoyarsk birch forest permits ahead of federal land-use policy volatility. |
| Ultrasonic Extraction Technology Licensing | Democratizes polysaccharide concentration ratios for mid-tier Canadian and United States processors. |
| Practitioner Education Platform Expansion | Builds channel loyalty through mycologist-led training materials for integrative medicine clinics. |
| Subscription Infrastructure Buildout | Captures quarterly replenishment cycles among Germany and Australia urban professionals aged thirty-five to fifty. |
Methodological Framework
Desk research of customs trade records, EFSA novel food submission databases, and FDA cGMP inspection precedents preceded structured interviews with extraction technology R&D directors, integrative medicine clinic procurement managers, wild-harvesting cooperative coordinators, and regulatory affairs specialists at functional beverage manufacturers. Bottom-up volume estimates from product-format shipment data were triangulated against top-down market sizing from ingredient trade flows.
Variance decomposition across product type, extraction method, end-user segment, and geographic regulatory cluster shaped analytical framework construction over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EFSA assessment timeline distributions, Siberian harvesting permit issuance patterns, and ultrasonic extraction equipment deployment trajectories.
Decision-makers should treat outputs as directional under sustained fourteen percent CAGR assumptions and stable boreal forest access; material deviation in birch bark substrate availability or EFSA backlog clearance would warrant model refresh. Recalibration cycles align with material shifts in extraction technology patent landscapes and geographic indication recognition movements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Tzatziki and Labneh Ferment Bases Market
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Plant Based Protein Market
Plant Based Food
Vegan Dips Market
Plant Based Food
Smart Plant Based Food Packaging Market
Plant Based Food
South America Meat Substitute Market
Plant Based Food
Plant-Based Bacon Market
Plant Based Food
Plant-Based Sausages Market
Plant Based Food
Vegan Diet Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Asia-Pacific Rice Protein Market
Plant Based Food
Plant-Based Protein Food Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
Vegan Dessert Market
Plant Based Food
Soy- Based Food Market
Plant Based Food
Vegan Pastry Market