
 Plant-Based Frozen Dessert Market | 2026-2036
Plant-Based Frozen Dessert Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Frozen Dessert Market Insights
Asset-light contract manufacturing is narrowing the capital barrier for new entrants in frozen dessert production. Oatly Group AB leverages its dedicated plant network to control oat-base quality from milling to freezing. Unilever PLC sustains broad retail distribution across multiple continents through its established logistics infrastructure. Danone S.A. specializes in almond and coconut milk formulations that anchor its premium positioning in European supermarkets.
Plant-based frozen dessert denotes a frozen, scoopable confection manufactured from non-dairy milk bases—typically coconut, almond, soy, or cashew—with fat content ranging from 8% to 14% and overrun between 70% and 120% to achieve creamy texture without lactoproteins. The product serves consumers with dairy allergies, lactose intolerance, or ethical dietary preferences across retail and foodservice channels. Non-dairy ice cream occupies the dominant volume position within product type segmentation, while sorbet captures margin pools through simpler ingredient lists and longer ambient shelf stability of base concentrates. Coconut milk formulations lead ingredient type demand due to superior fat structure and mouthfeel replication, though cashew milk variants command price premiums in specialty retail channels.
FDA allergen disclosure requirements under FALCPA shape coconut and nut-based labeling protocols, while EFSA novel food assessments govern oat protein isolate approvals in European formulations. USDA Organic certification and EU Organic Regulation create dual compliance tracks for brands targeting transatlantic distribution. Stakeholders must monitor evolving plant protein extraction technologies and shifting clean-label enforcement thresholds to anticipate reformulation cycles and regional market access shifts.
Market Dynamics
EFSA allergen labeling rules and EU Green Deal agricultural targets are compressing formulation flexibility while simultaneously redirecting capital toward compliant oat and pea protein extraction infrastructure.
Growth Catalysts
- Oat protein isolate approvals:EFSA novel food assessments in Europe are unlocking oat-base expansion beyond traditional soy and almond formulations. Foodservice operators in Germany and France are accelerating menu integration.
- Clean-label enforcement thresholds:USDA Organic certification and EU Organic Regulation dual compliance tracks are creating premium shelf positioning that commands price separation from conventional frozen desserts.
- Foodservice channel anchoring:Specialty grocers and restaurant chains in the United States are building dedicated freezer sections and dessert menus that normalize plant-based options for mainstream consumers.
Market Restraints
- Coconut milk supply concentration:Southeast Asian sourcing clusters expose processors to monsoon volatility and shipping lane congestion that disrupts fat structure consistency.
- Technical limitation in overrun control:Achieving 70-120% air incorporation without lactoproteins requires specialized freezing tunnel equipment that smaller contract manufacturers cannot access.
- FDA FALCPA disclosure friction:Tree nut and coconut allergen labeling triggers mandatory precautionary statements that deter trial among non-allergic consumers.
Strategic Opportunities
- Cashew milk premium tier:Specialty retail channels in the United Kingdom and Netherlands are absorbing price premiums for ultra-creamy formulations that replicate dairy mouthfeel.
- EU Green Deal agricultural incentives:Protein crop cultivation subsidies are reducing domestic oat and pea input costs for European processors.
- Sorbet concentrate stability:Ambient distribution of base concentrates unlocks foodservice preparation flexibility that ice cream bases cannot match.
Industry Challenges
- Plant protein extraction talent scarcity:Food science programs produce few specialists in enzymatic fractionation of oat and pea isolates with functional gelling properties.
- Dual certification capex burden:Simultaneous USDA Organic and EU Organic Regulation compliance requires parallel production lines and documentation systems.
- Reformulation cycle compression:Clean-label threshold tightening forces ingredient list revisions before amortization of previous formulation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Frozen Dessert Market |
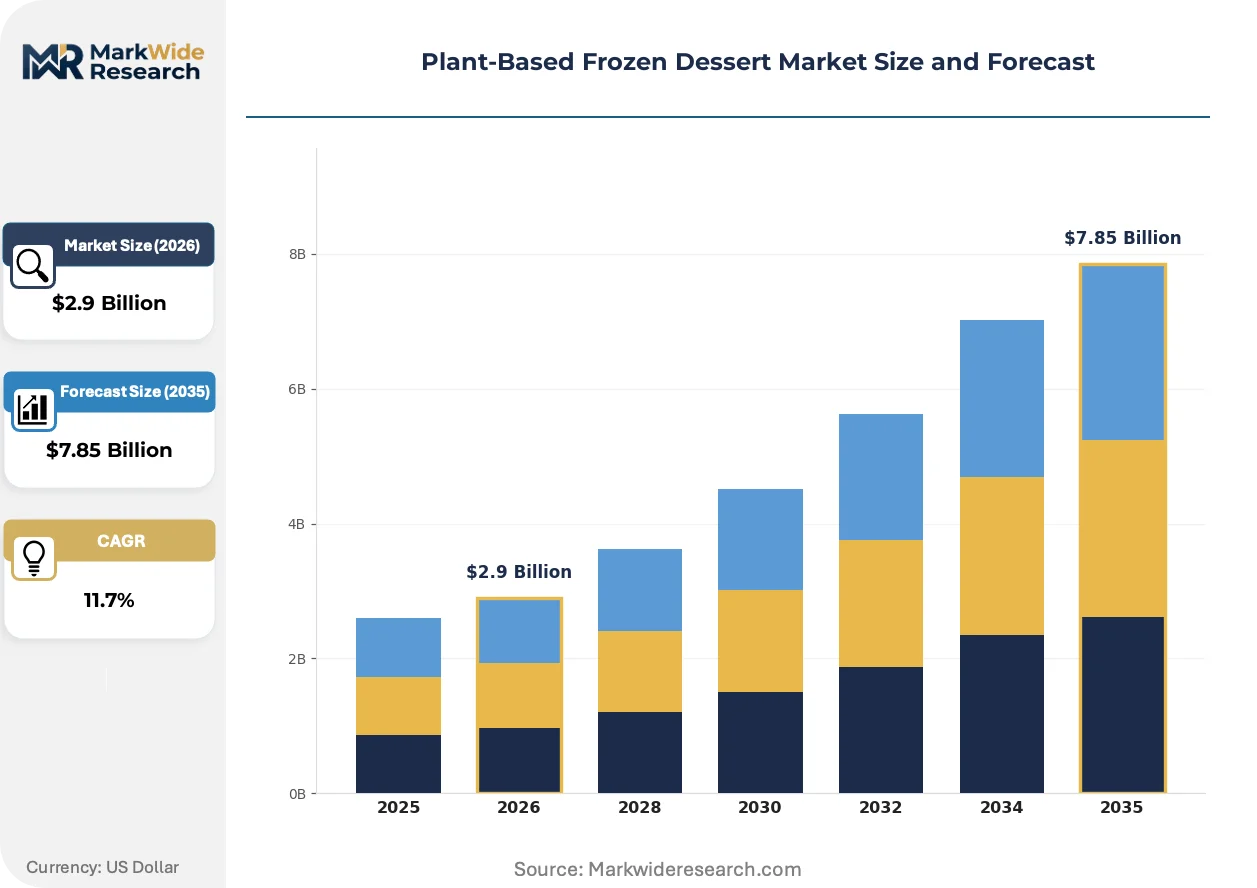
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: An ice cream, Sorbet, Frozen yogurt, Gelato End User: Retail Consumers, Foodservice Outlets, Cafés, Restaurants Ingredient Type: Coconut milk, Almond milk, Soy milk, Cashew milk Flavor Profile: Chocolate, Vanilla, Strawberry, Mango |
| Companies Covered | Oatly Group AB, Unilever PLC, Danone S.A., Nestlé S.A., General Mills Inc., So Delicious Dairy Free, NadaMoo!, Eclipse Foods, Tofutti Brands Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Frozen Dessert Market Trends and Innovations
Precision fermentation-derived dairy proteins are collapsing the functional gap between plant and animal frozen desserts while regulatory clarity lags technical capability.
Enzymatic lipid restructuring technology is collapsing the emulsion stability limitations that previously forced heavy reliance on coconut fat. Mid-size processors in the Netherlands and California are adopting continuous-phase inversion systems that reduce coconut milk dependency by half. This compression is enabling regional sourcing strategies that shorten supply chains.
EU Green Deal agricultural targets are mandating measurable carbon intensity reductions across ingredient supply chains. European processors must document farm-to-freezer emissions for oat and almond bases or face exclusion from public procurement channels. German retailers are demanding third-verified lifecycle assessments as listing prerequisites.
Direct-to-restaurant distribution is displacing traditional distributor intermediaries for sorbet concentrates and base mixes. Frozen dessert manufacturers in the United States are building captive delivery fleets that bypass broadline foodservice distributors. This channel compression is most visible in California and New York metro areas where chef-driven concepts demand formulation customization.
Plant-Based Frozen Dessert Market Segmentation
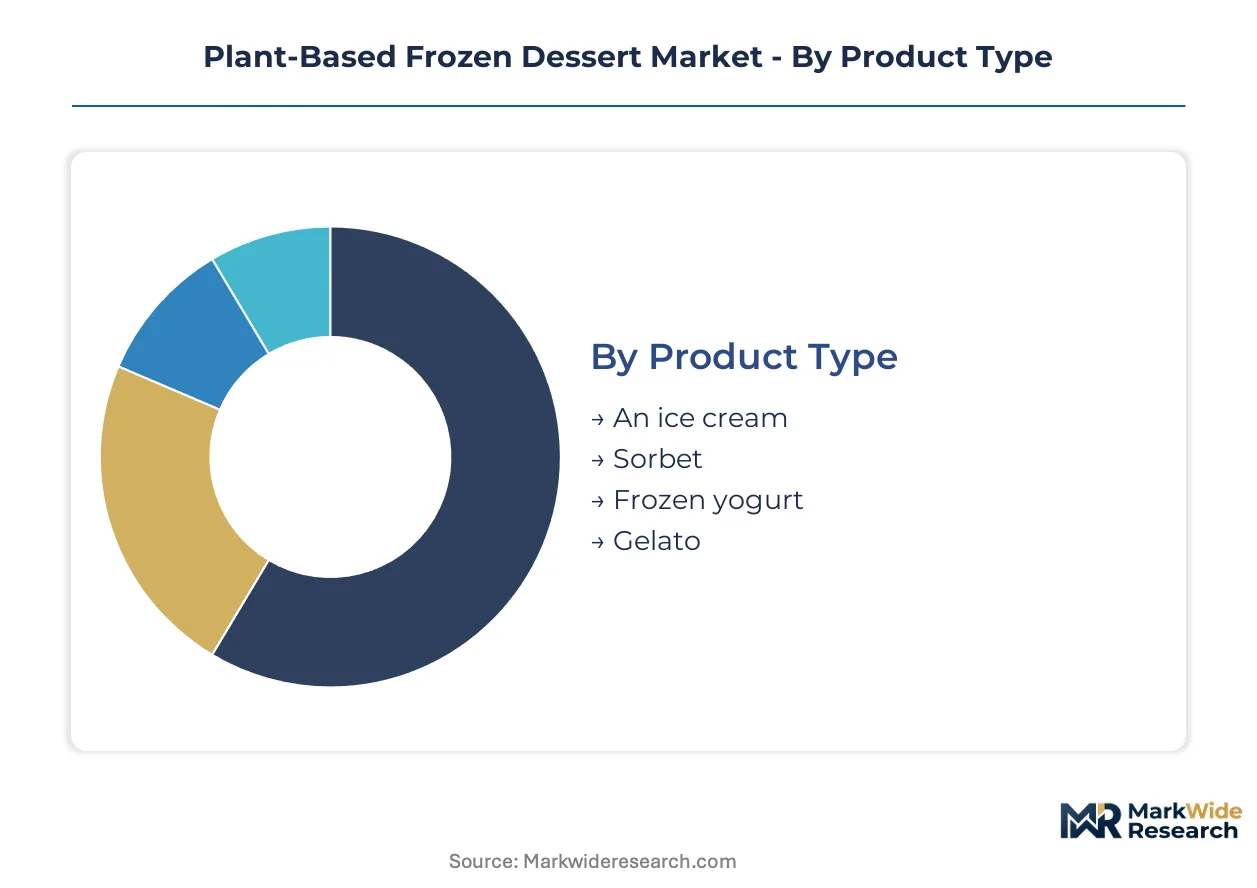
Plant-based frozen dessert manufacturers must align production configurations with distinct performance requirements across product formats and channel specifications. Ingredient viscosity, freezing tunnel calibration, and distribution temperature protocols vary sharply between retail pints and foodservice bulk formats.
Product Type:
After-sales service intensity diverges across frozen dessert formats, with ice cream requiring sustained technical support for overrun consistency and gelato demanding specialized display case calibration partnerships.
- An ice cream:Formulations achieve 8-14% fat content and 70-120% overrun through continuous freezing tunnels. Retail consumers in United States supermarket channels drive volume concentration, though equipment maintenance contracts for homogenization systems constrain margin recovery for smaller processors.
- Sorbet:Water-based formulations eliminate fat structuring challenges while delivering longer ambient shelf stability for base concentrates. Foodservice outlets in France and Italy absorb sorbet concentrates for on-premise preparation, bypassing frozen distribution complexity.
- Frozen yogurt:Live culture retention requires precise fermentation timing before blast freezing. Cultured base suppliers in California cluster technical service teams near processor facilities.
- Gelato:Lower overrun targets (20-35%) and warmer serving temperatures demand dedicated display equipment partnerships. Italian equipment manufacturers bundle formulation consulting with cabinet leases.
An ice cream holds the largest share; momentum sits with sorbet as foodservice operators seek preparation flexibility.
End User:
Cost tier stratification separates retail consumers seeking portion-controlled formats from foodservice buyers optimizing per-scoop economics through bulk procurement.
- Retail Consumers:Supermarket and specialty grocer channels dominate, with coconut milk formulations commanding shelf placement premiums. Clean-label certification requirements from USDA Organic and EU Organic Regulation create dual compliance burdens for brands targeting transatlantic distribution.
- Foodservice Outlets:Broadline distributors and captive delivery fleets compete for dessert menu placement, with formulation customization driving contract value. California and New York metro areas show concentrated direct-to-restaurant distribution displacement of traditional intermediaries.
- Cafés:Smaller volume accounts prioritize ambient-stable concentrates over frozen finished goods. Oat protein isolate formulations are gaining menu integration in Germany and Netherlands locations.
- Restaurants:Chef-driven concepts demand batch-specific flavor development and co-branded packaging. Technical collaboration intensity exceeds standard foodservice relationships.
Retail consumers anchor volume concentration; restaurants are expanding most quickly as premium positioning justifies formulation partnership investments.
Ingredient Type:
Application suitability determines ingredient selection, with coconut milk's fat structure suiting high-overrun ice cream and cashew milk's protein profile enabling premium mouthfeel replication.
- Coconut milk:Southeast Asian sourcing clusters supply lauric fat fractions that stabilize emulsions without lactoproteins. Monsoon volatility and shipping lane congestion expose processors to supply disruption risks that compress formulation flexibility.
- Almond milk:California cultivation concentration supports domestic United States supply chains, though water intensity constraints face sustainability scrutiny from German retailers demanding lifecycle assessments.
- Soy milk:Established protein isolation infrastructure yields cost-competitive bases, though allergen labeling friction under FDA FALCPA triggers precautionary statements that deter trial among non-allergic consumers.
- Cashew milk:Ultra-creamy formulations command price premiums in United Kingdom and Netherlands specialty retail channels. Protein content and fat structure most closely approximate dairy mouthfeel.
Coconut milk dominates formulation share; cashew milk gains share fastest as premium tier positioning justifies input cost premiums.
Flavor Profile:
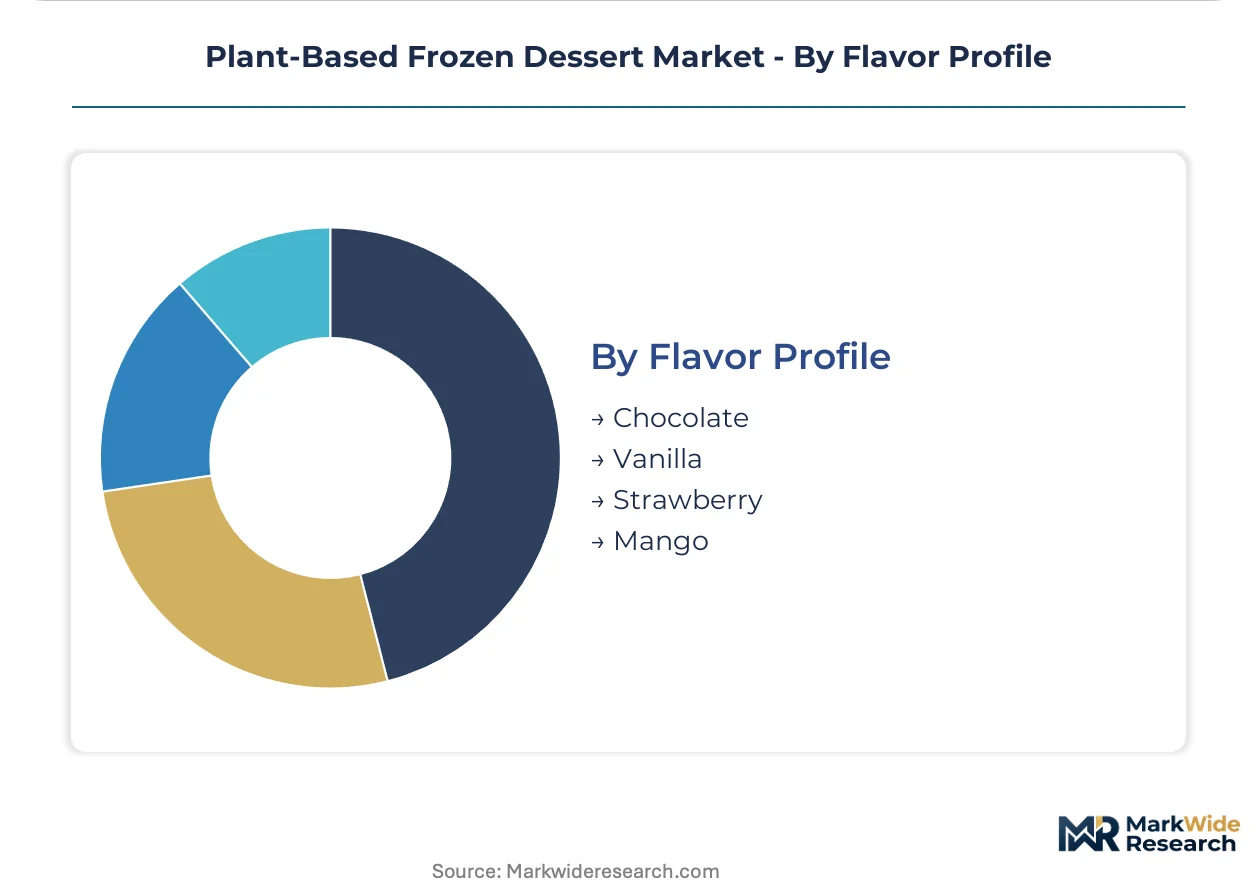
Volume concentration in chocolate and vanilla creates procurement scale advantages for cocoa and vanilla bean suppliers, while fruit flavors face seasonality constraints.
- Chocolate:Cocoa butter and cocoa powder formulations require precise fat bloom control during thermal cycling. West African sourcing concentration shapes procurement risk profiles.
- Vanilla:Madagascar and Tahitian vanilla extract grades stratify pricing tiers, with bourbon vanilla dominating mass-market applications.
- Strawberry:Freeze-dried and pureed formats compete on color stability and seed texture, with Pacific Northwest cultivation supplying premium processors.
- Mango:Alphonso cultivar demand from India concentrates in ethnic retail channels and South Asian restaurant dessert menus.
Chocolate holds the largest share; mango climbs the fastest as ethnic retail channel expansion broadens distribution access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal agricultural targets and protein crop cultivation subsidies are redirecting capital toward domestic oat and pea processing infrastructure across multiple jurisdictions. FDA allergen disclosure requirements under FALCPA and EFSA novel food assessments create divergent compliance tracks that shape regional formulation strategies. Demand clusters concentrate where foodservice channel expansion and specialty retail penetration intersect.
United States
Foodservice operators and specialty grocers anchor category expansion through dedicated freezer sections and dessert menu integration. FDA FALCPA disclosure requirements trigger precautionary allergen labeling that complicates coconut and nut-based formulation marketing. California processors cluster technical service teams near cultured base production facilities to support live culture retention protocols.
Germany
Retailers demand third-verified lifecycle assessments as listing prerequisites, compressing margin structures for non-compliant suppliers. EFSA novel food assessments unlock oat-base expansion beyond traditional soy and almond formulations. Foodservice operators in Berlin and Hamburg accelerate oat protein isolate menu integration.
France
Foodservice outlets absorb sorbet concentrates for on-premise preparation, bypassing frozen distribution complexity. EU Organic Regulation compliance creates premium shelf positioning that commands price separation from conventional frozen desserts. Paris-based chef-driven concepts demand batch-specific flavor development and co-branded packaging partnerships.
United Kingdom
Specialty retail channels absorb price premiums for ultra-creamy cashew milk formulations that replicate dairy mouthfeel. EFSA allergen labeling rules compress formulation flexibility while redirecting capital toward compliant extraction infrastructure. London metro processors build captive delivery fleets that bypass broadline foodservice distributors.
Netherlands
Mid-size processors adopt continuous-phase inversion systems that reduce coconut milk dependency by half. EU Green Deal agricultural targets mandate measurable carbon intensity reductions across ingredient supply chains. Rotterdam and Amsterdam clusters specialize in enzymatic lipid restructuring technology that collapses emulsion stability limitations.
Plant-Based Frozen Dessert Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: diversified multinationals with established logistics infrastructure, dedicated plant-based specialists with captive supply networks, and contract manufacturers serving private-label programs. Dominant competitive moves include backward integration into oat milling and protein isolation capacity, plus direct-to-restaurant distribution fleet construction that displaces traditional intermediaries.
Within the dedicated specialist tier, Oatly Group AB exemplifies vertical production control from milling through freezing. Among diversified multinationals, Unilever PLC and Danone S.A. occupy positions shaped by broad retail distribution scale and premium formulation specialization respectively. These three entities represent contrasting strategic postures: captive supply chain control, continental logistics leverage, and ingredient-specific premium positioning.
| Leading Market Players |
|---|
| Oatly Group AB |
| Unilever PLC |
| Danone S.A. |
| Nestlé S.A. |
| General Mills Inc. |
| So Delicious Dairy Free |
| NadaMoo! |
| Eclipse Foods |
| Tofutti Brands Inc. |
| Others |
Pricing and Supply Chain Analysis
Southeast Asian shipping lanes connecting coconut milk processors to European and North American markets carry freight cost volatility that compresses margin structures for formulations dependent on lauric fat sourcing. This logistics corridor's rate fluctuations simultaneously concentrate pricing power among integrated processors with captive milling capacity and force price differentiation across certification tiers for smaller contract manufacturers lacking upstream control.
Pricing Analysis
Certification level creates the primary spread across the market, with USDA Organic and EU Organic Regulation dual compliance commanding shelf price premiums over conventional formulations. Three-tier pricing structure across premium, standard, and economy levels reflects ingredient base differentiation, with cashew milk variants occupying the premium tier and soy milk formulations anchoring value positioning. Cost compression in the standard tier is intensifying because German retailers now demand third-verified lifecycle assessments as listing prerequisites. Retail consumers in supermarket channels show highest price sensitivity, while chef-driven restaurant concepts absorb formulation premiums for batch-specific customization.
Supply Chain Analysis
EU Green Deal agricultural restrictions on carbon intensity documentation limit flows from non-compliant Southeast Asian coconut processors into European public procurement channels. Raw material sourcing draws from Indonesia and the Philippines for coconut milk, California for almond cultivation, and domestic European acreage for oat protein expansion. Supply chain risk centers on monsoon volatility disrupting Southeast Asian fat structure consistency and shipping lane congestion extending lead times. Distribution runs through broadline foodservice intermediaries in most markets, though California and New York metro areas show concentrated direct-to-restaurant fleet displacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated foodservice operators and specialty retail chains capable of demanding formulation customization, fragmenting volume across smaller processor relationships and compressing margin recovery for undifferentiated suppliers.
For Market Incumbents: Entrench oat protein isolate capacity through backward integration into milling infrastructure before EFSA novel food assessments saturate European formulation pipelines. Defend shelf positioning by accelerating dual certification compliance ahead of clean-label threshold tightening that will obsolete single-certified competitors. For New Entrants and Emerging Players: Build out sorbet concentrate distribution through direct-to-restaurant channels in France and Italy, where ambient stability unlocks foodservice preparation flexibility that incumbent ice cream bases cannot match. Target café segments in Germany and Netherlands with oat protein isolate formulations gaining menu integration momentum. For Investors and Strategic Acquirers: EU Green Deal protein crop cultivation subsidies reshape the acquisition landscape toward European oat and pea processing infrastructure with documented carbon intensity reductions. Long-term viability favors mid-size processors with enzymatic lipid restructuring capabilities that reduce coconut milk dependency. Watch EFSA novel food assessment timelines as inflection indicators for oat-base expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oat Milling | Captive supply of protein isolate secures formulation consistency ahead of EFSA approval waves. |
| Direct-to-Restaurant Fleet Construction | Bypassing broadline distributors in California and New York metro areas captures chef-driven customization premiums. |
| Dual Certification Investment | USDA Organic and EU Organic Regulation compliance opens transatlantic shelf placement commanding price separation. |
| Enzymatic Lipid Restructuring Adoption | Continuous-phase inversion systems reduce Southeast Asian coconut milk dependency by half. |
| Sorbet Concentrate Ambient Distribution | Foodservice preparation flexibility in France and Italy bypasses frozen distribution complexity and cold chain costs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with frozen dessert brand managers, contract manufacturing procurement leads, foodservice menu development directors, and specialty grocer category buyers. Secondary validation drew from FDA FALCPA disclosure filings, EFSA novel food assessment registers, USDA Organic certification databases, and EU Green Deal agricultural target documentation. Bottom-up volume modeling from ingredient throughput data and top-down value reconciliation from retail audit channels were triangulated against processor capacity disclosures.
Calibration across the analysis window employed segment-specific growth coefficients derived from channel penetration rates and formulation substitution elasticities. Product type, ingredient base, end-use channel, and regional regulatory cluster dimensions were modeled with cross-elasticity matrices capturing coconut milk to oat protein isolate switching behavior. CAGRs were computed from year-over-year volume progression adjusted for shelf space allocation shifts and foodservice menu integration velocity.
Stress conditions across Southeast Asian monsoon patterns, EU Green Deal subsidy allocation, and EFSA novel food approval timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about clean-label enforcement threshold stability and oat protein isolate functional property consistency. Material shifts in EFSA regulatory velocity or EU agricultural subsidy redirection would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Europe Plant-Based Food Market
Plant Based Food
Plant Based Meal Kit Market
Plant Based Food
Middle East and Africa Meat Substitute Market
Plant Based Food
Soy- Based Food Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
Vegan Steak Market
Plant Based Food
Plant Based Ice Cream Market
Plant Based Food
Vegan Meals Market
Plant Based Food
Vegan Dessert Market
Plant Based Food
India Plant Based Meat Alternatives Market
Plant Based Food
Asia-Pacific Pea Protein Market
Plant Based Food
Pea Protein Market
Plant Based Food
Asia-Pacific Plant-Based Seafood Market
Plant Based Food
Pea Protein Isolate Market
Plant Based Food
Plant-Based Meatballs Market
Plant Based Food
Tempeh Market