
 Global Arrhythmia Monitoring Devices Market | 2026-2036
Global Arrhythmia Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Arrhythmia Monitoring Devices Market Foresight
Hospital procurement channels for arrhythmia monitoring hardware is tilting toward long-term service contracts that bundle devices with cloud analytics. Medtronic leverages its integrated cardiac care ecosystem to lock in multi-year hospital agreements across North American electrophysiology labs. Abbott Laboratories anchors its position through proprietary wireless transmission protocols that reduce clinic workflow friction. Biotronik competes on manufacturing scale in implantable loop recorders, sustaining cost advantages in European cardiac clinics.
Arrhythmia monitoring devices detect, record, and transmit cardiac electrical activity through surface electrodes, implantable sensors, or wearable patches, typically sampling at 128–1024 Hz with noise filtering below 0.05 Hz for diagnostic-grade rhythm classification. These systems serve the commercial purpose of identifying atrial fibrillation, ventricular tachycardia, and conduction disorders before stroke or sudden cardiac arrest events occur. Implantable loop recorders command premium margins due to extended multi-year monitoring and surgical placement workflows, while mobile cardiac telemetry represents the fastest-growing segment as ambulatory care centers seek continuous monitoring without bed occupancy. Holter monitors retain volume leadership in postoperative monitoring but face margin compression from lower-cost Asian manufacturers.
FDA breakthrough device designation and EU MDR conformity assessments shape product development timelines and market access costs for manufacturers targeting the United States and European Union. Japan's PMDA enforces distinct clinical evidence requirements for wearable sensors that delay entry relative to Western regulators. China's NMPA accelerates review pathways for AI-assisted ECG classification, redirecting vendor regulatory investment toward dual-carbon-aligned manufacturing certifications. Stakeholders must monitor reimbursement code fragmentation between in-clinic and home-based monitoring as payers recalibrate coverage thresholds.
Market Dynamics
Hospital procurement for arrhythmia monitoring hardware is consolidating around multi-year service contracts that bundle hardware, cloud analytics, and algorithm updates into single vendor relationships, compressing standalone device margins while elevating recurring revenue streams for integrated platform providers.
Growth Catalysts
- Value-based care penalties:US hospital systems under CMS readmission reduction programs deploy remote cardiac monitoring to avoid financial penalties, accelerating device procurement cycles in acute care settings.
- AI-enhanced ECG classification:FDA breakthrough device pathways compress regulatory timelines for machine learning algorithms, enabling faster commercialization of automated arrhythmia detection tools.
- Implantable loop recorder durability:Extended battery life and subcutaneous placement techniques extend monitoring windows to three-plus years, creating recurring replacement demand in electrophysiology practices.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundries dominate fabrication of low-power microcontrollers essential for wearable patch devices, exposing vendors to geographic supply disruption.
- EU MDR conformity costs:Extended clinical evidence requirements and notified body bottlenecks delay product launches and inflate regulatory expenditure for European market entry.
- Holter monitor commoditization:Lower-cost Asian manufacturers compress margins on conventional ambulatory ECG systems, forcing established vendors to abandon volume leadership in basic monitoring hardware.
Strategic Opportunities
- Underpenetrated Indian cardiac centers:Tier-two and tier-three cities lack continuous arrhythmia monitoring infrastructure, creating first-mover advantage for vendors establishing local service networks under CDSCO device regulations.
- Home-based mobile cardiac telemetry:Reimbursement code expansion for remote physiologic monitoring enables ambulatory care centers to capture continuous data without bed occupancy costs.
- Dual carbon manufacturing alignment:China's NMPA accelerates review pathways for devices produced under verified low-carbon certification schemes, redirecting capital toward sustainable production assets.
Industry Challenges
- Electrophysiologist training pipelines:Specialized expertise required for implantable device placement and data interpretation constrains procedure volume expansion in saturated US and German markets.
- Legacy EHR integration complexity:Proprietary data formats from competing monitoring platforms create interoperability friction, forcing hospitals to maintain redundant IT infrastructure or accept vendor lock-in.
- Algorithm bias validation:FDA and PMDA scrutiny of AI training data representativeness demands expanded clinical trials across diverse patient populations, extending development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Arrhythmia Monitoring Devices Market |
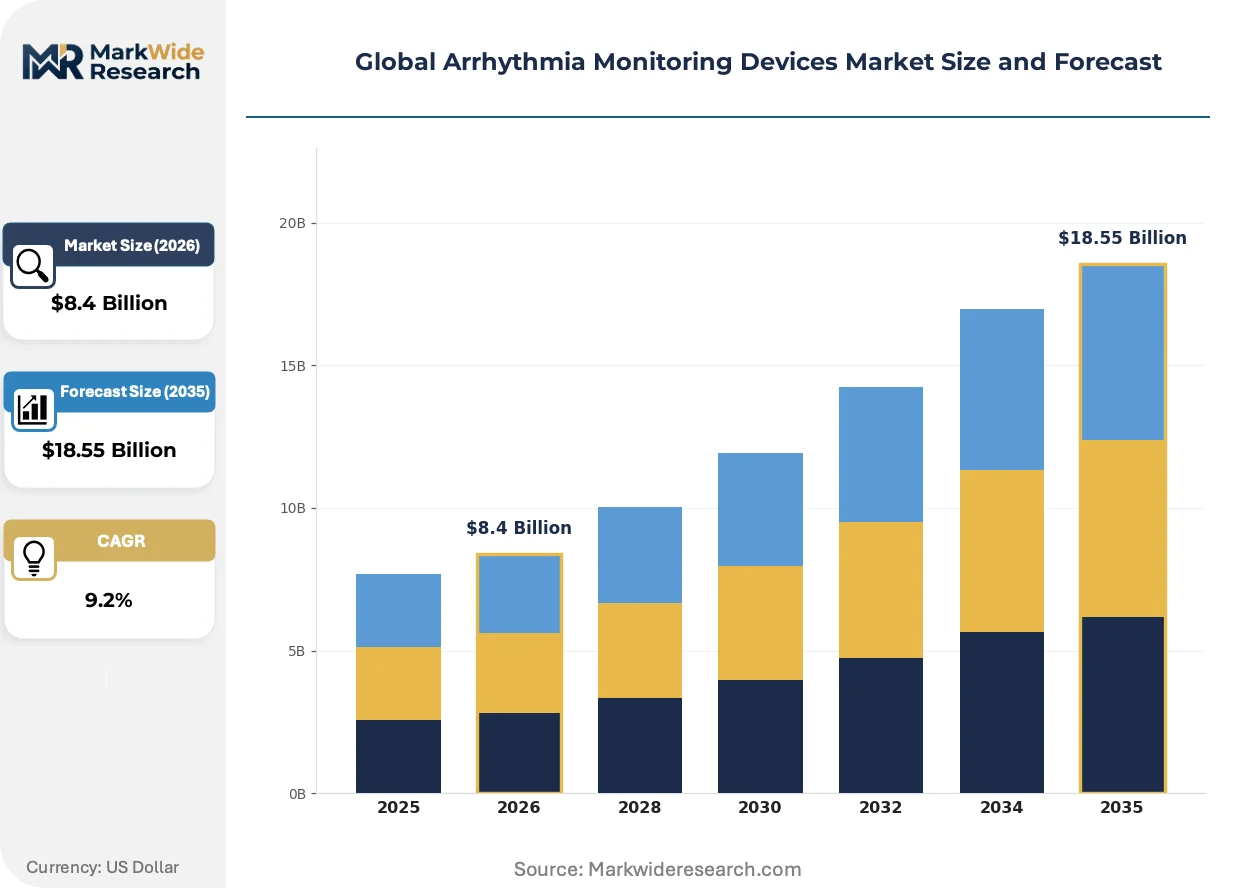
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Holter Monitors, Event Monitors, Implantable Loop Recorders, Mobile Cardiac Telemetry Technology: Wearable Sensors, Wireless Transmission, Mobile Applications, Cloud Data Storage Application: Postoperative Monitoring, Syncope Diagnosis, Stroke Prevention, Palpitation Detection End User: Cardiac Clinics, Electrophysiology Labs, Ambulatory Care Centers, Home Healthcare Providers |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific, GE Healthcare, Koninklijke Philips N.V., iRhythm Technologies, Biotronik, AliveCor, FUKUDA DENSHI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Arrhythmia Monitoring Devices Market Shifts & Advancements
Diagnostic-grade arrhythmia detection is migrating from clinic-bound hardware toward ambulatory and implantable sensor ecosystems, compressing the distinction between acute and continuous monitoring while elevating algorithm performance as the primary competitive differentiator.
Machine learning inference is migrating from cloud-based processing toward edge computing architectures embedded directly in wearable patches and implantable devices. Cardiology practices in Germany and Japan are piloting these systems to enable real-time alert generation without continuous cellular connectivity. This migration from centralized to distributed processing is compressing latency for critical arrhythmia notifications while reducing recurring cloud infrastructure costs for high-volume monitoring programs.
EU MDR Article 10 post-market surveillance requirements now mandate systematic collection of real-world performance data for implantable cardiac monitors, compelling manufacturers to fund long-term patient registries. The industrial consequence is a structural cost burden that favors large platforms with existing data infrastructure over mid-tier competitors. Implantable loop recorder vendors are responding by embedding automated data transmission protocols that reduce manual follow-up burden and ensure compliance with periodic safety update reporting obligations.
Hospital purchasing committees are consolidating vendor relationships around platforms offering integrated device-algorithm-service bundles, displacing standalone hardware procurement. Ambulatory surgery centers and electrophysiology labs in the United States are driving this consolidation, favoring multi-year agreements that include predictive analytics and remote patient monitoring infrastructure. This behavioral shift is most visible in integrated delivery networks seeking to standardize cardiac care protocols across geographically dispersed facilities.
Global Arrhythmia Monitoring Devices Market Segmentation
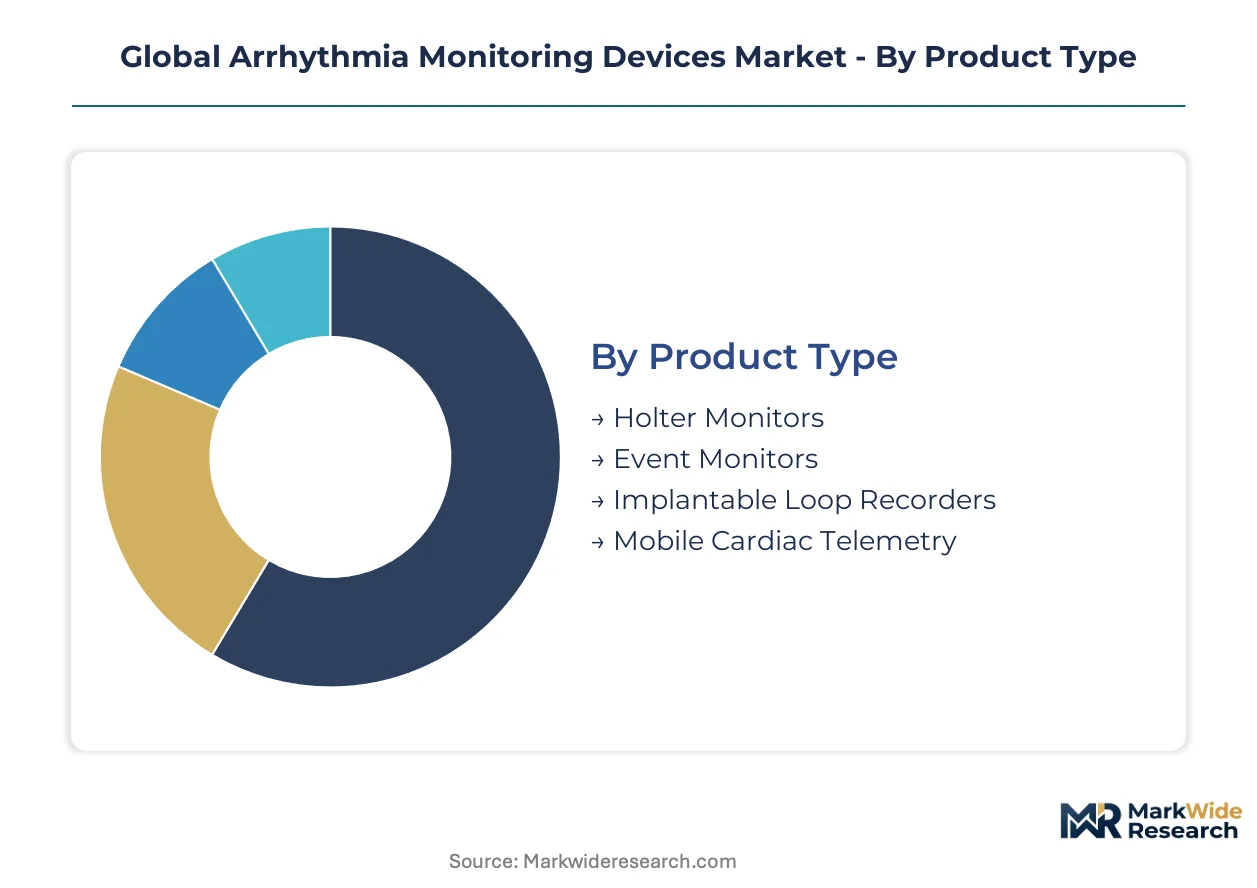
Arrhythmia monitoring devices fragment across hardware form factors, connectivity architectures, clinical use cases, and care delivery settings. Each dimension carries distinct margin profiles, regulatory pathways, and procurement dynamics that reshape competitive positioning across electrophysiology markets.
Product Type:
Cost tier determines reimbursement codes, battery replacement schedules, and service contract structures across ambulatory and implantable hardware categories.
- Holter Monitors:Ambulatory ECG systems with 24-48 hour recording windows using surface electrodes and solid-state storage. Demand concentrates in postoperative cardiac wards across United States hospitals facing CMS readmission penalties. Margin compression from Asian manufacturers forces established vendors toward premium service bundling.
- Implantable Loop Recorders:Subcutaneous devices with three-plus year battery life transmitting via proprietary wireless protocols. Electrophysiology labs in Germany and Japan command premium pricing for extended monitoring of cryptogenic stroke patients. Surgical placement workflows create recurring replacement demand cycles.
- Event Monitors:Patient-activated or auto-triggered external recorders capturing symptomatic episodes.
- Mobile Cardiac Telemetry:Real-time continuous monitoring patches with cellular transmission.
Implantable loop recorders command the established base. The steepest expansion runs through mobile cardiac telemetry.
Technology:
Application architecture choices reshape latency, connectivity dependency, and cloud infrastructure economics for high-volume monitoring programs.
- Wearable Sensors:Flexible electrode arrays and accelerometer-integrated patches sampling at diagnostic-grade frequencies. Ambulatory care centers in United States deploy these for home-based telemetry reimbursement expansion. Edge computing migration enables real-time alerts without continuous cellular dependency.
- Cloud Data Storage:HIPAA-compliant centralized repositories with algorithm update distribution and longitudinal rhythm databases. Hospital systems consolidating vendor relationships demand interoperability with existing EHR infrastructure. EU MDR Article 10 mandates systematic real-world performance data collection.
- Wireless Transmission:Proprietary or Bluetooth Low Energy protocols for device-to-hub communication.
- Mobile Applications:Patient-facing interfaces for symptom logging and alert reception.
Wearable sensors anchor current procurement volumes. Cloud data storage infrastructure is gaining share fastest among integrated delivery networks.
Application:
Clinical indication specificity drives device selection, monitoring duration requirements, and specialist referral patterns across cardiology practices.
- Stroke Prevention:Extended monitoring for atrial fibrillation detection in cryptogenic stroke patients. German cardiac centers prioritize implantable solutions given three-year monitoring windows. PMDA scrutiny of AI training data representativeness extends validation timelines for algorithm-enhanced detection.
- Syncope Diagnosis:Correlation of rhythm disturbances with transient loss of consciousness episodes. Electrophysiology labs in Japan pilot edge-computing wearables for real-time correlation without clinic-bound hardware. Diagnostic yield requirements shape device selection between external and implantable options.
- Postoperative Monitoring:Short-term surveillance following cardiac intervention or surgery.
- Palpitation Detection:Symptom-rhythm correlation for intermittent arrhythmia documentation.
Stroke prevention applications concentrate the premium tier. Syncope diagnosis is climbing the fastest as ambulatory monitoring displaces inpatient observation.
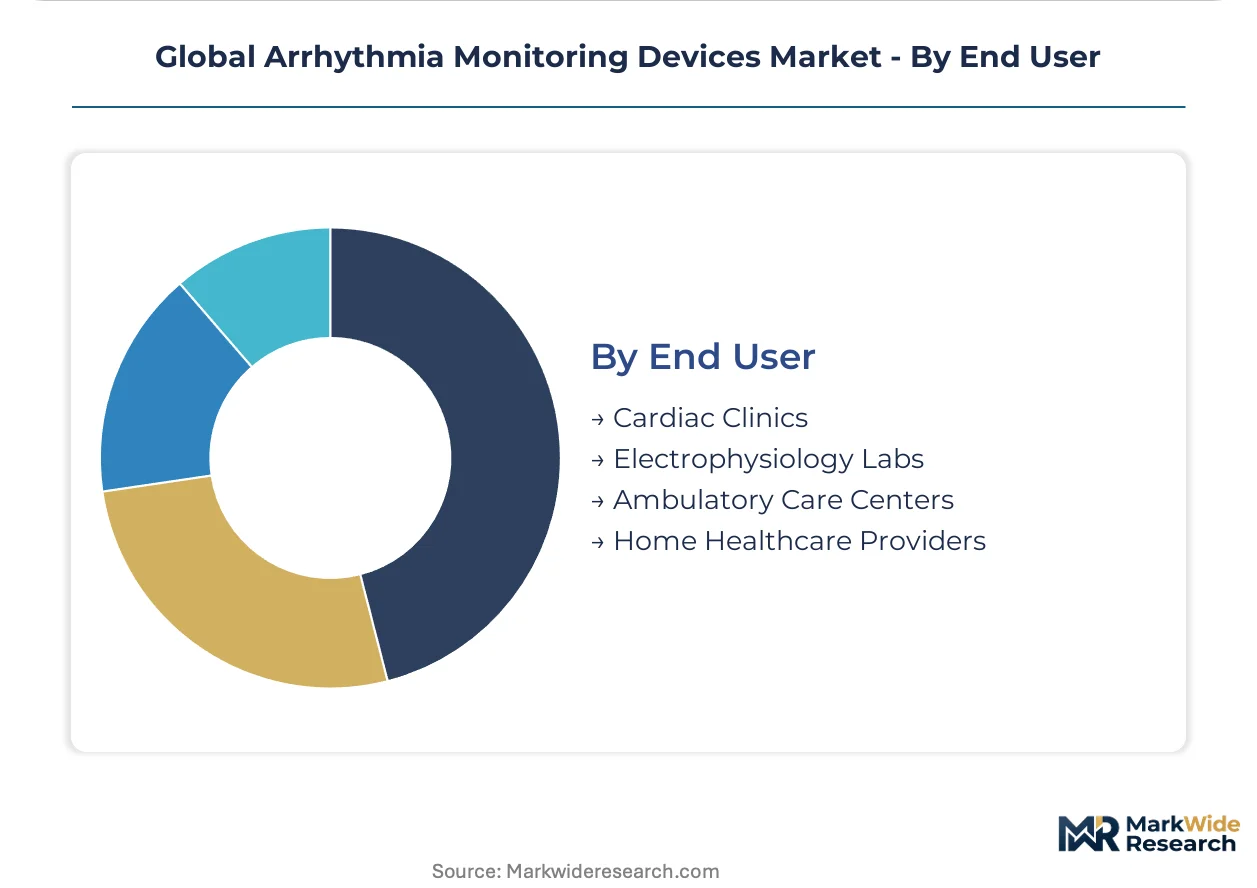
End User:
Customer type determines procurement authority, service contract structure, and integration complexity with existing cardiac care workflows.
- Electrophysiology Labs:Specialized procedural suites with implantable device placement capability and complex arrhythmia interpretation expertise. United States integrated delivery networks consolidate multi-year agreements around device-algorithm-service bundles. Training pipeline constraints limit procedure volume expansion in saturated markets.
- Ambulatory Care Centers:Outpatient facilities capturing continuous monitoring without bed occupancy costs. Reimbursement code expansion for remote physiologic monitoring enables volume growth in United States markets. Cloud analytics integration reduces manual follow-up burden.
- Cardiac Clinics:General cardiology practices with diagnostic interpretation and referral authority.
- Home Healthcare Providers:Remote patient monitoring services for post-discharge surveillance.
Electrophysiology labs retain the premium procurement tier. Ambulatory care centers are expanding most quickly under value-based care frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough pathways for AI-enhanced ECG algorithms anchor the United States as the dominant geography, while aging demographics and reimbursement clarity concentrate procurement across Germany, Japan, and select expansion markets.
United States
CMS readmission reduction programs and value-based care penalties accelerate hospital procurement of remote cardiac monitoring systems. FDA breakthrough device designations compress regulatory timelines for machine learning algorithms, enabling faster commercialization. Integrated delivery networks in Texas and the Northeast Corridor consolidate multi-year vendor agreements bundling devices with cloud analytics.
Germany
Electrophysiology labs in Bavaria and Baden-Württemberg command premium pricing for implantable loop recorders serving cryptogenic stroke patients. EU MDR Article 10 mandates systematic real-world performance data collection, elevating structural costs that favor large platforms. Berlin-Brandenburg hosts regulatory consulting clusters supporting MDR conformity assessments.
Japan
PMDA scrutiny of AI training data representativeness extends validation timelines for algorithm-enhanced detection systems. METI funding for aging-in-place technologies expands reimbursement coverage for home-based telemetry. Kansai region cardiac centers pilot edge-computing wearables enabling real-time alerts without continuous cellular dependency.
China
NMPA accelerates review pathways for AI-assisted ECG classification devices produced under verified low-carbon certification schemes. Dual carbon manufacturing alignment redirects vendor capital toward sustainable production assets. Yangtze River Delta medical device clusters scale wearable patch manufacturing for domestic and export markets.
India
Tier-two and tier-three cities lack continuous arrhythmia monitoring infrastructure, creating first-mover advantage for vendors establishing local service networks. CDSCO device regulations govern import and domestic manufacturing compliance. Maharashtra and Karnataka cardiac centers represent initial penetration targets for ambulatory monitoring expansion.
Global Arrhythmia Monitoring Devices Market Competitive Landscape
Integrated cardiac care platforms and specialized monitoring technology developers split the market into distinct competitive spheres. Hospital procurement consolidation around multi-year service contracts elevates recurring revenue importance over standalone hardware margins. Three archetypes dominate: diversified medical technology conglomerates with electrophysiology ecosystems, pure-play ambulatory monitoring specialists, and regional manufacturing-scale competitors. Dominant competitive moves include backward integration into proprietary wireless transmission protocols and strategic partnerships securing cloud analytics infrastructure.
Within the integrated platform tier, Medtronic and Abbott Laboratories exemplify archetypes leveraging device-algorithm-service bundles to lock hospital agreements. Biotronik occupies a position representing European manufacturing-scale specialization in implantable hardware. These anchors demonstrate how regulatory navigation capability and data infrastructure scale separate sustainable competitors from margin-compressed hardware vendors.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific |
| GE Healthcare |
| Koninklijke Philips N.V. |
| iRhythm Technologies |
| Biotronik |
| AliveCor |
| FUKUDA DENSHI |
| Others |
Supply & Pricing Matrix
Overcapacity in Taiwanese microcontroller foundries is compressing component costs for wearable patch manufacturers while simultaneously eroding pricing power for legacy Holter monitor vendors facing Asian competition.
Pricing Analysis
Geographic price spreads between German electrophysiology labs and Indian cardiac centers exceed threefold for equivalent implantable loop recorder hardware. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated AI-enhanced systems from basic ambulatory monitors and unbranded Asian imports. Cost compression in conventional Holter monitors is intensifying because lower-cost manufacturers from China and South Korea flood export markets with functionally equivalent hardware. Ambulatory care centers in the United States exhibit the lowest price sensitivity due to reimbursement code expansion, while tier-two Indian hospitals remain highly sensitive to upfront capital outlays.
Supply Chain Analysis
Upstream feedstock for diagnostic-grade electrodes draws from silver chloride processing facilities concentrated in China, Germany, and Japan. Low-power microcontrollers and flexible printed circuit boards source from Taiwan-based foundries and Shenzhen assembly clusters. Single-source vulnerability in Taiwan semiconductor fabrication creates exposure to geographic supply disruption. Distribution runs through hospital purchasing committees consolidating around multi-year vendor agreements rather than standalone device procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as CMS readmission penalties and value-based care frameworks accelerate hospital procurement of remote cardiac monitoring infrastructure previously considered optional.
For Market Incumbents: Insulate recurring revenue streams by deepening backward integration into proprietary wireless transmission protocols that lock hospital systems into device-algorithm-service bundles. Expand cloud analytics capacity in North American integrated delivery networks before EU MDR Article 10 compliance costs structurally favor large platforms over mid-tier competitors. Threat substitution from edge-computing wearables demands accelerated R&D investment in real-time inference architectures. For New Entrants and Emerging Players: Tier-two and tier-three Indian cities present the most penetrable white-space opportunity, with CDSCO regulatory pathways now streamlined for wearable sensor imports. Target ambulatory syncope diagnosis applications where edge-computing patches displace inpatient observation without requiring electrophysiologist placement expertise. A direct-to-cardiologist go-to-market model bypasses consolidated hospital purchasing committees in saturated Western markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-enhanced ECG classification sub-segments as FDA and PMDA scrutiny of training data representativeness demands expanded clinical trials. Long-term viability over the next decade rests on regulatory navigation capability and data infrastructure scale rather than hardware manufacturing excellence. Acquisition target archetypes include pure-play algorithm developers with cleared FDA pathways and established cloud analytics platforms. Watch for reimbursement code fragmentation between in-clinic and home-based monitoring as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review timelines compress commercialization cycles for AI-enhanced ECG algorithms in United States markets. |
| Hospital System Partnership | Multi-year service contracts bundle devices with cloud analytics, displacing standalone hardware procurement in electrophysiology labs. |
| Software Companion Development | Edge-computing inference architectures embedded in wearable patches reduce latency for critical arrhythmia notifications. |
| CE Marking Pathway | EU MDR Article 10 compliance elevates structural costs that favor large platforms with existing patient registry infrastructure. |
| Reimbursement Strategy | Remote physiologic monitoring code expansion enables ambulatory care centers to capture continuous data without bed occupancy costs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across electrophysiology labs, ambulatory care centers, hospital purchasing committees, and biomedical engineering directors. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR notified body registers, and GPO contract repositories. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation anchored volume and value estimates.
Calibration against historical regulatory approval timelines and reimbursement code expansions refined growth assumptions across the analysis window. Segmentation dimensions modeled include product form factor, connectivity architecture, clinical application, and care delivery setting. CAGRs were derived from installed base growth, replacement demand cycles, and algorithm penetration curves. Forecast inputs incorporated electrophysiologist training pipeline constraints and semiconductor foundry capacity utilization.
Macroeconomic conditions sit as an overlay; deviation in CMS penalty structures, EU MDR enforcement intensity, or Taiwan semiconductor supply would shift the trajectory. Cross-checking against hospital capital expenditure surveys and cardiac procedure volume registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Heart Rate Monitor Market
Patient Monitoring
Mobile Heart Monitoring Market
Patient Monitoring
Global Patient Temperature Monitoring Market
Patient Monitoring
AI in Remote Patient Monitoring Market
Patient Monitoring
South Africa Patient Monitoring Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Wearable Ambulatory Monitoring Device Market
Patient Monitoring
Multi-Channel Remote ECG Monitors Market
Patient Monitoring
Blood Temperature Indicator Market
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
ECG Monitoring System Market
Patient Monitoring
North America Self-Monitoring Blood Glucose Market
Patient Monitoring
Sleep Tracking Devices Market
Patient Monitoring
MRI Pulse Oximeters Market
Patient Monitoring
Respiratory Monitoring Devices Market
Patient Monitoring
Remote Patient Monitoring Devices Market