
 Asia-Pacific Fetal and Neonatal Monitoring Market | 2026-2036
Asia-Pacific Fetal and Neonatal Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fetal and Neonatal Monitoring Market Outlook
Wireless fetal monitoring is rewriting clinical workflows across Asia-Pacific obstetrics departments. GE Healthcare leverages its telemetry infrastructure to anchor large hospital contracts in Japan and Australia. Koninklijke Philips competes through integrated software-hardware platforms that extend from labor suites to neonatal intensive care units. Siemens Healthineers dominates advanced imaging-linked monitoring in China's premium hospital segment.
Fetal and neonatal monitoring encompasses electronic systems that track fetal heart rate, uterine contractions, neonatal vital signs, and oxygen saturation through transducer-based or Doppler ultrasound modalities, typically operating at 1-2 MHz for fetal cardiotocography. These devices serve the clinical imperative of detecting hypoxia, distress, or hemodynamic instability before irreversible organ damage occurs. CTG monitors occupy the largest installed base across Asia-Pacific tertiary hospitals, while wireless monitoring systems represent the fastest-expanding technology segment as facilities retrofit wired labor wards. Doppler devices sustain strong replacement demand in India's clinic network, where portability determines purchase decisions.
Japan's PMDA enforces stringent electromagnetic compatibility standards for neonatal incubators, effectively filtering non-compliant imports from Southeast Asian suppliers. Australia's TGA alignment with MDR-equivalent post-market surveillance requirements elevates documentation burdens for software-integrated telemetry systems. China's NMPA dual-certificate pathway for AI-assisted cardiotocography interpretation is concentrating vendor resources on algorithm validation. Stakeholders must weigh regulatory compliance costs against the margin premium of software-augmented monitoring platforms as purchasing criteria shift from hardware specifications to predictive analytics integration.
Market Dynamics
Wireless telemetry infrastructure is collapsing the traditional wired monitoring paradigm across Asia-Pacific obstetrics departments, forcing hardware vendors to restructure R&D budgets toward software-integrated platforms and predictive algorithm development.
Growth Catalysts
- India's PLI scheme for medical devices:Domestic manufacturers now capture incentives for locally produced cardiotocography equipment, reducing import dependence for tier-two hospital procurement.
- China's tier-one city maternal health infrastructure:Sustained public investment in Beijing, Shanghai, and Guangzhou creates concentrated demand for NICU expansion and wireless labor ward retrofitting.
- Southeast Asian hospital NICU capability expansion:Thailand, Vietnam, and Indonesia are prioritizing neonatal intensive care unit buildouts as central components of national health system upgrades.
Market Restraints
- Japan PMDA electromagnetic compatibility standards:Stringent EMC requirements for neonatal incubators filter non-compliant imports, limiting Southeast Asian supplier market access.
- Semiconductor component concentration:Disruption in Taiwan and South Korea foundry output creates supply volatility for Doppler ultrasound transducer chipsets.
- AI-assisted cardiotocography validation timelines:China's NMPA dual-certificate pathway extends algorithm approval cycles, compressing vendor cash conversion periods.
Strategic Opportunities
- India's clinic network Doppler replacement cycle:Portable device demand in secondary cities and rural districts remains underserved by current distribution models.
- Australia TGA-MDR alignment:Elevated post-market surveillance documentation requirements favor vendors with established quality management systems, creating barrier-protected positioning.
- Software-hardware platform convergence:Integration of cardiotocography data with electronic health records and remote monitoring dashboards opens recurring revenue streams beyond device sales.
Industry Challenges
- Biomedical engineer specialization gap:Shortage of technicians trained in wireless telemetry troubleshooting and predictive algorithm calibration slows deployment in Indonesian and Philippine facilities.
- Legacy wired infrastructure integration:Retrofitting 1980s-1990s era labor wards with wireless systems requires phased capital expenditure planning that conflicts with annual budget cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fetal and Neonatal Monitoring Market |
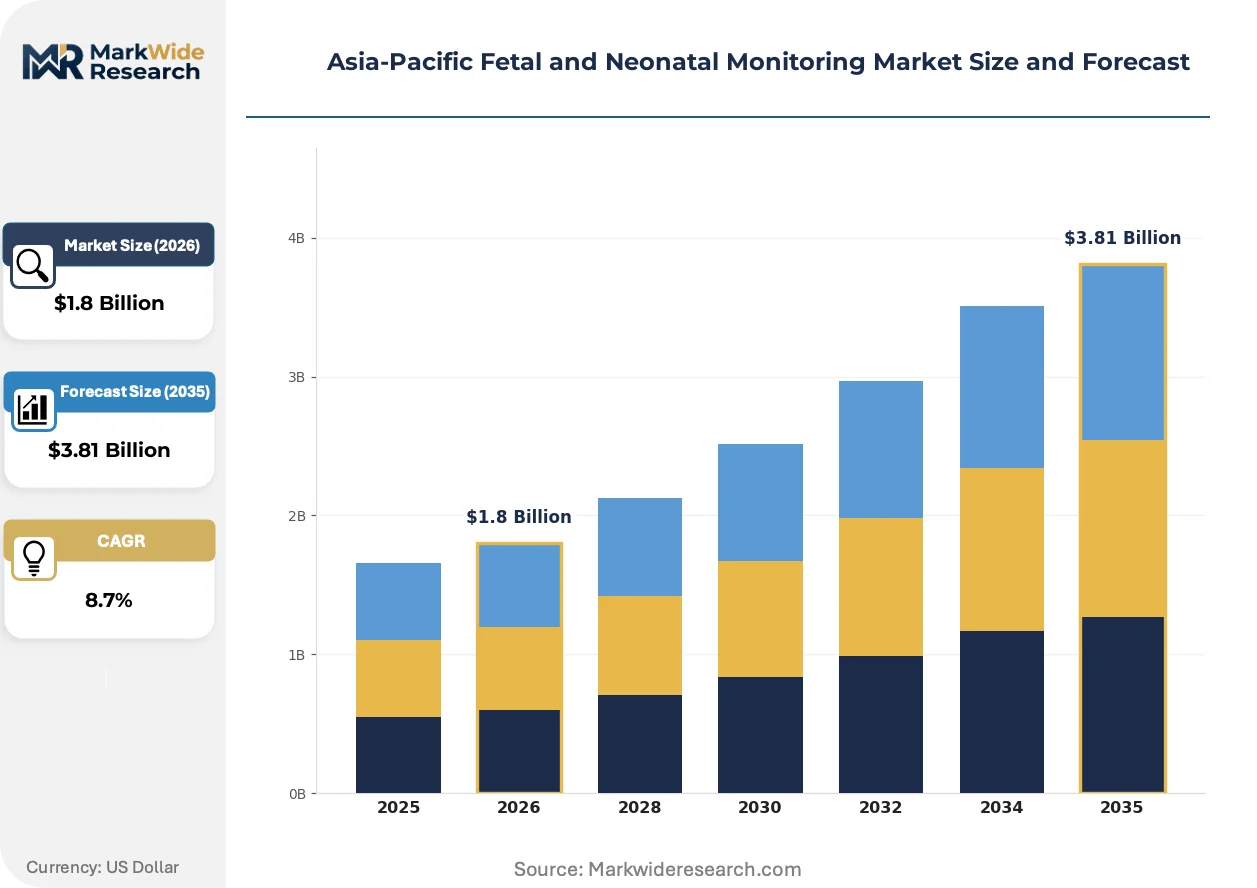
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CTG Monitors, Fetal Scopes, Neonatal Incubators, Doppler Devices End User: Hospitals, Clinics, Maternity Centers, Homecare Providers Technology: Wireless Monitoring, Portable Devices, Software Solutions, Telemetry Systems Application: Prenatal Monitoring, Labor Monitoring, Postnatal Care, Emergency Care |
| Companies Covered | GE Healthcare, Koninklijke Philips, Siemens Healthineers, Atom Medical, Drägerwerk AG & Co. KGaA, Medtronic, Becton Dickinson, Natus Medical, FUJIFILM SonoSite, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fetal and Neonatal Monitoring Market Strategic Shifts
Telemetry-enabled continuous monitoring is dissolving the boundary between labor suites and neonatal intensive care, creating unified data streams that reshape clinical decision architecture across Asia-Pacific tertiary facilities.
Wireless cardiotocography systems are collapsing the distinction between inpatient and remote monitoring modalities. These platforms transmit fetal heart rate and uterine contraction data through hospital Wi-Fi or cellular networks to centralized nursing stations. Australian and Japanese tertiary hospitals are deploying them at scale for ambulatory labor management. The structural consequence is compressing capital expenditure timelines, as facilities defer dedicated bedside monitor purchases in favor of subscription-based telemetry services.
China's NMPA dual-certificate pathway for AI-assisted cardiotocography interpretation is concentrating vendor resources on algorithm validation documentation. Manufacturers must secure separate approvals for software modules and hardware platforms, doubling regulatory submission costs. Premium hospital segments in Shanghai and Beijing are responding by demanding pre-validated integrated systems, shifting procurement criteria from hardware specifications to predictive analytics capabilities.
Hospital procurement committees across Southeast Asia are unbundling after-sales service contracts from device purchase agreements. Thai and Vietnamese facilities now negotiate maintenance, calibration, and software updates as separate line items, often with third-party biomedical service providers. This disintermediation is most visible in Malaysia's public hospital network, where centralized tendering processes favor modular contracting over bundled system sales.
Asia-Pacific Fetal and Neonatal Monitoring Market Segmentation
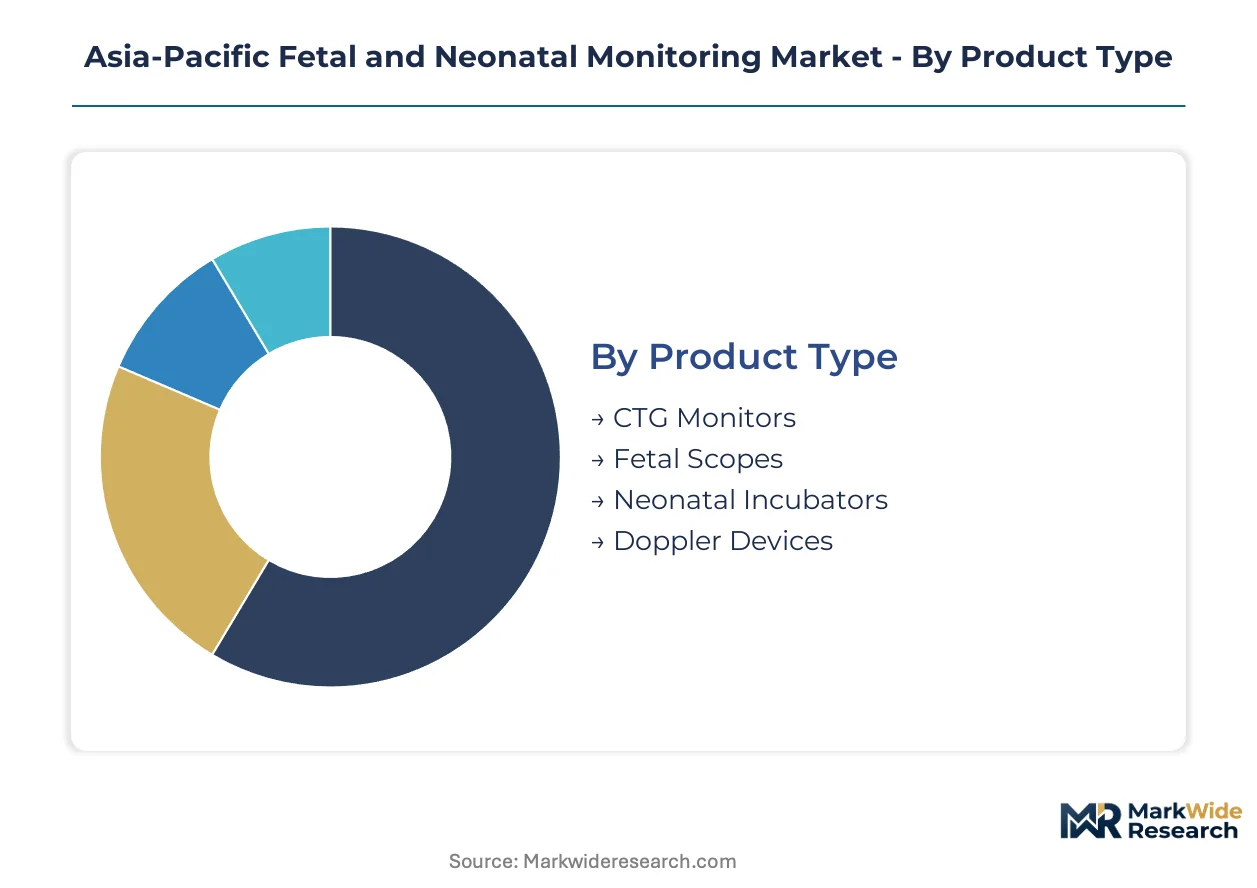
Segmentation in Asia-Pacific fetal and neonatal monitoring reveals divergent service intensity requirements across product categories. CTG monitors demand intensive calibration protocols, while wireless telemetry systems require continuous software maintenance contracts that reshape vendor revenue models.
Product Type:
After-sales-service intensity varies dramatically across product categories, with telemetry-integrated systems requiring multi-year software support commitments that alter hospital procurement budgeting cycles.
- CTG Monitors:Cardiotocography systems track fetal heart rate and uterine contractions through external tocodynamometer and ultrasound transducer arrays operating at standard medical frequencies. Demand concentrates in China's tier-one city tertiary hospitals where NICU expansion programs prioritize wired bedside installations for high-risk pregnancies.
- Doppler Devices:Handheld ultrasound units emit continuous-wave or pulsed-wave signals to detect fetal heart tones and blood flow velocity in umbilical and uterine arteries. India's clinic network in secondary cities drives replacement demand where portability outweighs telemetry integration requirements.
- Fetal Scopes:Electronic fetoscopes combine optical imaging with Doppler audio output for direct fetal visualization and auscultation.
- Neonatal Incubators:Thermoregulated enclosures with integrated vital sign monitoring face stringent Japan PMDA electromagnetic compatibility certification requirements.
CTG monitors hold the largest share; momentum sits with Doppler devices.
End User:
Customer type determines pricing architecture, with public hospital tendering processes favoring bundled device-service contracts that private maternity centers reject.
- Hospitals:Tertiary medical centers across Southeast Asia operate centralized NICU facilities requiring multi-parameter monitoring suites with EHR integration capabilities. Thailand's public hospital network prioritizes wireless telemetry retrofitting of legacy labor wards as part of national health system upgrades.
- Clinics:Secondary care facilities in India's district headquarters emphasize portable Doppler devices for antenatal screening programs where capital constraints limit multi-modal system purchases.
- Maternity Centers:Specialized obstetric facilities in Vietnam's urban corridors concentrate demand for ambulatory labor monitoring with reduced neonatal intensive care capabilities.
- Homecare Providers:Remote monitoring services in Australian metropolitan areas deploy wearable telemetry patches for high-risk pregnancy management outside institutional settings.
Hospitals dominate installed base volume; homecare providers are climbing the fastest.
Technology:
Technology architecture separates capital-intensive hardware purchases from recurring software revenue streams, with hybrid platforms capturing margin premiums in premium hospital segments.
- Wireless Monitoring:Wi-Fi and cellular-enabled telemetry systems transmit cardiotocography data to centralized nursing stations without tethering patients to bedside units. Australian tertiary hospitals deploy these at scale for ambulatory labor management, compressing capital expenditure timelines through subscription-based service models.
- Software Solutions:AI-assisted cardiotocography interpretation platforms require China's NMPA dual-certificate pathway approval, doubling regulatory submission costs while enabling predictive analytics integration.
- Portable Devices:Battery-operated Doppler and monitoring units serve India's rural clinic network where electrical infrastructure reliability constrains fixed installations.
- Telemetry Systems:Hospital-wide infrastructure for continuous physiological monitoring demands biomedical engineer specialization that Indonesian facilities struggle to staff.
Wireless monitoring holds the largest share; software solutions are gaining share fastest.
Application:
Clinical use case determines device specification requirements, with emergency care applications demanding ruggedized portable units distinct from stationary labor suite installations.
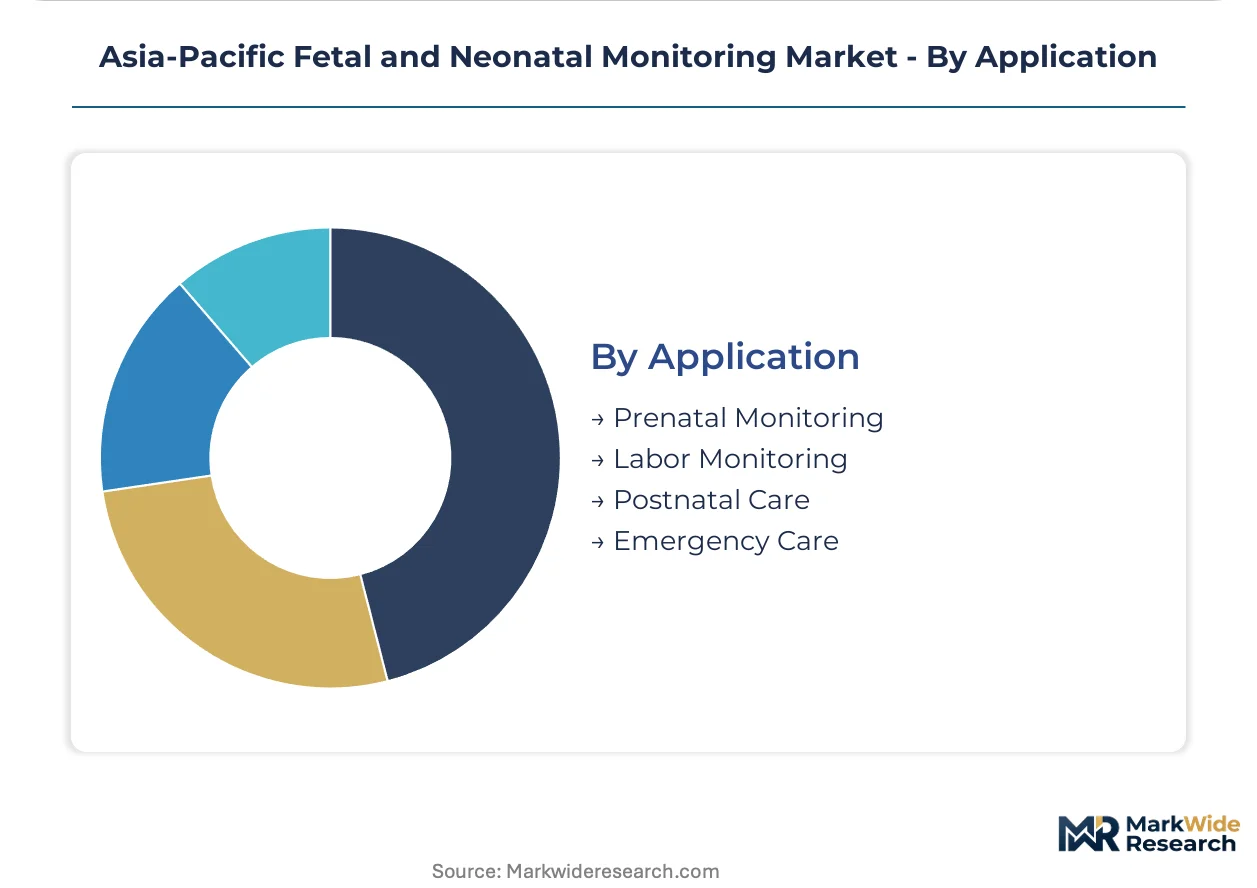
- Prenatal Monitoring:Antenatal surveillance encompasses non-stress tests and biophysical profiles performed in outpatient settings across China's municipal maternal health centers. Beijing and Shanghai public investment programs prioritize these capabilities in community health station networks.
- Labor Monitoring:Intrapartum cardiotocography requires continuous fetal heart rate and contraction pattern assessment during active delivery, driving wireless telemetry adoption in Japanese tertiary facilities.
- Postnatal Care:Neonatal vital sign surveillance in Vietnamese NICU buildouts concentrates demand for multi-parameter monitoring with apnea detection algorithms.
- Emergency Care:Transport incubator systems with integrated monitoring serve inter-hospital transfer requirements in Australia's regional health districts.
Labor monitoring holds the largest share; prenatal monitoring shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public hospital procurement committees dominate purchasing decisions across the Asia-Pacific region, with tier-one city maternal health infrastructure investments and national NICU expansion programs concentrating demand in specific metropolitan clusters.
China
Beijing, Shanghai, and Guangzhou municipal governments sustain public investment in community maternal health stations and tertiary hospital NICU buildouts. NMPA's dual-certificate pathway for AI-assisted cardiotocography interpretation is reshaping vendor approval strategies. The Yangtze River Delta cluster concentrates premium hospital demand for wireless telemetry retrofitting of legacy labor wards.
India
District headquarters clinics in secondary cities drive portable Doppler replacement cycles where electrical infrastructure constraints favor battery-operated units. CDSCO regulates medical device manufacturing under India's PLI scheme, which incentivizes domestic cardiotocography production. Maharashtra and Gujarat host emerging manufacturing clusters supplying tier-two hospital procurement networks.
Japan
PMDA enforces stringent electromagnetic compatibility standards for neonatal incubators that filter non-compliant imports from regional suppliers. Tokyo and Osaka metropolitan tertiary hospitals deploy wireless telemetry at scale for ambulatory labor management. Kanto region facilities prioritize integrated software-hardware platforms extending from labor suites to NICU environments.
Australia
TGA alignment with MDR-equivalent post-market surveillance requirements elevates documentation burdens for software-integrated telemetry systems. New South Wales and Victoria regional health districts concentrate demand for transport incubator systems serving inter-hospital transfer requirements. Sydney and Melbourne metropolitan areas deploy wearable telemetry patches for high-risk pregnancy homecare management.
Vietnam
Urban corridor maternity centers concentrate demand for ambulatory labor monitoring with reduced neonatal intensive care capabilities. The Ministry of Health prioritizes NICU buildouts as central components of national health system upgrades. Ho Chi Minh City and Hanoi public hospital networks negotiate unbundled after-sales service contracts separate from device purchase agreements.
Asia-Pacific Fetal and Neonatal Monitoring Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent procurement pathways, with consolidated telemetry infrastructure vendors anchoring large hospital contracts while portable device specialists serve fragmented clinic networks. The market structure tiers between premium integrated-platform vendors and economy-focused equipment fabricators. Three strategic archetypes dominate: full-stack medical technology conglomerates, regional manufacturing specialists, and software-augmented monitoring innovators. M&A activity concentrates on telemetry software capabilities, while capacity expansion targets India's PLI-incentivized production zones.
Among diversified medical technology conglomerates, GE Healthcare, Koninklijke Philips, and Siemens Healthineers exemplify the full-stack archetype with integrated hardware-software platforms spanning cardiotocography, imaging, and telemetry infrastructure. These entities occupy positions defined by regulatory validation depth and hospital system contract scale rather than discrete product specifications. Their competitive positioning depends on algorithm validation documentation and multi-year service commitment structures that align with public hospital procurement committee budgeting cycles.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips |
| Siemens Healthineers |
| Atom Medical |
| Drägerwerk AG & Co. KGaA |
| Medtronic |
| Becton Dickinson |
| Natus Medical |
| FUJIFILM SonoSite |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Taiwan and South Korea semiconductor foundries is compressing Doppler ultrasound transducer chipset availability, forcing manufacturers to accept longer lead times and pass input cost volatility through to hospital procurement committees while simultaneously accelerating domestic production incentives under India's PLI scheme.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate component sourcing agreements for telemetry-integrated monitoring systems. Three-tier pricing structure across premium, standard, and economy levels separates AI-validated platforms with NMPA dual-certificates from basic CTG hardware and portable Doppler units. Pricing pressure stems from unbundled after-sales service contracts in Thai and Vietnamese public hospital tenders. Tier-two hospital procurement networks in India exhibit highest price sensitivity, while Australian tertiary facilities prioritize predictive analytics capabilities over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced semiconductor manufacturing equipment limit foundry capacity expansion in Taiwan and South Korea, constraining Doppler transducer chipset flows. Component sourcing draws from Japan for precision sensors, China for printed circuit board assemblies, and Germany for thermoregulation modules. Single-source vulnerability concentrates in Taiwan's 28nm and below foundry output. Distribution runs through authorized medical device distributors with CDSCO or NMPA licensing, supplemented by direct hospital system contracts for large telemetry infrastructure deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive boundaries as software-hardware integration creates winner-take-most dynamics, with interoperability requirements between cardiotocography data streams and electronic health record systems establishing ecosystem lock-in effects across Asia-Pacific tertiary hospital networks.
For Market Incumbents: Build regulatory-validation moats through accelerated NMPA dual-certificate submissions for AI-assisted interpretation modules before algorithm validation timelines extend further. Deepen backward integration into semiconductor component buffering to mitigate Taiwan foundry disruption exposure. Consolidate service contract bundling capabilities to counter unbundling pressures in Southeast Asian public tenders. For New Entrants and Emerging Players: Build out portable Doppler distribution networks in India's secondary city clinic ecosystem where electrical infrastructure constraints favor battery-operated units and incumbent telemetry platforms over-serve demand. Target district headquarters procurement committees with PLI-compliant domestic manufacturing credentials. Pursue white-label partnerships with Maharashtra and Gujarat emerging production clusters to bypass import duty disadvantages. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-augmented monitoring sub-segments as subscription telemetry services displace capital-intensive bedside hardware purchases. Long-term viability favors vendors with recurring revenue architectures over pure equipment manufacturers. Acquisition targets should demonstrate validated algorithm documentation and established hospital system contract renewal rates. Monitor NMPA approval velocity for AI-assisted cardiotocography as inflection indicator for platform economics consolidation speed.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Dual-Certificate Acceleration | Secures algorithm validation lead time advantage in China's premium hospital segment before regulatory submission costs double. |
| PLI-Compliant Domestic Manufacturing | Captures tier-two hospital procurement preference under India's production-linked incentive scheme for cardiotocography equipment. |
| Telemetry Infrastructure Partnerships | Anchors large Australian and Japanese tertiary hospital contracts through Wi-Fi and cellular-enabled subscription service models. |
| Software-Hardware Platform Convergence | Opens recurring revenue streams via EHR integration and remote monitoring dashboards beyond one-time device sales. |
| Biomedical Engineer Training Programs | Addresses deployment bottlenecks in Indonesian and Philippine facilities where wireless telemetry troubleshooting specialization remains scarce. |
Study Parameters
Operator-level perspectives from hospital procurement committee directors, biomedical engineers, GPO contracts managers, and CDSCO regulatory affairs leads anchored the qualitative base. Primary interviews combined with secondary validation from NMPA approval databases, TGA post-market surveillance registers, hospital procurement tender records, and PLI scheme beneficiary disclosures. Bottom-up installed base modeling and top-down maternal health infrastructure investment flow analysis provided triangulation across volume and value estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with base, upside, and downside cases reflecting semiconductor supply disruption severity and NMPA approval velocity variation. Segmentation dimensions modeled include product type, end-user facility tier, technology architecture, and application use case, with regional regulatory cluster and public-private procurement pathway as cross-cutting stratifiers. CAGRs derived from logistic diffusion curves fitted to wireless telemetry adoption patterns and replacement cycle timing for legacy wired installations.
Stress conditions across Taiwan foundry output disruption duration, NMPA dual-certificate approval timeline extension, and PLI scheme incentive modification were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding maternal health infrastructure investment continuity and software validation cost trajectories. Material shifts in electromagnetic compatibility standard enforcement by Japan's PMDA or export-control expansion affecting semiconductor equipment flows would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Drowsiness Monitoring System Market
Patient Monitoring
UAE Patient Monitoring Equipment Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Cardiopulmonary Exercise Testing Market
Patient Monitoring
Europe Cardiac Holter Monitor Market
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
Australia Patient Monitoring Market
Patient Monitoring
ICU ECG Patient Monitor Market
Patient Monitoring
Europe Respiratory Monitoring Market
Patient Monitoring
Sleep Tracking Devices Market
Patient Monitoring
South America Body Temperature Monitoring Market
Patient Monitoring
Respiration Monitor Belt Market
Patient Monitoring
Medical Telemetry Market
Patient Monitoring
Abetalipoproteinemia Monitoring Systems Market
Patient Monitoring
Wearable Heart Monitoring Devices Market
Patient Monitoring
South America Cardiac Monitoring Market