
 Asia-Pacific Revenue Cycle Management Market | 2026-2036
Asia-Pacific Revenue Cycle Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Revenue Cycle Management Market Insights
Cloud-native specification tiers are bifurcating the competitive landscape between legacy on-premise incumbents and API-first challengers. Epic Systems Corporation anchors its position through deep EHR-revenue cycle integration across large hospital networks. Oracle Corporation leverages its Cerner acquisition to sustain database-layer control over patient financial data workflows. TCS differentiates through captive delivery centers that reduce implementation timelines for mid-market health systems across India and Australia.
Asia-Pacific Revenue Cycle Management encompasses the financial processes, software platforms, and outsourced services that manage patient registration, billing, claims adjudication, and revenue recovery for healthcare providers, typically operating through HL7 FHIR interoperability standards and real-time eligibility verification protocols to reduce denial rates and accelerate cash collection. The software segment dominates current procurement budgets as hospitals replace fragmented legacy billing modules with unified platforms, while the cloud-based deployment category captures the fastest expansion trajectory as India's hospital chains and Australia's regional health districts abandon capital-intensive server infrastructure. Services and consulting segments retain concentrated margin pools where implementation complexity around ICD-11 migration and payer-specific coding requirements creates pricing power for specialized vendors.
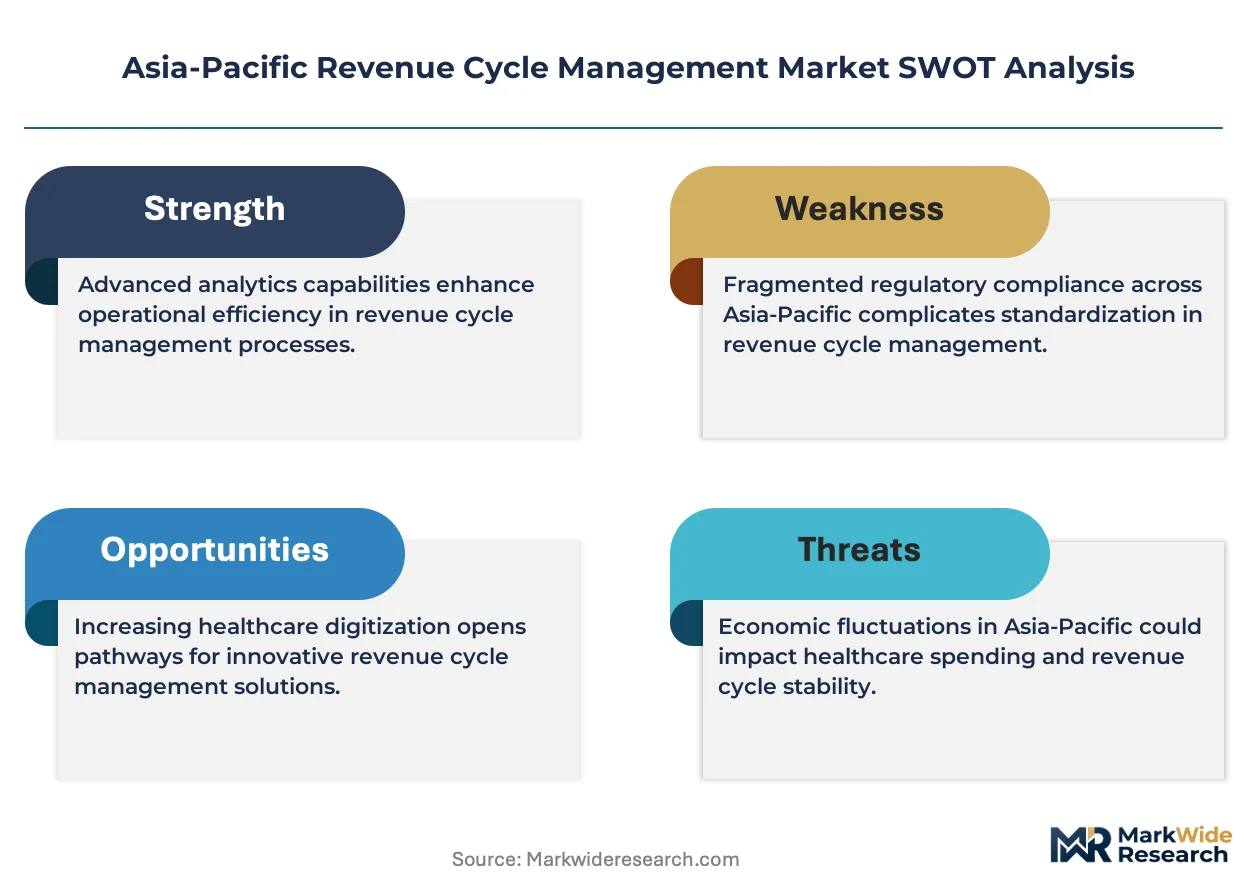
India's CDSCO data-localization guidelines, Australia's Office of the Australian Information Commissioner privacy frameworks, and Japan's METI healthcare digitization standards collectively shape product architecture decisions and market access requirements across the region. Compliance with these overlapping regulatory regimes forces platform vendors to maintain region-specific data residency configurations and audit trails, raising barriers for single-jurisdiction operators. Stakeholders must evaluate whether to build parallel regulatory compliance stacks or partner with established regional platforms that already navigate this fragmented certification landscape.
Market Dynamics
Hospital digitization mandates across Southeast Asia and India's PLI scheme for healthcare IT infrastructure are compressing procurement timelines for unified revenue cycle platforms, forcing vendors to reconfigure cloud-native architectures for fragmented regulatory compliance stacks.
Growth Catalysts
- India's PLI scheme for healthcare IT infrastructure:Production-linked incentives accelerate domestic manufacturing of billing-to-claims platforms, reducing import dependency for public hospital digitization programs.
- Australia's My Health Record interoperability mandates:Federal requirements for HL7 FHIR compliance drive replacement of legacy billing modules with API-first revenue cycle architectures across regional health districts.
- Cloud migration in Southeast Asian hospital networks:Capital-intensive server abandonment creates concentrated procurement cycles for subscription-based revenue cycle platforms with real-time eligibility verification.
Market Restraints
- Data-localization compliance costs:India's CDSCO guidelines, Australia's OAIC privacy frameworks, and Japan's METI standards force parallel regulatory stacks that raise implementation costs for single-jurisdiction operators.
- ICD-11 migration complexity:Payer-specific coding requirements and dual coding periods during transition create pricing pressure on specialized implementation vendors.
- Legacy EHR lock-in effects:Deep integration between incumbent billing modules and existing patient record systems creates switching friction for mid-market health systems.
Strategic Opportunities
- Indonesia's underpenetrated provincial hospital networks:Public health digitization programs outside Java present first-mover advantages for end-to-end revenue cycle platforms with offline-capable architectures.
- API-first challenger consolidation:Cloud-native specification tiers enable mid-market acquisition strategies targeting fragmented billing module vendors across Australia and New Zealand.
- Vietnam's emerging private insurer expansion:New commercial health plan licensing creates demand for real-time claims adjudication infrastructure with Vietnamese-language coding support.
Industry Challenges
- HL7 FHIR implementation talent scarcity:Shortage of certified interoperability engineers delays deployment timelines for health systems attempting simultaneous EHR and revenue cycle upgrades.
- Multi-payer configuration complexity:Australia's mixed public-private funding structure and India's state-wise insurance schemes require customized rule engines that strain platform standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Revenue Cycle Management Market |
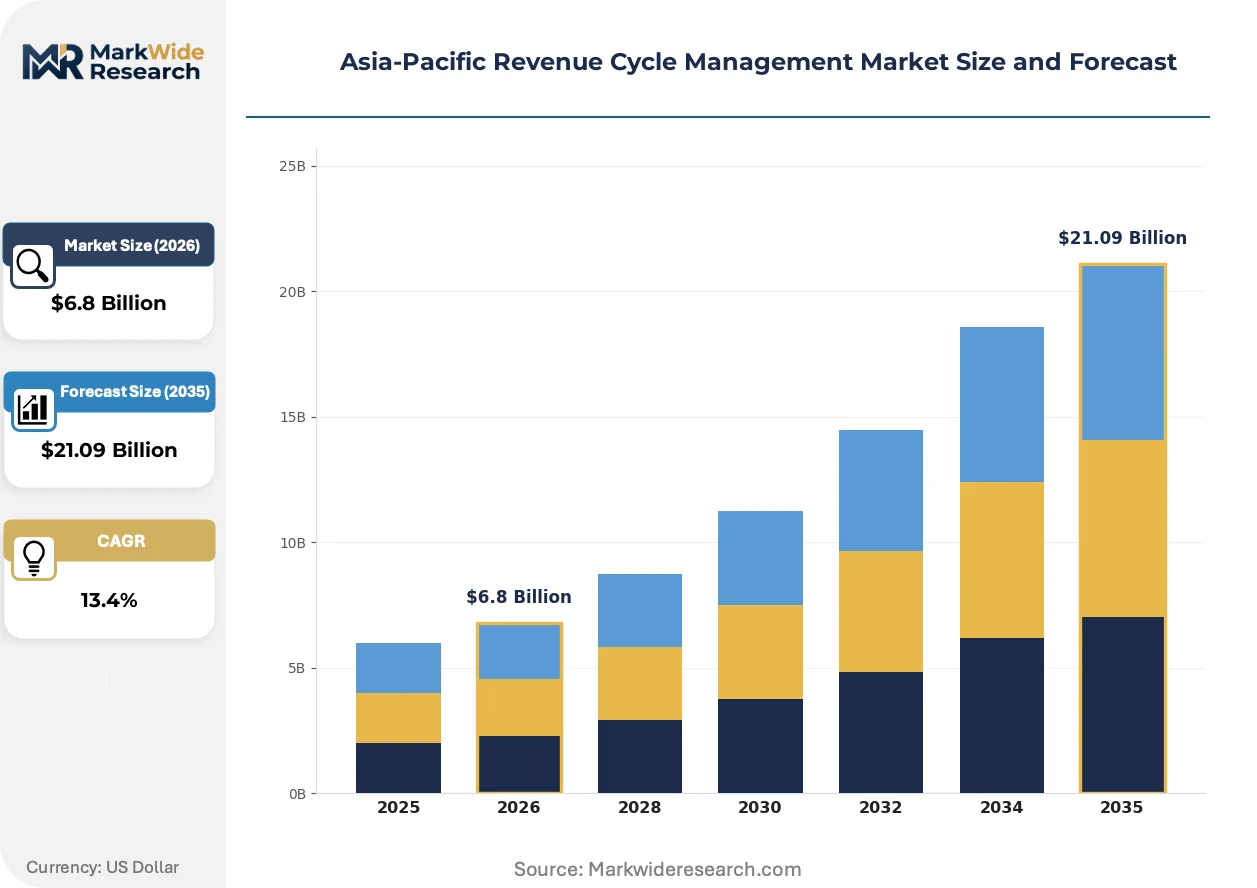
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Services, Analytics, Consulting End User: Hospitals, Independent Practices, Clinics, Urgent Care Centers Deployment: On-Premise, Cloud-Based, Hybrid, Web-Based Application: Patient Registration, Billing, Claims Management, Revenue Recovery |
| Companies Covered | McKesson Corporation, Athenahealth Inc., Quest Diagnostics Incorporated, Allscripts Healthcare Solutions Inc., R1 RCM Inc., Epic Systems Corporation, Oracle Corporation, TCS, Infosys Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Revenue Cycle Management Market Trends and Innovations
Real-time eligibility verification protocols and AI-assisted coding engines are compressing denial rates while reshaping competitive positioning between database-layer incumbents and workflow-agnostic challengers.
API-first revenue cycle architectures are supplanting monolithic on-premise billing systems across large Australian hospital networks. Queensland Health and New South Wales regional districts have accelerated procurement of modular platforms that decouple patient financial data from EHR core systems. This architectural shift is enabling best-of-breed vendor selection while compressing implementation timelines from 18-month cycles to 6-month deployments.
Japan's METI healthcare digitization standards now mandate audit trail retention periods that exceed most legacy platform capabilities. The industrial consequence forces vendors to rebuild data residency configurations or exit the market. Australian private hospital chains are responding fastest, using compliance-driven procurement to justify full-stack replacement of decade-old billing infrastructure.
Subscription-based pricing models are displacing perpetual license structures across India's mid-market hospital chains. Apollo and Max Healthcare procurement teams now prioritize operational expenditure alignment over capital budget absorption. This behavioral shift is most visible in tier-2 Indian cities where hospital chains face working capital constraints during expansion phases.
Asia-Pacific Revenue Cycle Management Market Segmentation
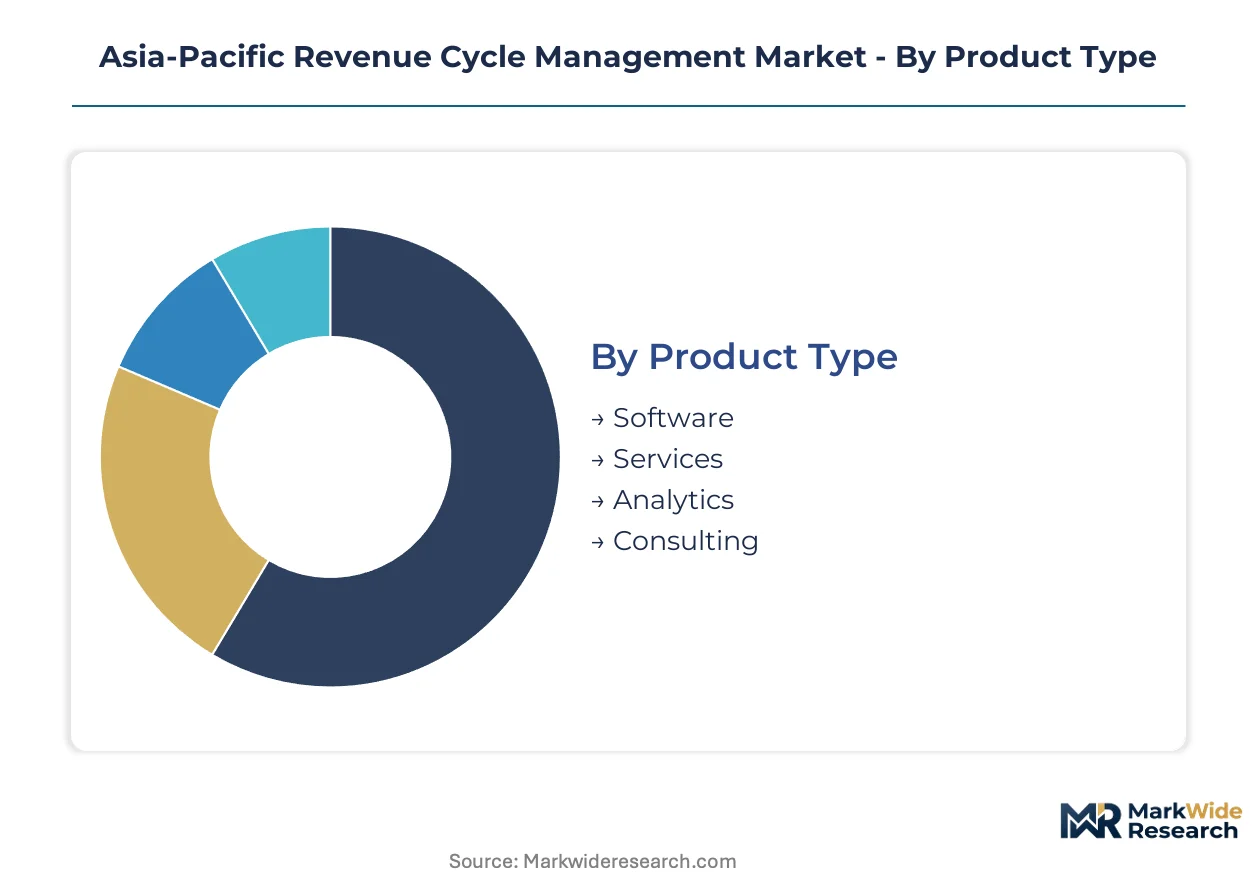
Revenue cycle platforms fragment across four structural dimensions that determine procurement priorities and vendor positioning. Product architecture, deployment infrastructure, clinical setting, and functional application each create distinct competitive arenas with divergent margin profiles and substitution risks.
Product Type:
Software segments face intensifying substitution pressure from API-first challengers unbundling monolithic billing suites, while services and consulting retain defensive moats through ICD-11 implementation complexity.
- Software:Unified billing-to-claims platforms integrating patient registration, charge capture, and denial management through HL7 FHIR protocols. India's public hospital digitization and Australia's My Health Record mandates are compressing procurement timelines for cloud-native replacements of fragmented legacy modules.
- Services:Implementation, training, and ongoing technical support bundled with platform deployment. Payer-specific coding requirements and dual coding periods during ICD-11 migration create pricing power for specialized vendors across Southeast Asian hospital networks.
- Analytics:Predictive denial risk scoring and revenue forecasting engines. Australian regional health districts leverage these tools to optimize cash collection cycles.
- Consulting:Regulatory compliance advisory and workflow redesign for multi-payer environments. India's CDSCO data-localization guidelines drive demand for region-specific audit trail configuration.
Software anchors the volume base while analytics gains share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive hospital networks from asset-light independent practices with divergent platform requirements and implementation budgets.
- Hospitals:Large acute care networks requiring end-to-end revenue cycle integration across inpatient, outpatient, and emergency departments. Apollo and Max Healthcare in India prioritize subscription-based pricing to align operational expenditure with expansion phases.
- Independent Practices:Small physician groups seeking lightweight billing modules with minimal IT overhead. Australia's OAIC privacy frameworks raise compliance costs that favor cloud-based solutions reducing on-premise infrastructure burdens.
- Clinics:Specialty diagnostic and outpatient facilities with focused procedure mixes. Vietnam's emerging private insurer expansion creates demand for real-time eligibility verification at point-of-service.
- Urgent Care Centers:High-volume, low-acuity settings requiring rapid patient throughput and same-day billing capture. Indonesia's provincial networks outside Java present first-mover opportunities for offline-capable architectures.
Hospitals dominate procurement value while urgent care centers expand most quickly as retail healthcare penetration deepens.
Deployment:
Volume concentration favors cloud migration trajectories as India's hospital chains and Australia's regional districts abandon server infrastructure capital commitments.
- Cloud-Based:Subscription-accessed platforms with automatic updates and elastic compute scaling. Queensland Health and New South Wales regional districts have compressed implementation timelines from 18-month cycles to 6-month deployments through modular API-first procurement.
- On-Premise:Legacy server installations retaining control over patient financial data workflows. Deep EHR-revenue cycle integration creates switching friction for mid-market health systems with sunk capital in existing infrastructure.
- Hybrid:Split configurations maintaining sensitive data on local servers while leveraging cloud analytics. Japan's METI audit trail retention mandates exceed most legacy capabilities, forcing architectural rebuilds.
- Web-Based:Browser-accessed solutions requiring minimal local installation. Tier-2 Indian city hospital chains adopt these for rapid deployment without dedicated IT staffing.
On-premise retains installed base density while cloud-based deployment climbs the fastest as capital constraints reshape procurement preferences.
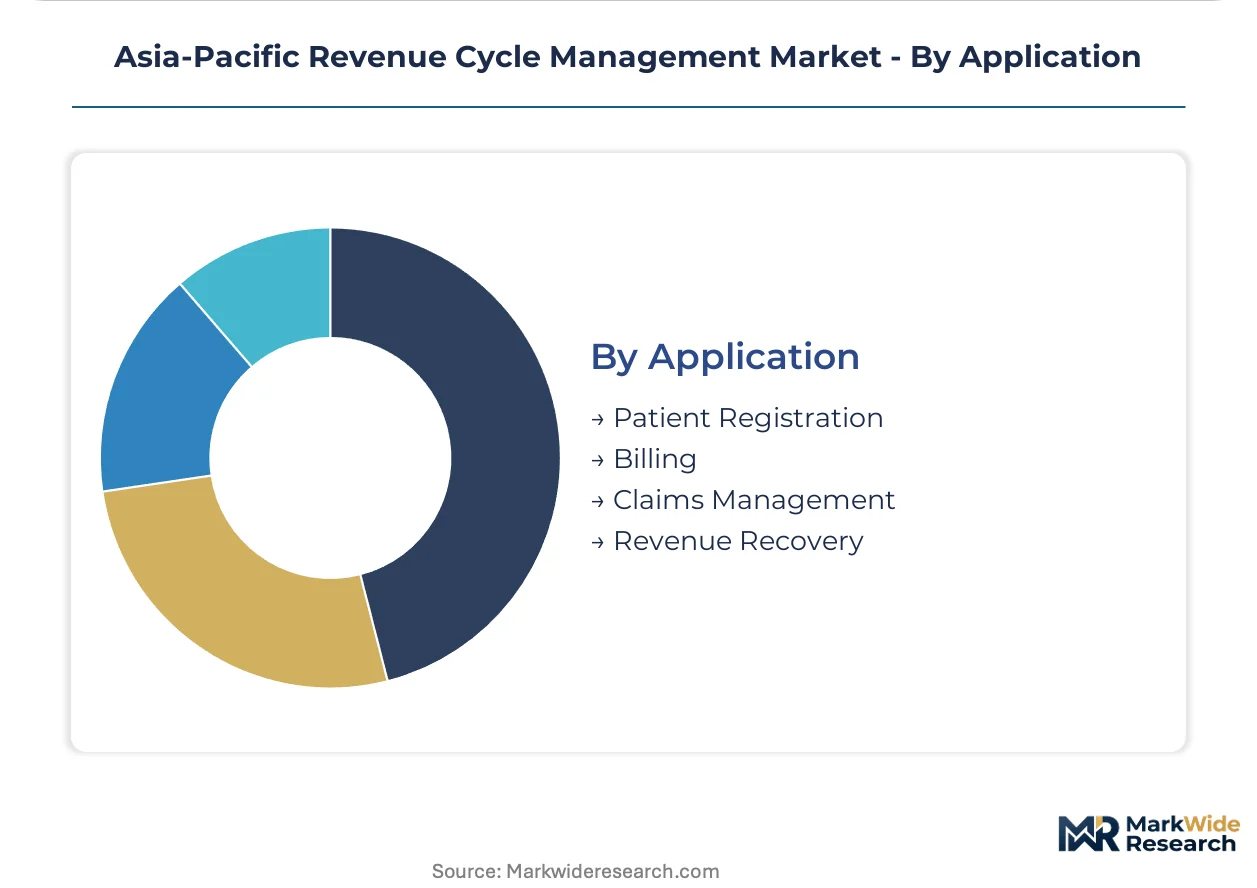
Application:
Customer type segmentation reveals workflow-agnostic challengers targeting specific functional modules against database-layer incumbents defending integrated suites.
- Claims Management:Payer submission, adjudication tracking, and denial appeals workflows. Australia's mixed public-private funding structure demands customized rule engines that strain platform standardization.
- Billing:Charge capture, coding, and patient statement generation. AI-assisted coding engines are compressing denial rates while reshaping vendor competitive positioning.
- Patient Registration:Eligibility verification, demographic capture, and financial clearance. Real-time protocols reduce front-end denials and accelerate cash collection for Southeast Asian hospital networks.
- Revenue Recovery:Denial root-cause analysis, appeals management, and bad debt collection. Specialized vendors capture concentrated margin pools where complexity creates pricing power.
Billing commands the largest addressable spend while claims management shows the steepest expansion trajectory as denial prevention becomes a C-suite priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Revenue cycle management platform trade flows across the Asia-Pacific region reflect divergent import dependency patterns, with India and Indonesia relying heavily on foreign software vendors while Australia and Japan cultivate domestic capabilities through regulatory localization mandates.
India
Apollo and Max Healthcare procurement teams drive subscription-based platform adoption across tier-2 cities, prioritizing operational expenditure alignment over capital deployment. CDSCO data-localization guidelines force foreign vendors to maintain domestic server infrastructure, raising compliance barriers for single-jurisdiction operators. Maharashtra's Mumbai-Pune corridor concentrates implementation talent pools where TCS and Infosys operate captive delivery centers.
Australia
Queensland Health and New South Wales regional districts compress implementation timelines through modular API-first procurement, abandoning 18-month legacy cycles. My Health Record interoperability mandates require HL7 FHIR compliance across all patient financial data workflows. Sydney and Melbourne anchor private hospital chain procurement, where compliance-driven replacement of decade-old billing infrastructure accelerates.
Japan
METI healthcare digitization standards mandate audit trail retention periods exceeding most legacy platform capabilities, forcing architectural rebuilds or market exit. Large hospital networks in Tokyo and Osaka prioritize database-layer control over patient financial data. Kansai region health systems lead adoption of hybrid deployment configurations balancing cloud analytics with local server retention.
Indonesia
Public health digitization programs outside Java present first-mover opportunities for end-to-end revenue cycle platforms with offline-capable architectures. Provincial hospital networks in Sumatra and Sulawesi lack dedicated IT staffing, favoring rapid-deployment web-based solutions. Jakarta anchors private insurer expansion creating demand for real-time claims adjudication infrastructure.
Vietnam
Emerging private insurer licensing creates concentrated procurement cycles for real-time eligibility verification at point-of-service. Ho Chi Minh City and Hanoi hospital chains seek Vietnamese-language coding support as commercial health plan penetration deepens. Foreign platform vendors face localization requirements around medical terminology databases and payer rule engines.
Asia-Pacific Revenue Cycle Management Market Competitive Landscape
Listed leaders compete with private specialists across cloud-native specification tiers, creating a bifurcated structure where database-layer incumbents defend integrated suites against API-first challengers unbundling monolithic billing modules. The vendor base concentrates around three strategic archetypes: EHR-anchored platforms leveraging deep patient record integration, captive delivery specialists compressing implementation timelines, and modular challengers decoupling financial data from core clinical systems. Dominant competitive moves include M&A-driven consolidation targeting mid-market billing module vendors and strategic partnerships navigating fragmented regulatory compliance stacks.
Within the EHR-anchored tier, Epic Systems Corporation and Oracle Corporation exemplify divergent approaches to patient financial data control, with the former emphasizing deep integration and the latter leveraging database-layer dominance. TCS occupies a position among captive delivery specialists, reducing implementation timelines for mid-market health systems across India and Australia through region-specific compliance expertise.
| Leading Market Players |
|---|
| McKesson Corporation |
| Athenahealth Inc. |
| Quest Diagnostics Incorporated |
| Allscripts Healthcare Solutions Inc. |
| R1 RCM Inc. |
| Epic Systems Corporation |
| Oracle Corporation |
| TCS |
| Infosys Limited |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Indian captive delivery centers compresses implementation cost floors for mid-market health systems across the region, concentrating supply-side pricing power among vendors with established domestic infrastructure while forcing single-jurisdiction operators toward partnership models or exit.
Pricing Analysis
Hospital procurement teams anchor Asia-Pacific revenue cycle management pricing through subscription-based SaaS tiers that stratify across enterprise, mid-market, and provincial hospital levels. Price differentiation rests on HL7 FHIR certification grade and implementation timeline guarantees, with TCS and Infosys commanding premiums for captive delivery center proximity. Cost compression in the mid-market tier is intensifying because India's PLI scheme accelerates domestic platform manufacturing, eroding import-dependent vendor margins. Provincial hospital networks outside Java and Vietnam's emerging private clinics exhibit highest price sensitivity, while Australian regional health districts show lowest sensitivity due to compliance-driven replacement mandates.
Supply Chain Analysis
Just-in-time deployment preferences dominate Asia-Pacific revenue cycle management procurement, with Queensland Health and New South Wales regional districts compressing implementation timelines from eighteen-month legacy cycles to six-month modular deployments. Geographic supply concentration centers on India for captive implementation services, Australia for HL7 FHIR interoperability engineering, and Japan for audit trail compliance architecture. Raw material dependencies include cloud compute infrastructure from hyperscalers, certified interoperability engineering talent, and localized medical coding databases. Single-source vulnerability around HL7 FHIR implementation talent scarcity strains platform standardization efforts. Distribution runs through direct enterprise sales to hospital networks, supplemented by GPO contracts and regional system integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific revenue cycle management represents a high-growth disruption as India's PLI scheme and Australia's My Health Record interoperability mandates compress procurement timelines for cloud-native platforms, creating concentrated vendor selection windows across the region.
For Market Incumbents: Secure deep EHR-revenue cycle integration through API-first architecture investments that defend against modular challengers decoupling financial data from core clinical systems. Prioritize captive delivery center expansion in Maharashtra's Mumbai-Pune corridor to compress implementation timelines for mid-market health systems facing ICD-11 migration complexity. Certification investment in India's CDSCO data-localization compliance and Japan's METI audit trail standards anchors regional market access against single-jurisdiction competitors. For New Entrants and Emerging Players: Differentiate on offline-capable architectures targeting Indonesia's underpenetrated provincial hospital networks in Sumatra and Sulawesi, where dedicated IT staffing scarcity favors rapid-deployment web-based solutions. Vietnam's emerging private insurer expansion presents the most penetrable geography, with Ho Chi Minh City and Hanoi hospital chains seeking Vietnamese-language coding support as commercial health plan penetration deepens. A direct-to-hospital sales model with localized medical terminology database partnerships accelerates payer rule engine configuration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among API-first challengers with established HL7 FHIR interoperability certification and regional compliance navigation capabilities. Long-term viability across the five-to-ten year window favors vendors with parallel regulatory compliance stacks spanning India's CDSCO guidelines, Australia's OAIC privacy frameworks, and Japan's METI standards. Acquisition target archetypes include mid-market billing module vendors across Australia and New Zealand with modular architectures enabling best-of-breed vendor selection. The signal to watch is procurement timeline compression at Queensland Health and New South Wales regional districts, where six-month deployment cycles indicate architectural shift velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures decouple patient financial data from EHR core systems across Australian regional health districts. |
| Acquisition of Specialist Firm | Mid-market billing module vendors in Australia and New Zealand enable modular procurement strategies. |
| Geographic Expansion | Offline-capable platforms capture first-mover advantages in Indonesia's provincial hospital networks outside Java. |
| Strategic Partnership | Localized medical coding database partnerships accelerate Vietnamese-language payer rule engine configuration. |
| Product Launch | Subscription-based SaaS tiers align operational expenditure with Apollo and Max Healthcare expansion phases in tier-2 Indian cities. |
Research Methodology
Desk research of hospital procurement databases, GPO contracts, and regulatory filings preceded structured interviews with hospital CIOs, revenue cycle directors, health system procurement committees, and interoperability engineers across India, Australia, and Southeast Asia. Primary fieldwork with platform vendors and implementation specialists combined with secondary validation from CDSCO guidance documents, Australia's My Health Record technical specifications, and Japan's METI digitization standards. Bottom-up sizing of software, services, analytics, and consulting segments triangulated against top-down expenditure estimates from public hospital digitization budgets and private insurer IT capex disclosures.
Variance decomposition across deployment models, end-user cost tiers, and functional applications anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product architecture, cloud versus on-premise infrastructure, clinical setting scale, and claims-billing-registration-recovery workflow modules. CAGRs derived from logistic adoption curves fitted to procurement timeline compression observed at Queensland Health and New South Wales regional districts, with ICD-11 migration schedules and PLI scheme incentive windows as industry-specific forecast inputs.
Forecasts assume regulatory continuity in India's CDSCO data-localization guidelines, Australia's OAIC privacy frameworks, and Japan's METI audit trail retention mandates; material policy shifts would require re-modeling of vendor compliance cost structures and data residency configuration requirements. Revision becomes warranted when HL7 FHIR implementation talent scarcity crosses thresholds that delay deployment timelines beyond health system procurement windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Global Patient Flow Management Solutions Market
Healthcare IT
E-Prescribing Systems Market
Healthcare IT
Medical Specimen Tracking System Market
Healthcare IT
Healthcare Contact Center Solution Market
Healthcare IT
Healthcare IT Market
Healthcare IT
Global Pharmacy Management System Market
Healthcare IT
US Urgent Care Center Software Market
Healthcare IT
Global Pharmaceutical Quality Management Software Market
Healthcare IT
Healthcare Ediscovery Market
Healthcare IT
Pharmaceutical Quality Management Systems Market
Healthcare IT
US Practice Management Systems Market
Healthcare IT
Healthcare Enterprise Software Market
Healthcare IT
North America Wireless Healthcare Market
Healthcare IT
Healthcare Credentialing Software Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market
Healthcare IT
Hospital Workforce Management Software Market