
 Global Consumer Healthcare Sensor Market | 2026-2036
Global Consumer Healthcare Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Consumer Healthcare Sensor Market Foresight
Asian semiconductor fabrication capacity is shifting toward biosensor-dedicated wafer lines as consumer health devices absorb more MEMS and photonic components. STMicroelectronics leverages its European foundry network to sustain dual-source production of inertial sensors for fitness wearables. Honeywell International Inc. anchors North American supply through its medical-grade pressure sensor division. Abbott Laboratories differentiates via electrochemical glucose sensing expertise that spans consumer and clinical boundaries.
Consumer healthcare sensors are electromechanical or photonic transducers that convert physiological signals into quantifiable digital outputs, typically operating within precision ranges of ±2% for Class II medical applications and enabling continuous biomarker tracking without clinical supervision. Their primary commercial purpose is to democratize preventive diagnostics by embedding clinical-grade measurement into daily-use consumer electronics. Wearable sensors and smart patches now capture the largest addressable base as skin-interfaced form factors achieve multi-day adhesion and wireless power transfer. Optical technology leads in unit volume due to pulse oximetry and PPG heart-rate modules saturating wrist-worn devices, while electrochemical platforms command premium positioning through enzymatic biosensing for metabolic indicators. Fitness tracking applications remain mature with compressed margins, whereas chronic disease management and sleep analysis concentrate margin pools through subscription-linked data services and diagnostic-grade validation requirements.
FDA 510(k) clearance pathways and CE marking under the EU MDR create divergent compliance burdens that filter market access for non-validated entrants, with FDA emphasizing predicate device equivalence and the EU requiring updated clinical evidence under stricter post-market surveillance. Japan's PMDA and South Korea's MFDS impose additional localization testing that extends certification timelines for foreign manufacturers. China's NMPA now requires in-country clinical trials for connected health devices transmitting data to cloud platforms. Stakeholders must monitor regulatory fragmentation across these jurisdictions as data-localization mandates and cybersecurity add-ons reshape product architecture decisions before scale deployment.
Market Dynamics
Telehealth providers now mandate medical-grade accuracy in wearable sensors, forcing component suppliers to bridge the gap between consumer electronics tolerances and FDA 510(k) predicate equivalence for remote patient monitoring deployments.
Growth Catalysts
- EU MDR post-market surveillance mandates:Stricter clinical evidence requirements under the EU Medical Device Regulation are filtering out non-validated competitors and consolidating demand around certified suppliers with established quality management systems.
- Aging-in-place infrastructure buildouts:Government programs in Japan, Germany, and the United States are subsidizing connected health device procurement for elderly populations requiring continuous biomarker tracking without clinical supervision.
- Photonic integration:MEMS and photonic component convergence is enabling multi-sensor fusion in skin-interfaced form factors, expanding the addressable use cases beyond fitness into chronic disease management.
Market Restraints
- Wafer capacity allocation:Asian semiconductor fabrication lines dedicated to biosensor production face competing demand from automotive and industrial MEMS, creating input bottlenecks for consumer health device manufacturers.
- FDA predicate device scarcity:The 510(k) pathway's emphasis on substantial equivalence to legally marketed devices limits novel sensor modalities without predicate matches, extending regulatory timelines for breakthrough form factors.
- Enzymatic biosensor stability:Electrochemical glucose and lactate sensors suffer from protein denaturation and calibration drift, constraining wearable deployment to short-duration applications despite clinical demand for multi-day adhesion.
Strategic Opportunities
- Sleep analysis subscription services:Diagnostic-grade validation requirements for overnight oximetry and respiratory monitoring are concentrating margin pools in data-analytics platforms rather than hardware alone.
- India PLI scheme for electronics manufacturing:Production-linked incentives for medical device assembly are attracting contract manufacturers to establish sensor packaging and testing facilities serving domestic and export markets.
- Wireless power transfer convergence:Elimination of physical charging ports in skin-interfaced patches is enabling hermetic sealing for swimming and showering use cases, opening premium positioning in continuous monitoring.
Industry Challenges
- Cybersecurity architecture redesign:China's NMPA in-country clinical trial requirements for cloud-connected devices are forcing foreign manufacturers to restructure data-localization protocols before scale deployment.
- Multi-jurisdiction certification sequencing:Divergent FDA 510(k), EU MDR, Japan PMDA, and South Korea MFDS timelines create portfolio management complexity, with post-market surveillance obligations in Europe requiring dedicated regulatory affairs headcount.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Consumer Healthcare Sensor Market |
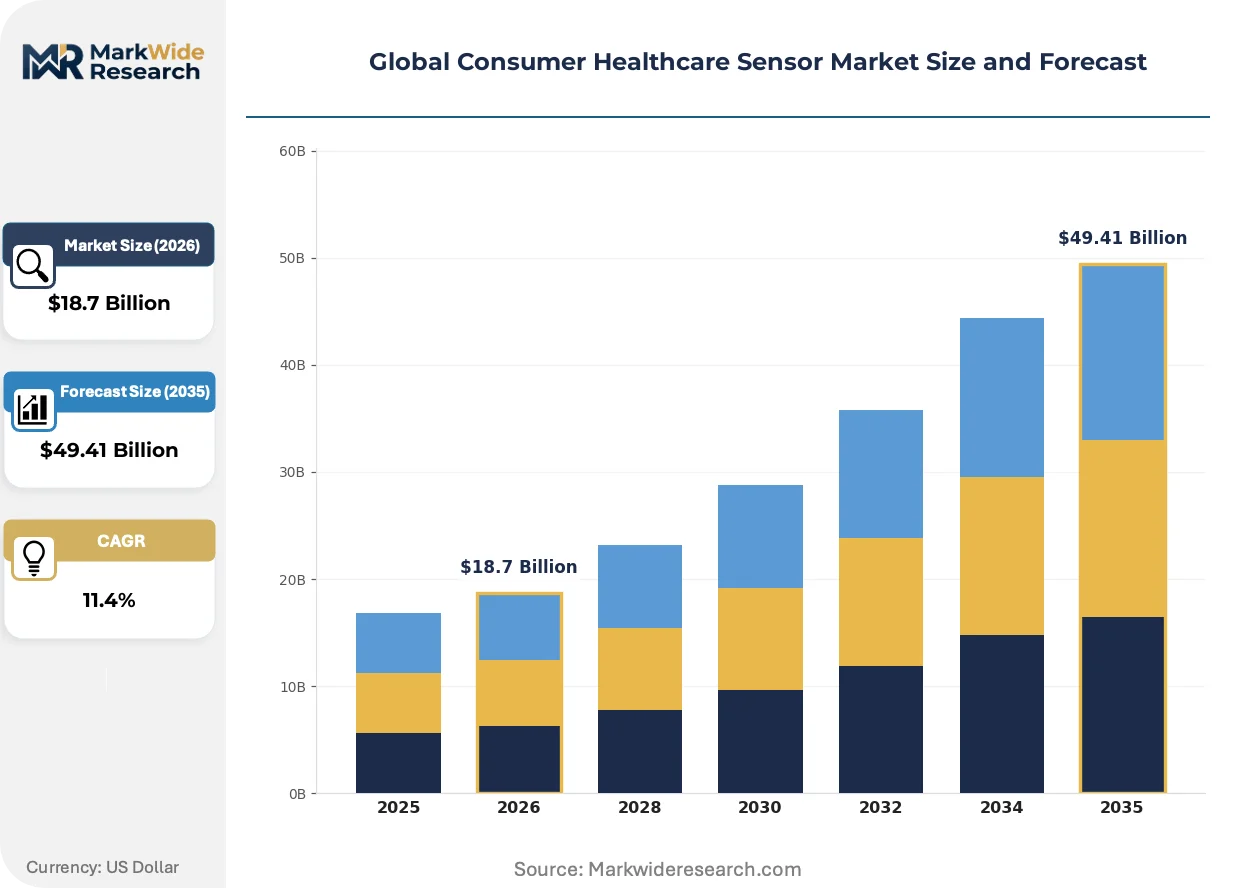
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Implantable Sensors, Portable Monitors, Smart Patches, Contactless Sensors Technology: Optical, Electrochemical, Piezoelectric, Capacitive, Thermoelectric, Acoustic Application: Vital Sign Monitoring, Chronic Disease Management, Fitness Tracking, Sleep Analysis, Stress Detection End User: Individual Consumers, Fitness Centers, Telehealth Providers, Wellness Clinics, Pharmaceutical Companies |
| Companies Covered | Analog Devices Inc., Koninklijke Philips, GE Healthcare Technologies, Medtronic plc, Infineon Technologies AG, STMicroelectronics, Sensirion AG, Abbott Laboratories, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Consumer Healthcare Sensor Market Shifts & Advancements
Optical sensing architectures are compressing hardware margins while software-defined biomarker extraction is electrifying competitive differentiation. Three developments are restructuring value capture in consumer healthcare sensors.
Solid-state photoplethysmography arrays with multi-wavelength LED configurations are electrifying the transition from single-point pulse oximetry to continuous blood pressure estimation. Smartwatch manufacturers in the United States and South Korea are integrating these modules at scale, displacing discrete photodiode suppliers with vertically integrated optical engine providers. The structural consequence is margin compression in commodity PPG components and premium capture in algorithm-integrated subsystems.
EU AI Act risk classification for medical decision-support functions is forcing sensor manufacturers to document training data provenance and performance drift monitoring. Devices marketed with diagnostic claims now require conformity assessment procedures that extend CE marking timelines by twelve to eighteen months. Germany and France are seeing early enforcement, with notified bodies rejecting submissions lacking algorithm change control protocols.
Hospital-at-home programs are unbundling after-sales service from device procurement, with Medicare Advantage plans in the United States contracting directly with remote monitoring platforms rather than purchasing sensors outright. This shifts buyer concentration from individual consumers to payor procurement committees, compressing switching cycles and demanding enterprise-grade data interoperability. The model is most visible in chronic heart failure and diabetes management verticals.
Global Consumer Healthcare Sensor Market Segmentation
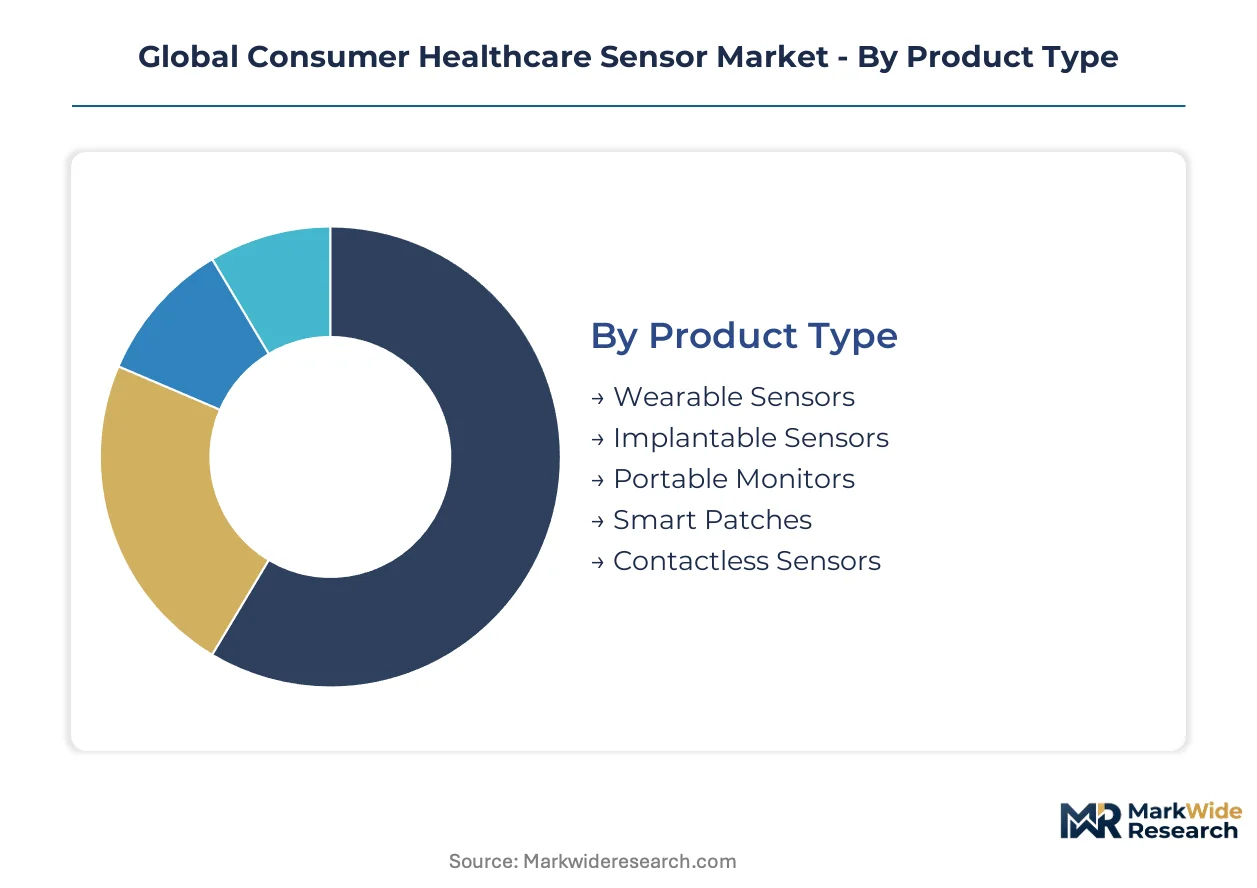
Consumer healthcare sensor procurement patterns diverge sharply across form factors, sensing modalities, and care settings. Upgrade cycles compress where optical modules saturate wrist-worn devices, while medical-grade validation extends replacement timelines for chronic disease applications.
Product Type:
Replacement dynamics vary from annual consumer refresh cycles for fitness wearables to multi-year adhesion timelines for implantable devices, with skin-interfaced form factors dominating upgrade frequency.
- Wearable Sensors:Wrist-worn and clip-on devices integrate PPG, accelerometry, and temperature sensing in sealed polymer housings. Demand concentrates in the United States and South Korea as Apple, Samsung, and Garmin compress hardware refresh cycles to 18-24 months. FDA 510(k) predicate scarcity for novel optical modalities forces incumbents to sustain backward compatibility in sensor fusion architectures.
- Smart Patches:Flexible substrate devices with multi-day adhesive interfaces enable continuous glucose, lactate, and hydration monitoring through enzymatic or impedance-based transduction. Germany and Japan subsidize procurement through aging-in-place infrastructure programs, though enzymatic biosensor stability constraints limit wearable deployment despite clinical demand for week-long adhesion.
- Portable Monitors:Handheld or pocket-sized units for spot-check blood pressure, pulse oximetry, or ECG acquisition.
- Implantable Sensors:Subcutaneous or intracavitary devices for long-term biomarker tracking requiring surgical placement.
- Contactless Sensors:Radar, camera, or thermal imaging systems enabling vital sign extraction without physical skin contact.
Wearable sensors sit at the top of the volume ranking, with smart patches climbing the fastest.
Technology:
Cost tier stratification separates commodity optical modules from premium electrochemical platforms, with photonic integration enabling multi-sensor fusion at mid-range price points.
- Optical:LED-photodiode arrays operating in visible and near-infrared spectra for PPG, pulse oximetry, and spectroscopic glucose estimation. Unit volume saturates wrist-worn devices from Shenzhen to San Francisco, though margin compression in commodity components shifts value capture to algorithm-integrated subsystems.
- Electrochemical:Enzymatic and mediator-based transducers for glucose, lactate, ketone, and cortisol quantification with clinical-grade precision. Abbott and Dexcom anchor North American supply through vertically integrated manufacturing of continuous glucose monitoring filaments.
- Piezoelectric:Ceramic or polymer transducers converting mechanical strain into electrical signals for blood pressure and motion sensing.
- Capacitive:Electrode arrays measuring dielectric property changes for hydration status and body composition analysis.
- Thermoelectric:Temperature gradient sensors for continuous core body temperature monitoring in fertility and metabolic applications.
- Acoustic:MEMS microphones and ultrasonic transducers for respiratory rate, cough detection, and vascular flow characterization.
Optical technology commands the highest shipment volumes, with electrochemical platforms gaining share fastest in chronic disease management verticals.
Application:
Customer type differentiation separates subscription-linked diagnostic services from one-time hardware purchases, with sleep analysis and chronic disease management concentrating recurring revenue pools.
- Chronic Disease Management:Continuous glucose monitoring, cardiac arrhythmia detection, and hypertension tracking requiring FDA 510(k) or EU MDR validation. Medicare Advantage plans in the United States contract directly with remote monitoring platforms, shifting buyer concentration from consumers to payor procurement committees.
- Sleep Analysis:Overnight oximetry, respiratory effort, and EEG-derived sleep stage classification with diagnostic-grade validation requirements. Germany's DGUV and France's ANSM enforce EU AI Act conformity assessments for algorithmic sleep scoring, extending CE marking timelines.
- Vital Sign Monitoring:Spot-check or continuous tracking of heart rate, blood pressure, SpO2, and temperature in acute and ambulatory settings.
- Fitness Tracking:Step counting, calorie estimation, and workout intensity measurement in consumer wearables with compressed hardware margins.
- Stress Detection:HRV-derived sympathetic activation indices and cortisol biomarker correlation for wellness applications.
Fitness tracking maintains the largest installed base, with sleep analysis expanding most quickly through payor reimbursement expansion.
End User:
Supply concentration favors telehealth providers and pharmaceutical sponsors over individual consumers, with enterprise procurement demanding interoperability certifications that filter non-validated suppliers.
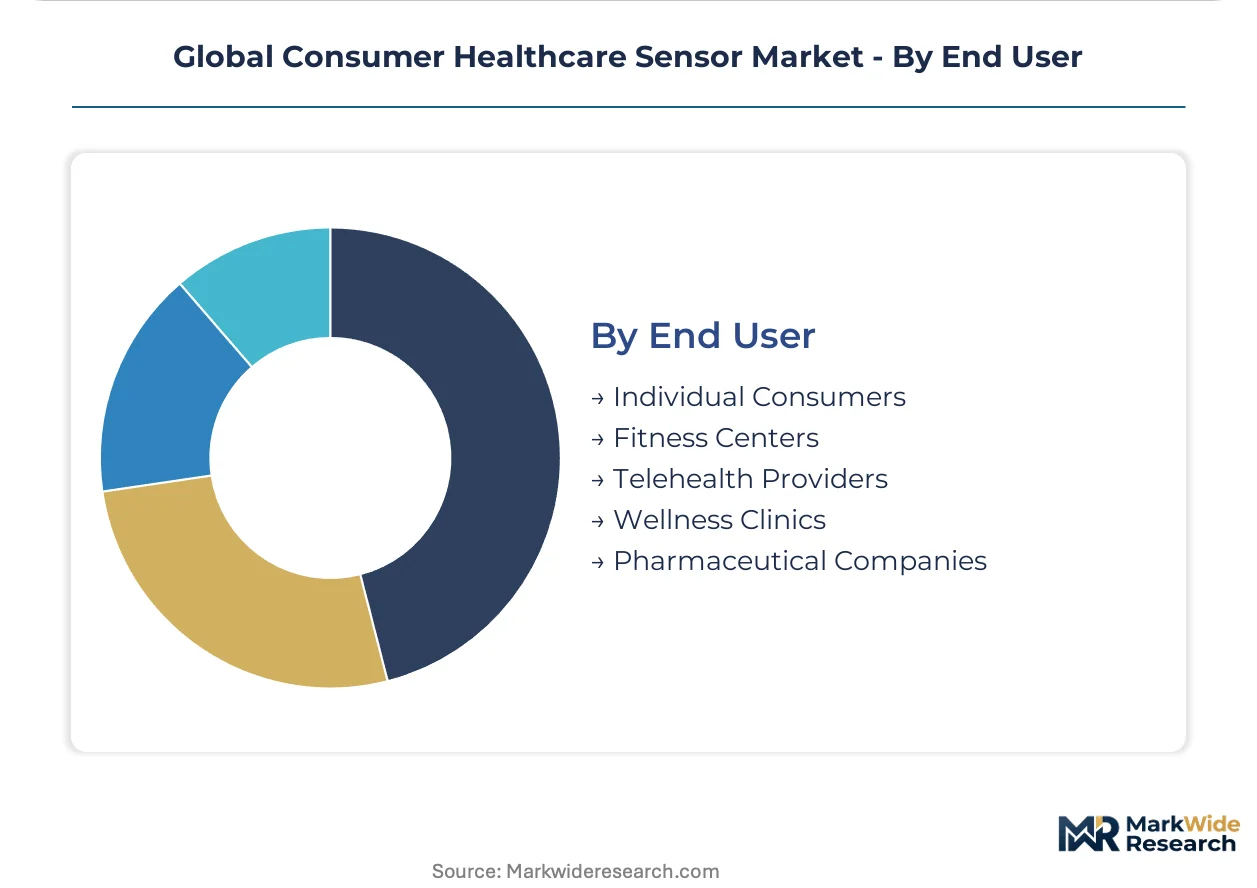
- Telehealth Providers:Remote patient monitoring platforms requiring FDA-cleared sensors with predicate device equivalence for reimbursement eligibility. Teladoc, Amwell, and Livongo mandate medical-grade accuracy in wearable deployments, forcing component suppliers to bridge consumer electronics tolerances and clinical validation thresholds.
- Pharmaceutical Companies:Clinical trial sponsors deploying sensors for decentralized endpoint capture in drug development programs. Japan's PMDA and South Korea's MFDS impose localization testing that extends certification timelines for foreign manufacturers supplying trial-grade devices.
- Individual Consumers:Direct-to-purchaser sales through retail and e-commerce channels with price sensitivity dominating selection criteria.
- Fitness Centers:Corporate wellness programs and gym chains integrating member health tracking into subscription services.
- Wellness Clinics:Concierge and preventive medicine practices offering biometric screening and longitudinal health monitoring.
Individual consumers represent the largest addressable population, with telehealth providers driving the steepest expansion trajectory through hospital-at-home program scale-up.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing manufacturing capacity as cost-of-compliance gaps between jurisdictions widen. Sensor producers are relocating packaging and testing operations to jurisdictions with streamlined certification pathways while maintaining design centers in premium markets.
United States
Medicare Advantage hospital-at-home programs are driving procurement volume for FDA 510(k)-cleared remote monitoring devices. The FDA's predicate device equivalence requirements filter market access for novel sensor modalities. Boston and San Francisco Bay Area clusters concentrate algorithm development and clinical validation operations for telehealth-integrated platforms.
Germany
Aging-in-place infrastructure subsidies are accelerating demand for continuous biomarker tracking devices among elderly populations. EU MDR post-market surveillance mandates and EU AI Act conformity assessments extend CE marking timelines for algorithm-integrated sensors. Munich and Stuttgart industrial corridors host precision manufacturing operations serving both domestic and export markets.
Japan
Government programs subsidizing connected health device procurement for aging populations are expanding the addressable market for skin-interfaced sensors. PMDA localization testing requirements extend certification timelines for foreign manufacturers. Tokyo-Osaka industrial belt concentrates MEMS fabrication and electrochemical sensor assembly operations.
China
NMPA in-country clinical trial mandates for cloud-connected devices are forcing foreign manufacturers to restructure data-localization protocols. Domestic production-linked incentives for medical device assembly are attracting contract manufacturers. Yangtze River Delta and Pearl River Delta clusters dominate biosensor-dedicated wafer fabrication capacity expansion.
South Korea
Smartwatch manufacturers are integrating multi-wavelength PPG modules at scale, displacing discrete component suppliers with vertically integrated optical engine providers. MFDS localization testing extends certification timelines for trial-grade devices. Seoul Capital Area concentrates consumer electronics OEM procurement and sensor fusion architecture development.
Global Consumer Healthcare Sensor Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue algorithm-integrated premium positioning through diagnostic-grade validation. The vendor base stratifies across three tiers: diversified electronics conglomerates with captive sensor divisions, specialized MEMS foundries serving multiple end-markets, and venture-backed startups targeting single-parameter breakthrough modalities. Competitive moves concentrate on strategic partnerships with telehealth platforms and capacity reservations at Asian semiconductor fabrication lines.
Among diversified technology conglomerates, Analog Devices Inc. and STMicroelectronics exemplify the integrated-device-manufacturer archetype with captive fabrication and broad end-market exposure. Abbott Laboratories occupies a position representing the clinical-validation premium tier, spanning consumer and clinical boundary applications. Honeywell International Inc. anchors the industrial-heritage medical-grade segment with pressure sensing expertise. Infineon Technologies AG and Sensirion AG sit within the specialized-component supplier tier, serving multiple OEM customers across fitness and medical verticals.
| Leading Market Players |
|---|
| Analog Devices Inc. |
| Koninklijke Philips |
| GE Healthcare Technologies |
| Medtronic plc |
| Infineon Technologies AG |
| STMicroelectronics |
| Sensirion AG |
| Abbott Laboratories |
| Honeywell International Inc. |
| Others |
Supply & Pricing Matrix
MEMS fabrication engineers concentrated in Taiwan and South Korea command wage premiums that cascade through three-tier pricing structures separating FDA-cleared medical-grade sensors from consumer fitness modules. Labor-cost differentials between these specialized wafer-fabrication clusters and emerging packaging hubs in India widen spreads between premium electrochemical platforms and commodity optical components.
Pricing Analysis
Distributor margins on wearable sensors compress as direct-to-OEM contracts for telehealth platforms bypass traditional channel layers. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) certification status and algorithm-integrated diagnostic claims. Pricing pressure stems from optical module commoditization in wrist-worn devices, while margins expand in electrochemical biosensors with enzymatic stability patents. Individual consumers exhibit highest price sensitivity in fitness-tracking segments, whereas Medicare Advantage procurement committees prioritize interoperability certifications over unit cost.
Supply Chain Analysis
Workforce availability for precision electrochemical sensor assembly concentrates in Germany, Japan, and the United States where medical-device technician certification programs sustain specialized labor pools. Raw material dependencies span silicon wafers from Taiwan, photonic components from South Korea, and enzymatic reagents from Swiss specialty chemical suppliers. Single-source vulnerability in MEMS foundry capacity creates bottlenecks when automotive demand competes for biosensor-dedicated lines. Distribution runs through GPO contracts for hospital-at-home programs and direct OEM procurement for consumer electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on photonic integration cost-down curves and the shift toward subscription-linked diagnostic services that capture recurring revenue beyond hardware replacement cycles.
For Market Incumbents: Lock in capacity reservations at Asian semiconductor fabrication lines before automotive MEMS demand intensifies biosensor wafer competition. Deepen backward integration into optical engine design to displace discrete photodiode suppliers, while accelerating FDA 510(k) submissions for novel sensor modalities before predicate device scarcity hardens. Telehealth platform consolidation threatens component supplier bargaining power without exclusive data-integration partnerships. For New Entrants and Emerging Players: Solid-state blood pressure estimation algorithms represent a technology-first wedge into the smartwatch supply chain where incumbents lack multi-wavelength PPG arrays. Target sleep analysis subscription services in Germany and France where EU AI Act compliance delays create temporary white space for algorithm-native entrants. Pursue direct contracting with hospital-at-home programs rather than retail channel buildout. For Investors and Strategic Acquirers: Telehealth platforms and pharmaceutical clinical-trial sponsors are the most active acquirers in this space, seeking sensor capabilities for decentralized endpoint capture. Five-to-ten-year viability favors electrochemical biosensor specialists with enzymatic stability IP over commodity optical module producers. Watch FDA breakthrough device designations for novel transduction modalities as inflection signals for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR post-market surveillance mandates extend timelines for algorithm-integrated sensors entering Germany and France. |
| Hospital System Partnership | Medicare Advantage hospital-at-home programs in the United States concentrate procurement through GPO contracts rather than retail. |
| Software Companion Development | Diagnostic-grade sleep scoring algorithms require EU AI Act conformity assessments that filter non-validated entrants. |
| Reimbursement Strategy | FDA 510(k) predicate equivalence unlocks remote patient monitoring reimbursement eligibility for telehealth-integrated sensors. |
| Backward Integration | Captive optical engine production displaces discrete photodiode suppliers in South Korean smartwatch manufacturing. |
Research Methodology
Multiple input streams — sensor manufacturer executives, telehealth platform procurement directors, FDA regulatory consultants, and semiconductor foundry operations managers — were reconciled against secondary validation from FDA 510(k) filings, EU MDR notified body databases, CMS Medicare reimbursement schedules, and Asian trade customs records. Bottom-up unit shipment estimates by form factor and technology modality were cross-checked against top-down market sizing from equipment purchasing patterns across hospital-at-home programs.
Historical volume trajectories were cross-referenced against panel input from biomedical engineers and GPO contracts managers to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include product type, sensing technology, application vertical, and end-user procurement archetype. CAGRs were derived from fitted growth curves incorporating wafer capacity expansion schedules, regulatory approval timelines, and payor reimbursement policy shifts.
The model holds under stable FDA predicate device availability and continued Medicare Advantage hospital-at-home expansion; deviation in EU AI Act enforcement intensity or NMPA data-localization mandates would shift regional demand trajectories. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Middle East and Africa Body Temperature Monitoring Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Brain Monitoring Systems Market
Patient Monitoring
Asia-Pacific Hemodynamic Monitoring Market
Patient Monitoring
Multi-Parameter Patient Monitoring Market
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
MRI Compatible Patient Monitoring Systems Market
Patient Monitoring
Latin America Self -Monitoring Blood Glucose Market
Patient Monitoring
Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Asia-Pacific Respiratory Monitoring Market
Patient Monitoring
Wireless Healthcare Market
Patient Monitoring
South America Cardiac Monitoring Market
Patient Monitoring
Global Fetal and Neonatal Monitoring Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
Middle-East and Africa Hemodynamic Monitoring Market
Patient Monitoring
Compartment Syndrome Monitoring Devices Market