
 South Korea Patient Monitoring Market | 2026-2036
South Korea Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Patient Monitoring Market Analytics
The Ministry of Food and Drug Safety's accelerated digital health approval framework is recalibrating how domestic manufacturers prioritize software-integrated hardware development. Mediana Co., Ltd. leverages its Seoul-based manufacturing footprint to dominate local distribution of bedside monitoring systems. Samsung Electronics Co., Ltd. anchors its position through deep R&D investment in biosensor miniaturization for consumer-facing wearables. SK Telecom Co., Ltd. competes by extending its 5G network infrastructure into hospital-specific private networks for real-time patient data transmission.
Patient monitoring encompasses electronic systems that acquire, process, and display physiological parameters including electrocardiogram waveforms, blood pressure values, glucose levels, and temperature readings through embedded sensors and signal processing algorithms. These systems serve clinical decision-making by enabling continuous or intermittent surveillance of patient status across acute care, ambulatory, and residential environments. Wearable monitors and remote monitors are capturing disproportionate investment attention as reimbursement policies shift toward home-based care models, while fixed monitors retain stable demand in surgical suites and intensive care units where precision and reliability standards are most stringent. Electrocardiogram and glucose monitoring technologies concentrate the largest installed bases, though blood pressure monitoring applications are expanding fastest in homecare settings where hypertension prevalence drives routine self-management protocols.
MFDS device classification rules and the Ministry of Health and Welfare's long-term care insurance standards jointly determine which monitoring modalities qualify for reimbursement and institutional procurement. KHIDI health technology assessment guidelines further shape hospital purchasing committees by mandating cost-effectiveness evidence for premium-tier devices. Stakeholders must track how evolving interoperability mandates between the Ministry of Science and ICT and healthcare providers affect data platform choices and device certification requirements.
Market Dynamics
MFDS digital health approval pathways are compressing time-to-market for software-integrated monitoring devices, forcing domestic manufacturers to restructure R&D pipelines around accelerated clearance timelines rather than traditional hardware-centric development cycles.
Growth Catalysts
- 5G private hospital networks:SK Telecom's infrastructure deployments in Seoul and Busan medical centers enable real-time transmission of high-fidelity physiological data streams, expanding the addressable market for continuous remote surveillance.
- Long-term care insurance expansion:Ministry of Health and Welfare reimbursement standards now cover glucose and blood pressure monitoring for homebound elderly patients, creating institutional pull for ambulatory device procurement.
- Biosensor miniaturization:Advances in flexible electronics and low-power signal processing are enabling patch-form factor monitors that integrate unobtrusively with daily patient routines in metropolitan aging populations.
Market Restraints
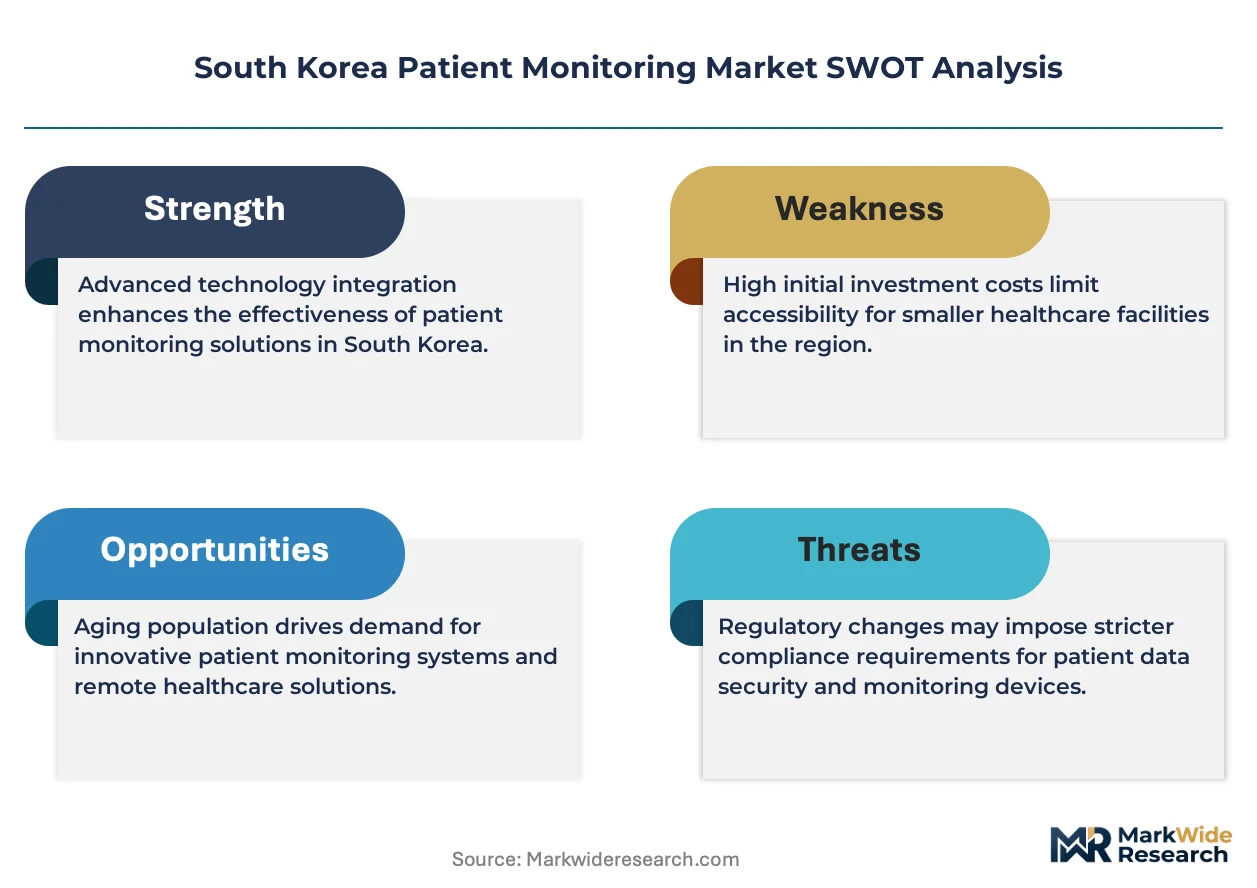
- KHIDI cost-effectiveness mandates:Health technology assessment guidelines require premium-tier device manufacturers to submit multi-center economic evidence, extending sales cycles for advanced monitoring systems.
- Display panel supply concentration:Domestic bedside monitor production depends on imported OLED and high-resolution LCD components, exposing manufacturers to shipping volatility and currency fluctuation risks.
- Interoperability fragmentation:Lack of unified data exchange protocols between Ministry of Science and ICT certification frameworks and hospital legacy IT architectures creates integration friction for new platform deployments.
Strategic Opportunities
- Daegu-Gyeongbuk medical device cluster:Regional government incentives for manufacturing relocation offer tax advantages and subsidized R&D facilities for companies establishing production outside Seoul's cost-intensive zone.
- AI-enabled predictive analytics:Convergence of continuous monitoring data streams with machine learning algorithms creates white space for early-warning systems targeting cardiovascular event detection in tertiary hospital settings.
- Pharmacy channel expansion:MFDS reclassification of select wearable monitors as over-the-counter devices permits direct-to-consumer sales through retail pharmacy networks, bypassing hospital procurement committees.
Industry Challenges
- Embedded software validation:MFDS software-as-a-medical-device requirements demand specialized regulatory affairs expertise that domestic engineering teams often lack, creating hiring bottlenecks.
- Legacy HIS integration:Seoul National University Hospital and Asan Medical Center operate decades-old patient data architectures that resist seamless API connectivity with modern cloud-native monitoring platforms.
- Biocompatibility certification timelines:Skin-contact wearable submissions require extended cytotoxicity and sensitization testing protocols that delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Patient Monitoring Market |
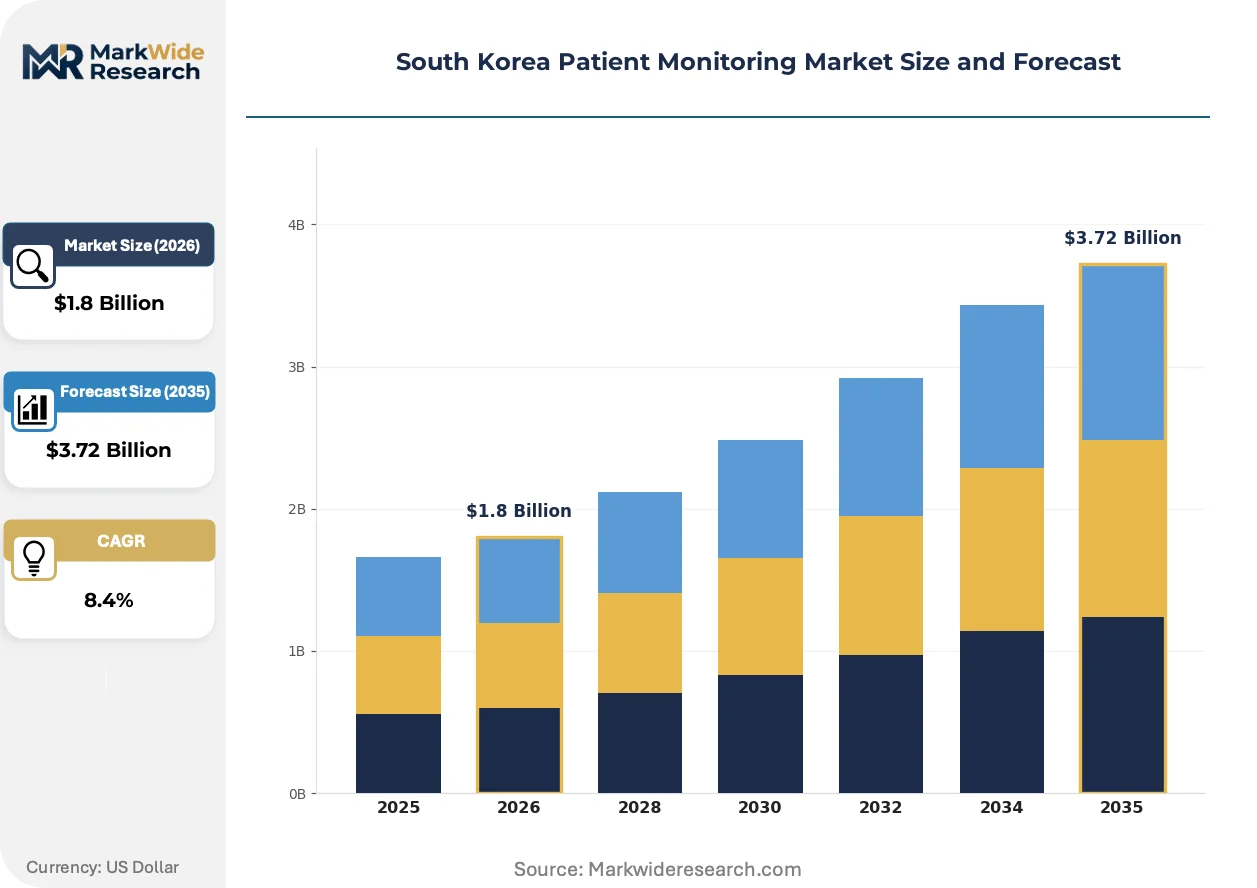
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Wearable Monitors, Portable Monitors, Fixed Monitors, Remote Monitors Technology: Electrocardiogram, Blood Pressure Monitoring, Glucose Monitoring, Temperature Monitoring End User: Hospitals, Homecare Settings, Rehabilitation Centers, Nursing Facilities Application: Chronic Disease Management, Emergency Care, Surgical Care, Wellness Monitoring |
| Companies Covered | Mediana Co., Ltd., GE Healthcare, Samsung Electronics Co., Ltd., Siemens Healthineers, Philips Healthcare, LG Electronics Inc., Nihon Kohden Corporation, Mindray Medical International Limited, SK Telecom Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Patient Monitoring Market Evolving Landscape
Software-defined monitoring architectures are displacing hardware-fixed systems across South Korean healthcare infrastructure, with algorithmic capability rather than sensor specification becoming the primary competitive differentiator in procurement evaluations.
Photoplethysmography-enhanced wearables are rewriting how cardiovascular parameters are captured outside clinical settings. Samsung Electronics and domestic startups deploy multi-wavelength optical sensors in wrist and ring form factors. Tertiary hospitals in Seoul now prescribe these devices for post-discharge arrhythmia surveillance, compressing the traditional gap between acute monitoring and ambulatory care.
MFDS software-as-a-medical-device guidance issued in 2023 is restructuring submission requirements for algorithm-driven diagnostic features. Manufacturers must now validate machine learning models across demographically representative Korean patient cohorts. Blood glucose prediction applications face the steepest compliance burden, with sponsors required to demonstrate non-inferiority against laboratory reference methods.
Hospital purchasing committees are unbundling device procurement from data platform subscriptions, treating connectivity infrastructure as a separate vendor decision. Asan Medical Center and Severance Hospital have issued distinct RFPs for monitoring hardware and cloud analytics in 2024. This bifurcation favors specialized software firms over integrated device manufacturers in Seoul's most influential academic medical centers.
South Korea Patient Monitoring Market Segmentation
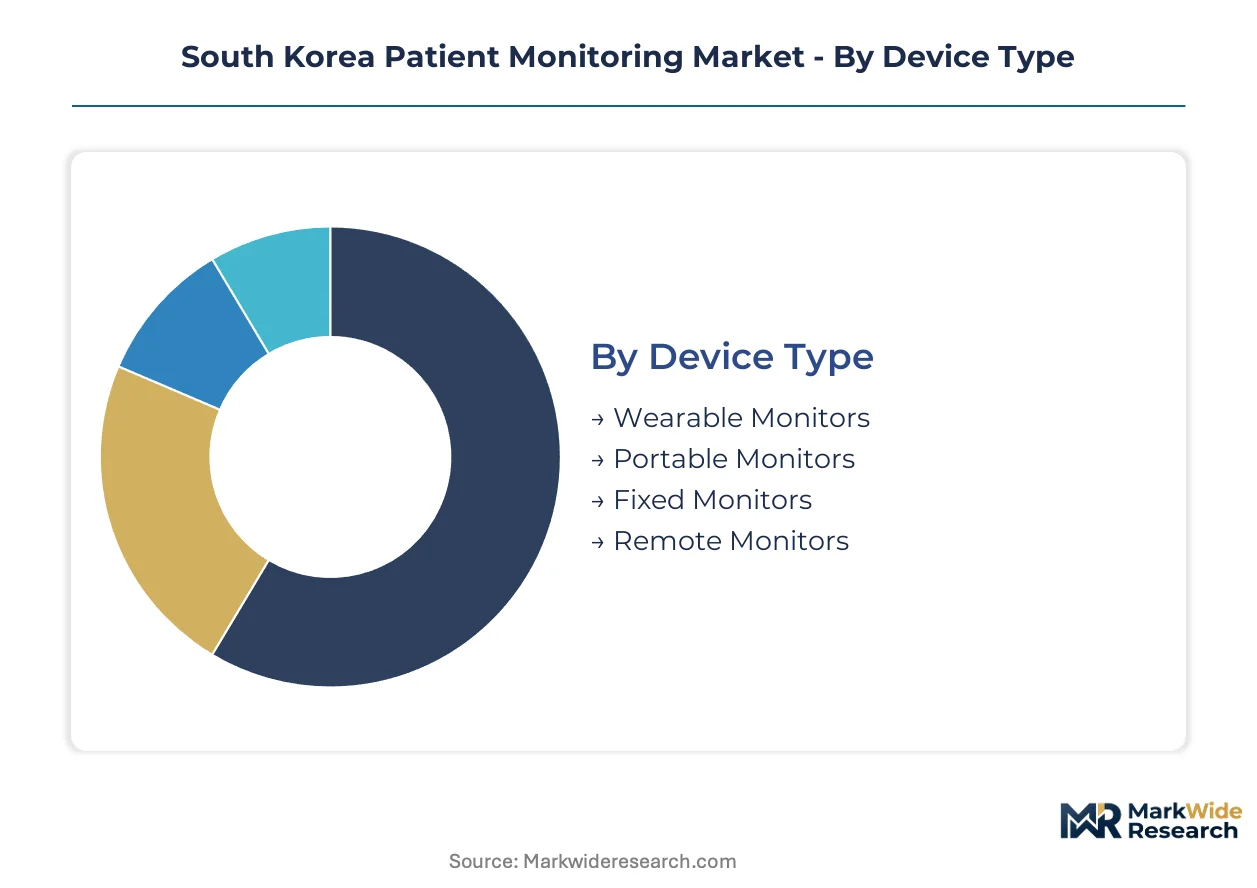
Patient monitoring systems fragment across multiple technical and operational dimensions that determine procurement pathways, reimbursement eligibility, and integration complexity. Understanding these segment boundaries clarifies where capital deployment concentrates and which technology trajectories reshape competitive positioning.
Device Type:
Capital requirements vary dramatically across form factors, with fixed installation systems demanding the heaviest upfront infrastructure investment while wearable platforms prioritize R&D expenditure over manufacturing scale.
- Fixed Monitors:Bedside and central station systems integrate multi-parameter acquisition modules with high-resolution display panels and alarm management software. Tertiary hospitals in Seoul and Busan anchor demand for these units, though procurement cycles extend due to KHIDI cost-effectiveness documentation requirements.
- Wearable Monitors:Patch and wrist-worn devices employ flexible biosensors and low-power wireless chipsets for ambulatory physiological tracking. MFDS reclassification of select models as over-the-counter devices accelerates pharmacy channel penetration in metropolitan aging populations.
- Portable Monitors:Handheld multi-parameter units serve emergency transport and bedside-to-bedside patient transfer scenarios with battery-optimized designs.
- Remote Monitors:Cloud-connected hub systems aggregate data from distributed sensors for centralized clinical surveillance, with SK Telecom's 5G private networks enabling real-time transmission in Seoul medical centers.
Most installed capacity flows through Fixed Monitors. Expansion is steepest in Wearable Monitors.
Technology:
Sensor modality selection determines regulatory pathway complexity, with invasive glucose measurement facing steeper MFDS validation burdens than optical cardiovascular detection methods.
- Glucose Monitoring:Continuous interstitial glucose sensors and flash monitoring systems target diabetes management in homebound elderly patients now covered under expanded long-term care insurance standards. MFDS software-as-a-medical-device guidance imposes rigorous machine learning validation requirements for predictive glucose algorithms.
- Electrocardiogram:Multi-lead diagnostic systems and single-lead screening wearables capture cardiac electrical activity through electrodes and photoplethysmography enhancement. Post-discharge arrhythmia surveillance programs at Seoul National University Hospital and Asan Medical Center drive ambulatory ECG device prescription volumes.
- Blood Pressure Monitoring:Oscillometric cuff devices and emerging cuffless optical estimation methods address hypertension self-management protocols in residential settings.
- Temperature Monitoring:Continuous skin-surface and core temperature tracking supports infection surveillance and post-surgical recovery monitoring across acute care environments.
Electrocardiogram systems carry the largest installed base. Glucose Monitoring is gaining share fastest among ambulatory care models.
End User:
Procurement authority and reimbursement mechanisms diverge sharply across care settings, with hospital purchasing committees operating under centralized KHIDI guidelines while homecare procurement responds to Ministry of Health and Welfare insurance standards.
- Hospitals:Tertiary academic medical centers and general hospitals deploy comprehensive monitoring infrastructure across ICUs, emergency departments, and step-down units. Asan Medical Center and Severance Hospital have unbundled hardware procurement from cloud analytics subscriptions, reshaping vendor selection criteria.
- Homecare Settings:Individual patients and family caregivers operate consumer-facing devices for chronic condition self-management, with pharmacy retail channels expanding following MFDS over-the-counter reclassifications.
- Rehabilitation Centers:Post-acute facilities employ portable and wearable systems for mobility-preserving physiological surveillance during physical therapy protocols.
- Nursing Facilities:Long-term care institutions integrate remote monitoring hubs with nurse call systems for elderly resident oversight, qualifying for reimbursement under expanded national insurance coverage.
Hospitals dominate capital expenditure. Homecare Settings show the steepest expansion trajectory as reimbursement shifts toward residential care models.
Application:
Clinical use case determines performance specification requirements and data integration depth, with emergency and surgical applications demanding highest-fidelity signal processing while wellness applications prioritize user adherence and comfort.
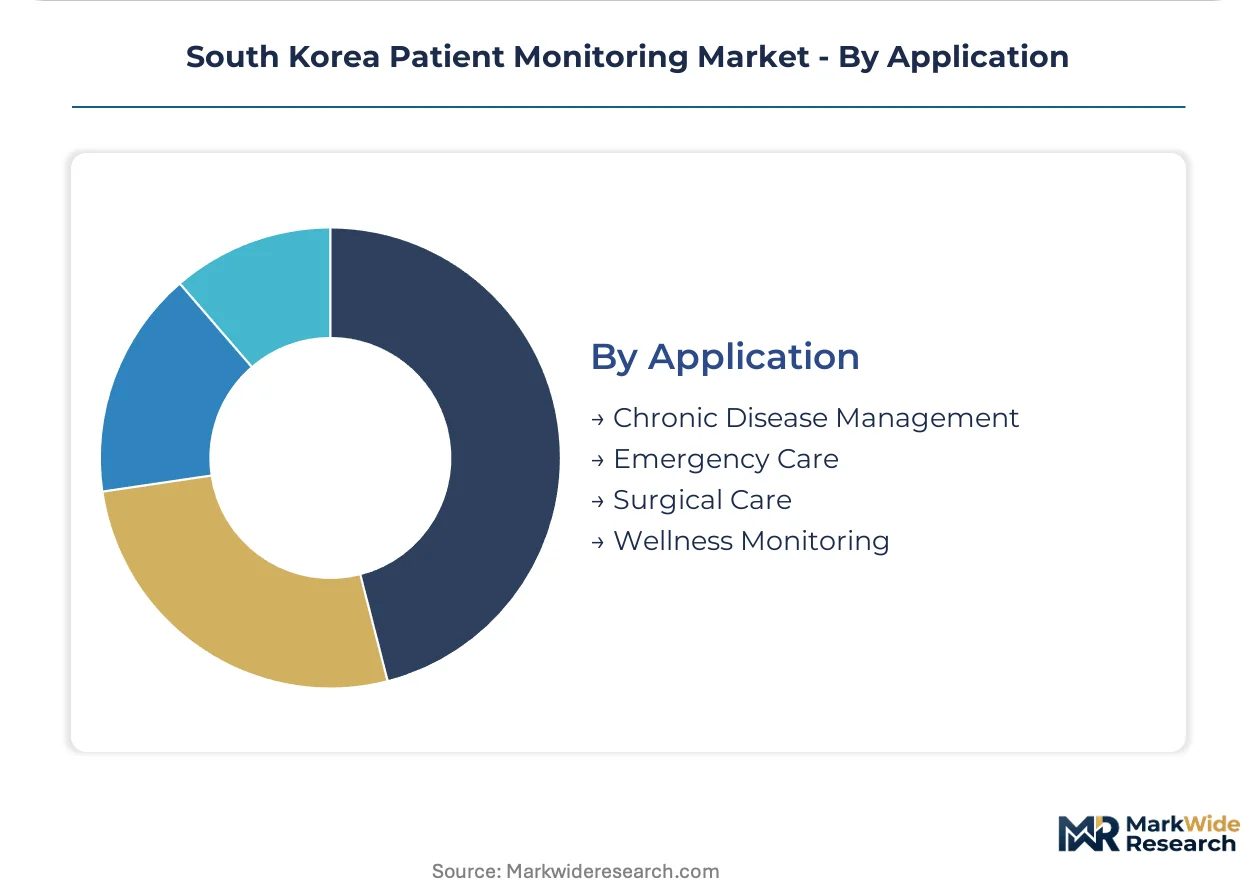
- Chronic Disease Management:Longitudinal monitoring of diabetes, hypertension, and cardiovascular conditions dominates device utilization hours. Biosensor miniaturization enables patch-form factor monitors that integrate unobtrusively with daily routines in Seoul and Busan metropolitan populations.
- Emergency Care:Rapid-deployment portable monitors serve pre-hospital and resuscitation scenarios where signal acquisition speed and artifact rejection capabilities determine clinical utility.
- Surgical Care:Operating room and post-anesthesia care unit applications require invasive pressure monitoring and depth-of-anesthesia sensing with stringent electromagnetic compatibility standards.
- Wellness Monitoring:Consumer-facing fitness and stress tracking applications operate outside clinical reimbursement frameworks, with Samsung Electronics anchoring position through retail distribution networks.
Chronic Disease Management commands the majority of device-hours. Wellness Monitoring is climbing the fastest as consumer health awareness expands in urban demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient monitoring technology in South Korea originated from Seoul's dense concentration of tertiary academic medical centers, where early adoption of multi-parameter bedside systems established the metropolitan corridor as the industry's founding geography before manufacturing capabilities dispersed to secondary cities.
Seoul Capital Area
Asan Medical Center and Severance Hospital drive demand for unbundled hardware and cloud analytics procurement. MFDS digital health approval pathways accelerate software-enabled device clearances for local manufacturers. The Gangnam and Yeongdeungpo districts concentrate headquarters operations for Mediana Co., Ltd. and Samsung Electronics Co., Ltd.
Busan-Ulsan
SK Telecom deploys 5G private hospital networks enabling real-time physiological data transmission. The Ministry of Health and Welfare's long-term care insurance expansion covers glucose and blood pressure monitoring for homebound elderly patients. Ulsan's industrial port infrastructure supports import of OLED and high-resolution LCD components for bedside monitor assembly.
Daegu-Gyeongbuk
Regional government incentives attract manufacturing relocation through tax advantages and subsidized R&D facilities. The Daegu-Gyeongbuk medical device cluster offers lower operational costs than Seoul's cost-intensive zone. Local production facilities serve domestic distribution networks while reducing exposure to shipping volatility.
Daejeon-Sejong
KHIDI health technology assessment guidelines mandate cost-effectiveness evidence for premium-tier devices purchased by government-affiliated research hospitals. The Korea Advanced Institute of Science and Technology anchors biosensor miniaturization research. Sejong's administrative city status attracts regulatory affairs specialists for MFDS software-as-a-medical-device compliance.
Gwangju-Honam
Rehabilitation centers and nursing facilities expand remote monitoring hub installations qualifying for national insurance reimbursement. The region's aging demographic concentration drives pharmacy channel sales of over-the-counter wearable monitors. Local distributors leverage MFDS reclassifications to bypass hospital procurement committees.
South Korea Patient Monitoring Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across South Korea's patient monitoring sector, with integrated device manufacturers maintaining fabrication capabilities while software specialists rely on contract manufacturing partnerships. The market exhibits tiered concentration, with domestic champions defending local distribution against multinational medical technology conglomerates. Three archetypes dominate: Seoul-based integrated manufacturers with captive R&D and production, global healthcare technology multinationals with established service networks, and telecommunications infrastructure providers extending into hospital connectivity. Competitive dynamics center on vertical integration into biosensor supply chains and strategic partnerships with tertiary hospital purchasing committees.
Within the integrated manufacturing tier, Mediana Co., Ltd. exemplifies domestic production scale, while Samsung Electronics Co., Ltd. occupies a position bridging consumer electronics and clinical-grade wearable development. SK Telecom Co., Ltd. represents the infrastructure-provider archetype, leveraging telecommunications assets for healthcare vertical penetration. These three Seoul-based entities anchor distinct competitive vectors: bedside systems, biosensor miniaturization, and private network deployment.
| Leading Market Players |
|---|
| Mediana Co., Ltd. |
| GE Healthcare |
| Samsung Electronics Co., Ltd. |
| Siemens Healthineers |
| Philips Healthcare |
| LG Electronics Inc. |
| Nihon Kohden Corporation |
| Mindray Medical International Limited |
| SK Telecom Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Captive in-house production of biosensor modules and signal processing chipsets anchors both cost control and premium pricing power for Seoul-based integrated manufacturers competing against import-dependent assemblers. This vertical integration choice separates Mediana and Samsung Electronics from competitors tethered to foreign component sourcing, enabling margin defense against OLED panel price volatility and currency fluctuation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with KHIDI cost-effectiveness certification and MFDS software validation tier separating tiers. Price differentiation hinges on algorithmic capability depth and after-sales service bundling rather than hardware specifications alone. Cost compression in the standard tier intensifies because SK Telecom's 5G infrastructure commoditizes connectivity features. Homecare buyers show highest price sensitivity; tertiary hospital purchasing committees prioritize total cost of ownership over unit price.
Supply Chain Analysis
Dual-sourcing requirements from Asan Medical Center and Severance Hospital mandate qualified suppliers for both display panels and wireless chipsets, forcing manufacturers to maintain relationships across Taiwan, Japan, and domestic foundries. Raw material dependencies center on OLED substrates from LG Display, high-resolution LCD glass, and low-power Bluetooth SoCs. Single-source vulnerability concentrates in advanced biosensor membranes imported from Japanese specialty chemical producers. Distribution runs through hospital GPO contracts for fixed monitors and pharmacy retail networks for wearable devices following MFDS over-the-counter reclassification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's patient monitoring sector functions as a stable compounder, with MFDS regulatory acceleration and long-term care insurance expansion providing predictable demand tailwinds across the analysis window.
For Market Incumbents: Anchor market position through backward integration into flexible biosensor substrate production and captive software validation teams that reduce MFDS submission timelines. Cloud-native platform entrants threaten hardware-centric revenue streams; defend by unbundling analytics subscriptions from device sales to match Asan Medical Center's procurement preferences. Prioritize certification investment in AI-enabled predictive algorithms for cardiovascular event detection. For New Entrants and Emerging Players: Launch via pharmacy channel partnerships targeting Gwangju-Honam's aging demographic concentration, bypassing Seoul's saturated hospital procurement committees. The Daegu-Gyeongbuk medical device cluster offers lowest-cost manufacturing entry with regional tax incentives and subsidized R&D facilities. Target blood pressure monitoring applications in homecare settings where reimbursement coverage is expanding fastest under Ministry of Health and Welfare standards. For Investors and Strategic Acquirers: Roll-up economics work for specialized software firms with validated machine learning models because hospital purchasing committees now separate hardware and cloud analytics procurement decisions. Five-to-ten year viability favors asset-light algorithm developers over capital-intensive device manufacturers. Watch MFDS software-as-a-medical-device clearance velocity as the inflection signal for platform valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Software-as-a-Medical-Device Submission | Accelerated clearance timelines compress competitive moats for algorithm-enabled diagnostics. |
| 5G Private Hospital Network Deployment | SK Telecom's infrastructure creates real-time data transmission standards that reshape device connectivity requirements. |
| Backward Integration into Biosensor Substrates | In-house production of flexible electronics reduces exposure to Japanese import volatility and currency risk. |
| Pharmacy Channel Expansion | MFDS over-the-counter reclassification unlocks direct-to-consumer distribution outside hospital procurement. |
| AI-Enabled Predictive Analytics Development | Machine learning validation across Korean patient cohorts creates differentiation in tertiary hospital RFPs. |
Research Methodology
Direct dialogue with hospital purchasing committee members, biomedical engineers at Seoul National University Hospital and Asan Medical Center, MFDS regulatory affairs specialists, and GPO contracts managers grounded qualitative insights. Secondary validation drew from MFDS device registration databases, KHIDI health technology assessment publications, Ministry of Health and Welfare reimbursement bulletins, and hospital procurement RFP archives. Bottom-up and top-down triangulation reconciled manufacturer shipment data with institutional purchasing records.
Bottom-up modeling segmented the market across device type, technology modality, end-user setting, and application use case, with particular attention to software-enabled versus hardware-only systems. Top-down validation referenced national healthcare expenditure trends and insurance reimbursement expansion trajectories. CAGRs were derived from installed base evolution and replacement cycle analysis rather than extrapolated shipment growth. Biosensor miniaturization cost curves and 5G infrastructure deployment schedules served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MFDS regulatory timeline delays or KHIDI cost-effectiveness mandate tightening. Deviation in long-term care insurance reimbursement coverage for ambulatory monitoring would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Wrist Blood Pressure Monitors Market
Patient Monitoring
Global IOT Sensors in Healthcare Market
Patient Monitoring
Multi-Parameter Patient Monitoring Market
Patient Monitoring
Mobile Continuous Patient Monitors Market
Patient Monitoring
Middle East and Africa Remote Patient Monitoring Market
Patient Monitoring
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market
Patient Monitoring
Bedside Monitors Market
Patient Monitoring
South Africa Patient Monitoring Market
Patient Monitoring
Middle-East and Africa Hemodynamic Monitoring Market
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
Global Vital Sign Monitoring Market
Patient Monitoring
North America Remote Patient Monitoring Systems Market
Patient Monitoring
Middle East and Africa Patient Monitoring Market
Patient Monitoring
Respiratory Gas Monitors Market
Patient Monitoring
Wearable ECG Monitors Market
Patient Monitoring
Wireless Fetal Monitoring Systems Market