
 Italy Continuous Glucose Monitoring Devices Market | 2026-2036
Italy Continuous Glucose Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Continuous Glucose Monitoring Devices Market Insights
Homecare patients is rotating toward self-managed glucose tracking as Italy's aging population seeks fewer clinic visits. Abbott Diabetes Care leverages its European distribution infrastructure to sustain pharmacy channel dominance across the peninsula. Dexcom Inc anchors its position through reimbursement partnerships with regional health authorities. Medtronic PLC competes on integrated pump-sensor ecosystems that reduce manual intervention.
Continuous Glucose Monitoring Devices are wearable electrochemical sensor systems that measure interstitial glucose levels through a subcutaneous microneedle probe, transmitting data to handheld receivers or smartphones for real-time metabolic management. Flash Glucose Monitoring occupies the largest installed base due to lower per-test cost and simpler user workflow, while Real-time Glucose Monitoring captures the fastest expansion as predictive alerts reduce hypoglycemic events. Patch Sensors concentrate margin pools through disposable recurring revenue models, whereas Integrated Insulin Pumps face slower uptake constrained by endocrinologist training bottlenecks.
Italy's AIFA determines national reimbursement tiers that directly shape patient out-of-pocket costs and regional adoption variance, while CE marking under the EU MDR governs sensor accuracy claims and clinical evidence requirements for market access. The Ministry of Health coordinates with regional diabetes networks to standardize CGM prescribing protocols across Lombardy, Veneto, and Emilia-Romagna. Stakeholders must monitor whether AIFA expands full reimbursement beyond Type 1 patients to capture the prediagnostic segment.
Market Dynamics
AIFA's expanding reimbursement pathways for diabetes technology are compressing patient out-of-pocket costs and accelerating regional adoption variance across Italy's regional health authorities.
Growth Catalysts
- Regional Reimbursement Expansion:Lombardy and Veneto regional health networks now subsidize CGM sensors for Type 2 patients, widening addressable demand beyond traditional Type 1 cohorts.
- Flash Glucose Monitoring:Lower per-test economics and simplified workflows are pulling homecare patients away from fingerstick glucometers toward self-managed metabolic tracking.
- Integrated Pump-Sensor Ecosystems:Closed-loop insulin delivery systems reduce manual intervention burden for aging diabetes populations seeking fewer clinic visits.
Market Restraints
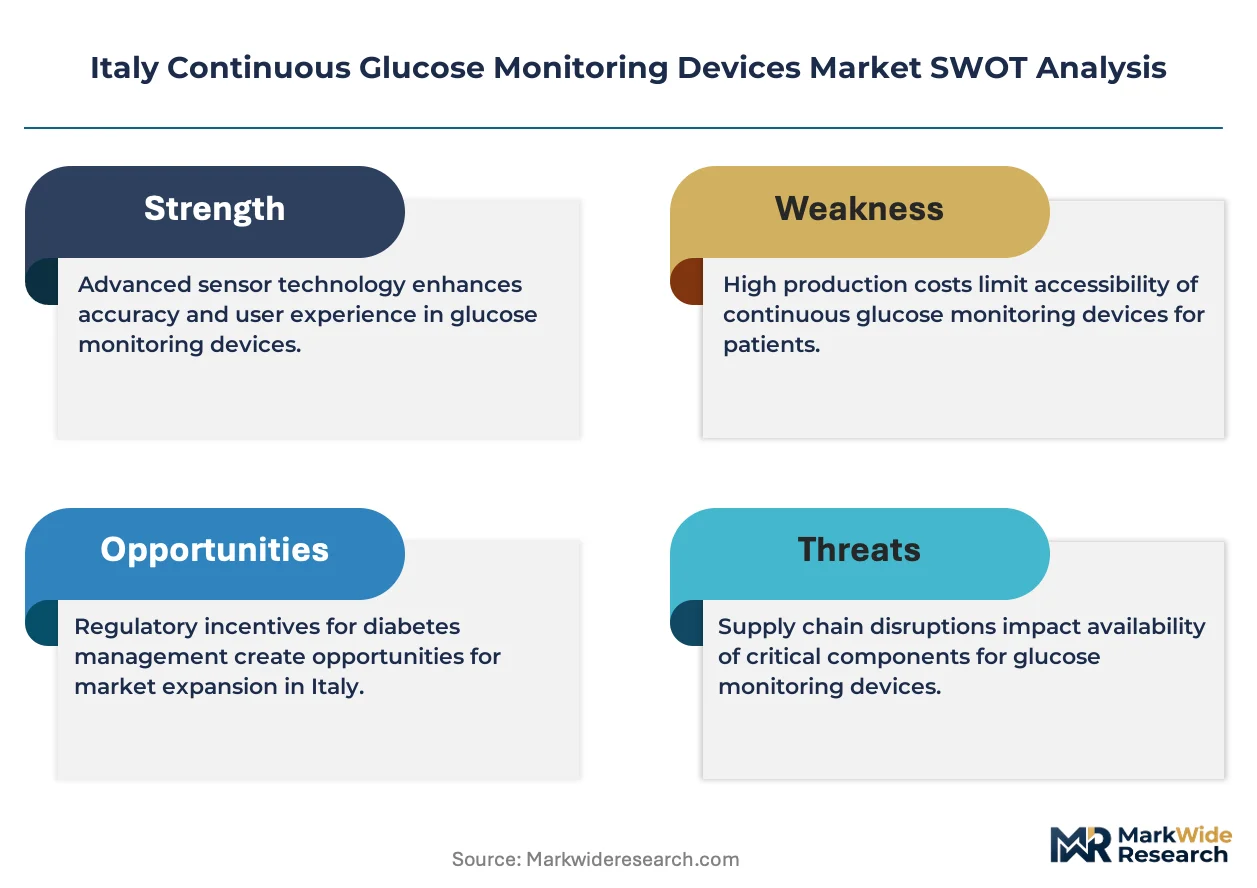
- Endocrinologist Training Bottlenecks:Limited specialist availability in southern provinces slows uptake of integrated pump-sensor systems requiring physician calibration.
- Sensor Input Cost Volatility:Platinum-based electrochemical sensor electrodes face price pressure from precious metal commodity swings affecting disposable manufacturing margins.
- CE Marking Friction:EU MDR clinical evidence requirements for glucose accuracy claims extend regulatory timelines for new sensor entrants seeking Italian market access.
Strategic Opportunities
- Prediagnostic Segment Capture:AIFA's potential expansion of full reimbursement to prediabetic populations would unlock preventive glucose monitoring across Emilia-Romagna's aging industrial workforce.
- Pharmacy Channel Deepening:Direct-to-consumer sensor pickup at Lombardy pharmacy networks bypasses endocrinology appointment delays and captures impulse switching from traditional glucometers.
- Smartphone-Native Telemetry:Bluetooth-enabled patch sensors converging with iOS and Android health platforms eliminate dedicated receiver hardware and reduce patient device burden.
Industry Challenges
- Biocompatibility Certification Timelines:Subcutaneous microneedle polymers require extended cytotoxicity testing under EU MDR, stretching product development cycles for Italian market entry.
- Interoperability Fragmentation:Proprietary data protocols between sensor manufacturers and insulin pump systems force patients into single-vendor ecosystems, limiting switching flexibility.
- Supply Chain Reconfiguration:Northern Italian distribution hubs face last-mile complexity serving dispersed rural diabetes populations in Calabria and Sicily with temperature-sensitive sensor shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Continuous Glucose Monitoring Devices Market |
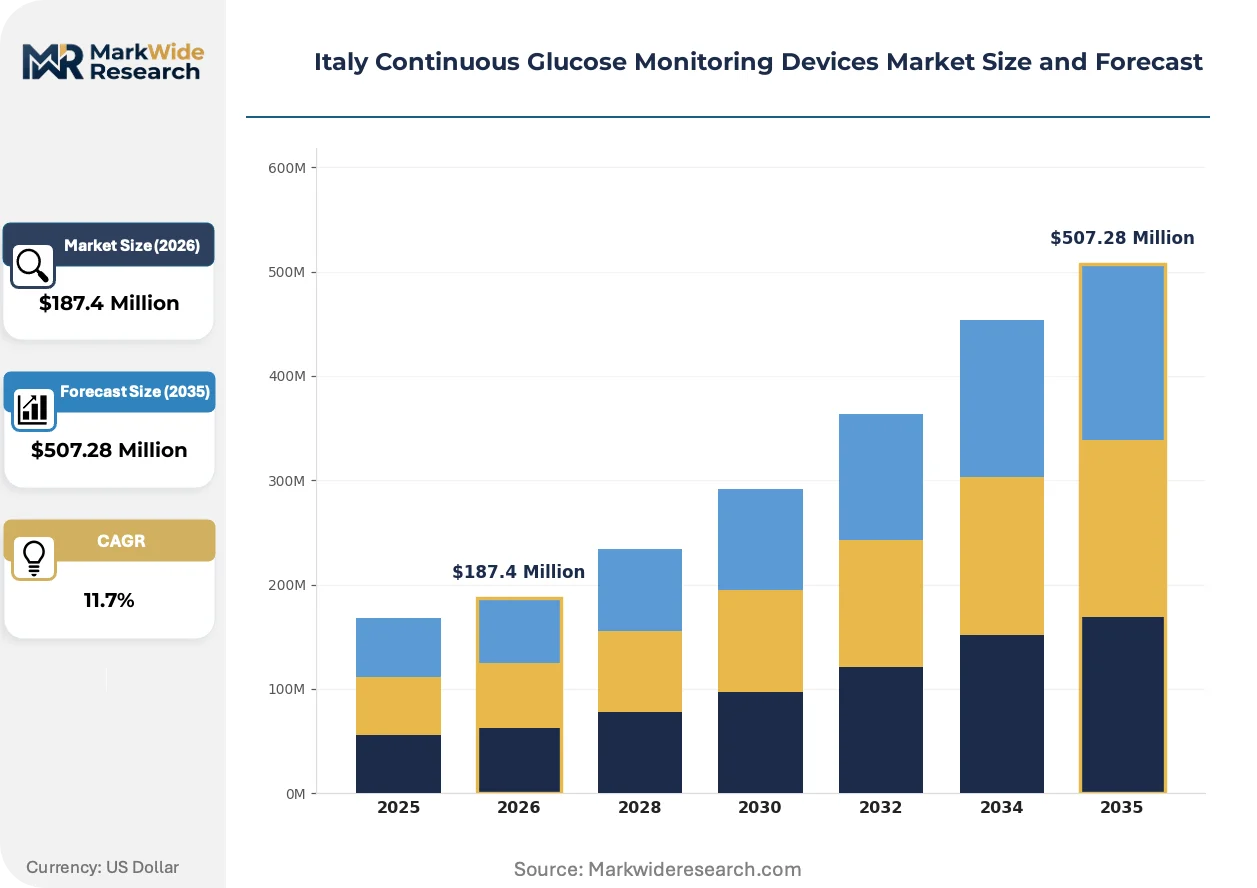
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flash Glucose Monitoring, Real-time Glucose Monitoring, Continuous Glucose Sensors, Integrated Insulin Pumps End User: Consumers, Hospitals, Clinics, Homecare Technology: Microneedle, Electrochemical, Optical, Transdermal Form Factor: Wearable Devices, Mobile Applications, Handheld Monitors, Patch Sensors |
| Companies Covered | Ascensia Diabetes Care, GlySens, Abbott Diabetes Care, Roche Diabetes Care, Senseonics Holdings, Inc, Dexcom Inc, F. Hoffmann-La Roche Ltd, Sibionics, Medtronic PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Continuous Glucose Monitoring Devices Market Trends and Innovations
Wearable glucose telemetry is fragmenting into specialized form factors as patient segments diverge in their tolerance for device complexity and data density.
Non-adhesive microneedle arrays are decomposing the traditional patch sensor form factor. Italian homecare patients with adhesive skin sensitivities are piloting these alternatives through Lombardy regional hospital networks. The technology is compressing the disposable sensor supply chain by eliminating hydrocolloid substrate manufacturing steps.
AIFA's coordination with the Ministry of Health on standardized CGM prescribing protocols is harmonizing regional variance. The framework reduces administrative friction for physicians across Lombardy, Veneto, and Emilia-Romagna. Integrated pump-sensor manufacturers face accelerated documentation requirements while flash monitor vendors gain streamlined pathway access.
Patients are consolidating glucose data management within smartphone-native platforms, displacing dedicated receiver hardware. Italian pharmacy channels report rising demand for Bluetooth-enabled sensors compatible with Apple Health and Google Fit. This behavioral pivot concentrates most visibly among Milan's working-age Type 1 population seeking seamless workplace glucose discretion.
Italy Continuous Glucose Monitoring Devices Market Segmentation
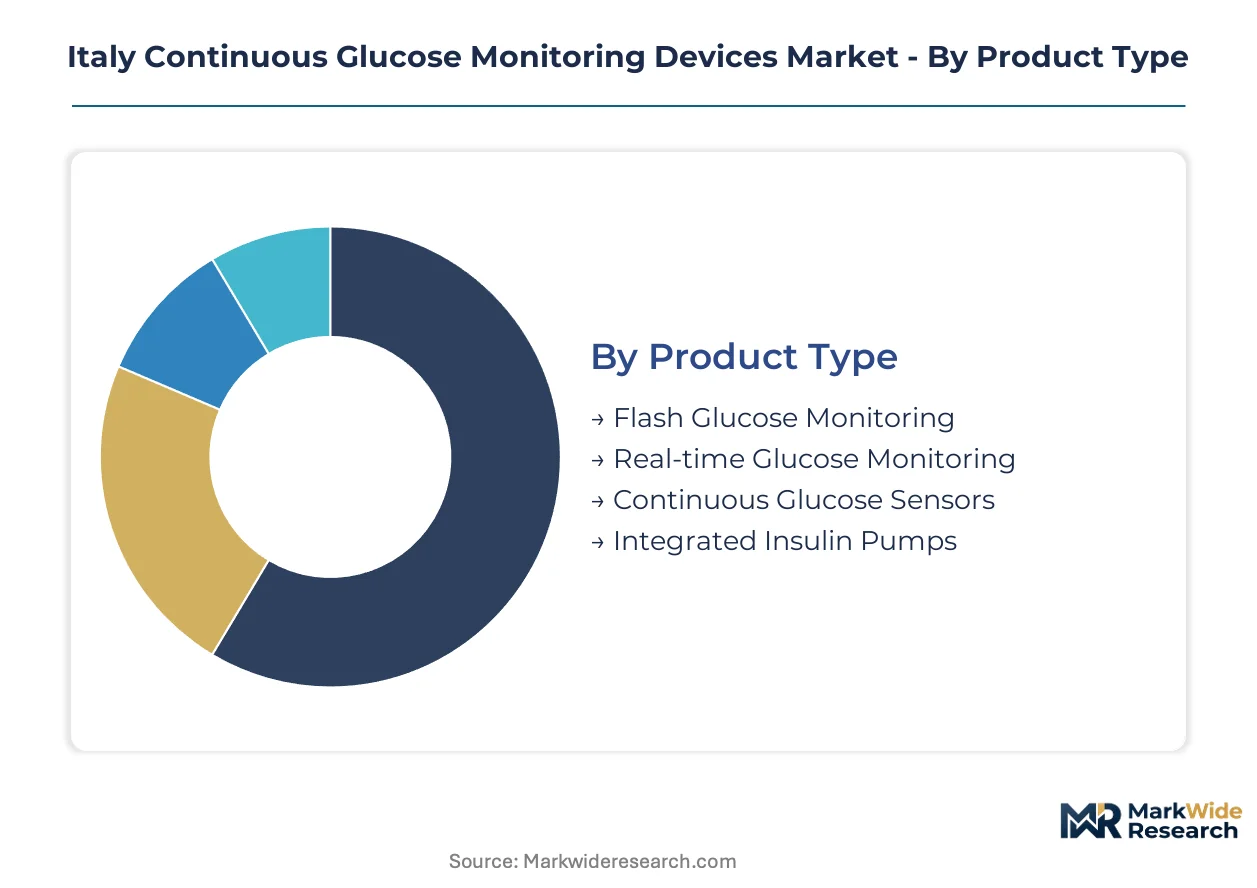
Patient workflow preferences and reimbursement pathways in Italy fragment demand across distinct product architectures. Regional health authority purchasing power concentrates volume in specific technology tiers while homecare expansion reshapes end-user distribution.
Product Type:
Domestic demand concentrates in reimbursed categories with established AIFA coverage, while export-oriented manufacturers push advanced integrated systems through northern industrial clusters.
- Flash Glucose Monitoring:Electrochemical sensor arrays store glucose readings for retrospective download via near-field communication. Lombardy pharmacy networks drive volume as patients bypass endocrinology appointments for sensor pickup. AIFA reimbursement compresses out-of-pocket costs below fingerstick alternatives.
- Real-time Glucose Monitoring:Bluetooth-enabled transmitters stream interstitial glucose data continuously to smartphone displays. Milan's working-age Type 1 population favors this architecture for workplace discretion and predictive hypoglycemic alerts.
- Continuous Glucose Sensors:Disposable subcutaneous probes with 10-14 day wear durations anchor recurring revenue models for patch manufacturers.
- Integrated Insulin Pumps:Closed-loop systems combining sensor input with algorithmic insulin delivery face uptake constraints from endocrinologist training bottlenecks in southern provinces.
Flash Glucose Monitoring holds the largest share; momentum sits with Real-time Glucose Monitoring.
End User:
Procurement authority separates institutional buyers with centralized tender processes from fragmented consumer self-pay channels.
- Homecare:Self-managed patients purchase sensors directly through pharmacy networks or regional reimbursement portals. Aging demographics across Emilia-Romagna's industrial workforce accelerate this segment's expansion as clinic visit avoidance becomes priority.
- Consumers:Prediagnostic individuals seeking preventive monitoring drive emerging demand outside reimbursement boundaries, particularly in northern urban centers.
- Hospitals:Acute care settings deploy CGM for glycemic control in critical care units with inpatient telemetry infrastructure.
- Clinics:Endocrinology practices in Veneto serve as prescription gatekeepers for reimbursed sensor access.
Homecare captures the dominant volume position; Consumers represent the steepest expansion trajectory.
Technology:
Manufacturing complexity and biocompatibility certification timelines stratify competitive entry barriers across sensing modalities.
- Electrochemical:Platinum-based electrodes measure glucose oxidation currents through enzymatic reactions. Mature supply chains in northern Italian distribution hubs support cost-efficient disposable production.
- Microneedle:Subcutaneous polymer arrays penetrate stratum corneum without reaching nerve endings. Extended cytotoxicity testing under EU MDR stretches development cycles for Italian market entrants.
- Optical:Near-infrared spectroscopy attempts non-invasive glucose measurement through dermal tissue, facing accuracy validation challenges.
- Transdermal:Interstitial fluid extraction through minimally invasive membranes remains pre-commercial in Italian clinical settings.
Electrochemical dominates current installed base; Microneedle gains share through form factor innovation.
Form Factor:
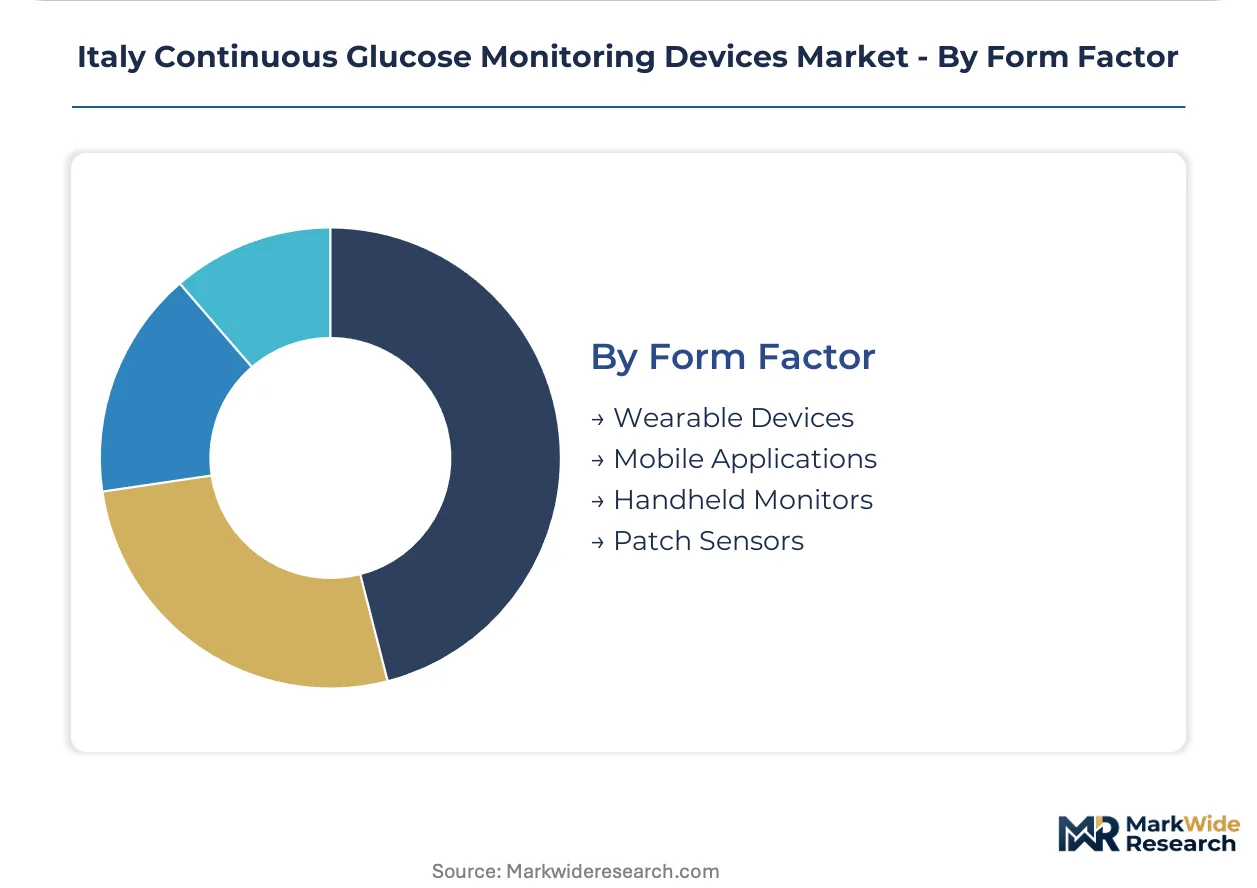
Device burden tolerance varies sharply between pediatric patients, working-age adults, and elderly cohorts managing multiple comorbidities.
- Patch Sensors:Fully disposable adhesive-mounted units eliminate separate transmitter hardware. Temperature-sensitive supply chains face last-mile complexity serving Calabria and Sicily from northern distribution hubs.
- Mobile Applications:Software layers aggregating Bluetooth sensor data into iOS and Android health platforms displace dedicated receiver hardware. Italian pharmacy channels report rising compatibility inquiries for Apple Health and Google Fit integration.
- Wearable Devices:Smartwatch-integrated glucose displays target Milan's fashion-conscious Type 1 demographic seeking discretion.
- Handheld Monitors:Dedicated receiver units persist among elderly populations uncomfortable with smartphone dependency.
Patch Sensors command the largest revenue pool; Mobile Applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Brenner Base Tunnel and Milan-Venice high-speed rail corridor knit northern Italy's industrial diabetes technology clusters into a contiguous logistics network serving sensor distribution across the Alpine arc.
Lombardy
Milan's working-age Type 1 population drives real-time glucose monitoring demand for workplace discretion and predictive alerts. AIFA reimbursement protocols administered through the Lombardy regional health authority compress patient out-of-pocket costs below fingerstick alternatives. Pharmacy networks across the metropolitan area bypass endocrinology appointment delays through direct-to-consumer sensor pickup.
Piedmont
Turin's aging industrial workforce accelerates homecare adoption as clinic visit avoidance becomes priority for diabetes management. The Ministry of Health coordinates standardized CGM prescribing protocols with regional diabetes networks. Medical device distribution hubs in the province face last-mile complexity serving dispersed rural populations with temperature-sensitive sensor shipments.
Veneto
Regional health networks now subsidize CGM sensors for Type 2 patients, widening addressable demand beyond traditional Type 1 cohorts. CE marking under the EU MDR governs sensor accuracy claims for Veneto-based clinical evidence submissions. Endocrinology practices in Verona and Padua serve as prescription gatekeepers for reimbursed sensor access.
Emilia-Romagna
AIFA's potential expansion of full reimbursement to prediabetic populations would unlock preventive glucose monitoring across the region's aging industrial workforce. Bologna's regional hospital networks pilot non-adhesive microneedle arrays for patients with adhesive skin sensitivities. The Po Valley manufacturing corridor supports mature supply chains for electrochemical sensor disposable production.
Lazio
Rome's healthcare procurement authority centralizes tender processes for hospital and clinic CGM deployment across central Italy. The national pharmaceutical regulator determines reimbursement tiers that directly shape regional adoption variance. Academic medical centers in the capital coordinate clinical validation studies for EU MDR market access requirements.
Italy Continuous Glucose Monitoring Devices Market Competitive Landscape
Listed leaders compete with private specialists across reimbursement partnership depth and pharmacy channel penetration. The vendor base stratifies into three tiers: multinational diabetes care divisions with European distribution infrastructure, integrated pump-sensor ecosystem providers, and emerging sensor technology specialists seeking CE marking pathways. Strategic moves concentrate on regional health authority contracting and smartphone-native telemetry integration.
Within the multinational tier, Abbott Diabetes Care, Dexcom Inc, and Medtronic PLC exemplify distinct competitive archetypes. Abbott occupies a position emphasizing pharmacy channel dominance and flash glucose monitoring economics. Dexcom anchors the real-time telemetry vector through reimbursement partnerships with regional health authorities. Medtronic sits within the integrated ecosystem tier competing on closed-loop insulin delivery systems. Roche Diabetes Care and Ascensia Diabetes Care represent European-origin players with established diagnostic device distribution networks. Senseonics Holdings, Inc and GlySens exemplify emerging technology specialists navigating extended EU MDR clinical evidence timelines.
| Leading Market Players |
|---|
| Ascensia Diabetes Care |
| GlySens |
| Abbott Diabetes Care |
| Roche Diabetes Care |
| Senseonics Holdings, Inc |
| Dexcom Inc |
| F. Hoffmann-La Roche Ltd |
| Sibionics |
| Medtronic PLC |
| Others |
Pricing and Supply Chain Analysis
Forty-five-to-sixty-day sensor electrode lead times from Asian platinum suppliers compress margin buffers for Italian patch manufacturers while amplifying volume-discount leverage for multinational distributors with forward-contracted inventory positions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated pump-sensor ecosystems from flash monitors and basic electrochemical patches. CE marking tier and AIFA reimbursement status drive price differentiation, with MDR-certified sensors commanding 15-20% premiums over legacy-marked alternatives. Pricing pressure stems from regional health authority tender consolidation in Lombardy and Veneto, where centralized procurement squeezes per-unit margins. Homecare patients exhibit highest price sensitivity, while hospital systems prioritize accuracy certification over cost.
Supply Chain Analysis
Container availability fluctuations on the Asia-Mediterranean trade lane strain inbound logistics for platinum electrode shipments and polymer substrate materials. Manufacturing concentration rests on Germany, Switzerland, and Ireland for precision electrochemical components, with final assembly gravitating toward northern Italian hubs. Platinum and hydrocolloid adhesive dependencies expose producers to commodity volatility and biocompatibility certification delays. Single-source vulnerability concentrates in enzymatic glucose oxidase suppliers. Distribution runs through temperature-controlled pharmacy networks and regional health authority procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's CGM market functions as a defensive-moat arena where AIFA reimbursement entrenchment and endocrinologist prescribing relationships create switching costs that protect incumbent positions.
For Market Incumbents: Fortify pharmacy channel control through direct-to-consumer sensor pickup partnerships with Lombardy and Veneto regional networks, insulating against emerging Bluetooth-native entrants. Deepen backward integration into electrochemical electrode manufacturing to offset platinum cost volatility. Expand CE marking investment under EU MDR to maintain accuracy-claim advantages over pre-commercial microneedle alternatives.
For New Entrants and Emerging Players: Differentiate on smartphone-native telemetry architecture targeting Milan's working-age Type 1 population seeking workplace discretion. Prediagnostic monitoring in Emilia-Romagna offers the most penetrable white space pending AIFA reimbursement expansion. Pursue pharmacy channel bypass models that eliminate endocrinology appointment friction.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue compounding play because disposable sensor replacement cycles generate predictable cash flows insulated from acute care budget volatility. Acquisition targets should display established regional health authority contracting relationships and MDR certification pathways. Monitor AIFA prediabetic reimbursement policy signals as volume inflection catalyst.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements govern sensor accuracy claims for Italian market access. |
| Regional Health Authority Partnership | Lombardy and Veneto tender processes determine volume allocation across reimbursed categories. |
| Pharmacy Channel Expansion | Direct-to-consumer sensor pickup bypasses endocrinology appointment bottlenecks in northern clusters. |
| Software Companion Development | Bluetooth-enabled iOS and Android integration eliminates dedicated receiver hardware burden. |
| Reimbursement Strategy | AIFA tier positioning directly shapes patient out-of-pocket costs and adoption velocity. |
Research Methodology
Cross-validation between hospital procurement databases and AIFA reimbursement filings anchors the qualitative findings on regional adoption variance. Primary interviews with endocrinologists, hospital purchasing committees, biomedical engineers, and pharmacy network managers combined with secondary validation from CE marking databases, GPO contracts, and regional health authority tender records. Bottom-up sensor volume estimates and top-down market sizing triangulate through northern Italian distribution hub shipment data.
Sensitivity analysis across reimbursement expansion scenarios and platinum price bands stress-tests volume projections over the projection horizon. Segmentation dimensions include product architecture, end-user procurement authority, technology modality, and form factor burden tolerance. CAGRs derive from fitted growth curves applied to AIFA-covered patient cohorts, calibrated against regional diabetes prevalence data and pharmacy channel expansion rates.
Decision-makers should treat outputs as directional under assumptions of stable AIFA reimbursement tiers and EU MDR enforcement continuity; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Diabetic Pen Cap Market
Diabetes Care
Malaysia Diabetes Care Devices Market
Diabetes Care
Global Type 2 Diabetes Treatment Market
Diabetes Care
Global Glucose Monitoring Devices Market
Diabetes Care
Italy Oral Anti-Diabetic Drug Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
Canada Self-Monitoring Blood Glucose Market
Diabetes Care
Continuous Glucose Monitoring Market
Diabetes Care
Type 2 Diabetes Market
Diabetes Care
Vietnam Insulin Drug and Delivery Device Market
Diabetes Care
Combination Anti-Diabetes Drugs Market
Diabetes Care
South Korea Oral Anti-Diabetic Drug Market
Diabetes Care
Diabetic Lancing Devices Market
Diabetes Care
Middle East and Africa Insulin Infusion Pumps Market
Diabetes Care
South Africa Oral Antidiabetic Drug Market
Diabetes Care
Asia-Pacific Diabetes Care Devices Market