
 Patient Scales Market | 2026-2036
Patient Scales Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Scales Market Intelligence
Aluminum load-cell housings are restructuring cost structures across mid-range digital scales, displacing stamped-steel assemblies that dominated prior generations. Seca GmbH leverages captive German fabrication to sustain margin control on clinical-grade platforms. Hillrom anchors North American hospital contracts through integrated room-furniture bundling. Detecto Scale Company differentiates via USDA-certified scales for renal dialysis and bariatric programs.
Patient scales encompass precision weighing instruments engineered for clinical, home, and fitness environments, typically achieving accuracy within 0.1 kg and incorporating load-cell transducers calibrated to ISO 9001 traceability standards. Their primary purpose is to deliver reproducible mass measurement for diagnostic monitoring, pharmaceutical dosing, and therapeutic progression tracking. Digital scales lead volume shipments due to EMR integration demand, while wheelchair scales command premium positioning in long-term care facilities where accessibility compliance drives replacement cycles. Body composition analysis represents the fastest-growing application segment, propelled by metabolic disease management protocols in outpatient clinics.
FDA 510(k) clearance requirements and IEC 60601-1-2 electromagnetic-compatibility standards shape product development timelines and international market access for manufacturers. The EU Medical Device Regulation imposes additional clinical-evidence obligations on Class I measuring devices sold in member states. Stakeholders must monitor evolving cybersecurity annexes to IEC 81001-5-1 as connected-scale deployments expand across health-system networks.
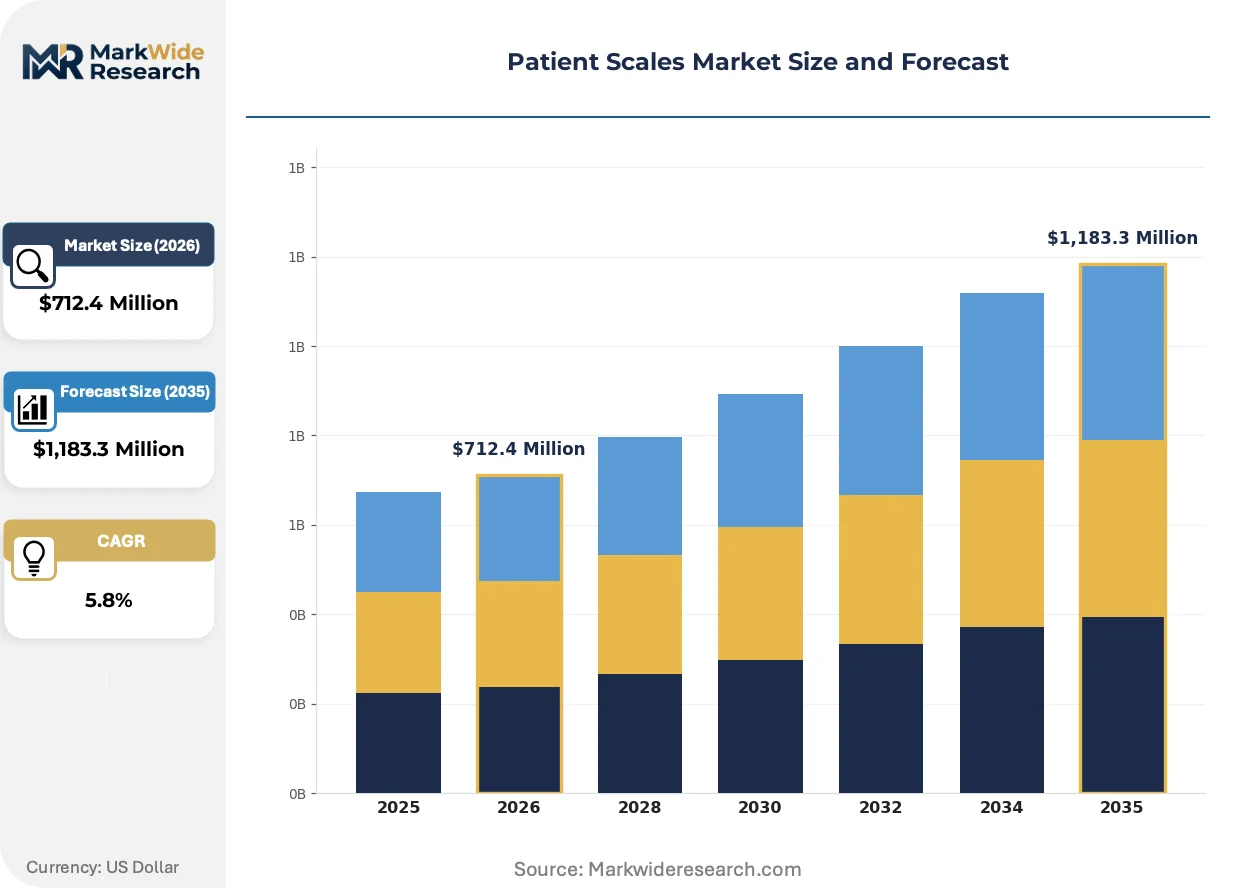
Market Dynamics
EMR integration mandates are forcing hospital procurement departments to prioritize digital connectivity over standalone weighing accuracy, compressing replacement cycles for analog equipment and elevating software certification requirements alongside hardware precision.
Growth Catalysts
- EU Medical Device Regulation:Class I measuring devices now require enhanced clinical evidence, creating upgrade demand among European healthcare facilities seeking compliant platforms.
- Metabolic disease protocols:Outpatient clinics are expanding body composition analysis capabilities to monitor diabetes progression and therapeutic response.
- Aluminum load-cell housings:Mid-range digital scales achieve cost parity with stamped-steel predecessors while improving corrosion resistance in high-humidity clinical environments.
Market Restraints
- Load-cell supply concentration:Strain-gauge manufacturing clusters in Germany and Japan create vulnerability to regional logistics disruptions.
- IEC 60601-1-2 electromagnetic compatibility:Testing protocols for connected scales extend development timelines by 8-14 months and raise non-recurring engineering costs.
- Smartphone health apps:Consumer-grade bioimpedance devices capture low-acuity wellness monitoring, displacing entry-level clinical scale purchases in home care segments.
Strategic Opportunities
- Brazil renal dialysis expansion:ANVISA-certified bariatric platforms face limited domestic competition as public health programs scale chronic kidney disease treatment capacity.
- IEC 81001-5-1 cybersecurity annexes:Connected-scale deployments in health-system networks create first-mover advantage for vendors with validated secure-by-design architectures.
- Long-term care accessibility mandates:Wheelchair scales with integrated ramps and handrails command premium positioning as ADA compliance drives replacement investment.
Industry Challenges
- ISO 9001 traceability calibration:Field service networks require specialized technicians to maintain load-cell certification across distributed hospital footprints.
- Legacy EMR interoperability:Proprietary data formats in older hospital information systems complicate API development for seamless weight-data transmission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Scales Market |
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,183.3 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Scales, Mechanical Scales, Wheelchair Scales, Pediatric Scales End User: Hospitals, Clinics, Home Care, Fitness Centers Technology: Load Cell, Strain Gauge, Electromechanical, Analog Application: Weight Monitoring, Body Composition Analysis, Pediatric Measurements, Geriatric Assessments |
| Companies Covered | Health O Meter, Detecto Scale Company, Seca GmbH, Algen Scale Corp., Hillrom, Tanita, Natus Medical Inc., Doran Scales Inc, Marsden Weighing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Scales Market Strategic Shifts & Innovations
Connectivity architectures and material substitutions are restructuring how precision weighing equipment integrates into clinical workflows and supply chains. Manufacturers are racing to embed intelligence without compromising measurement reliability.
Strain-gauge load-cell assemblies with digital signal conditioning is modularizing platform construction across wheelchair and bed-scale categories. Long-term care facilities in Germany are standardizing on interchangeable sensor modules that reduce field-service downtime. This architecture is modularizing maintenance economics and compressing total cost of ownership calculations for procurement committees.
FDA 510(k) clearance pathways for software-as-medical-device components are tightening evidentiary requirements for scale-integrated algorithms. Manufacturers must now submit clinical validation data for body-fat estimation and metabolic index calculations previously treated as accessory features. North American hospital systems are responding by consolidating vendor relationships to reduce regulatory audit burden across their device portfolios.
Hospital procurement departments are unbundling after-sales service contracts from initial equipment purchases, creating standalone calibration and certification revenue streams. Third-party service providers in Texas and Bavaria are capturing recurring maintenance relationships previously held by original manufacturers. This shift is most pronounced in academic medical centers with centralized biomedical engineering departments capable of in-house ISO 17025 calibration.
Patient Scales Market Segmentation
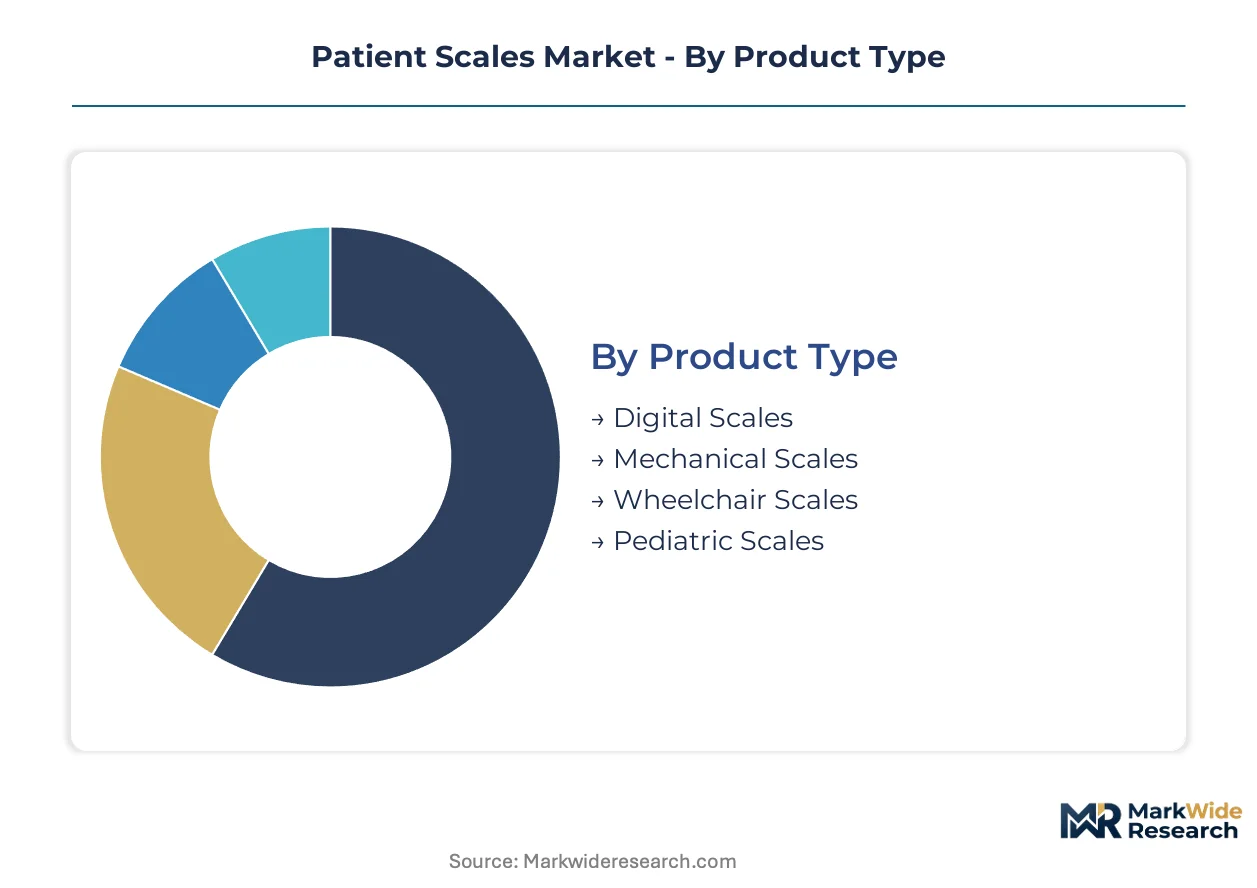
Patient scales fragment across four distinct dimensions where procurement priorities diverge sharply between clinical accuracy mandates and cost containment pressures. Each category reveals how technology choices cascade into regulatory obligations, service economics, and competitive positioning.
Product Type:
Supply concentration among German and Japanese load-cell specialists tilts manufacturing economics toward digitally integrated platforms over mechanical alternatives.
- Digital Scales:Semiconductor-based signal conditioning enables EMR interoperability and automated calibration logging. Hospital procurement departments in Germany prioritize these platforms to satisfy MDR traceability requirements for Class I measuring devices.
- Wheelchair Scales:Integrated ramp systems and handrail configurations address ADA accessibility mandates in long-term care facilities. Premium positioning reflects bariatric capacity ratings and corrosion-resistant aluminum framing.
- Mechanical Scales:Spring-based platforms persist in resource-constrained clinics where electromagnetic interference immunity outweighs connectivity demands.
- Pediatric Scales:Cradle configurations with 10-gram resolution target neonatal units requiring pharmaceutical dosing precision.
Today's leader: Digital Scales. Tomorrow's challenger: Wheelchair Scales.
End User:
Procurement authority concentration determines pricing leverage and service contract structures across institutional versus consumer channels.
- Hospitals:Centralized biomedical engineering departments negotiate enterprise-scale calibration agreements. FDA 510(k) clearance and IEC 60601-1-2 electromagnetic compatibility certification filter vendor pools to established manufacturers with regulatory documentation capabilities.
- Home Care:Consumer-grade bioimpedance devices from smartphone ecosystem vendors erode addressable market for entry-level clinical platforms.
- Clinics:Outpatient metabolic disease protocols drive body composition analysis adoption with lower capital thresholds than hospital systems.
- Fitness Centers:Commercial-grade durability requirements prioritize load-cell redundancy over medical-grade precision.
Hospitals command vendor attention through volume concentration. Clinics are climbing fastest on metabolic protocol expansion.
Technology:
Sensor architecture choices cascade into calibration intervals, field service requirements, and total cost of ownership calculations.
- Load Cell:Wheatstone bridge configurations with digital signal conditioning dominate mid-range and premium segments. Strain-gauge manufacturing clusters in Germany and Japan create supply vulnerability but enable ISO 9001 traceability certification.
- Strain Gauge:Thin-film deposition techniques on aluminum substrates achieve corrosion resistance for high-humidity clinical environments.
- Electromechanical:Hybrid architectures balance mechanical reliability with basic digital output for legacy facility upgrades.
- Analog:Passive resistance networks persist in price-sensitive installations where electromagnetic immunity outweighs data integration needs.
Load Cell anchors current procurement decisions. Strain Gauge variants are expanding most quickly on material substitution trends.
Application:
Clinical workflow integration requirements separate diagnostic-grade investments from wellness-oriented purchases.
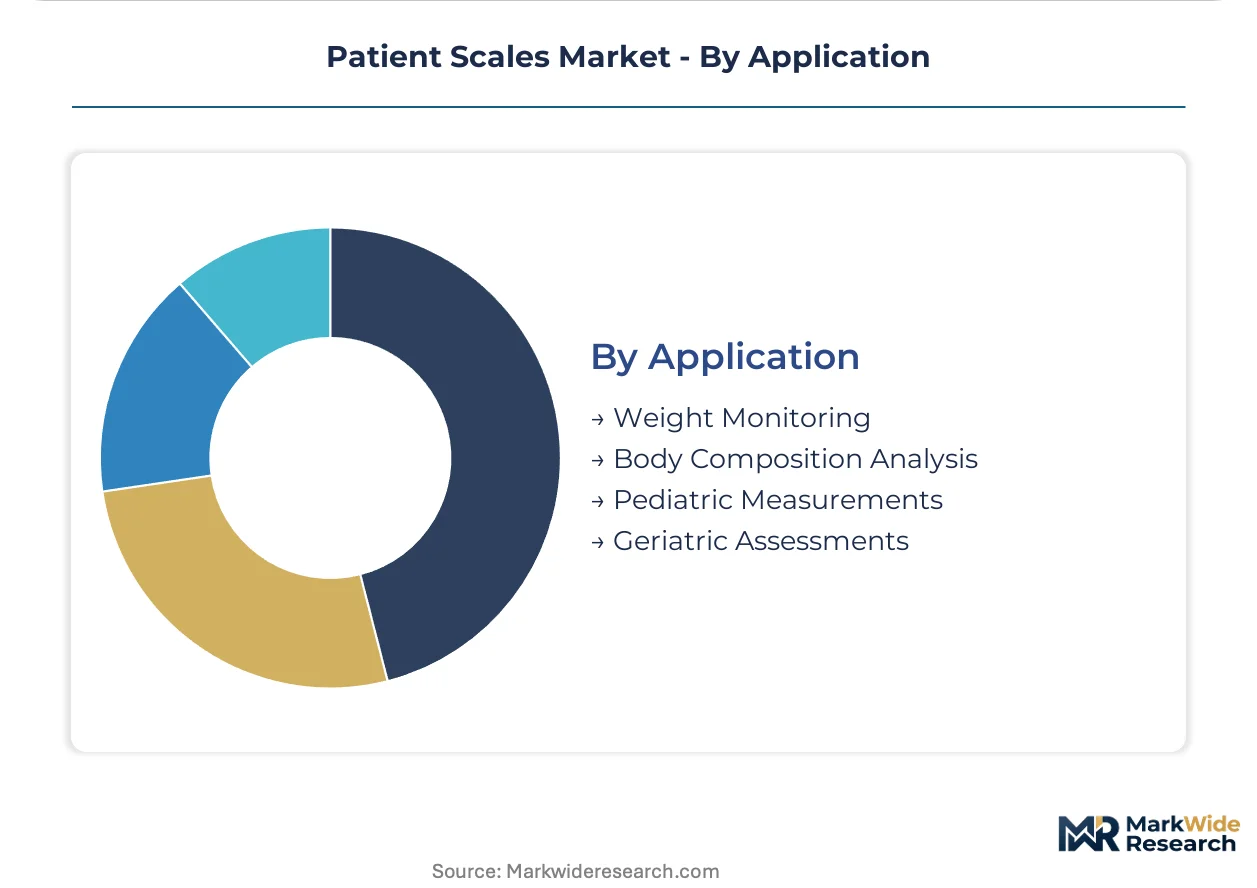
- Body Composition Analysis:Bioimpedance spectroscopy and segmental analysis algorithms require FDA software-as-medical-device validation. Outpatient clinics in metabolic disease management programs drive fastest adoption.
- Weight Monitoring:Baseline mass measurement for pharmaceutical dosing and fluid balance tracking remains the volume foundation across all care settings.
- Pediatric Measurements:Cradle and chair configurations with motion-compensation algorithms address uncooperative patient scenarios.
- Geriatric Assessments:Fall-risk protocols and sarcopenia screening integrate grip-strength correlation with lean-mass quantification.
Weight Monitoring dominates current installed base. Body Composition Analysis shows steepest expansion trajectory on chronic disease protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seca GmbH's Hamburg manufacturing cluster anchors European production capacity for clinical-grade load-cell assemblies, with fabrication networks extending into Bavaria's precision engineering corridor.
United States
Hospital procurement consolidation around integrated room-furniture bundling drives enterprise-scale contracts. FDA 510(k) clearance requirements filter vendor pools to established manufacturers with regulatory documentation capabilities. Hillrom anchors North American hospital relationships through Midwest-based biomedical engineering support networks.
Germany
EU Medical Device Regulation compliance mandates elevate clinical-evidence requirements for Class I measuring devices. Strain-gauge manufacturing clusters in Hamburg and Bavaria enable ISO 9001 traceability certification for domestic and export markets. Seca GmbH leverages captive German fabrication to sustain margin control on precision platforms.
Japan
Metabolic disease management protocols in outpatient clinics accelerate body composition analysis adoption. PMDA device classification aligns with IEC 60601-1 third-edition electromagnetic compatibility standards. Tokyo-Osaka industrial corridors concentrate thin-film deposition expertise for corrosion-resistant sensor substrates.
Brazil
Public health program expansion for chronic kidney disease treatment scales demand for ANVISA-certified bariatric platforms. Limited domestic competition creates procurement opportunities for imported precision equipment. São Paulo's medical device distribution hubs coordinate nationwide calibration service networks.
United Kingdom
NHS procurement frameworks prioritize digital connectivity for EMR integration in acute care settings. MHRA post-Brexit device registration requirements reshape import certification workflows. London-Southeast biomedical engineering clusters specialize in third-party ISO 17025 calibration services for academic medical centers.
Patient Scales Market Key Industry Players
Strategic partnerships dominate the current landscape as vendors consolidate regulatory expertise and service capabilities. The vendor base stratifies across three tiers: integrated room-furniture bundlers, precision fabrication specialists with captive manufacturing, and regional calibration service providers. German and Japanese load-cell specialists occupy premium positioning through ISO 9001 traceability certification. Competitive moves concentrate on M&A for regulatory documentation portfolios and geographic expansion into underpenetrated chronic disease management markets.
Among German-based precision manufacturers, Seca GmbH exemplifies the captive fabrication archetype with Hamburg-centered production networks. Hillrom occupies the integrated systems tier through North American hospital contracting relationships. Detecto Scale Company represents the specialized certification segment, anchoring USDA-compliant positioning for renal dialysis and bariatric program applications.
| Leading Market Players |
|---|
| Health O Meter |
| Detecto Scale Company |
| Seca GmbH |
| Algen Scale Corp. |
| Hillrom |
| Tanita |
| Natus Medical Inc. |
| Doran Scales Inc |
| Marsden Weighing |
| Others |
Cost & Logistics Intelligence
Family-owned precision manufacturers in Germany anchor supply-side discipline through captive Hamburg fabrication networks, translating ISO 9001 traceability certification into pricing power that resists commodity erosion across clinical-grade platforms.
Pricing Analysis
Aluminum load-cell substrate costs pass through differentially across product tiers, with corrosion-resistant thin-film deposition commanding premium positioning over stamped-steel predecessors. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared platforms with software validation from basic digital units and mechanical alternatives. Cost compression in mid-range segments is intensifying because smartphone health apps erode entry-level clinical demand. Home care buyers exhibit highest price sensitivity, while hospital procurement committees prioritize EMR interoperability over unit economics.
Supply Chain Analysis
Container freight volatility from Hamburg and Tokyo-Osaka corridors shapes landed cost calculations for North American and Brazilian importers. Strain-gauge manufacturing clusters in Germany, Japan, and select Bavarian precision engineering zones feed global assembly networks. Raw material dependencies center on aluminum substrate stock, semiconductor signal conditioners, and medical-grade calibration weights. Single-source vulnerability concentrates in thin-film deposition expertise for corrosion-resistant sensor housings. Distribution runs through hospital GPO contracts, regional medical device distributors, and third-party calibration service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play: EU MDR compliance costs in Germany create 15-20% cost disadvantages versus Brazilian import channels where ANVISA certification faces limited domestic competition.
For Market Incumbents: Lock in captive fabrication economies by securing long-term aluminum substrate contracts from Hamburg suppliers before commodity volatility spreads. Deepen hospital GPO relationships through bundled calibration service agreements that smartphone ecosystem vendors cannot replicate. Defend against software-as-medical-device regulatory creep by pre-validating body composition algorithms for FDA 510(k) submission. For New Entrants and Emerging Players: Begin with ANVISA-certified bariatric platforms for Brazil's public renal dialysis expansion, where import competition remains thin and procurement cycles favor first-mover certification. Target outpatient metabolic disease clinics in Japan with body composition analysis units at capital thresholds below hospital system requirements. Pursue direct calibration service partnerships with São Paulo distribution hubs to bypass incumbent field-service networks. For Investors and Strategic Acquirers: Valuations sit cheapest among regional calibration service providers in Texas and Bavaria that captured standalone maintenance relationships from original manufacturers. Five-to-ten-year viability hinges on cybersecurity validation for IEC 81001-5-1 connected-scale deployments. Watch ANVISA regulatory harmonization with FDA standards as the inflection signal for Brazilian market consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements for Class I measuring devices elevate compliance barriers for non-European manufacturers. |
| Hospital System Partnership | Enterprise-scale EMR integration contracts with Midwest academic medical centers consolidate procurement authority. |
| Software Companion Development | FDA 510(k) clearance for body-fat estimation algorithms transforms accessory features into regulated medical device components. |
| Backward Integration into Load Cells | Captive strain-gauge fabrication in Hamburg insulates margin control from Japanese supply concentration risks. |
| Reimbursement Strategy | Metabolic disease protocol adoption in outpatient clinics creates insurance coding pathways for body composition analysis. |
Research Approach
Multiple input streams — hospital procurement database analysis, regulatory filing review, and primary field interviews — were reconciled through bottom-up and top-down triangulation. Conversations captured perspectives from biomedical engineering directors, GPO contracts managers, hospital purchasing committees, and third-party calibration technicians. Secondary validation drew from FDA 510(k) clearances, EU MDR technical documentation, CMS Medicare durable medical equipment data, and ANVISA registration filings.
Historical shipment patterns were cross-referenced against panel input from German and Japanese load-cell specialists to anchor volume assumptions across the projection horizon. Segmentation modeling spanned product type, end-user institution scale, sensor technology architecture, and application workflow integration. CAGRs were derived from fitted trend extrapolation calibrated to regulatory timeline impacts and replacement cycle compression from EMR mandates. Industry-specific forecast inputs included IEC 60601-1-2 electromagnetic compatibility testing delays and aluminum substitution elasticities in mid-range platform manufacturing.
Several conditions sit outside the modeled scope, including geopolitical trade restrictions on precision sensor exports, sudden cybersecurity standard revisions, and pandemic-era hospital capital budget freezes. Forecasts reflect documented assumptions about regulatory harmonization timelines and load-cell supply concentration persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Cardiopulmonary Exercise Testing Market
Patient Monitoring
Remote Patient Monitoring System Market
Patient Monitoring
AI in Remote Patient Monitoring Market
Patient Monitoring
Multi-Item Patient Monitor Market
Patient Monitoring
Cardiac Patch Monitor Market
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
North America Hemodynamic Monitoring Market
Patient Monitoring
France Patient Monitoring Market
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
Brain Monitoring Systems Market
Patient Monitoring
Central Patient Monitoring System Market
Patient Monitoring
Remote Patient Monitoring Devices Market
Patient Monitoring
Asia-Pacific Respiratory Monitoring Market
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
ECG Monitoring System Market