
 Heart Failure POC and LOC Devices Market | 2026-2036
Heart Failure POC and LOC Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Failure POC and LOC Devices Market Foresight
Home care is pivoting toward decentralized cardiac monitoring platforms as payors and health systems prioritize reduced hospital readmission costs. Abbott Laboratories leverages its integrated diagnostics portfolio to anchor hospital-to-home workflows. Siemens Healthineers sustains technology leadership in ultrasound-based cardiac assessment. bioMérieux competes through specialized molecular diagnostic platforms that extend into cardiovascular biomarker detection.
Heart failure POC and LOC devices integrate miniaturized biosensors, microfluidic cartridges, and wireless telemetry to deliver natriuretic peptide quantification and hemodynamic monitoring outside centralized laboratories. These systems enable therapeutic decision-making at the bedside, in ambulatory settings, or within patient residences. Monitor and sensor segments lead current revenue contribution due to recurring consumable attach rates and continuous monitoring protocols. Bioelectronic technology platforms represent the fastest-growing dimension as electrochemical impedance spectroscopy and graphene-based electrodes mature from research into commercial validation. Telemetry-enabled diagnostics command premium positioning where real-time clinician notification integrates with electronic health record architectures.
FDA 510(k) pathways and EU MDR conformity assessments shape product development timelines and market access requirements for cardiovascular diagnostic devices. The EPA and ISO 13485 quality management frameworks additionally govern manufacturing site validation and environmental compliance for disposable cartridge production. Stakeholders must monitor evolving CLIA waiver expansions and remote patient monitoring reimbursement codes that determine economic viability for home-based heart failure detection platforms.
Market Dynamics
Decentralized cardiac monitoring is compressing traditional hospital-centric diagnostic workflows into ambulatory and residential settings, forcing manufacturers to reengineer device portfolios for wireless telemetry and CLIA-waived operation.
Growth Catalysts
- CLIA Waiver Expansion:CMS reimbursement codes for remote patient monitoring in the United States incentivize health systems to deploy natriuretic peptide testing outside central laboratories.
- Graphene Electrode Maturation:Bioelectronic platforms utilizing electrochemical impedance spectroscopy achieve commercial validation for continuous hemodynamic surveillance.
- Japan's Super-Aged Society:METI funding directives accelerate home-based cardiac diagnostic adoption where hospital bed capacity constraints intensify demand for decentralized monitoring.
Market Restraints
- EU MDR Conformity Costs:Extended technical documentation requirements and notified body bottlenecks delay cardiovascular device market access by 18-24 months for mid-tier manufacturers.
- Microfluidic Cartridge Supply Concentration:Precision polymer molding capacity clusters in southern Germany and Switzerland, creating single-source vulnerability for disposable consumable production.
- Electrochemical Sensor Drift:Calibration degradation in non-laboratory environments limits assay reliability for point-of-care BNP quantification outside controlled temperature conditions.
Strategic Opportunities
- India's Tier-2 Hospital Network:CDSCO streamlined approval pathways for Class B cardiovascular diagnostics open penetration into 400+ district hospital hubs lacking centralized lab infrastructure.
- Wearable-Telemetry Convergence:Integration of photoplethysmography with implantable loop recorders creates continuous outpatient monitoring platforms bridging acute and chronic heart failure management.
- Outcome-Based Reimbursement:United States CMS bundled payment models for 30-day heart failure readmission reduction reward health systems investing in pre-discharge POC diagnostic protocols.
Industry Challenges
- Multi-Site ISO 13485 Auditing:Disposable cartridge manufacturing across Asian contract facilities requires synchronized quality management system validation to maintain FDA 510(k) clearance integrity.
- EHR Interoperability Friction:Proprietary data formats from telemetry-enabled devices resist seamless integration with Epic and Cerner architectures, delaying real-time clinician alert deployment.
- Bioelectronic Talent Scarcity:Electrochemical sensor engineering expertise concentrates within academic research clusters, constraining commercial-scale product engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Failure POC and LOC Devices Market |
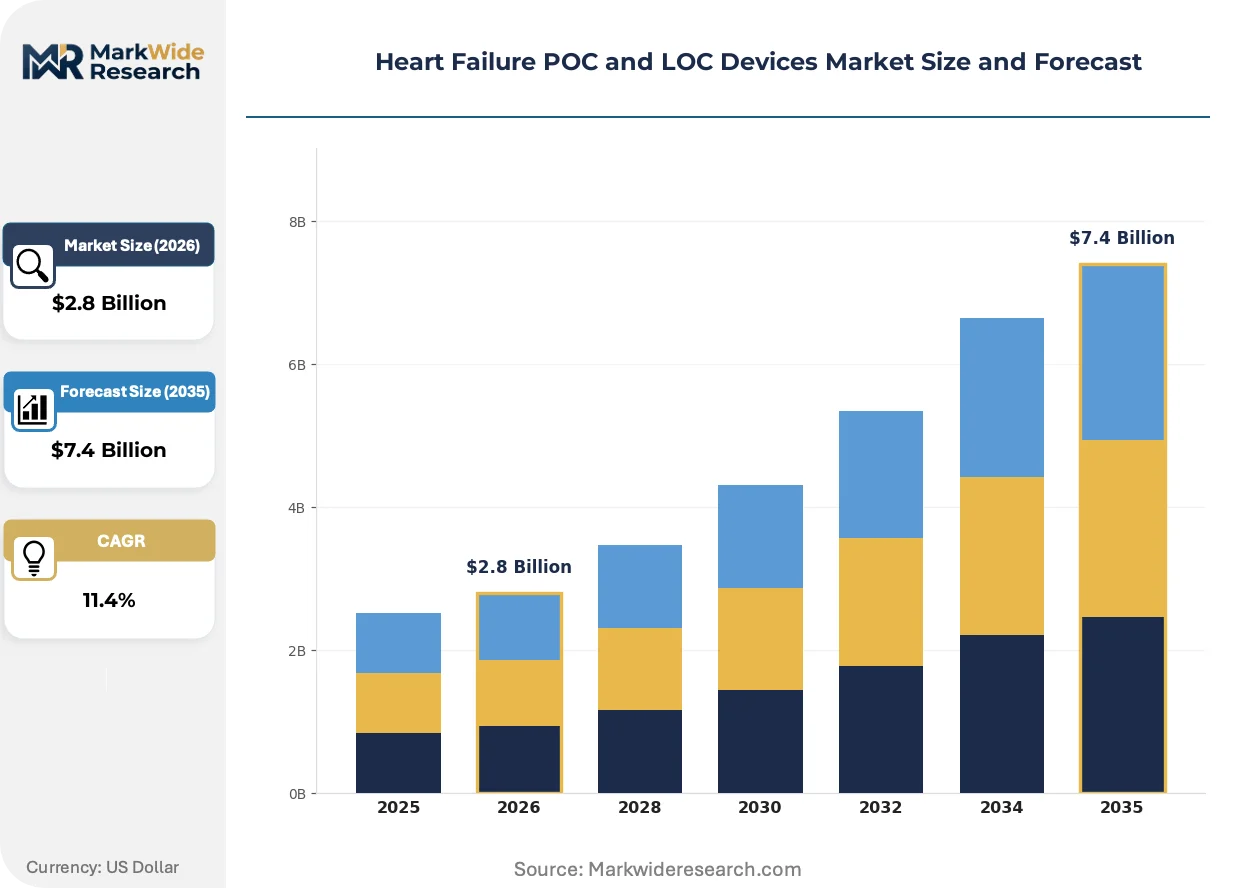
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitor, Pump, Sensor, Analyzer End User: Clinics, Home Care, Hospitals, Ambulatory Surgical Centers Technology: Bioelectronic, Ultrasound, Spectroscopy, Telemetry Application: Diagnostics, Patient Monitoring, Therapy, Emergency Care |
| Companies Covered | F. Hoffmann-La Roche Ltd, QuidelOrtho Corporation, Abbott Laboratories, Abaxis, Inc, Trinity Biotech, Siemens Healthineers, bioMérieux, Instrumentation Laboratory, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Failure POC and LOC Devices Market Shifts & Advancements
Wireless telemetry architectures are displacing wired bedside monitors as the default connectivity standard, compressing deployment timelines and enabling continuous data streams from patient residences to cloud-based clinical decision support systems.
Graphene-based electrode arrays are consolidating electrochemical detection sensitivity for natriuretic peptide quantification at femtomolar concentrations. Cardiology departments in German university hospitals are piloting these platforms for same-day discharge protocols. The technology is consolidating multiple assay steps into single-cartridge workflows that eliminate laboratory technician involvement.
EU MDR Article 10 technical documentation requirements are forcing cardiovascular diagnostic manufacturers to restructure clinical evidence portfolios. Notified body capacity constraints in the Netherlands and Germany are extending conformity assessment timelines. Device categories lacking predicate equivalence face de novo pathway migration toward clinical trial obligations.
Hospital procurement committees are unbundling device acquisition from consumable supply contracts, separating capital expenditure approval from recurring operational budgets. This purchasing pattern shift pressures manufacturers to demonstrate standalone ROI for telemetry hardware independent of cartridge attach rates. German integrated delivery networks pioneered this bifurcation, with United States health systems adopting comparable committee structures.
Heart Failure POC and LOC Devices Market Segmentation
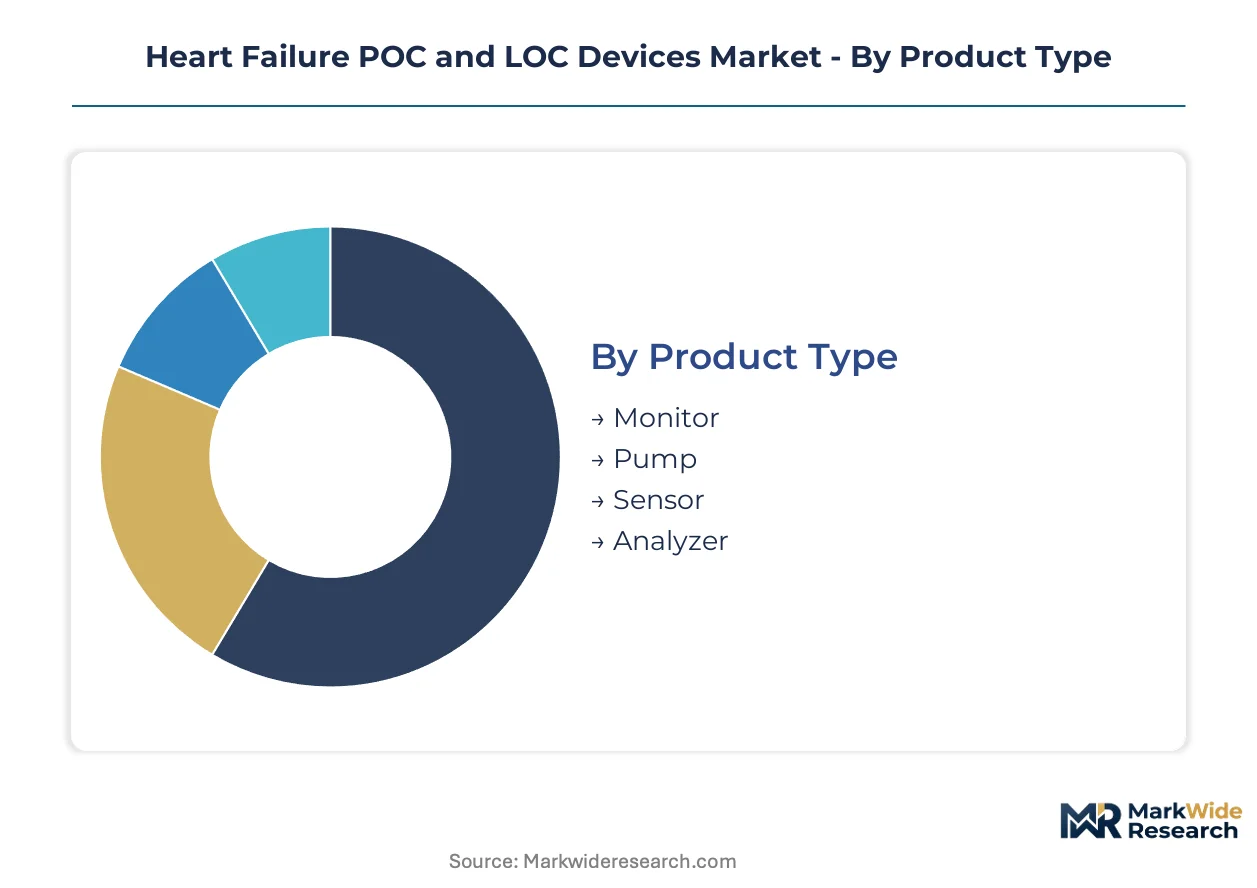
Segmentation in heart failure POC and LOC devices determines where capital equipment investments concentrate versus consumable-driven recurring revenue. Product architecture choices—standalone bedside units versus embedded sensor networks—shape procurement patterns across hospital, ambulatory, and residential settings.
Product Type:
Integration depth separates capital-intensive standalone systems from embedded disposable architectures that lock in recurring revenue.
- Monitor:Continuous hemodynamic surveillance platforms integrate wireless telemetry with cloud-based clinical decision support. Demand clusters in United States integrated delivery networks where CMS remote patient monitoring reimbursement codes justify capital deployment.
- Sensor:Miniaturized biosensors utilizing electrochemical impedance spectroscopy enable natriuretic peptide quantification at femtomolar sensitivity. German university hospitals pilot graphene-based electrode arrays for same-day discharge protocols, accelerating validation timelines.
- Pump:Portable infusion systems for inotropic therapy delivery in ambulatory settings.
- Analyzer:Benchtop and handheld systems for rapid biomarker quantification outside central laboratories.
Sensor leads volumes today; Monitor is gaining share fastest.
End User:
Cost tier stratification separates high-acuity hospital investments from lean ambulatory and home-based deployments.
- Hospitals:Academic medical centers and community hospitals deploy comprehensive POC diagnostic suites with full CLIA-waived assay menus. United States health systems prioritize pre-discharge BNP testing to reduce 30-day readmission penalties under CMS bundled payment models.
- Home Care:Decentralized cardiac monitoring platforms leverage wearable-telemetry convergence for continuous outpatient surveillance. Japan's super-aged society drives METI-funded adoption where hospital bed constraints intensify residential diagnostic demand.
- Clinics:Physician office laboratories with limited technician staffing favor single-cartridge workflows.
- Ambulatory Surgical Centers:Same-day procedure facilities require rapid pre-operative cardiac risk stratification tools.
Hospital procurement dominates absolute spending; Home Care climbs the fastest.
Technology:
Technology maturity curves determine which platforms transition from research validation to commercial scale.
- Bioelectronic:Electrochemical impedance spectroscopy and graphene-based electrode arrays achieve commercial validation for continuous hemodynamic monitoring. Academic research clusters in Germany and Switzerland concentrate electrochemical sensor engineering expertise, constraining commercial-scale team expansion.
- Telemetry:Wireless architectures displace wired bedside connectivity as default standards, enabling real-time data streams from patient residences to EHR systems. Premium positioning commands where Epic and Cerner interoperability friction limits competitive alternatives.
- Ultrasound:Handheld cardiac assessment devices sustain technology leadership through portable imaging workflows.
- Spectroscopy:Optical detection methods for biomolecular quantification in resource-limited settings.
Telemetry anchors current revenue; Bioelectronic shows steepest expansion trajectory.
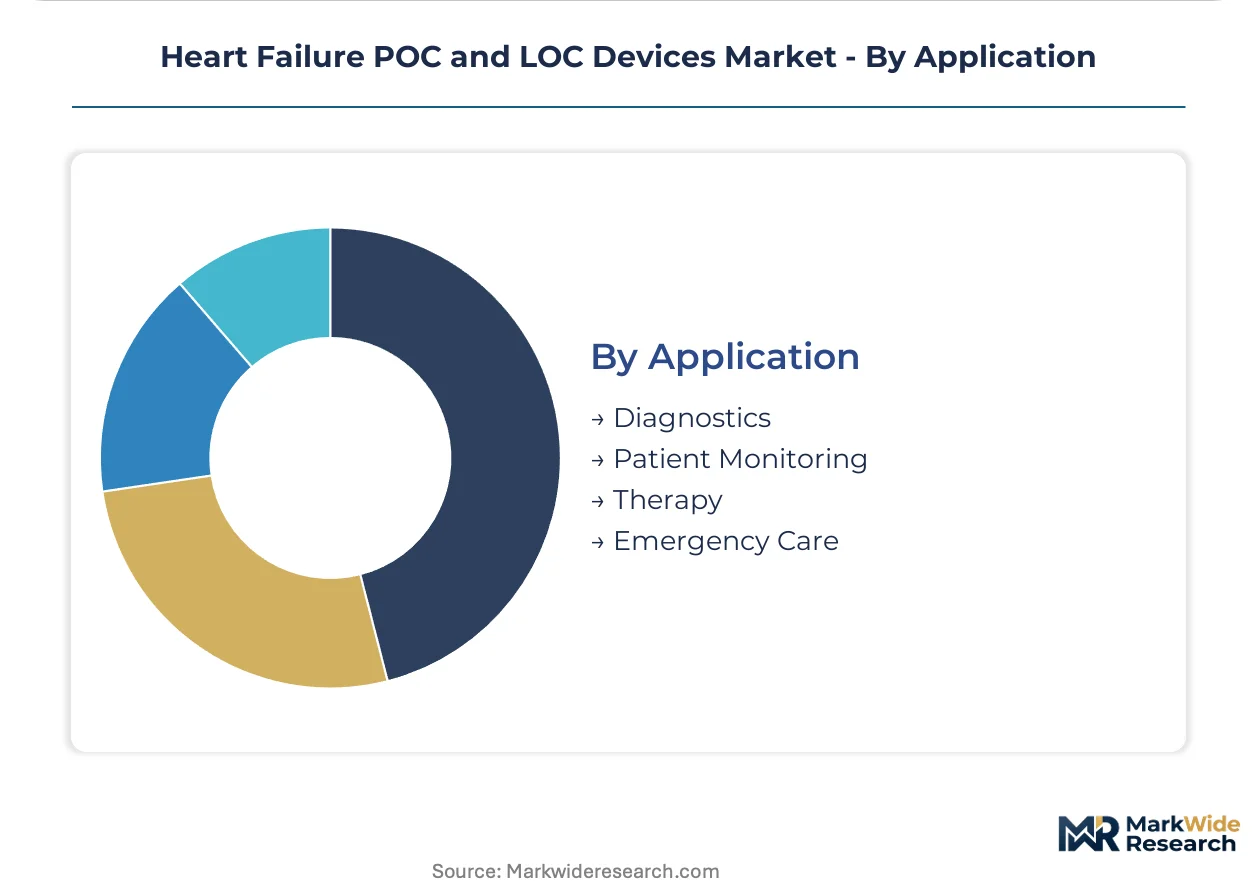
Application:
Application focus determines whether device portfolios target episodic diagnostic events or continuous therapeutic management.
- Patient Monitoring:Continuous outpatient surveillance platforms bridge acute and chronic heart failure management through wearable-telemetry integration. Demand concentrates in United States Medicare Advantage plans where outcome-based reimbursement rewards readmission reduction.
- Diagnostics:Rapid natriuretic peptide quantification enables therapeutic decision-making at the point of care without laboratory technician involvement. CDSCO streamlined approval pathways open India's tier-2 hospital network to Class B cardiovascular diagnostic penetration.
- Therapy:Integrated diagnostic-therapeutic systems for guided inotropic or diuretic administration.
- Emergency Care:Rapid triage tools for undifferentiated dyspnea in emergency department settings.
Patient Monitoring leads installed base; Diagnostics expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as cardiovascular device makers relocate precision polymer molding to jurisdictions with streamlined quality management validation. FDA 510(k) clearance timelines and EU MDR conformity costs now determine where electrochemical sensor production concentrates.
United States
Medicare Advantage plans and CMS bundled payment models for 30-day heart failure readmission reduction drive pre-discharge POC diagnostic adoption. FDA CLIA waiver expansions for natriuretic peptide testing accelerate deployment outside central laboratories. Greater Boston's medical device cluster anchors wireless telemetry engineering talent for continuous monitoring platforms.
Germany
University hospitals in Baden-Württemberg pilot graphene-based electrode arrays for same-day discharge protocols, compressing validation timelines for bioelectronic platforms. EU MDR notified body bottlenecks in Munich and Hamburg extend conformity assessment timelines by 18-24 months for mid-tier manufacturers. Precision polymer molding capacity concentrates in southern Germany, creating single-source vulnerability for microfluidic cartridge supply.
Japan
METI funding directives accelerate home-based cardiac diagnostic adoption where hospital bed capacity constraints intensify demand for decentralized monitoring. PMDA streamlined approval pathways for Class II cardiovascular diagnostics align with super-aged society demographics. The Kansai region's Osaka-Kobe medical technology corridor hosts electrochemical sensor research clusters migrating toward commercial scale.
India
CDSCO streamlined approval pathways for Class B cardiovascular diagnostics open penetration into 400+ district hospital hubs lacking centralized lab infrastructure. Government PLI scheme incentives for medical device manufacturing attract precision molding investment to Gujarat and Maharashtra. Hyderabad's diagnostic reagent cluster expands into cartridge-based cardiac biomarker production for domestic and export markets.
Switzerland
Swissmedic conformity assessment efficiency and ISO 13485 quality management expertise attract electrochemical sensor engineering teams from academic research clusters. Precision microfluidics manufacturing in the Basel-Zurich corridor supplies disposable consumables to EU and US device makers. The country's dual-track regulatory alignment with both EU MDR and FDA standards reduces market access friction for multinational portfolios.
Heart Failure POC and LOC Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated diagnostics conglomerates commanding hospital procurement committees while niche sensor engineering firms capture consumable attach rates. The vendor base organizes around three archetypes: diversified medtech conglomerates with full CLIA-waived assay menus, pure-play bioelectronic specialists advancing graphene electrode commercialization, and precision polymer contract manufacturers supplying microfluidic cartridges. Competitive intensity centers on M&A activity targeting telemetry-enabled diagnostics and strategic partnerships bridging wearable-telemetry convergence.
Among diversified diagnostics conglomerates, Abbott Laboratories and Siemens Healthineers occupy positions anchoring hospital-to-home workflow integration. Swiss-domiciled Roche exemplifies the premium-tier archetype through specialized molecular diagnostic platforms. These three entities represent contrasting strategic postures: Abbott leverages integrated portfolio breadth, Siemens sustains ultrasound-based cardiac assessment leadership, and Roche concentrates cardiovascular biomarker detection capabilities.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| QuidelOrtho Corporation |
| Abbott Laboratories |
| Abaxis, Inc |
| Trinity Biotech |
| Siemens Healthineers |
| bioMérieux |
| Instrumentation Laboratory |
| Danaher Corporation |
| Others |
Supply & Pricing Matrix
Graphene electrode substrate costs cascade through three pricing tiers as precision polymer molding capacity in southern Germany and Switzerland constrains downstream cartridge economics. Raw material scarcity for electrochemical sensor substrates compresses margins at the economy tier while CLIA-waived certification premiums defend pricing power at the premium tier where hospital procurement committees unbundle capital from consumable contracts.
Pricing Analysis
Distributor margin layers absorb 15-25 point spreads between OEM gate pricing and hospital procurement committee landed costs. The dominant structure is tiered premium-standard-economy pricing stratified across FDA 510(k) clearance tiers, ISO 13485 certification levels, and wireless telemetry integration depth. Pricing pressure stems from German integrated delivery networks pioneering hardware-consumable unbundling that forces standalone ROI demonstration for telemetry platforms. Price sensitivity concentrates in ambulatory surgical centers and India's tier-2 hospital network, while academic medical centers in the United States and Japan exhibit lowest sensitivity due to bundled payment model alignment.
Supply Chain Analysis
ISO 13485 certification gating funnels precision microfluidics manufacturing toward the Basel-Zurich corridor and southern Germany where Swissmedic and EU MDR quality management expertise concentrates. Electrochemical sensor production draws from graphene substrate suppliers in Germany, precision polymer molders in Switzerland, and contract assembly facilities in India. Single-source vulnerability runs through microfluidic cartridge molding capacity clustered in Baden-Württemberg. Distribution runs through specialized medtech distributors serving hospital procurement committees and direct OEM relationships with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Heart Failure POC and LOC Devices Market represents a late-cycle quality story where METI funding directives in Japan and CMS bundled payment models in the United States shift demand toward telemetry-enabled platforms with demonstrated readmission reduction outcomes.
For Market Incumbents: Anticipate margin compression from hardware-consumable unbundling by deepening backward integration into precision polymer molding capacity in Switzerland and Germany. Defend positioning through exclusive GPO contracts with United States integrated delivery networks and accelerated CE marking pathways for bioelectronic platforms before EU MDR notified body bottlenecks extend further. Prioritize in-house production of graphene electrode substrates to reduce single-source dependency on academic research cluster suppliers. For New Entrants and Emerging Players: CDSCO streamlined approval pathways in India open a window for Class B cardiovascular diagnostic penetration into 400+ district hospital hubs lacking centralized lab infrastructure. Target India's tier-2 hospital network through portable analyzer platforms with simplified single-cartridge workflows and localized cartridge production partnerships in Gujarat. Pursue go-to-market execution through government PLI scheme incentives and direct relationships with state-level procurement authorities bypassing established distributor networks. For Investors and Strategic Acquirers: Consolidation pressure builds where bioelectronic talent scarcity constrains commercial-scale electrochemical sensor engineering team expansion beyond academic research clusters. Long-term viability favors pure-play sensor specialists with validated graphene electrode platforms and telemetry-enabled diagnostics demonstrating Epic or Cerner interoperability. Watch FDA CLIA waiver expansion announcements for natriuretic peptide testing as the inflection signal determining home-based platform economic viability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates CLIA-waived pathway for natriuretic peptide quantification in ambulatory settings. |
| CE Marking Pathway | Navigates EU MDR Article 10 requirements for bioelectronic platform market access. |
| Hospital System Partnership | Secures preferred vendor status within United States integrated delivery network procurement committees. |
| Software Companion Development | Resolves EHR interoperability friction with Epic and Cerner architectures for real-time clinician alerts. |
| Reimbursement Strategy | Aligns telemetry platform deployment with CMS remote patient monitoring codes and bundled payment models. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at cardiovascular diagnostic manufacturers were combined with secondary validation from FDA 510(k) filings, EU MDR notified body databases, CMS Medicare reimbursement code updates, and hospital procurement contract disclosures. Triangulation across these sources ensures segmentation integrity for product type, end user, technology, and application dimensions.
Historical trendline analysis of installed base growth, consumable attach rates, and capital equipment replacement cycles informed projection frameworks across the analysis window. Segmentation modeling incorporated bioelectronic platform maturity curves, telemetry adoption velocity, and regional regulatory pathway differentiation. CAGRs were derived from regression analysis against demographic aging trajectories, reimbursement policy shifts, and technology validation timelines specific to electrochemical impedance spectroscopy commercialization.
Revisions become necessary when EU MDR notified body capacity constraints extend beyond current assessment timelines or when CMS issues material changes to remote patient monitoring reimbursement codes. Forecasts reflect assumptions regarding graphene electrode manufacturing scale-up, microfluidic cartridge supply chain stability, and CLIA waiver expansion trajectories. A model refresh is warranted upon material change in FDA regulatory pathway requirements for point-of-care cardiovascular diagnostics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bronchial Blocker Devices Market
Medical Devices
South Korea Ultrasound Devices Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Auto-Transfusion Systems Market
Medical Devices
Global Gynecology Devices Market
Medical Devices
Global Deep Brain Stimulation Devices Market
Medical Devices
South Korea Drug Delivery Devices Market
Medical Devices
Asia-Pacific Ostomy Care and Accessories Market
Medical Devices
3D Printed Hip and Knee Implants Market
Medical Devices
Sperm Separation Systems Market
Medical Devices
Europe Arthroscopy Devices Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Global Blood Warmer Devices Market
Medical Devices
Nerve Ablation Devices Market
Medical Devices
TMJ Implants Market
Medical Devices
United States Implantable Medical Devices Market