
 Telemonitoring Systems Market | 2026-2036
Telemonitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Telemonitoring Systems Market Analytics
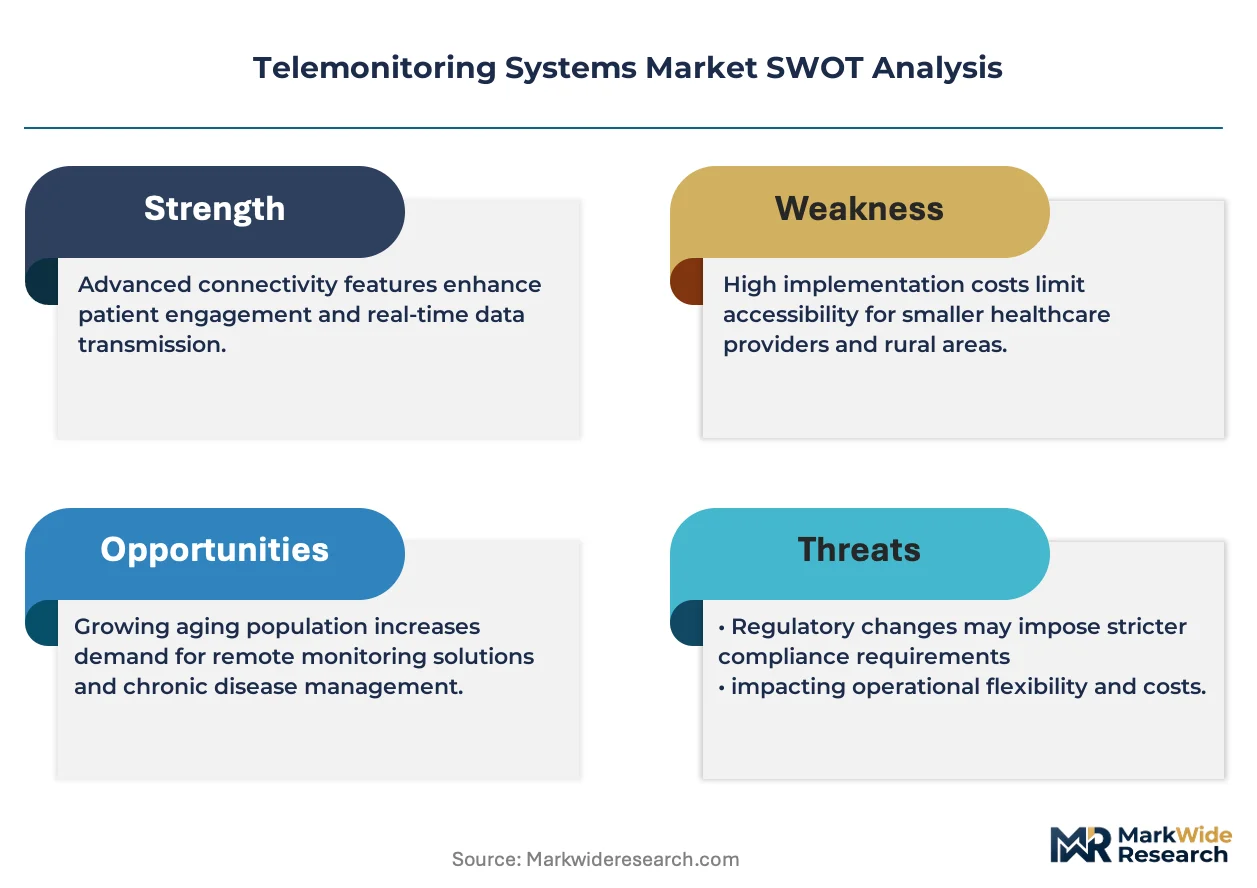
The telemonitoring systems landscape is restructuring around a sharp split between hospital-grade platforms with FDA-cleared algorithms and consumer wellness devices lacking clinical validation. Philips Healthcare dominates the premium institutional tier through its IntelliVue ecosystem, while Omron Healthcare competes aggressively in the home blood-pressure monitoring segment with pharmacy-retail distribution. Dexcom, Inc. anchors the continuous glucose monitoring niche with sensor-software integration that sustains recurring revenue through disposable consumables.
Telemonitoring systems encompass networked hardware and software platforms that capture, transmit, and analyze patient physiologic data outside traditional clinical settings, typically incorporating cloud-based dashboards with configurable alert thresholds for clinical decision support. The device-type dimension shows wearable devices capturing the fastest expansion as miniaturized biosensors extend battery life beyond fourteen days, while bedside monitors retain the largest installed base in acute-care transitions. Cellular technology leads connectivity deployments in rural homecare where broadband infrastructure remains inconsistent, whereas Bluetooth dominates urban rehabilitation center installations with reliable local-area coverage.
The FDA's digital health pre-certification program and HIPAA security rule collectively shape product development timelines and data architecture requirements for any system handling protected health information across state lines. The EU MDR and GDPR impose parallel conformity and privacy obligations on vendors seeking access to European hospital procurement channels. Stakeholders must monitor evolving reimbursement granularity from CMS and comparable national payers, as coverage determinations for specific clinical indications will separate commercially viable platforms from unsupported hardware deployments.
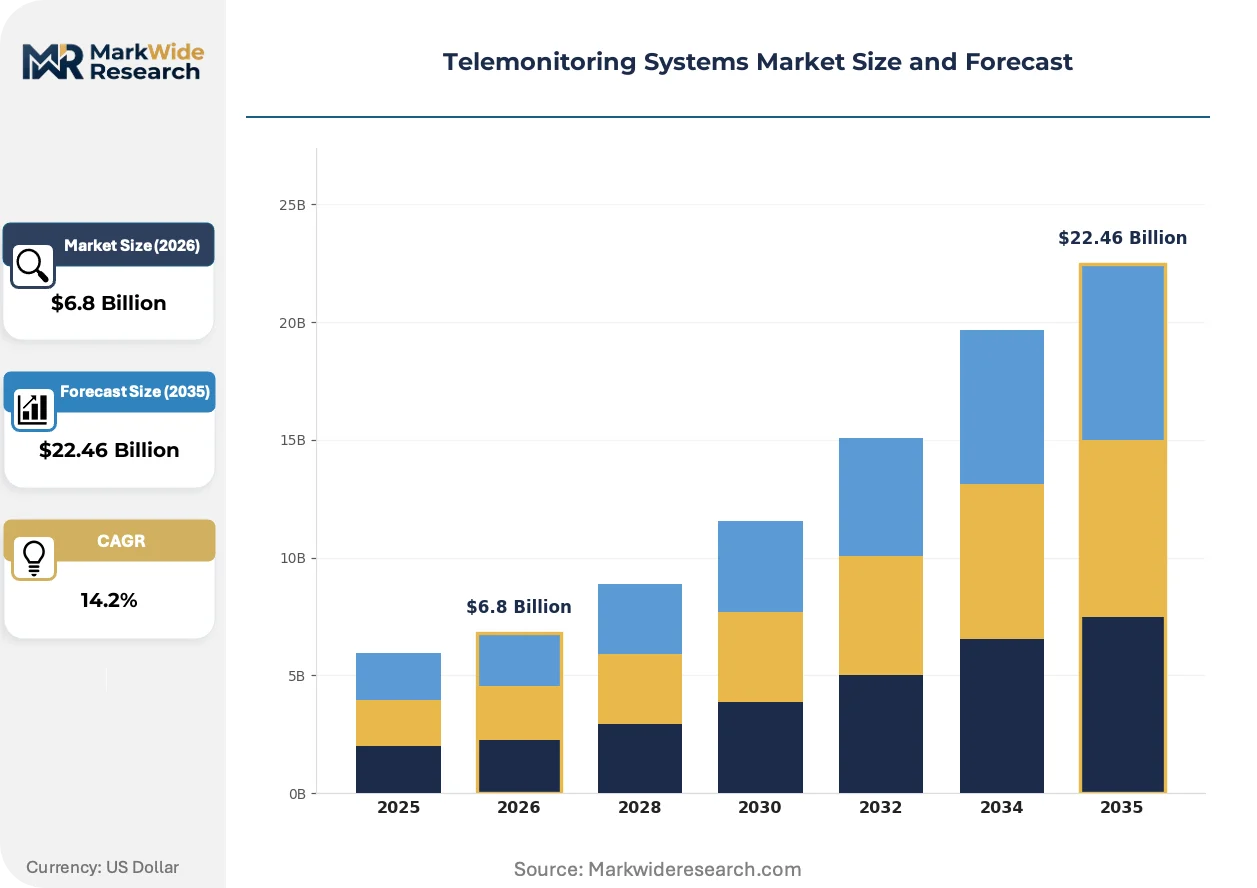
Market Dynamics
Medicare reimbursement pathway expansion for remote physiologic monitoring is restructuring competitive economics, compressing hardware margins while amplifying software and service attach rates across institutional procurement cycles.
Growth Catalysts
- FDA Digital Health Pre-Certification:Accelerated software-as-medical-device pathways compress time-to-market for algorithm-driven platforms, enabling faster clinical validation cycles.
- Hospital Readmission Penalty Programs:CMS payment adjustments for excess readmissions drive health system investment in post-acute remote monitoring infrastructure.
- Cellular Connectivity Infrastructure:Rural broadband gaps sustain demand for LTE-M and NB-IoT modules in homecare deployments where Wi-Fi remains unreliable.
Market Restraints
- HIPAA State-Level Fragmentation:Cross-border data transmission requirements create architectural complexity for multi-state health system deployments, inflating compliance engineering costs.
- Biosensor Component Concentration:MEMS foundry capacity constraints in East Asian manufacturing clusters generate lead time volatility for wearable device OEMs.
- Clinical Validation Burden:Algorithm performance thresholds for FDA 510(k) clearance demand prospective studies that extend development timelines beyond eighteen months.
Strategic Opportunities
- Behavioral Health Integration:Underpenetrated psychiatric and substance-use monitoring applications present white space as reimbursement codes expand beyond cardiopulmonary indications.
- EU MDR Conformity Pathways:Harmonized European device regulations create streamlined access to hospital procurement channels across Germany, France, and the Netherlands.
- Bluetooth 5.3 + AI Edge Convergence:Low-power on-device inference enables real-time anomaly detection without cloud dependency, opening ambulatory and athletic monitoring segments.
Industry Challenges
- Interoperability Architecture:HL7 FHIR implementation gaps between legacy EHR systems and cloud-native monitoring platforms force costly middleware development.
- Cybersecurity Certification:State-by-state breach notification laws compound with FDA cybersecurity guidance to create multi-layered validation requirements for firmware updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telemonitoring Systems Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Wearable Devices, Bedside Monitors, Mobile Health Applications, Remote Patient Monitoring Devices Technology: Bluetooth, Wi-Fi, Cellular, Satellite End User: Hospitals, Homecare Providers, Rehabilitation Centers, Patients Application: Chronic Disease Management, Postoperative Monitoring, Emergency Response, Mental Health Support |
| Companies Covered | Philips Healthcare, GE Healthcare, Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, Omron Healthcare, ResMed Inc., Dexcom, Inc., Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telemonitoring Systems Market Evolving Landscape
Algorithmic automation of clinical decision support is compressing the role of traditional telemetry technicians, while sensor miniaturization and edge computing architectures redefine hardware-software boundaries across care settings.
Multi-parameter wearable patches integrating ECG, SpO2, and temperature sensing is consolidating discrete single-function devices into unified form factors. Cardiology departments at academic medical centers in the United States and Germany are piloting these platforms for post-surgical monitoring, displacing bedside telemetry for stable step-down unit patients. This consolidation is compressing capital equipment procurement cycles while elevating software licensing and disposable adhesive component economics.
The EU MDR's clinical evidence requirements for Class IIa software devices are extending conformity assessment timelines, forcing vendors to restructure technical documentation and post-market surveillance systems. Manufacturers targeting European hospital procurement channels must now maintain clinical investigation data across the full device lifecycle. This regulatory shift most acutely affects algorithm-driven diagnostic platforms, with vendors responding through strategic investments in notified body relationships and EU-based authorized representative infrastructure.
Health system procurement committees are unbundling hardware acquisition from ongoing clinical interpretation services, creating separate vendor relationships for device supply and remote monitoring staffing. This bifurcation disrupts traditional integrated service contracts that bundled telemetry technicians with equipment leases. The pattern is most visible in United States multi-hospital systems, where centralized remote monitoring centers now contract separately with device OEMs and clinical staffing firms.
Telemonitoring Systems Market Segmentation
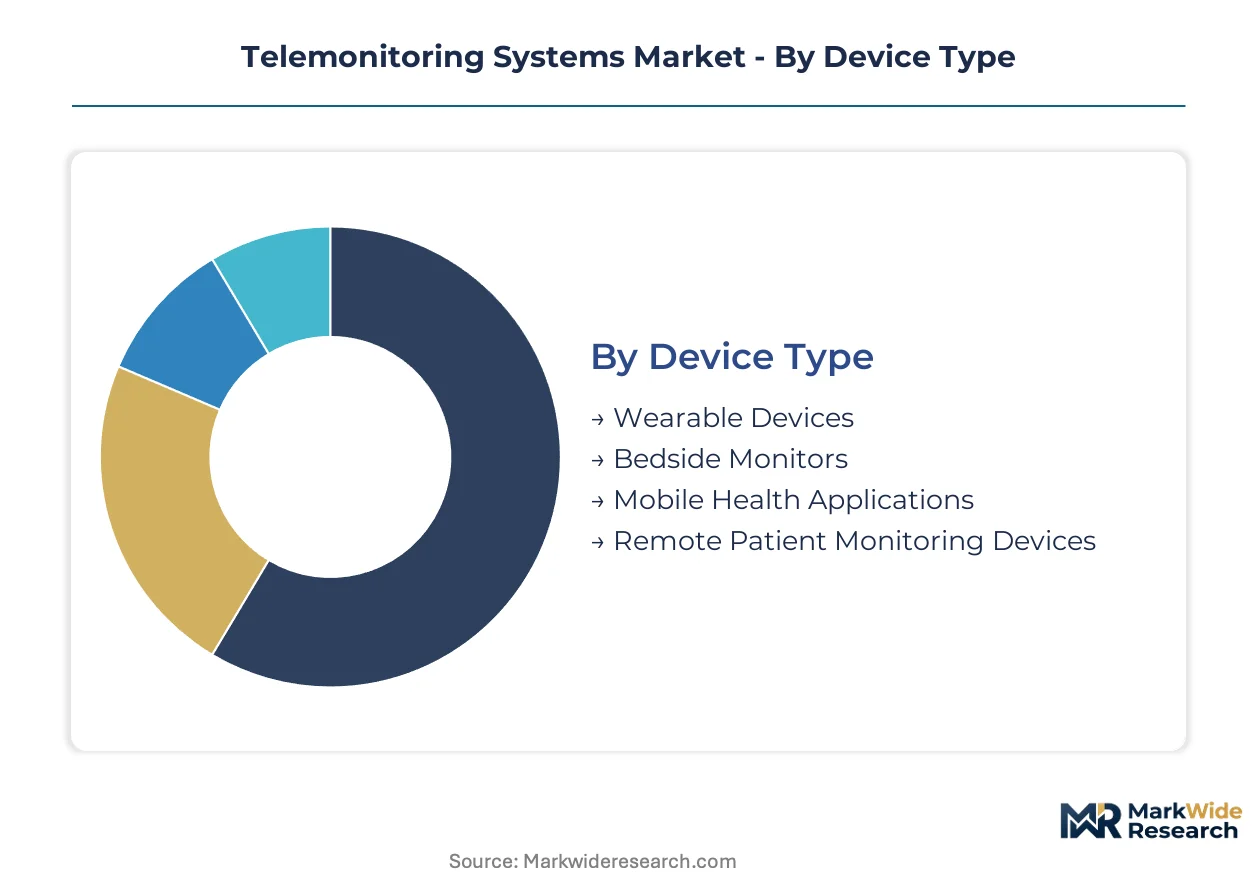
Telemonitoring systems fragment across device form factors, connectivity protocols, care settings, and clinical use cases. Each dimension carries distinct regulatory, reimbursement, and procurement implications that reshape vendor economics and competitive positioning.
Device Type:
Supply concentration in MEMS foundries and adhesive component manufacturing clusters shapes cost structures and lead time volatility across hardware categories.
- Wearable Devices:Miniaturized biosensor patches integrate ECG, SpO2, and temperature sensing into single-form-factor platforms. Academic medical centers in the United States and Germany deploy these for post-surgical step-down monitoring, displacing traditional bedside telemetry while elevating disposable adhesive economics.
- Bedside Monitors:Institutional-grade platforms with FDA-cleared algorithms anchor acute-care transitions and step-down units. Health system procurement committees increasingly unbundle hardware acquisition from clinical interpretation services, compressing capital equipment cycles.
- Mobile Health Applications:Software-only platforms leverage smartphone sensors and user-reported data for low-acuity monitoring.
- Remote Patient Monitoring Devices:Dedicated hardware kits bundle peripherals for specific clinical indications under Medicare reimbursement pathways.
Bedside monitors absorb the bulk of installed capacity; wearable devices are expanding most quickly.
Technology:
Connectivity choice hinges on infrastructure reliability and patient mobility requirements across urban, suburban, and rural deployment scenarios.
- Bluetooth:Low-power protocols dominate urban rehabilitation centers with reliable local-area coverage and minimal interference. Bluetooth 5.3 convergence with AI edge computing enables on-device anomaly detection without cloud dependency.
- Cellular:LTE-M and NB-IoT modules sustain homecare deployments in rural geographies where broadband infrastructure remains inconsistent. Rural broadband gaps preserve demand for cellular-native device architectures.
- Wi-Fi:Higher bandwidth supports multi-parameter streaming in institutional settings with managed network infrastructure.
- Satellite:Emergency response and remote expedition applications leverage global coverage beyond cellular footprints.
Bluetooth captures the greatest deployment volume; cellular connectivity is gaining share fastest in reimbursement-eligible homecare expansion.
End User:
Procurement authority and reimbursement eligibility diverge sharply between institutional purchasers and direct-to-patient channels.
- Hospitals:Health systems invest in remote monitoring infrastructure to reduce CMS readmission penalties and manage post-acute transitions. Centralized remote monitoring centers now contract separately with device OEMs and clinical staffing firms.
- Homecare Providers:Medicare reimbursement codes for remote physiologic monitoring create sustainable payment pathways that reshape competitive economics toward software and service attach rates.
- Rehabilitation Centers:Post-acute facilities deploy monitoring to track recovery trajectories and justify continued skilled nursing eligibility.
- Patients:Direct-pay consumer wellness devices lack clinical validation and sit outside reimbursement frameworks.
Hospitals command the largest procurement budgets; homecare providers are climbing the fastest as reimbursement granularity expands.
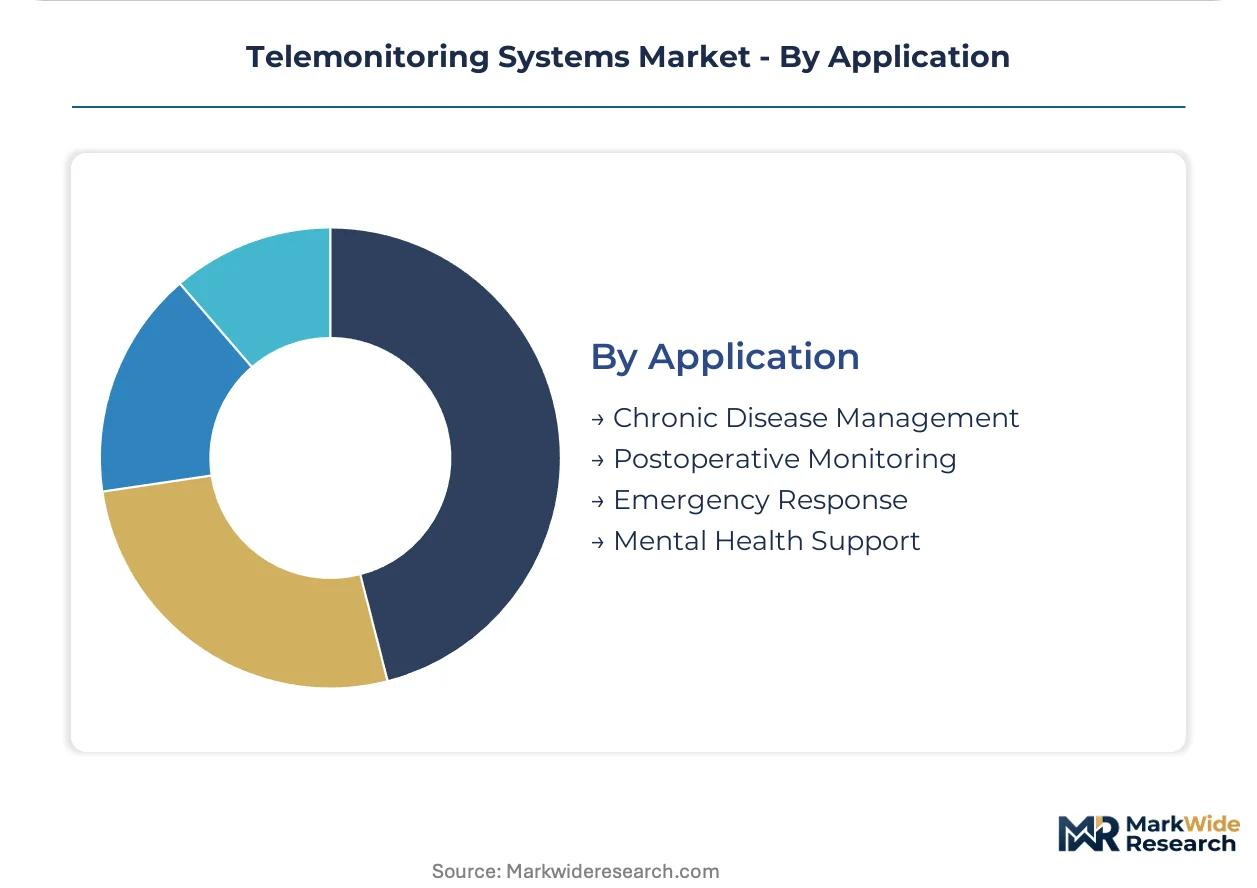
Application:
Clinical validation requirements and reimbursement coverage determinations separate commercially viable platforms from unsupported hardware deployments.
- Chronic Disease Management:Cardiopulmonary and diabetes monitoring anchor established reimbursement codes with prospective payment models. Dexcom's continuous glucose monitoring demonstrates sensor-software integration sustaining recurring revenue through disposable consumables.
- Postoperative Monitoring:Cardiology departments pilot multi-parameter patches for stable surgical patients, consolidating discrete devices and compressing telemetry technician roles.
- Emergency Response:Fall detection and acute event alerting systems integrate with emergency medical services dispatch protocols.
- Mental Health Support:Psychiatric and substance-use monitoring applications present underpenetrated white space as reimbursement codes expand beyond traditional indications.
Chronic disease management holds the deepest reimbursement infrastructure; mental health support is expanding most quickly as behavioral health integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American telemonitoring innovation through its concentration of academic medical centers and FDA-cleared algorithm developers. The metropolitan corridor hosts health system procurement committees that unbundle hardware acquisition from clinical staffing contracts. This pattern reshapes vendor economics across the United States.
United States
Medicare reimbursement codes for remote physiologic monitoring sustain payment pathways that compress hardware margins while amplifying software attach rates. The FDA's digital health pre-certification program accelerates software-as-medical-device classifications. Health systems in the Southeast deploy cellular-enabled homecare kits to reduce CMS readmission penalties in rural broadband gap zones.
Germany
Academic medical centers in Munich and Heidelberg pilot multi-parameter wearable patches for post-surgical step-down monitoring. The EU MDR extends conformity assessment timelines for algorithm-driven diagnostic platforms. Manufacturers maintain notified body relationships through Frankfurt-based authorized representative infrastructure.
China
Domestic MEMS foundry capacity expansion targets biosensor component supply for wearable device OEMs. The NMPA regulates software-as-medical-device classifications parallel to FDA pathways. Shenzhen hardware clusters integrate Bluetooth 5.3 with AI edge computing for low-power on-device inference.
Japan
Aging demographics drive demand for home-based chronic disease management platforms with cellular connectivity. The PMDA oversees clinical validation requirements for algorithm performance thresholds. Tokyo metropolitan health systems centralize remote monitoring centers that contract separately with device suppliers and clinical interpretation services.
United Kingdom
NHS procurement frameworks prioritize interoperability with HL7 FHIR standards for cloud-native monitoring platforms. The MHRA implements post-Brexit device regulations that retain EU MDR clinical evidence requirements. London-based health technology assessment bodies evaluate cost-effectiveness of remote patient monitoring for cardiopulmonary indications.
Telemonitoring Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the telemonitoring systems landscape. Hospital-grade platform developers maintain FDA-cleared algorithm portfolios and notified body relationships, while consumer wellness device manufacturers leverage pharmacy-retail distribution without clinical validation burdens. Three archetypes dominate: institutional-grade systems vendors, home monitoring specialists with disposable consumable economics, and software-native platforms with cloud-based clinical decision support. Competitive moves concentrate on strategic partnerships with health system procurement committees and geographic expansion into reimbursement-eligible homecare markets.
Within the institutional systems tier, Philips Healthcare and GE Healthcare occupy positions defined by enterprise-scale EHR integration capabilities. Dexcom, Inc. exemplifies the sensor-software integration archetype with recurring revenue models through disposable consumables. Medtronic plc anchors the diversified medical technology conglomerate position spanning cardiac rhythm management with remote monitoring infrastructure.
| Leading Market Players |
|---|
| Philips Healthcare |
| GE Healthcare |
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Omron Healthcare |
| ResMed Inc. |
| Dexcom, Inc. |
| Nihon Kohden Corporation |
| Others |
Value Network & Pricing Analysis
Health system procurement committees unbundling hardware acquisition from clinical interpretation services are forcing OEMs to absorb margin compression on capital equipment while capturing recurring software licensing revenue. This shift toward subscription economics concentrates pricing power with vendors who control algorithm portfolios and FDA-cleared decision support modules.
Pricing Analysis
Outcome-based pricing tied to reduced hospital readmission rates anchors value propositions for institutional-grade platforms. Pricing stratifies across FDA-cleared premium tiers, CE-marked standard tiers, and uncertified economy hardware for wellness applications. Cost compression in bedside monitor hardware is intensifying because procurement committees now compare total cost of ownership across five-year depreciation cycles. Homecare providers exhibit the highest price sensitivity due to thin Medicare reimbursement margins, while academic medical centers prioritize clinical validation over unit cost.
Supply Chain Analysis
Freight cost volatility for MEMS biosensor components has elevated inventory carrying costs for wearable device OEMs dependent on East Asian manufacturing clusters. Supply concentrates in Taiwan, South Korea, and China for MEMS foundry capacity, with adhesive substrate production centered in Japan and Germany. Component sourcing draws from specialized polymer suppliers, lithium-cell manufacturers, and semiconductor packaging facilities. Single-source vulnerability in advanced biosensor foundries creates lead time risk for multi-parameter patch launches. Distribution runs through health system GPO contracts, pharmacy-retail channels for consumer devices, and direct-to-provider agreements for homecare kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-parameter wearable patches integrating edge AI inference are displacing legacy bedside telemetry for stable post-surgical patients, compressing capital equipment procurement cycles while elevating disposable consumable economics.
For Market Incumbents: Hedge algorithm portfolio obsolescence by accelerating FDA submissions for Bluetooth 5.3-enabled edge computing platforms before software-as-medical-device pathways tighten. Deepen backward integration into MEMS foundry relationships to secure biosensor capacity against East Asian supply volatility. Prioritize notified body certification investments in Germany and the Netherlands to maintain EU MDR market access as conformity assessment timelines extend. For New Entrants and Emerging Players: CMS reimbursement code expansion for remote physiologic monitoring in the United States opens a window for behavioral health monitoring platforms in psychiatric and substance-use applications. Target underpenetrated mental health integration segments where clinical validation requirements remain lower than cardiopulmonary indications. Pursue hospital-at-home partnership models that bundle device supply with remote monitoring staffing to bypass established OEM service contracts. For Investors and Strategic Acquirers: The window for entry favors sensor-software integration specialists with recurring revenue models through disposable consumables. Viability over the next decade hinges on reimbursement pathway durability rather than hardware innovation cycles. Monitor FDA digital health pre-certification program expansion as the signal for accelerated software-as-medical-device valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Pre-Certification | Accelerates software-as-medical-device pathways for algorithm-driven diagnostic platforms. |
| CE Marking Pathway Investment | Secures EU MDR conformity for European hospital procurement channel access. |
| Hospital System Partnership | Enables unbundled hardware-service contracts with centralized remote monitoring centers. |
| Software Companion Development | Amplifies attach rates and recurring revenue through cloud-based clinical decision support. |
| Reimbursement Strategy | Aligns product portfolios with Medicare remote physiologic monitoring payment pathways. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving hospital procurement managers, biomedical engineers, GPO contracts specialists, and remote monitoring center directors. FDA 510(k) clearance databases, EU MDR technical documentation, CMS Medicare reimbursement schedules, and hospital procurement databases provided validation points. Bottom-up device shipment modeling and top-down health system spending estimates were triangulated to constrain variance.
Granularity extended to device-type, connectivity protocol, care setting, and clinical application dimensions across the projection horizon. CAGRs were derived from logistic diffusion modeling of reimbursement pathway adoption and health system infrastructure investment cycles. Forecast inputs incorporated MEMS foundry capacity utilization trends, cellular module pricing trajectories, and algorithm performance validation timelines.
The model assumes a particular technology adoption path; alternative pathways for AI edge computing convergence would alter the outlook if on-device inference latency drops below clinical alert thresholds faster than projected. Forecasts reflect documented assumptions about reimbursement granularity expansion and regulatory clearance velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Middle East and Africa Patient Monitoring Market
Patient Monitoring
Brain Monitoring Systems Market
Patient Monitoring
Drowsiness Monitoring System Market
Patient Monitoring
Global Multi-Parameter Patient Monitoring Equipment Market
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
Wearable Patient Monitor Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
United States Patient Monitoring Market
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
Patient Monitoring Devices Market
Patient Monitoring
Global Heart Rate Monitor Market
Patient Monitoring
South America Respiratory Monitoring Market
Patient Monitoring
Abetalipoproteinemia Monitoring Systems Market
Patient Monitoring
Latin America Self -Monitoring Blood Glucose Market
Patient Monitoring
Europe Fetal and Neonatal Monitoring Market
Patient Monitoring
Asthma Monitoring Devices Market