
 Oyster Sauce Market | 2026-2036
Oyster Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Oyster Sauce Market Analytics
Thailand is reconfiguring its position as a secondary oyster sauce manufacturing hub alongside established Chinese supply bases. Foshan Haitian Flavouring & Food Co. Ltd. dominates domestic distribution networks through backward integration into soy and oyster extraction facilities. Lee Kum Kee leverages century-old brand equity to anchor premium positioning in overseas Chinese diaspora markets. Kikkoman Corporation competes in the same premium tier with Japanese-style variants that emphasize lower sodium formulations.
Oyster sauce is a thick, dark brown condiment produced by reducing oyster extracts with salt, sugar, and caramel for umami depth, typically containing 30-45% soluble solids and serving as a finishing or cooking seasoning across East and Southeast Asian cuisines. Premium oyster sauce commands disproportionate margin pools in urban retail channels where consumers trade up for higher oyster extract content and cleaner label profiles. Vegetarian oyster sauce, formulated from mushrooms or kelp, captures the fastest-growing demand vector among plant-forward food manufacturers and institutional catering contracts seeking allergen-friendly alternatives.
China's SAMR enforces GB standards on fermented condiment labeling and additive limits, while Thailand's FDA-equivalent national food regulator monitors export certification for halal and quality compliance. The EU's EFSA evaluates imported sauce batches for heavy metal residues and sulfite declarations, creating compliance thresholds that filter smaller exporters from European supermarket listings. Stakeholders must monitor evolving clean-label mandates and extract-sourcing transparency requirements that will reshape supplier qualification protocols.
Market Dynamics
Home cooking penetration through digital recipe platforms is redrawing demand geography for oyster sauce, pulling manufacturing capacity toward Southeast Asian export corridors as North American retail adoption accelerates.
Growth Catalysts
- GB Standards Compliance:China's SAMR enforcement of stricter fermented condiment labeling and additive limits is filtering out subscale producers, concentrating volume among qualified manufacturers with captive extraction facilities.
- Plant-Forward Formulation:Mushroom and kelp-derived vegetarian variants are capturing institutional catering contracts seeking allergen-friendly alternatives, opening new procurement channels beyond traditional retail.
- Southeast Asian Export Infrastructure:Thai and Vietnamese production bases are scaling cold-chain logistics linking fermentation facilities to North American distribution hubs, reducing transit spoilage rates.
Market Restraints
- Oyster Extract Input Volatility:Wild oyster harvest fluctuations and aquaculture disease outbreaks in the Pearl River Delta create raw material cost instability for traditional formulation manufacturers.
- Heavy Metal Residue Thresholds:EFSA batch testing protocols for imported sauces screen smaller exporters from European supermarket listings, concentrating supply among large-scale certified producers.
- Sodium Reformulation Limits:Technical barriers to maintaining umami depth below 500mg sodium per serving constrain premium positioning for health-conscious urban consumers.
Strategic Opportunities
- Halal Certification Expansion:Thailand's FDA-equivalent national food regulator is streamlining export certification for halal compliance, unlocking Middle Eastern retail channels previously dominated by domestic producers.
- Clean-Label Transparency Mandates:Evolving extract-sourcing disclosure requirements are reshaping supplier qualification protocols, creating first-mover advantage for vertically integrated players with traceable supply chains.
- Direct-to-Consumer Digital Channels:Recipe platform integration and subscription box partnerships are bypassing traditional grocery slotting fees, enabling margin capture for mid-tier brands.
Industry Challenges
- Fermentation Microbiology Talent Scarcity:Skilled technicians capable of managing controlled enzymatic breakdown in oyster extraction are concentrated among legacy producers, constraining new facility commissioning.
- Legacy Equipment Retrofit Costs:Stainless steel tank farms and temperature-controlled aging cellars require substantial capital outlay, disadvantaging entrants against established depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oyster Sauce Market |
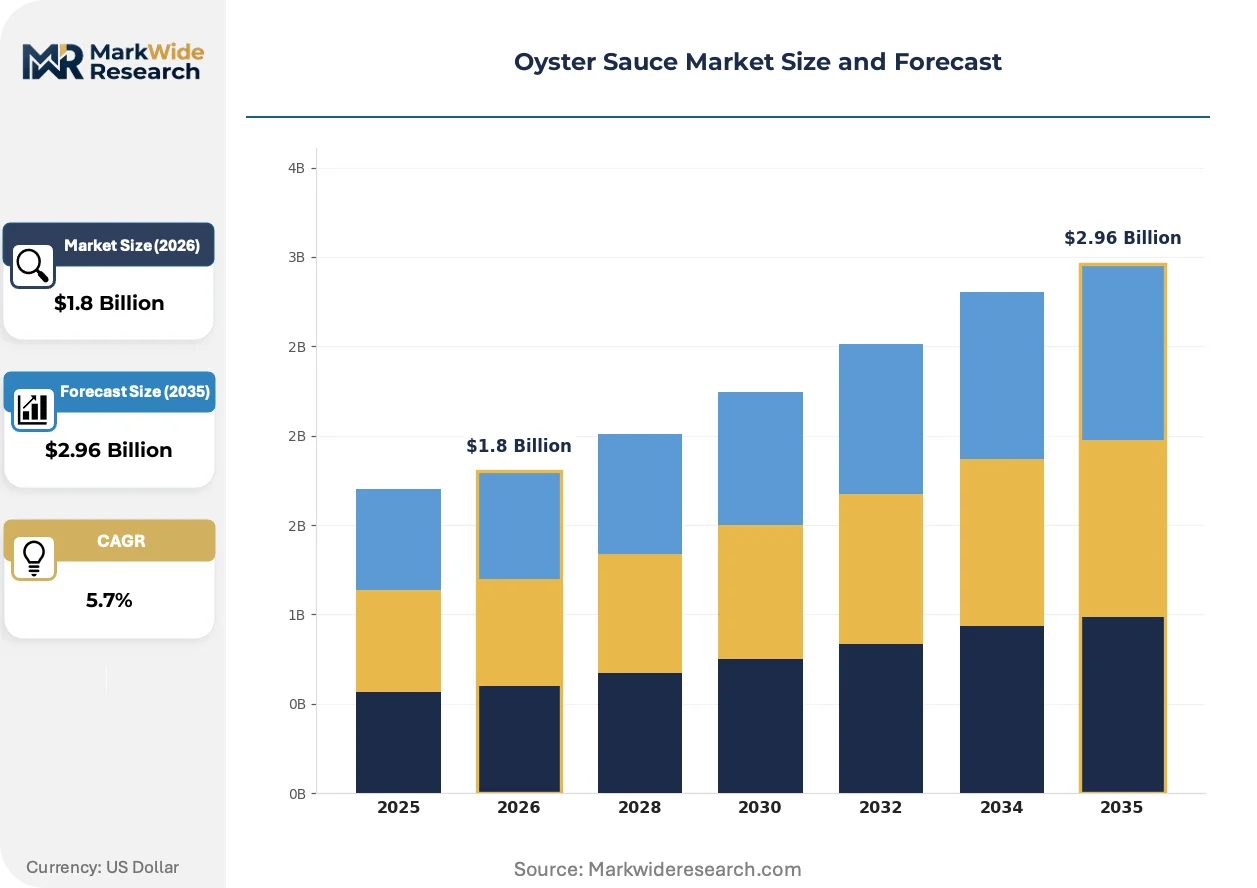
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Premium Oyster Sauce, Vegetarian Oyster Sauce, Organic Oyster Sauce, Chili Oyster Sauce End User: Restaurants, Home Cooks, Food Manufacturers, Catering Services Packaging Type: Bottles, Jars, Sachets, Tubs Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Food Service Distributors |
| Companies Covered | Ajinomoto Co., Inc., Fraser & Neave Holdings Bhd, Foshan Haitian Flavouring & Food Co. Ltd., Daesang Corp., Bachun Food Industries Pte Ltd., Lee Kum Kee, Nestlé SA, Wing Soon Food Manufacturer Pte Ltd., Kikkoman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oyster Sauce Market Evolving Landscape
Formulation science and regulatory transparency are converging to compress traditional manufacturing advantages, while digital channels rewire how home cooks discover and purchase condiments.
Enzymatic hydrolysis technology is collapsing the time required for oyster protein breakdown from months to days, enabling smaller batch production with consistent flavor profiles. Specialty sauce startups in Vietnam and Thailand are adopting these systems to serve regional restaurant chains demanding customized viscosity and salinity. This compression is eroding the scale advantages historically held by century-old fermentation houses with sunk-cost tank infrastructure.
EFSA heavy metal screening protocols and sulfite declaration requirements are tightening import documentation for European-bound shipments. Manufacturers must now maintain batch-level traceability from oyster bed to bottling line, increasing compliance overhead but also creating defensible positioning for certified exporters. Premium urban retail channels in Germany and France are responding by demanding third-party audit documentation as a listing prerequisite.
Recipe-driven discovery is displacing traditional aisle browsing as the primary purchase trigger for home cooks. Food content creators on short-form video platforms are embedding direct purchase links, compressing the path from inspiration to transaction. This behavioral shift is most visible in North American metropolitan markets where Asian cuisine penetration through digital media outpaces in-store ethnic aisle expansion.
Oyster Sauce Market Segmentation
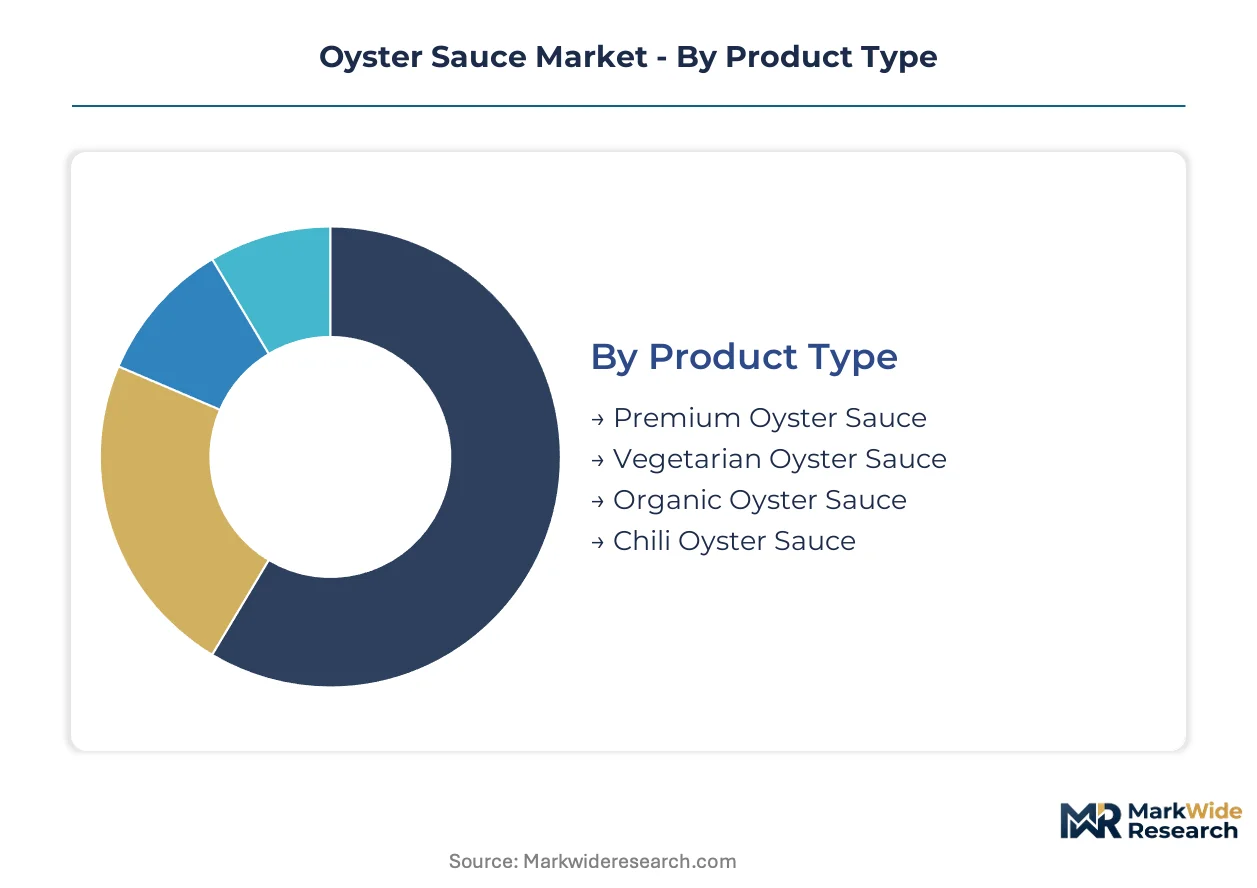
Oyster sauce manufacturers compete across distinct value tiers where formulation complexity and extract concentration determine margin capture. Packaging and channel strategies must align with divergent usage patterns between institutional food service and digital-native home cooks.
Product Type:
Premium formulations turn inventory slowest due to aging protocols and concentrated extract sourcing, while flavored variants cycle faster through promotional retail calendars.
- Premium Oyster Sauce:Contains 40-50% oyster extract by soluble solids, reduced with minimal caramel and no MSG. Urban retail channels in Shanghai and Bangkok drive demand as consumers trade up for cleaner labels and traceable sourcing.
- Vegetarian Oyster Sauce:Kelp and shiitake hydrolysates replicate umami depth for plant-forward institutional contracts. This segment is expanding most quickly among Southeast Asian exporters qualifying for Middle Eastern halal certification.
- Organic Oyster Sauce:Certified organic oyster beds and additive-free processing command shelf space in European premium grocers monitored by EFSA residue protocols.
- Chili Oyster Sauce:Regional Thai and Vietnamese variants with bird's eye pepper infusions target heat-preference segments in North American metropolitan markets.
Premium oyster sauce dominates installed base value. Vegetarian formulations are where expansion concentrates.
End User:
Cost tier stratification separates high-volume contract catering from discretionary retail purchases with divergent price elasticity profiles.
- Restaurants:Cantonese and Southeast Asian kitchen operations consume bulk formats through food service distributors. Consistency specifications and gallon-container logistics lock in supplier relationships across metropolitan dining corridors.
- Home Cooks:Recipe platform discovery drives trial of premium 150ml bottles in North American and European urban households. Digital purchase links embedded in short-form content compress traditional aisle-browsing behavior.
- Food Manufacturers:Industrial buyers procure standardized umami bases for frozen dim sum and ready-meal production under B2B contract terms with viscosity and salinity specifications.
- Catering Services:Institutional contract feeders source mid-tier formulations balancing cost controls with allergen-label compliance for large-batch preparation.
Restaurants anchor volume throughput. Home cooks are where margin expansion concentrates.
Packaging Type:
Application requirements dictate format selection—single-serve convenience versus kitchen-scale economy—with distinct supply chain implications for shelf stability and logistics density.
- Bottles:PET and glass containers dominate retail shelf presence across Chinese supermarkets and Southeast Asian export markets. Tamper-evident closures and pour-control spouts support premium positioning.
- Jars:Wide-mouth glass formats serve high-frequency home cooking segments requiring spoon-access for marinade preparation. Heavier unit economics limit export viability.
- Sachets:Single-serve foil pouches penetrate institutional catering and airline meal contracts where portion control and waste reduction override per-unit cost premiums.
- Tubs:Multi-kilogram polyethylene containers supply restaurant back-of-house operations through food service distributors with pallet-scale logistics.
Bottles dominate retail shelf space. Sachets are where format innovation concentrates.
Distribution Channel:
Geographic reach and customer acquisition cost separate consolidated supermarket listings from emerging direct-to-consumer pathways with divergent margin structures.
- Supermarkets:Tier-one chains in China, Thailand, and Vietnam control primary access to mass-market home cooks. Slotting fees and promotional calendar participation filter smaller brands from ethnic aisle placement.
- Online Retailers:E-commerce platforms and recipe-embedded purchase links bypass traditional grocery gatekeepers. Subscription box partnerships enable mid-tier brands to capture recurring revenue without retail markup.
- Specialty Stores:Asian grocery independents in North American and European cities serve diaspora communities seeking authentic import labels with Chinese or Thai origin marking.
- Food Service Distributors:Broadline operators like Sysco and US Foods handle institutional volume with customized viscosity and private-label formulation services.
Supermarkets anchor mass-market penetration. Online retailers are where customer acquisition concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity clusters along coastal aquaculture belts where oyster extraction feeds condiment manufacturing. China's Pearl River Delta anchors extraction volume, while Thailand and Vietnam scale export-oriented production for North American retail channels.
China
Domestic consumption absorbs the majority of fermented condiment output from Guangdong and Fujian provinces. SAMR enforces GB standards on additive limits and labeling transparency, filtering subscale producers from supermarket listings. Foshan hosts backward-integrated facilities combining soy and oyster extraction under single corporate control.
Thailand
Halal certification expansion unlocks Middle Eastern procurement channels previously closed to non-compliant exporters. The country's FDA-equivalent national food regulator streamlines export documentation for quality compliance. Bangkok-linked cold-chain corridors connect fermentation facilities to North American distribution hubs with reduced spoilage rates.
Vietnam
Specialty sauce startups adopt enzymatic hydrolysis systems to serve regional restaurant chains demanding customized formulations. Provincial manufacturing zones near Ho Chi Minh City concentrate mid-tier production for Southeast Asian intra-regional trade. E-commerce platform integration enables direct shipment to diaspora communities in Europe and North America.
United States
Recipe-driven discovery on short-form video platforms accelerates trial of premium imported bottles in metropolitan households. FDA labeling requirements govern imported condiment declarations, including sulfite and allergen disclosures. West Coast Asian grocery independents in Los Angeles and San Francisco anchor authentic import distribution.
Germany
EFSA heavy metal screening protocols and batch testing requirements filter smaller exporters from supermarket listings. Urban premium grocers in Berlin and Munich demand third-party audit documentation as a listing prerequisite. Clean-label positioning captures margin pools among health-conscious consumers seeking traceable sourcing.
Oyster Sauce Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with captive extraction or formulation capabilities. Market structure concentrates volume among legacy fermentation houses with sunk-cost tank infrastructure and century-old brand equity. Three archetypes dominate: vertically integrated condiment conglomerates with backward integration into raw material sourcing; premium specialists competing on extract concentration and clean-label positioning; and regional exporters leveraging halal certification and geographic proximity to emerging demand corridors. Competitive moves center on enzymatic technology licensing to collapse production timelines and strategic partnerships with recipe platforms to embed direct purchase links.
Among heritage-anchored specialists, Lee Kum Kee and Kikkoman Corporation occupy positions defined by brand longevity and premium-tier formulation science. Foshan Haitian Flavouring & Food Co. Ltd. exemplifies the integrated conglomerate archetype with in-house control over extraction and distribution networks. These three entities represent distinct competitive vectors: diaspora-market brand equity, Japanese-style health-positioned variants, and domestic Chinese scale with upstream captive supply.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Fraser & Neave Holdings Bhd |
| Foshan Haitian Flavouring & Food Co. Ltd. |
| Daesang Corp. |
| Bachun Food Industries Pte Ltd. |
| Lee Kum Kee |
| Nestlé SA |
| Wing Soon Food Manufacturer Pte Ltd. |
| Kikkoman Corporation |
| Others |
Value Network & Pricing Analysis
Wild oyster harvest volatility in the Pearl River Delta compresses margin spreads between premium and economy tiers while forcing manufacturers toward captive aquaculture or alternative protein sourcing. This input instability simultaneously widens price differentials for traceable supply chains and reshapes procurement geography toward Thailand and Vietnam.
Pricing Analysis
China's SAMR enforcement of GB standards on fermented condiment labeling dictates the pricing tier structure by filtering subscale producers from supermarket listings. Premium-mid-economy pricing differentiation hinges on oyster extract concentration and clean-label certification status. Cost compression in the economy tier is intensifying because bulk industrial buyers negotiate contract terms with viscosity specifications. Food service distributors exhibit highest price sensitivity while diaspora-market specialty stores accept substantial premiums for import-labeled authenticity.
Supply Chain Analysis
Oyster extraction capacity draws from China's Guangdong and Fujian provinces, Thailand's coastal aquaculture belts, and Vietnam's Mekong Delta fermentation zones. Raw material flows hinge on wild oyster beds, aquaculture pond systems, and kelp-shiitake hydrolysate inputs for vegetarian variants. Single-source vulnerability concentrates in Pearl River Delta extraction facilities facing disease outbreak risks. Distribution runs through Southeast Asian cold-chain corridors linking fermentation plants to North American retail hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated North American retail chains and recipe-platform aggregators, fragmenting traditional grocery slotting-fee leverage while concentrating volume among digitally integrated suppliers.
For Market Incumbents: Build certification moats through halal and organic audit documentation that EFSA and Thailand's FDA-equivalent now demand for European listings. Secure backward integration into aquaculture operations to buffer wild harvest volatility. Deepen channel control via direct recipe-platform partnerships that bypass traditional ethnic-aisle gatekeepers. Counter enzymatic hydrolysis startups by leveraging sunk-cost tank infrastructure for consistent batch aging. For New Entrants and Emerging Players: Pursue white-space positioning in vegetarian oyster sauce formulations for institutional catering contracts seeking allergen-friendly alternatives. Target Middle Eastern procurement channels where Thailand's streamlined halal certification creates entry pathways previously blocked to non-compliant Chinese exporters. Anchor go-to-market strategy through subscription box partnerships that capture recurring revenue without retail markup absorption. For Investors and Strategic Acquirers: EFSA heavy metal screening protocol expansion reshapes the acquisition landscape by filtering uncertified exporters from European supermarket listings. Five-to-ten year viability favors vertically integrated players with traceable supply chains from oyster bed to bottling line. Acquisition target archetype: Southeast Asian mid-tier manufacturers with halal certification and enzymatic technology licensing. Signal to monitor: batch-level traceability mandates spreading beyond Europe to North American retail chains.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Licensing | Collapses production timelines from months to days for smaller batch consistency. |
| Halal Certification Expansion | Unlocks Middle Eastern retail channels previously dominated by domestic producers. |
| Recipe Platform Integration | Embeds direct purchase links that compress inspiration-to-transaction pathways. |
| Backward Aquaculture Integration | Captures oyster bed supply to buffer wild harvest volatility and disease outbreaks. |
| Clean-Label Transparency Investment | Meets evolving extract-sourcing disclosure requirements reshaping supplier qualification. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with condiment manufacturing executives, fermentation microbiologists, food service procurement managers, and retail category buyers; and secondary validation through customs export records, SAMR GB standard filings, EFSA batch testing protocols, and Thai FDA-equivalent certification databases. Bottom-up volume triangulation from extraction facility capacity combined with top-down value estimation from retail channel markup structures anchored the market sizing.
Forecast inputs span product type segmentation by extract concentration and formulation, end-user stratification across restaurants and digital-native home cooks, packaging format economics, and distribution channel margin structures. CAGRs were derived from elasticity modeling against oyster input cost trajectories and regulatory compliance cost burdens. Industry-specific inputs include enzymatic technology adoption curves and halal certification penetration rates across Southeast Asian export corridors.
Sensitivities concentrate around wild oyster harvest fluctuations, aquaculture disease outbreaks, and tightening heavy metal residue thresholds that could revise volume assumptions. Forecasts reflect documented assumptions on technology diffusion and regulatory enforcement intensity. Quarterly review of EFSA screening protocol updates, SAMR labeling enforcement actions, and recipe-platform partnership announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
Vegan Sauces, Dressings and Spreads Market
Condiments & Sauces
Soy-Based Sauce Market
Condiments & Sauces
Sugar Toppings Market
Condiments & Sauces
Salad Dressings Market
Condiments & Sauces
United States Pasta Sauce Market
Condiments & Sauces
Vegan Pasta Sauce Market
Condiments & Sauces
Hot Sauce Powder Market
Condiments & Sauces
Low Salt Soy Sauce Market
Condiments & Sauces
Europe Pasta Sauce Market
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Ketchup Market
Condiments & Sauces
Vinegar and Vinaigrette Market
Condiments & Sauces
Table Sauce Market
Condiments & Sauces
Mayonnaise Market
Condiments & Sauces
Sandwich Spread Market