
 Cheese Sauce Market | 2026-2036
Cheese Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Cheese Sauce Market Analysis
North American dairy processors is shifting capacity toward aseptic cheese sauce production to serve quick-service restaurant chains. Kraft Heinz Company anchors retail shelf presence through its iconic brand portfolio and controlled distribution networks. Nestlé leverages global R&D infrastructure to develop regional flavor variants tailored to local palates. Gehl Foods specializes in aseptic pouch formats for foodservice fountain systems, sustaining its technical leadership in hot-hold applications.
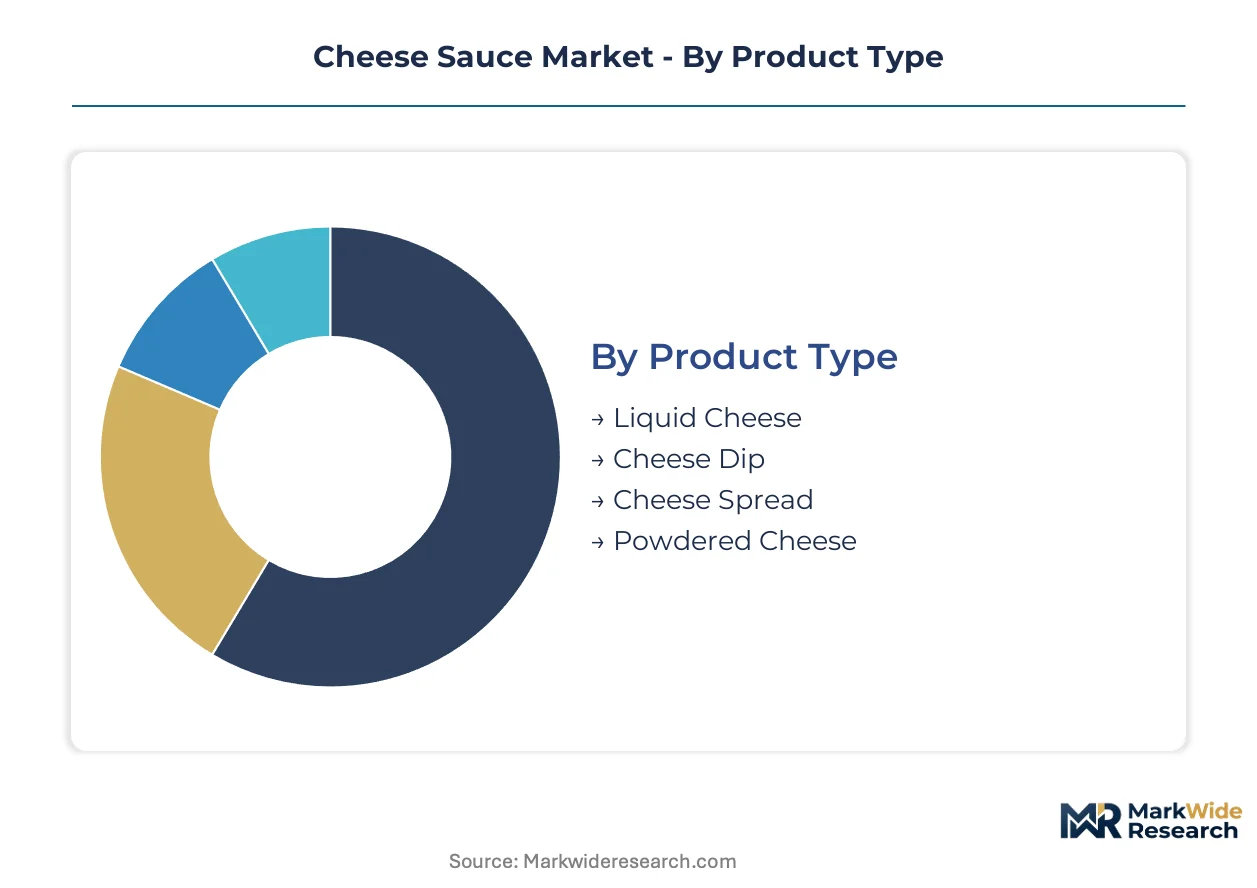
Cheese sauce is an emulsified dairy-based condiment typically containing processed cheese, milk solids, stabilizers, and emulsifying salts, manufactured through high-shear mixing and thermal processing to achieve pourable or dippable viscosity for hot or cold application across foodservice and retail channels. Liquid cheese leads volume due to fountain dispenser compatibility across quick-service chains, while cheese dip commands premium positioning in retail. Powdered cheese is accelerating fastest among industrial users seeking extended shelf stability and reduced freight costs, though margin pools concentrate in cheese spread formats sold through supermarkets.
The FDA governs cheese sauce labeling under standards of identity for pasteurized processed cheese products, while USDA oversight applies to school nutrition program formulations requiring specific fat and sodium thresholds. State-level dairy grading systems in Wisconsin and California create additional compliance layers for interstate suppliers. Stakeholders must monitor evolving sodium reduction targets and plant-based dairy alternative classifications that could reshape ingredient sourcing and competitive positioning.
Market Dynamics
Quick-service restaurant chains are forcing cheese sauce suppliers to accelerate clean-label reformulations while maintaining fountain-dispenser viscosity standards. FDA sodium reduction mandates are compressing product development timelines and requiring reformulation of legacy formulations.
Growth Catalysts
- Limited-Time Menu Cycles:Quick-service chains in the United States are rotating cheese sauce applications into seasonal offerings, driving volume spikes and supplier capacity expansion.
- Street-Food Flavor Localization:Demand concentration in Mexico is pulling regional product development toward chili-lime and chipotle variants tailored to local palates.
- Aseptic Pouch Technology:High-barrier packaging formats are extending hot-hold stability for foodservice fountain systems, enabling longer service windows without quality degradation.
Market Restraints
- Dairy Input Volatility:Fluid milk and cheese block prices fluctuate with commodity cycles, squeezing margin predictability for processors locked into annual quick-service contracts.
- Emulsifying Salt Dependence:Reformulation away from phosphates to meet clean-label demands degrades melt stability and shelf life, creating technical trade-offs.
- Interstate Compliance Friction:Wisconsin and California dairy grading systems impose divergent quality standards that fragment production batching for national distribution.
Strategic Opportunities
- Plant-Based Dairy Alternatives:FDA classification uncertainty around cashew and oat-based cheese sauces creates first-mover positioning for suppliers who secure GRAS determinations ahead of competitors.
- Industrial Powder Acceleration:Food manufacturers seeking extended shelf stability and reduced freight costs are shifting procurement toward dehydrated cheese sauce concentrates.
- School Nutrition Program Reformulation:USDA fat and sodium thresholds for K-12 meal programs create a captive institutional segment for compliant low-sodium formulations.
Industry Challenges
- Clean-Label Talent Scarcity:Food chemists skilled in phosphate-free emulsification and natural stabilizer systems command premium compensation and limited availability.
- Dual Certification Timelines:Simultaneous FDA standards-of-identity compliance and state dairy grading audits extend product launch cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheese Sauce Market |
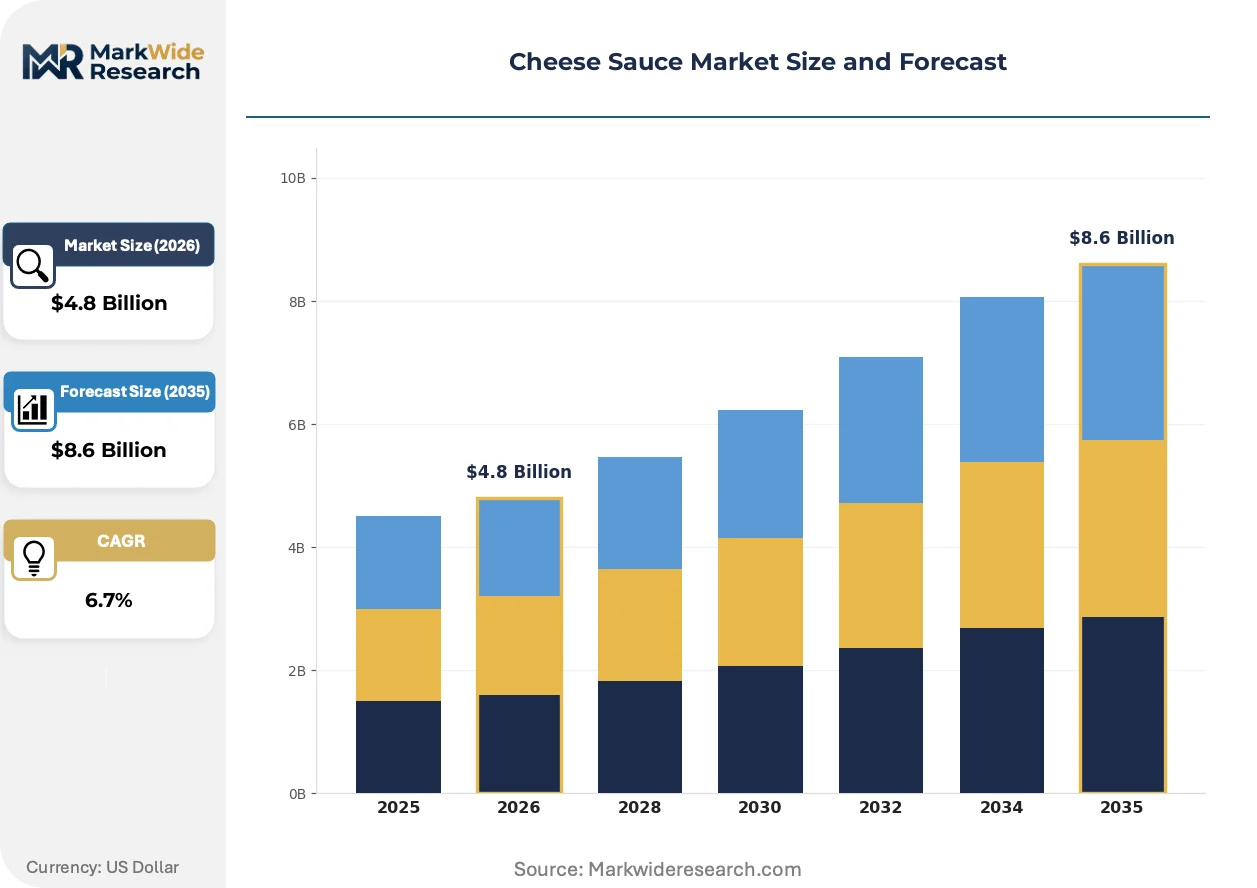
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cheese, Cheese Dip, Cheese Spread, Powdered Cheese End User: Food Service, Retail, Industrial, Catering Packaging Type: Tubs, Pouches, Jars, Cans Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Food Distributors |
| Companies Covered | Unilever, Campbell Soup Company, Kraft Heinz Company, Gehl Foods, McCormick & Company, Nestlé, Kerry Group, Cargill, Conagra Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheese Sauce Market Emerging Trajectories
Automation and regulatory pressure are converging to reshape cheese sauce manufacturing, with suppliers investing in precision processing to meet simultaneous demands for consistency, compliance, and customization.
High-shear thermal processing systems are automating viscosity control and emulsion stability in real-time production environments. Quick-service chains and co-manufacturers are adopting these systems to reduce batch-to-batch variation and eliminate manual quality checkpoints. This automation is compressing technical staff requirements while raising capital barriers for mid-tier processors.
FDA sodium reduction targets are forcing reformulation of pasteurized processed cheese products below current palatability thresholds. Manufacturers are responding with potassium chloride blends and umami enhancers, though these substitutes alter melt behavior in fountain applications. School nutrition programs and retail health-positioned lines face the steepest compliance cliffs.
Direct procurement from dairy processors is displacing traditional distributor intermediaries among large quick-service chains. Chains with sufficient volume are negotiating captive supply agreements that specify milk sourcing regions and processing parameters. This pattern concentrates most visibly in the United States, where vertical integration between restaurant chains and dairy cooperatives is deepening.
Cheese Sauce Market Segmentation
Cheese sauce suppliers face divergent certification burdens across product formats, with aseptic packaging and USDA school nutrition compliance creating tiered barriers to entry. Understanding how these requirements map to segment boundaries shapes both portfolio strategy and capital allocation decisions.
Product Type:
FDA standards of identity govern liquid cheese and processed cheese spreads most stringently, while powdered cheese operates under more flexible food additive classifications. USDA oversight applies selectively to formulations targeting institutional feeding programs.
- Liquid Cheese:Pourable emulsified dairy suspension designed for fountain dispenser compatibility. Quick-service chains in the United States concentrate procurement here, driven by limited-time menu cycles that demand consistent hot-hold viscosity across extended service windows.
- Cheese Dip:Thickened spoonable formulation with higher solids content and enhanced shelf stability. Retail channels in Mexico favor chili-lime and chipotle variants, with street-food flavor localization pulling regional product development investment.
- Cheese Spread:Refrigerated tub format with spreadable texture at ambient temperature. Margin pools concentrate in supermarket deli sections.
- Powdered Cheese:Dehydrated concentrate delivering extended shelf stability and reduced freight costs. Industrial users seeking formulation flexibility drive procurement shifts toward this format.
Liquid cheese sits at the top of the volume ranking, with powdered cheese climbing the fastest.
End User:
Cost tier differentiation separates commodity-scale foodservice contracts from premium retail positioning, with institutional procurement governed by distinct nutritional thresholds.
- Food Service:Fountain dispenser and hot-hold applications across quick-service chains and casual dining. FDA sodium reduction mandates compress reformulation timelines for legacy formulations.
- Retail:Branded and private-label offerings through supermarkets and convenience stores. Clean-label demands pressure emulsifying salt substitution.
- Industrial:Ingredient supply to processed food manufacturers. Powdered cheese procurement dominates here for shelf stability and freight efficiency.
- Catering:Bulk foodservice for events and institutional feeding. Wisconsin and California dairy grading systems fragment compliance for interstate suppliers.
Food service commands the largest revenue pool, with industrial procurement expanding most quickly.
Packaging Type:
Application requirements dictate format selection, with hot-hold stability and portion control driving divergent material specifications.
- Tubs:Refrigerated retail format for cheese spreads and dips. Supermarket deli placement demands eye-level positioning investment.
- Pouches:Aseptic high-barrier format extending hot-hold stability for fountain systems. Gehl Foods specializes here for foodservice technical leadership.
- Jars:Shelf-stable retail presentation with resealable closure. Premium positioning supports margin capture.
- Cans:Industrial-scale format for food manufacturing ingredient supply. Extended shelf life supports just-in-time procurement.
Pouches lead in foodservice volume growth, with tubs retaining retail dominance.
Distribution Channel:
Supply concentration varies sharply by channel, with direct procurement displacing traditional intermediaries among volume buyers.
- Online Retail:Direct-to-consumer and subscription formats. Premium positioning supports specialty flavor variants.
- Supermarkets:Primary retail channel for branded and private-label spreads. Kraft Heinz anchors shelf presence through controlled distribution networks.
- Convenience Stores:Grab-and-go cheese dip and spread portions. Impulse placement drives trial.
- Food Distributors:Broadline and specialty distribution to foodservice operators. Direct chain procurement is compressing this channel's share.
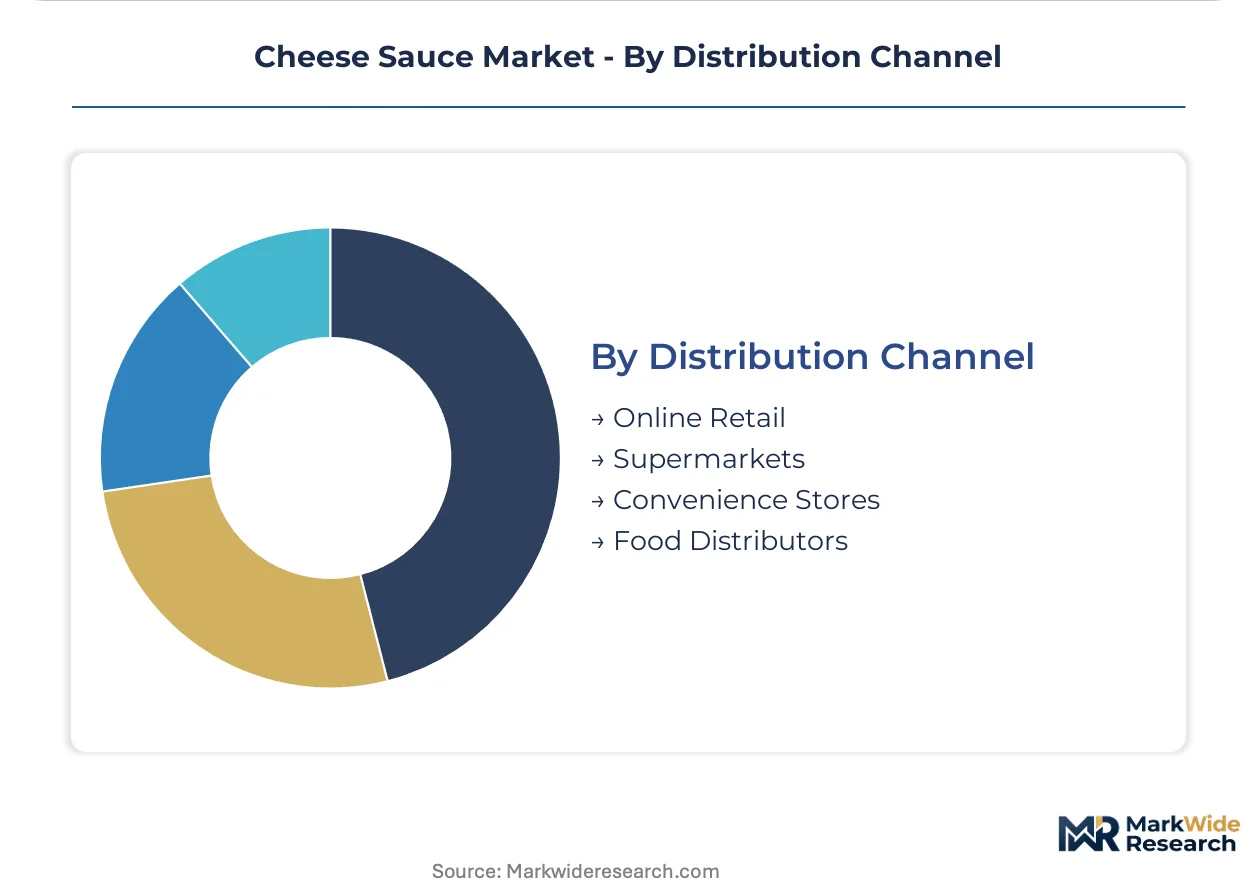
Supermarkets retain the largest transaction volume, with online retail gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cheese sauce production migrates toward jurisdictions with streamlined dairy grading protocols, creating cost-of-compliance arbitrage between state-level systems and federal frameworks. FDA sodium reduction mandates compress reformulation timelines unevenly across production bases, favoring facilities with integrated R&D capabilities.
United States
Quick-service restaurant chains drive procurement concentration through direct supply agreements specifying milk sourcing regions and processing parameters. FDA standards of identity for pasteurized processed cheese products govern labeling compliance, while USDA oversight applies to school nutrition program formulations. Wisconsin and California dairy grading systems fragment interstate production batching, with processors maintaining dual certification timelines extending launch cycles by six to nine months.
Mexico
Street-food-inspired flavor profiles pull regional product development toward chili-lime and chipotle variants tailored to local palates. The country's national food safety regulator enforces labeling standards for processed dairy products while accommodating traditional preparation methods. Mexico City Metro anchors foodservice demand, with quick-service chains rotating limited-time cheese sauce applications into seasonal offerings.
Canada
Health Canada governs cheese sauce formulations through dairy product regulations requiring bilingual labeling and compositional standards. Ontario and Quebec dairy processing clusters supply cross-border foodservice contracts, with aseptic pouch technology adoption extending hot-hold stability for fountain systems. Direct procurement from dairy cooperatives displaces traditional distributor intermediaries among large quick-service chains.
Germany
EFSA guidelines on processed cheese additives shape reformulation strategies for export-oriented manufacturers. Bavaria and North Rhine-Westphalia host dairy processing infrastructure serving retail private-label and foodservice channels. Clean-label demands pressure emulsifying salt substitution, with potassium chloride blends and umami enhancers altering melt behavior in heated applications.
United Kingdom
Retail channel concentration in supermarkets drives margin capture for branded and private-label cheese spreads. The Food Standards Agency enforces compositional standards for processed cheese products post-EU regulatory transition. London/Southeast anchors foodservice demand, with convenience store grab-and-go portions driving impulse trial for cheese dip formats.
Cheese Sauce Market Vendor Landscape
United States producers anchor one tier; European specialists hold formulation expertise for clean-label transitions. The vendor base clusters around three strategic archetypes: diversified food conglomerates with controlled distribution networks, dairy-focused processors with aseptic packaging technical leadership, and ingredient suppliers serving industrial powder acceleration. Competitive moves concentrate on backward integration into milk sourcing regions and captive supply agreements with volume buyers.
Within the diversified conglomerate tier, Kraft Heinz Company and Nestlé occupy positions defined by retail shelf presence and global R&D infrastructure respectively. Gehl Foods exemplifies the specialized processor archetype, with its company name indicating technical focus on foodservice fountain systems. Kerry Group represents the ingredient supplier vector, serving industrial users seeking dehydrated cheese sauce concentrates. These three anchors illustrate how competitive positioning fragments across retail anchoring, technical specialization, and industrial supply.
| Leading Market Players |
|---|
| Unilever |
| Campbell Soup Company |
| Kraft Heinz Company |
| Gehl Foods |
| McCormick & Company |
| Nestlé |
| Kerry Group |
| Cargill |
| Conagra Brands |
| Others |
Supply Flow & Price Mechanics
Fluid milk and cheese block commodity volatility cascades through processor margins into three-tier pricing structure across premium, standard, and economy levels, with quick-service chain contracts absorbing upstream cost swings while retail channels pass through spot-market adjustments.
Pricing Analysis
Distributor margin compression at the foodservice tier separates captive supply agreements from spot procurement. Pricing stratifies across premium, standard, and economy tiers based on aseptic certification grade and volume scale commitments. Cost compression in the industrial powder segment is intensifying because freight efficiency demands concentrate procurement power among large food manufacturers. Retail channels exhibit highest price sensitivity due to private-label substitution elasticity, while institutional school nutrition programs show lowest sensitivity given compliant formulation mandates.
Supply Chain Analysis
Workforce availability constraints in Wisconsin and California dairy processing clusters limit batch expansion capacity during seasonal demand spikes. Supply concentrates in the United States, Mexico, and Canada, with raw material dependencies on fluid milk, processed cheese solids, and emulsifying salts. Single-source vulnerability around phosphate-free stabilizer suppliers creates reformulation bottlenecks for clean-label transitions. Distribution runs through direct procurement agreements displacing traditional broadline foodservice intermediaries among volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where quick-service chains are shifting procurement specifications toward extended hot-hold stability and sodium-compliant formulations that command premium positioning.
For Market Incumbents: Deepen backward integration into milk sourcing regions to lock in cost predictability against commodity volatility. Secure dual FDA standards-of-identity and state dairy grading certifications ahead of competitors to compress launch timelines. Prioritize captive supply agreements with expanding quick-service chains in Mexico where street-food flavor localization accelerates volume concentration. For New Entrants and Emerging Players: Phosphate-free emulsification expertise offers entry into the clean-label reformulation segment where talent scarcity limits incumbent response speed. Target industrial powder procurement where extended shelf stability requirements favor new processing infrastructure. Pursue school nutrition program compliance as a go-to-market anchor given USDA fat and sodium thresholds create captive institutional demand. For Investors and Strategic Acquirers: Consolidation pressure builds where dual certification timelines extend product launch cycles by six to nine months, advantaging scaled processors with integrated R&D capabilities. Mid-tier dairy processors with aseptic pouch technical leadership represent priority acquisition archetypes. Watch FDA plant-based dairy alternative classification determinations as an inflection signal for first-mover positioning in cashew and oat-based cheese sauce segments.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Pouch Capacity Expansion | Gehl Foods' technical leadership in hot-hold fountain systems extends service windows without quality degradation. |
| Clean-Label Reformulation Investment | Potassium chloride blends and umami enhancers alter melt behavior for FDA sodium reduction compliance. |
| Direct Supply Agreement Negotiation | Kraft Heinz and Nestlé anchor retail and foodservice positioning through controlled distribution networks. |
| Regional Flavor Variant Development | Chili-lime and chipotle formulations tailored to Mexico City Metro quick-service demand pull R&D investment southward. |
| Industrial Powder Production Scale-Up | Kerry Group serves food manufacturers seeking dehydrated concentrates for shelf stability and freight efficiency. |
Methodological Framework
Bottom-up foodservice and retail channel modeling reconciled against top-down dairy processor capacity tracking forms the analytical core. Primary interviews with quick-service chain procurement directors, dairy cooperative supply managers, foodservice distribution executives, and regulatory compliance officers combined with secondary validation from FDA standards-of-identity filings, USDA school nutrition program specifications, Wisconsin and California dairy grading records, and SEC processor filings.
Input-output matrices map fluid milk supply through processed cheese solids to finished sauce formats across product type, end user, packaging, and distribution channel dimensions. CAGRs derive from segment-level volume trajectories calibrated against historical commodity price cycles and quick-service menu rotation patterns. Forecast inputs incorporate aseptic packaging adoption curves and sodium reduction compliance timelines without year-specific anchoring.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA plant-based classification rulings and dairy input commodity volatility. Material deviation in clean-label reformulation technology availability or interstate compliance friction warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Sun-Dried Tomato Umami Concentrate Systems Market
Condiments & Sauces
Vinegar and Vinaigrette Market
Condiments & Sauces
Dips and Spreads Market
Condiments & Sauces
Vegan Pasta Sauce Market
Condiments & Sauces
Gluten-Free Soups and Sauces Market
Condiments & Sauces
Tomato Ketchup Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Oriental Sauce Market
Condiments & Sauces
Fat Free Salad Dressings Market
Condiments & Sauces
Horseradish Sauce Market
Condiments & Sauces
Table Sauce Market
Condiments & Sauces
Latin America Pasta Sauce Market
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
Mayonnaise Market
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
Asia Pacific Fish Sauce Market