
 Vegan Sauces Market | 2026-2036
Vegan Sauces Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Sauces Market Analytics
North American production capacity is fragmenting as co-manufacturers and specialty food processors add dedicated allergen-free lines across the United States and Canada. Amy's Kitchen leverages its organic supply chain infrastructure to secure premium placement in natural grocery channels. Daiya Foods competes through cheese-alternative expertise that extends into creamy sauce formulations. Follow Your Heart anchors West Coast distribution with refrigerated plant-based dressings that command dedicated cooler space.
Vegan sauces comprise emulsified or suspended condiment formulations derived exclusively from plant sources, excluding all animal derivatives such as dairy, eggs, honey, or fish-based ingredients, with shelf stability typically achieved through pH adjustment below 4.6 or thermal processing at 85–95°C. These products serve commercial foodservice operators and retail consumers seeking flavor delivery without animal inputs. Salad dressings occupy the largest margin pool due to refrigerated premium positioning and shorter ingredient lists that justify price premiums. Nuts and seeds as ingredient sources represent the fastest-expanding formulation category, driven by cashew-based creaminess that mimics dairy mouthfeel. Foodservice distribution channels sustain higher volume throughput despite thinner per-unit margins, particularly in burger chains and salad-bar concepts.
The FDA governs allergen labeling and facility segregation requirements for plant-based foods manufactured in shared equipment environments, while USDA Organic certification shapes ingredient sourcing premiums across the supply base. The EU Green Deal's sustainability reporting obligations, implemented through CSRD, now require mid-sized vegan food producers to document Scope 3 emissions from agricultural inputs. Stakeholders must monitor how FDA guidance on dairy identity standards evolves, as enforcement actions against plant-based labeling claims could force reformulation costs or packaging redesigns across the category.
Market Dynamics
EU Green Deal labeling mandates and FDA dairy identity standard debates are forcing simultaneous reformulation and packaging redesign across the vegan sauces category, compressing margin recovery timelines for mid-sized producers.
Growth Catalysts
- CSRD Scope 3 reporting:The EU's sustainability disclosure rules now require documented agricultural emissions from ingredient suppliers, accelerating consolidation toward vertically integrated organic processors who control farm-level data.
- Quick-service restaurant procurement:Burger chains and salad-bar concepts across the United States and Canada now specify plant-based condiments in contract tenders, pulling volume through foodservice distribution at scale.
- Cashew cream emulsion technology:Advances in high-pressure processing of nut-based suspensions achieve dairy-comparable mouthfeel without stabilizer-heavy formulations, opening clean-label positioning in refrigerated dressings.
Market Restraints
- Input cost volatility:Organic cashew prices fluctuate with West African and South Asian harvest cycles, squeezing margin predictability for premium-positioned creamy sauce lines.
- Shared equipment segregation:FDA allergen labeling requirements for facilities processing both dairy and plant-based products impose costly line-dedicated capital expenditure or third-party co-manufacturer premiums.
- pH-stability technical ceiling:Clean-label vinegar alternatives struggle to achieve sub-4.6 pH thresholds without synthetic acidulants, limiting shelf-stable clean-positioned offerings.
Strategic Opportunities
- German retail shelf expansion:Discounters and conventional supermarkets in Germany have quadrupled dedicated vegan condiment facings since Farm to Fork strategy implementation, creating first-mover positioning for imported brands.
- Direct-to-foodservice formulation services:Custom sauce development for regional burger chains bypasses retail slotting fee barriers while capturing higher margin through exclusive supply agreements.
- USDA Organic certification arbitrage:Mid-sized processors who secure organic supply chain verification command 15-30% price premiums in natural grocery channels where certification substitutes for brand recognition.
Industry Challenges
- Food safety certification timelines:SQF and BRCGS audits for allergen-free line validation extend 6-12 months, delaying commercialization of reformulated products during peak demand windows.
- Emulsion chemistry talent scarcity:Formulation chemists with plant-protein stabilization expertise command premium compensation, constraining R&D throughput for emerging brands without captive technical teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Sauces Market |
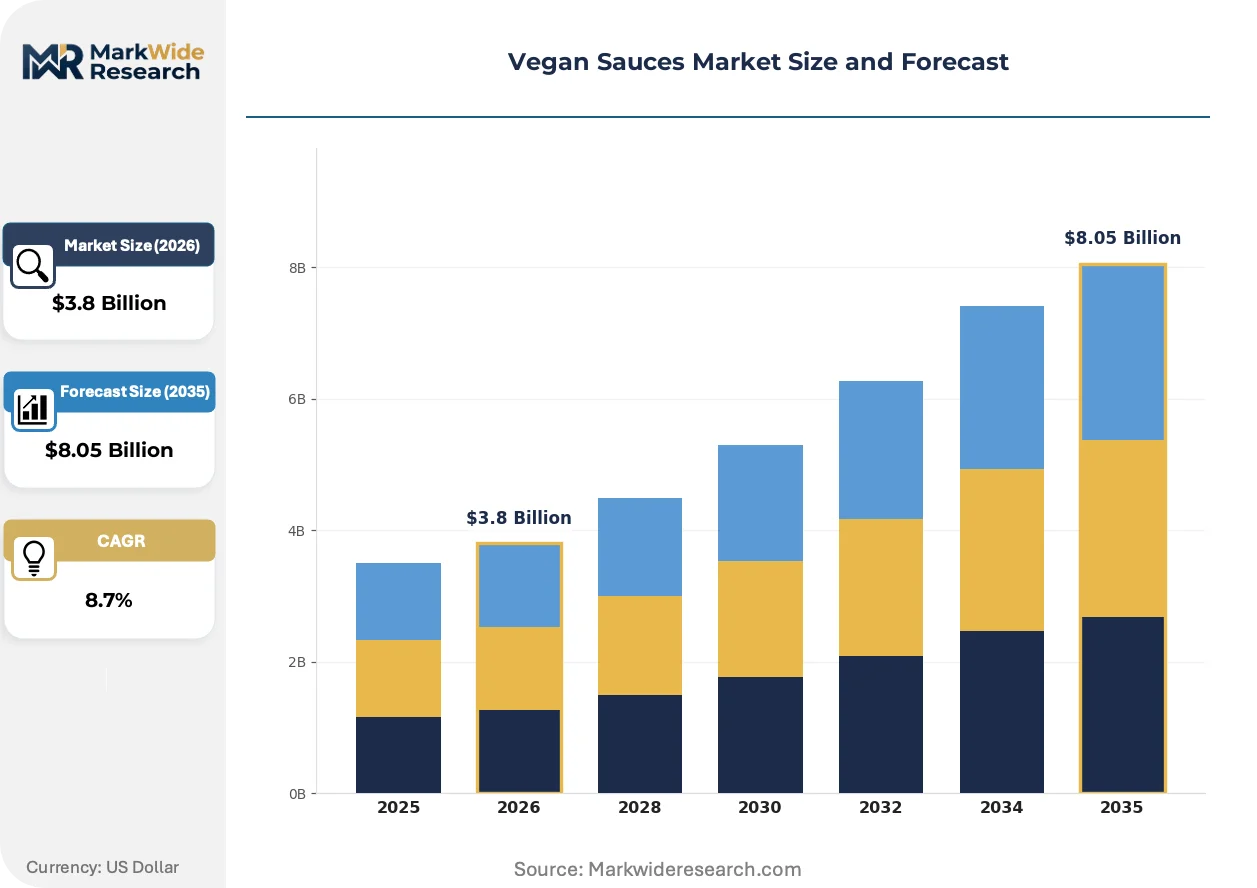
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ketchup, Mustard, Salad Dressings, Marinades Ingredient Source: Legumes, Nuts, Vegetables, Seeds Packaging Type: Bottles, Pouches, Jars, Tubs Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Foodservice |
| Companies Covered | Amy's Kitchen, B&G Foods, Follow Your Heart, Daiya Foods, Bear Pond Farm, Litehouse, Red Duck Foods, Meridian Foods, KENSINGTON & SONS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Sauces Market Evolving Landscape
Clean-label emulsion science and regulatory disclosure mandates are compressing traditional formulation approaches while reshaping how producers document supply chain provenance.
High-pressure processing of raw cashew and sunflower seed bases is collapsing the performance gap between plant-derived creams and conventional dairy emulsions. Refrigerated dressing manufacturers in California and New York have adopted this technology at commercial scale since 2023. The resulting mouthfeel parity eliminates the stabilizer-heavy ingredient decks that previously limited clean-label claims.
EU Green Deal Farm to Fork strategy implementation through CSRD now mandates Scope 3 emissions documentation from agricultural inputs. Mid-sized vegan sauce producers must trace nut and oilseed farming practices back to cultivation. German and Dutch facilities face the most immediate compliance deadlines, driving accelerated supplier consolidation toward vertically integrated organic operations.
Foodservice operators are unbundling condiment procurement from broadline distributor agreements. Regional quick-service chains now negotiate direct formulation contracts with specialty sauce processors, bypassing traditional redistribution markups. This pattern concentrates most visibly in Texas and Florida burger markets where plant-based menu penetration has outpaced national averages.
Vegan Sauces Market Segmentation
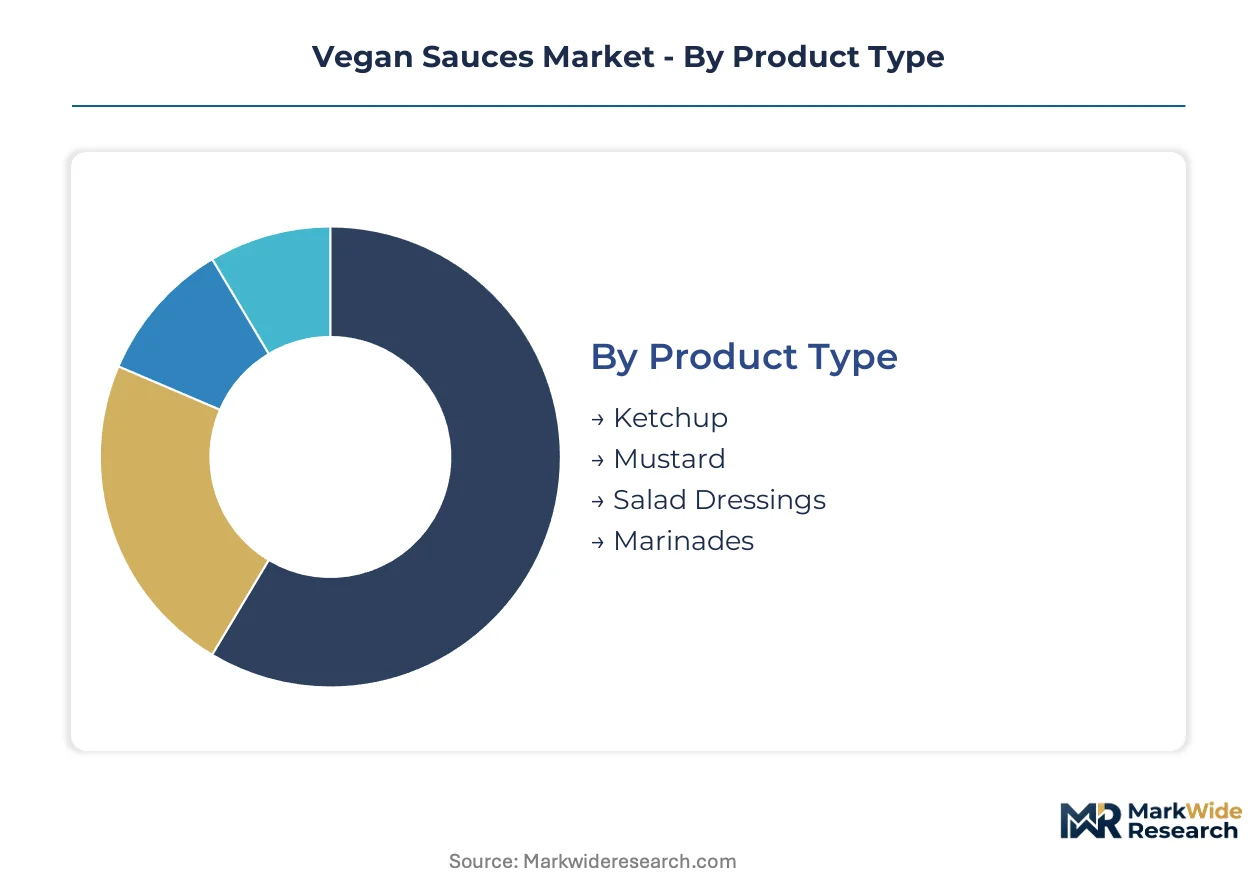
Vegan sauces fragment across formulation chemistry, ingredient provenance, and channel velocity. Each segmentation axis reveals distinct margin structures and capital intensity requirements that shape producer strategic positioning.
Product Type:
Inventory velocity varies dramatically across this category, with refrigerated lines turning three to four times faster than shelf-stable formulations due to shorter dating and premium placement.
- Salad Dressings:Emulsified oil-and-acid suspensions requiring refrigerated cold chain maintenance. Demand clusters in natural grocery channels across the United States and Germany, where shorter ingredient lists support 40-60% price premiums over conventional alternatives. FDA dairy identity standard debates create labeling uncertainty that favors oil-based formulations over nut-cream emulsions in mass retail.
- Ketchup:Thermally processed tomato-based condiments with pH-adjusted shelf stability below 4.6. Quick-service burger chains in Texas and Florida specify plant-based tomato profiles in procurement contracts, driving volume through foodservice redistribution networks at thinner per-unit margins.
- Mustard:Acidulated seed pastes achieving preservation through vinegar content and low water activity. German retail expansion under Farm to Fork implementation has quadrupled dedicated facings for Dijon and whole-grain variants.
- Marinades:High-acid liquid formulations for protein pre-treatment with shorter commercialization timelines due to simpler emulsion requirements. Asian-inspired flavor profiles gain traction in California and New York metro areas.
Salad dressings dominate installed base value. Marinades represent where expansion concentrates most steeply among emerging brands seeking lower barrier-to-entry positioning.
Ingredient Source:
Cost tiers stratify sharply based on agricultural input scarcity and processing complexity, with tree nuts commanding 3-5x premiums over legume bases.
- Nuts:Cashew and almond suspensions processed through high-pressure homogenization to achieve dairy-comparable mouthfeel. West African and South Asian harvest volatility squeezes margin predictability for premium creamy sauce lines dependent on organic certification.
- Seeds:Sunflower and hemp emulsions gaining formulation share as cashew cost pressures mount. German processors lead commercial adoption of seed-based clean-label positioning.
- Legumes:Chickpea and lentil bases offering the lowest raw material cost structure with neutral flavor profiles suitable for neutral carrier applications.
- Vegetables:Tomato, pepper, and root vegetable purees forming the backbone of shelf-stable condiment categories with established agricultural supply chains.
Vegetables anchor volume throughput. Nuts capture where margin expansion concentrates.
Packaging Type:
Channel requirements dictate format selection, with foodservice favoring operational efficiency and retail prioritizing shelf differentiation.
- Bottles:PET and glass containers dominating retail condiment aisles with established consumer handling expectations and established filling line infrastructure across United States and Canadian production facilities.
- Pouches:Flexible film formats reducing shipping cube and material cost for foodservice bulk delivery. Salad-bar concepts in quick-service chains specify pouch dispensing compatibility.
- Jars:Wide-mouth glass containers for spoonable spreads and thicker emulsions requiring scoop access. Premium positioning in specialty retail channels.
- Tubs:Refrigerated dairy-alternative formats mimicking conventional sour cream and yogurt packaging for consumer familiarity in natural grocery.
Bottles retain installed base dominance. Pouches are where foodservice format innovation concentrates.
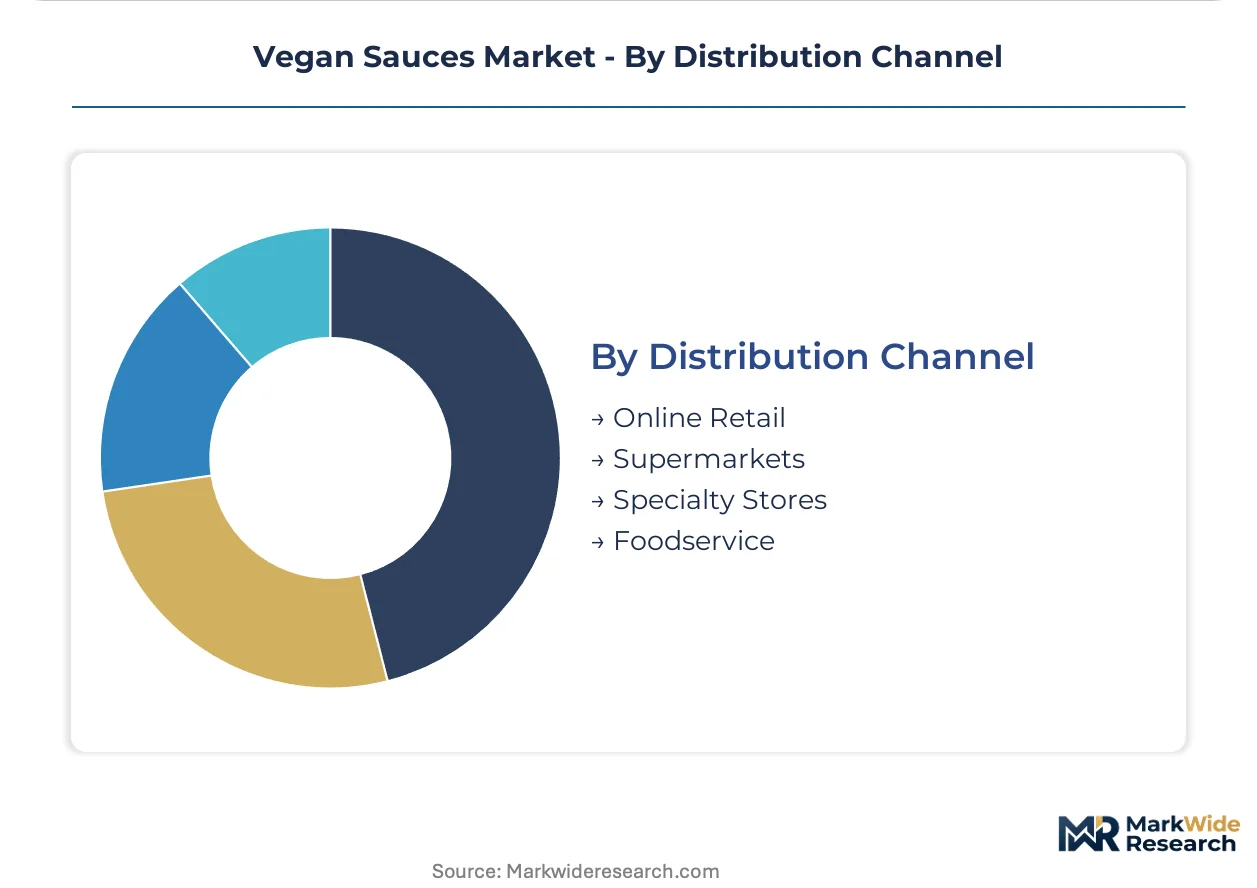
Distribution Channel:
Margin structure inverts across this axis, with direct foodservice contracts capturing higher per-unit economics despite lower brand visibility.
- Foodservice:Direct formulation agreements with regional burger chains and salad-bar concepts bypassing traditional redistribution markups. Volume concentrates in Texas and Florida markets where plant-based menu penetration exceeds national benchmarks.
- Supermarkets:Conventional grocery placement requiring slotting fee investment and refrigerated cooler space negotiation. German discounters have quadrupled vegan condiment facings since EU Green Deal implementation.
- Specialty Stores:Natural grocery channels where USDA Organic certification substitutes for brand recognition and commands 15-30% price premiums.
- Online Retail:Direct-to-consumer subscription models for niche flavor profiles with higher fulfillment cost absorption through premium pricing.
Supermarkets dominate installed base reach. Foodservice is where producer margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites European distribution capacity for refrigerated plant-based condiments, while Union Pacific's refrigerated rail corridors connect California production clusters to Texas and Florida foodservice markets.
United States
Quick-service burger chains in Texas and Florida specify plant-based condiments in procurement contracts, pulling volume through foodservice redistribution networks. FDA dairy identity standard debates create labeling uncertainty that favors oil-based formulations over nut-cream emulsions in mass retail. California's high-pressure processing facilities anchor clean-label refrigerated dressing production for natural grocery channels.
Germany
Discounters and conventional supermarkets have quadrupled dedicated vegan condiment facings since EU Green Deal Farm to Fork implementation. CSRD Scope 3 reporting requirements now mandate documented agricultural emissions from nut and oilseed suppliers. Cologne and Hamburg processing facilities face immediate compliance deadlines, driving supplier consolidation toward vertically integrated organic operations.
Canada
Co-manufacturers across Ontario and Quebec add dedicated allergen-free lines to serve North American contract manufacturing demand. Health Canada facility segregation requirements for shared dairy and plant-based equipment impose validation timelines that extend commercialization windows. Toronto-area processors capture USDA Organic certification premiums for cross-border natural grocery distribution.
United Kingdom
Refrigerated plant-based dressing demand clusters in London and Southeast England natural grocery channels. FSA allergen labeling enforcement maintains strict facility segregation standards for nut-based emulsion production. Manchester and Birmingham distribution hubs coordinate Irish Sea freight connections to continental European retail networks.
Netherlands
Amsterdam and Rotterdam serve as consolidation points for EU Green Deal compliance documentation across agricultural input supply chains. EFSA novel food approval pathways for emerging seed-based emulsions create regulatory bottlenecks that Dutch processors navigate through pre-submission consultation protocols. Wageningen University research partnerships accelerate clean-label formulation development for export-oriented sauce producers.
Vegan Sauces Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient supply and co-manufacturing services. The vendor base stratifies across three tiers: multinational condiment houses with broadline distribution, mid-sized organic processors with captive supply chain verification, and emerging specialty brands focused on single-format excellence. Two dominant competitive moves define current positioning: direct-to-foodservice formulation contracts that bypass retail slotting fees, and backward integration into organic nut and seed sourcing to secure Scope 3 emissions documentation for EU market access.
Within the organic processor tier, Amy's Kitchen and Follow Your Heart exemplify supply chain infrastructure strategies that secure premium placement in natural grocery channels. Daiya Foods occupies a position at the intersection of cheese-alternative expertise and creamy sauce formulation extension. These three California-based entities represent distinct archetypes of how regional production clusters leverage organic certification, refrigerated distribution networks, and clean-label positioning to capture margin premiums in a category where regulatory compliance costs increasingly favor scaled operations with captive technical teams.
| Leading Market Players |
|---|
| Amy's Kitchen |
| B&G Foods |
| Follow Your Heart |
| Daiya Foods |
| Bear Pond Farm |
| Litehouse |
| Red Duck Foods |
| Meridian Foods |
| KENSINGTON & SONS |
| Others |
Value Network & Pricing Analysis
California's high-pressure processing clusters anchor clean-label refrigerated dressing capacity, translating equipment scarcity into 15-30% price premiums for USDA Organic-certified processors who command natural grocery shelf placement.
Pricing Analysis
Volume-discount tiering structures stratify across three levels: premium refrigerated lines with organic certification, standard shelf-stable formulations, and economy private-label alternatives. Price differentiation rests on certification grade and cold-chain delivery cost. Pricing pressure intensifies in the premium tier as organic cashew input volatility squeezes margin predictability. Quick-service burger chains exhibit highest price sensitivity through foodservice contract negotiations, while specialty natural grocery consumers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Ontario and Quebec co-manufacturers hold expanding allergen-free line capacity for North American contract manufacturing demand. Raw material flows draw from West African and South Asian cashew harvests, California sunflower seed processors, and domestic vegetable puree suppliers. Single-source vulnerability concentrates in organic nut supply chains subject to climate-driven harvest disruption. Distribution runs through refrigerated rail corridors connecting California production to Texas and Florida foodservice markets, with Port of Rotterdam cold chain infrastructure underwriting European reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a regulatory-entrenchment defensive moat, where EU Green Deal CSRD compliance documentation and FDA facility segregation requirements create capital barriers that favor scaled operators with captive supply chain verification systems.
For Market Incumbents: Entrench positioning through backward integration into organic nut and seed sourcing to secure Scope 3 emissions documentation for EU market access, while expanding dedicated allergen-free line capacity in California and Ontario to capture co-manufacturing premiums from emerging brands lacking SQF validation capabilities. For New Entrants and Emerging Players: Pursue white-space positioning in German discounter shelf expansion under Farm to Fork implementation, where quadrupled vegan condiment facings create first-mover import opportunities. Direct-to-foodservice formulation contracts for regional burger chains bypass retail slotting fee barriers while capturing higher margin through exclusive supply agreements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated organic processors with captive farm-level data systems and established SQF/BRCGS certifications. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than brand equity alone. The signal to watch is FDA enforcement action evolution on dairy identity standards, which could force reformulation costs that disproportionately burden non-compliant targets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Sourcing | Captive supply of certified nuts and seeds secures CSRD Scope 3 documentation for EU Green Deal compliance. |
| High-Pressure Processing Capacity Expansion | Clean-label emulsion technology eliminates stabilizer-heavy ingredient decks in refrigerated dressing production. |
| Direct-to-Foodservice Formulation Contracts | Exclusive supply agreements with Texas and Florida burger chains bypass retail slotting fees and capture margin premiums. |
| SQF/BRCGS Allergen-Free Line Certification | Six-to-twelve month validation timelines create competitive barriers against emerging brands lacking technical infrastructure. |
| German Retail Shelf Positioning | Farm to Fork strategy implementation has quadrupled dedicated vegan condiment facings in discounter channels. |
Research Methodology
The analysis maps salad dressing, ketchup, mustard, and marinade sub-sectors, each validated through formulation chemists, foodservice procurement directors, natural grocery category buyers, and co-manufacturing facility managers. Primary interview data triangulates against FDA guidance documents, USDA Organic certification databases, EU CSRD implementation frameworks, and refrigerated distribution trade flow records. Bottom-up production capacity modeling converges with top-down retail velocity estimates.
Assumptions held fixed include EU Green Deal Farm to Fork implementation timelines and FDA dairy identity standard debate resolution pathways, while organic input cost volatility and quick-service restaurant plant-based menu penetration rates were varied across sensitivity scenarios. Segmentation dimensions span formulation chemistry, ingredient provenance, packaging format, and channel velocity. CAGRs derive from installed base turnover analysis and premium positioning elasticity. Forecast inputs incorporate West African cashew harvest cycle patterns and high-pressure processing equipment deployment trajectories.
Sensitivities concentrate around FDA enforcement action timing on plant-based labeling claims and organic certification audit backlog durations. Forecasts reflect documented assumptions regarding regulatory implementation cadence and foodservice contract renewal cycles. Quarterly review of CSRD compliance deadline adjustments and quick-service chain procurement specification changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
West Africa Mayonnaise Market
Condiments & Sauces
Chocolate Syrup Market
Condiments & Sauces
Asia Pacific Fish Sauce Market
Condiments & Sauces
Mayonnaise Sauce Market
Condiments & Sauces
Pasta Sauce Market
Condiments & Sauces
Dips and Spreads Market
Condiments & Sauces
Global Hot Pot Condiment Market
Condiments & Sauces
Sweet and Savory Spread Market
Condiments & Sauces
Egg-Free Mayonnaise Market
Condiments & Sauces
UK Prepared Mustard Market
Condiments & Sauces
Latin America Pasta Sauce Market
Condiments & Sauces
Mayonnaise Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Hoisin Sauce Market
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Cocktail Syrups Market