
 Sugar Toppings Market | 2026-2036
Sugar Toppings Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Toppings Market Analysis
Modular portion packs and single-serve sachets are broadening buyer choice across foodservice channels. Cargill Inc. leverages its integrated sweetener supply chain to dominate bulk liquid sugar deliveries to national restaurant chains. The Hershey Company sustains brand loyalty through specialty chocolate-sugar blends positioned at premium price points. Monin Inc. competes in the café segment with flavored syrup-topping hybrids that reduce inventory complexity for baristas.
Sugar toppings comprise crystalline, liquid, and powdered sucrose-based formulations applied to finished foods for sweetness, texture, and visual appeal, with particle size and moisture content determining functional performance in baking and beverage applications. Granulated and brown sugar variants anchor household purchasing through supermarket and convenience store channels, while liquid sugar concentrates capture margin pools in industrial food manufacturing where dosing precision reduces waste. Powdered sugar leads baking applications due to its rapid dissolution, though confectionery demand for specialty grain sizes is expanding fastest among artisan producers.
The FDA enforces added-sugar disclosure on Nutrition Facts panels, compelling reformulation toward reduced-sugar or alternative sweetener blends that retain topping functionality. The USDA administers sugar import quotas and domestic price supports that directly shape raw material costs for U.S. manufacturers. Stakeholders must monitor evolving clean-label expectations alongside supply chain volatility in beet and cane sugar sourcing to preserve margin structures without sacrificing product performance.
Market Dynamics
The FDA's added-sugar disclosure mandate is compressing formulation flexibility across U.S. manufacturers, forcing simultaneous investment in alternative sweetener R&D and clean-label repositioning to retain retail shelf space and foodservice contracts.
Growth Catalysts
- Café chain expansion:National coffeehouse operators are standardizing specialty topping bars, creating pull-through demand for flavored syrups and crystalline finishing sugars across thousands of locations.
- Clean-label reformulation:The FDA's updated Nutrition Facts requirements for added sugars disclosure are accelerating manufacturer migration toward reduced-sugar blends that maintain functional performance in baking and beverage applications.
- Artisan bakery proliferation:Independent bakeries in urban clusters are sourcing specialty grain-size sugars for decorative finishing, expanding the addressable market beyond commodity granulated products.
Market Restraints
- Beet sugar supply concentration:U.S. domestic sugar production concentrates in Upper Midwest beet-growing regions, exposing processors to weather-driven yield volatility and USDA price support mechanics.
- Cane import quota rigidity:The USDA-administered tariff-rate quota system limits cost-effective access to Brazilian and Central American raw cane sugar, constraining margin flexibility for industrial liquid sugar producers.
- Alternative sweetener substitution:Stevia, monk fruit, and allulose blends are capturing share in reduced-sugar beverage and bakery segments, threatening volume growth in traditional sucrose toppings.
Strategic Opportunities
- Single-serve portion innovation:Modular sachet formats for foodservice channels reduce operator waste and enable premium pricing per unit volume across quick-service and fast-casual chains.
- Specialty chocolate-sugar hybrid positioning:Confectionery-grade blends that combine cocoa solids with crystalline toppings are opening margin pools in premium dessert and frozen beverage applications.
- Flavored syrup-topping convergence:Barista-focused products that merge liquid sweetness with visual finishing capability reduce inventory SKUs for café operators while capturing higher per-ounce value.
Industry Challenges
- Reformulation timeline compression:Manufacturers face 12-18 month product development cycles to validate alternative sweetener blends that match sucrose functionality in moisture retention and Maillard browning.
- Clean-label certification complexity:Multiple third-party non-GMO and organic standards create auditing burden and supply chain verification costs without unified industry acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Toppings Market |
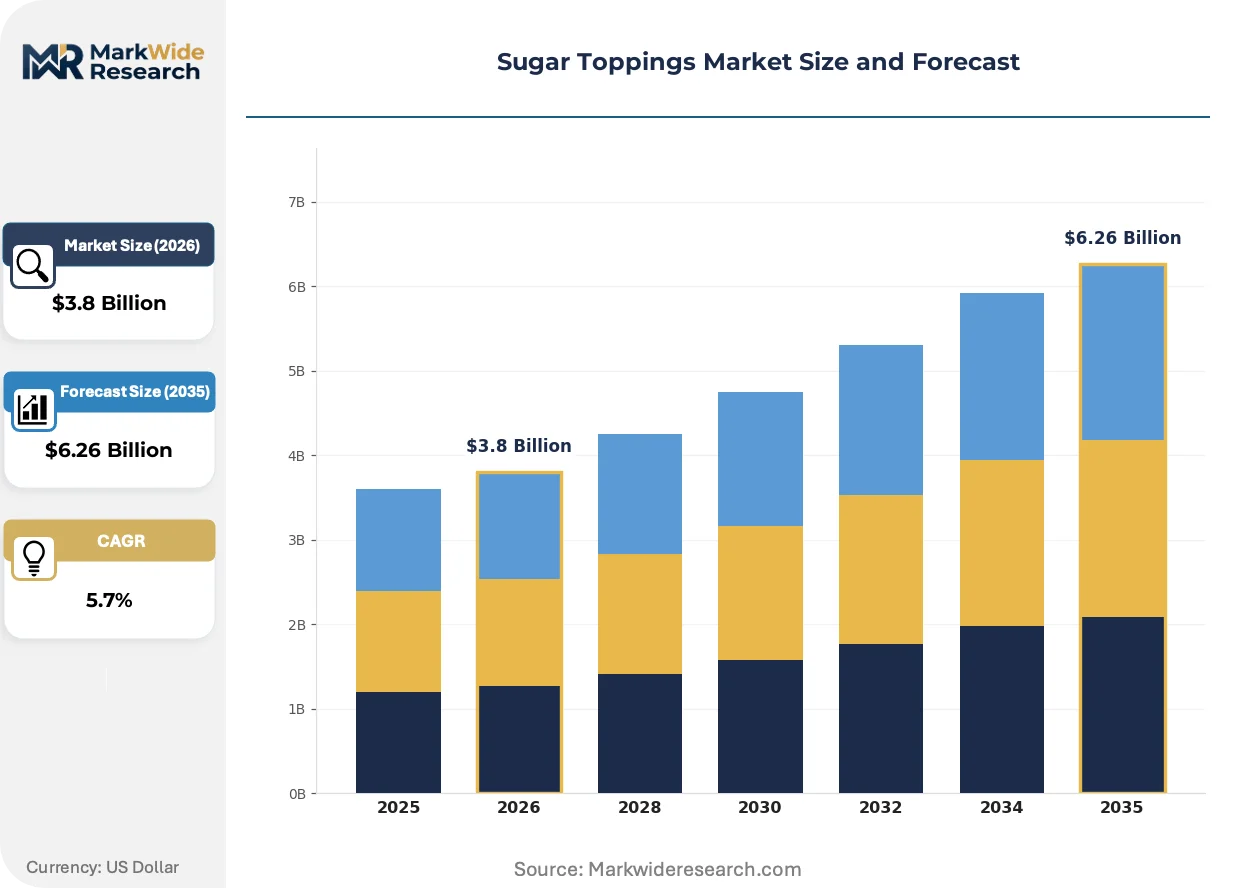
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated Sugar, Brown Sugar, Powdered Sugar, Liquid Sugar Application: Baking, Confectionery, Beverage, Ice Cream End User: Households, Restaurants, Cafés, Food Manufacturers Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Stores |
| Companies Covered | Baldwin Richardson Foods Co., The Hershey Company, Monin Inc., The Kraft Heinz Company, The J.M. Smucker Company, Cargill Inc., Dr. Oetker GmbH, General Mills, Inc., Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Toppings Market Emerging Trajectories
Precision particle engineering and hybrid liquid-crystalline formats are redefining functional performance benchmarks across baking and beverage applications, while regulatory pressure on added-sugar disclosure accelerates investment in sensory-masking technologies.
Advanced milling systems for controlled particle size distribution are consolidating quality differentiation among artisan and industrial bakers alike. European and Japanese equipment suppliers are deploying cryogenic grinding technology to preserve volatile flavor compounds in specialty brown sugar variants. This capability compression is enabling smaller regional processors to match national brands on texture performance without equivalent capital scale.
The FDA's enforcement of added-sugar line-item disclosure on Nutrition Facts panels is compressing permissible formulation space for conventional sucrose toppings. Industrial food manufacturers are responding with dual-track product portfolios—maintaining full-sugar lines for export markets while accelerating reduced-sugar domestic variants. Bakery and confectionery segments face the steepest compliance timelines given their reliance on sugar for structural properties.
Café operators are unbundling topping procurement from consolidated beverage suppliers, establishing direct relationships with specialty sugar and syrup producers. This channel disintermediation is fragmenting volume concentration previously captured by integrated sweetener distributors. The United States exhibits the most pronounced shift, where independent coffeehouse chains and regional bakery-café concepts prioritize customizable topping bars as competitive differentiation against national brands.
Sugar Toppings Market Segmentation
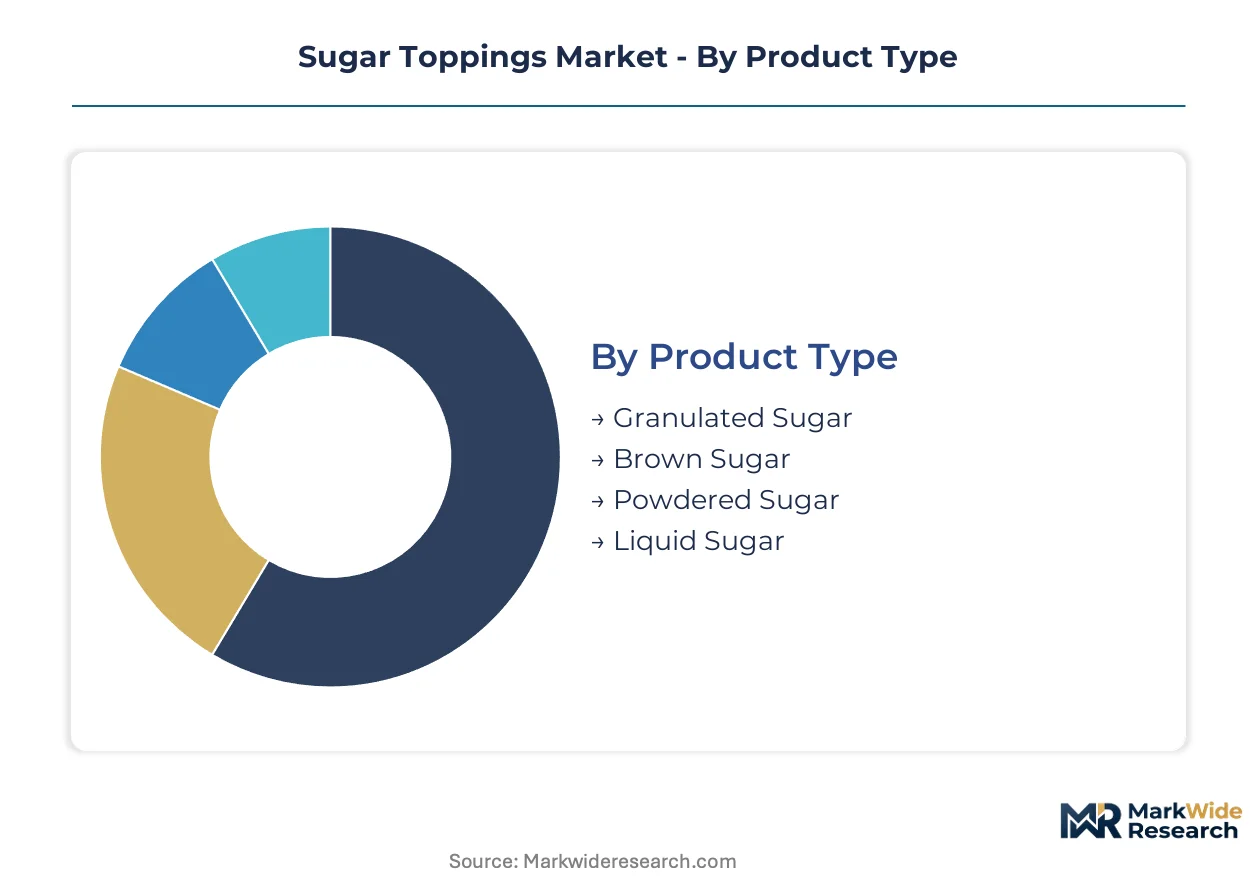
Sugar toppings fragment across functional form, end-use intensity, and procurement channel, with particle engineering and dissolution speed determining price realization. Buyers trade off convenience against customization, while foodservice operators prioritize dosing precision and inventory efficiency.
Product Type:
Purchase volume correlates directly with application flexibility and storage stability across temperature-variable supply chains.
- Granulated Sugar:Standard crystalline sucrose with medium particle size serves universal sweetening needs from home baking to industrial beverage production. Households in the United States anchor baseline demand through supermarket replenishment cycles, though café operators are downsizing granulated formats in favor of pre-dosed alternatives.
- Powdered Sugar:Finely milled sucrose with anti-caking additives delivers rapid dissolution critical for icing, dusting, and decorative finishing. Artisan bakeries in urban United States clusters are expanding specialty grain-size procurement for visual differentiation, bypassing commodity suppliers for regional millers.
- Brown Sugar:Crystalline sucrose retaining molasses content for moisture retention and caramel flavor profiles. BBQ sauce manufacturers and cookie producers value hygroscopic properties.
- Liquid Sugar:Dissolved sucrose concentrates enabling precise dosing and reduced handling in high-volume manufacturing. Industrial food manufacturers in the Midwest United States contract for tanker deliveries to optimize batch consistency.
Volume sits with granulated formats; growth tilts toward liquid concentrates in food manufacturing.
Application:
Functional requirements around thermal stability and Maillard reaction rates segment demand by processing intensity.
- Baking:Structural sugar applications requiring precise moisture management and browning control. Commercial bakeries in the United States specify particle size distribution to standardize spread and rise across production runs.
- Beverage:Rapid-dissolution formats for cold and hot drink applications. Coffeehouse chains are consolidating syrup and crystalline procurement into hybrid topping bars.
- Confectionery:Specialty grain sizes for decorative finishing and texture modulation. Premium chocolate enrobing demands ultra-fine powdered grades.
- Ice Cream:Variegated and inclusion applications requiring freeze-thaw stability. Mix-in manufacturers specify low-moisture granulated to prevent ice crystal formation.
Baking commands absolute tonnage; beverage applications are expanding most quickly through chain café standardization.
End User:
Scale economies and formulation expertise separate commodity purchasers from specialty buyers.
- Food Manufacturers:Industrial-scale buyers contracting for liquid concentrates and bulk granulated with specification control. Cereal and sauce producers in the United States negotiate multi-year supply agreements to lock input costs.
- Cafés:Experience-focused operators curating customizable topping bars for competitive differentiation. Independent coffeehouses are disintermediating consolidated beverage suppliers for direct specialty sugar relationships.
- Restaurants:Mid-scale foodservice balancing portion control against menu customization. Fast-casual chains are piloting single-serve sachet programs.
- Households:Price-sensitive retail purchasers through supermarket and convenience channels. Pantry stocking cycles concentrate demand around holiday baking seasons.
Food manufacturers dominate procurement volume; cafés are driving specification upgrades fastest.
Distribution Channel:
Channel selection reflects buyer urgency, order fragmentation, and private-label penetration.
- Supermarkets:Primary retail channel for household granulated and brown sugar replenishment. National chains in the United States are expanding private-label powdered sugar to capture margin from branded alternatives.
- Online Retail:Direct-to-consumer and bulk procurement for specialty and artisan formats. Regional millers are bypassing traditional distribution to reach boutique bakeries.
- Convenience Stores:Emergency and travel-sized purchases with premium per-ounce pricing. Urban locations stock single-serve packets for immediate consumption.
- Specialty Stores:Curated selection for professional and enthusiast bakers. Restaurant supply depots carry European-imported specialty grain sizes.
Supermarkets retain volume leadership; online retail is gaining share fastest among artisan and commercial buyers seeking direct miller relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Dubai and Jebel Ali anchor Middle Eastern sugar topping distribution, while Midwest beet-processing corridors in the United States concentrate North American supply. Regulatory divergence across FDA, EFSA, and FSSAI jurisdictions is fragmenting formulation standards.
United States
Specialty coffeehouse chains in Seattle and Portland drive flavored syrup-topping procurement, while artisan bakeries in Brooklyn and Austin source decorative grain-size sugars. The FDA enforces added-sugar line-item disclosure on Nutrition Facts panels, compressing permissible formulation space for conventional sucrose products. Beet sugar processing clusters in Minnesota and North Dakota supply industrial liquid sugar to cereal manufacturers in Battle Creek and Chicago.
Germany
Precision milling equipment manufacturers in Baden-Württemberg supply cryogenic grinding systems to regional sugar processors. The EFSA maintains strict additive approval frameworks for anti-caking agents in powdered sugar formulations. Cologne and Düsseldorf host confectionery innovation centers where specialty chocolate-sugar hybrids undergo sensory validation for export markets.
India
Quick-service restaurant expansion in Mumbai and Delhi NCR creates foodservice demand for single-serve sachet formats. The FSSAI mandates nutritional labeling for pre-packaged sugar products, accelerating domestic manufacturer compliance investments. Uttar Pradesh and Maharashtra cane-processing cooperatives supply bulk granulated sugar to bakery clusters in Bangalore and Hyderabad.
Brazil
Ethanol-flexible sugar mills in São Paulo state pivot between fuel and food-grade sucrose production based on commodity arbitrage. ANVISA regulates food-contact substances in sugar packaging materials, affecting export-ready product specifications. Port terminals in Santos channel raw cane sugar to United States refineries under USDA tariff-rate quota allocations.
Japan
Convenience store chains in Tokyo and Osaka stock premium finishing sugars for home baking enthusiasts. The Consumer Affairs Agency enforces strict origin labeling for imported sugar products, favoring domestic beet sugar from Hokkaido. Nagoya-based equipment suppliers deploy particle-size control systems for matcha-dusting and wagashi confectionery applications.
Sugar Toppings Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated market structure. Integrated agribusiness operators leverage captive sweetener supply chains to capture foodservice volume contracts. Three archetypes dominate: commodity bulk processors, specialty ingredient blenders, and café-focused syrup hybrid innovators. Capacity expansion and clean-label portfolio diversification represent the dominant competitive moves as manufacturers respond to regulatory disclosure mandates.
Within the integrated agribusiness tier, Cargill Inc. and Archer Daniels Midland Company exemplify scale-driven supply chain control, while The Hershey Company and Monin Inc. occupy positions in specialty confectionery and beverage-flavoring segments respectively. Dr. Oetker GmbH represents European precision-formulation expertise in baking applications. These named entities anchor competitive dynamics without exhausting the full vendor landscape.
| Leading Market Players |
|---|
| Baldwin Richardson Foods Co. |
| The Hershey Company |
| Monin Inc. |
| The Kraft Heinz Company |
| The J.M. Smucker Company |
| Cargill Inc. |
| Dr. Oetker GmbH |
| General Mills, Inc. |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
Cryogenic grinding technology deployment across European and Japanese equipment suppliers is compressing capital barriers for regional millers while simultaneously eroding price premiums previously commanded by national brands on particle-size precision. This capability democratization redistributes margin capture toward mid-scale processors with direct foodservice relationships.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with artisan bakeries and independent cafés paying elevated per-unit rates for specialty grain-size sugars delivered within compressed windows versus industrial buyers absorbing lower spot prices on bulk liquid concentrates scheduled months ahead. Three-tier pricing structure across premium, standard, and economy levels separates certified organic specialty blends from conventional powdered grades and commodity granulated formats. Price differentiation hinges on certification tier and volume scale, with USDA organic and non-GMO Project Verified commands sustaining 15-40% uplifts. Pricing pressure stems from alternative sweetener substitution in reduced-sugar beverage formulations. Household retail purchasers exhibit highest price sensitivity, while food manufacturers with multi-year supply agreements demonstrate lowest elasticity.
Supply Chain Analysis
Freight cost volatility on bulk liquid sugar tanker deliveries between Midwest beet-processing clusters and industrial manufacturing centers in Battle Creek and Chicago compresses margin pools for regional distributors without captive logistics assets. Geographic supply concentrates in the United States, Brazil, and India, with beet sugar from Minnesota and North Dakota anchoring North American industrial demand while São Paulo state mills and Uttar Pradesh cane cooperatives feed export raw material streams. Raw material dependencies rest on sugar beet harvest yields, cane crushing capacity, and molasses availability for brown sugar variants. Tariff-rate quota rigidity on Brazilian and Central American cane imports constitutes primary structural risk. Distribution runs through integrated agribusiness operators for foodservice volume, with direct miller relationships fragmenting among artisan bakery and café channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where FDA disclosure mandates and reformulation timeline compression force undercapitalized regional processors toward exit or acquisition.
For Market Incumbents: Extend clean-label certification coverage across reduced-sugar and alternative sweetener blends to defend shelf space against stevia and allulose substitution threats. Deepen upstream control over beet sugar processing capacity in Upper Midwest corridors to secure input cost predictability amid USDA price support volatility. Accelerate single-serve sachet format innovation for fast-casual chain contracts. For New Entrants and Emerging Players: Capture specialty grain-size demand from Brooklyn and Austin artisan bakeries bypassing commodity suppliers for direct regional miller relationships. Target independent coffeehouse chains in Seattle and Portland standardizing customizable topping bars as competitive differentiation against national brands. Lead with flavored syrup-topping hybrid positioning that reduces barista inventory complexity. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale specialty ingredient blenders possessing FDA-compliant reduced-sugar portfolios and direct café channel relationships given clean-label mandate acceleration. Long-term viability favors processors with backward integration into beet sugar sourcing and cryogenic grinding capability. Monitor USDA tariff-rate quota allocation announcements as inflection indicator for raw material cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Portfolio Diversification | Reduced-sugar and alternative sweetener blends retain retail shelf space under FDA disclosure mandates. |
| Backward Integration into Beet Processing | Captive supply from Minnesota and North Dakota clusters insulates margin from USDA price support mechanics. |
| Single-Serve Sachet Format Expansion | Modular portion packs command premium pricing per unit volume across quick-service and fast-casual chains. |
| Direct Café Channel Relationships | Disintermediation from consolidated beverage distributors captures specification upgrade demand in urban clusters. |
| Cryogenic Grinding Capability Investment | European and Japanese equipment deployment matches national brand texture performance without equivalent capital scale. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving bakery procurement managers, café chain beverage directors, sugar mill operations heads, and food manufacturer R&D formulation leads. USDA tariff-rate quota allocations, FDA guidance documents on added-sugar disclosure, and beet sugar production statistics from Upper Midwest agricultural departments supplemented volume triangulation. Bottom-up segment sizing across product type, application, and end-user channels reconciled with top-down market value estimates.
Data-stream reconciliation across shipment volumes, import quota utilization rates, and foodservice channel procurement surveys informed the analytical framework over the projection horizon. Segmentation dimensions modeled encompassed functional form, end-use intensity, and procurement channel alongside particle engineering tier and dissolution speed specifications. CAGRs derived from trend extrapolation validated against input cost trajectories and regulatory compliance timeline assumptions. Forecast inputs incorporated café chain expansion rates and artisan bakery formation patterns in urban United States clusters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to alternative sweetener substitution velocity, beet crop yield volatility, and tariff-rate quota policy shifts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Low Fat Mayo Market
Condiments & Sauces
Sauces and Condiments Market
Condiments & Sauces
Acciughe Pasta Sauce Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Culinary Sauces Market
Condiments & Sauces
Vegan Sauces, Dressings and Spreads Market
Condiments & Sauces
Soy-Based Sauce Market
Condiments & Sauces
Global Fish Sauce Market
Condiments & Sauces
Vegan Pasta Sauce Market
Condiments & Sauces
Horseradish Sauce Market
Condiments & Sauces
Sauce Market
Condiments & Sauces
Vegan Sauces Market
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Low Salt Soy Sauce Market
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
Chocolate Syrup Market