
 Mediterranean Barley Beta-Glucan Ingredients Market | 2026-2036
Mediterranean Barley Beta-Glucan Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Mediterranean Barley Beta-Glucan Ingredients Market Insights
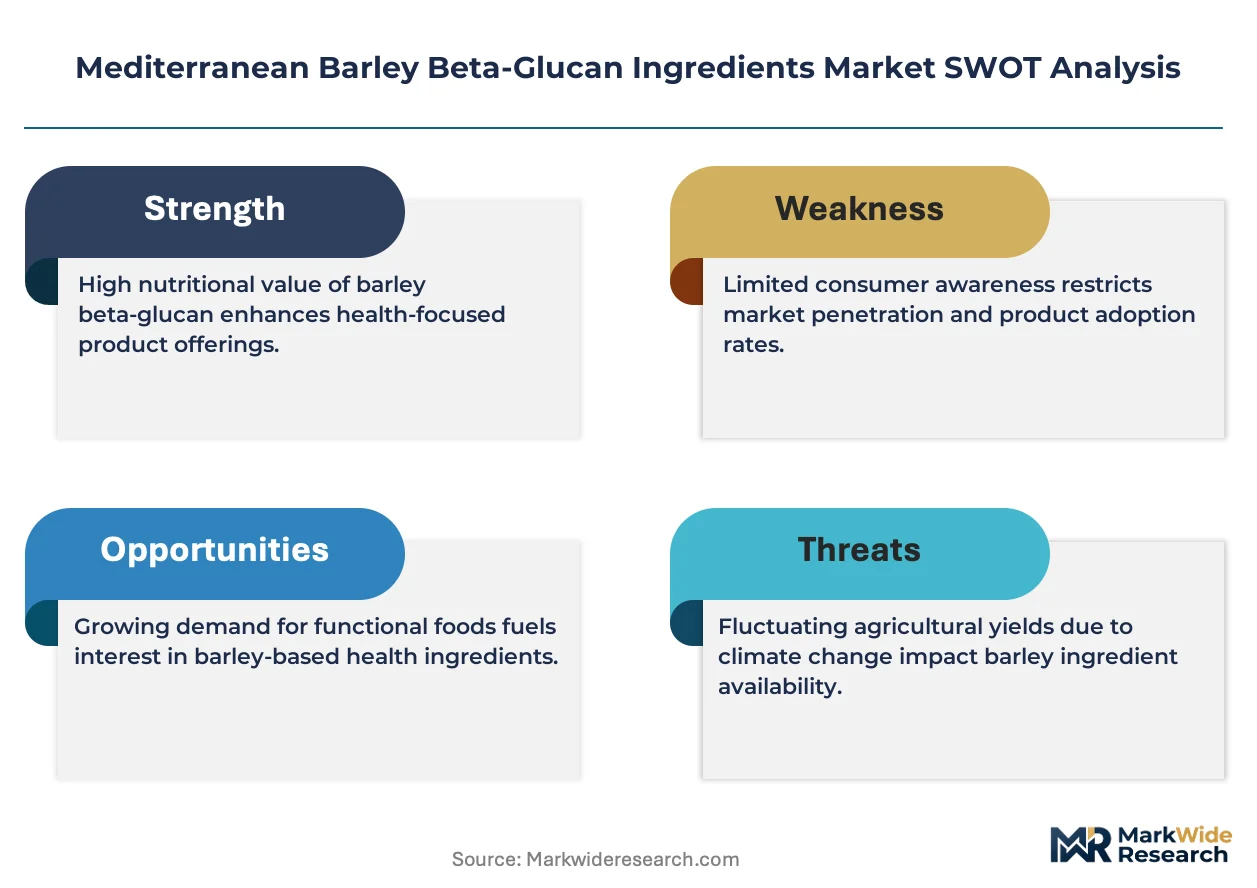
Asset-light toll-milling and third-party extraction leasing is fragmenting competitive entry barriers across the Mediterranean barley beta-glucan supply base. BENEO leverages its integrated chicory-root expertise to anchor beta-glucan distribution through established European food-ingredient channels. Cerabeta specializes in Scandinavian-origin barley sourcing but competes aggressively for Southern European nutraceutical contracts. ALSIANO extends its Spanish ingredient-portfolio breadth to occupy a brokerage position between Mediterranean millers and Italian functional-food formulators.
Mediterranean barley beta-glucan comprises soluble fiber extracted from Hordeum vulgare endosperm cell walls, typically standardized to 20-40% beta-glucan content by weight through aqueous extraction and spray-drying for viscosity-stable food integration. Its primary commercial purpose centers on cholesterol-management and glycemic-response claims in EFSA-regulated health-positioning. Powder formulations dominate current volume owing to blending flexibility in bakery and pasta applications, while Extract grades command premium positioning in clinical-nutrition and pharmaceutical-adjacent dietary supplements where higher purity thresholds apply. Functional Foods represents the most mature application segment with established retail penetration, whereas Contract Manufacturers as an end-user channel is growing fastest as private-label nutraceutical brands outsource beta-glu can premix production.
EFSA health-claim authorization frameworks, EU Novel Food regulations for non-traditional extraction processes, and national food-safety authority enforcement across Spain, Italy, and Greece collectively determine which beta-glucan products achieve commercializable health-positioning and cross-border market access. REACH chemical-safety documentation requirements for novel extraction solvents further constrain process innovation timelines and capital deployment decisions. Stakeholders must monitor pending EFSA opinion revisions on barley beta-glucan dosage thresholds, as these will determine whether existing product formulations retain compliant label claims or require reformulation investment.
Market Dynamics
EFSA health-claim dosage thresholds for barley beta-glucan cholesterol reduction are compressing formulation margins across Southern European contract manufacturers, forcing simultaneous reformulation investment and label-claim defense.
Growth Catalysts
- EFSA Article 13.1 Health Claims:Authorized barley beta-glucan cholesterol-reduction claims at 3g daily intake create legally defensible product positioning for Italian and Spanish functional food brands.
- Clinical Nutrition Segment:Hospital and medical-food formulators in Greece and Portugal are expanding beta-glucan inclusion for glycemic management protocols.
- Bologna-Parma Manufacturing Corridor:Concentrated Italian contract manufacturing capacity enables pan-European nutraceutical brands to source beta-glucan premixes with reduced logistics complexity.
Market Restraints
- Scandinavian Sourcing Concentration:Premium beta-glucan supply concentrates with Nordic millers, exposing Southern European formulators to currency and freight volatility.
- REACH Solvent Documentation:Novel aqueous extraction processes require extended ECHA safety dossier preparation, delaying process innovation timelines by 18-24 months.
- Oat Beta-Glucan Substitution:EFSA-equivalent health claims for Avena sativa extracts enable cost-driven switching in price-sensitive bakery applications.
Strategic Opportunities
- Spanish Toll-Milling Expansion:Underutilized Andalusian barley processing capacity offers asset-light entry for Italian nutraceutical brands seeking Mediterranean-origin supply.
- EU Green Deal Bioeconomy Funding:Circular extraction process investments qualify for NextGenerationEU agricultural innovation grants in Italy and Spain.
- Pharmaceutical-Adjacent Supplements:Higher-purity extract grades targeting clinical nutrition command 40-60% price premiums over standard food-grade powders.
Industry Challenges
- EFSA Opinion Revision Monitoring:Pending dosage threshold reviews require continuous regulatory intelligence investment to preempt formulation obsolescence.
- Extraction Technician Scarcity:Specialized aqueous processing expertise for viscosity-stable beta-glucan concentrates remains concentrated with Scandinavian equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mediterranean Barley Beta-Glucan Ingredients Market |
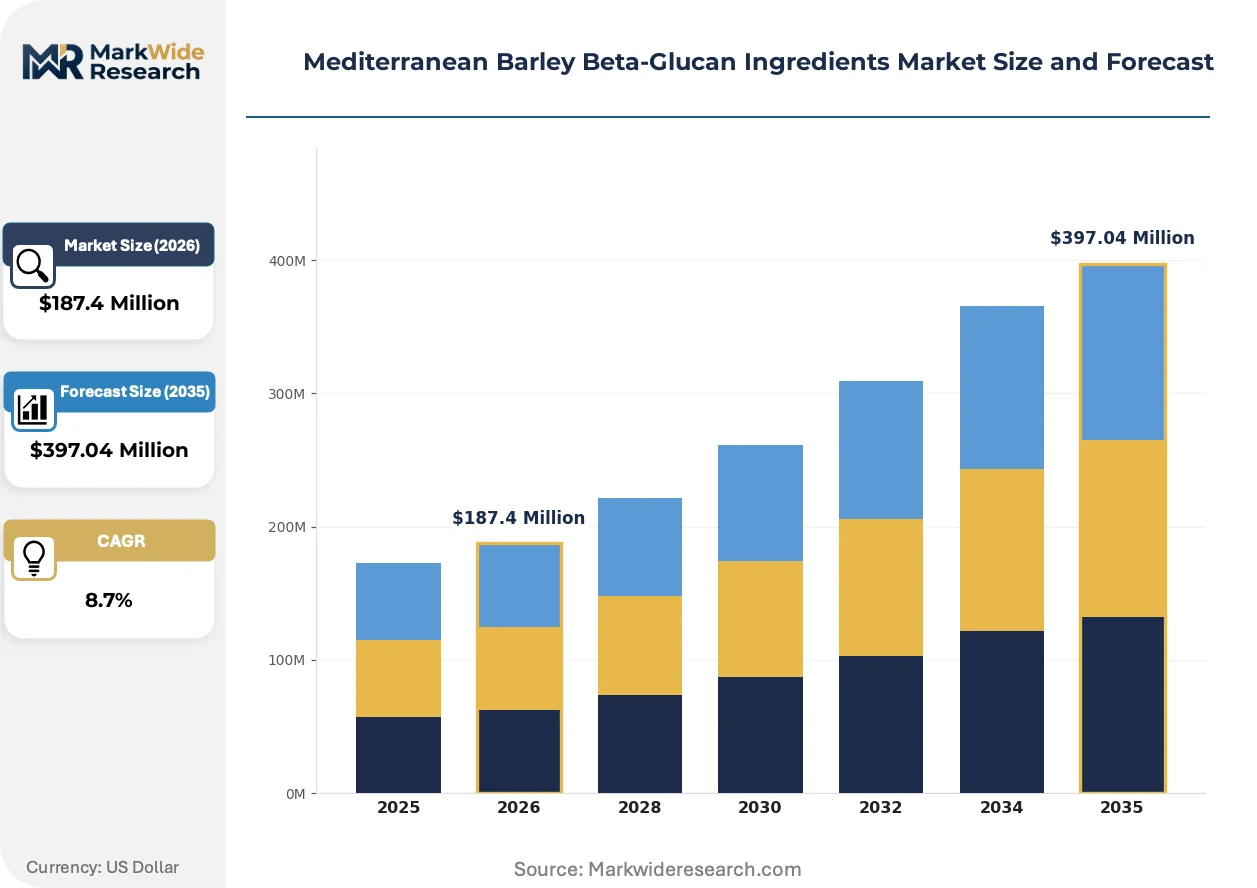
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Extract, Concentrate, Isolate Application: Functional Foods, Nutraceuticals, Dietary Supplements, Food & Beverage End User: Food Manufacturers, Supplement Producers, Beverage Companies, Contract Manufacturers Packaging Type: Bags, Bottles, Sachets, Bulk Containers |
| Companies Covered | BENEO, Ardent Mills, Sunny Boy Foods, ALSIANO, BECARRE Natural, Neogen Corporation, Cerabeta, Lantmännen Biorefineries, Ohly, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mediterranean Barley Beta-Glucan Ingredients Market Trends and Innovations
Digital process control and regulatory automation are compressing batch-to-batch variability in beta-glucan extraction, while EFSA compliance tools reshape competitive differentiation across Mediterranean ingredient suppliers.
Enzymatic precision extraction is virtualizing traditional aqueous processing by enabling targeted beta-glucan molecular weight standardization. Italian contract manufacturers in Emilia-Romagna are adopting these systems for pharmaceutical-grade output. This technology is virtualizing quality control overhead into real-time spectroscopic monitoring, reducing lab testing cycles from days to hours.
EFSA's pending opinion revisions on barley beta-glucan dosage thresholds are forcing proactive reformulation pipelines across Southern Europe. Manufacturers must maintain dual-label claim strategies pending regulatory clarity. Spanish and Italian functional food brands are most exposed, with cholesterol-reduction positioning central to their retail value propositions.
Buyer concentration among pan-European nutraceutical private-label brands is compressing supplier negotiation cycles. Mediterranean toll-millers face annual contract renegotiation with volume guarantees replacing spot purchasing. This pattern concentrates most visibly in Italy's functional food corridor, where Bologna-based contract manufacturers serve German and French brand owners.
Mediterranean Barley Beta-Glucan Ingredients Market Segmentation
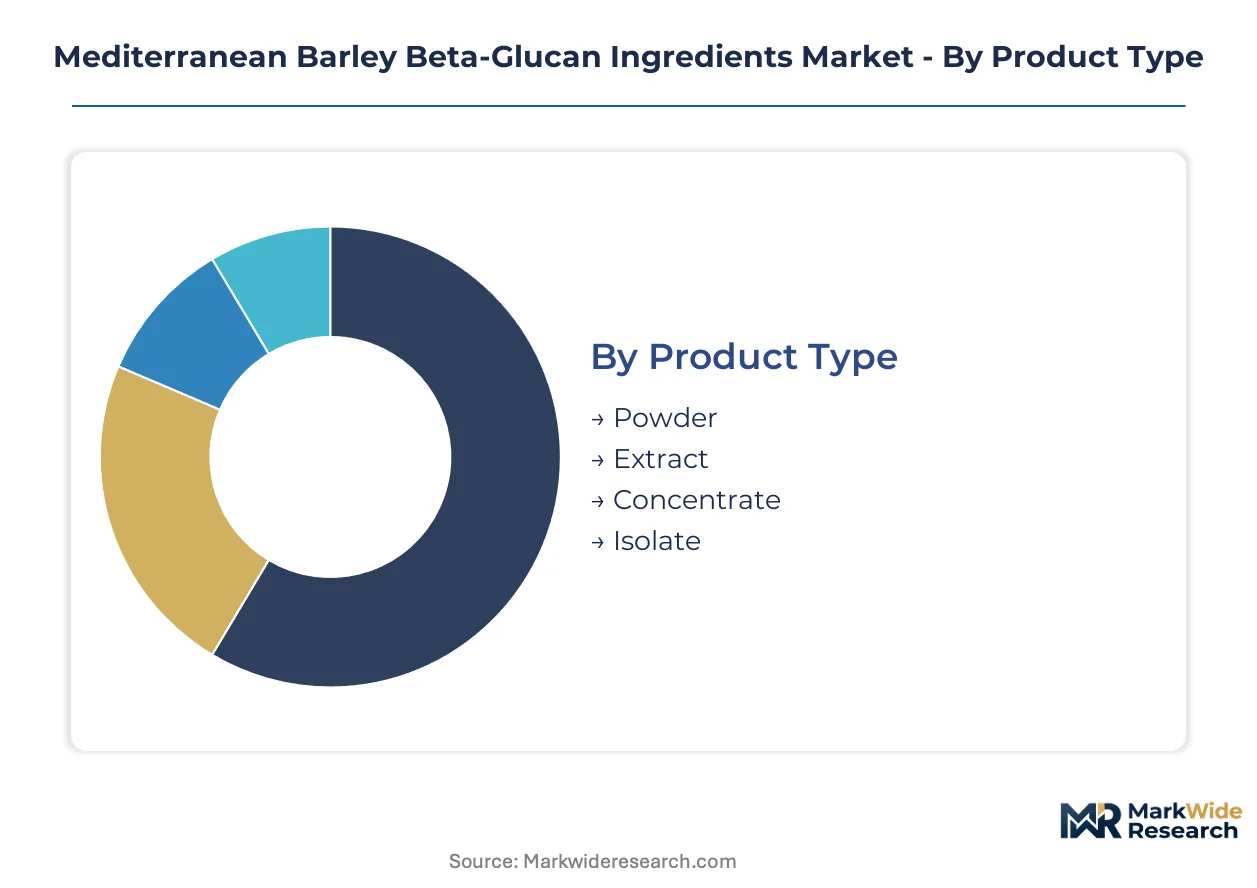
Mediterranean barley beta-glucan ingredient suppliers configure product specifications, application targeting, and channel access around EFSA health-claim compliance thresholds and the viscosity stability requirements of Southern European food processing infrastructure.
Product Type:
Mature powder formats dominate current volume, while higher-purity extracts and isolates capture emerging premium positioning in pharmaceutical-adjacent nutrition.
- Powder:Standardized to 20-40% beta-glucan content through aqueous extraction and spray-drying, powder formulations offer blending flexibility for bakery and pasta applications across Italian and Spanish manufacturing facilities.
- Extract:Higher-purity grades command substantial price premiums in clinical nutrition and pharmaceutical-adjacent dietary supplements, where molecular weight standardization meets stricter viscosity specifications for glycemic management protocols.
- Concentrate:Intermediate purity positioning serves cost-sensitive functional food brands seeking compliant cholesterol-reduction claims without isolate-grade investment.
- Isolate:Maximum purity tier targets medical-food formulators in Greece and Portugal requiring precise dosage control for hospital nutrition protocols.
Powder retains volume leadership; Isolate holds the steepest expansion curve.
Application:
Cost tier stratification separates established retail penetration from emerging clinical and wellness positioning.
- Functional Foods:The most commercially developed segment, with established retail penetration in Italian and Spanish bakery and dairy fortification where EFSA cholesterol-reduction claims drive consumer purchase decisions.
- Nutraceuticals:Premium capsule and tablet formats concentrate in the Bologna-Parma manufacturing corridor, serving pan-European private-label brands with outsourced premix production.
- Dietary Supplements:Standalone beta-glucan positioning competes with oat beta-glucan substitutes in price-sensitive Southern European markets.
- Food & Beverage:Beverage integration remains technically constrained by viscosity stability challenges in aqueous systems, limiting adoption to specialized formulation partnerships.
Functional Foods commands the revenue base; Contract Manufacturers as a channel is gaining share fastest.
End User:
Customer type fragmentation reflects divergent procurement sophistication between integrated food manufacturers and outsourced nutraceutical production.
- Food Manufacturers:Spanish and Italian bakery and dairy producers drive bulk powder procurement with annual volume guarantees replacing spot purchasing patterns.
- Supplement Producers:German and French brand owners source through Italian contract manufacturers, compressing supplier negotiation cycles and demanding real-time batch documentation.
- Beverage Companies:Limited adoption due to technical barriers in viscosity-stable aqueous integration.
- Contract Manufacturers:Fastest-growing channel as private-label nutraceutical brands outsource beta-glucan premix production to Bologna-based specialists.
Food Manufacturers anchor procurement volume; Contract Manufacturers show the most rapid demand acceleration.
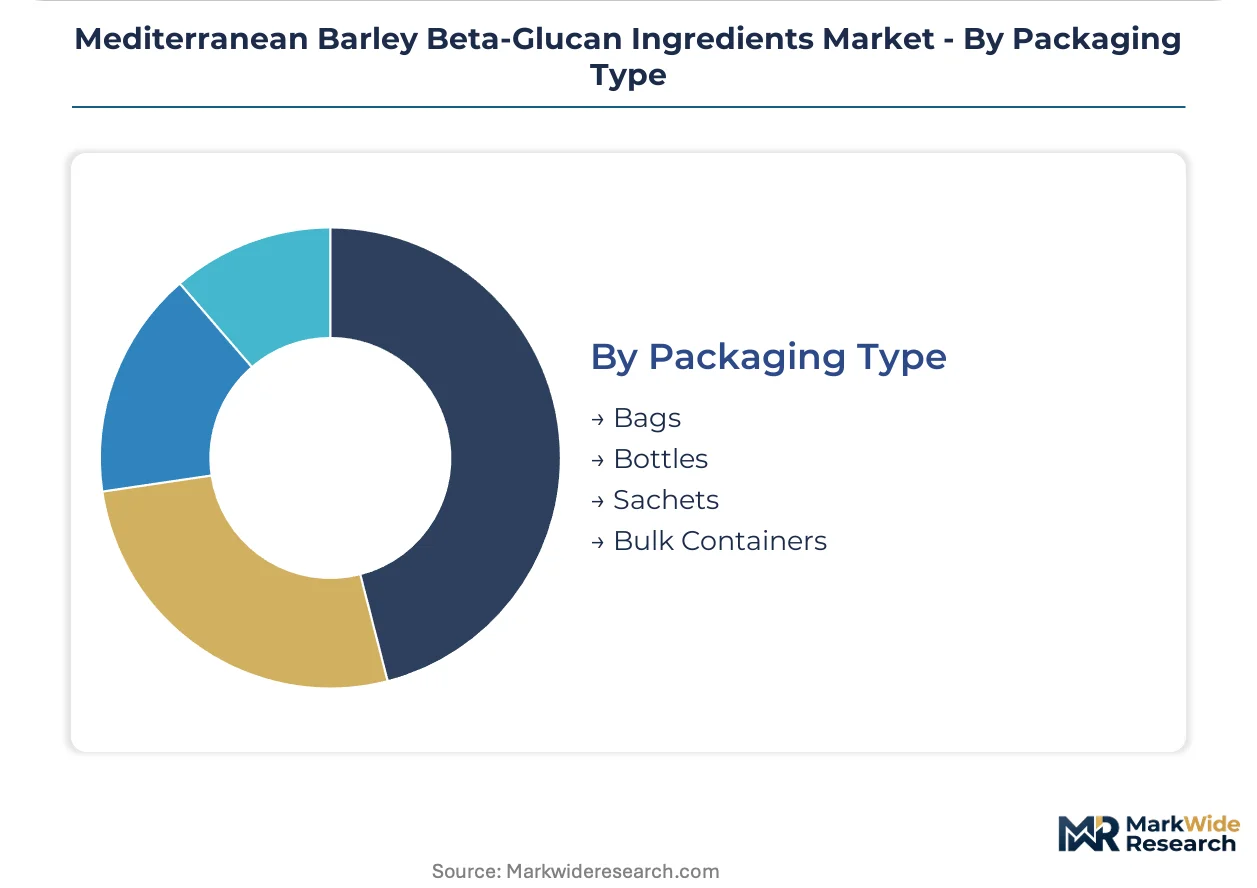
Packaging Type:
Supply concentration in Nordic sourcing shapes logistics economics across Mediterranean distribution configurations.
- Bags:Standard 25kg multi-wall paper bags serve high-volume Italian and Spanish food manufacturing with established handling infrastructure.
- Bottles:PET and HDPE containers target retail supplement channels with moisture-barrier properties for humidity-sensitive Southern European climates.
- Sachets:Single-serve formats gain traction in Portuguese and Greek clinical nutrition for precise hospital-portion control.
- Bulk Containers:Flexible intermediate bulk containers reduce freight costs for toll-milling operations in Andalusian processing facilities.
Bags maintain shipment dominance; Sachets are climbing fastest on clinical nutrition demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal Bioeconomy Funding and NextGenerationEU agricultural innovation grants are redirecting capital toward circular extraction investments in Italy and Spain. EFSA health-claim frameworks determine commercial viability across all Southern European markets.
Italy
Functional food manufacturers in the Bologna-Parma corridor drive concentrated demand for beta-glucan premixes serving German and French private-label brands. EFSA Article 13.1 cholesterol-reduction claims anchor retail positioning for bakery and dairy fortification. Emilia-Romagna contract manufacturers are adopting enzymatic precision extraction systems for pharmaceutical-grade output.
Spain
Andalusian toll-milling capacity offers asset-light entry points for Italian nutraceutical brands seeking Mediterranean-origin supply alternatives to Nordic sourcing. The country's national food-safety authority enforces EFSA-compliant labeling standards across bakery applications. Barcelona-based ingredient distributors broker connections between regional millers and Southern European formulators.
Greece
Hospital nutrition protocols are expanding beta-glucan inclusion for glycemic management in clinical settings. EU Novel Food regulations govern extraction process approvals for new market entrants. Athens-area medical-food formulators are developing higher-purity isolate grades for precise dosage control.
Portugal
Single-serve sachet formats gain traction in Portuguese clinical nutrition for hospital portion control applications. REACH chemical-safety documentation requirements constrain novel solvent introduction timelines. Lisbon-based supplement producers are sourcing through Spanish toll-millers to reduce freight exposure from Scandinavian supply concentration.
Mediterranean Barley Beta-Glucan Ingredients Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Integrated ingredient distributors leverage established food-industry relationships to anchor beta-glucan distribution, while toll-milling specialists capture outsourced production demand. Three archetypes dominate: Nordic-origin millers with extraction expertise, Mediterranean brokerage-positioned distributors, and clinical-nutrition purity specialists. Competitive moves concentrate on geographic sourcing diversification and enzymatic extraction technology licensing.
Within the brokerage-positioned tier, ALSIANO occupies a position between Mediterranean millers and Italian functional-food formulators. Among Nordic-origin specialists, Cerabeta exemplifies Scandinavian barley sourcing concentration. BENEO anchors beta-glucan distribution through established European food-ingredient channels derived from integrated chicory-root expertise. These three represent distinct competitive vectors: geographic sourcing control, channel integration depth, and extraction technology specialization.
| Leading Market Players |
|---|
| BENEO |
| Ardent Mills |
| Sunny Boy Foods |
| ALSIANO |
| BECARRE Natural |
| Neogen Corporation |
| Cerabeta |
| Lantmännen Biorefineries |
| Ohly |
| Others |
Pricing and Supply Chain Analysis
Baltic-to-Mediterranean freight corridors impose cost volatility that amplifies Nordic sourcing premiums while compressing margins for Italian contract manufacturers seeking Mediterranean-origin alternatives. This logistics tension structures price differentiation between Scandinavian-extracted isolates and Spanish toll-milled concentrates.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade isolates and standard food powders. Three-tier pricing structure across EFSA-validated premium grades, compliant standard concentrates, and economy powders without health-claim positioning anchors the market. Cost compression in standard concentrates intensifies as oat beta-glucan substitutes capture price-sensitive bakery procurement. Supplement producers show highest price sensitivity due to annual contract renegotiation pressure.
Supply Chain Analysis
REACH documentation requirements for novel extraction solvents constrain technology transfer from Nordic equipment suppliers to Mediterranean processors. Supply concentrates in Scandinavian barley milling, Spanish Andalusian toll-milling, and Italian Emilia-Romagna contract manufacturing. Raw material flows depend on Hordeum vulgare cultivar availability, aqueous extraction chemical inputs, and enzymatic processing reagents. Single-source vulnerability concentrates with Nordic-origin beta-glucan for clinical-grade isolates. Distribution runs through Barcelona-based ingredient distributors and Bologna-anchored contract manufacturing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mediterranean barley beta-glucan market is recovering from EFSA regulatory uncertainty cycles, with pending dosage threshold revisions representing the current cyclical inflection driver.
For Market Incumbents: Build regulatory intelligence moats around EFSA opinion monitoring capabilities. Incumbents should anchor supply relationships with Andalusian toll-millers to diversify beyond Nordic concentration, while investing in enzymatic precision extraction licensing to defend against oat beta-glucan substitution in bakery applications. EFSA dosage threshold revisions pose the critical threat requiring dual-label claim pipeline maintenance. For New Entrants and Emerging Players: Portuguese clinical nutrition sachet formats offer underpenetrated white-space with hospital procurement opening to Mediterranean-origin supply. New entrants should target Greek medical-food formulators developing glycemic management protocols, leveraging Spanish toll-milling partnerships to bypass Nordic freight exposure. A certification-first go-to-market angle emphasizing EFSA Article 13.1 compliance documentation accelerates buyer adoption. For Investors and Strategic Acquirers: Extraction-technology licensing specialists with enzymatic precision capabilities represent the priority acquisition archetype. The market's five-to-ten year viability hinges on EFSA health-claim durability and pharmaceutical-adjacent supplement expansion. Investors should monitor pending EFSA opinion publication timing as the signal indicating reformulation investment cycles and margin compression severity.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Precision Extraction Licensing | Enables Italian contract manufacturers to produce pharmaceutical-grade isolates meeting EFSA viscosity specifications. |
| Andalusian Toll-Milling Partnership | Reduces Nordic sourcing concentration for Spanish and Italian functional food brands facing freight volatility. |
| EFSA Dual-Label Claim Pipeline | Preserves cholesterol-reduction positioning pending regulatory clarity on dosage threshold revisions. |
| Clinical Nutrition Sachet Expansion | Captures Portuguese and Greek hospital portion-control demand with moisture-barrier packaging. |
| Circular Extraction Process Investment | Qualifies for EU Green Deal Bioeconomy Funding while reducing aqueous processing chemical inputs. |
Research Methodology
Operator-level perspectives from extraction technicians at Scandinavian equipment suppliers, procurement leads at Italian contract manufacturers, regulatory affairs specialists at Spanish ingredient distributors, and quality control directors at Bologna-based premix formulators anchored the qualitative base. Secondary validation drew from EFSA health-claim registers, ECHA REACH dossier databases, EU Novel Food approval records, and Mediterranean customs trade flows. Bottom-up volume estimates from toll-milling capacity and top-down demand segmentation from end-use applications were triangulated for convergence.
Scenario-bracketing around EFSA opinion timing and oat beta-glucan substitution rates structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product purity tier, application category, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating EFSA health-claim authorization durability and clinical nutrition protocol adoption rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by oat beta-glucan suppliers or enzymatic extraction technology licensors would shift outcomes. Material shifts in EFSA dosage threshold determinations or REACH solvent documentation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cultured Non-Fat Dairy Ingredients Market
Ingredients
Global Malt Ingredients Market
Ingredients
Specialty Malt Market
Ingredients
Bean Ingredients Market
Ingredients
Moringa Ingredients Market
Ingredients
Pea Hull Fiber Market
Ingredients
Hydrogenated Palm Oil Market
Ingredients
Kilned Malt Market
Ingredients
Desiccated Coconut Market
Ingredients
Asia-Pacific Lipids Market
Ingredients
North America Gums Market
Ingredients
Barley Malt Extract Market
Ingredients
France Soy Protein Market
Ingredients
Psyllium Products Market
Ingredients
North America Bioactive Ingredients Market
Ingredients
Salad Oil Market