
 Europe Gluten-Free Soups and Sauces Market | 2026-2036
Europe Gluten-Free Soups and Sauces Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gluten-Free Soups and Sauces Market Foresight
Asset-light co-manufacturing partnerships is rewriting competitive entry costs for mid-sized brands in European gluten-free soups and sauces. Dr. Schär AG/SPA leverages its dedicated gluten-free production infrastructure to sustain premium positioning across Continental Europe. Amy's Kitchen Inc. competes through certified organic-gluten-free overlap, while Barilla Holdings anchors shelf presence via its established pasta-to-sauce brand extension strategy.
Europe gluten-free soups and sauces comprise thermally processed, starch-thickened liquid food preparations formulated without wheat, barley, rye, or cross-contaminated oats, typically achieving sub-20 ppm gluten content through segregated supply chains and enzymatic testing protocols. These products serve diagnosed celiac patients, gluten-sensitive consumers, and mainstream households pursuing perceived digestive wellness. Soups and broths draw the deepest ingredient-source segmentation, with vegetable-based variants commanding margin premiums over commodity chicken stocks. Pouch packaging is gaining fastest in online and foodservice channels due to reduced shipping weight and extended ambient shelf stability versus glass jars.
EFSA gluten threshold standards and national celiac society certifications across Germany, Italy, and Spain create a multi-layered compliance architecture that filters out uncertified imports. The EU Green Deal's packaging waste directives are pressuring manufacturers to shift from multi-layer pouches toward recyclable tetrapaks or aluminum-free cans. Stakeholders must monitor whether upcoming ECJ rulings on cross-border e-commerce food labeling will harmonize or fragment national enforcement practices.
Market Dynamics
EU Green Deal packaging waste directives are forcing rapid format migration across European gluten-free soups and sauces, compressing multi-layer flexible packaging toward aluminum-free cans and recyclable tetrapaks while manufacturers absorb retooling costs.
Growth Catalysts
- EFSA Sub-20 ppm Threshold:The European Food Safety Authority's strict gluten contamination ceiling under Regulation (EU) No 1169/2011 creates enforceable quality floors that certified brands leverage for retail shelf access.
- United Kingdom Celiac Surge:Sharply rising diagnosis rates in British healthcare systems expand the addressable patient base beyond niche positioning into mainstream grocery channels.
- Enzymatic Testing Protocols:Advances in lateral-flow immunoassay and PCR-based oat contamination detection reduce batch rejection rates while accelerating quality-release cycles.
Market Restraints
- Segregated Supply Chain Costs:Dedicated gluten-free grain handling infrastructure at European milling facilities commands 15-25% ingredient premiums versus commodity equivalents.
- Cross-Border Labeling Fragmentation:Pending ECJ rulings on e-commerce food labeling create enforcement uncertainty that delays pan-European product launches.
- Starch-Thickener Input Volatility:Tapioca and modified corn starch prices fluctuate with Brazilian and Ukrainian harvest cycles, squeezing margin stability.
Strategic Opportunities
- Spanish Foodservice Underpenetration:Hospital and institutional catering channels in Madrid and Barcelona remain underserved by certified gluten-free liquid meal solutions.
- Pouch-to-Tetrapak Channel Innovation:Ambient-stable carton formats unlock pharmacy and healthcare retail placements previously blocked by glass jar weight constraints.
- CSRD Scope 3 Reporting:The EU Corporate Sustainability Reporting Directive incentivizes manufacturers to document supply chain emissions, creating first-mover advantage for carbon-labeled soup portfolios.
Industry Challenges
- Multi-Certification Timeline Compression:Simultaneous pursuit of German DZG, Italian AIC, and Spanish FACE celiac society approvals extends product-to-market cycles by 8-14 months.
- Legacy Canning Line Retrofit Requirements:Aluminum-free welding and interior coating technologies demand capital deployment that mid-sized co-manufacturers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gluten-Free Soups and Sauces Market |
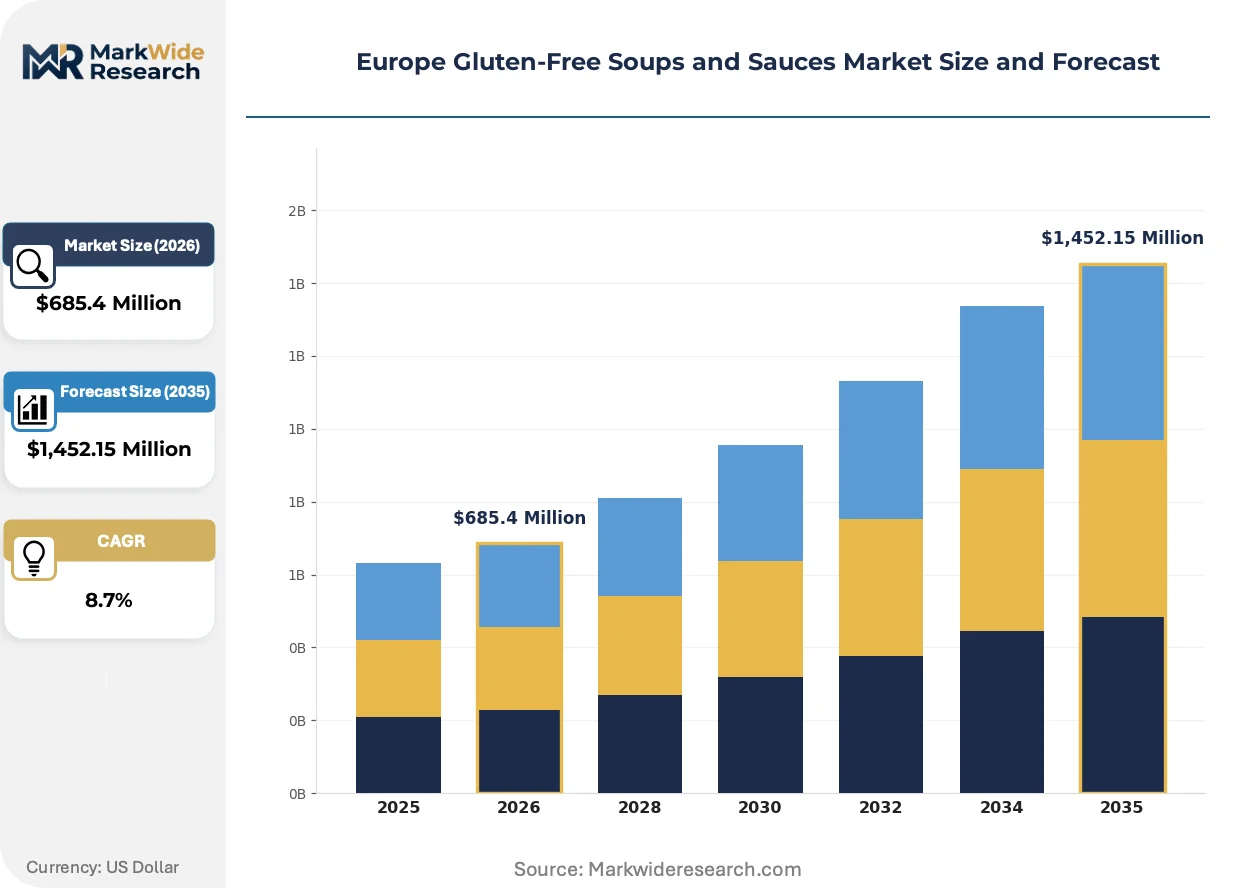
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soups, Sauces, Broths, Stocks Ingredient Source: Vegetable, Chicken, Beef, Seafood Packaging Type: Jars, Pouches, Cans, Tetrapaks Distribution Channel: Online, Supermarkets, Specialty Stores, Foodservice |
| Companies Covered | The Kraft Heinz Company, The Campbell Soup Company, Amy's Kitchen Inc., Barilla Holdings, Conagra Brands Inc., Baxter Food Group Ltd, General Mills Inc., Dr. Schär AG/SPA, Nestlé S.A, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gluten-Free Soups and Sauces Market Shifts & Advancements
Clean-label starch alternatives and ambient-stable packaging formats are actively restructuring competitive advantage in European gluten-free soups and sauces, rewarding manufacturers who integrate regulatory compliance with sensory performance.
Modified tapioca-cassava starch blends with native viscosity stability are rendering obsolete conventional corn-based thickeners in premium soup formulations. German and French retail chains now specify these alternatives for private-label development. The shift compresses supplier power toward South American and Southeast Asian ingredient processors with verified gluten-free handling.
EU Green Deal packaging waste directives are mandating aluminum reduction and mono-material recyclability across food-contact applications. Manufacturers face reformulation of retort-stable interior coatings and seam compounds. Italian and Spanish producers with existing tetrapak filling capacity capture share from glass-dependent competitors in UK and French online channels.
Direct-to-patient subscription models through celiac society partnerships are displacing traditional supermarket replenishment cycles for core broth and sauce SKUs. British and Dutch consumers diagnosed through national health pathways increasingly prefer curated quarterly deliveries over aisle-based discovery. Pharmacy channel integration in Germany accelerates this behavioral pivot toward clinically endorsed procurement.
Europe Gluten-Free Soups and Sauces Market Segmentation
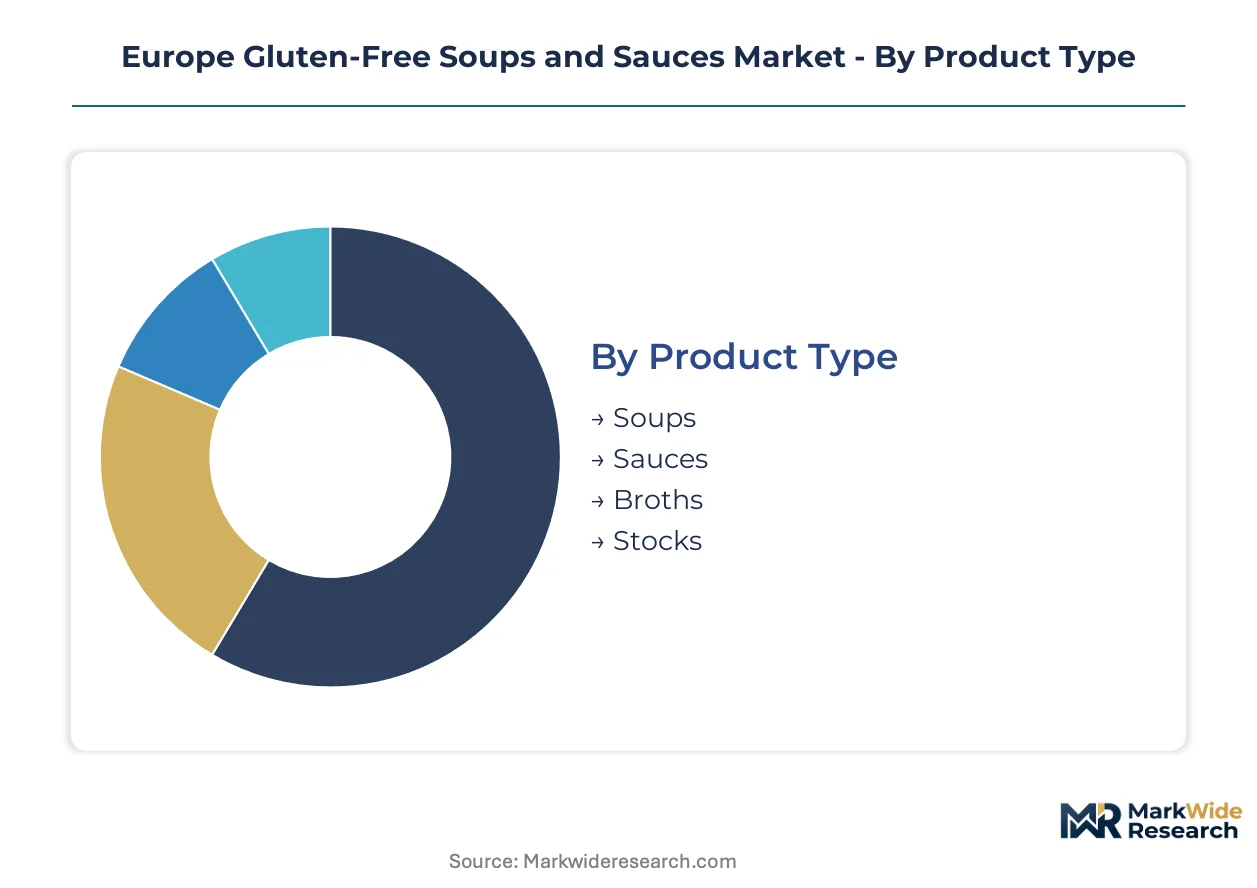
Segmentation in the Europe gluten-free soups and sauces market reveals how certified manufacturers align product architecture with divergent procurement channels. Each dimension—product format, ingredient provenance, packaging technology, and route-to-market—carries distinct compliance burdens and margin profiles that shape competitive positioning.
Product Type:
Product format determines thermal processing intensity and shelf-stability requirements across the use-case spectrum from home cooking to institutional catering.
- Soups:Thermally processed liquid preparations requiring retort or aseptic filling systems. United Kingdom retail chains specify these for dedicated free-from aisles, driven by celiac society endorsement requirements and pharmacy channel integration.
- Sauces:Viscosity-controlled emulsions and reductions with starch-thickened or reduction-thickened bases. German and French private-label programs favor these for pasta-to-sauce brand extension strategies, constrained by EFSA sub-20 ppm threshold enforcement.
- Broths:Concentrated liquid extracts with lower solids content. Home delivery subscriptions through Dutch and British celiac societies favor these for quarterly replenishment cycles.
- Stocks:Reduced-sodium foundations for culinary preparation. Foodservice procurement in Madrid and Barcelona institutional kitchens shows emerging adoption for hospital catering compliance.
Established volume favors Soups; emerging adoption favors Stocks.
Ingredient Source:
Raw material provenance dictates segregated supply chain costs and certification complexity across cost tiers from commodity proteins to premium vegetable bases.
- Vegetable:Plant-based formulations utilizing tomato, mushroom, or legume foundations with native starch content. These command margin premiums in Italian and Spanish retail, constrained by tapioca and modified corn starch price volatility tied to Brazilian harvest cycles.
- Chicken:Poultry-derived stocks and broths requiring allergen-controlled slaughter and processing facilities. United Kingdom supermarket channels concentrate demand here, filtered by simultaneous pursuit of German DZG and Italian AIC certifications.
- Beef:Bovine-extract preparations with longer reduction times. French and German foodservice distributors specify these for traditional cuisine applications.
- Seafood:Fish and shellfish-based formulations with umami-forward profiles. Nordic retail markets show specialized demand, limited by cross-contamination protocols at marine processing facilities.
Ingredient premiums concentrate in Vegetable; volume scale concentrates in Chicken.
Packaging Type:
Format selection balances EU Green Deal compliance deadlines against channel-specific logistics constraints from e-commerce shipping weight to pharmacy shelf dimensions.
- Jars:Glass containers with metal lug closures and interior epoxy coatings. These face displacement in UK and French online channels due to weight-based shipping penalties and breakage rates.
- Pouches:Multi-layer flexible films with retort stability and reduced shipping mass. German and Dutch direct-to-patient subscription models favor these, though aluminum-layer elimination mandates under packaging waste directives force coating reformulation.
- Cans:Aluminum-free welded cylinders with modified interior linings. Italian and Spanish producers with legacy canning infrastructure capture foodservice share, constrained by capital requirements for mid-sized co-manufacturer retrofit.
- Tetrapaks:Recyclable carton formats with aseptic filling capability. Pharmacy and healthcare retail placements in Germany accelerate adoption, enabled by ambient stability without glass jar constraints.
Legacy volume resides in Jars; steepest expansion trajectory belongs to Tetrapaks.
Distribution Channel:
Route-to-market selection determines labeling compliance exposure and customer relationship depth across customer types from institutional procurement to individual diagnosis pathways.
- Online:Direct-to-consumer and marketplace platforms with cross-border fulfillment complexity. Pending ECJ rulings on e-commerce food labeling create enforcement uncertainty that delays pan-European launches.
- Supermarkets:Mass retail with dedicated free-from shelf space expansion. German and French chains drive specification of clean-label starch alternatives for private-label development.
- Specialty Stores:Health-focused retailers with pharmacist consultation integration. These accelerate clinically endorsed procurement in Germany and the Netherlands.
- Foodservice:Institutional and commercial catering with batch-scale requirements. Spanish hospital and institutional channels in Madrid and Barcelona remain underpenetrated by certified solutions.
Volume concentration sits with Supermarkets; channel innovation centers on Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal packaging mandates and EFSA gluten threshold enforcement are redistributing manufacturing capacity across Continental Europe. National celiac society certifications now determine retail shelf access in ways that favor domestic producers with established testing protocols.
United Kingdom
NHS diagnosis pathways have expanded the celiac patient base beyond historical levels. British retailers now dedicate expanded free-from shelf space to thermally processed soups. London-based pharmacy chains integrate direct-to-patient subscription models that displace traditional supermarket replenishment cycles.
Germany
Dr. Schär AG/SPA leverages dedicated gluten-free production infrastructure to sustain premium positioning across Continental Europe. DZG certification requirements filter out uncertified imports from Eastern European competitors. Bavarian milling facilities command ingredient premiums for segregated grain handling infrastructure.
France
Private-label development favors clean-label starch alternatives specified by major retail chains. ANSM oversight of food-contact materials intersects with EU Green Deal aluminum reduction mandates. Parisian foodservice distributors specify viscosity-controlled emulsions for traditional cuisine applications.
Italy
AIC certification timelines extend product-to-market cycles for foreign entrants. Tetrapak filling capacity in Emilia-Romagna captures share from glass-dependent competitors in online channels. Italian producers dominate pasta-to-sauce brand extension strategies across Mediterranean export markets.
Spain
Hospital and institutional catering channels in Madrid and Barcelona remain underpenetrated by certified solutions. FACE celiac society approvals create multi-layered compliance architecture alongside EFSA baseline requirements. Valencia-based canning infrastructure faces retrofit pressure for aluminum-free welding technologies.
Europe Gluten-Free Soups and Sauces Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: dedicated gluten-free specialists with captive production infrastructure, diversified food conglomerates leveraging brand extension strategies, and organic-certified players occupying premium overlap segments. Competitive moves center on co-manufacturing partnerships that compress entry costs for mid-sized brands, and packaging format migration toward EU Green Deal-compliant tetrapaks and aluminum-free cans.
Among dedicated specialists, Dr. Schär AG/SPA exemplifies the infrastructure-heavy archetype with segregated supply chain control, while Amy's Kitchen Inc. occupies the organic-gluten-free premium intersection. Barilla Holdings represents brand extension logic, anchoring shelf presence through established pasta-to-sauce customer relationships. These three patterns illustrate how certification depth, production integration, and brand equity combine to determine competitive position.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| The Campbell Soup Company |
| Amy's Kitchen Inc. |
| Barilla Holdings |
| Conagra Brands Inc. |
| Baxter Food Group Ltd |
| General Mills Inc. |
| Dr. Schär AG/SPA |
| Nestlé S.A |
| Others |
Supply & Pricing Matrix
Brazilian tapioca and Southeast Asian cassava starch processors anchor ingredient cost structures, concentrating margin capture upstream while European manufacturers absorb 15-25% premiums for segregated gluten-free handling. This feedstock geography shapes where pricing power accumulates across the value chain.
Pricing Analysis
Certification level creates the primary spread across the European gluten-free soups and sauces landscape, with German DZG, Italian AIC, and Spanish FACE endorsements commanding tiered premiums above baseline EFSA compliance. Subscription-based direct-to-patient models through British and Dutch celiac societies extract recurring value, while mass retail private-label programs compress margins through volume-scale negotiations. Cost compression in standard-tier SKUs is intensifying because modified corn starch prices fluctuate with Ukrainian harvest cycles. Foodservice distributors in France and Germany show least price sensitivity due to institutional compliance mandates, whereas online marketplace shoppers exhibit highest elasticity.
Supply Chain Analysis
Modified tapioca-cassava starch feedstock draws from Brazilian processors and Southeast Asian suppliers with verified gluten-free handling protocols. Segregated grain milling infrastructure rests on dedicated facilities in Germany, Italy, and Spain with enzymatic testing capabilities. Single-source vulnerability concentrates around South American harvest disruptions and cross-contamination protocols at marine processing facilities for seafood-based formulations. Distribution runs through retail chain procurement offices, foodservice distributors, and direct-to-patient subscription platforms with pharmacy channel integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal packaging mandates and EFSA sub-20 ppm threshold enforcement are accelerating format migration and certification complexity, creating asymmetric advantage for producers with pre-positioned compliance infrastructure.
For Market Incumbents: Harden tetrapak filling capacity and aluminum-free canning infrastructure against pending packaging waste directive deadlines. Deepen backward integration into South American starch supply through long-term offtake agreements with verified gluten-free handlers. This counters margin erosion from Brazilian harvest volatility and emerging private-label competition.
For New Entrants and Emerging Players: Establish a beachhead in Spanish hospital and institutional catering channels, where FACE certification requirements have filtered out foreign competitors. Target Madrid and Barcelona foodservice procurement with ambient-stable broth and stock formulations. Pursue co-manufacturing partnerships with Italian or German facilities already holding multi-certification status to compress 8-14 month approval timelines.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aluminum-free canning and tetrapak filling sub-segments due to legacy line retrofit requirements. Mid-sized European producers with existing DZG-AIC-FACE certification stacks represent prime acquisition targets. Monitor ECJ rulings on cross-border e-commerce food labeling as a signal for pan-European scalability inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Stack Acceleration | Simultaneous DZG-AIC-FACE pursuit unlocks shelf access across German, Italian, and Spanish retail simultaneously. |
| Starch Supply Backward Integration | Long-term Brazilian tapioca offtake agreements hedge against harvest-cycle price volatility squeezing margin stability. |
| Format Migration to Tetrapaks | Recyclable carton adoption captures pharmacy channel placements previously blocked by glass jar weight constraints. |
| Direct-to-Patient Subscription Launch | NHS and Dutch diagnosis pathway integration displaces traditional supermarket replenishment with clinically endorsed procurement. |
| Spanish Foodservice Channel Expansion | Madrid and Barcelona institutional catering penetration addresses certified-solution underpenetration in hospital kitchens. |
Research Methodology
A standing panel of category buyers at German and French retail chains, procurement directors at Spanish foodservice distributors, regulatory affairs leads at certified manufacturers, and celiac society program managers provided ongoing calibration. Primary interview insights combined with secondary validation from EFSA guidance documents, EU Green Deal packaging waste directive texts, national celiac society certification protocols, and customs trade data for modified starch imports. Bottom-up SKU-level volume builds triangulated against top-down category spend estimates from retail audit databases.
Scenario-bracketing framed analytical approaches across the projection horizon, with base, upside, and downside cases reflecting regulatory enforcement variance and packaging format migration speed. Segmentation dimensions modeled included product format, ingredient provenance, packaging technology, and distribution channel, with additional granularity on certification tier and thermal processing intensity. CAGRs derived from logistic diffusion curves fitted to diagnosed celiac population growth and mainstream adoption patterns. Forecast inputs incorporated NHS diagnosis pathway expansion rates and EU Corporate Sustainability Reporting Directive Scope 3 documentation requirements.
Sensitivities concentrate around ECJ e-commerce labeling rulings, Brazilian tapioca harvest yields, and aluminum-free canning line retrofit financing availability. Forecasts reflect documented assumptions on certification timeline compression and pharmacy channel integration velocity. Cross-checking against national celiac society membership growth statistics and retail free-from aisle space allocation data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Pesto Sauces Market
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
Horseradish Sauce Market
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
Soy-Based Sauce Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
Table Sauce Market
Condiments & Sauces
Gluten-Free Soups and Sauces Market
Condiments & Sauces
Dips and Spreads Market
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
Asia-Pacific Condiments Market
Condiments & Sauces
Vegan Pasta Sauce Market
Condiments & Sauces
Vegan Sauces, Dressings and Spreads Market
Condiments & Sauces
Ketchup Concentrates Market
Condiments & Sauces
North America Mayonnaise Market
Condiments & Sauces
Sour Dressings Market