
 UK Prepared Mustard Market | 2026-2036
UK Prepared Mustard Market Size, Share, and Industry Trends Forecast 2026-2036
UK Prepared Mustard Market Insights
Clean-label formulation is tilting production toward reduced-additive recipes and transparent ingredient sourcing across British manufacturing facilities. Colman's of Norwich Limited anchors its competitive stance through heritage brand equity and East Anglian production heritage. Unilever Group leverages multi-channel distribution scale to sustain shelf presence across Tesco, Sainsbury's, and Asda networks. McCormick & Company differentiates through premium positioning of its specialty mustard lines in UK gourmet retail.
Prepared mustard denotes a condiment manufactured from ground mustard seeds (Sinapis alba or Brassica juncea), combined with vinegar, water, salt, and stabilizers, then milled to specific particle sizes ranging from smooth (under 0.1 mm) to coarse whole-grain textures. The product functions primarily as a flavor enhancer, emulsifier, and preservative adjunct in sandwiches, processed meats, salad dressings, and marinades across British food manufacturing and foodservice operations. Dijon mustard commands the premium tier in UK retail, where higher mustard seed concentration and wine-based acidity justify elevated price positioning against standard yellow formats. Whole grain mustard occupies a growing niche among artisan food producers and catering companies seeking textural distinction and visual appeal in plated applications. Sachet pack formats dominate foodservice procurement, where portion control and reduced waste drive institutional buyer preference.
The Food Standards Agency enforces compositional and labeling requirements that mandate minimum mustard seed content and allergen declarations for UK condiment manufacturers. BSI standards for food packaging materials, combined with Environment Agency wastewater regulations affecting mustard seed processing facilities, shape operational compliance costs and capital allocation decisions. Retail buyers and foodservice procurement teams must monitor evolving FSA guidance on front-of-pack nutritional labeling, as proposed salt reduction targets could force reformulation across standard yellow mustard lines.
Market Dynamics
Clean-label formulation mandates from the Food Standards Agency are compressing additive usage across British prepared mustard manufacturing, forcing recipe reformulation and supplier audits throughout East Anglian production facilities.
Growth Catalysts
- Premium Foodservice Expansion:London sandwich chains and charcuterie specialists are specifying whole-grain and Dijon formats for visual differentiation. This specification pull elevates average unit values in foodservice procurement.
- FSA Compositional Standards:Mandatory mustard seed content declarations and allergen labeling create compliance barriers that favor established manufacturers with dedicated quality infrastructure.
- South East Retail Density:Concentrated premium grocery networks in Surrey, Kent, and Hertfordshire generate disproportionate volume for specialty mustard lines relative to national population distribution.
Market Restraints
- Mustard Seed Price Volatility:Brassica juncea seed costs fluctuate with Canadian and Indian harvest yields, squeezing margin stability for standard yellow mustard producers.
- East Anglian Production Concentration:Norwich-area facilities handle disproportionate national volume, creating geographic vulnerability to localized supply disruptions or environmental compliance events.
- Vinegar-Based Acidity Substitution:Wine-based acidity in premium Dijon formats faces consumer price resistance during cost-of-living compression, pushing some buyers toward lower-specification alternatives.
Strategic Opportunities
- Scotland and Northern England Penetration:Edinburgh, Glasgow, and Manchester foodservice markets show underdeveloped artisan mustard adoption relative to London benchmarks.
- Sachet Format Innovation:Single-serve portion packs for airline and rail catering reduce waste and open procurement relationships with transport operators.
- Salt Reduction Tailwinds:Proposed FSA front-of-pack nutritional labeling revisions incentivize reformulated low-sodium recipes that preempt regulatory mandates.
Industry Challenges
- Clean-Label Technical Reformulation:Removing stabilizers and artificial preservatives while maintaining emulsion stability and shelf life requires extended R&D cycles and sensory testing.
- Multi-Species Seed Sourcing Complexity:Sinapis alba and Brassica juncea varietals demand distinct agronomic contracts and quality testing protocols, fragmenting procurement operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Prepared Mustard Market |
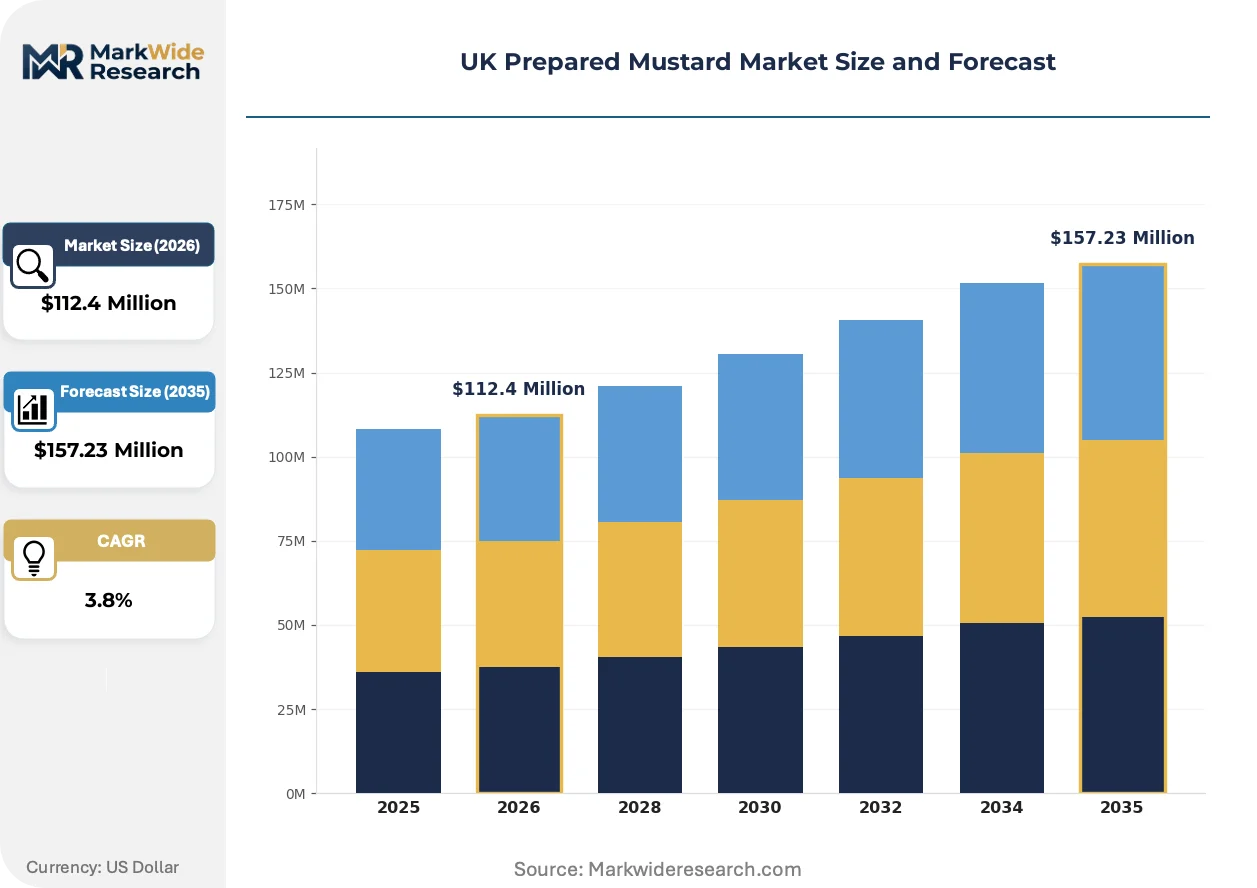
| Market Size in 2026 | $112.4 Million |
| Market Size in 2035 | $157.23 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yellow Mustard, Dijon Mustard, Honey Mustard, Spicy Brown, Whole Grain Mustard Packaging Type: Glass Jar, Plastic Bottle, Sachet Pack, Tube, Tin Can Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Foodservice Providers, Wholesale Distributors End User: Households, Food Manufacturers, Catering Companies, Restaurants, Cafes |
| Companies Covered | Unilever Group, McCormick & Company, Inc., The Kraft Heinz Company, Conagra Brands, Inc., Colman's of Norwich Limited, French's Food Company LLC, Mustard Foods Limited, Cargill Incorporated, Archer-Daniels-Midland Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Prepared Mustard Market Trends and Innovations
Digital traceability systems and automated quality monitoring are reshaping how British mustard manufacturers demonstrate compliance and manage ingredient provenance across complex seed-to-shelf supply chains.
Blockchain-enabled batch tracking is digitizing seed origin documentation and allergen cross-contamination protocols for East Anglian production facilities. Sainsbury's and Waitrose procurement teams now require this transparency layer for premium-tier supplier qualification. The technology is digitizing audit workflows that previously consumed manual quality-assurance resources.
Proposed Food Standards Agency salt reduction targets are compressing sodium content across standard yellow mustard formulations. Manufacturers face sensory reformulation challenges as salt functions as both flavor carrier and preservative adjunct. South East retail buyers are accelerating low-sodium line trials ahead of mandatory implementation timelines.
Direct-to-caterer subscription models are fragmenting traditional wholesale distribution for artisan mustard producers. London-based restaurant groups now source specialty formats through curated supplier portals rather than broadline distributors. This channel shift concentrates in independent hospitality clusters where menu differentiation commands procurement priority.
UK Prepared Mustard Market Segmentation
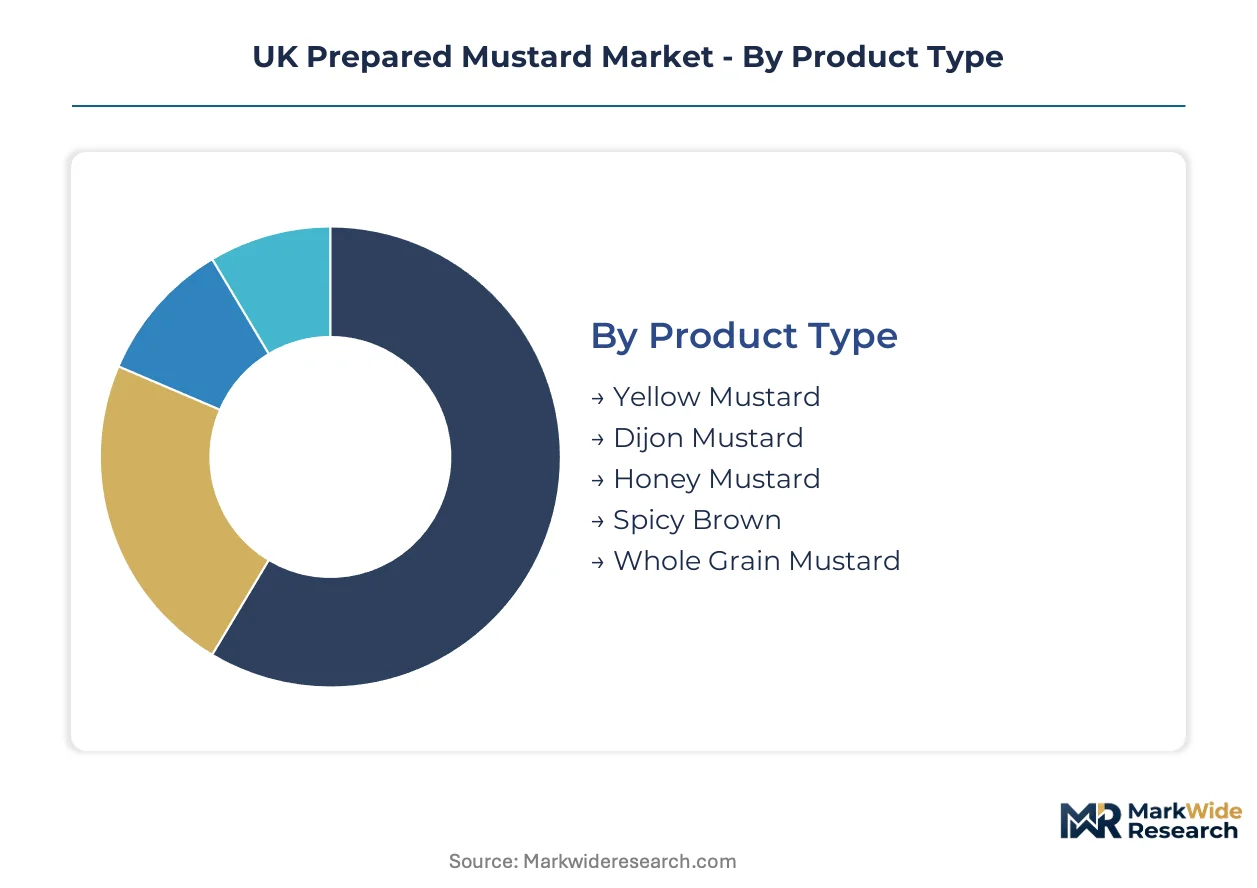
Segmentation in the UK prepared mustard market reveals how product specifications, packaging formats, and channel strategies align with distinct usage occasions and buyer requirements. Understanding these divides clarifies where manufacturers must invest in formulation, compliance infrastructure, and distribution relationships.
Product Type:
After-sales service intensity varies sharply across mustard formats, with premium lines requiring technical support for foodservice specification and standard variants demanding minimal post-purchase engagement.
- Yellow Mustard:Formulated from Sinapis alba seeds with vinegar-based acidity and turmeric-derived coloring, this format delivers consistent emulsion stability for high-volume manufacturing. Demand concentrates in food manufacturing facilities across the Midlands, where cost-sensitive procurement for processed meat applications drives specification. The format faces margin pressure from proposed FSA salt reduction mandates.
- Dijon Mustard:Higher Brassica juncea seed concentration combined with wine-based acidity creates a sharper flavor profile and premium positioning. London sandwich chains and South East delicatessens specify this format for menu differentiation, though cost-of-living compression has pushed some buyers toward lower-specification alternatives.
- Honey Mustard:Blended sweetener addition targets family household segments and salad dressing applications.
- Spicy Brown:Coarser grind and elevated heat profile serves regional taste preferences in Northern England foodservice.
- Whole Grain Mustard:Intact mustard seeds suspended in vinegar base provide visual distinction for charcuterie plating and artisan retail positioning.
By volume, Yellow Mustard leads. By growth pace, Whole Grain Mustard is gaining share fastest among premium foodservice specifications.
Packaging Type:
Cost tier stratification separates premium glass formats from economy sachet solutions, with mid-market plastic bottles capturing mainstream retail volume.
- Glass Jar:Heritage presentation format dominates premium retail shelves in Waitrose and Marks & Spencer networks, where tactile weight and label visibility support brand equity investments. East Anglian manufacturers maintain dedicated filling lines for this format despite higher logistics costs versus plastic alternatives.
- Sachet Pack:Single-serve portion control dominates airline, rail catering, and institutional foodservice procurement where waste reduction drives buyer preference. The format opens procurement relationships with transport operators seeking operational efficiency.
- Plastic Bottle:Squeeze-dispensing convenience captures mainstream supermarket volume across Tesco and Sainsbury's standard lines.
- Tube:Precision dispensing format targets gourmet cooking applications and travel retail channels.
- Tin Can:Industrial bulk format serves food manufacturing and catering supply operations with extended shelf-life requirements.
By installed production capacity, Glass Jar leads. By procurement momentum, Sachet Pack is expanding most quickly in transport catering contracts.
Distribution Channel:
Customer type concentration shapes channel investment, with foodservice providers demanding technical specification support that supermarkets rarely require.
- Supermarkets:Tesco, Sainsbury's, Asda, and Morrisons account for the dominant share of household retail volume, where shelf placement fees and promotional calendars determine competitive outcomes. These buyers are accelerating low-sodium line trials ahead of FSA mandatory implementation timelines.
- Foodservice Providers:Broadline distributors and specialty caterer portals serve London restaurant groups and national contract catering operations. Direct-to-caterer subscription models are fragmenting traditional wholesale distribution for artisan producers.
- Convenience Stores:Impulse purchase occasions and limited shelf space favor compact formats and recognized brand names.
- Online Retailers:Ocado and Amazon Fresh channels enable specialty format discovery for households outside London premium retail catchments.
- Wholesale Distributors:Cash-and-carry and delivered wholesale serve independent foodservice operators and catering companies with volume pricing structures.
By transaction volume, Supermarkets lead. By margin structure, Foodservice Providers is climbing the fastest as specification premiums persist.
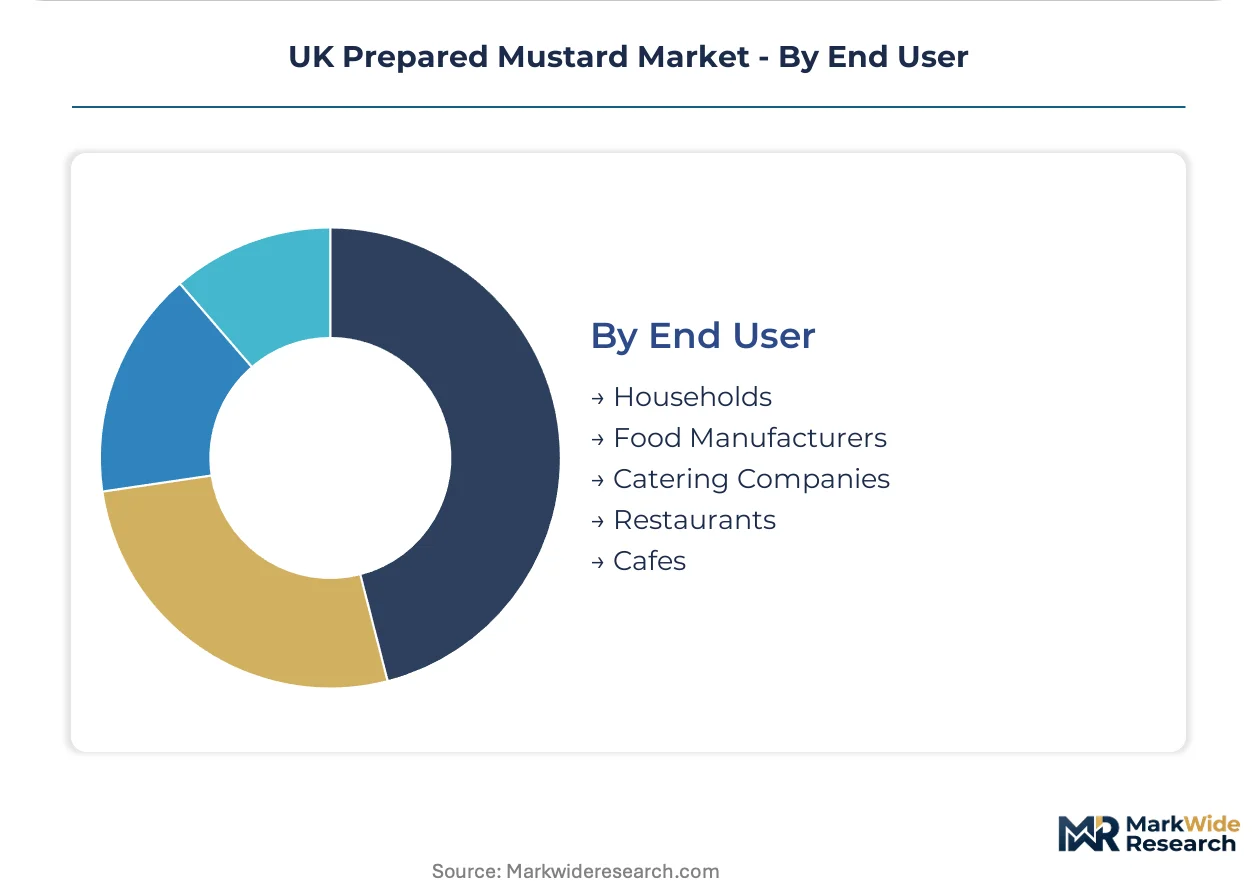
End User:
Application maturity separates established household consumption from emerging food manufacturer integration opportunities.
- Households:Domestic consumption concentrates in London and the South East, where premium grocery retailing and foodservice exposure elevate quality expectations. South East retail density in Surrey, Kent, and Hertfordshire generates disproportionate volume for specialty lines.
- Restaurants:London sandwich chains and charcuterie specialists specify whole-grain and Dijon formats for visual differentiation and menu storytelling.
- Food Manufacturers:Processed meat, dressing, and sauce producers integrate mustard as flavor carrier and preservative adjunct in industrial formulations.
- Catering Companies:Institutional and event catering operations prioritize portion-controlled formats and consistent supply security.
- Cafes:Independent coffee shop networks in Edinburgh, Glasgow, and Manchester show underdeveloped artisan mustard adoption relative to London benchmarks.
By absolute consumption, Households lead. By specification upgrading, Restaurants is showing the steepest expansion trajectory as menu differentiation commands procurement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration in London and the South East drives disproportionate demand for premium mustard formats, while regional foodservice networks and manufacturing clusters shape supply-side investment across British sub-markets.
London and the South East
Sandwich chains and charcuterie specialists in Central London specify whole-grain and Dijon formats for menu differentiation. The Food Standards Agency maintains strict compositional standards for condiment labeling that manufacturers must navigate. Surrey, Kent, and Hertfordshire retail density generates concentrated volume for specialty lines relative to national population distribution.
East Anglia
Mustard seed processing facilities in the Norwich area handle disproportionate national production volume. Environment Agency wastewater regulations shape operational compliance costs for local manufacturers. Colman's heritage production heritage anchors competitive positioning in this cluster.
Midlands
Food manufacturing facilities across Birmingham and Leicester integrate standard yellow mustard as flavor carrier for processed meat applications. BSI standards for food packaging materials influence procurement specifications. Cost-sensitive industrial buyers concentrate procurement decisions in this manufacturing belt.
Scotland
Edinburgh and Glasgow foodservice markets show underdeveloped artisan mustard adoption relative to London benchmarks. Proposed FSA front-of-pack nutritional labeling revisions create reformulation pressure across standard lines. Independent hospitality clusters in Scottish cities present penetration opportunities for specialty format suppliers.
North England
Manchester-based restaurant groups and catering operations drive emerging demand for premium condiment specifications. Regional taste preferences favor spicier brown mustard formats in institutional foodservice. Transport catering contracts through Manchester Airport and rail networks open sachet format procurement relationships.
UK Prepared Mustard Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered shelf-space and specification-driven procurement environments. The market structure consolidates around heritage brand equity and multi-channel distribution scale, with three strategic archetypes dominating: established condiment conglomerates with grocery network dominance, regional heritage specialists with provenance-based positioning, and premium gourmet specialists targeting foodservice specification. Competitive moves concentrate on clean-label reformulation and direct-to-caterer channel fragmentation.
Among established condiment conglomerates, Unilever Group and McCormick & Company exemplify scale-driven archetypes with multi-channel presence. Colman's of Norwich Limited occupies a position as the heritage specialist anchor, leveraging East Anglian production provenance. These three represent the competitive tension between grocery retail shelf dominance and foodservice specification premium capture that shapes strategic positioning across British mustard manufacturing.
| Leading Market Players |
|---|
| Unilever Group |
| McCormick & Company, Inc. |
| The Kraft Heinz Company |
| Conagra Brands, Inc. |
| Colman's of Norwich Limited |
| French's Food Company LLC |
| Mustard Foods Limited |
| Cargill Incorporated |
| Archer-Daniels-Midland Company |
| Others |
Pricing and Supply Chain Analysis
Canadian and Indian mustard seed harvest volatility anchors margin instability across British manufacturing tiers, compressing standard yellow format pricing while amplifying premium Dijon spreads and reshaping procurement toward multi-origin sourcing contracts.
Pricing Analysis
Cost-plus contracts with Brassica juncea indexation dominate raw material procurement for East Anglian processors. Three-tier pricing structure across premium, standard, and economy levels separates wine-based Dijon formulations from vinegar-driven yellow variants and basic catering sachets. Cost compression in standard lines intensifies because of proposed FSA salt reduction mandates requiring expensive reformulation. Food manufacturers in the Midlands exhibit highest price sensitivity, while London sandwich chains accept specification premiums for whole-grain formats.
Supply Chain Analysis
Contract-manufacturing concentration in Norwich-area facilities leaves limited alternative capacity for quality-assured mustard seed processing. Canadian prairies and Indian Rajasthan supply the bulk of Brassica juncea and Sinapis alba seedstock respectively, with smaller Ukrainian volumes disrupting traditional flows. Single-source vulnerability concentrates in East Anglian milling infrastructure where Environment Agency wastewater permits constrain expansion. Distribution runs through Tesco and Sainsbury's central depots for retail, with direct-to-caterer portals fragmenting foodservice wholesaling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is tilting toward consolidated London restaurant groups and supermarket procurement teams, fragmenting traditional wholesale relationships and compressing margin capture for mid-tier suppliers.
For Market Incumbents: Harden quality infrastructure around FSA compliance to defend against emerging clean-label specialists. Deepen backward integration into Canadian seed contracting to secure Brassica juncea supply against Indian harvest volatility. Expand dedicated filling capacity for glass jar formats serving Waitrose and Marks & Spencer premium positioning. For New Entrants and Emerging Players: Pursue underdeveloped Edinburgh and Glasgow foodservice markets where artisan mustard adoption lags London benchmarks. Exploit direct-to-caterer subscription portals to bypass broadline distributor gatekeeping. Target Manchester Airport and rail catering sachet contracts as a volume anchor for transport operator procurement relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors heritage-provenance specialists with East Anglian production roots. Long-term viability rests on clean-label reformulation capabilities and foodservice specification relationships rather than commodity retail volume. Monitor FSA salt reduction implementation timelines as the critical inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | FSA salt reduction mandates force additive removal while maintaining emulsion stability for Norwich manufacturers. |
| Direct-to-Caterer Portal Launch | London restaurant groups now source specialty formats outside traditional wholesale distribution networks. |
| Canadian Seed Contracting Expansion | Brassica juncea supply security buffers against Indian harvest yield fluctuations and price spikes. |
| Sachet Format Innovation | Single-serve portion packs open procurement with airline and rail catering operators seeking waste reduction. |
| Blockchain Traceability Implementation | Sainsbury's and Waitrose now require digitized seed origin documentation for premium supplier qualification. |
Research Methodology
The analysis maps yellow mustard, Dijon mustard, whole-grain formats, and honey mustard variants, each validated through procurement directors at broadline distributors, category buyers at Tesco and Sainsbury's, technical directors at East Anglian manufacturing facilities, and regulatory affairs specialists at the Food Standards Agency. Primary interview insights triangulate against FSA guidance documents, BSI packaging standards, Environment Agency wastewater discharge records, and customs import data for mustard seed arrivals from Canada and India. Bottom-up volume modeling from individual facility throughput reconciles with top-down grocery retail audit estimates.
Assumptions held FSA salt reduction timelines and Canadian harvest yield patterns as fixed baseline conditions, with mustard seed price volatility and foodservice specification upgrading treated as variable sensitivities. Segmentation modeling spans product type, packaging format, distribution channel, and end-user application across the projection horizon. CAGRs derive from fitted trend extrapolation against historical volume trajectories, incorporating industrial mustard integration rates into processed meat formulations and salad dressing manufacturing as category-specific demand drivers.
Sensitivities concentrate around FSA regulatory acceleration, Canadian prairie drought cycles, and London foodservice consolidation pace. Forecasts embed documented assumptions about clean-label transition speed and transport catering contract award timing. Quarterly review of FSA consultation publications, Agriculture and Agri-Food Canada crop reports, and Manchester Airport catering procurement notices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Sandwich Spread Market
Condiments & Sauces
Salad Dressings and Mayonnaise Market
Condiments & Sauces
Table Sauce Market
Condiments & Sauces
Asia Pacific Hot Sauce Market
Condiments & Sauces
Ketchup Market
Condiments & Sauces
Vegan Sauces Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
United States Pasta Sauce Market
Condiments & Sauces
Acciughe Pasta Sauce Market
Condiments & Sauces
Hot Sauce Market
Condiments & Sauces
Salad Dressings Market
Condiments & Sauces
Sauces, Condiments, and Dressings Market
Condiments & Sauces
Dry Cooking Sauces Market
Condiments & Sauces
Europe Pasta Sauce Market
Condiments & Sauces
Cooking Sauces Market
Condiments & Sauces
Cheese Sauce Market