
 Low Fat Mayo Market | 2026-2036
Low Fat Mayo Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Mayo Market Analytics
Clean-label emulsification technology is fragmenting traditional manufacturing approaches across the condiment industry. Unilever leverages its global R&D network to sustain reformulation pipelines that reduce fat content without sacrificing mouthfeel. Kraft Heinz Company anchors North American shelf presence through broad retail distribution and private-label adjacent positioning. Sir Kensington's differentiates via premium ingredient sourcing and avocado-oil-based low-fat variants that command specialty channel placement.
Low fat mayonnaise is an oil-in-water emulsion typically containing 35-50% less fat than standard mayonnaise, stabilized with modified food starches or gum blends to replicate traditional viscosity and coating properties. Classic Mayo occupies the dominant volume position across retail and food service channels, while Vegan Mayo captures the fastest expansion as plant-based dietary patterns reshape condiment purchasing. Squeeze Bottles lead packaging format preferences for convenience-oriented households, though Tubs retain strength in club-store and food service procurement where portion control and dispensing efficiency matter.
FDA nutrition labeling mandates and USDA school meal standards shape product formulation thresholds and permissible health claims across the United States. The EPA and state-level environmental regulations additionally influence packaging material selection, particularly for single-serve pouches and plastic squeeze formats. Stakeholders must monitor evolving clean-label certification standards and emerging state-level sodium reduction initiatives that could trigger additional recipe engineering cycles.
Market Dynamics
Clean-label emulsification technology is fragmenting traditional manufacturing approaches across the condiment industry. Modified food starches and gum blends now stabilize low-fat emulsions that previously required egg yolk lecithin, enabling reformulation pipelines that reduce saturated fat content without sacrificing mouthfeel or coating properties.
Growth Catalysts
- FDA Nutrition Labeling Mandates:Updated packaged food requirements pressure manufacturers toward lower saturated fat thresholds, accelerating reformulation investment across retail portfolios.
- USDA School Meal Standards:K-12 procurement specifications for reduced-fat dressings expand institutional volume placements and normalize light mayonnaise acceptance among younger consumers.
- Plant-Based Dietary Patterns:Vegan mayonnaise variants capture fastest expansion as egg-free emulsification technologies mature and specialty channel velocity accelerates.
Market Restraints
- Input Cost Volatility:Avocado oil and specialty vegetable oil prices fluctuate with climate-driven harvest variability, compressing margins on premium low-fat variants.
- Technical Limitation:Fat reduction beyond 50% degrades emulsion stability and shelf life, capping reformulation ambition without breakthrough hydrocolloid systems.
- Substitution Threat:Greek yogurt-based dressings and hummus spreads displace mayonnaise occasions in health-conscious household pantries.
Strategic Opportunities
- Single-Serve Pouch Formats:Food service operators and convenience retailers seek portion-controlled packaging that reduces waste and simplifies inventory management.
- Clean-Label Certification Standards:Emerging third-party non-GMO and organic certifications command shelf placement premiums and specialty channel access.
- Avocado-Oil Technology Convergence:Cold-pressed extraction methods combined with modified starch stabilization enable premium positioning with validated health claims.
Industry Challenges
- Emulsion Science Talent Gap:Food technologists with specialized hydrocolloid and stabilizer expertise command premium compensation, constraining R&D team expansion.
- Legacy Equipment Retrofit Costs:Existing mayonnaise production lines require capital-intensive modification to handle lower-viscosity low-fat formulations and alternative packaging formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Mayo Market |
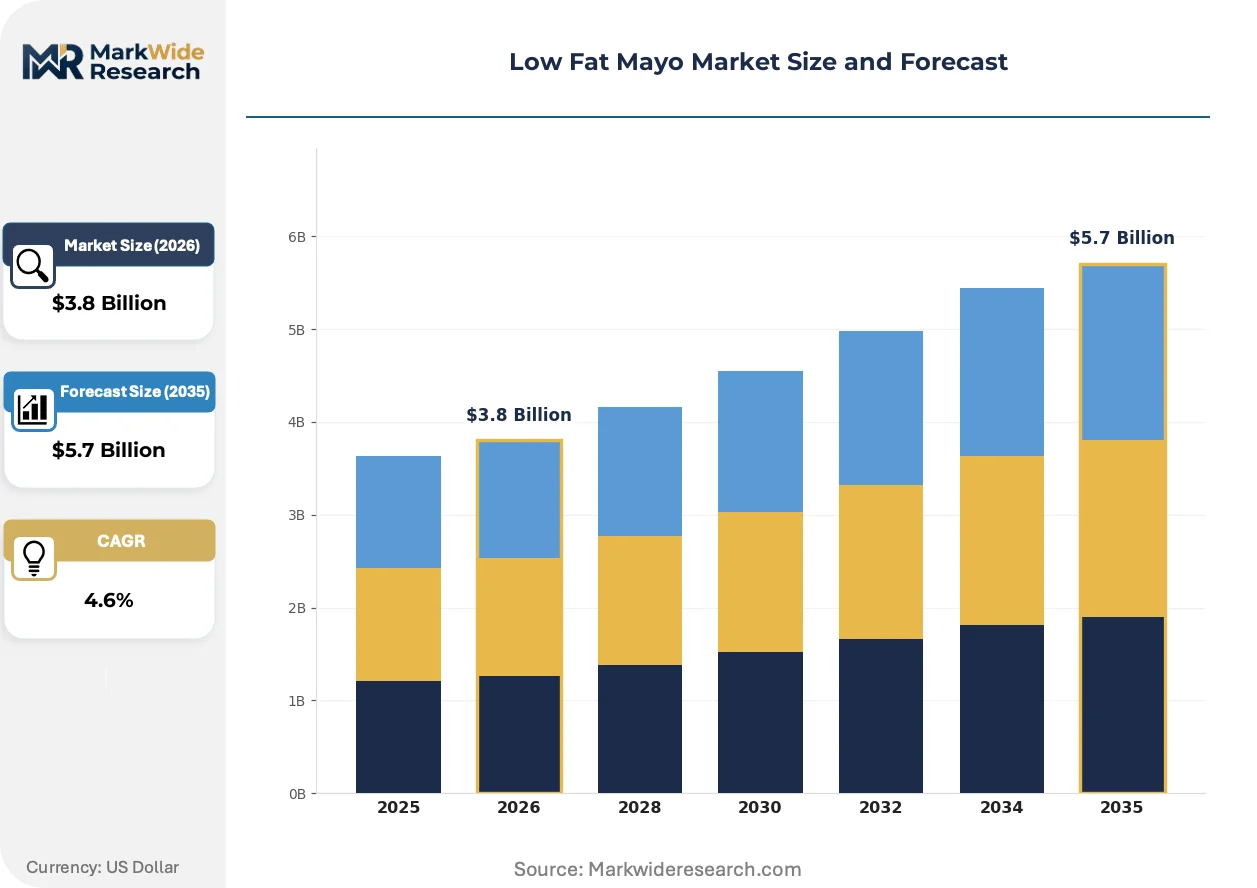
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Mayo, Chipotle Mayo, Garlic Mayo, Vegan Mayo Packaging Type: Tubs, Squeeze Bottles, Jars, Pouches Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale Distributors End User: Households, Restaurants, Food Service, Catering Businesses |
| Companies Covered | Unilever, Kraft Heinz Company, Hellmann's, Best Foods, Sir Kensington's, Duke's Mayonnaise, McCormick & Company, Kewpie Corporation, Nestle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Mayo Market Evolving Landscape
Reformulation science is actively displacing conventional ingredient hierarchies across the mayonnaise category. Manufacturers now engineer texture through molecular gastronomy techniques rather than fat concentration, creating structural separation between premium and commodity positioning.
Clean-label emulsification systems utilizing pea protein and sunflower lecithin are rendering obsolete traditional egg-based stabilization across vegan and allergen-free product lines. Specialty retailers and direct-to-consumer channels are adopting these formulations fastest, with natural grocery chains resetting shelf sets quarterly. The structural consequence compresses conventional mayonnaise R&D timelines and forces legacy manufacturers into accelerated partnership strategies with ingredient technology suppliers.
EPA and state-level environmental regulations are reshaping packaging material selection across single-serve and squeeze bottle formats. Extended producer responsibility frameworks in California and New York mandate recycled content minimums and end-of-life collection infrastructure investment. Food service procurement contracts now specify compliant packaging as a threshold qualification, with non-compliant suppliers disqualified from national account bidding.
Health-conscious consumers are rotating purchasing patterns toward certification-driven preference hierarchies. Retail velocity now concentrates in SKUs displaying non-GMO Project verification or organic USDA seals, displacing conventional light mayonnaise in mainstream grocery. This behavior is most visible in coastal metropolitan markets and club-store channels where household penetration of premium condiments exceeds national averages.
Low Fat Mayo Market Segmentation
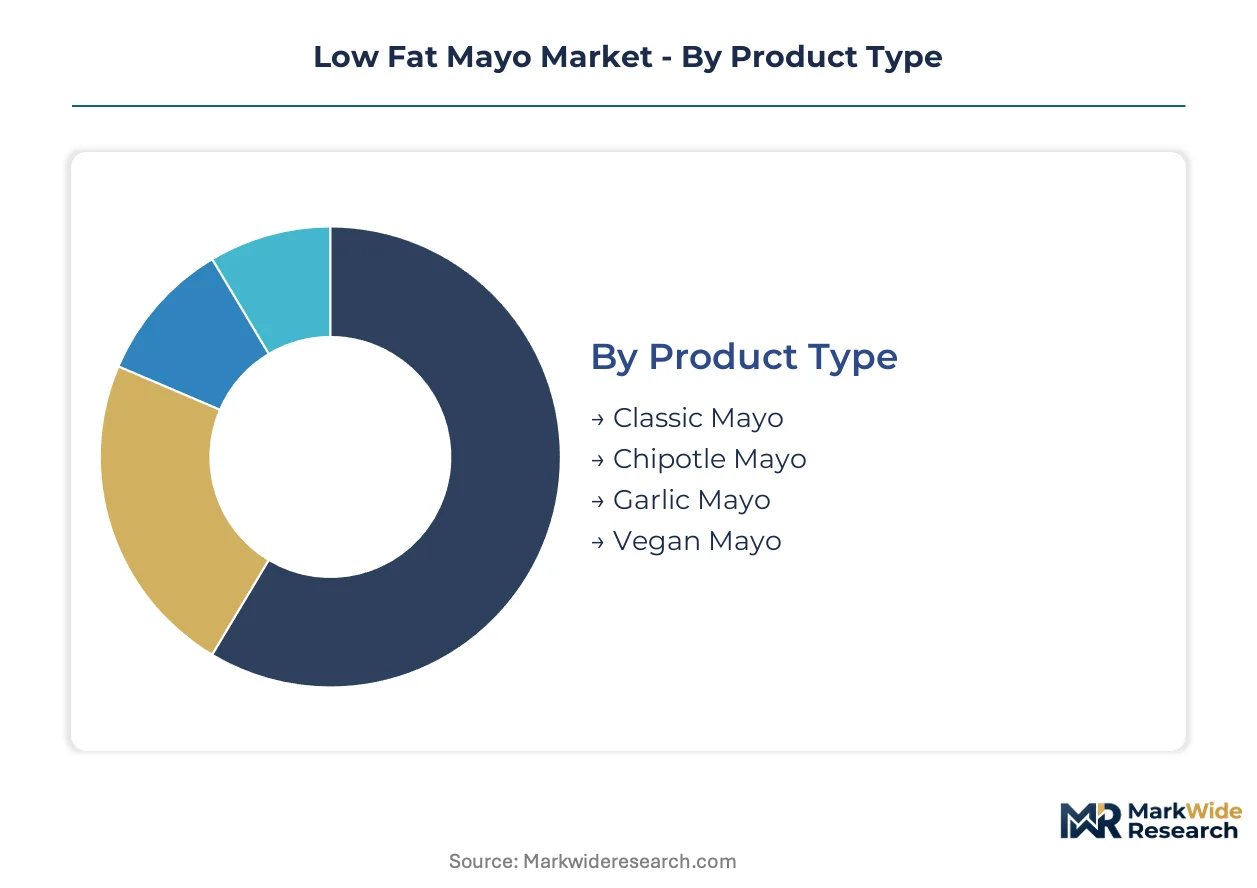
Low fat mayonnaise segmentation reveals divergent velocity patterns across product formats and channel structures. Classic formulations turn inventory fastest through mainstream retail, while emerging variants command longer development cycles and specialty placement timelines.
Product Type:
Cycle times vary dramatically across formulation architectures, with traditional emulsions achieving production scale within weeks while plant-based alternatives require extended stabilization testing and certification protocols.
- Classic Mayo:Oil-in-water emulsions containing 35-50% reduced fat content stabilized with modified food starches. Retail velocity concentrates in United States conventional grocery channels where health-conscious households prioritize familiar taste profiles with validated nutrition claims.
- Vegan Mayo:Egg-free formulations utilizing pea protein or sunflower lecithin emulsification systems. Demand accelerates through natural grocery chains and direct-to-consumer platforms as allergen-free certification and clean-label positioning command shelf placement premiums.
- Chipotle Mayo:Flavored variants incorporating smoked chili emulsions for sandwich and wrap applications.
- Garlic Mayo:Aromatized formulations targeting Mediterranean cuisine occasions and specialty food service menus.
Classic Mayo anchors the volume base while Vegan Mayo gains share at the steepest rate.
Packaging Type:
Cost tier differentiation separates commodity formats from premium positioning, with material specifications and dispensing mechanisms driving per-unit economics across the portfolio.
- Squeeze Bottles:Polyethylene or PET constructions with silicone valve dispensing systems. Convenience-oriented households in United States suburban markets drive procurement velocity through club-store and mass retail channels where portion control and storage efficiency matter.
- Pouches:Flexible film laminates with tear-notch or spout configurations. Food service operators and institutional caterers specify single-serve formats that reduce waste and simplify inventory rotation under FDA food safety protocols.
- Tubs:Polypropylene containers with snap-fit lids retaining strength in club-store procurement.
- Jars:Glass or PET wide-mouth containers commanding specialty retail placement and premium positioning.
Tubs retain institutional volume leadership while Pouches expand most quickly through food service contract specifications.
Distribution Channel:
Application concentration varies by channel archetype, with procurement specifications and velocity requirements shaping supplier qualification thresholds.
- Supermarkets:Conventional grocery and mass merchandiser shelf sets spanning conventional, light, and specialty mayonnaise tiers. United States coastal metropolitan markets reset planograms quarterly to accommodate clean-label SKU proliferation and certification-driven consumer preferences.
- Wholesale Distributors:Broadline and specialty food service purveyors managing temperature-controlled logistics. National account bidding processes now specify EPA-compliant packaging and extended producer responsibility frameworks as threshold qualifications.
- Online Retail:Direct-to-consumer and marketplace platforms with subscription and bulk configurations.
- Specialty Stores:Natural grocery and gourmet food retailers with curated condiment assortments.
Supermarkets maintain the deepest SKU penetration while Online Retail climbs the fastest through subscription model adoption.
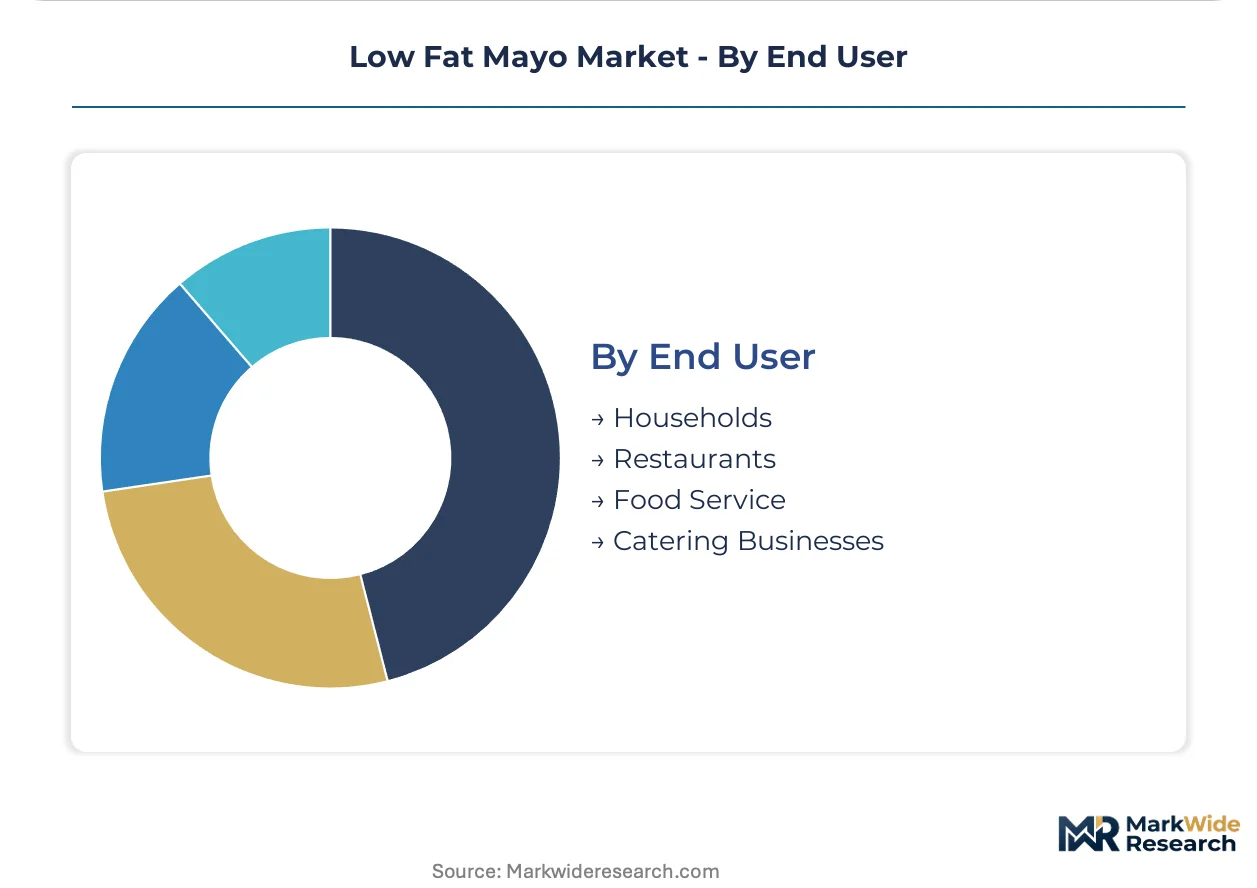
End User:
Customer type segmentation separates household purchasing patterns from institutional procurement behaviors, with volume scale and specification complexity diverging accordingly.
- Restaurants:Full-service and limited-service operators specifying reduced-fat dressings for menu compliance with evolving nutrition transparency requirements. United States quick-service chains accelerate reformulation partnerships to meet USDA school meal standards and corporate wellness commitments.
- Households:Residential consumers purchasing through retail channels with preference hierarchies shaped by certification seals and health claims.
- Food Service:Institutional cafeterias, healthcare facilities, and corporate dining operations with procurement governed by federal nutrition guidelines.
- Catering Businesses:Event and contract caterers requiring portion-controlled formats and extended shelf stability for off-premise service.
Restaurants drive specification innovation while Food Service institutional contracts deliver the most predictable volume commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious households in the United States drive the majority of retail velocity for reduced-fat dressings, with food service operators in Canada and Western Europe following procurement specifications shaped by federal nutrition guidelines.
United States
Supermarket chains along the Eastern Seaboard reset planograms quarterly to accommodate clean-label SKU proliferation. FDA nutrition labeling mandates pressure manufacturers toward lower saturated fat thresholds. The Chicago metropolitan area anchors Midwest distribution networks where club-store procurement of squeeze bottle formats concentrates.
Canada
Health Canada guidelines on sodium reduction influence reformulation pipelines for cross-border retail portfolios. The country's national food regulator maintains alignment with USDA school meal standards for institutional procurement. Toronto and Vancouver metropolitan clusters drive specialty channel velocity for organic-certified variants.
Germany
Retail discounters in Bavaria and North Rhine-Westphalia specify private-label low-fat mayonnaise with EFSA-compliant health claims. The EU Green Deal packaging directives accelerate recycled content adoption for squeeze bottle formats. Hamburg anchors northern European distribution through temperature-controlled logistics hubs serving Scandinavian markets.
United Kingdom
Supermarket own-label penetration in Greater London and the Southeast compresses branded shelf space for conventional light mayonnaise. The Food Standards Agency enforces front-of-pack labeling schemes that privilege reduced-fat variants. Manchester and Birmingham industrial clusters supply reformulated emulsions meeting RSPCA welfare standards for egg sourcing.
Japan
Convenience store chains in the Kanto region specify single-serve pouch formats for bento box applications. METI guidelines on food waste reduction incentivize portion-controlled packaging innovation. The Osaka-Kobe manufacturing corridor concentrates emulsion technology expertise for Asian export markets.
Low Fat Mayo Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered shelf space allocations. The structure consolidates around multinational consumer goods conglomerates with broad retail distribution, while premium positioning fragments among clean-label specialists. Two strategic archetypes dominate: scale-driven portfolio operators leveraging R&D networks, and ingredient-transparent challengers commanding specialty channel premiums. Competitive moves concentrate on reformulation partnerships with hydrocolloid suppliers and accelerated certification acquisition for non-GMO and organic seals.
Within the scale-driven tier, Unilever and Kraft Heinz Company occupy positions anchored by global manufacturing footprints and retail shelf presence. Sir Kensington's exemplifies the premium-specialist archetype, representing clean-label positioning through avocado-oil-based formulation approaches. These three entities collectively illustrate the competitive tension between mass-market velocity and specialty-channel margin capture that defines current strategic positioning.
| Leading Market Players |
|---|
| Unilever |
| Kraft Heinz Company |
| Hellmann's |
| Best Foods |
| Sir Kensington's |
| Duke's Mayonnaise |
| McCormick & Company |
| Kewpie Corporation |
| Nestle |
| Others |
Value Network & Pricing Analysis
Commodity volatility in vegetable oil markets determines both pricing tier spreads and supply chain shape across low fat mayonnaise manufacturing. Avocado oil price swings from climate-driven harvest variability in Mexico and California compress margins on premium variants while forcing reformulation toward modified starch stabilization in economy tiers.
Pricing Analysis
Cost-plus contracts with vegetable oil indexation dominate procurement between manufacturers and bulk oil suppliers. Three-tier pricing structure across premium, standard, and economy levels separates avocado-oil-based clean-label SKUs from modified-starch conventional formulations and private-label commodity offerings. Pricing pressure stems from Greek yogurt dressings and hummus spreads displacing mayonnaise occasions in health-conscious households. Food service operators exhibit highest price sensitivity due to thin menu margins, while specialty retail channels absorb premium positioning for certified organic variants.
Supply Chain Analysis
Tariff exposure between the United States and Mexico dominates input cost planning for avocado oil sourcing. Manufacturing concentrates in the United States, Mexico, and Germany where emulsion technology expertise and temperature-controlled logistics infrastructure cluster. Raw material dependencies center on vegetable oils, egg yolk lecithin or pea protein alternatives, and modified food starches. Single-source vulnerability runs through Mexican avocado harvests for premium positioning. Distribution runs through broadline food service purveyors and retail grocery networks with quarterly planogram resets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label emulsification technology is reshaping competitive positioning through molecular gastronomy texture engineering that fragments traditional manufacturing approaches.
For Market Incumbents: Entrench market position through accelerated certification acquisition for non-GMO and organic seals that command shelf placement premiums. Defend against Sir Kensington's and other clean-label challengers by retrofitting legacy production lines for lower-viscosity low-fat formulations. Priority levers include backward integration into hydrocolloid supply and exclusive reformulation partnerships with pea protein technology suppliers. For New Entrants and Emerging Players: Pursue white-space opportunities in single-serve pouch formats for food service contract specifications where established players lag packaging innovation. Target institutional procurement channels governed by USDA school meal standards with reformulated emulsions meeting sodium reduction thresholds. Go-to-market angle should emphasize EPA-compliant packaging qualifications that disqualify legacy suppliers from national account bidding. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors ingredient-transparent specialists with clean-label certification depth. Long-term viability over the next decade hinges on emulsion science talent pipelines and hydrocolloid R&D partnerships. Acquisition target archetype includes mid-scale manufacturers with established avocado oil supply relationships and pending organic certification. Signal to watch is state-level sodium reduction initiative passage triggering additional recipe engineering cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Certification Investment | Non-GMO Project verification unlocks specialty channel placement premiums in coastal metropolitan markets. |
| Single-Serve Pouch Format Launch | Portion-controlled packaging meets food service procurement specifications for waste reduction under FDA protocols. |
| Backward Integration into Hydrocolloids | In-house modified starch production insulates margin compression from gum blend supplier concentration. |
| Avocado Oil Supply Agreement | Long-term offtake contracts with Mexican and California producers lock in premium positioning raw material access. |
| Reformulation Partnership | Collaboration with pea protein technology suppliers accelerates vegan variant development for allergen-free certification. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA nutrition labeling guidance documents, USDA school meal procurement databases, and EPA packaging compliance records. Industry stakeholders interviewed include condiment brand managers, category buyers at supermarket chains, food service procurement directors, and emulsion technology R&D leads. Secondary validation draws from Nielsen retail audit data, customs import records for vegetable oils, and state-level environmental regulatory filings. Bottom-up volume modeling triangulates against top-down market sizing across product type, packaging format, and distribution channel segments.
Forecast inputs incorporate reformulation pipeline timelines, certification acquisition cycles, and channel shelf reset frequencies. The analytical framework models Classic Mayo, Vegan Mayo, and flavored variants across squeeze bottle, pouch, tub, and jar formats through supermarket, wholesale distributor, online retail, and specialty store channels. CAGRs derive from velocity trend extrapolation adjusted for regulatory mandate implementation schedules. Industry-specific inputs include hydrocolloid technology maturity curves and state-level extended producer responsibility framework adoption patterns.
Sensitivities concentrate around FDA sodium reduction guidance timing, avocado oil harvest variability from climate patterns, and clean-label certification standard evolution. Forecasts reflect assumptions about emulsion stability breakthroughs enabling fat reduction beyond current technical limits. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Organic Condiments Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
Soy-Based Sauce Market
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Asia-Pacific Condiments Market
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Vegan Sauces Market
Condiments & Sauces
Sandwich Spread Market
Condiments & Sauces
Oriental Sauce Market
Condiments & Sauces
Pasta Sauce Market
Condiments & Sauces
Hot Sauce Market
Condiments & Sauces
West Africa Mayonnaise Market
Condiments & Sauces
Mayonnaise Sauce Market
Condiments & Sauces
Vinegar and Vinaigrette Market
Condiments & Sauces
Gluten-Free Soups and Sauces Market
Condiments & Sauces
Low Fat Pasta Sauce Market