
 Commercial Refrigerated Display Cabinet Market | 2026-2036
Commercial Refrigerated Display Cabinet Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Refrigerated Display Cabinet Market Insights
Supermarket procurement is consolidating around fewer national and multinational chains with standardized equipment specifications and centralized vendor qualification. Hussmann Corporation leverages its direct-store-delivery service network to sustain long-term maintenance contracts with these consolidated buyers. Epta S.p.A. anchors its competitive position through vertical integration into compressor and refrigeration system manufacturing, while Carrier Corporation differentiates via connected cold-chain platforms that integrate display cabinet telemetry with broader facility management systems.
A commercial refrigerated display cabinet is an insulated enclosure with forced-air or gravity-coil refrigeration designed to maintain food-safe temperatures between 0°C and 4°C for fresh products, or below -18°C for frozen goods, while permitting full product visibility through glass panels. These units employ polyurethane foam insulation, hermetic or semi-hermetic compressors, and electronic expansion valves to achieve precise temperature control with minimal energy loss. Vertical configurations dominate installed base volumes due to their floor-space efficiency in high-traffic retail environments, while smart technologies represent the fastest-expanding technology segment as retailers deploy IoT-enabled cabinets for predictive maintenance and energy optimization. The freestanding installation category retains the broadest addressable market across retrofit and new-build scenarios, though modular systems are gaining share in flexible-format convenience stores.
The US EPA SNAP program and the EU F-Gas Regulation are restricting hydrofluorocarbon refrigerants and mandating lower-global-warming-potential alternatives, which forces manufacturers to redesign compressor systems and recertify entire product lines. Japan's METI energy-efficiency standards and China's GB national standards for commercial refrigeration impose minimum performance coefficients that filter out lower-tier suppliers and concentrate certification burdens on established manufacturers. Stakeholders must monitor refrigerant transition timelines and efficiency standard convergence across major economies to align R&D roadmaps with compliance windows.
Market Dynamics
Supermarket chains are consolidating procurement around standardized equipment specifications, forcing manufacturers to recertify entire product lines for natural refrigerant compatibility under tightening EU F-Gas Regulation and US EPA SNAP mandates.
Growth Catalysts
- EU F-Gas Regulation phase-down:Mandates restricting hydrofluorocarbon refrigerants accelerate technology transitions toward CO2 and hydrocarbon systems, creating replacement demand across installed bases.
- Fresh food section expansion:Supermarket chains are enlarging produce and deli departments, requiring additional vertical display cabinets with precise temperature control.
- IoT-enabled predictive maintenance:Connected cabinet telemetry allows retailers to optimize energy consumption and reduce downtime through real-time monitoring.
Market Restraints
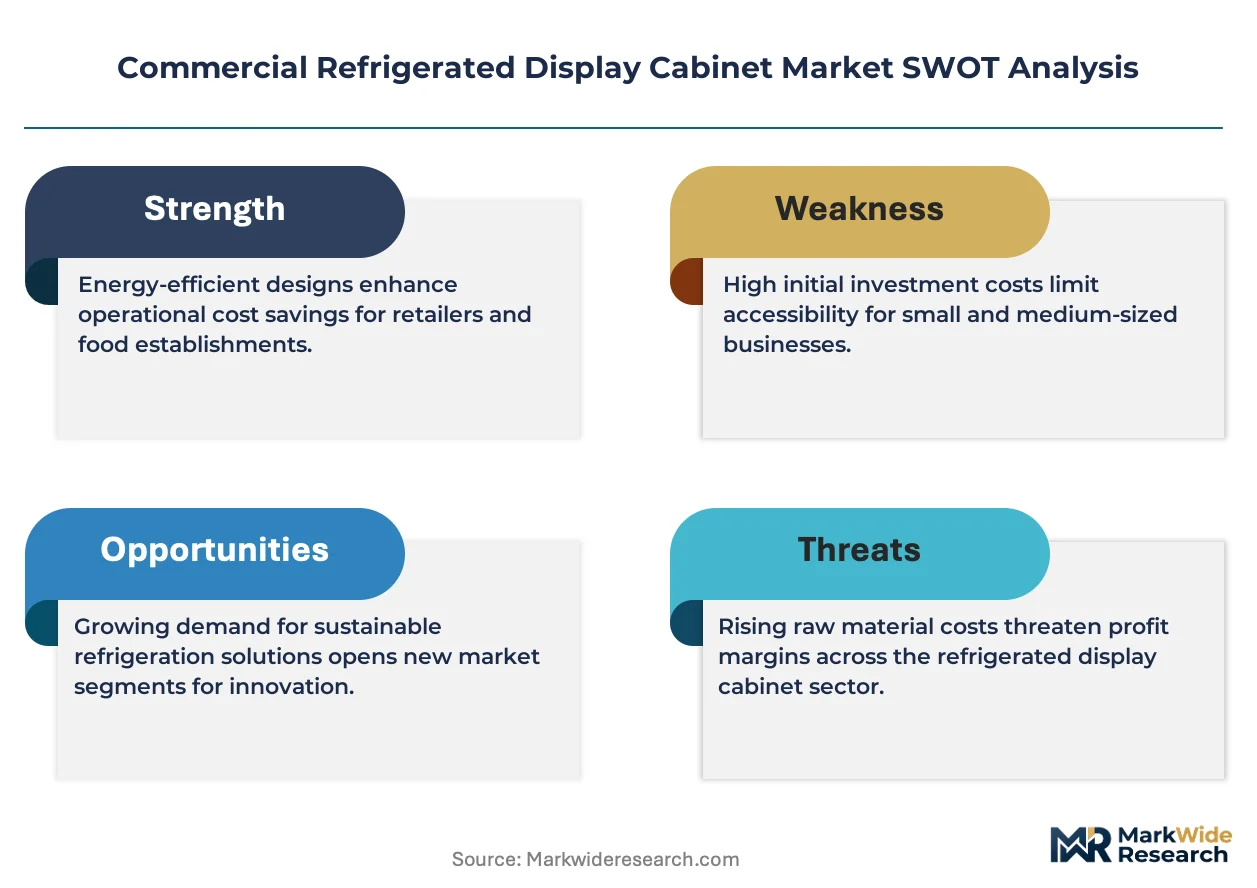
- Copper and aluminum price volatility:Compressor manufacturing and coil fabrication face input cost instability that compresses margins on fixed-price contracts.
- Refrigerant supply concentration:Natural refrigerant production clusters in limited chemical processing regions, exposing manufacturers to supply interruptions.
- Semi-hermetic compressor technical limitations:These systems struggle to achieve efficiency targets under China's GB national standards without substantial redesign.
Strategic Opportunities
- India's modern retail infrastructure:Organized food retail penetration remains below levels seen in China or Germany, creating whitespace for modular cabinet deployments.
- Convenience store format proliferation:Flexible-format retailers seek compact, plug-and-play display solutions that retrofit existing spaces without structural modification.
- Japan's METI energy-efficiency incentives:Subsidy programs for high-performance commercial refrigeration equipment accelerate premium product adoption.
Industry Challenges
- Natural refrigerant technician scarcity:CO2 transcritical and hydrocarbon systems require specialized installation and service skills that the workforce currently lacks.
- Multi-jurisdiction certification timelines:Manufacturers must secure separate approvals under US EPA SNAP, EU F-Gas, and China's GB standards before market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Refrigerated Display Cabinet Market |
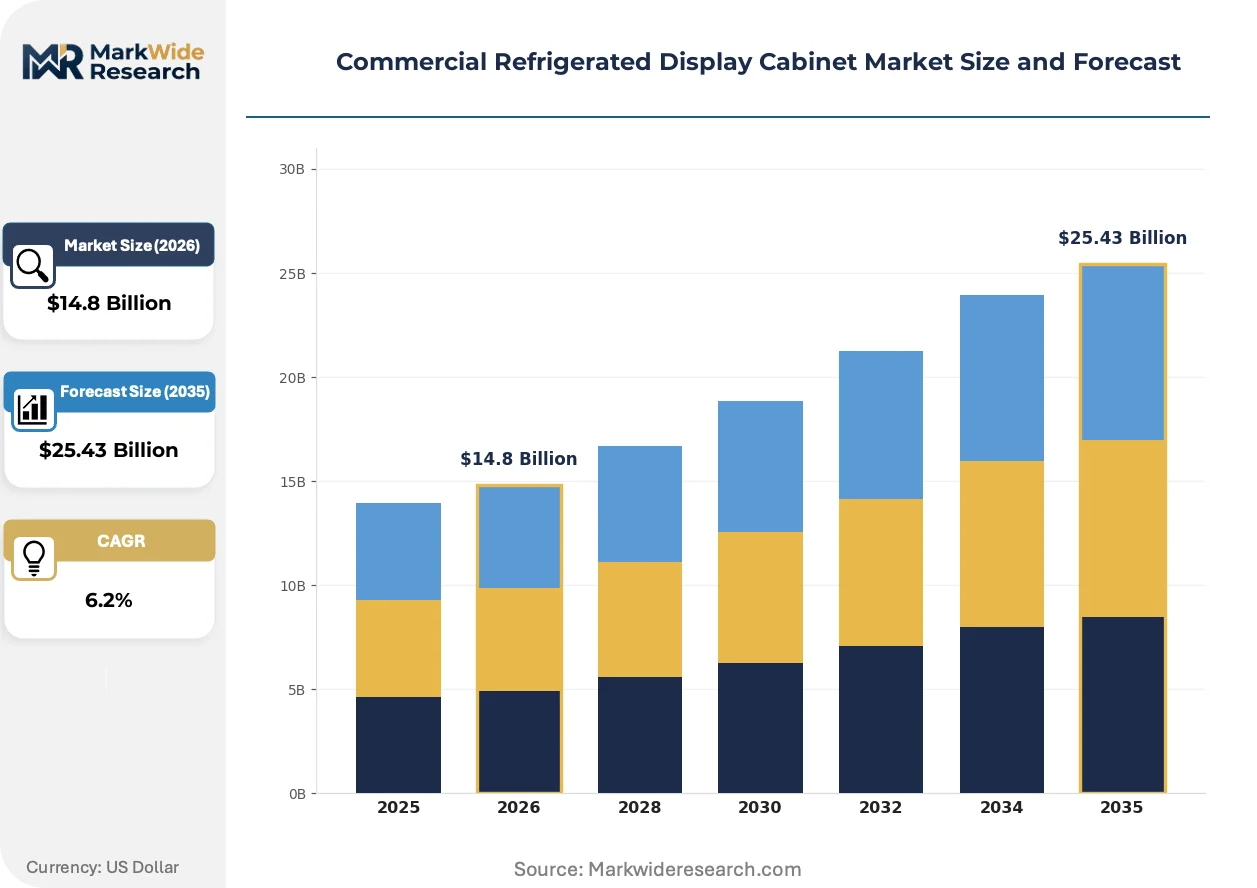
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical, Horizontal, Counter, Specialty End User: Supermarkets, Convenience Stores, Restaurants, Cafés Installation: Built-in, Freestanding, Modular, Integrated Technology: Static Cooling, Dynamic Cooling, Eco-friendly Refrigerants, Smart Technologies |
| Companies Covered | Hussmann Corporation, Epta S.p.A., Carrier Corporation, Haier Group Corporation, Hillphoenix Inc., AHT Cooling Systems GmbH, Frigoglass S.A.I.C., True Manufacturing Co. Inc., Liebherr-International Deutschland GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Refrigerated Display Cabinet Market Trends and Innovations
Refrigeration technology is converging with digital infrastructure and natural refrigerant chemistry, compressing traditional equipment lifecycles while opening new service revenue streams for manufacturers.
CO2 transcritical booster systems are rewriting efficiency benchmarks for medium-temperature display cabinets in warm climates. European supermarket chains operating stores in Spain and Italy are retrofitting conventional HFC systems ahead of regulatory deadlines. This technology is rewriting competitive positioning by rewarding manufacturers with in-house compressor engineering capabilities.
The EU F-Gas Regulation's refrigerant quota system tightens hydrofluorocarbon availability through 2030. Equipment manufacturers must redesign expansion valves and pressure vessels for higher-operating-pressure natural alternatives. Frozen food sections face the steepest compliance burden due to lower-temperature requirements.
Centralized vendor qualification portals now dominate multinational supermarket procurement. Regional equipment distributors lose direct buyer relationships as chains consolidate technical specifications and maintenance contracts at headquarters level. Germany's REWE and EDEKA chains exemplify this concentration most visibly.
Commercial Refrigerated Display Cabinet Market Segmentation
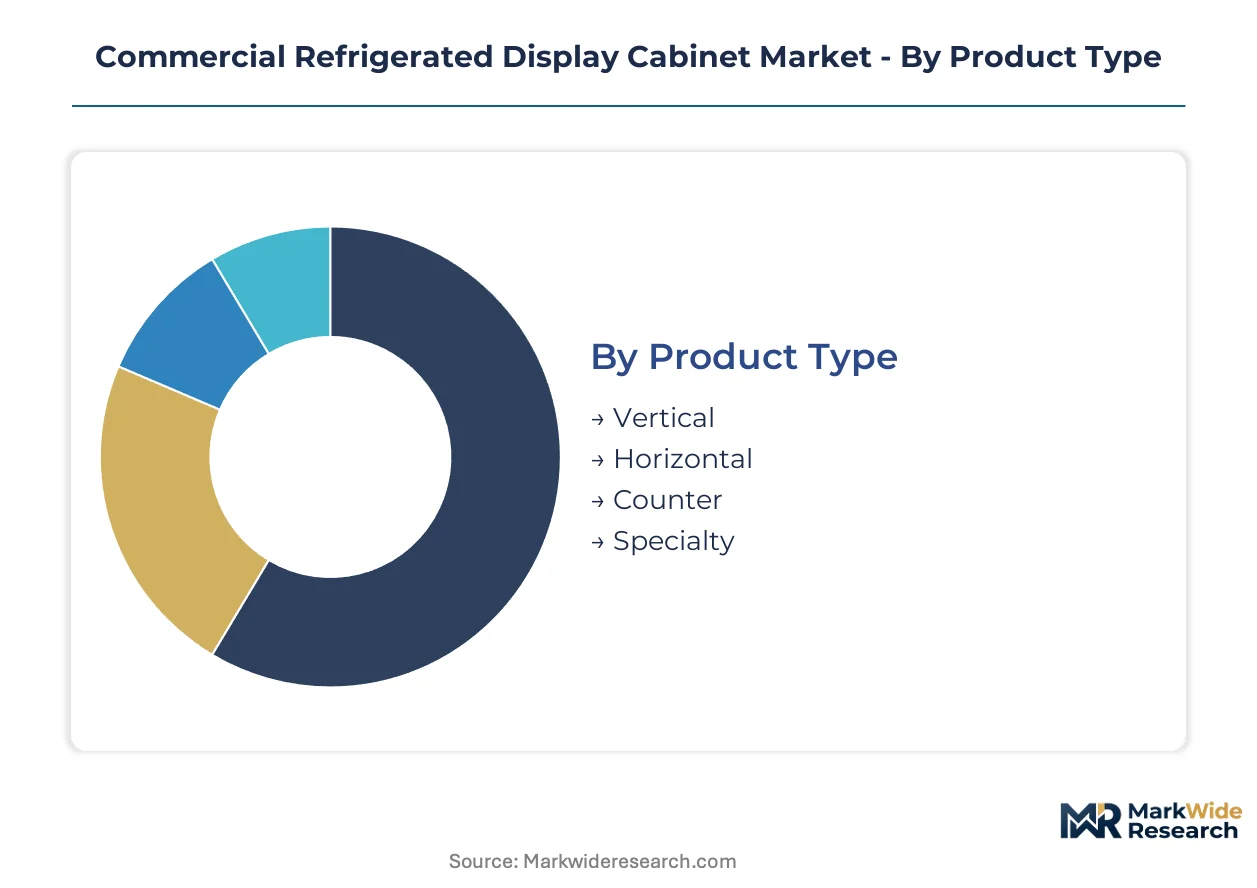
Retail format diversity and refrigerant transition timelines fragment demand across incompatible technical specifications. Manufacturers must maintain parallel product lines serving frozen-food supermarkets in Germany, grab-and-go convenience stores in Japan, and open-kitchen restaurants in Dubai.
Product Type:
Supply concentrates among three configurations that dominate floor-space planning in modern retail architecture.
- Vertical:Tall glass-door enclosures maximize product visibility per square meter in high-traffic supermarket aisles. Supermarket chains in Germany and the United States specify these units for fresh produce sections, driving replacement cycles under EU F-Gas Regulation deadlines.
- Horizontal:Chest-style cabinets with sliding or lift-up glass tops serve frozen-food sections where bulk storage density matters more than browsing convenience. Convenience store operators in Japan favor compact horizontal units for limited floor plates.
- Counter:Low-profile units integrate with checkout lanes and service counters for impulse-purchase categories.
- Specialty:Custom-configured enclosures serve bakeries, seafood displays, and wine storage with precise humidity control.
Today's leader: Vertical. Tomorrow's challenger: Horizontal.
End User:
Procurement scale separates national supermarket chains from fragmented foodservice operators.
- Supermarkets:Centralized technical specifications dominate capital expenditure, with REWE and EDEKA in Germany standardizing on connected cabinet platforms. These buyers negotiate multi-year maintenance contracts that lock in vendor relationships.
- Convenience Stores:Smaller footprints in Japan and South Korea demand plug-and-play modular systems with rapid installation cycles. METI energy-efficiency incentives accelerate premium product adoption in this segment.
- Restaurants:Open-kitchen concepts in Dubai and Singapore specify glass-front display cabinets as design elements.
- Cafés:Limited refrigeration loads focus on pastry and beverage display with minimal frozen storage.
Supermarket chains consolidate procurement. Convenience stores represent the steepest expansion trajectory.
Installation:
Retrofit flexibility determines addressable market breadth across aging retail infrastructure.
- Freestanding:Self-contained units with integrated compressors deploy without structural modification, capturing replacement demand in existing stores. This configuration serves the broadest geographic footprint from suburban US supermarkets to Indian urban retail.
- Modular:Component-based systems allow reconfiguration as convenience store formats evolve, gaining share in flexible-format retail in South Korea and Japan.
- Built-in:Custom-integrated enclosures serve flagship supermarket locations with architectural specifications.
- Integrated:Whole-system designs merge display cabinets with centralized refrigeration plants.
Freestanding dominates installed base volumes. Modular systems gain share fastest in Asia-Pacific convenience retail.
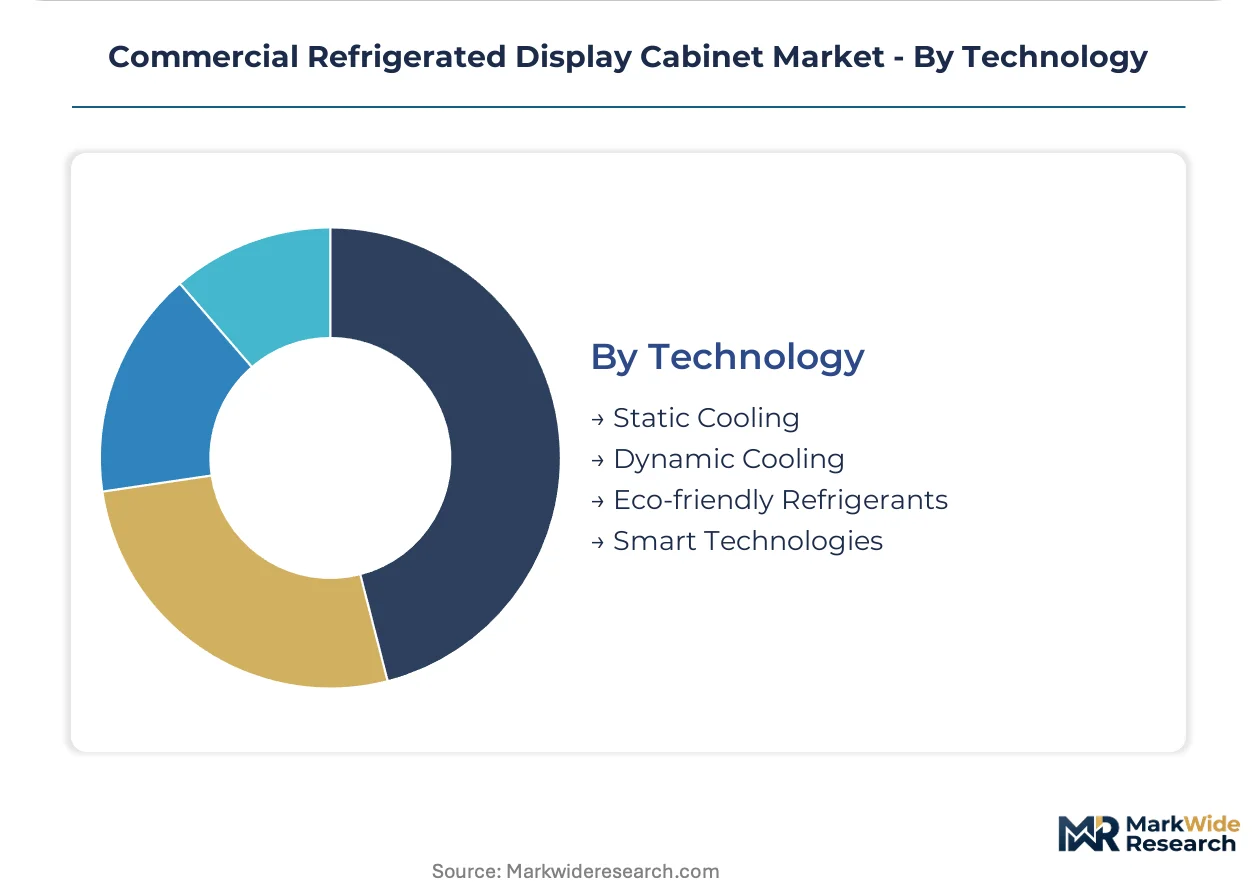
Technology:
Regulatory phase-downs are concentrating R&D investment on natural refrigerant architectures.
- Smart Technologies:IoT-enabled telemetry platforms from Hussmann and Carrier integrate cabinet sensors with facility management systems. Supermarket chains in Germany and the United States deploy these for predictive maintenance and energy optimization.
- Eco-friendly Refrigerants:CO2 transcritical and hydrocarbon systems replace hydrofluorocarbon equipment under EU F-Gas Regulation and US EPA SNAP mandates, requiring redesigned pressure vessels and expansion valves.
- Dynamic Cooling:Forced-air circulation maintains precise temperature uniformity for fresh produce.
- Static Cooling:Gravity-coil refrigeration serves frozen goods with minimal air movement.
Smart Technologies command premium pricing. Eco-friendly Refrigerants face the steepest regulatory compliance burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's supermarket chains outpace Germany's in absolute installation volumes, yet German retailers enforce stricter refrigerant transition timelines that compress equipment replacement cycles.
China
Fresh food section expansions at Hema Fresh and Yonghui Superstores drive vertical cabinet procurement in Shanghai and Beijing. GB national standards for commercial refrigeration filter lower-tier suppliers through minimum performance coefficients. Yangtze River Delta manufacturing clusters produce compressor systems for domestic retrofit programs.
Germany
REWE and EDEKA chains centralize technical specifications and maintenance contracts at headquarters level. EU F-Gas Regulation mandates accelerate CO2 transcritical retrofits ahead of 2030 quota deadlines. Industrial concentration in Bavaria and North Rhine-Westphalia hosts engineering centers for natural refrigerant system redesign.
United States
Walmart and Kroger procurement consolidation standardizes equipment specifications across national footprints. EPA SNAP program restrictions on hydrofluorocarbons force compressor system recertification. Texas and California distribution hubs coordinate direct-store-delivery networks for long-term maintenance contracts.
Japan
Convenience store format proliferation in Tokyo and Osaka demands compact modular systems with rapid installation cycles. METI energy-efficiency incentives subsidize high-performance commercial refrigeration equipment. Kanto region engineering facilities develop IoT-enabled telemetry platforms for predictive maintenance deployment.
India
Organized food retail penetration remains below Chinese levels, creating whitespace for modular cabinet deployments in Mumbai and Delhi-NCR. FSSAI food safety enforcement intensifies cold-chain infrastructure requirements. Maharashtra and Gujarat manufacturing zones assemble freestanding units for urban retrofit scenarios.
Commercial Refrigerated Display Cabinet Market Competitive Landscape
German and Italian producers anchor the premium systems tier; Chinese fabricators hold volume positions in standardized configurations. Market structure concentrates around multinational refrigeration specialists with captive compressor engineering capabilities and regional distributors serving fragmented convenience store operators. Two strategic archetypes dominate: vertically integrated manufacturers controlling upstream component production, and connected-platform providers integrating cabinet telemetry with facility management systems. Competitive moves center on refrigerant transition R&D acceleration and centralized vendor qualification portal penetration.
Among North American refrigeration specialists, Hussmann Corporation and Carrier Corporation exemplify divergent platform strategies. European manufacturers concentrate competitive depth: Epta S.p.A. occupies a position within the integrated systems tier, while AHT Cooling Systems GmbH anchors the Austrian-German engineering corridor. Haier Group Corporation represents scale-driven manufacturing archetypes originating from Chinese industrial bases. These named entities illustrate how geographic origin and corporate structure correlate with strategic positioning across natural refrigerant transition timelines.
| Leading Market Players |
|---|
| Hussmann Corporation |
| Epta S.p.A. |
| Carrier Corporation |
| Haier Group Corporation |
| Hillphoenix Inc. |
| AHT Cooling Systems GmbH |
| Frigoglass S.A.I.C. |
| True Manufacturing Co. Inc. |
| Liebherr-International Deutschland GmbH |
| Others |
Pricing and Supply Chain Analysis
Backward integration into compressor manufacturing anchors both cost position and pricing power for European and North American refrigeration specialists, insulating premium-tier producers from copper and aluminum volatility while forcing Asian fabricators toward volume-based standardization.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for standardized vertical cabinets, compressing margins on fixed-price contracts for mid-tier suppliers. Three-tier pricing structure across premium, standard, and economy levels separates connected-platform systems with predictive maintenance bundling from basic freestanding units. Pricing pressure stems from refrigerant transition R&D recertification costs under EU F-Gas Regulation deadlines. National supermarket chains exhibit lowest price sensitivity due to centralized vendor qualification portals, while fragmented convenience store operators in India and Southeast Asia drive hardest bargain negotiations.
Supply Chain Analysis
Ocean freight rate fluctuations from Shanghai to Hamburg and Long Beach directly impact landed costs for complete cabinet systems, favoring regional manufacturing footprints in Germany and the United States for time-sensitive retrofit programs. Supply concentrates in China, Germany, and Italy for compressor systems, polyurethane foam insulation, and electronic expansion valves respectively. Raw material dependencies center on copper coil stock, aluminum heat exchangers, and specialized refrigerant-grade steel. Single-source vulnerability in natural refrigerant chemical processing exposes manufacturers to supply interruptions. Distribution runs through direct-store-delivery networks for national supermarket chains and regional equipment distributors serving fragmented foodservice operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial refrigerated display cabinet market functions as a stable compounder, with regulatory-mandated equipment replacement cycles under EU F-Gas Regulation and US EPA SNAP programs generating predictable refresh demand across installed bases.
For Market Incumbents: Lock in long-term maintenance contracts with consolidating supermarket procurement portals before refrigerant transition deadlines concentrate vendor relationships. Deepen backward integration into compressor engineering to capture CO2 transcritical system premiums. Defend against Asian fabricators by accelerating IoT platform deployment for predictive maintenance revenue streams. For New Entrants and Emerging Players: Enter via modular plug-and-play systems targeting India's underpenetrated organized food retail sector in Mumbai and Delhi-NCR. Exploit whitespace in convenience store format proliferation across South Korea and Japan where rapid installation cycles favor agile suppliers. Pursue METI energy-efficiency certification to access Japanese subsidy programs and establish credibility with premium buyers. For Investors and Strategic Acquirers: Roll-up economics work for regional distributors with captive service networks because centralized vendor qualification is displacing direct buyer relationships and concentrating maintenance contract value at headquarters level. Five-to-ten year viability rests on natural refrigerant transition execution capabilities. Target acquisition archetype: mid-tier European manufacturers with in-house compressor engineering and established EU F-Gas recertification pipelines. Watch CO2 transcritical adoption rates in warm-climate European markets as inflection indicator for technology winner determination.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant System Redesign | EU F-Gas Regulation mandates force compressor recertification ahead of 2030 quota deadlines. |
| IoT Platform Integration | Connected cabinet telemetry from Hussmann and Carrier merges with facility management systems. |
| Vertical Integration into Compressors | Epta's captive manufacturing of refrigeration systems insulates margins from input cost volatility. |
| Geographic Manufacturing Expansion | Texas and California distribution hubs coordinate direct-store-delivery networks for Walmart and Kroger. |
| Energy Efficiency Certification Investment | China's GB national standards filter lower-tier suppliers through minimum performance coefficients. |
Research Methodology
Bottom-up supermarket and convenience store procurement modeling reconciled against top-down compressor and refrigeration system manufacturing tracking forms the analytical core of this study. Primary interviews with equipment procurement directors at REWE and EDEKA chains, maintenance contract managers at Hussmann Corporation, plant engineers at Yangtze River Delta manufacturing clusters, and regulatory affairs specialists at EPA and METI combined with secondary validation from EU F-Gas Regulation filings, EPA SNAP program submissions, China's GB standards documentation, and customs trade data for compressor imports.
Input-output matrices map refrigerant technology transitions, installation format preferences, and end-user procurement scale across product type, installation configuration, and regional regulatory cluster dimensions. CAGRs derive from equipment replacement cycle analysis and fresh food section expansion trajectories. Forecast inputs include supermarket chain capital expenditure disclosures and METI energy-efficiency subsidy allocation patterns.
Inputs from centralized vendor qualification portals and national standards bodies were available through the study window; gaps in privately negotiated maintenance contract terms introduce uncertainty bands around service revenue projections. Forecasts reflect documented assumptions about refrigerant transition timelines and efficiency standard convergence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Bar Equipment Market
Food Service Equipment
Hospital Foodservice Equipment Market
Food Service Equipment
Retail Cooler Market
Food Service Equipment
Beverage Refrigeration Market
Food Service Equipment
Scroll Chiller Market
Food Service Equipment
Saudi Arabia Foodservice Disposable Packaging Market
Food Service Equipment
Commercial Rotisserie Oven Market
Food Service Equipment
Low-Sugar Rice Cooker Market
Food Service Equipment
Rapid Cook-High Speed Ovens Market
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Global Frozen Drink Machines Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Global Commercial Cooking Equipment Market
Food Service Equipment
Food Serving Equipment Market
Food Service Equipment
Countertop Ice Dispensers Market
Food Service Equipment
Restaurant Equipment Market