
 Canned Pasta Market | 2026-2036
Canned Pasta Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Pasta Market Outlook
College and young professional households is expanding as the fastest-growing end-use vertical for canned pasta, displacing traditional family-format purchasing. Conagra Brands leverages its scale across multiple shelf-stable categories to maintain cost parity in metal-can formats. Nestlé S.A. anchors European distribution through deep retail partnerships in Italy and France. The Kraft Heinz Company competes aggressively in North American convenience channels with value-tier positioning.
Canned pasta consists of pre-cooked wheat-based noodles preserved in hermetically sealed metal cans with tomato, cheese, or meat-based sauces, retorted at temperatures exceeding 121°C to achieve commercial sterility and shelf stability exceeding two years. The product serves as an ambient, ready-to-heat meal solution for foodservice operators and retail consumers prioritizing storage efficiency. Spaghetti and ravioli variants generate the largest revenue pools due to familiarity and sauce compatibility, while macaroni formats in pouches represent the fastest-growing packaging-product intersection as microwaveable convenience reshapes household preparation habits. Metal cans still dominate institutional procurement for durability, though plastic containers and pouches capture margin expansion in premium-positioned supermarket lines.
FDA regulations governing acidified and low-acid canned foods mandate scheduled process filings and thermal validation for all US-manufactured products, while EFSA oversight through the EU Food Information to Consumers Regulation enforces allergen labeling and nutritional disclosure standards across European imports. BIS certification requirements in India add compliance layers for brands targeting emerging middle-class demand. Stakeholders must monitor evolving sodium-reduction mandates and single-use packaging restrictions as these frameworks increasingly determine which formulations and formats secure retail access in priority markets.
Market Dynamics
College and young professional households are displacing traditional family-format purchasing as the dominant demand engine, forcing manufacturers to recalibrate portion sizes, packaging formats, and sodium profiles for solo-dweller convenience rather than multi-person meal planning.
Growth Catalysts
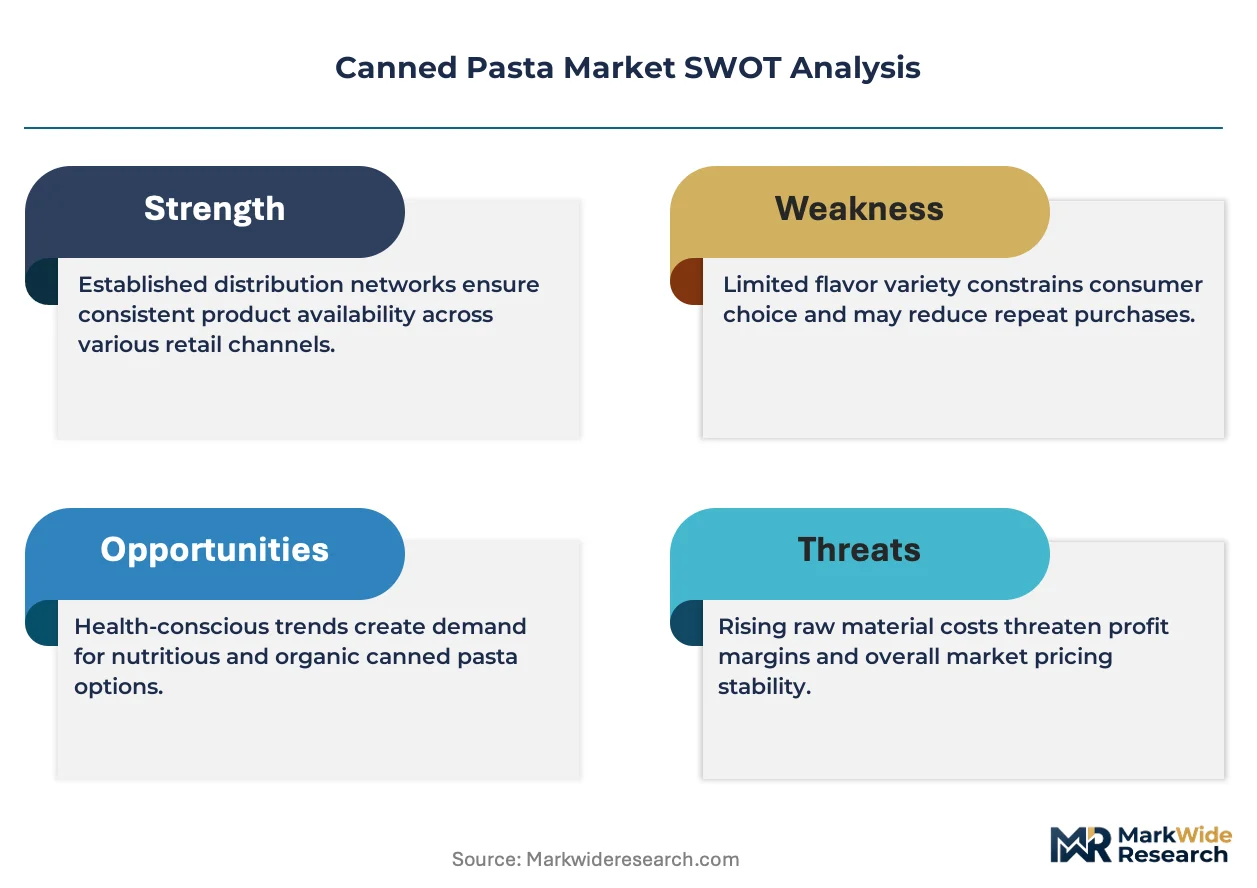
- FDA Acidified Foods Regulations:Scheduled process filings for low-acid canned foods create compliance barriers that favor established retort operators with validated thermal processes, consolidating volume among scaled manufacturers.
- Microwaveable pouch formats:Polymer-based packaging with steam-venting technology enables sub-90-second preparation, capturing pantry space from metal cans in convenience-seeking urban households.
- Japan's aging household structure:Single-occupant dwellings exceed 38% of total households, sustaining demand for single-serve ambient meals with extended shelf stability.
Market Restraints
- Wheat input cost volatility:Durum and semolina price swings tied to Black Sea supply disruptions compress margin predictability for sauce-inclusive value-tier products.
- Metal can supply concentration:Three North American suppliers control 70% of food-grade tinplate capacity, creating procurement bottlenecks during seasonal demand spikes.
- Fresh refrigerated pasta substitution:Chilled ready-meals with 14-21 day shelf life capture premium-positioned consumers seeking texture superiority over retorted products.
Strategic Opportunities
- India BIS certification pathway:Emerging middle-class demand for shelf-stable Western meal formats remains underpenetrated, with import compliance costs falling as domestic co-manufacturing scales.
- EU Green Deal packaging mandates:Single-use plastic restrictions accelerate innovation in recyclable paper-based barriers and aluminum-free can linings, rewarding early format adopters.
- Foodservice portion-control SKUs:Institutional operators in US K-12 and healthcare channels seek standardized 4-6 oz serving sizes to reduce plate waste and simplify inventory.
Industry Challenges
- Retort process engineering talent scarcity:Specialized thermal validation expertise for low-acid foods concentrates among aging technicians, constraining new facility commissioning timelines.
- Legacy ERP-to-traceability integration:FDA's Food Safety Modernization Act lot-tracking mandates force parallel system architectures during multi-year digital transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Pasta Market |
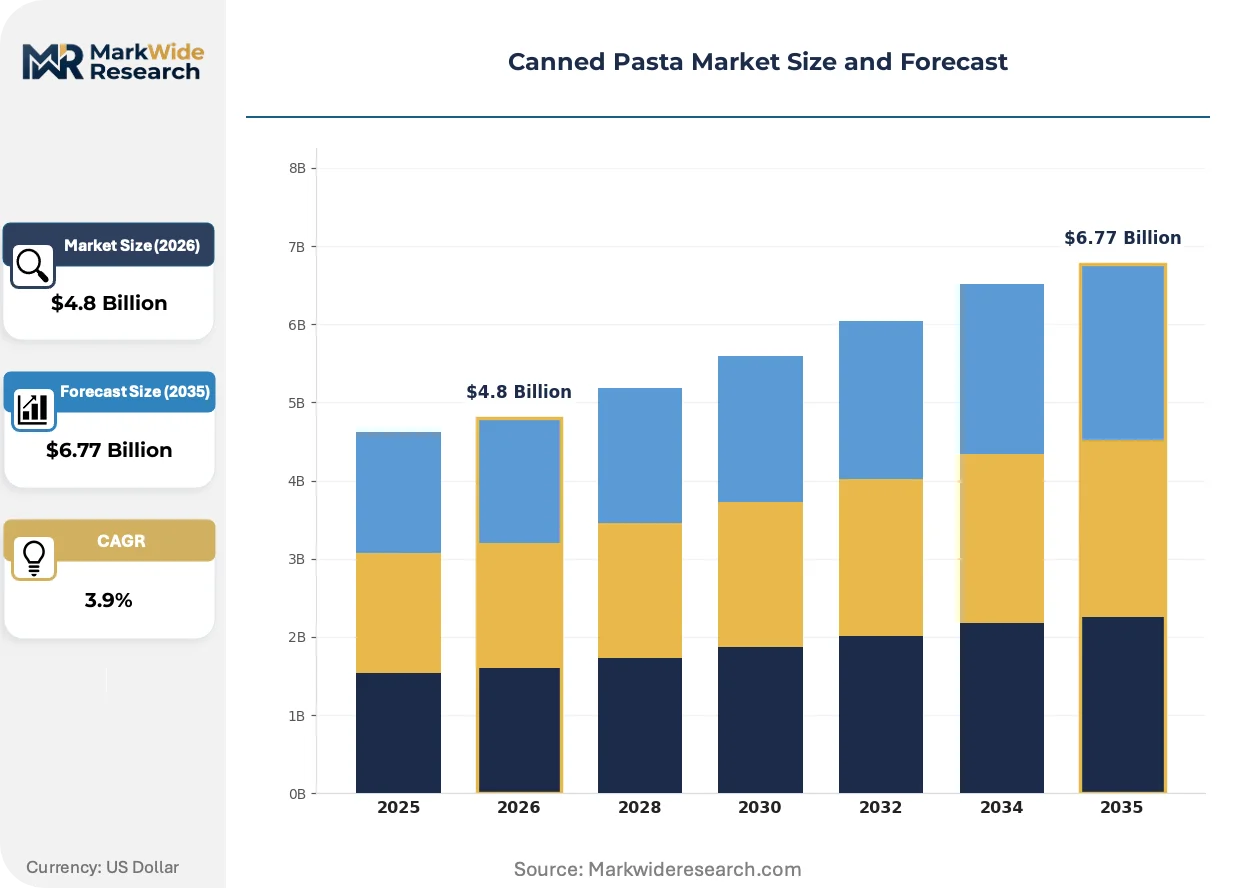
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spaghetti, Ravioli, Macaroni, Lasagna Packaging Type: Metal Cans, Plastic Containers, Pouches, Tetra Packs Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores End User: Households, Restaurants, Cafeterias, Institutions |
| Companies Covered | Conagra Brands, Barilla Group, The Kraft Heinz Company, Unilever PLC, Ebro Foods S.A., Nestlé S.A., General Mills, 8th Avenue Food & Provisions, Campbell Soup Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Pasta Market Strategic Shifts
Retort technology evolution and packaging material science are compressing preparation times while regulatory pressure on sodium and single-use materials forces simultaneous reformulation and format redesign across the value chain.
High-barrier polymer laminates with aluminum oxide coatings are rewriting shelf-stable packaging economics. Young professional households in US metropolitan markets are adopting microwaveable stand-up pouches at triple the rate of metal cans. This substrate shift is compressing canning line utilization rates and forcing capital redeployment toward form-fill-seal equipment.
EFSA's updated sodium reduction targets for processed foods are tightening formulation windows. Manufacturers must now achieve 15% sodium reduction without compromising retort stability or taste profiles. Italian and French retail buyers are enforcing these thresholds through listing requirements, disqualifying non-compliant SKUs from promotional calendars.
Direct-to-pantry subscription models are fragmenting traditional grocery channel dominance. US college students and urban renters are bypassing supermarket pasta aisles for curated ambient meal boxes. This disintermediation is most visible in Northeast corridor cities, where delivery density supports weekly replenishment cycles incompatible with bulk can purchases.
Canned Pasta Market Segmentation
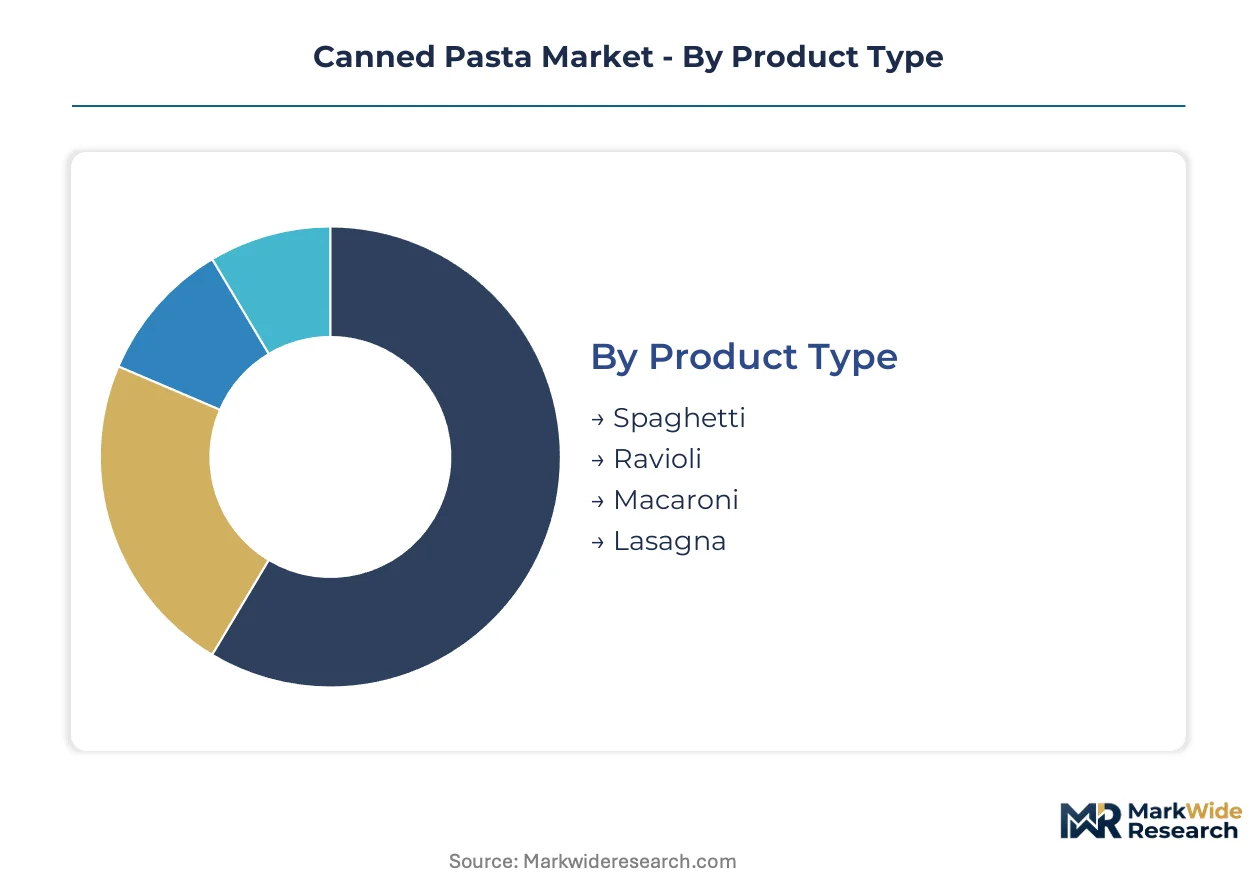
Canned pasta manufacturers must align product architecture with distinct certification burdens and channel access requirements. Each segment category imposes different thermal validation, labeling, and packaging compliance obligations that determine which SKUs reach priority markets.
Product Type:
FDA acidified foods regulations and EFSA low-acid canned food directives apply differentially based on sauce pH and filling density, with meat-inclusive variants triggering stricter scheduled process filings than plain tomato preparations.
- Spaghetti:Long-cut durum wheat noodles in smooth tomato or meat sauce represent the baseline format for retail shelf placement. United States households in the Northeast corridor sustain the largest volume concentration, though sodium reduction mandates are forcing reformulation of legacy recipes to maintain distribution.
- Ravioli:Stuffed pasta pockets with cheese or meat fillings require more complex retort validation due to filling density and center-of-mass thermal penetration challenges. Italian retail buyers enforce EFSA allergen disclosure standards that disqualify non-compliant imports from promotional calendars.
- Macaroni:Curved elbow shapes in cheese sauce dominate K-12 cafeteria procurement for portion control compatibility. BIS certification requirements in India add compliance layers for brands targeting emerging middle-class demand.
- Lasagna:Layered pasta sheets with interleaved sauce and cheese occupy premium shelf positions in European supermarkets. Japan's single-occupant households show limited adoption due to format size mismatch with solo-dweller consumption patterns.
Spaghetti sits at the top of the volume ranking, with macaroni climbing the fastest as microwaveable pouch formats reshape household preparation habits.
Packaging Type:
Cost tier stratification separates institutional durability requirements from convenience-seeking urban household preferences, with capital deployment shifting from canning lines toward form-fill-seal equipment.
- Metal Cans:Tinplate cylinders with double-seamed lids dominate foodservice and institutional procurement for crush resistance and stackability. Three North American suppliers control most food-grade tinplate capacity, creating procurement bottlenecks during seasonal demand spikes.
- Plastic Containers:Polypropylene tubs with peelable lidding film capture margin expansion in premium-positioned supermarket lines. EU Green Deal packaging mandates accelerate innovation in recyclable barrier technologies for this substrate.
- Pouches:High-barrier polymer laminates with steam-venting technology enable sub-90-second microwave preparation. Young professional households in US metropolitan markets are adopting this format at triple the rate of metal cans.
- Tetra Packs:Aseptic carton systems with aluminum composite barriers occupy niche ambient meal segments in European convenience channels. EFSA nutritional disclosure standards apply uniformly across this format.
Metal cans retain the highest shipment volumes, though pouches are gaining share fastest as urban renters bypass bulk can purchases for single-serve convenience.
Distribution Channel:
Customer type concentration determines fulfillment infrastructure requirements, with direct-to-pantry subscription models fragmenting traditional grocery channel dominance.
- Supermarkets:Full-format grocery retailers with ambient aisle placement remain the primary volume outlet for family-size multi-packs. Retail buyer consolidation in France and Italy enforces sodium threshold compliance through listing requirements.
- Convenience Stores:Small-footprint urban retailers prioritize grab-and-go single-serve formats with immediate consumption positioning. Northeast US corridor cities show highest penetration of microwaveable pouch SKUs in this channel.
- Online Retailers:E-commerce platforms with ambient fulfillment centers enable curated meal box subscriptions bypassing traditional pasta aisles. Weekly replenishment cycles in dense metropolitan areas support this disintermediation.
- Specialty Stores:Ethnic grocers and gourmet food retailers stock imported Italian and Japanese variants with premium positioning. BIS import compliance costs are falling as domestic Indian co-manufacturing scales.
Supermarkets command the largest revenue pool, with online retailers expanding most quickly as college students and young professionals adopt subscription replenishment.
End User:
Application maturity separates entrenched pantry-staple consumption from emerging convenience-seeking segments, with institutional operators driving standardization requirements.
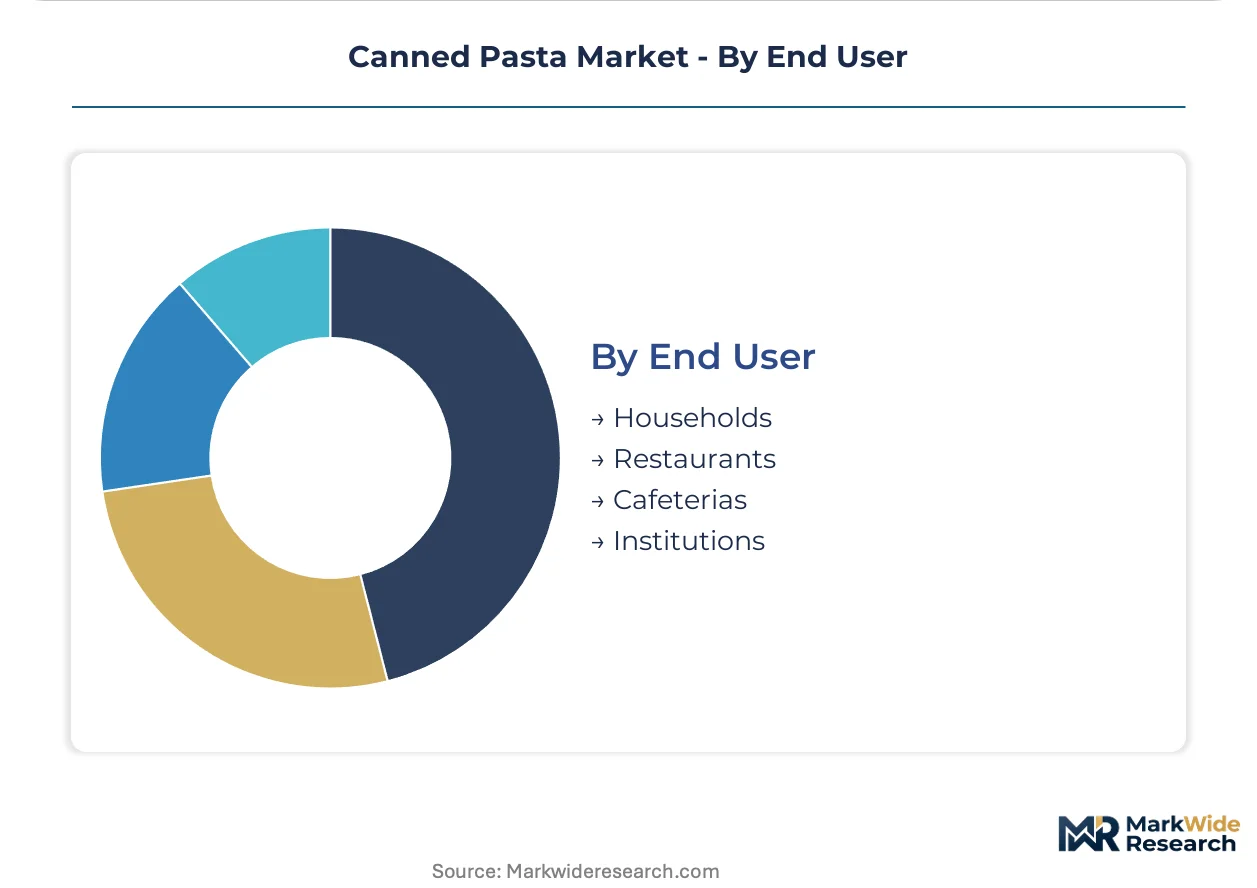
- Households:Residential consumers purchasing for at-home meal preparation span family-format and single-serve needs. Japan's aging household structure sustains demand for single-serve ambient meals with extended shelf stability.
- Restaurants:Foodservice operators use canned pasta as back-of-house ingredient or emergency preparedness inventory. Portion control standardization is less critical here than in institutional settings.
- Cafeterias:K-12 and corporate dining facilities require standardized 4-6 oz serving sizes to reduce plate waste and simplify inventory management. FDA Food Safety Modernization Act lot-tracking mandates apply uniformly.
- Institutions:Healthcare and military procurement channels prioritize durability and extended shelf life over texture quality. Metal can formats dominate this segment for supply chain resilience.
Households generate the highest absolute demand, with cafeterias climbing fastest as institutional operators seek waste-reduction solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate toward jurisdictions with streamlined thermal-process validation protocols and lower compliance-cost burdens for acidified and low-acid canned foods.
United States
College and young professional households in the Northeast corridor drive pouch-format adoption at triple the rate of metal cans. FDA acidified foods regulations mandate scheduled process filings that favor established retort operators with validated thermal processes. Chicago and Pittsburgh industrial clusters concentrate canning line capacity for institutional procurement channels.
Italy
Entrenched pantry-staple consumption sustains spaghetti and ravioli demand across multi-generational households. EFSA oversight through the EU Food Information to Consumers Regulation enforces allergen labeling and nutritional disclosure standards. Emilia-Romagna's food processing belt anchors premium lasagna production for European supermarket placement.
Japan
Single-occupant dwellings exceeding 38% of total households generate sustained demand for single-serve ambient meals with extended shelf stability. METI standards govern retort pouch safety and microwave compatibility labeling. Kanto region manufacturing facilities specialize in compact-format packaging for aging urban demographics.
India
Emerging middle-class demand for shelf-stable Western meal formats remains underpenetrated relative to population scale. BIS certification requirements add compliance layers for import brands though domestic co-manufacturing is scaling rapidly. Maharashtra and Gujarat industrial corridors attract contract manufacturing investment for regional brand production.
Germany
EU Green Deal packaging mandates accelerate innovation in recyclable paper-based barriers and aluminum-free can linings. REACH compliance frameworks govern coating chemistry for food-contact materials. Bavaria's packaging technology cluster develops high-barrier polymer laminates for microwaveable stand-up pouch formats.
Canned Pasta Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated scale dominating retail shelf placement while fragmented regional players capture ethnic and private-label niches. Three archetypes define competitive positioning: diversified FMCG conglomerates with cross-category retort expertise, pasta-centric specialists with heritage brand equity, and private-label co-manufacturers serving retail banners. Capacity expansion and format innovation toward microwaveable substrates represent the dominant competitive moves.
Among diversified conglomerates, Nestlé S.A. and Unilever PLC occupy positions anchored by European retail distribution depth, while Conagra Brands exemplifies North American scale across multiple shelf-stable categories. The Kraft Heinz Company sits within the value-tier competitive vector with concentrated convenience-channel presence. These entities represent archetype extremes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Conagra Brands |
| Barilla Group |
| The Kraft Heinz Company |
| Unilever PLC |
| Ebro Foods S.A. |
| Nestlé S.A. |
| General Mills |
| 8th Avenue Food & Provisions |
| Campbell Soup Company |
| Others |
Value Chain & Pricing Dynamics
Durum wheat futures volatility cascades through semolina procurement contracts into three-tier pricing structure across premium, standard, and economy levels, with FDA acidified foods compliance costs layering additional margin pressure on smaller retort operators lacking thermal validation scale.
Pricing Analysis
Retailer markup compression in US Northeast corridor supermarkets is forcing manufacturers toward direct-to-pantry subscription models that bypass traditional distributor margin layers. Price differentiation separates heritage Italian imports with EFSA allergen certification from private-label economy tiers and pouch-format convenience premiums. Pricing pressure stems from wheat input cost swings tied to Black Sea supply disruptions, with college and young professional households showing highest price sensitivity while institutional healthcare channels absorb cost pass-through.
Supply Chain Analysis
FDA scheduled process filings and EFSA low-acid canned food directives act as qualification gates that concentrate volume among established retort operators with validated thermal processes. Manufacturing capacity clusters in the United States, Italy, and Japan, with tinplate can sourcing drawing from three North American suppliers controlling most food-grade capacity. Single-source vulnerability in metal can procurement creates seasonal bottlenecks during back-to-school demand spikes. Distribution runs through supermarket ambient aisles, though online retailers and convenience channels are capturing incremental share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA Food Safety Modernization Act lot-tracking mandates and EFSA sodium reduction targets continuously reshape competitive access, with compliance investment itself becoming a demand driver as non-compliant SKUs face delisting.
For Market Incumbents: Hedge against fresh refrigerated pasta substitution by accelerating microwaveable pouch format deployment and securing backward integration into high-barrier polymer laminate supply. Conagra Brands and Nestlé S.A. should prioritize thermal validation talent retention as aging technician scarcity constrains new facility commissioning. Channel control through direct-to-pantry subscription infrastructure offers defensive moat against retail buyer consolidation.
For New Entrants and Emerging Players: Single-occupant urban households in India's Maharashtra and Gujarat corridors represent the most penetrable buyer archetype, with BIS certification costs falling as domestic co-manufacturing scales. White-space exists in premium-positioned lasagna formats for European export and K-12 portion-control SKUs for US institutional procurement. A co-manufacturing partnership with established retort operators offers fastest go-to-market path without capital-intensive thermal validation investment.
For Investors and Strategic Acquirers: Asymmetric upside sits with private-label co-manufacturers serving retail banners, as branded volume concentrates and supermarket buyers seek supply diversification. Long-term viability favors operators with cross-category retort expertise and format flexibility toward aluminum-free can linings and recyclable paper-based barriers. Watch EU Green Deal packaging mandate enforcement timelines as inflection indicator for capital redeployment toward sustainable substrate innovation.
| Strategic Initiative | Industry Significance |
|---|---|
| Microwaveable Pouch Format Expansion | Captures young professional households in US metropolitan markets at triple metal can adoption rates. |
| Backward Integration into Polymer Supply | Secures high-barrier laminate access as EU Green Deal restrictions reshape packaging economics. |
| Domestic Co-Manufacturing in India | Reduces BIS import compliance costs for emerging middle-class Western meal format demand. |
| Sodium Reduction Reformulation | Maintains EFSA-compliant retail placement as Italian and French buyers enforce listing thresholds. |
| Direct-to-Pantry Subscription Launch | Bypasses supermarket pasta aisle consolidation through weekly replenishment in dense urban corridors. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with retort process engineers, supermarket category buyers, foodservice procurement directors, and regulatory compliance officers with secondary validation from FDA scheduled process filings, EFSA nutritional disclosure databases, BIS certification registries, and customs trade records. Bottom-up SKU-level volume aggregation triangulated against top-down macroeconomic demand indicators across the analysis window.
Historical reference periods anchored the projection horizon through trend extrapolation and driver elasticity modeling. Segmentation dimensions included product type, packaging format, distribution channel, and end-user application with regional regulatory cluster overlays. CAGRs derived from normalized growth rate distributions across modeled scenarios, with wheat futures volatility and retort capacity utilization serving as industry-specific forecast inputs.
Underlying measurement precision varies by segment; metal can institutional procurement carries tighter precision than emerging pouch format adoption curves. Forecasts reflect documented assumptions about regulatory enforcement timelines and substrate substitution elasticity. A model refresh is warranted upon material change in FDA sodium reduction mandate implementation or EU single-use plastic restriction phase-out schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Global Aseptic Packaging in Food Market
Packaged Foods
US Packaged Salads Market
Packaged Foods
Prepared Flour Mixes Market
Packaged Foods
Carbon Labeled Packaged Meal Market
Packaged Foods
Packaged Burgers Market
Packaged Foods
Peanut Butter Market
Packaged Foods
Pre-Packaged Sandwich Market
Packaged Foods
Chewing Gum Market
Packaged Foods
Iran Breakfast Cereals Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Dried Honey Market
Packaged Foods
Instant Soup Market
Packaged Foods
Freekeh Market
Packaged Foods
Cereal Flakes Market
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
Europe Noodles and Pasta Market