
 Sweet and Savory Spread Market | 2026-2036
Sweet and Savory Spread Market Size, Share, and Industry Trends Forecast 2026-2036
Sweet and Savory Spread Market Outlook
Single-serve sachet and portion-cup bundling is recalibrating how food-service buyers procure spreads, shifting volume from bulk tubs to calibrated single-use formats that reduce waste and simplify inventory. The J.M. Smucker Company leverages its institutional channel strength to dominate breakfast-syrup and portion-pack placements across North American hotel chains. Ferrero Group anchors its premium positioning through controlled distribution of Nutella in travel-retail and hospitality mini-packs. Unilever PLC extends its spread portfolio into plant-based variants, competing for shelf space against dairy-based incumbents in European retail.
Sweet and savory spreads comprise shelf-stable, semi-viscous food preparations—typically 20–70 percent sugar or fat content, pH-adjusted for ambient stability, and processed through batch pasteurization or aseptic filling—designed for direct consumption on bread or as recipe inputs in commercial kitchens. Jams and honey retain the largest volume share within product type, though nut butters generate disproportionate margin growth as protein-positioned alternatives displace conventional breakfast spreads. Food manufacturers represent the fastest-expanding end-user segment, integrating spreads into bakery fillings, ice-cream variegates, and ready-meal sauces that demand consistent viscosity and microbiological stability.
FDA nutritional labeling rules and EFSA health-claim assessments constrain permissible front-of-pack messaging, forcing reformulation toward reduced-sugar profiles that meet dual-jurisdiction compliance thresholds. REACH and EU Packaging and Packaging Waste Regulation obligations on recyclability are accelerating migration from multi-layer plastic tubs to mono-material or glass alternatives across export-oriented production lines. Stakeholders must monitor evolving front-of-pack warning systems in Latin America and Asia-Pacific, where Chilean octagon labels and proposed Indian nutrition thresholds threaten conventional spread positioning in import channels.
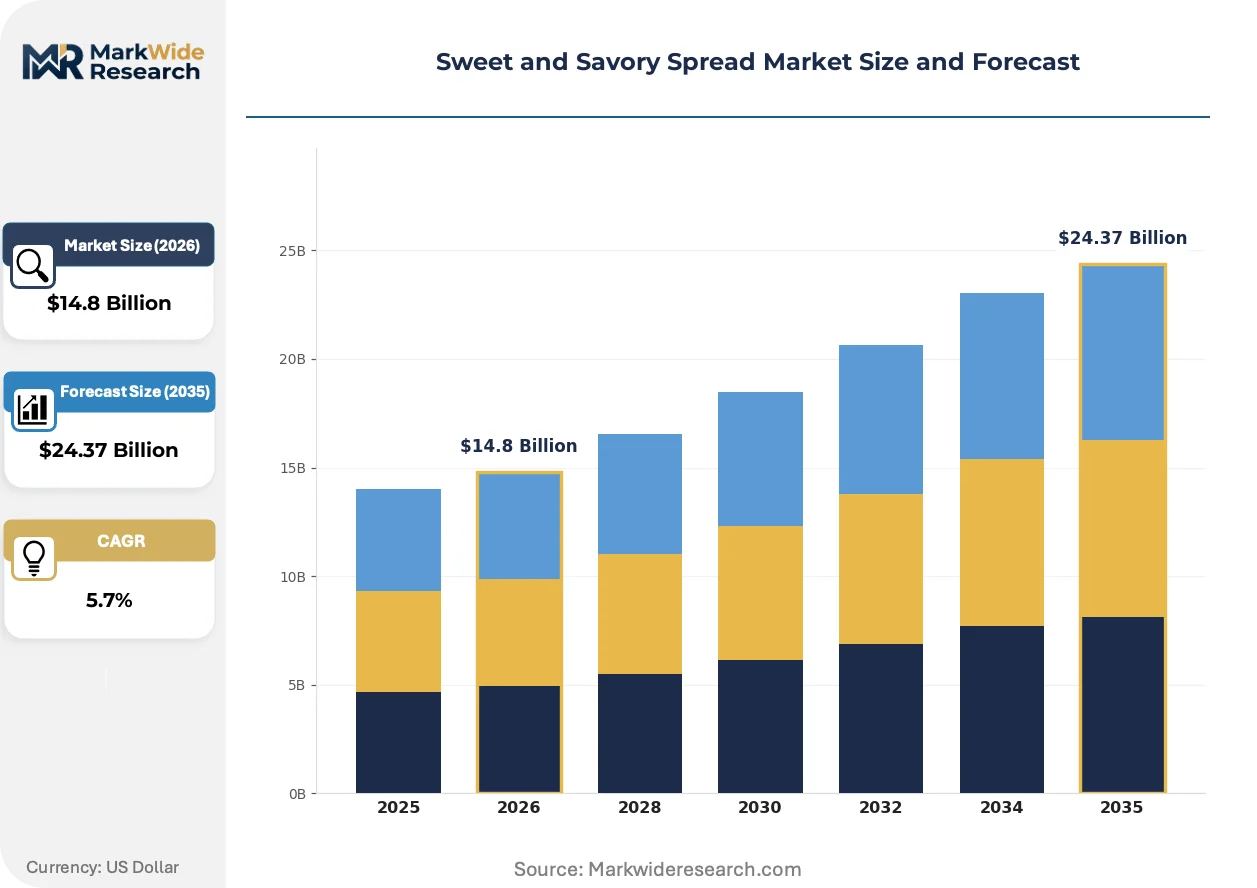
Market Dynamics
Clean-label reformulation under EFSA and FDA guidance is compressing formulation timelines while forcing ingredient substitution at scale, reshaping procurement relationships between spread manufacturers and their specialty ingredient suppliers.
Growth Catalysts
- Portion-control packaging:Food-service buyers in hotel and café chains are consolidating procurement around single-serve sachets and portion cups that reduce waste and simplify inventory management.
- REACH recyclability mandates:EU Packaging and Packaging Waste Regulation obligations are accelerating migration from multi-layer plastic tubs to mono-material or glass alternatives across export-oriented production lines.
- Protein-positioned nut butters:Bakery and ice-cream manufacturers are integrating nut-based spreads as functional ingredients, displacing conventional fillings in premium product formulations.
Market Restraints
- Sugar reduction technical limits:FDA and EFSA dual-jurisdiction compliance thresholds constrain permissible front-of-pack messaging, forcing costly reformulation cycles that degrade sensory profiles.
- Glass supply concentration:Mono-material and glass packaging migration concentrates dependency on Italian and German container manufacturers with limited surge capacity.
- Front-of-pack warning proliferation:Chilean octagon labels and proposed Indian nutrition thresholds threaten conventional spread positioning in key import channels without warning-adapted formulations.
Strategic Opportunities
- Travel-retail hospitality mini-packs:Controlled distribution of premium spreads in airport and hotel channels captures margin compression-resistant segments in Germany and France.
- Plant-based spread variants:EFSA health-claim assessments create regulatory space for dairy-free formulations competing against incumbent dairy-based spreads in European retail.
- Ready-meal sauce integration:Food manufacturers represent underpenetrated demand for spreads as viscosity-stable inputs in commercial sauce and filling applications.
Industry Challenges
- Microbiological stability expertise:Batch pasteurization and aseptic filling competency gaps constrain mid-tier manufacturers attempting clean-label transitions.
- Dual-jurisdiction compliance timelines:Simultaneous FDA nutritional labeling and EFSA health-claim assessments extend product launch cycles and increase regulatory capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweet and Savory Spread Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jams, Honey, Nut Butters, Marmalade End User: Households, Restaurants, Cafés, Food Manufacturers Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesalers Packaging Type: Glass Jars, Plastic Containers, Sachets, Tubs |
| Companies Covered | Mondelez International, Inc., Nestlé S.A., The J.M. Smucker Company, General Mills, Conagra Brands, Inc., The Kraft Heinz Company, Unilever PLC, Hormel Foods Corporation, Ferrero Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweet and Savory Spread Market Strategic Shifts
Aseptic processing technology is compressing shelf-life extension costs while enabling cleaner ingredient decks, fundamentally altering the capital intensity required for ambient-stable spread production.
High-pressure processing is converging with reduced-sugar formulation science to maintain microbiological stability without thermal degradation of flavor compounds. Artisanal spread producers in Germany and France are piloting this combination to preserve volatile aromatic profiles in fruit-based preparations. The technology is converging with clean-label positioning to compress the price premium between conventional and premium spread tiers.
EU Packaging and Packaging Waste Regulation recyclability mandates are forcing material science investments in mono-material barrier films and returnable glass systems. Manufacturers with German and Italian production footprints are absorbing capex increases of 15-25 percent for compliant packaging lines. Export-oriented spread producers are most affected, with smaller regional players exiting cross-border channels rather than absorbing compliance costs.
Buyer consolidation among North American hotel chains is compressing supplier negotiation cycles and unbundling after-sales service from product procurement. Chain procurement officers now demand calibrated single-use formats with embedded inventory tracking, displacing traditional bulk tub relationships with distributors. This pattern is most visible in US and Canadian breakfast-service operations, where three national hotel groups now control majority volume.
Sweet and Savory Spread Market Segmentation
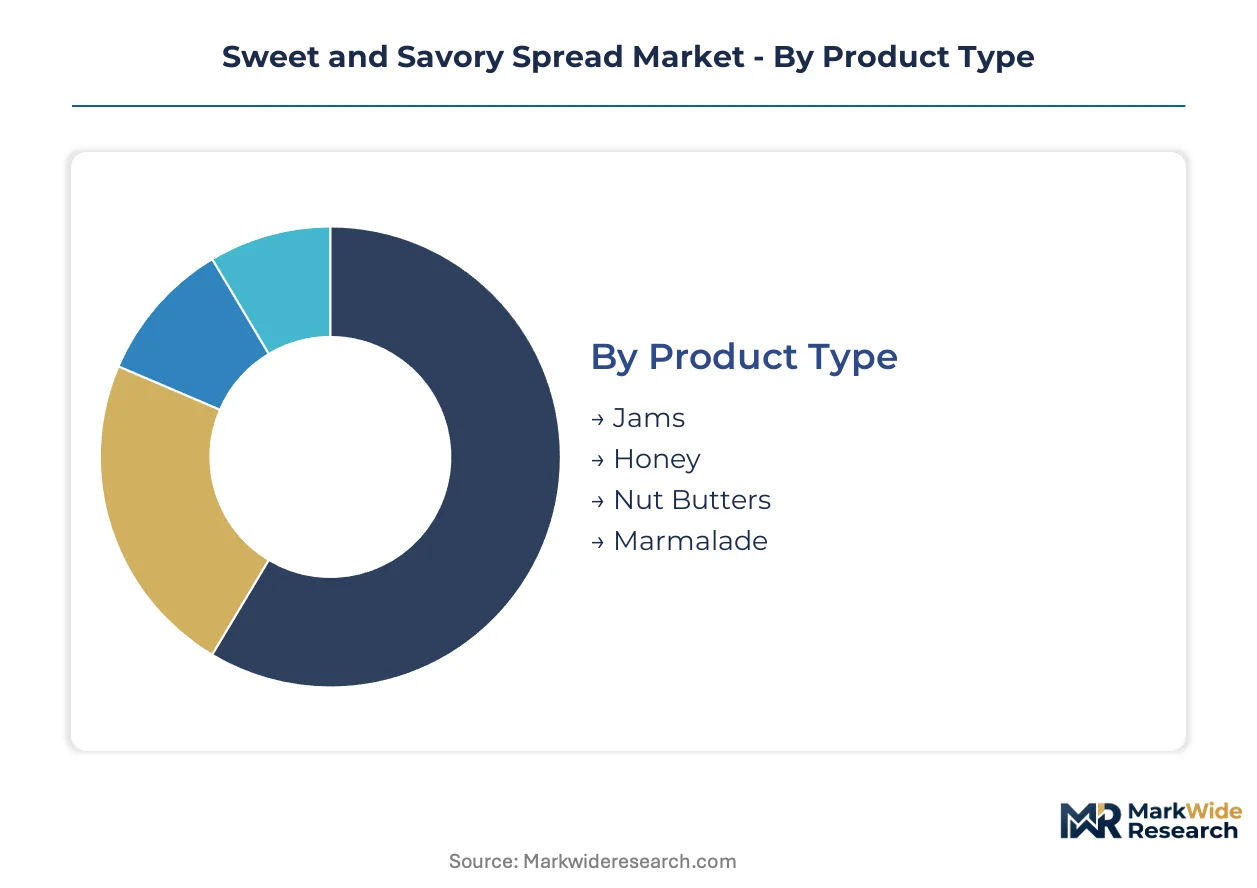
Spread manufacturers calibrate formulation viscosity, sugar content, and packaging formats to match distinct consumption occasions across household breakfast tables and industrial food production. Segmentation discipline separates premium artisanal positioning from commodity volume plays, with channel-specific packaging requirements often dictating margin structure more than ingredient cost.
Product Type:
Customization intensity spans from standardized commodity honey to highly differentiated regional marmalade recipes with protected designations of origin.
- Jams:Fruit-based preparations with 30–60 percent sugar content, pH-adjusted to 3.0–3.5 for ambient stability. German and French breakfast service operators specify lower-sugar profiles under EFSA-influenced procurement guidelines, compressing traditional formulation margins. Most installed capacity flows through Jams. Expansion is steepest in Nut Butters.
- Nut Butters:Protein-positioned spreads with 15–25 percent protein content, processed through dry roasting and hydraulic pressing to preserve lipid integrity. Food manufacturers in bakery and ice-cream applications specify these as functional filling replacements, displacing conventional fat-based spreads in premium product formulations.
- Honey:Shelf-stable invert sugar syrup with enzymatic and floral provenance variations, standardized by moisture content and HMF levels for commercial grading.
- Marmalade:Citrus-based preparation with suspended peel fragments, concentrated in UK and Irish retail channels with protected geographical indication variants commanding shelf price premiums.
Volume leadership sits with traditional fruit preserves. Protein-positioned alternatives are climbing the fastest as ingredient buyers reformulate.
End User:
Application requirements diverge sharply between direct consumption viscosity preferences and industrial specifications for thermal stability and batch consistency.
- Households:Retail purchasers prioritize spreadability at refrigerated temperatures and clean-label ingredient decks with fewer than seven components. German and French consumers demonstrate strongest willingness to pay for organic certification and protected designation of origin status.
- Food Manufacturers:Industrial buyers specify spreads with narrow viscosity ranges for automated depositor compatibility and extended microbiological stability for frozen dough and ice-cream variegate applications. This segment is gaining share fastest as ready-meal and bakery outsourcing accelerates.
- Restaurants:Food-service operators demand calibrated portion-control formats with embedded inventory tracking codes, shifting procurement from bulk tubs to single-serve sachets.
- Cafés:Breakfast-focused chains consolidate procurement through national distributor contracts, prioritizing brand recognition and consistent supply over formulation differentiation.
Household channels absorb the largest absolute volume. Food manufacturer integration represents the steepest expansion trajectory.
Distribution Channel:
Channel economics separate high-frequency replenishment formats from destination purchasing occasions with different margin and working capital requirements.
- Supermarkets:Mass retail placement demands promotional slotting fees and seasonal display investments, with private-label penetration strongest in German and UK grocery multiples. EFSA nutritional labeling compliance costs disproportionately burden smaller brands seeking shelf access.
- Online Retail:Direct-to-consumer channels enable subscription-based recurring revenue with premium positioning, though shipping weight constraints favor smaller format glass jars over bulk tubs. This channel is expanding most quickly as pantry stocking behavior shifts post-pandemic.
- Specialty Stores:Artisanal and protected designation of origin variants command price premiums through curated assortment and staff expertise, concentrated in French and Italian urban centers.
- Wholesalers:Institutional and food-service volume moves through distributor networks with consolidated delivery logistics, compressing supplier margins in exchange for predictable offtake.
Supermarket placements dominate current revenue. Online retail shows the fastest share gain.
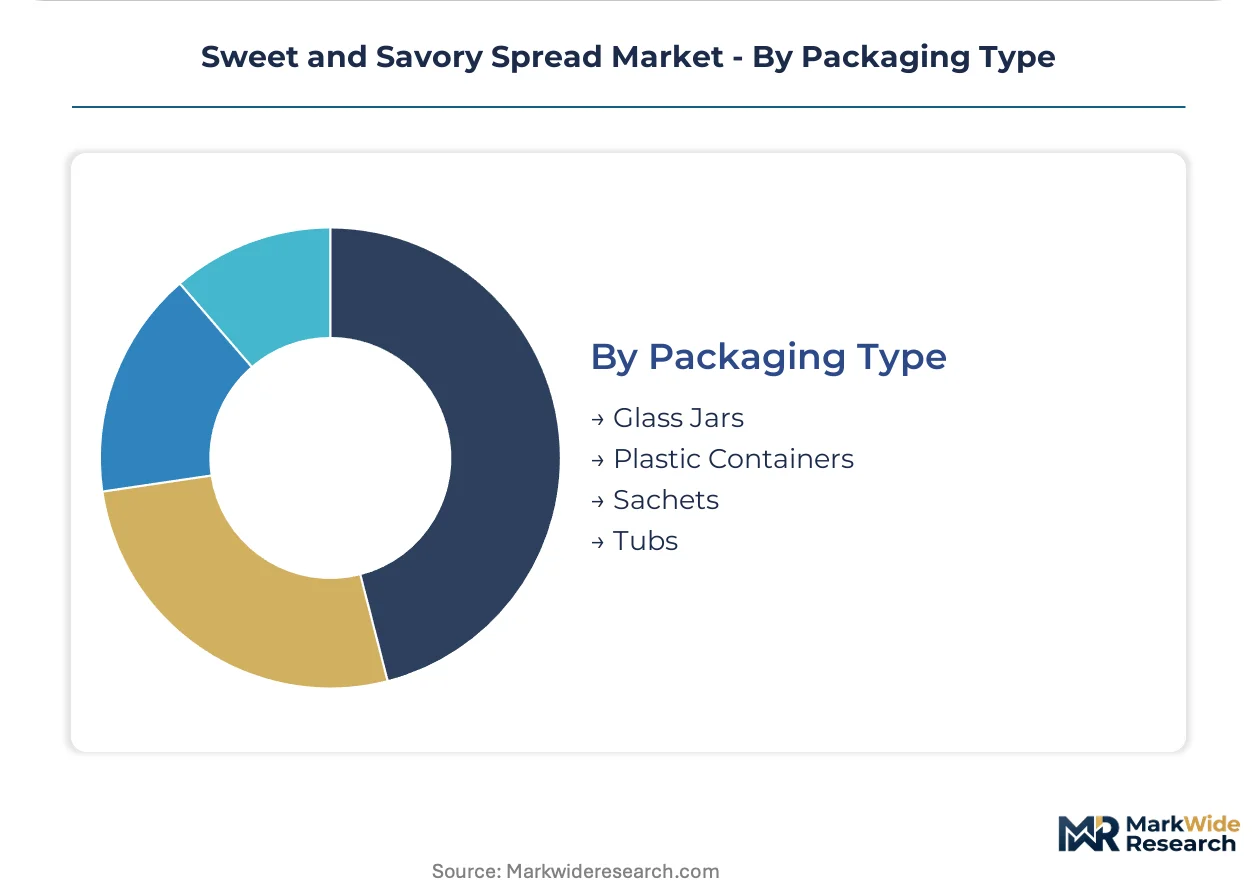
Packaging Type:
Material selection trade-offs between barrier performance, recyclability compliance, and line speed compatibility define procurement decisions across export-oriented production.
- Glass Jars:Inert barrier properties support extended ambient shelf life without flavor scalping, though Italian and German container supply concentration creates surge capacity constraints. REACH and EU Packaging and Packaging Waste Regulation recyclability mandates favor this format despite 15–25 percent packaging line capex increases.
- Sachets:Single-serve flexible formats with multi-layer barrier films are migrating to mono-material constructions under EU regulatory pressure, with portion-control specifications increasingly standardized by North American hotel chain procurement officers.
- Plastic Containers:Polypropylene tubs with in-mold labels offer line speed advantages and lightweight logistics, though multi-layer constructions face recyclability compliance headwinds in export markets.
- Tubs:Bulk institutional formats with resealable lids retain food-service penetration but lose share to calibrated single-serve alternatives in hotel and café channels.
Glass jar capacity represents the largest installed base. Sachet lines are adding capacity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial fruit preservation originated in the Mediterranean basin during the nineteenth century, with industrial-scale production later consolidating in Northern Europe. Contemporary spread manufacturing now distributes across five national clusters where regulatory frameworks and hospitality procurement patterns diverge sharply.
Germany
Artisanal and private-label spreads command premium shelf positioning in German retail, with breakfast service operators in cafés and hotels expanding portion-controlled offerings. EFSA guidance on clean-label reformulation pressures ingredient sourcing decisions across Bavarian and North Rhine-Westphalian production facilities. The Cologne-Düsseldorf corridor hosts concentrated private-label manufacturing capacity serving pan-European retail multiples.
France
Protected designation of origin marmalades and regional fruit preserves sustain price premiums through curated specialty retail channels. EU Packaging and Packaging Waste Regulation obligations accelerate migration from multi-layer plastic tubs to mono-material or glass alternatives across export-oriented production lines in the Île-de-France and Auvergne-Rhône-Alpes regions. Lyon-based cooperatives pilot high-pressure processing for volatile aromatic preservation in premium fruit preparations.
United States
North American hotel chains consolidate procurement around single-serve sachets and portion cups that reduce waste and simplify inventory management. FDA nutritional labeling rules constrain permissible front-of-pack messaging, forcing reformulation toward reduced-sugar profiles. Cincinnati and Chicago anchor institutional channel distribution networks serving consolidated breakfast-service operators across the Midwest and Southeast.
Italy
Glass container supply concentration creates surge capacity constraints for export-oriented spread producers, with Italian manufacturers absorbing capex increases for compliant packaging lines. REACH recyclability mandates favor mono-material barrier films and returnable glass systems across Emilia-Romagna and Lombardy production footprints. Parma-based processors specialize in viscosity-stable preparations for industrial bakery and ice-cream applications.
United Kingdom
Citrus-based marmalade consumption concentrates in UK retail channels, with protected geographical indication variants commanding shelf price premiums. Clean-label reformulation timelines compress as manufacturers simultaneously navigate EFSA health-claim assessments and domestic retailer sustainability requirements. The Midlands and Greater London host blended manufacturing capacity serving both household direct consumption and food-service portion-control segments.
Sweet and Savory Spread Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation sophistication and channel access, with controlled distribution in travel-retail and hospitality mini-packs separating margin-compression-resistant positioning from bulk institutional supply. The vendor base organizes around three strategic archetypes: diversified packaged food conglomerates with institutional channel strength, premium chocolate and confectionery specialists with travel-retail dominance, and plant-based innovation-focused multinationals competing for dairy-alternative shelf space. Dominant competitive moves include portfolio diversification into protein-positioned nut butters and strategic partnerships with North American hotel chain procurement officers for calibrated single-use format standardization.
Within the diversified conglomerate tier, Mondelez International, Inc. and Nestlé S.A. occupy positions spanning commodity through premium spread categories across multiple continental markets. The J.M. Smucker Company exemplifies institutional channel specialization, anchoring breakfast-syrup and portion-pack placements across consolidated North American hospitality networks. Ferrero Group represents the premium-tier archetype through controlled distribution strategies in travel-retail and hospitality mini-packs. Unilever PLC sits within the plant-based innovation vector, extending spread portfolios into dairy-free formulations competing against incumbent dairy-based spreads in European retail channels.
| Leading Market Players |
|---|
| Mondelez International, Inc. |
| Nestlé S.A. |
| The J.M. Smucker Company |
| General Mills |
| Conagra Brands, Inc. |
| The Kraft Heinz Company |
| Unilever PLC |
| Hormel Foods Corporation |
| Ferrero Group |
| Others |
Value Chain & Pricing Dynamics
Artisanal pasteurization specialists in Bavaria and North Rhine-Westphalia command wage premiums that compress margins at premium-tier producers while widening spreads between craft and commodity positioning. Labor-cost differentials across German, Italian, and Eastern European production clusters directly map to three-tier pricing stratification across protected designation of origin, private-label, and bulk institutional segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates protected designation of origin marmalades from private-label fruit preserves and bulk food-service tubs. Price differentiation hinges on organic certification tier and glass-packaging premium versus plastic alternatives. Cost compression in standard-tier spreads is intensifying as REACH compliance capex flows through to unit economics. Food-service buyers in consolidated North American hotel chains exhibit highest price sensitivity, while German specialty retail consumers demonstrate lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Italian and German glass container manufacturers whose surge capacity constraints tighten during seasonal demand peaks. Geographic supply concentration clusters in Germany, France, and Italy for fruit preservation, with hazelnut and almond sourcing drawing from Turkish and Californian growing regions. Raw material dependencies span citrus peel, cane sugar, and mono-material barrier films under EU Packaging and Packaging Waste Regulation transition. Tariff exposure on nut imports from Turkey threatens margin stability at nut-butter specialists. Distribution runs through wholesaler networks for institutional volume and direct retail relationships for premium artisanal tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in sweet and savory spreads rests on clean-label reformulation cost-down curves and premium-tier shift toward protein-positioned nut butters displacing conventional fruit preserves.
For Market Incumbents: Deepen controlled distribution in travel-retail hospitality mini-packs to defend against private-label encroachment in European retail. Anchor backward integration into hazelnut and almond sourcing to offset Turkish tariff exposure and secure lipid integrity for premium nut-butter positioning. Prioritize aseptic processing competency investments to compress clean-label transition timelines ahead of mid-tier competitors. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the most penetrable route for artisanal producers seeking bypass of supermarket slotting-fee barriers. Target food-manufacturer integration for spreads as viscosity-stable inputs in bakery and ice-cream applications, where automated depositor compatibility specifications create technical moats. Lead with high-pressure processing pilot credentials to capture premium fruit-preparation contracts from Lyon-based cooperatives. For Investors and Strategic Acquirers: Diversified packaged food conglomerates are the most active acquirer in this space, seeking protein-positioned spread portfolios to offset commodity jam margin compression. Long-term viability favors targets with installed aseptic capacity and EFSA health-claim assessment track records. Watch for inflection when North American hotel chain procurement consolidation accelerates single-serve format standardization, signaling channel-capture winners.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | EFSA and FDA dual-jurisdiction compliance creates first-mover advantage in reduced-sugar positioning. |
| Mono-Material Packaging Migration | EU Packaging and Packaging Waste Regulation mandates absorb 15-25 percent capex increases for compliant lines. |
| Portion-Control Format Standardization | Consolidated North American hotel chain procurement embeds inventory tracking in calibrated single-serve specifications. |
| High-Pressure Processing Pilot Expansion | Lyon-based cooperatives preserve volatile aromatic profiles without thermal degradation in premium fruit preparations. |
| Plant-Based Spread Line Extension | Unilever PLC and specialty entrants compete for dairy-alternative shelf space against incumbent dairy-based spreads. |
Study Parameters
Multiple input streams — regulatory filing analysis, trade customs data, and hospitality procurement database tracking — were reconciled through bottom-up and top-down triangulation. Primary interviews with spread manufacturing executives, specialty ingredient procurement leads, food-service distributor category managers, and EFSA regulatory affairs specialists were cross-validated against secondary sources including FDA nutritional labeling guidance documents, EFSA health-claim assessment registers, EU Packaging and Packaging Waste Regulation compliance disclosures, and Nielsen retail audit data.
Data-stream reconciliation anchored volume and value outputs across product type, end-user application, distribution channel, and packaging format dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic consumption drivers. Industry-specific forecast inputs included clean-label reformulation adoption curves, aseptic processing capacity expansion timelines, and REACH recyclability mandate compliance schedules.
The model assumes a particular technology adoption path; alternative pathways for high-pressure processing scale-up would alter the outlook for premium-tier spread margin compression. Forecasts reflect assumptions around EFSA health-claim assessment throughput, Turkish hazelnut supply stability, and North American hotel chain procurement consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Mayonnaise Sauce Market
Condiments & Sauces
Vegan Sauces, Dressings and Spreads Market
Condiments & Sauces
Asia-Pacific Condiments Market
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
Hot Sauce Powder Market
Condiments & Sauces
Latin America Pasta Sauce Market
Condiments & Sauces
Mayonnaise Market
Condiments & Sauces
Vinegar and Vinaigrette Market
Condiments & Sauces
Sauce Market
Condiments & Sauces
Sun-Dried Tomato Umami Concentrate Systems Market
Condiments & Sauces
Fat Free Salad Dressings Market
Condiments & Sauces
United States Pasta Sauce Market
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Vegan Sauces Market
Condiments & Sauces
Sandwich Spread Market
Condiments & Sauces
Chocolate Syrup Market