
 Europe Hot Sauce Market | 2026-2036
Europe Hot Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hot Sauce Market Intelligence
The European hot sauce category is decoupling along a sharp premium-commodity fault line, with small-batch craft producers commanding price multiples over mass-market table sauces while both segments expand volume. The Kraft Heinz Company leverages its continental distribution network to sustain supermarket dominance across Northern Europe. McIlhenny Company anchors its position through brand heritage and controlled scarcity of aged pepper mash stocks. East Coast Chilli Company competes on heat-forward formulations that occupy the super-premium niche in British and Scandinavian markets.
Europe hot sauce comprises chili pepper-based condiments manufactured through fermentation, vinegar preservation, or fresh blending, with Scoville heat units ranging from mild piquillo bases to extreme Carolina Reaper extracts, serving primarily as flavor enhancers for prepared foods and home cooking. Pepper sauce and sriracha variants lead value growth as restaurants and retail buyers shift toward recognizable global formats with transparent ingredient decks. Squeeze bottles dominate foodservice throughput while glass jars sustain premium positioning in specialty retail channels.
EFSA capsaicin threshold guidelines and EU Regulation 1169/2011 food information standards shape formulation choices and front-of-pack labeling obligations across member states. REACH compliance for imported chili oleoresins and national organic certification schemes in France and Germany create layered compliance barriers that favor established suppliers with technical documentation capacity. Stakeholders must monitor evolving Novel Food designations for emerging pepper cultivars and prepare for consolidated retailer demands on clean-label verification.
Market Dynamics
The European hot sauce category is bifurcating along a craft-commodity divide where EFSA capsaicin disclosure mandates and organic certification schemes in France and Germany are accelerating formulation transparency while squeezing out undifferentiated private-label suppliers.
Growth Catalysts
- Iberian consumption density:Spain and Portugal maintain per capita chili condiment usage rates that exceed Northern European averages by substantial margins, anchoring volume demand for fermented pepper mash products.
- EFSA labeling clarity:Standardized Scoville heat unit declarations under EU food information standards are reducing consumer confusion and expanding trial rates among heat-averse demographics.
- Fermentation infrastructure:Controlled aging in oak barrels and pH-monitored anaerobic systems is enabling flavor complexity that commands shelf space in British and Scandinavian specialty retail.
Market Restraints
- Capsaicin import volatility:REACH compliance documentation for chili oleoresins sourced from India and Mexico creates batch-to-batch cost unpredictability for small-scale producers.
- Glass packaging concentration:Premium positioning dependence on amber and cobalt glass jars ties margins to energy-intensive manufacturing clusters in Italy and Poland.
- Vinegar substitution pressure:Citrus-based and yogurt-based hot condiments in Mediterranean foodservice are capturing occasions traditionally served by vinegar-preserved pepper sauces.
Strategic Opportunities
- Eastern European retail whitespace:Poland, Romania, and Hungary show underdeveloped craft hot sauce penetration relative to Western European saturation, with local chili cultivation reducing import dependency.
- Clean-label convergence:EU organic certification and France's AB label are creating dual-badge products that access both supermarket mainstream and specialty channels simultaneously.
- Direct-to-restaurant supply:Bypassing consolidated retail distributors through refrigerated logistics partnerships with independent pizzeria and taco chains in the United Kingdom.
Industry Challenges
- Novel Food designation uncertainty:Emerging pepper cultivars including Pepper X derivatives face pending EFSA safety assessments that freeze formulation pipelines for 18-24 month windows.
- Heat measurement standardization:Inconsistent HPLC testing protocols across German, French, and British laboratories create label claim disputes and retailer rejection risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hot Sauce Market |
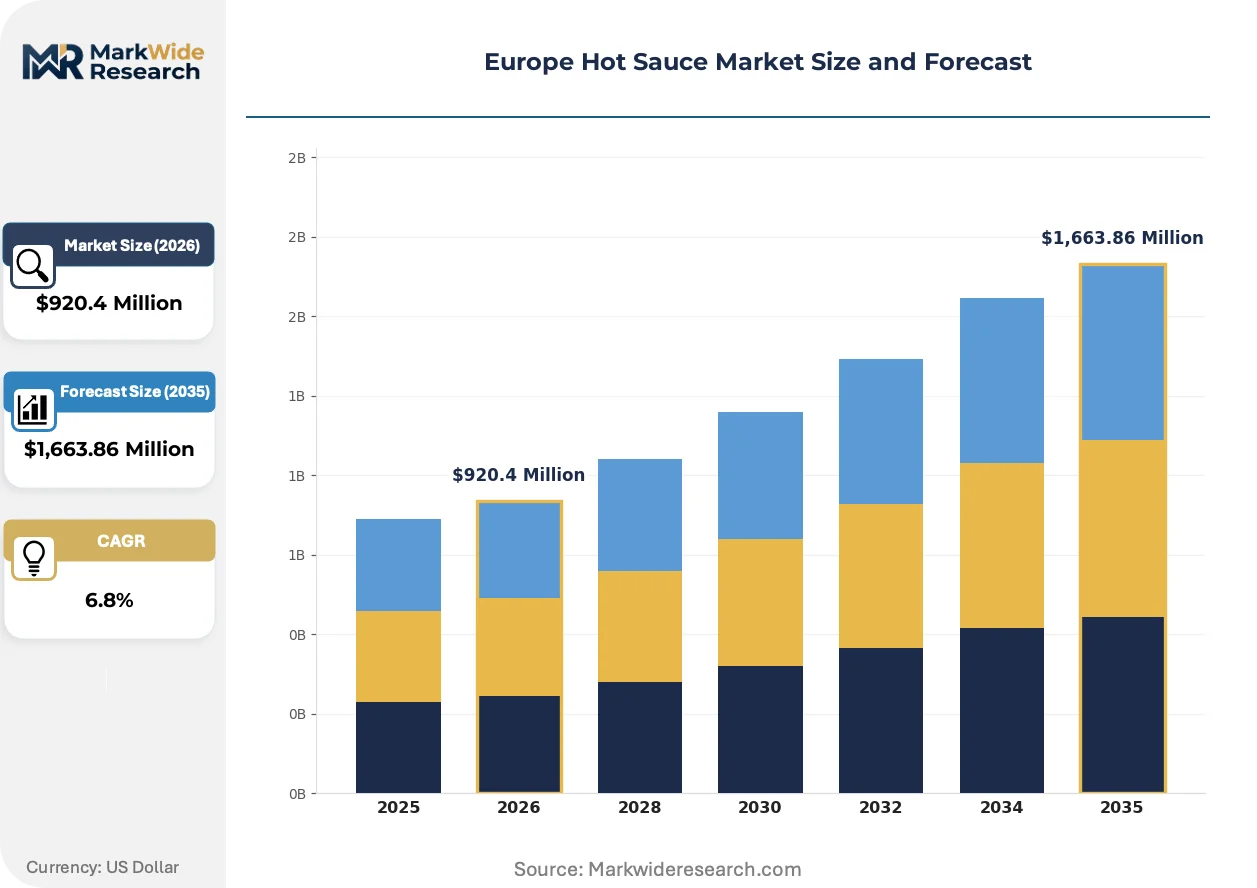
| Market Size in 2026 | $920.4 Million |
| Market Size in 2035 | $1,663.86 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chili Sauce, Pepper Sauce, Spicy Ketchup, Sriracha Packaging Type: Squeeze Bottles, Jars, Pouches, Cans End User: Restaurants, Retail, Food Manufacturers, Caterers Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesalers |
| Companies Covered | The Kraft Heinz Company, Unilever PLC, McIlhenny Company, East Coast Chilli Company, Doctor Salsas, Chilli No. 5, Crazy Bastard Sauce, Daddy Cool’s Chilli Sauce, Pip’s Hot Sauce, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hot Sauce Market Strategic Shifts & Innovations
Fermentation science and precision agriculture are converging to reshape how pepper mash is produced, aged, and positioned across European retail and foodservice channels.
Controlled-environment fermentation is unifying traditional barrel aging with real-time pH and temperature monitoring. British craft producers are retrofitting Scotch whisky casks with IoT sensors to standardize microbial activity. This convergence is compressing batch variation and enabling vintage-dated releases that previously required decades of tacit knowledge.
EFSA's evolving Novel Food guidance for high-pungency extracts is forcing reformulation roadmaps across the industry. The regulatory friction most acutely affects super-premium producers in Scandinavia who rely on Carolina Reaper and Trinidad Scorpion concentrates. German laboratories are expanding HPLC certification capacity to preempt compliance bottlenecks.
Restaurant procurement teams are consolidating supplier relationships around transparent ingredient decks and single-origin pepper provenance. Independent pizzerias in Milan and Barcelona are displacing multi-source distributors with direct contracts to Andalusian and Calabrian growers. This disintermediation is most visible in Mediterranean urban markets where menu transparency commands diner loyalty.
Europe Hot Sauce Market Segmentation
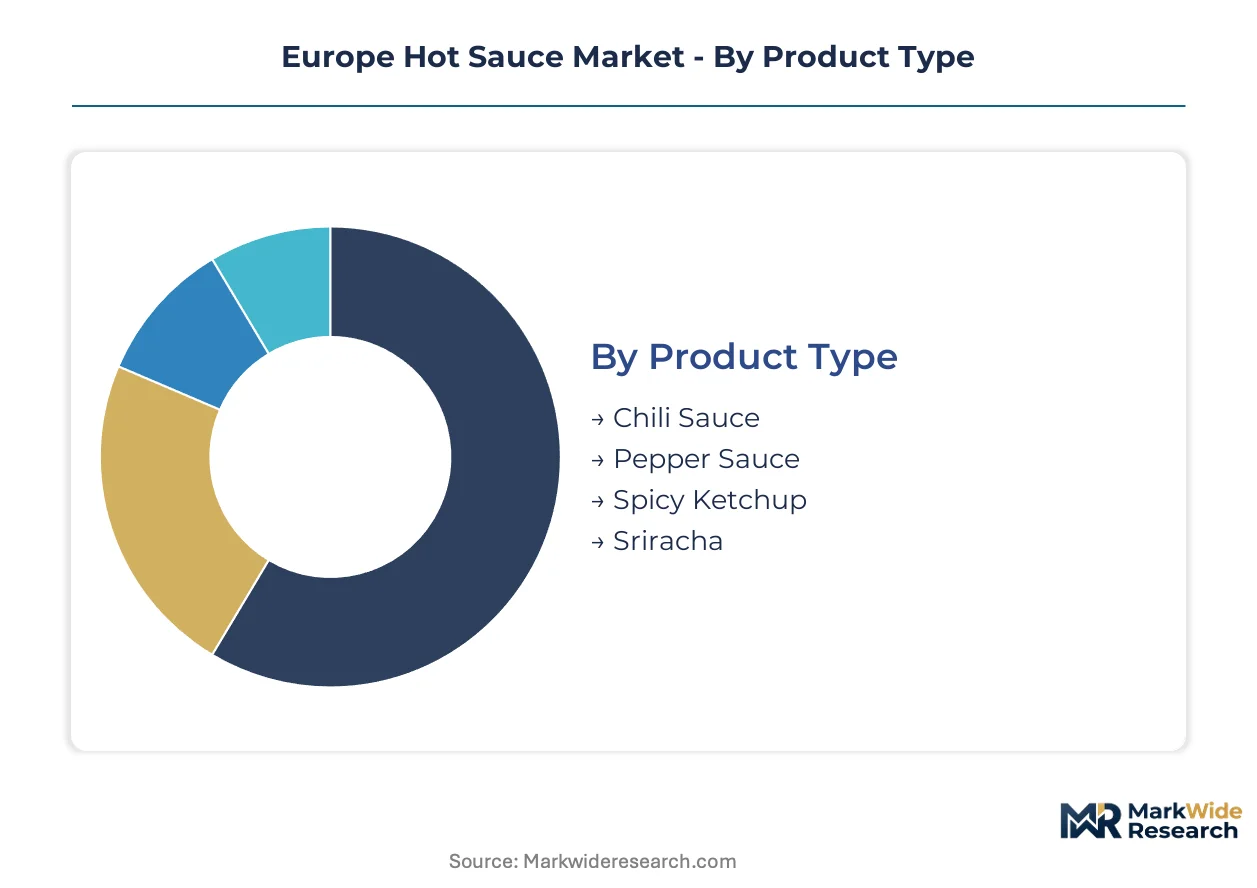
Hot sauce segmentation across Europe reflects divergent consumption rituals and channel economics. Product formulation, packaging format, and procurement pathway each dictate margin structure and regulatory exposure differently across Mediterranean and Northern European markets.
Product Type:
Formulation chemistry and pepper provenance define the competitive terrain, with fermentation methods and vinegar bases creating distinct shelf-life and labeling obligations under EFSA guidelines.
- Pepper Sauce:Aged pepper mash preserved in distilled vinegar delivers the category's most concentrated Scoville profiles. British and Scandinavian retail buyers favor this format for its transparent ingredient decks and controlled heat consistency. EFSA capsaicin disclosure mandates favor established producers with HPLC testing infrastructure.
- Sriracha:Fermented chili-garlic emulsions with elevated sugar content occupy the fastest-expanding niche in European foodservice. German and Dutch restaurants are displacing traditional pepper sauces with this format for burger and pizza applications, though REACH compliance for imported chili paste creates documentation burdens for smaller suppliers.
- Chili Sauce:Tomato-based formulations with moderate heat levels dominate Iberian household penetration.
- Spicy Ketchup:Mass-market condiment blending familiar tomato sweetness with chili extract.
Pepper Sauce leads on scale; Sriracha leads on momentum.
Packaging Type:
Material choice locks in channel access and margin structure, with glass concentration in premium retail and plastic dominance in high-throughput foodservice.
- Squeeze Bottles:High-density polyethylene and PET formats enable portion-controlled dispensing for restaurant line cooks. United Kingdom pizzeria chains and Spanish tapas bars specify this format for speed-of-service requirements, though Italian packaging clusters face energy cost volatility.
- Jars:Amber and cobalt glass containers sustain specialty retail positioning across French and German organic channels. AB label and EU organic certification visibility favors this format, with Calabrian and Andalusian producers leveraging provenance storytelling on ceramic-labeled vessels.
- Pouches:Flexible film formats reduce shipping cube for food manufacturers integrating hot sauce into ready-meal production.
- Cans:Metal packaging preserves ultra-high Scoville extracts for industrial food processing applications.
Squeeze Bottles capture the highest volume throughput; Jars command the steepest price premiums.
End User:
Procurement sophistication varies sharply across buyer categories, with consolidated retail demanding clean-label verification while fragmented foodservice prioritizes cost-per-portion.
- Restaurants:Independent pizzerias and taco concepts in Milan and Barcelona are consolidating direct supplier relationships. Menu transparency requirements favor single-origin pepper provenance and vintage-dated fermentation batches.
- Retail:German and French supermarket chains are expanding shelf space for craft and artisanal varieties. Dual-badge organic products access both mainstream and specialty channels simultaneously.
- Food Manufacturers:Industrial buyers integrate hot sauce into ready-meal and snack seasoning formulations.
- Caterers:Event and institutional foodservice demands bulk formats with extended ambient stability.
Restaurants drive the steepest expansion trajectory; Retail anchors absolute revenue concentration.
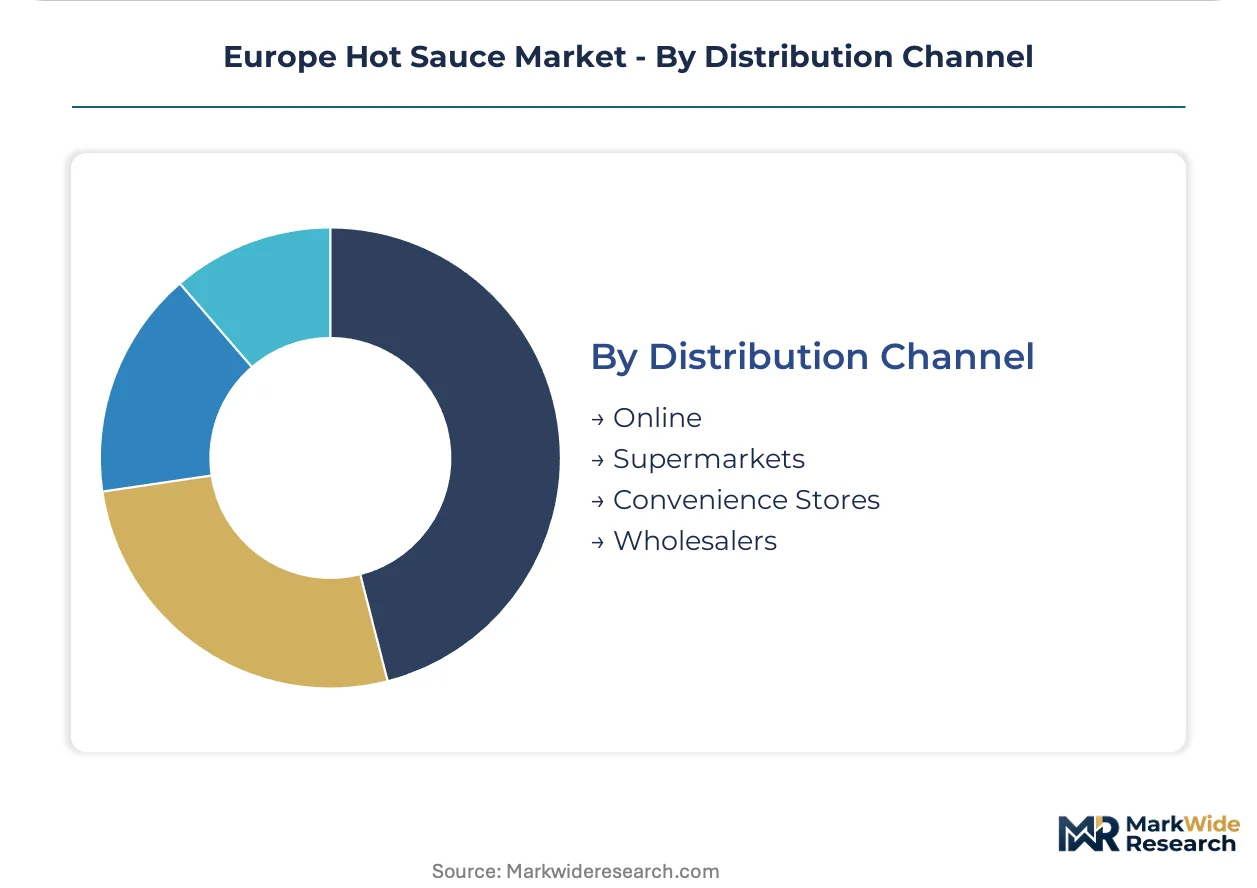
Distribution Channel:
Channel selection determines margin capture and consumer data access, with direct-to-restaurant models bypassing consolidated retail distributors.
- Supermarkets:Rewe, Carrefour, and Tesco control the primary pathway for mass-market and mid-premium formats. Shelf-space negotiations favor suppliers with EFSA-compliant labeling and consolidated logistics coverage across multiple member states.
- Online:Direct-to-consumer platforms enable craft producers to reach heat-forward enthusiasts in Scandinavia and the Baltic states. Subscription models for limited-release barrel-aged products generate recurring revenue without retail slotting fees.
- Convenience Stores:Impulse-oriented formats stock recognizable global brands in travel-size packaging.
- Wholesalers:Foodservice distributors aggregate demand from fragmented restaurant and catering accounts.
Supermarkets dominate absolute volume; Online gains share fastest among premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Craft fermentation specialists cluster in British urban centers and Calabrian valleys, anchoring Europe's premium hot sauce production capacity. Their technical workforce sustains barrel-aging traditions while adapting to EFSA compliance protocols.
United Kingdom
London and Bristol house the continent's densest concentration of small-batch hot sauce artisans, with Scotch whisky cask repurposing for pepper mash aging now standard practice. British craft producers navigate EFSA capsaicin disclosure mandates through partnerships with certified HPLC laboratories in Cambridge. Yorkshire packaging clusters supply amber glass capacity for premium export lines targeting Scandinavian markets.
Germany
Rewe and Edeka supermarket chains command shelf space negotiations that favor dual-badge organic suppliers with REACH-compliant documentation. Berlin-based food tech startups integrate IoT-enabled fermentation monitoring into traditional oak barrel systems. Bavarian analytical laboratories are expanding HPLC certification capacity to preempt EFSA compliance bottlenecks for imported chili oleoresins.
Spain
Andalusian pepper growers supply single-origin provenance to Milan and Barcelona restaurants demanding menu transparency. Spanish per capita chili condiment consumption exceeds Northern European benchmarks substantially. Valencia packaging manufacturers face energy cost volatility in glass jar production for AB label-certified exports to French organic channels.
France
Carrefour's clean-label verification requirements are squeezing undifferentiated private-label suppliers from shelf space allocations. Provence-Alpes-Côte d'Azur specialty retailers leverage AB label visibility to command price premiums in Parisian organic channels. Lyonnaise foodservice distributors are consolidating direct supplier relationships with Calabrian growers for independent pizzeria accounts.
Italy
Calabrian 'Nduja traditions anchor fermentation expertise that British producers now license for premium export formulations. Milan restaurant procurement teams displace multi-source distributors with direct contracts to Andalusian pepper growers. Emilia-Romagna packaging clusters supply cobalt glass capacity for vintage-dated craft releases targeting German specialty retail.
Europe Hot Sauce Market Key Industry Players
Top-tier vendors anchor supermarket dominance through continental distribution networks, while craft specialists occupy super-premium niches with controlled scarcity positioning. The vendor base splits between mass-market condiment conglomerates and small-batch fermentation houses. Three archetypes define competitive positioning: heritage brands leveraging aged stock scarcity, heat-forward specialists commanding super-premium pricing, and private-label suppliers facing squeeze from clean-label verification demands. Consolidated retail distributors and direct-to-restaurant logistics partnerships represent the dominant competitive moves reshaping channel access.
Within the heritage brand tier, McIlhenny Company exemplifies controlled scarcity through aged pepper mash stock management, while The Kraft Heinz Company anchors mass-market scale across Northern European supermarket channels. East Coast Chilli Company occupies the heat-forward specialist position in British and Scandinavian markets. These three entities represent the structural poles—heritage scarcity, mass scale, and craft intensity—around which European competitive dynamics organize.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Unilever PLC |
| McIlhenny Company |
| East Coast Chilli Company |
| Doctor Salsas |
| Chilli No. 5 |
| Crazy Bastard Sauce |
| Daddy Cool's Chilli Sauce |
| Pip's Hot Sauce |
| Others |
Cost & Logistics Intelligence
Family-owned fermentation houses across Calabria and Andalusia anchor supply discipline through generational stock management, while their refusal to dilute equity for rapid scale preserves premium pricing power against private-label erosion. Their concentrated ownership patterns concentrate supply decisions in founder hands, insulating barrel-aging programs from quarterly margin pressure.
Pricing Analysis
Bundle-unbundle splits separate aged pepper mash base stocks from finished sauce formulations across British craft producers. Three-tier pricing structure across premium, standard, and economy levels stratifies by AB label certification and single-origin provenance documentation. Price differentiation hinges on barrel vintage transparency and HPLC-verified Scoville consistency. Cost compression in economy tiers intensifies because private-label suppliers face clean-label verification squeeze. Food manufacturers integrating hot sauce into ready-meals exhibit highest price sensitivity; Scandinavian specialty retailers show least.
Supply Chain Analysis
Regional distribution centers in Yorkshire, Emilia-Romagna, and Valencia orchestrate hub-and-spoke patterns for glass jar and amber bottle fulfillment. Raw material flows draw from Indian chili oleoresin extractors, Mexican pepper mash exporters, and Andalusian fresh pepper cooperatives. Supply chain risk centers on REACH documentation bottlenecks for imported oleoresins that freeze batch release timelines. Distribution runs through Rewe, Carrefour, and Tesco consolidation layers for mass-market tiers, while refrigerated logistics partnerships serve direct-to-restaurant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Hot Sauce Market functions as a stable compounder, with EFSA labeling mandates creating durable barriers that protect incumbent margin structures from undifferentiated competition.
For Market Incumbents: Deploy barrel-aging capacity expansion as the primary defensive lever. Lock in multi-year pepper mash supply contracts with Andalusian growers before Novel Food designations restrict cultivar access. Acquire HPLC-certified German laboratories to preempt EFSA compliance bottlenecks for super-premium formulations. Channel control through direct-to-restaurant logistics partnerships insulates against retail consolidation pressure. For New Entrants and Emerging Players: Independent pizzeria procurement teams in Milan and Barcelona represent the most penetrable channel white-space. Target Eastern European retail whitespace in Poland, Romania, and Hungary where craft penetration lags Western saturation. Launch subscription models for limited-release barrel-aged products to bypass supermarket slotting fees and capture heat-forward enthusiasts in Scandinavia. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale fermentation specialists with AB label certification but underdeveloped export infrastructure. Long-term viability frames around 5-10 year windows where EFSA compliance capacity becomes acquisition currency. Target acquisition archetype: British craft producers with Scotch cask aging programs and Cambridge HPLC partnerships. Watch for EFSA Novel Food designation announcements as inflection indicators for formulation pipeline freezes.| Strategic Initiative | Industry Significance |
|---|---|
| Barrel-Aging Capacity Expansion | Scotch whisky cask repurposing in Bristol and London creates vintage-dated scarcity positioning. |
| Dual-Badge Organic Certification | AB label plus EU organic access unlocks simultaneous mainstream and specialty channel presence. |
| Direct-to-Restaurant Logistics | Refrigerated partnerships with Milan pizzerias bypass Rewe and Carrefour consolidation layers. |
| HPLC Laboratory Acquisition | Cambridge and Bavarian certification capacity preempts EFSA capsaicin disclosure bottlenecks. |
| Eastern European Distribution Buildout | Polish and Romanian retail whitespace offers first-mover craft positioning before saturation. |
Research Approach
Coverage spans Western Europe, Northern Europe, and Southern Europe, with primary inputs from each regional cluster. Primary interviews with fermentation specialists, supermarket category buyers, restaurant procurement managers, and EFSA regulatory consultants combined with secondary validation from customs records, Nielsen retail audit data, and EFSA guidance documents. Bottom-up triangulation across product type, packaging format, and end-user segmentation integrated with top-down macroeconomic anchoring.
Granularity-level framing modeled volume and value outputs at the country-product-packaging intersection across the projection horizon. Segmentation dimensions included formulation chemistry, material format, procurement pathway, and regional regulatory cluster. CAGRs derived from trend extrapolation against per capita consumption benchmarks and channel shift assumptions. Forecast inputs incorporated EFSA Novel Food pipeline status and glass packaging energy cost trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA capsaicin threshold revisions and REACH enforcement intensity for imported oleoresins. Forecasts reflect documented assumptions about regulatory trajectory and consumption pattern stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Cocktail Syrups Market
Condiments & Sauces
Condiments Market
Condiments & Sauces
Sour Dressings Market
Condiments & Sauces
Organic Condiments Market
Condiments & Sauces
Sun-Dried Tomato Umami Concentrate Systems Market
Condiments & Sauces
Ketchup Concentrates Market
Condiments & Sauces
Sugar Toppings Market
Condiments & Sauces
Global Fish Sauce Market
Condiments & Sauces
Salad Dressings and Mayonnaise Market
Condiments & Sauces
Vegan Cheese Sauce Market
Condiments & Sauces
Egg-Free Dressing Market
Condiments & Sauces
Low Fat Mayo Market
Condiments & Sauces
Asia Pacific Fish Sauce Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
GCC Condiment Sauces (for Hospitality Sector) Market
Condiments & Sauces
Barbecue Sauce Market