
 Soups and Sauces Market | 2026-2036
Soups and Sauces Market Size, Share, and Industry Trends Forecast 2026-2036
Soups and Sauces Market Analysis
Capital-intensity divergence between automated retort facilities and artisanal batch kitchens is bifurcating competitive returns in prepared foods. Nestlé S.A. leverages its global nutrition science infrastructure to dominate clean-label reformulation pipelines. Campbell Soup anchors North American shelf-stable demand through direct-store-delivery networks that competitors struggle to replicate. Kraft Heinz specializes in condiment portfolio breadth, extending its manufacturing scale into emerging market joint ventures.
Soups and sauces comprise thermally processed or ready-to-serve liquid and semi-liquid food preparations, typically acidified or retort-sterilized to achieve water activity below 0.85 for ambient shelf stability, serving as meal bases, flavor enhancers, or standalone convenience nutrition. The ingredient-type dimension reveals structural momentum: organic and gluten-free sub-categories command premium positioning as FSSAI in India and FDA in the United States tighten additive disclosure rules, while meat-based formulations sustain volume leadership in East Asian convenience retail. Pouch packaging captures share from glass jars in food service channels where portion control and reduced shipping weight determine procurement decisions.
Regulators including the FDA, EFSA, and FSSAI enforce progressively stricter sodium reduction targets and clean-label standards, compelling manufacturers to reformulate emulsifier systems and replace artificial preservatives with cultured dextrose or high-pressure processing. REACH compliance in Europe and evolving GB standards in China add compliance layers for imported flavor compounds and packaging substrates. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal reshape energy-intensive retort operations and whether biodegradable pouch films achieve cost parity before channel mandates harden.
Market Dynamics
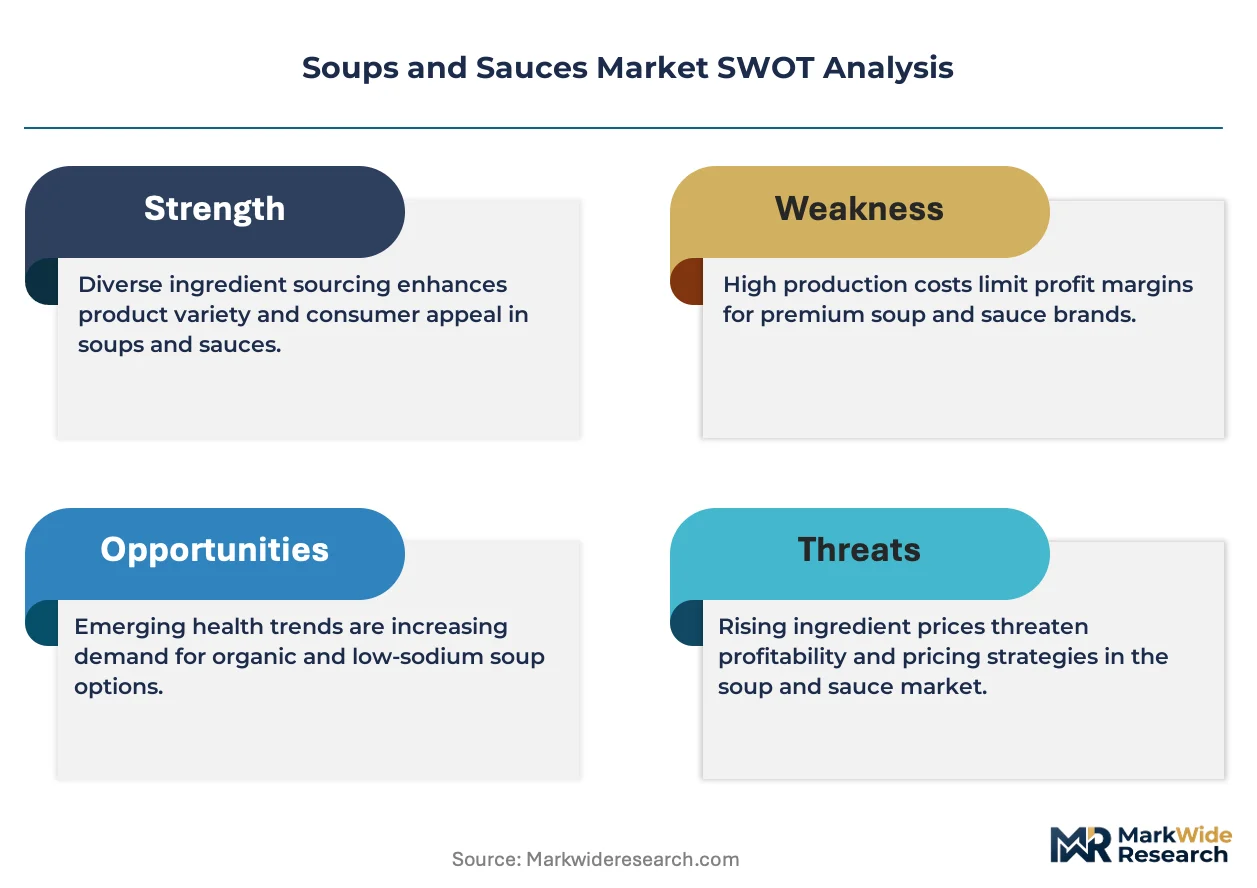
Clean-label mandates across multiple jurisdictions are compressing formulation timelines while retort sterilization costs climb, forcing manufacturers to choose between capital-heavy automation and premium positioning that absorbs compliance overhead.
Growth Catalysts
- EU Green Deal carbon targets:Energy-intensive retort operations face retrofit deadlines that favor early movers with renewable thermal contracts, creating first-mover advantages in shelf-stable clean-label portfolios.
- Food service channel recovery:Institutional buyers in Vietnam and Indonesia are consolidating procurement around single-source pouch suppliers who guarantee portion consistency and reduced shipping weight.
- High-pressure processing (HPP):Cold-pasteurization technology eliminates thermal degradation of volatile flavor compounds, enabling refrigerated clean-label sauces to capture ambient shelf-stable volume in premium urban retail.
Market Restraints
- Tomato paste and dairy input volatility:Concentrate supply from California and New Zealand experiences climate-driven harvest variance that squeezes gross margins on tomato-based and cream-based formulations.
- Retort equipment supplier concentration:German and Italian sterilization system manufacturers command 18-24 month delivery backlogs, constraining capacity expansion for mid-tier processors.
- Substitution by fresh-prepared:Ghost kitchen operators and meal-kit assemblers displace ambient soup occasions with refrigerated short-shelf-life alternatives in dense metropolitan markets.
Strategic Opportunities
- Secondary city penetration in Indonesia:Modern trade expansion into Surabaya and Bandung creates distribution infrastructure for ambient pouch formats previously confined to Jakarta.
- FSSAI clean-label incentive alignment:India's phased additive disclosure mandates reward early reformulators with preferential retail placement in organized grocery chains.
- Biodegradable film-pouch convergence:Barrier-coated cellulose and PLA-laminate technologies mature simultaneously, enabling shelf-stable packaging that satisfies EU single-use plastic directives without aluminum layers.
Industry Challenges
- Flavor chemist scarcity:Reformulation of emulsifier-free systems requires specialized expertise in natural stabilizer interactions that outpaces current training pipeline output.
- Legacy ERP integration with batch traceability:Artisanal producers upgrading to automated retort lines face data architecture friction when connecting new SCADA systems to existing inventory platforms.
- Dual certification timelines:Simultaneous pursuit of organic and halal credentials for Southeast Asian export creates documentation bottlenecks that extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soups and Sauces Market |
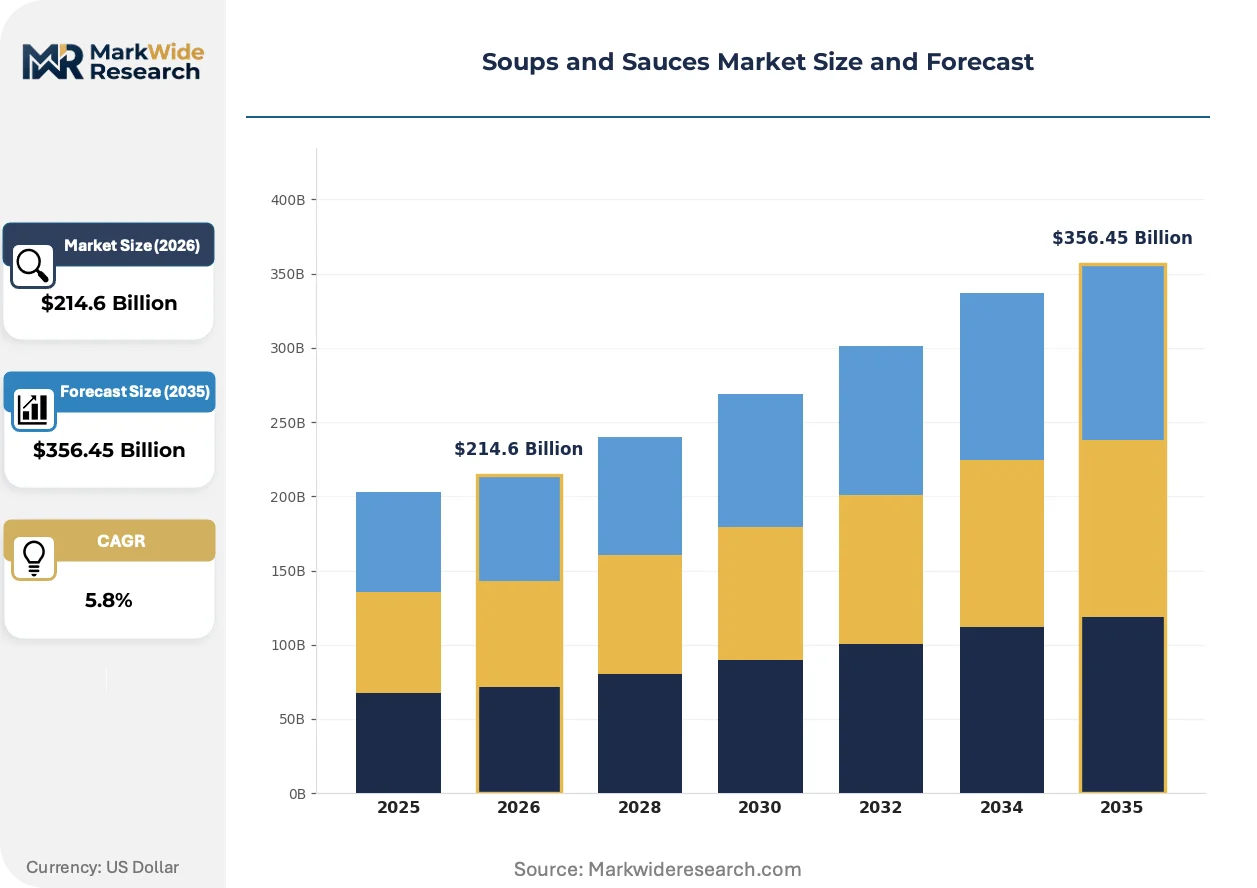
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $356.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Soups, Instant Soups, Pasta Sauces, Condiments Ingredient Type: Vegetarian, Meat-Based, Organic, Gluten-Free Packaging Type: Glass Jars, Plastic Containers, Pouches, Tetra Packs Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service |
| Companies Covered | Acecook Vietnam, Campbell Soup, Nestlé S.A., House Foods Group, General Mills, Unilever Food Solutions, Kraft Heinz, Baxters Food Group, Nissin Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soups and Sauces Market Emerging Trajectories
Formulation science and packaging engineering are converging to redefine shelf stability without synthetic preservation, while procurement patterns among institutional buyers compress supplier qualification cycles.
Retort pouch technology is miniaturizing sterilization chambers and control systems to enable distributed production at smaller batch scales. Regional co-packers in Vietnam and Thailand are adopting these compact systems to serve food service accounts with customized portion formats. The technology is miniaturizing capital requirements for market entry, fragmenting production geography away from centralized mega-facilities.
REACH compliance for flavor compounds and packaging substrates tightens disclosure thresholds for substances of very high concern across European supply chains. Manufacturers reformulating for clean-label positioning must now document full material composition to pre-registration deadlines. Sauce exporters to Germany and France face the steepest requalification burdens as downstream retailers demand batch-level chemical footprint data.
Buyer concentration among contract food service management companies is compressing supplier qualification from multi-year trials to single-season performance gates. Sodexo and Compass-style operators in Southeast Asia now award annual contracts based on three-month pilot programs rather than legacy 18-month validation cycles. Vietnam's institutional catering sector exhibits the most aggressive timeline compression as hospital and university procurement teams centralize decision authority.
Soups and Sauces Market Segmentation
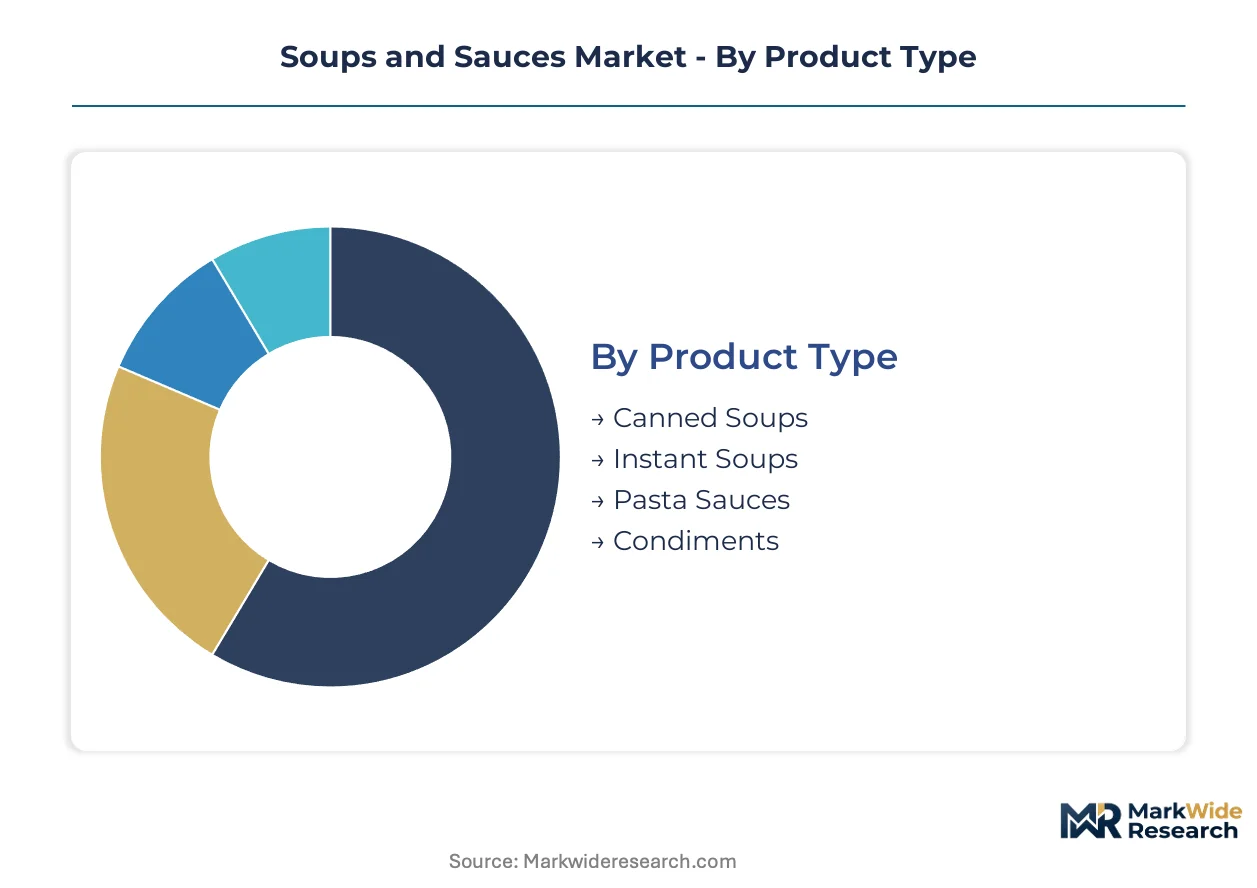
Soups and sauces manufacturers navigate divergent margin profiles across thermal processing methods and preservation technologies. Segmentation reveals where clean-label premiums offset reformulation costs and which channels concentrate volume as food service procurement centralizes.
Product Type:
Fresh-prepared alternatives and ghost kitchen operators exert substitution pressure most acutely on ambient shelf-stable formats, compressing occasion windows for traditional categories.
- Canned Soups:Retort-sterilized metal-can formats dominate North American pantry stockpiling behavior and emergency preparedness purchasing. Volume concentrates in Midwest US retail chains where direct-store-delivery networks maintain facings dominance despite pouch encroachment.
- Instant Soups:Dehydrated or freeze-dried formulations requiring only hot water activation command premium pricing in Asian convenience retail and European outdoor recreation channels. Demand clusters in Japan's railway kiosks and German trekking supply outlets where portion weight determines procurement.
- Pasta Sauces:Tomato-based and cream-based preparations face input volatility from California concentrate and New Zealand dairy supply swings.
- Condiments:Acidified or fermented flavor enhancers span table-top bottles to food service portion cups.
Canned soups anchor the volume base while instant soups gain share at the steepest rate.
Ingredient Type:
Cost tier stratification separates commodity formulations from certified premiums, with organic and gluten-free credentials commanding shelf placement allowances in organized retail.
- Vegetarian:Plant-based broths and pulse-thickened sauces leverage lentil, mushroom, and coconut milk bases to achieve umami depth without animal inputs. European retailers under EFSA sodium reduction mandates favor these formulations for cleaner nutritional panels.
- Meat-Based:Bone broths, poultry stocks, and rendered meat emulsions sustain dominance in East Asian convenience retail where dashi and chicken essence traditions anchor consumption habits. Volume concentrates in Vietnam and Indonesia urban supermarkets.
- Organic:Certified pesticide-free ingredient sourcing requires dual documentation for EU organic regulation and US National Organic Program equivalence.
- Gluten-Free:Modified starch and rice flour thickeners replace wheat-based roux in sauce formulations targeting celiac and wellness-positioned consumers.
Meat-based formulations retain the largest volume footprint while organic certifications expand most quickly among new product launches.
Packaging Type:
Shipping weight and breakage rates determine procurement preferences as food service operators consolidate around suppliers who guarantee supply chain resilience.
- Pouches:Multi-layer polymer or aluminum-laminate retort pouches reduce shipping weight by 60-70% versus glass equivalents while enabling microwave-in-bag convenience. Food service procurement in Vietnam and Indonesia now mandates pouch formats for institutional catering contracts.
- Glass Jars:Premium pasta sauces and condiments retain jar packaging for shelf presence and reuse value in European and North American retail. Breakage costs and freight density disadvantages constrain expansion in emerging market modern trade.
- Plastic Containers:Polypropylene tubs dominate refrigerated clean-label segments where HPP replaces thermal sterilization.
- Tetra Packs:Aseptic carton formats suit liquid stocks and cooking sauces in European ambient retail where recycling infrastructure accepts composite materials.
Glass jars maintain the volume foundation in developed retail while pouches capture the steepest expansion trajectory across food service channels.
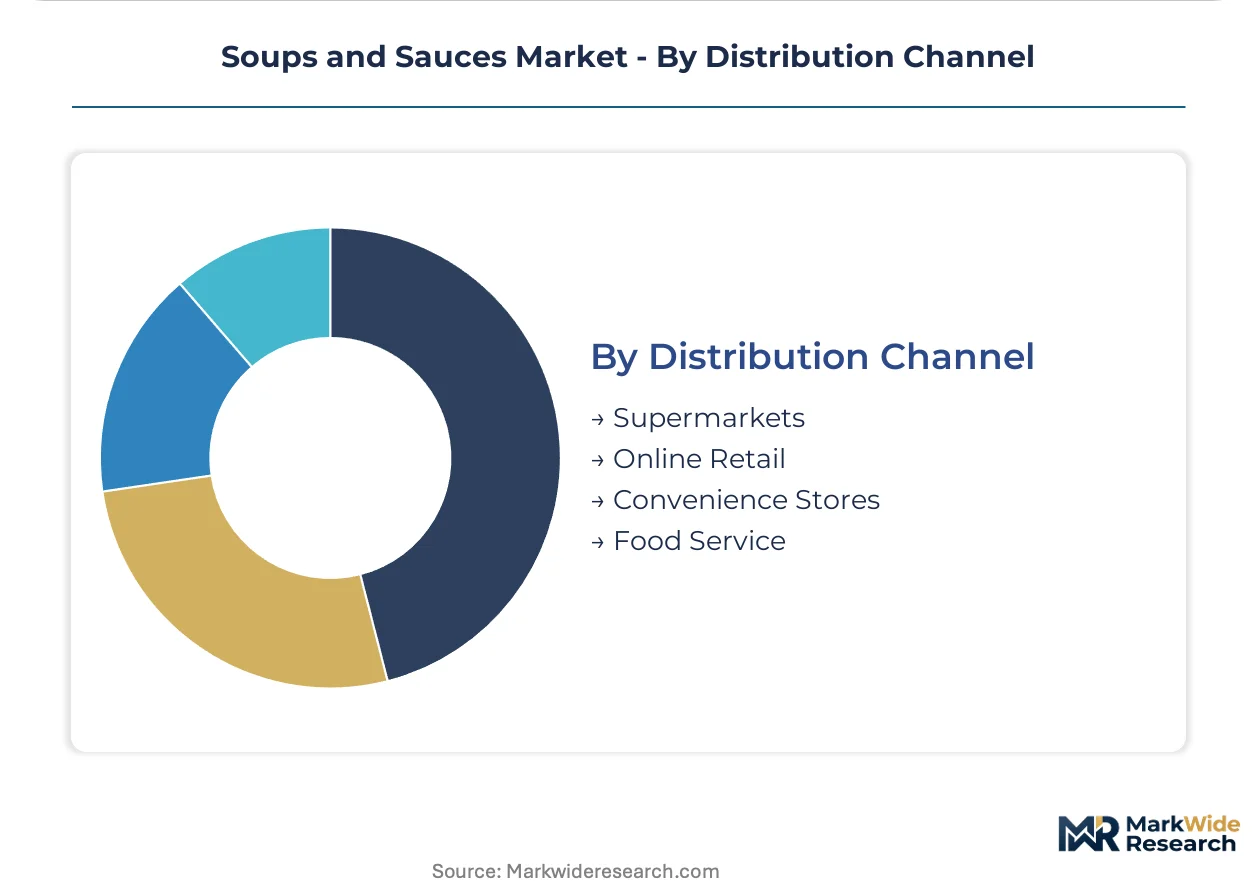
Distribution Channel:
Customer type concentration separates household stock-up purchasing from just-in-time replenishment patterns among commercial operators.
- Food Service:Contract catering management companies and chain restaurant procurement teams consolidate annual awards around single-source pouch suppliers. Vietnam's hospital and university sectors exhibit the most aggressive supplier qualification compression, reducing validation cycles to single-season performance gates.
- Supermarkets:Organized grocery chains in India leverage FSSAI clean-label incentive alignment to grant preferential placement for early reformulators. Shelf-stable soup facings concentrate in Jakarta, Surabaya, and Bandung as modern trade penetrates secondary Indonesian cities.
- Online Retail:Direct-to-pantry subscription models and quick-commerce platforms displace emergency stock-up purchasing in dense metropolitan markets.
- Convenience Stores:Grab-and-go single-serve formats target transit-oriented consumption in Japan's railway kiosks and Southeast Asian petrol station retail.
Supermarkets retain the broadest volume base while food service channels climb the fastest as institutional procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics vary sharply across major markets, with net importers in Southeast Asia driving pouch format adoption while European regulators accelerate clean-label compliance costs for external suppliers.
United States
Midwest retail chains sustain canned soup volume through direct-store-delivery networks that Campbell Soup dominates. FDA sodium reduction targets and bioengineered food disclosure rules compel reformulation of cream-based sauces. Chicago and Cincinnati anchor manufacturing clusters where retort capacity serves both domestic pantry stockpiling and Canadian export.
Germany
REACH compliance deadlines and EU Green Deal carbon mandates reshape procurement for tomato-based pasta sauces. EFSA clean-label standards favor vegetarian formulations with lentil and mushroom bases. The Rhine-Ruhr industrial corridor concentrates aseptic carton production for liquid stocks distributed across Benelux markets.
Vietnam
Urban supermarket expansion in Ho Chi Minh City and Hanoi accelerates pouch soup adoption as modern retail penetrates beyond traditional wet markets. Hospital and university procurement centralization compresses supplier qualification cycles to single-season performance gates. Acecook Vietnam and Nissin Foods anchor local production for ASEAN export.
Indonesia
Secondary city growth in Surabaya and Bandung creates distribution infrastructure previously confined to Jakarta. FSSAI-aligned clean-label positioning from Indian exporters competes with domestic halal-certified production. Institutional catering contracts now mandate portion-controlled pouch formats for food service channels.
India
FSSAI phased additive disclosure mandates reward early reformulators with preferential placement in organized grocery chains. Maharashtra and Gujarat host manufacturing clusters serving both domestic urban retail and Middle East export. Organic and gluten-free sub-categories command shelf placement allowances as certification infrastructure matures.
Soups and Sauces Market Vendor Landscape
Concentration sits with diversified nutrition conglomerates and specialized prepared foods operators. The market structure exhibits tiered consolidation, with global CPG majors controlling clean-label reformulation pipelines and regional specialists capturing food service procurement. Three archetypes dominate: nutrition-science-driven conglomerates with R&D infrastructure, direct-store-delivery specialists with channel captive networks, and Asian instant food specialists with distributed pouch manufacturing. Competitive moves center on portfolio diversification into emerging market joint ventures and strategic partnerships for biodegradable packaging scale.
Within the diversified nutrition tier, Nestlé S.A. and Unilever Food Solutions exemplify global reformulation capabilities spanning multiple regulatory jurisdictions. Kraft Heinz occupies a position on condiment portfolio breadth, while Campbell Soup anchors North American shelf-stable distribution density. Among Asian instant food specialists, Acecook Vietnam and Nissin Foods represent distributed production models serving ASEAN food service procurement centralization. House Foods Group and Baxters Food Group sit within the premium-positioned tier, with General Mills bridging mass retail and health-positioned sub-categories.
| Leading Market Players |
|---|
| Acecook Vietnam |
| Campbell Soup |
| Nestlé S.A. |
| House Foods Group |
| General Mills |
| Unilever Food Solutions |
| Kraft Heinz |
| Baxters Food Group |
| Nissin Foods |
| Others |
Supply Flow & Price Mechanics
Retort sterilization capacity utilization above 85% in Thailand and Vietnam generates scale economies that compress unit costs for pouch-format soups while establishing price floors that artisanal batch producers cannot match. This concentration of thermal processing infrastructure grants volume leaders procurement leverage over California tomato concentrate and New Zealand dairy inputs that smaller competitors lack.
Pricing Analysis
Industrial food service buyers anchor contract pricing through annual volume commitments that secure preferential rates against spot-market volatility. Three-tier pricing structure across premium clean-label, standard retort-stable, and economy dehydrated formats separates organic-certified SKUs from commodity formulations. Cost compression in standard-tier tomato-based sauces is intensifying because California concentrate harvest variance has tightened supplier margins. Quick-commerce platforms exhibit the highest price sensitivity, while hospital procurement teams prioritize supply assurance over unit cost.
Supply Chain Analysis
Thailand, Vietnam, and Indonesia anchor retort pouch manufacturing for ASEAN food service procurement, with Ho Chi Minh City and Bangkok hosting the densest co-packer clusters. Raw material flows draw from California tomato paste, New Zealand whey powder, and Chinese modified starch for thickener systems. Single-source vulnerability concentrates in German and Italian sterilization equipment suppliers whose 18-24 month delivery backlogs constrain capacity expansion. Distribution runs through consolidated contract catering management companies that centralize annual awards around single-source pouch suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soups and sauces market exhibits cyclical recovery characteristics as away-from-home consumption normalizes following pandemic-era disruptions, with food service channel rehabilitation representing the primary cyclical driver.
For Market Incumbents: Consolidate retort capacity positions in Vietnam and Indonesia before equipment delivery backlogs extend further, locking in thermal processing infrastructure that emerging competitors cannot replicate. Deepen backward integration into California tomato concentrate sourcing to buffer margin compression from climate-driven harvest variance. Prioritize FSSAI clean-label pre-certification to secure preferential placement in India's organized grocery chains ahead of phased additive disclosure mandates.
For New Entrants and Emerging Players: Lead with biodegradable pouch formats targeting EU single-use plastic directive compliance gaps that incumbent retort lines cannot address without capital-intensive retrofit. Target Surabaya and Bandung's secondary city modern trade expansion where distribution infrastructure remains underdeveloped relative to Jakarta. Pursue co-manufacturing partnerships with Thai regional co-packers adopting miniaturized sterilization chambers to bypass centralized mega-facility capital requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty clean-label reformulators with proven emulsifier-free stabilization expertise that outpaces current flavor chemist training pipeline output. Long-term viability hinges on portfolio exposure to HPP-enabled refrigerated segments displacing ambient shelf-stable volume in premium urban retail. Watch biodegradable barrier-coated cellulose cost parity achievement as the inflection signal for packaging-mandate-driven channel switching.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Pipeline | FSSAI and FDA additive disclosure mandates reward early movers with preferential retail placement. |
| Retort Pouch Capacity Expansion | Vietnamese and Indonesian food service procurement now mandates portion-controlled pouch formats exclusively. |
| Biodegradable Packaging Scale-Up | Barrier-coated cellulose maturation satisfies EU single-use plastic directives without aluminum laminate layers. |
| High-Pressure Processing Adoption | Cold-pasteurization technology preserves volatile flavor compounds in premium refrigerated clean-label sauces. |
| Secondary City Distribution Buildout | Surabaya and Bandung modern trade penetration creates infrastructure for ambient pouch formats beyond Jakarta. |
Methodological Framework
Operator-level perspectives from food service procurement directors, retail category buyers, retort equipment manufacturers, and flavor formulation chemists anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from FDA sodium reduction guidance documents, EFSA clean-label standards filings, FSSAI additive disclosure circulars, and ASEAN customs trade statistics. Bottom-up volume modeling across ingredient type, packaging format, and distribution channel dimensions triangulated against top-down macroeconomic consumption indicators.
Sensitivity analysis tested forecast robustness across alternative regulatory implementation timelines and raw material price volatility scenarios. Segmentation dimensions modeled include thermal processing method, preservation technology, ingredient certification tier, packaging substrate, and regional regulatory cluster. CAGRs were derived from normalized historical volume trajectories projected through demographic urbanization trends and modern retail penetration curves. Forecast inputs incorporated food service channel recovery rates, clean-label reformulation adoption elasticities, and biodegradable packaging cost convergence assumptions.
Forecasts assume regulatory continuity in FDA, EFSA, and FSSAI implementation regimes; material policy shifts would require re-modeling. Specific risks that could revise projections include retort equipment supplier delivery extensions beyond current backlogs, California tomato concentrate harvest failures, and EU Green Deal carbon target acceleration affecting thermal processing energy costs. Recalibration cycles align with material shifts in food service procurement centralization, clean-label mandate enforcement, and sustainable packaging substrate maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Sun-Dried Tomato Umami Concentrate Systems Market
Condiments & Sauces
Sauces, Condiments, and Dressings Market
Condiments & Sauces
Australia and New Zealand Tomato Sauce Market
Condiments & Sauces
Horseradish Sauce Market
Condiments & Sauces
Oriental Sauce Market
Condiments & Sauces
Cocktail Syrups Market
Condiments & Sauces
Low Salt Soy Sauce Market
Condiments & Sauces
Sandwich Spread Market
Condiments & Sauces
United States Hot Sauce Market
Condiments & Sauces
Dipping Sauces Market
Condiments & Sauces
Global Fish Sauce Market
Condiments & Sauces
Chocolate Syrup Market
Condiments & Sauces
Prepared Mustard Market
Condiments & Sauces
United States Pasta Sauce Market
Condiments & Sauces
Sauces and Condiments Market
Condiments & Sauces
Europe Pasta Sauce Market