
 Browning Enhancers Market | 2026-2036
Browning Enhancers Market Size, Share, and Industry Trends Forecast 2026-2036
Browning Enhancers Market Analytics
Artisan and premium bakery buyers is bifurcating demand away from mass-market snack producers across the Browning Enhancers Market. Kerry Group plc leverages its integrated flavor technology platforms to serve clean-label bread and pastry manufacturers. Tate & Lyle PLC anchors supply relationships with industrial bakeries seeking reduced-sugar Maillard solutions. DSM competes through its specialty enzyme portfolio targeting controlled browning in frozen dough applications.
Browning enhancers comprise food-grade additives and agents that accelerate or control non-enzymatic Maillard reactions and enzymatic polyphenol oxidase activity, typically operating at temperatures between 120°C and 180°C with pH ranges of 5.0 to 8.0 to achieve desired color, flavor, and crust formation in thermally processed foods. Natural enhancers occupy the premium pricing tier as EFSA and FDA clean-label pressures reshape formulation standards across European and North American manufacturing bases. Enzymatic browning agents represent the fastest-expanding product category, driven by bakery and beverage applications where processors require precise color control without synthetic additive declarations.
EFSA additive re-evaluation protocols, FDA GRAS self-affirmation requirements, and EU Regulation 1333/2008 on food additives collectively determine which browning technologies achieve commercial scale in regulated markets. These frameworks push manufacturers toward enzymatic and natural alternatives while restricting certain sulfite-based and artificial chemical agents in specific applications. Stakeholders must monitor evolving maximum-level determinations for emerging natural enhancers and align R&D pipelines with jurisdiction-specific approval timelines.
Market Dynamics
Clean-label bakery procurement in Europe is pulling demand away from conventional snack formulations as EFSA additive re-evaluation protocols intensify scrutiny of artificial browning agents. This regulatory pressure is restructuring supplier relationships and R&D priorities across the value chain.
Growth Catalysts
- Enzymatic browning technology:Controlled polyphenol oxidase activity enables precise color management in frozen dough without synthetic additive declarations. Industrial bakeries in France and Germany are accelerating adoption.
- EU Regulation 1333/2008:Maximum-level determinations for sulfite-based agents are pushing manufacturers toward natural alternatives. This framework creates commercial runway for enzymatic and plant-derived enhancers.
- Artisan bakery segment:Premium bread and pastry producers require Maillard control without artificial ingredient labels. Clean-label positioning commands pricing premiums in urban European markets.
Market Restraints
- Input cost volatility:Specialty enzyme feedstocks face agricultural supply fluctuations. Wheat-derived and fungal-sourced enzyme precursors experience seasonal pricing instability.
- Technical limitation:Enzymatic agents require narrow pH windows between 5.0 and 8.0. Formulation flexibility is constrained versus chemical alternatives across diverse product matrices.
- Substitution threat:Unmodified baking processes and extended thermal exposure can achieve comparable browning without additive cost. Cost-sensitive mass-market producers retain this option.
Strategic Opportunities
- Beverage application expansion:Coffee roasting and malt beverage production seek controlled enzymatic browning. This adjacent vertical offers formulation technology transfer from bakery expertise.
- Frozen dough channel innovation:Extended distribution networks for par-baked and frozen bakery products require shelf-stable browning control. Enzyme-stabilized formulations address this unmet need.
- EFSA natural additive approval pipeline:Emerging plant-derived enhancers under evaluation create first-mover positioning. Early regulatory alignment secures commercial scale ahead of competitor entry.
Industry Challenges
- Formulation science talent scarcity:Enzyme stabilization and pH optimization require specialized food chemistry expertise. Competition for experienced technologists intensifies between ingredient suppliers.
- Legacy equipment incompatibility:Existing thermal processing lines operate at fixed temperature profiles. Retrofitting for enzymatic browning's narrower operating windows demands capital expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Browning Enhancers Market |
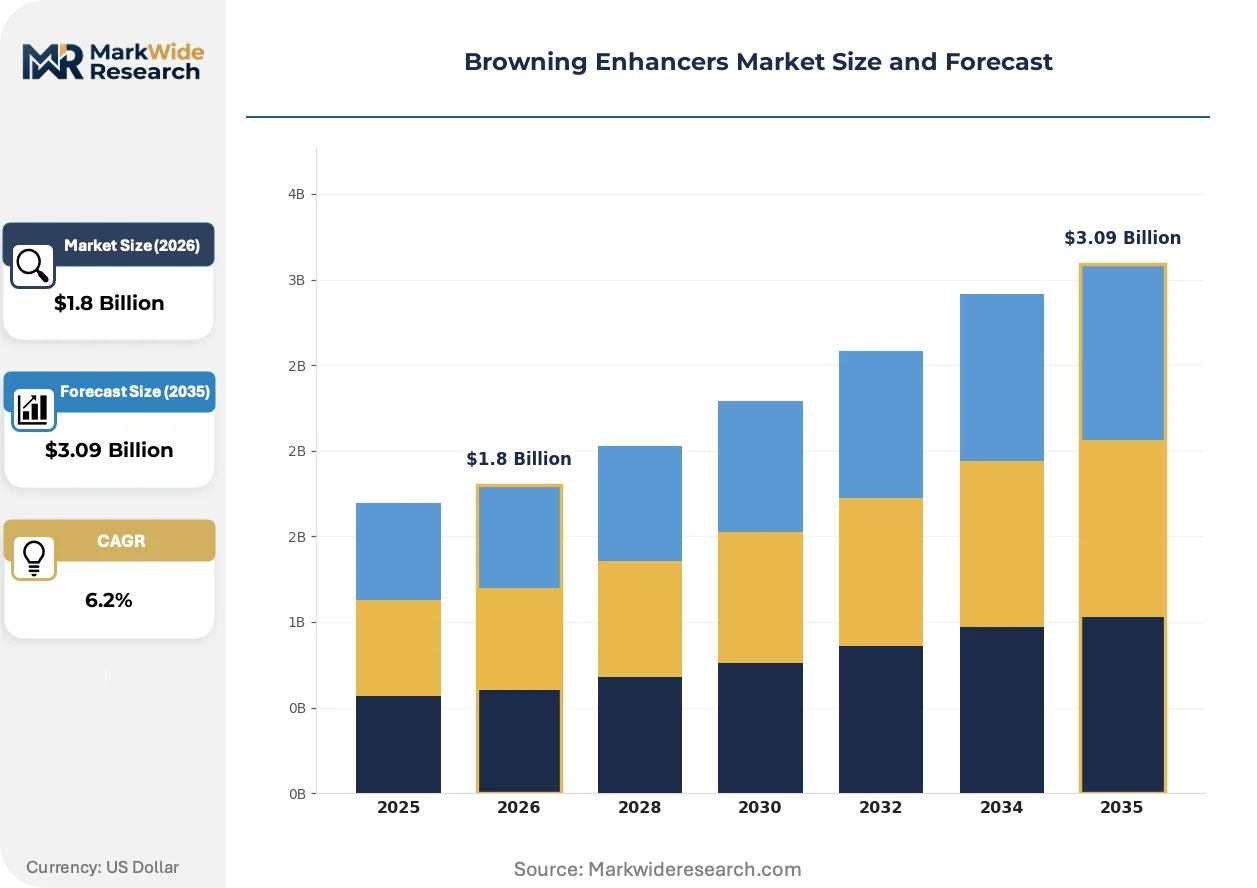
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.09 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Enhancers, Artificial Enhancers, Enzymatic Browning Agents, Chemical Browning Agents Application: Beverages, Bakery, Snacks, Sauces End User: Food Manufacturers, Restaurants, Catering Services, Retailers Form: Liquid, Powder, Granular, Concentrate |
| Companies Covered | Kerry Group plc, Ingredion Incorporated, Tate & Lyle PLC, Cargill, ADM, DSM, Sensient Technologies Corporation, Chr. Hansen Holding A/S, Givaudan SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Browning Enhancers Market Evolving Landscape
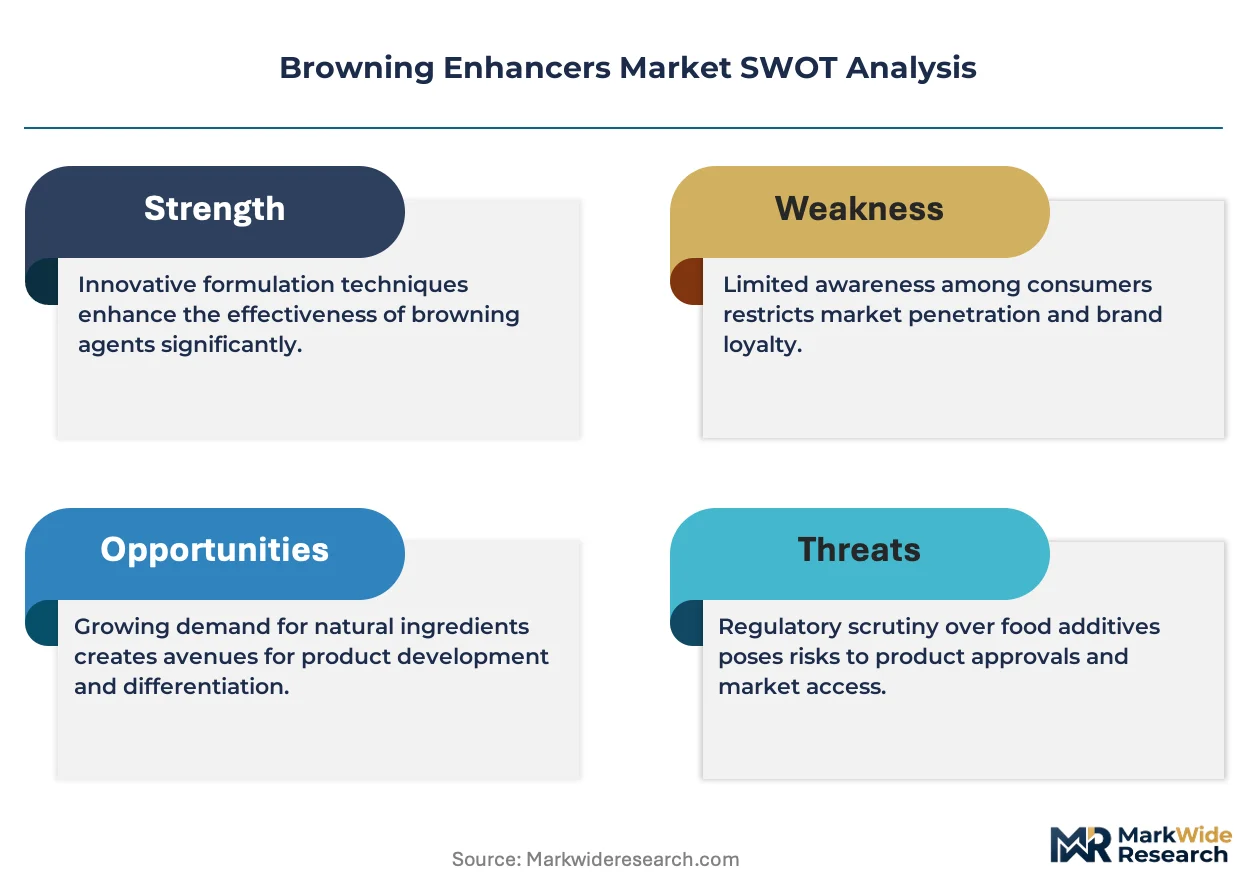
Enzymatic browning platforms are bifurcating competitive positioning between precision-controlled premium formulations and cost-optimized conventional alternatives. This technological divergence is reshaping R&D investment and customer segmentation strategies.
Glucose oxidase and hexose oxidase systems are bifurcating the frozen dough segment from conventional chemical browning. Premium bakery manufacturers in Germany and Italy are adopting these platforms for clean-label crust development. The technology is bifurcating supplier relationships toward integrated enzyme-flavor houses capable of co-developing color and taste profiles.
REACH chemical registration requirements and EFSA additive re-evaluation protocols are compressing approval timelines for novel synthetic agents. Industrial consequence includes accelerated defunding of traditional chemical browning R&D pipelines. Bakery applications in France face the most immediate substitution pressure as sulfite-based agents face renewed maximum-level scrutiny.
Direct procurement relationships between artisan bakery chains and specialty enzyme suppliers are displacing traditional distributor-mediated purchasing. Regional bakery cooperatives in Northern Italy and Bavaria are consolidating volumes to secure formulation customization. This channel restructuring is most visible in urban clusters where clean-label positioning drives consumer premium willingness.
Browning Enhancers Market Segmentation
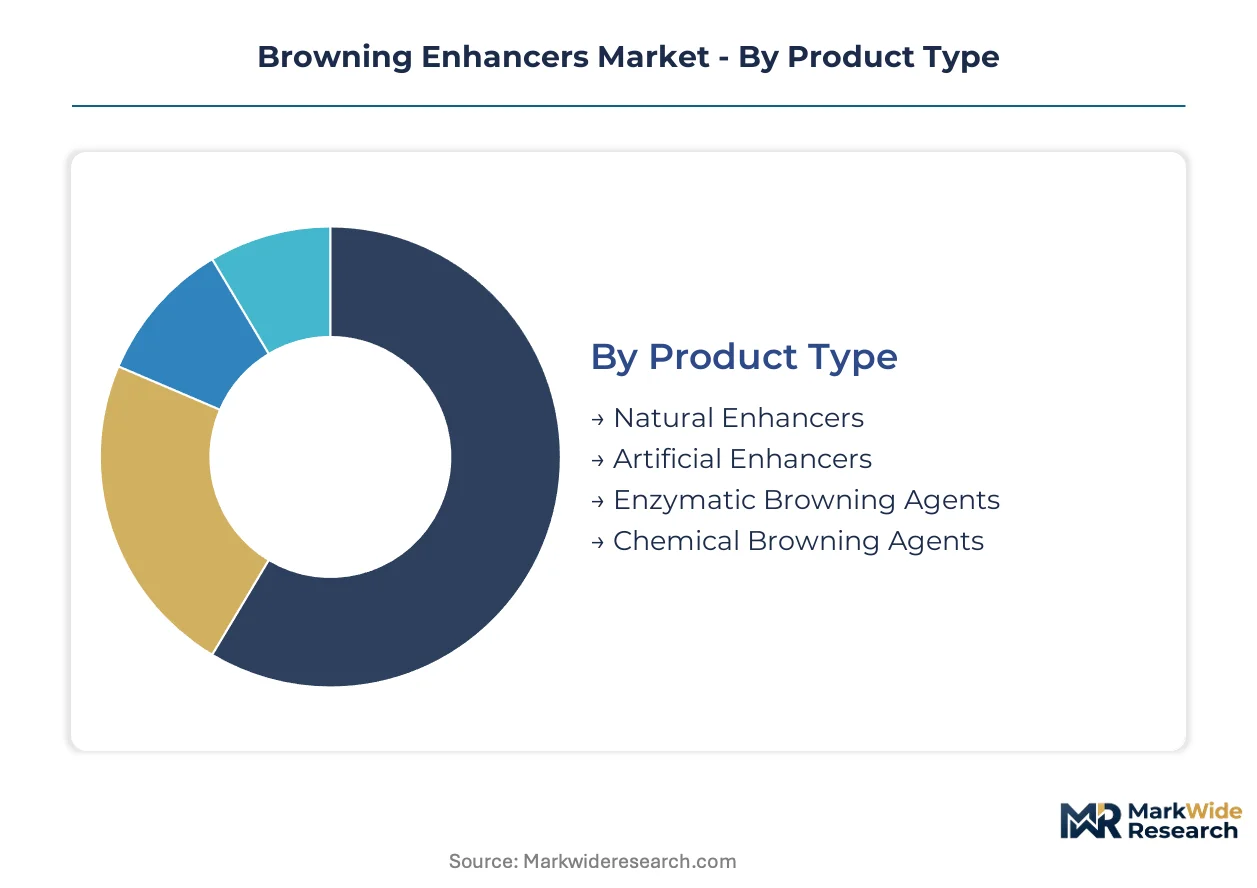
Segmentation in the Browning Enhancers Market reveals how regulatory pressure and clean-label procurement reshape competitive positioning. Manufacturers align R&D investments with specific formulation requirements across enzymatic, natural, and chemical platforms.
Product Type:
Premium margin pools concentrate in enzymatic and natural enhancers as EFSA and FDA clean-label protocols restrict artificial alternatives. Chemical agents compete on cost but face shrinking approved applications.
- Natural Enhancers:Plant-derived polyphenol and amino acid concentrates operate within pH 5.0-8.0 windows. Artisan bakeries in France and Germany absorb supply at premium pricing as sulfite-based agents face EFSA maximum-level scrutiny.
- Enzymatic Browning Agents:Glucose oxidase and hexose oxidase systems enable precise Maillard control in frozen dough. Industrial bakeries accelerate procurement for clean-label crust development without synthetic additive declarations.
- Artificial Enhancers:Synthetic color precursors face compressed commercial runway under REACH registration requirements.
- Chemical Browning Agents:Sulfite-based formulations retain cost-sensitive mass-market applications despite regulatory headwinds.
The dominant share belongs to Chemical Browning Agents, while Enzymatic Browning Agents is closing the gap fastest.
Application:
Volume concentration diverges between thermal-process categories requiring precise color control and ambient-stable formulations where browning is incidental.
- Bakery:Bread, pastry, and frozen dough applications demand controlled crust formation at 120°C-180°C. Par-baked distribution networks in Northern Italy and Bavaria drive enzyme-stabilized formulation adoption.
- Beverages:Coffee roasting and malt beverage production seek enzymatic color management. This vertical transfers technology from bakery expertise into controlled roasting applications.
- Snacks:Conventional extruded and fried products face clean-label reformulation pressure from European procurement shifts.
- Sauces:Thermal-processed condiments require Maillard modulation for visual appeal in retail packaging.
Bakery commands the largest volume position, though Beverages is expanding most quickly as roasting technology crosses over from bakery enzyme platforms.
End User:
Procurement authority concentrates with integrated manufacturers controlling formulation specifications, while foodservice operators prioritize cost and operational simplicity.
- Food Manufacturers:Industrial bakeries and beverage processors specify enzymatic systems for clean-label compliance. Direct supplier relationships with enzyme houses displace traditional distributor channels.
- Restaurants:Premium bakery chains and coffee roasters seek consistent browning without artificial ingredient labels.
- Catering Services:High-volume operators balance visual standards against preparation speed constraints.
- Retailers:Private-label bakery programs drive specification requirements upstream to contract manufacturers.
Food Manufacturers hold the dominant procurement volume, with Restaurants gaining influence fastest through direct supplier engagement.
Form:
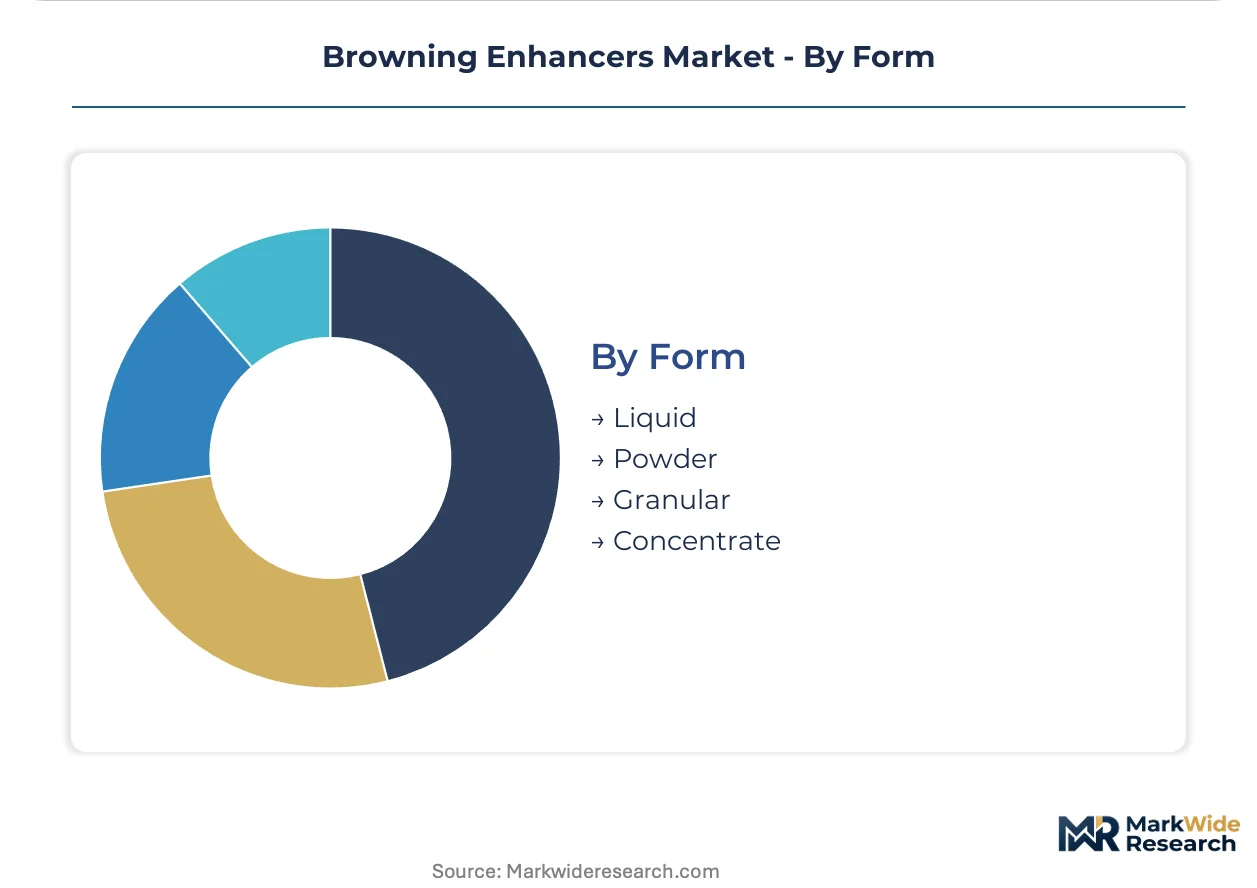
Supply chain efficiency and shelf stability requirements determine format preference across distribution distances and storage conditions.
- Powder:Spray-dried enzyme concentrates offer extended stability for frozen dough distribution networks. German and Italian industrial bakeries standardize on this format for inventory flexibility.
- Liquid:Ready-to-use solutions integrate directly into continuous processing lines. Beverage applications favor liquid enzymatic systems for dosing precision in roasting operations.
- Granular:Free-flowing formats suit dry-blend bakery premix applications.
- Concentrate:High-potency forms reduce transport costs for long-distance supply to centralized manufacturing.
Powder maintains the leading position, while Liquid is climbing the fastest as beverage roasting applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German enzymatic browning agent exports supply French and Italian bakery manufacturers seeking EFSA-compliant clean-label formulations. This trade corridor channels premium-grade glucose oxidase systems into artisan bread and frozen dough applications across Continental Europe.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia drive procurement of enzyme-stabilized browning systems for par-baked distribution networks. EU Regulation 1333/2008 maximum-level determinations for sulfite-based agents accelerate substitution toward natural alternatives. The Munich-Stuttgart corridor concentrates formulation R&D partnerships between enzyme houses and frozen dough manufacturers.
France
Artisan bakery chains in Paris and Lyon absorb premium-priced natural enhancers for clean-label crust development. ANSM and EFSA coordinated additive re-evaluation protocols restrict artificial browning agent approvals. The Île-de-France region anchors direct procurement relationships between regional bakery cooperatives and specialty enzyme suppliers.
Italy
Frozen dough processors in Lombardy and Emilia-Romagna specify enzymatic browning for extended shelf-life export products. REACH chemical registration requirements compress approval timelines for novel synthetic agents. Northern Italian bakery cooperatives consolidate volumes to secure customized hexose oxidase formulations from integrated suppliers.
United States
Commercial bakeries and beverage roasters seek FDA GRAS-affirmed enzymatic systems for reduced-sugar Maillard applications. FDA self-affirmation requirements and USDA organic certification standards shape natural enhancer commercialization pathways. The Midwest industrial baking belt spanning Illinois and Ohio standardizes on powder-format enzyme concentrates for inventory flexibility.
United Kingdom
Premium bread manufacturers in Greater London and the Midlands reformulate away from artificial additives ahead of potential divergence from EU additive frameworks. UK Food Standards Agency additive review protocols create uncertainty for sulfite-based agent continuance. The Southeast England corridor hosts pilot-scale partnerships between artisan bakery chains and enzyme technology developers.
Browning Enhancers Market Competitive Landscape
Player mix skews toward integrated ingredient conglomerates with enzyme technology platforms and specialty chemical divisions. Tiered competitive structure separates premium enzymatic specialists from cost-optimized chemical browning suppliers. Dominant archetypes include integrated flavor-enzyme houses, diversified agricultural processors, and fermentation technology specialists. Capacity expansion in European enzyme production and strategic partnerships for beverage application technology represent the primary competitive moves.
Within the integrated ingredient conglomerate tier, Kerry Group plc and Tate & Lyle PLC occupy positions exemplifying the convergence of flavor technology and enzymatic browning capabilities. DSM represents the fermentation technology specialist archetype with controlled polyphenol oxidase applications. These three anchors illustrate how supplier relationships bifurcate between clean-label bakery formulators and industrial-scale manufacturers seeking Maillard control without synthetic additive declarations.
| Leading Market Players |
|---|
| Kerry Group plc |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Cargill |
| ADM |
| DSM |
| Sensient Technologies Corporation |
| Chr. Hansen Holding A/S |
| Givaudan SA |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for fungal-sourced enzyme precursors concentrate cost volatility in German and Italian supply channels, amplifying pricing power for integrated producers with captive fermentation capacity while squeezing margin for distributor-dependent formulators.
Pricing Analysis
Current-generation enzymatic systems command 40-60% premiums over sulfite-based chemical alternatives, while next-generation hexose oxidase platforms price at additional 25-35% markups for frozen dough applications. Three-tier pricing structure across premium enzymatic, standard natural, and economy chemical levels stratifies by EFSA compliance tier and volume commitment scale. Pricing pressure stems from agricultural feedstock volatility in wheat-derived and fungal-sourced precursors. Mass-market snack producers exhibit highest price sensitivity, while artisan bakery chains absorb premiums for clean-label positioning.
Supply Chain Analysis
Baltic Sea port congestion periodically chokes enzyme concentrate flows from Danish fermentation hubs to Continental bakery manufacturers, injecting lead-time uncertainty into par-baked distribution networks. Supply concentrates in Germany, Denmark, and the Netherlands for enzymatic production, with Italy and France anchoring natural enhancer extraction. Raw material dependencies center on fungal biomass, wheat gluten fractions, and plant polyphenol isolates. Single-source vulnerability runs through specialized fermentation capacity for glucose oxidase. Distribution runs through direct procurement relationships displacing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated bakery cooperatives in Northern Italy and Bavaria, as volume aggregation enables specification leverage against fragmented enzyme suppliers.
For Market Incumbents: Compound formulation customization capabilities to lock in direct relationships with artisan bakery chains facing EFSA sulfite restrictions. Expand captive fermentation capacity in Denmark or the Netherlands to secure supply continuity against Baltic logistics disruptions. Defend margin position by accelerating GRAS self-affirmation pipelines for next-generation enzymatic platforms before regulatory windows narrow. For New Entrants and Emerging Players: FDA GRAS fast-track pathways offer entry acceleration for novel plant-derived polyphenol concentrates targeting US organic certification standards. White-space targets include beverage roasting applications seeking Maillard control technology transfer from bakery expertise, and UK premium bread manufacturers reformulating ahead of potential additive framework divergence. Go-to-market through regional bakery cooperative consortia rather than national distributor networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agricultural processors with underutilized fermentation assets and stranded enzyme technology IP. Long-term viability hinges on regulatory alignment with EFSA natural additive approval pipelines and FDA clean-label certification trends. Acquisition focus: mid-cap specialists with integrated flavor-enzyme co-development capabilities. Signal to watch: EFSA maximum-level determinations for emerging plant-derived enhancers as inflection indicator for first-mover scale opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive production of glucose oxidase precursors insulates German suppliers from Baltic logistics volatility. |
| EFSA Natural Additive Approval Fast-Track | Early regulatory alignment secures commercial scale ahead of competitor entry for plant-derived enhancers. |
| Beverage Application Technology Transfer | Crossover from bakery enzyme platforms opens coffee roasting and malt beverage adjacencies. |
| Direct Procurement Channel Establishment | Displacing distributor relationships with Northern Italian bakery cooperatives captures specification control. |
| GRAS Self-Affirmation Pipeline Investment | FDA compliance acceleration enables US market entry for enzymatic systems ahead of regulatory compression. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA additive re-evaluation protocols, EU Regulation 1333/2008 implementation records, and REACH chemical registration databases. Primary interviews engaged formulation scientists at enzyme houses, procurement directors at industrial bakeries, regulatory affairs leads at ingredient suppliers, and technical directors at frozen dough manufacturers. Secondary sources included customs trade data for enzymatic concentrate flows, SEC filings of integrated ingredient conglomerates, and ANSM additive review documentation. Bottom-up volume triangulation against top-down value estimates validated segment-level outputs.
Segmentation dimensions modeled span product type (enzymatic, natural, chemical, artificial), application (bakery, beverages, snacks, sauces), end user (food manufacturers, restaurants, catering services, retailers), and form (powder, liquid, granular, concentrate). CAGRs were derived from regression analysis of historical procurement volumes against regulatory event timelines and clean-label adoption curves. Industry-specific forecast inputs incorporated EFSA approval pipeline velocity and frozen dough distribution network expansion rates across the analysis window.
Decision-makers should treat outputs as directional under assumptions of sustained EFSA scrutiny intensity and stable agricultural feedstock availability; material deviation in regulatory timelines or enzyme precursor supply would warrant model refresh. Practitioners should keep alternative scenarios live as EU additive framework evolution and UK Food Standards Agency divergence pathways mature.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Fortified Eggs Market
Food Enhancers and Additives
Fortifying Agent Market
Food Enhancers and Additives
Dysphagia Diet Thickening Market
Food Enhancers and Additives
South Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Mexico Food Flavor and Enhancer Market
Food Enhancers and Additives
India Food Flavor and Enhancer Market
Food Enhancers and Additives
Vegetable Shortening Market
Food Enhancers and Additives
Food Thickeners Market
Food Enhancers and Additives
Dough Conditioners Market
Food Enhancers and Additives
Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Veratrole Market
Food Enhancers and Additives
Spain Food Flavor and Enhancer Market
Food Enhancers and Additives
Feed Palatability Enhancers and Modifiers Market
Food Enhancers and Additives
Japan Water Enhancer Market
Food Enhancers and Additives
Enriched Yeast Extract Market
Food Enhancers and Additives
Crumb Softener Market