
 Oriental Sauce Market | 2026-2036
Oriental Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Oriental Sauce Market Analytics
China's Guangdong fermentation corridor is reconfiguring capacity for premium soy sauce output. Kikkoman Corporation leverages its centuries-old brewing heritage to sustain price premiums in North American retail. Lee Kum Kee anchors Cantonese-style oyster sauce production through backward integration into sugar refining and spice sourcing. Foshan Haitian Flavouring & Food dominates domestic volume with automated koji-making lines that cut batch-to-batch variation.
Oriental sauce denotes a class of fermented or brewed condiments derived from soybeans, wheat, salt, and specialized cultures, typically aged in temperature-controlled vats for months to develop amino acid complexity and Maillard browning potential. These products function as foundational flavor modifiers in East Asian cooking, delivering umami depth through glutamate and nucleotide compounds without requiring lengthy stock preparation. Soy sauce occupies the mature volume core, while gluten-free variants within ingredient-type segmentation capture expanding margin pools as celiac-sensitive households trade up from conventional alternatives. The food service distribution channel leads absolute tonnage, though online stores represent the fastest-growing outlet as direct-to-pantry subscription models gain traction among diaspora consumers seeking authentic regional variants.
China's SAMR enforces GB standards for amino nitrogen content and preservative limits that determine shelf eligibility for domestic soy sauce brands. The FDA's Food Safety Modernization Act import rules require foreign facilities to register and undergo hazard analysis, filtering smaller exporters from US market access. EFSA's ongoing evaluations of 3-MCPD esters in thermally processed sauces are pushing European buyers toward low-acid fermentation methods. Stakeholders must monitor how divergent contaminant thresholds between jurisdictions reshape supplier qualification costs and determine which production technologies warrant capital commitment.
Market Dynamics
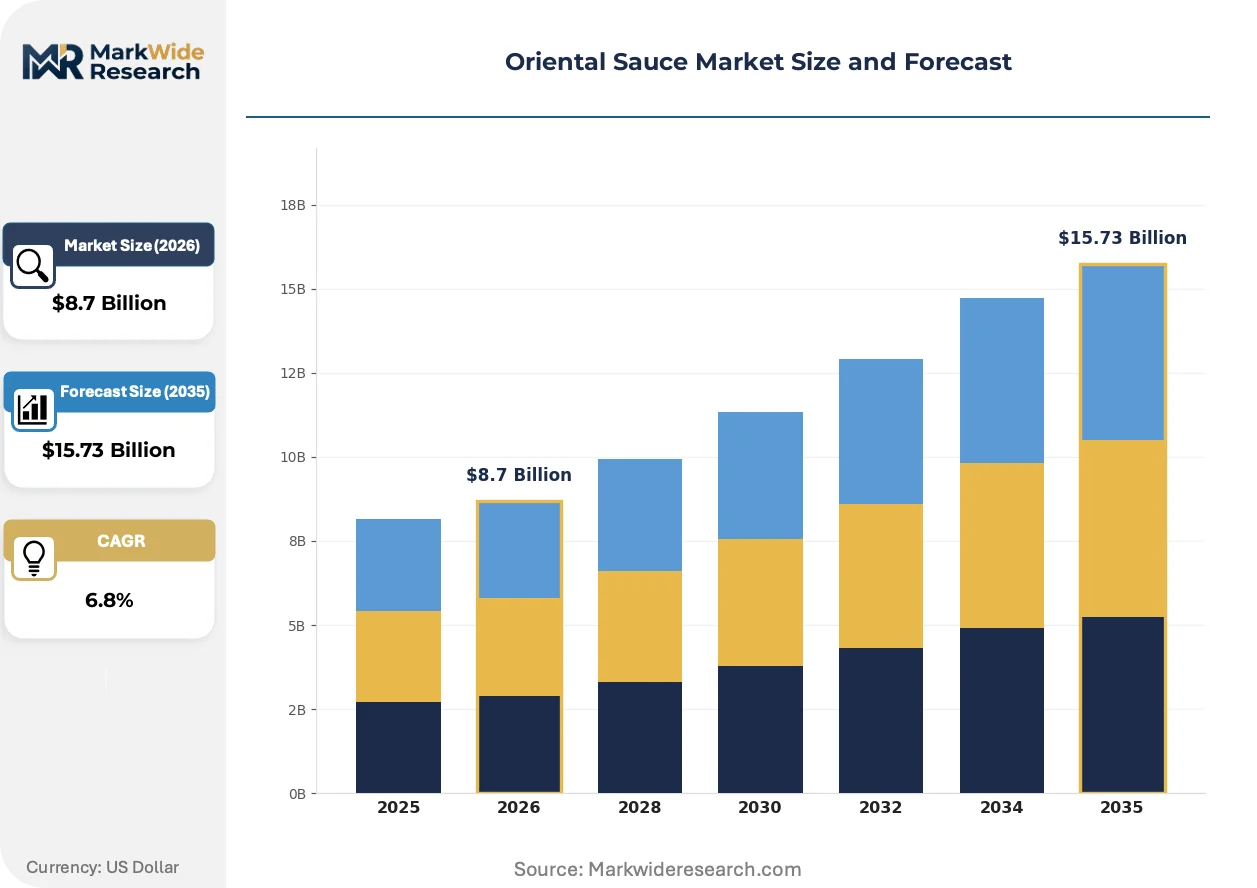
Fermentation technology upgrades and tightening contaminant thresholds across import jurisdictions are compressing supplier margins while rewarding capital-intensive producers with certified low-acid processes and automated koji control systems.
Growth Catalysts
- Clean-label fermentation protocols:Low-acid methods that minimize 3-MCPD ester formation are unlocking shelf access in EFSA-regulated European markets, displacing conventional thermally processed imports.
- Food service corridor densification:Vietnam's Ho Chi Minh City and Hanoi urban food service networks are absorbing bulk umami condiment volumes as chain restaurant penetration accelerates.
- GB standards enforcement:China's SAMR amino nitrogen grading system is consolidating domestic soy sauce tiers, pushing branded manufacturers toward premium positioning with measurable quality differentiation.
Market Restraints
- Soybean input cost volatility:Crush margin compression and South American weather variability transmit directly into fermented sauce production economics, squeezing mid-tier producers without captive crushing assets.
- Guangdong supply concentration:Overreliance on the Foshan-Shunde fermentation cluster creates single-point vulnerability to regional energy rationing or water discharge enforcement actions.
- Gluten-free certification friction:Celiac-sensitive households face limited verified alternatives as cross-contamination protocols and third-party testing add 15-20% cost premiums to conventional brewing lines.
Strategic Opportunities
- Diaspora direct-to-pantry channels:Subscription models targeting Vietnamese and Chinese expatriate households in North America bypass conventional retail slotting fees while capturing authentic regional variant demand.
- Dual carbon alignment:China's MEE carbon intensity targets for food processing create first-mover advantage for breweries deploying anaerobic digestion and waste-heat recovery systems.
- Umami-forward menu integration:Southeast Asian quick-service chains are expanding dedicated sauce stations and customizable condiment bars, opening food service formulation partnerships beyond traditional wholesale drums.
Industry Challenges
- Master brewer succession gaps:Traditional koji-making expertise concentrated among aging practitioners in Japan's Noda and China's Foshan regions faces transfer failures as automated systems displace apprentice pipelines.
- Multi-jurisdiction contaminant compliance:Divergent FDA, EFSA, and SAMR thresholds for 3-MCPD and amino nitrogen force parallel product runs or reformulation costs that fragment production scale economies.
- Legacy distributor integration:Food service wholesalers with decades-old refrigerated logistics networks resist temperature-controlled fermented sauce handling protocols required for live-culture premium variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oriental Sauce Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Sauce, Teriyaki Sauce, Hoisin Sauce, Oyster Sauce Use Case: Dressing, Marinade, Cooking Sauce, Dipping Sauce Ingredient Type: Organic, Gluten-Free, Low Sodium, Conventional Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Food Service |
| Companies Covered | Wan Ja Shan, Kimlan Foods, Kikkoman Corporation, Sempio Foods Company, Foshan Haitian Flavouring & Food, Lee Kum Kee, Pearl River Bridge, Jiajia Food Group, Yamasa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oriental Sauce Market Evolving Landscape
Digital sensing and automated fermentation control are displacing experiential craft knowledge, while regulatory divergence on processing contaminants and direct-to-consumer channel experimentation are fragmenting traditional wholesale-centric distribution architectures.
NIR spectroscopy coupled with AI-driven batch prediction is digitizing quality assurance in koji propagation rooms, cutting variation in amino nitrogen yields. Mid-cap breweries in Japan's Chiba Prefecture and China's Jiangsu corridor are retrofitting legacy vat houses with sensor networks that compress quality control cycles from days to hours. This convergence is digitizing the traditional master brewer's tacit knowledge into replicable process parameters, eroding the wage premium for experiential expertise while enabling geographic expansion of consistent output.
EFSA's rolling evaluations of 3-MCPD esters in thermally processed sauces are tightening import eligibility for conventional acid-hydrolyzed soy sauce categories. European buyers are requalifying supplier bases toward low-acid fermentation methods with documented contaminant profiles below 0.4 mg/kg thresholds. This regulatory pivot is compressing market access for Southeast Asian exporters without capital reserves to retrofit production lines, concentrating import share among Japanese and Korean facilities with established low-acid certifications.
Food service procurement is fragmenting from consolidated national distributors toward specialized Asian-ingredient importers with direct mill relationships. Independent Vietnamese restaurants in California and Texas are bypassing broadline wholesalers to source regional fish sauce variants through container-direct arrangements with Phu Quoc and Phan Thiet producers. This channel disintermediation is most visible in diaspora-dense metropolitan corridors where authenticity signaling outweighs procurement convenience, forcing legacy distributors to add specialized Asian condiment SKUs or cede volume to niche competitors.
Oriental Sauce Market Segmentation
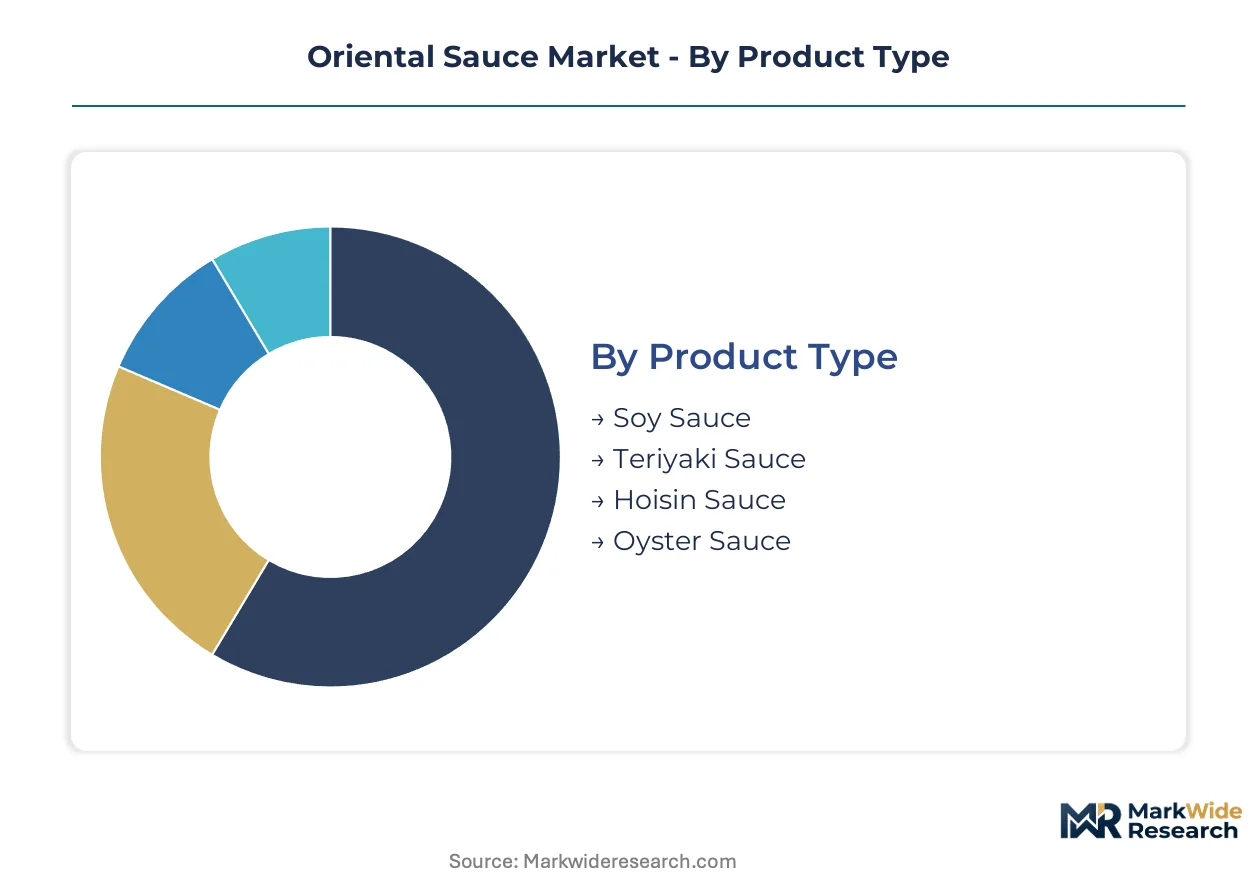
Segmentation in the Oriental sauce market reveals how fermentation scale, ingredient certification, and channel access determine margin capture. Producers must align production technology with the specific quality thresholds and handling protocols each segment demands.
Product Type:
Cost tier stratification separates commodity volume from heritage-positioned premiums, with fermentation duration and amino nitrogen density as the primary value markers.
- Soy Sauce:Brewed from soybeans, wheat, and Aspergillus cultures in temperature-controlled vats lasting 6-24 months, delivering glutamate concentrations above 1.0g/100ml. China's Foshan-Shunde corridor supplies bulk food service volumes, though EFSA contaminant thresholds now filter conventional exports from European retail shelves.
- Teriyaki Sauce:A cooked reduction combining soy sauce base with mirin, sake, and sugar, yielding a glossy Maillard coating for grilled proteins. North American retail chains favor this format for its ready-to-use convenience, bypassing the skill barrier of scratch preparation in home kitchens.
- Hoisin Sauce:Fermented soybean paste blended with sweet potato, garlic, and spices, delivering thick viscosity for glazing and stir-fry finishing.
- Oyster Sauce:Reduced oyster extract caramelized with soy sauce and brine, concentrated in Cantonese-style production clusters with backward integration into sugar refining.
Soy sauce commands the established base. The steepest expansion runs through oyster sauce as Southeast Asian quick-service chains expand dedicated umami stations.
Use Case:
Application context dictates viscosity specifications, salt loading, and packaging formats across household and commercial deployment scenarios.
- Cooking Sauce:Higher osmolality formulations engineered for heat stability during reduction and protein denaturation. Vietnam's Ho Chi Minh City food service corridors absorb bulk volumes as chain restaurant penetration accelerates, with procurement shifting toward container-direct arrangements bypassing broadline distributors.
- Dipping Sauce:Lower viscosity variants with balanced acid-salt profiles for raw or lightly cooked accompaniment. Japanese and Korean low-acid fermentation certifications unlock European retail access as EFSA tightens 3-MCPD thresholds.
- Dressing:Emulsified or light-bodied formats adapted for cold application over salads and chilled proteins.
- Marinade:Enzyme-active formulations with proteolytic tenderization potential, typically higher in sugar content for caramelization.
Cooking sauce anchors food service procurement volumes. The fastest trajectory climbs through dipping sauce as diaspora direct-to-pantry subscription models capture authentic regional variant demand.
Ingredient Type:
Certification tier determines production line segregation costs and the price premiums achievable in health-sensitive household segments.
- Gluten-Free:Brewed with rice or single-source soybean substrates, requiring dedicated koji rooms and third-party testing protocols to prevent cross-contamination. Celiac-sensitive households in North America face 15-20% cost premiums as verification adds processing overhead, limiting verified alternatives on conventional retail shelves.
- Organic:USDA or EU organic certified inputs with traceable supply chains and restricted additive palettes. Japanese Chiba Prefecture breweries retrofit legacy vat houses with sensor networks to document compliance, compressing quality control cycles while maintaining certification integrity.
- Low Sodium:Reduced salt formulations using post-fermentation dialysis or modified koji strains, targeting hypertension-conscious demographics.
- Conventional:Standard fermentation with no certification constraints, dominating absolute tonnage in price-sensitive food service channels.
Conventional production retains volume leadership. The steepest margin expansion flows through gluten-free as supply scarcity sustains pricing power in certified channels.
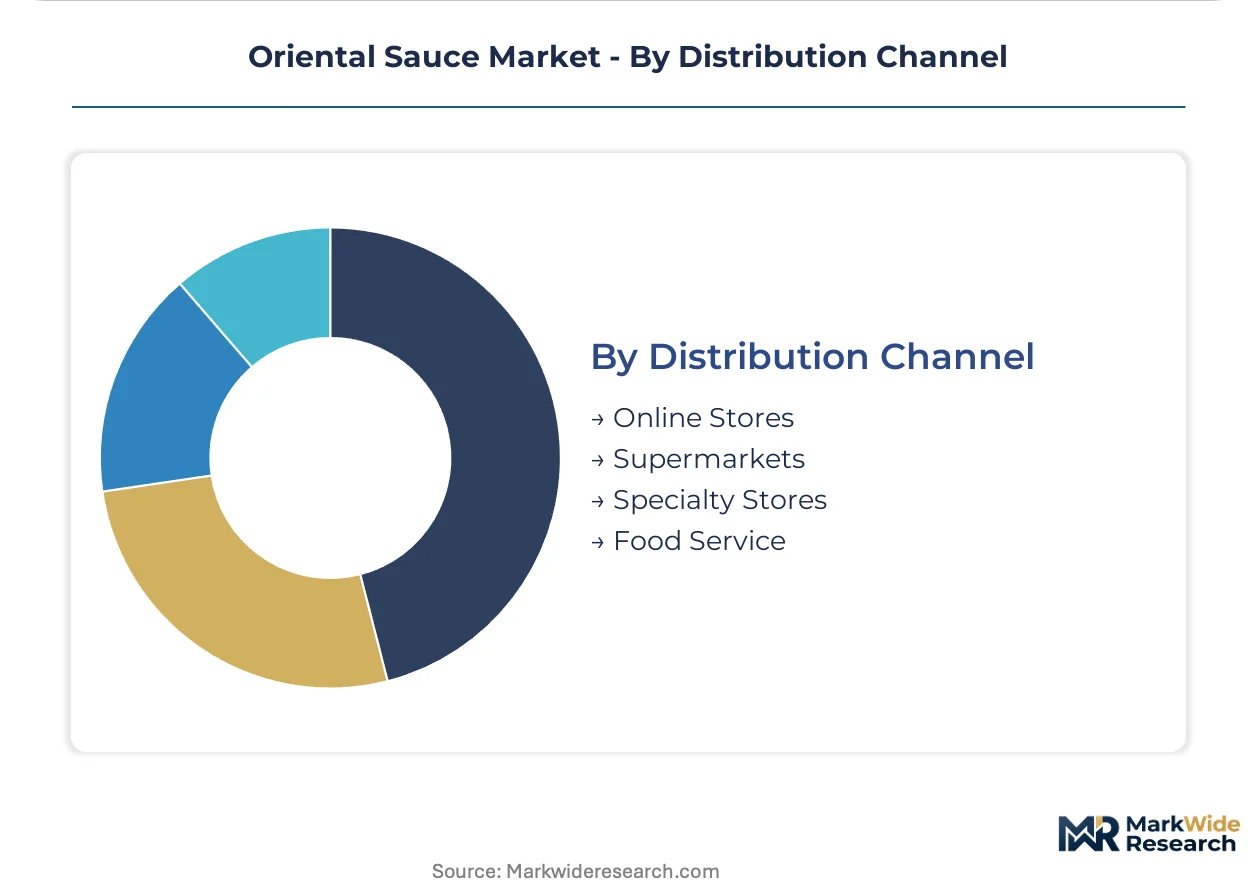
Distribution Channel:
Customer type and handling requirements fragment logistics architecture between temperature-controlled live-culture premiums and ambient-stable commodity flows.
- Food Service:Bulk drum and tote formats delivered through specialized Asian-ingredient importers with direct mill relationships. California and Texas Vietnamese restaurant clusters bypass broadline wholesalers for Phu Quoc and Phan Thiet fish sauce variants, forcing legacy distributors to add specialized SKUs or cede volume.
- Online Stores:Direct-to-pantry subscription models targeting diaspora households seeking authentic regional variants unavailable in conventional retail. This channel climbs fastest as digital platforms eliminate slotting fee barriers and enable micro-lot curation.
- Supermarkets:Mass retail placement requiring standardized packaging, barcode compliance, and trade promotion budgets.
- Specialty Stores:Curated shelf space in Asian grocery formats and gourmet food retailers, emphasizing provenance and small-batch credentials.
Food service channels dominate absolute tonnage. The most rapid expansion courses through online stores as subscription models capture diaspora authenticity demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong's Foshan-Shunde fermentation corridor concentrates over half of global soy sauce capacity, though EFSA contaminant thresholds and SAMR amino nitrogen grading now filter export eligibility and domestic tier consolidation.
China
Urban food service corridors in Ho Chi Minh City and Hanoi absorb bulk umami condiment volumes as Vietnamese quick-service chains expand. SAMR enforces GB standards for amino nitrogen content that determine shelf eligibility and premium positioning. The Foshan-Shunde cluster reconfigures capacity toward automated koji-making lines that cut batch-to-batch variation while meeting stricter discharge protocols.
Japan
Noda and Chiba Prefecture breweries leverage centuries-old brewing heritage to sustain price premiums in North American retail channels. METI carbon intensity targets push facilities toward anaerobic digestion and waste-heat recovery systems. Mid-cap producers retrofit legacy vat houses with NIR spectroscopy and AI-driven batch prediction, compressing quality control cycles from days to hours.
United States
Diaspora households in California and Texas drive direct-to-pantry subscription demand for authentic regional variants unavailable in conventional retail. FDA Food Safety Modernization Act import rules require foreign facility registration and hazard analysis, filtering smaller exporters from market access. Independent Vietnamese restaurants in Los Angeles and Houston bypass broadline wholesalers for container-direct arrangements with Phu Quoc producers.
South Korea
Low-acid fermentation certifications unlock European retail access as EFSA tightens 3-MCPD ester thresholds below 0.4 mg/kg. MFDS labeling requirements align with export market specifications, reducing parallel product run costs. Seoul-based importers consolidate procurement from certified Japanese and domestic facilities to serve European buyer requalification trends.
Vietnam
Phu Quoc and Phan Thiet fish sauce producers face channel disintermediation as diaspora restaurants in North America source through container-direct arrangements. The country's food safety authority enforces amino nitrogen and preservative standards that determine export eligibility. Urban food service network densification in Ho Chi Minh City concentrates bulk absorption for chain restaurant penetration.
Oriental Sauce Market Competitive Landscape
Heritage-positioned brewers and scale-driven commodity producers split the market along fermentation duration and certification tier lines. Consolidation pressure concentrates among mid-tier exporters lacking capital reserves for low-acid line retrofits. Three archetypes dominate: centuries-old Japanese brewing houses with experiential brand equity, Chinese automated volume leaders with backward integration into sugar refining, and diaspora-focused specialty importers with direct mill relationships. Competitive moves center on M&A for koji expertise acquisition and capacity expansion in certified low-acid corridors.
Within the heritage-tier, Kikkoman Corporation and Yamasa Corporation anchor positions through tacit brewing knowledge digitization and EFSA-compliant export certification. Lee Kum Kee and Foshan Haitian Flavouring & Food occupy scale-driven roles, with the former exemplifying backward integration into spice sourcing and the latter representing automated koji control deployment. These four names illustrate how geographic origin and organizational structure map onto divergent competitive vectors.
| Leading Market Players |
|---|
| Wan Ja Shan |
| Kimlan Foods |
| Kikkoman Corporation |
| Sempio Foods Company |
| Foshan Haitian Flavouring & Food |
| Lee Kum Kee |
| Pearl River Bridge |
| Jiajia Food Group |
| Yamasa Corporation |
| Others |
Value Network & Pricing Analysis
Guangdong's Foshan-Shunde fermentation corridor anchors over half of global soy sauce capacity, and its automated koji-making scale directly compresses per-unit costs for food service drum formats while squeezing margin recovery for smaller exporters lacking backward integration into sugar refining and spice sourcing.
Pricing Analysis
China's SAMR amino nitrogen grading system dictates the pricing tier structure across domestic and export markets, separating premium first-grade brews from standard and economy tiers through measurable quality differentiation. Gluten-free certification adds 15-20% cost premiums as dedicated koji rooms and third-party testing protocols segregate production lines. Pricing pressure stems from soybean input cost volatility transmitting through crush margin compression, particularly squeezing mid-tier producers without captive crushing assets. Food service buyers exhibit highest price sensitivity due to bulk volume procurement, while diaspora subscription channels tolerate premium positioning for authentic regional variants unavailable in conventional retail.
Supply Chain Analysis
EFSA's tightening 3-MCPD ester thresholds below 0.4 mg/kg function as de facto export controls limiting conventional acid-hydrolyzed flows into European retail. Supply concentrates in China's Guangdong corridor, Japan's Chiba and Noda prefectures, and Vietnam's Phu Quoc-Phan Thiet fish sauce clusters. Raw material dependencies rest on South American soybean crush output, wheat sourcing from Black Sea and North American origins, and oyster extract from Cantonese coastal aquaculture. Single-source vulnerability runs through the Foshan-Shunde cluster's exposure to regional energy rationing or water discharge enforcement. Distribution runs through specialized Asian-ingredient importers with direct mill relationships, bypassing legacy broadline wholesalers in diaspora-dense metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Traditional koji-making expertise concentrated among aging practitioners in Japan's Noda and China's Foshan regions faces transfer failures as automated systems displace apprentice pipelines, creating a structural capability gap that rewards early digitization investments and erodes wage premiums for experiential craft knowledge.
For Market Incumbents: Insulate core fermentation capacity by acquiring distressed mid-tier breweries in certified low-acid corridors before EFSA thresholds fully filter conventional exporters from European shelf access. Deploy anaerobic digestion and waste-heat recovery systems to capture China's MEE carbon intensity compliance advantages and defend margin position against energy cost volatility. For New Entrants and Emerging Players: Build out direct-to-pantry subscription infrastructure targeting Vietnamese and Chinese diaspora households in California and Texas, where authenticity signaling outweighs procurement convenience and digital platforms eliminate conventional retail slotting fee barriers. Prioritize gluten-free certification to capture supply-scarcity pricing power in celiac-sensitive household segments. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because mid-tier exporters lacking capital reserves for low-acid line retrofits face compressed market access and distressed valuation entry points. Target acquisition profiles center on Japanese and Korean facilities with established EFSA-compliant certifications and sensor-networked koji propagation rooms. The signal to watch is divergent contaminant threshold enforcement between FDA, EFSA, and SAMR jurisdictions forcing parallel product run costs that fragment production scale economies.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Acid Fermentation Retrofit | EFSA-compliant certification unlocks European retail shelf access previously filtered from conventional exporters. |
| Automated Koji Control Deployment | NIR spectroscopy and AI-driven batch prediction compress quality control cycles from days to hours. |
| Diaspora Direct-to-Pantry Launch | Subscription models bypass broadline wholesalers and capture authentic regional variant demand in North America. |
| Backward Integration into Sugar Refining | Lee Kum Kee's model anchors Cantonese-style oyster sauce cost control through captive supply. |
| Carbon-Intensity Compliance Investment | MEE targets create first-mover advantage for breweries deploying anaerobic digestion systems. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fermentation plant managers, food service procurement leads at Asian restaurant chains, retail category buyers, and regulatory affairs specialists at export-oriented breweries. Secondary validation drew from SAMR GB standard filings, EFSA contaminant evaluation reports, FDA Food Safety Modernization Act facility registration databases, and customs trade flow records. Bottom-up volume triangulation across production facility capacities was cross-checked against top-down demand modeling across food service, online, and retail channels.
Calibration against historical amino nitrogen grading shifts and EFSA threshold implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, use case, ingredient certification tier, and distribution channel, with geographic regulatory cluster as an additional industry-specific dimension. CAGRs were derived from growth rate convergence analysis across these segments. Forecast inputs incorporated soybean crush margin trajectories and diaspora household formation patterns in North American metropolitan corridors.
Stress conditions across South American weather variability, energy rationing severity in Guangdong, and EFSA 3-MCPD threshold enforcement pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on fermentation technology adoption curves and channel disintermediation velocity. Material shifts in SAMR amino nitrogen grading stringency or MEE carbon intensity compliance deadlines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Cocktail Syrups Market
Condiments & Sauces
Hot Sauce Market
Condiments & Sauces
West Africa Mayonnaise Market
Condiments & Sauces
Asia Pacific Fish Sauce Market
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Low Fat Pasta Sauce Market
Condiments & Sauces
Salad Dressings Market
Condiments & Sauces
United States Pasta Sauce Market
Condiments & Sauces
Mayonnaise Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Sandwich Spread Market
Condiments & Sauces
Dipping Sauces Market
Condiments & Sauces
Fat Free Salad Dressings Market
Condiments & Sauces
Low Fat Spaghetti Sauce Market
Condiments & Sauces
Europe Pasta Sauce Market
Condiments & Sauces
Mayonnaise Sauce Market