

High Performance Epoxy Coating Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Epoxy Coating Market Insights
REACH is pivoting the cost-of-entry calculus for European suppliers toward compliant low-VOC formulations. AkzoNobel leverages its marine coatings heritage to dominate Nordic offshore markets. PPG sustains R&D intensity across ambient-cure technologies for field-applied infrastructure. Hempel A/S anchors its position through backward integration into resin supply chains.
High performance epoxy coatings comprise cross-linked thermoset polymers formed from epichlorohydrin and bisphenol-A or novolac precursors, cured via amine or polyamide hardeners to achieve chemical resistance above 200°C service temperatures. These systems protect steel substrates from corrosion in immersion and chemical-exposure environments. Water-based formulations are gaining fastest among product types as environmental compliance tightens across industrialized economies. Marine equipment and oil and gas infrastructure applications command the deepest margin pools due to specification intensity and recoat cycles. Powder coatings occupy a mature trajectory in factory-controlled settings where electrostatic application dominates.
EPA standards in the United States restrict volatile organic compound emissions from industrial maintenance coatings, redirecting procurement toward compliant water-based and high-solids alternatives. ECHA enforces REACH registration and SVHC restrictions that reshape raw material sourcing across European supply chains. China's MEE implements dual carbon goals that tighten manufacturing emissions benchmarks for coating production. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation investments and misaligned capacity.
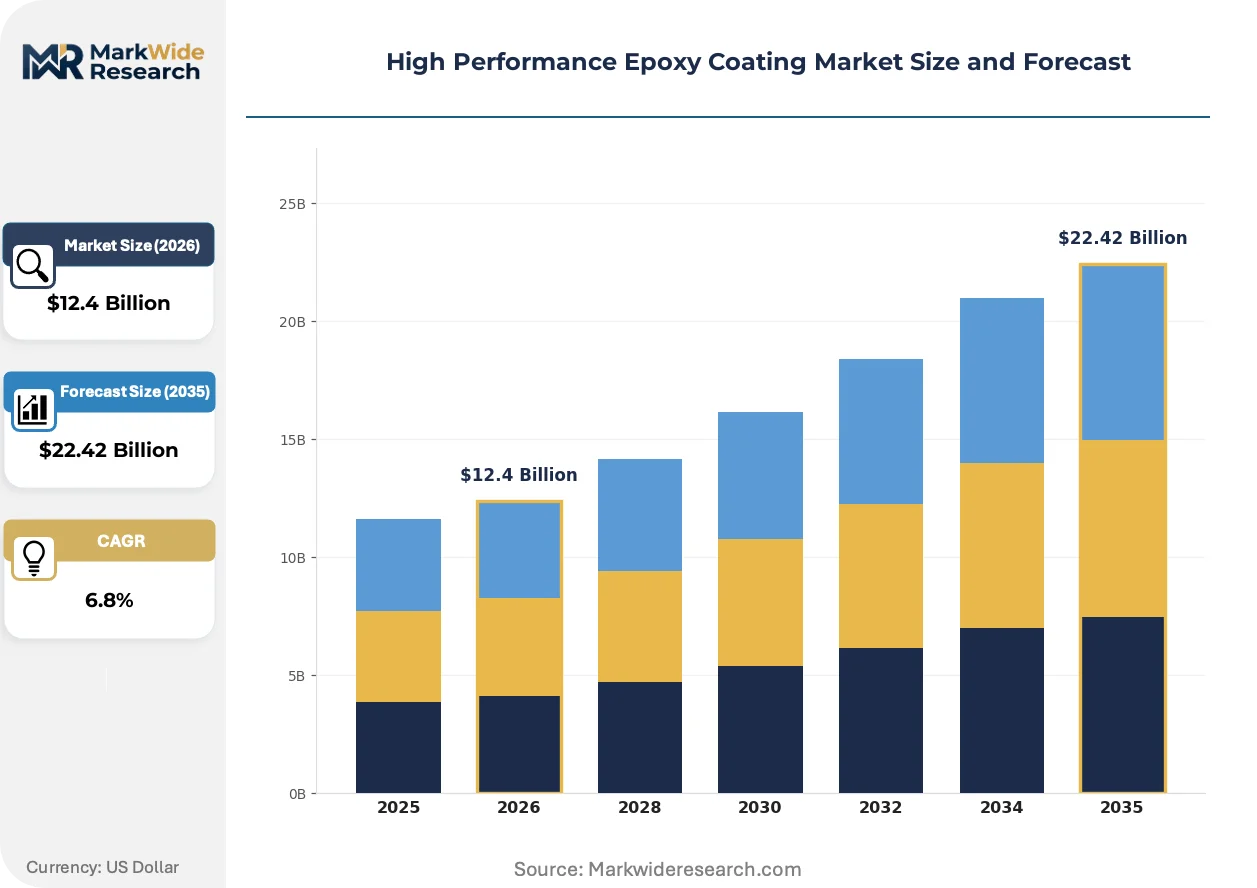
Market Dynamics
REACH compliance is forcing European formulators to abandon solvent-borne systems entirely, while China's coastal manufacturing corridors absorb capacity shifts from shuttered European lines. This regulatory divergence is compressing margins for non-compliant suppliers and rewarding early movers in water-based resin chemistry.
Growth Catalysts
- Offshore platform corrosion cycles:North Sea and Gulf of Mexico operators face accelerated recoat schedules due to harsher immersion conditions, driving specification intensity for amine-cured novolac systems.
- EPA industrial maintenance standards:The agency's VOC emission limits redirect procurement toward high-solids and water-based alternatives in US refinery and petrochemical maintenance.
- Dual carbon goals in China:MEE manufacturing emissions benchmarks force domestic producers toward cleaner curing technologies, opening import substitution windows for compliant foreign suppliers.
Market Restraints
- Epichlorohydrin supply concentration:Chinese and Middle Eastern producers control upstream bisphenol-A and epichlorohydrin feedstock, exposing coating formulators to petrochemical price volatility.
- REACH SVHC registration timelines:ECHA's substance evaluation delays new hardener chemistries by 18-36 months, freezing formulation pipelines for European suppliers.
- Polyurea spray displacement:Fast-set polyurea systems capture secondary containment and flooring applications where rapid return-to-service trumps epoxy durability.
Strategic Opportunities
- India's coastal infrastructure buildout:Jawaharlal Nehru Port and Mundra Port expansions create specification windows for immersion-grade systems in tank farm and jetty applications.
- Electrostatic powder convergence:Factory-applied powder epoxies penetrate pipeline coating shops as fusion-bonded epoxy specifications tighten for sour gas service.
- EU Green Deal public procurement:Green public procurement criteria favor low-VOC coating systems in municipal water infrastructure tenders across Germany, Netherlands, and Denmark.
Industry Challenges
- NACE coating inspector certification scarcity:Qualified inspectors for offshore asset condition assessment command premium wages, constraining project velocity in Nordic markets.
- Legacy solvent-borne inventory stranding:Distributors face write-downs on non-compliant stock as regional VOC deadlines accelerate, forcing working capital reallocation.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Epoxy Coating Market Trends and Innovations
Water-based curing technologies are displacing conventional solvent carriers across immersion-grade applications, while digital specification tools compress the engineer-to-contractor decision chain. These shifts favor formulators with captive resin synthesis and certified application training networks.
Bio-based epichlorohydrin from glycerol feedstock is rewriting raw material sourcing strategies for sustainability-mandated projects. Marine OEMs in Northern Europe specify these systems for newbuild vessels. The chemistry is compressing the carbon intensity gap between petrochemical and renewable feedstock routes.
REACH authorization requirements for bisphenol-A are tightening industrial coating formulations across German and Dutch manufacturing. ECHA's sunset date enforcement is accelerating hardener substitutions toward novolac and aliphatic amine alternatives. Water-based epoxy primers for tank linings face the steepest compliance timeline pressure.
Asset owner engineering teams now specify coating systems through integrated digital platforms rather than traditional distributor relationships. Engineering-procurement-construction firms in the US Gulf Coast consolidate vendor lists to three approved suppliers per chemistry type. This concentration rewards formulators with API-certified quality management and embedded technical service teams.
High Performance Epoxy Coating Market Segmentation
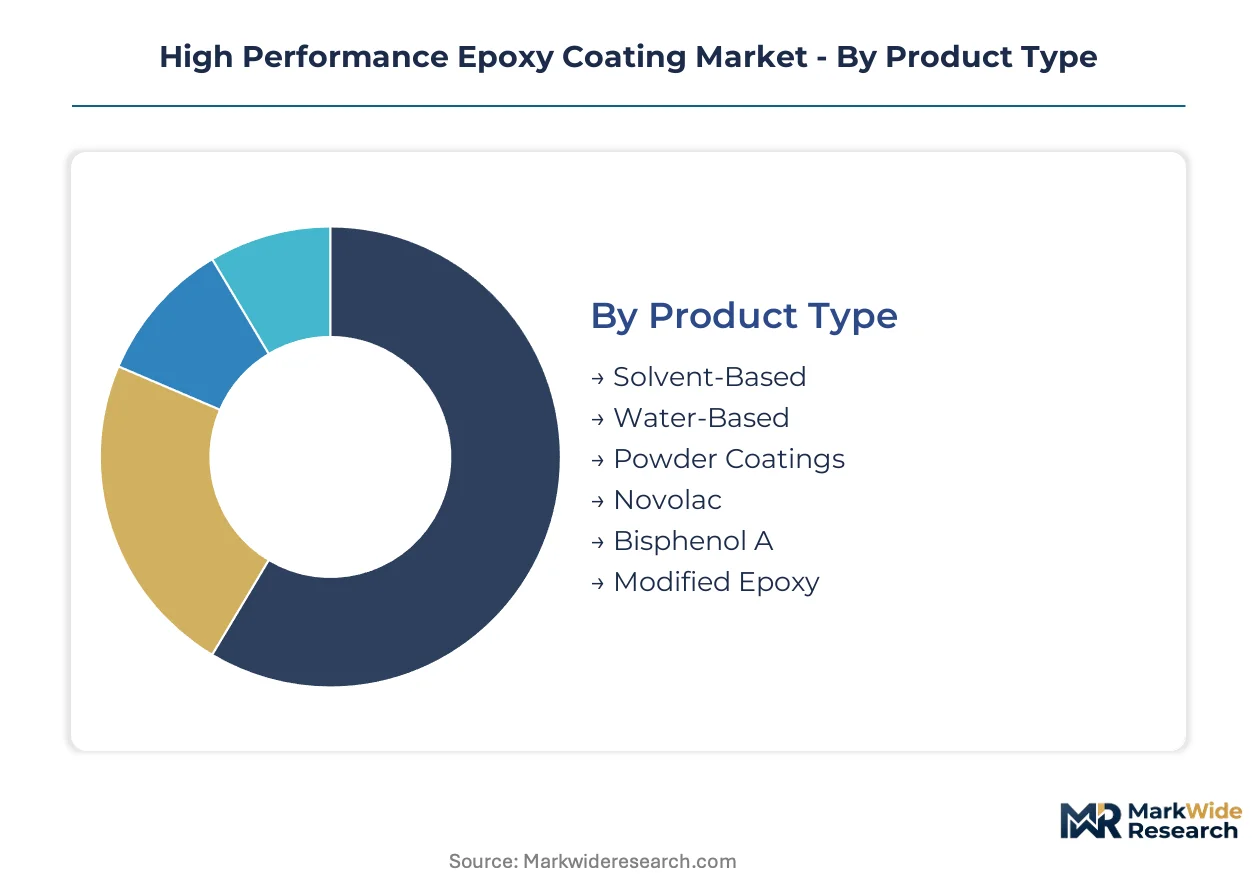
Segmentation in high performance epoxy coatings reveals how specification intensity, cure chemistry, and regulatory compliance reshape procurement patterns across asset-intensive industries. Buyers prioritize corrosion resistance ratings, VOC compliance thresholds, and recoat cycle economics over unit price.
Product Type:
Cost tier determines specification authority — premium systems command engineer-led selection while commodity grades flow through distributor channels.
- Water-Based:These systems employ aqueous resin dispersions with amine hardeners to achieve sub-100 g/L VOC content. Demand concentrates in German municipal water infrastructure and US Gulf Coast refinery maintenance where EPA and REACH deadlines force solvent displacement.
- Solvent-Based:Conventional aromatic hydrocarbon carriers deliver maximum film build and substrate wetting for immersion service. Volume sits with legacy offshore platforms in the North Sea and Gulf of Mexico where recoat windows tolerate longer cure schedules.
- Powder Coatings:Thermoset powders achieve zero VOC emissions through electrostatic application and oven fusion. Factory-controlled pipeline coating shops in Texas and Alberta specify these for fusion-bonded epoxy under API standards.
- Novolac:Phenolic-modified epoxies provide superior chemical resistance against acids and solvents at elevated temperatures. Chemical processing facilities in Louisiana and Rotterdam specify novolac tank linings for sulfuric acid service.
- Bispol A:Standard diglycidyl ether resins balance cost and performance for general industrial protection. Widely specified for structural steel in commercial construction and light manufacturing.
- Modified Epoxy:Hybrid formulations incorporate polyurethane or acrylic segments to improve flexibility and weathering. Bridge deck and exterior infrastructure applications in coastal Japan favor these systems.
Volume sits with Solvent-Based formulations; growth tilts toward Water-Based systems.
Application:
Application context dictates cure chemistry selection — immersion service demands novolac amine systems while atmospheric exposure permits ambient-cure alternatives.
- Oil & Gas Infrastructure:Offshore platforms, subsea pipelines, and refinery vessels require immersion-grade protection against sour gas and produced water. Norwegian North Sea operators and US Gulf independents drive specification intensity for amine-cured novolac systems with 25-year design life.
- Marine Equipment:Ballast tanks, cargo holds, and deck structures face cyclic wet-dry exposure and mechanical abrasion. Korean and Chinese shipyards specify these coatings for newbuild vessels under IMO PSPC standards.
- Chemical Processing Plants:Reactors, storage vessels, and secondary containment demand resistance to aggressive acids, caustics, and solvents. German and Dutch chemical clusters specify high-functionality novolac systems.
- Construction Materials:Structural steel, rebar, and concrete reinforcement require atmospheric corrosion protection with UV resistance. Infrastructure buildouts in India and Vietnam absorb volume for standard bisphenol-A epoxies.
- Aerospace Components:Fuel tank sealants and composite primers demand low-outgassing, high-temperature performance. US and French aerospace OEMs specify qualified products under AMS specifications.
- Electronics Protection:Potting compounds and conformal coatings insulate circuit boards from moisture and thermal cycling. Electronics manufacturing in Taiwan and South Korea drives demand for low-viscosity formulations.
Specification intensity clusters in Oil & Gas Infrastructure; fastest expansion occurs in Marine Equipment as fleet renewal accelerates.
End User:
Customer type determines technical service requirements — asset owners demand embedded inspection support while fabricators prioritize throughput and price.
- Industrial Plants:Refineries, chemical complexes, and power stations operate in-house maintenance teams with NACE-certified inspectors. These buyers specify coating systems directly and demand 24-hour technical response.
- Maintenance Contractors:Third-party turnaround and repair specialists execute recoat campaigns during scheduled outages. US Gulf Coast and Singapore-based contractors consolidate vendor lists to three approved suppliers per chemistry.
- Fabricators:Steel structure and vessel manufacturers apply coatings in shop conditions before field erection. Mexican and Polish fabricators serve North American and European project markets respectively.
- Equipment Manufacturers:Pump, valve, and heat exchanger OEMs specify coatings for new equipment corrosion protection. German and Italian machinery builders integrate coating specifications into procurement standards.
- Fabrication Workshops:Small-scale metalworkers apply standard epoxy primers and topcoats for commercial and light industrial projects. Price-sensitive demand concentrates in Southeast Asian supply chains.
- Assembly Units:Modular construction and prefabrication facilities apply coatings to standardized components before site delivery. Growing segment in UAE and Saudi infrastructure projects.
Procurement authority rests with Industrial Plants; Maintenance Contractors show steepest growth as asset owners outsource turnaround execution.
Technology:
Cure mechanism determines capital requirements and field applicability — heat-cure systems demand oven infrastructure while ambient technologies enable in-situ application.
- Ambient Cure:Polyamine and polyamide hardeners react at temperatures above 10°C without external heating. Field-applied maintenance coatings in Alaska, North Sea, and Siberian pipelines rely exclusively on ambient-cure chemistry.
- Heat Cure:Elevated temperature acceleration achieves full chemical resistance in hours rather than days. Shop-applied vessel linings and powder coating operations in Germany and Japan require batch oven infrastructure.
- Powder Coating:Electrostatic spray deposition with subsequent oven fusion eliminates solvent handling. Pipeline coating facilities in Alberta and Texas operate continuous fusion-bonded epoxy lines.
- UV Cure:Photoinitiator-triggered polymerization enables instant handling for thin-film applications. Electronics and optical coating applications in South Korea and Taiwan employ UV-cure epoxies.
- Electrostatic Spray:Charged particle deposition maximizes transfer efficiency for liquid coatings in factory settings. Automotive and appliance manufacturing in Mexico and Eastern Europe specify this application method.
- Flameless Spray:Plural-component heated spray systems deliver high-build films without solvent flash hazards. Offshore platform maintenance contractors in the Gulf of Mexico favor this technology for live-plant application.
Deployment breadth favors Ambient Cure; technology transition accelerates toward Powder Coating as environmental compliance tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal manufacturing corridors concentrate capacity expansion, with bonded zones in Ningbo and Qingdao offering VAT rebates that attract coating formulation investments from multinational suppliers.
United States
Gulf Coast petrochemical complexes drive specification intensity for immersion-grade systems. EPA industrial maintenance standards redirect procurement toward high-solids alternatives. Houston and Corpus Christi anchor demand for amine-cured novolac tank linings in refinery turnarounds.
Germany
Chemical processing clusters in North Rhine-Westphalia specify high-functionality novolac systems for acid service. REACH authorization timelines for bisphenol-A accelerate hardener substitutions. The Port of Rotterdam hinterland absorbs compliant water-based formulations for tank farm infrastructure.
China
Dual carbon goals from MEE tighten manufacturing emissions benchmarks for domestic producers. Yangtze River Delta shipyards specify marine coatings under IMO PSPC standards. Qingdao and Dalian anchor capacity shifts from shuttered European solvent-borne lines.
Norway
North Sea offshore operators face accelerated recoat schedules due to harsher immersion conditions. ECHA SVHC restrictions reshape raw material sourcing across Nordic supply chains. Stavanger and Bergen concentrate specification authority for 25-year design life systems.
India
Jawaharlal Nehru Port and Mundra Port expansions create specification windows for immersion-grade applications. Central Pollution Control Board emissions norms tighten for coating manufacturing. Gujarat's coastal industrial belt attracts import substitution from compliant foreign suppliers.
High Performance Epoxy Coating Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers. The vendor base stratifies into three tiers: integrated petrochemical giants with captive resin supply, regional coating specialists with certified application networks, and commodity blenders serving price-sensitive fabrication workshops. Consolidation pressures concentrate among mid-scale European formulators facing REACH compliance cost escalation. Dominant competitive moves include backward integration into epoxy resin synthesis and geographic expansion into India's coastal infrastructure buildout.
Among diversified chemical conglomerates, BASF exemplifies scale-driven positioning through petrochemical integration. AkzoNobel and PPG occupy positions within the premium marine and industrial maintenance tiers, leveraging heritage specifications in Nordic offshore and US Gulf Coast markets respectively. These three anchors represent distinct competitive archetypes: feedstock-integrated supply security, specification-led marine dominance, and R&D-intensive ambient-cure technology leadership.
| Leading Market Players |
|---|
| AkzoNobel |
| PPG |
| Hempel A/S |
| Nippon Paint Holdings |
| Jotun |
| Axalta Coating Systems |
| BASF |
| The Sherwin-Williams Company |
| Kansai Paint |
| Others |
Pricing and Supply Chain Analysis
Water-based resin chemistry adoption simultaneously compresses production costs for compliant formulators and concentrates supply authority among producers with captive aqueous dispersion capabilities. This dual effect rewards early movers in low-VOC formulation while marginalizing distributors holding legacy solvent-borne inventory.
Pricing Analysis
Short lead-time premiums command substantial markups in offshore platform maintenance windows where recoat schedules tolerate no delay. Three-tier pricing structure across certified immersion-grade, standard industrial, and commodity shop-applied tiers reflects specification intensity and certification grade. Cost compression in commodity bisphenol-A formulations is intensifying because Chinese coastal producers absorb capacity shifts from shuttered European lines. Maintenance contractors in the US Gulf Coast prove least price-sensitive due to consolidated vendor lists and penalty clauses for coating failure.
Supply Chain Analysis
Domestic-content mandates in India's Jawaharlal Nehru Port and Mundra Port expansions are reshaping sourcing toward local formulation partnerships. Feedstock concentration centers on Chinese and Middle Eastern producers of epichlorohydrin and bisphenol-A, with German and Dutch chemical clusters providing specialty novolac hardeners. Single-source vulnerability in amine hardener supply exposes European formulators to ECHA SVHC evaluation delays. Distribution runs through API-certified technical service networks for asset owner direct procurement, and through consolidated distributor channels for fabrication workshop spot buying.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over epoxy resin synthesis determines margin capture. Players are pursuing backward integration into feedstock supply to defend against petrochemical price volatility.
For Market Incumbents: Deepen captive resin production capabilities to offset epichlorohydrin supply concentration risk. Secure NACE-certified inspector training networks before qualified assessor scarcity constrains project velocity in Nordic offshore markets. Acquire distressed mid-scale European formulators facing REACH compliance cost escalation to consolidate specification authority. For New Entrants and Emerging Players: Digital specification platforms offer a direct route to bypass entrenched distributor relationships and access asset owner engineering teams. Target India's coastal infrastructure buildout as the most penetrable geography given import substitution windows from Central Pollution Control Board emissions tightening. Lead with water-based immersion-grade formulations certified for municipal water infrastructure tenders. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified chemical conglomerates seeking marine coatings capabilities. Long-term viability favors formulators with demonstrated REACH compliance and established API-certified quality management. Watch for ECHA bisphenol-A authorization sunset enforcement as the inflection signal accelerating hardener substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Hempel A/S anchors Nordic offshore market position through captive epoxy resin production. |
| Water-Based Formulation Transition | AkzoNobel leverages marine heritage to dominate German municipal water infrastructure tenders. |
| NACE Certification Network Expansion | PPG sustains US Gulf Coast project velocity through embedded inspector training programs. |
| India Coastal Infrastructure Partnership | Compliant foreign suppliers capture Jawaharlal Nehru Port tank farm specification windows. |
| Digital Specification Platform Deployment | Engineering-procurement-construction firms consolidate vendor lists to three approved suppliers per chemistry. |
Research Methodology
Independent corroboration across plant managers at coating formulation facilities, procurement leads at downstream oil and gas operators, distribution channel partners, and technical R&D directors underwrites the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and API specification documentation. Bottom-up demand modeling triangulates against top-down petrochemical feedstock consumption patterns.
Rate-of-change decomposition separates volume growth from value expansion across product type, application context, cure technology, and regional regulatory cluster dimensions. CAGRs derive from modeled segment trajectories over the projection horizon. Forecast inputs incorporate ECHA SVHC evaluation timelines, EPA industrial maintenance standard enforcement phases, and MEE dual carbon goal implementation benchmarks.
The model holds under stable petrochemical feedstock pricing and regulatory deadline adherence; deviation in epichlorohydrin supply disruption or accelerated REACH sunset dates would shift formulation economics and capacity relocation patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.