
 Canada Floor Coatings Market | 2026-2036
Canada Floor Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Floor Coatings Market Outlook
Subscription-based coating maintenance programs is restructuring how Canadian facility managers procure floor protection, shifting capital expenditure into operational budgets. RPM International Inc. anchors this transition through service-contract bundling across industrial accounts. PPG Industries Inc. leverages its distribution network to dominate specification-driven commercial projects in Ontario and Quebec. The Sherwin-Williams Company differentiates via color-matching software that tightens contractor loyalty in retail and automotive segments.
Canada floor coatings comprise resin-based protective layers—epoxy, polyurethane, acrylic, or polyaspartic systems—typically applied at 10–250 mils dry film thickness to concrete substrates for chemical resistance, abrasion protection, and aesthetic finish in commercial and industrial environments. Epoxy formulations retain the largest volume share due to their cost-performance balance in manufacturing settings, though polyaspartic systems are gaining specification share where rapid return-to-service drives project economics. Water-based formulations are outpacing solvent-based alternatives in residential and light-commercial applications as VOC compliance tightens across provincial building codes. Contractors and facility managers represent the most concentrated demand channel, with procurement consolidating toward approved-vendor lists that privilege technical service capabilities over unit pricing.
Health Canada's PMRA regulates biocide content in antimicrobial floor coatings, while the Canadian Environmental Protection Act governs VOC emissions that directly constrain solvent-based product formulations. Provincial regulators in Ontario and British Columbia enforce additional workplace exposure limits that elevate demand for low-odor, water-based systems in occupied facilities. Stakeholders must monitor evolving federal chemical management priorities and provincial green building standards to anticipate specification shifts before they cascade through contractor purchasing behavior.
Market Dynamics
Health Canada's PMRA is tightening volatile organic compound limits under the Canadian Environmental Protection Act, forcing manufacturers to abandon solvent-based formulations and rebuild supply chains around water-based resin systems. This regulatory compression is redrawing competitive boundaries between incumbent coating suppliers and specialty chemical entrants.
Growth Catalysts
- Ontario Manufacturing Corridor Refurbishment Cycles:Industrial facilities in Hamilton, Windsor, and Kitchener-Waterloo are compressing floor recoating intervals from seven years to four years. This demand concentration is pulling epoxy and polyurethane volumes upward.
- Polyaspartic Technology Maturation:Rapid-cure polyaspartic systems are penetrating automotive assembly plants and cold-storage warehouses where 24-hour return-to-service justifies premium formulation costs.
- Green Building Standards:Toronto and Vancouver municipal codes are mandating low-VOC materials in commercial construction. LEED v4.1 compliance is becoming a specification gatekeeper for new build projects.
Market Restraints
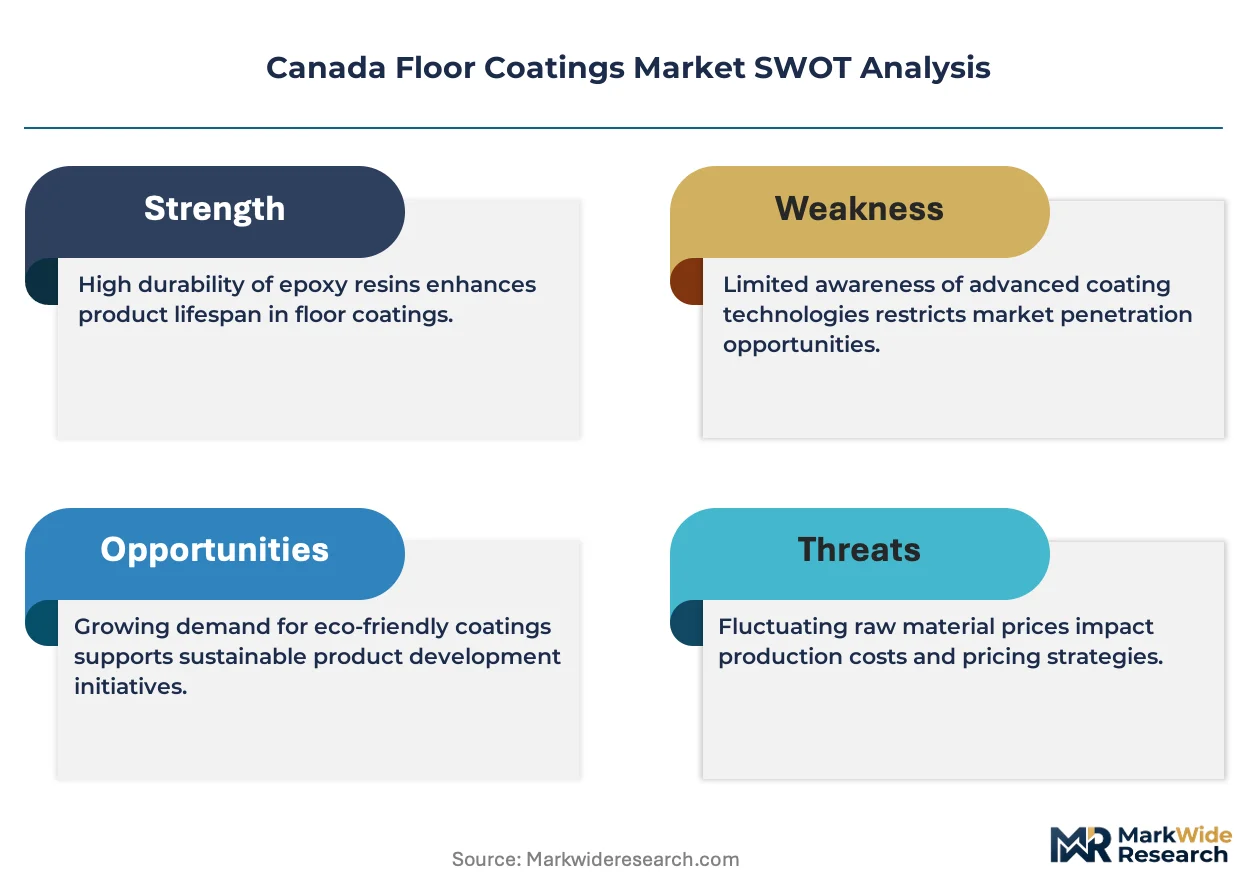
- Petrochemical Feedstock Volatility:Epoxy resin prices fluctuate with benzene and propylene markets. Canadian formulators lack backward integration into basic chemicals, exposing margins to Gulf Coast refinery outages.
- Specialty Contractor Concentration:Certified applicators for high-performance systems cluster in Toronto, Montreal, and Calgary. Smaller markets face 6-8 week project backlogs during peak construction seasons.
- Cure Temperature Limitations:Water-based epoxies require minimum 10°C substrate temperatures. This technical constraint shuts down outdoor and unheated industrial applications across Prairie provinces for 4-5 months annually.
Strategic Opportunities
- Atlantic Canada Infrastructure Renewal:Halifax and St. John's port modernization programs are specifying heavy-duty coatings for marine-terminal floors. This geography remains underpenetrated by national distributors.
- Antimicrobial Formulation Demand:Healthcare facilities in Quebec and Ontario are specifying silver-ion or copper-additive coatings. Health Canada PMRA biocide registration creates first-mover advantages for compliant suppliers.
- Subscription Maintenance Programs:Facility management firms are bundling coating reapplication into multi-year service contracts. This channel innovation converts capital expenditure into predictable operational budgets.
Industry Challenges
- Certified Applicator Shortage:Moisture-tolerant epoxy and polyaspartic systems require specialized surface preparation training. The gap between certified technicians and project demand is widening in secondary markets.
- Cross-Provincial Compliance Complexity:British Columbia's workplace exposure limits for isocyanates are stricter than federal guidelines. Formulators must maintain parallel product SKUs or reformulate for provincial distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Floor Coatings Market |
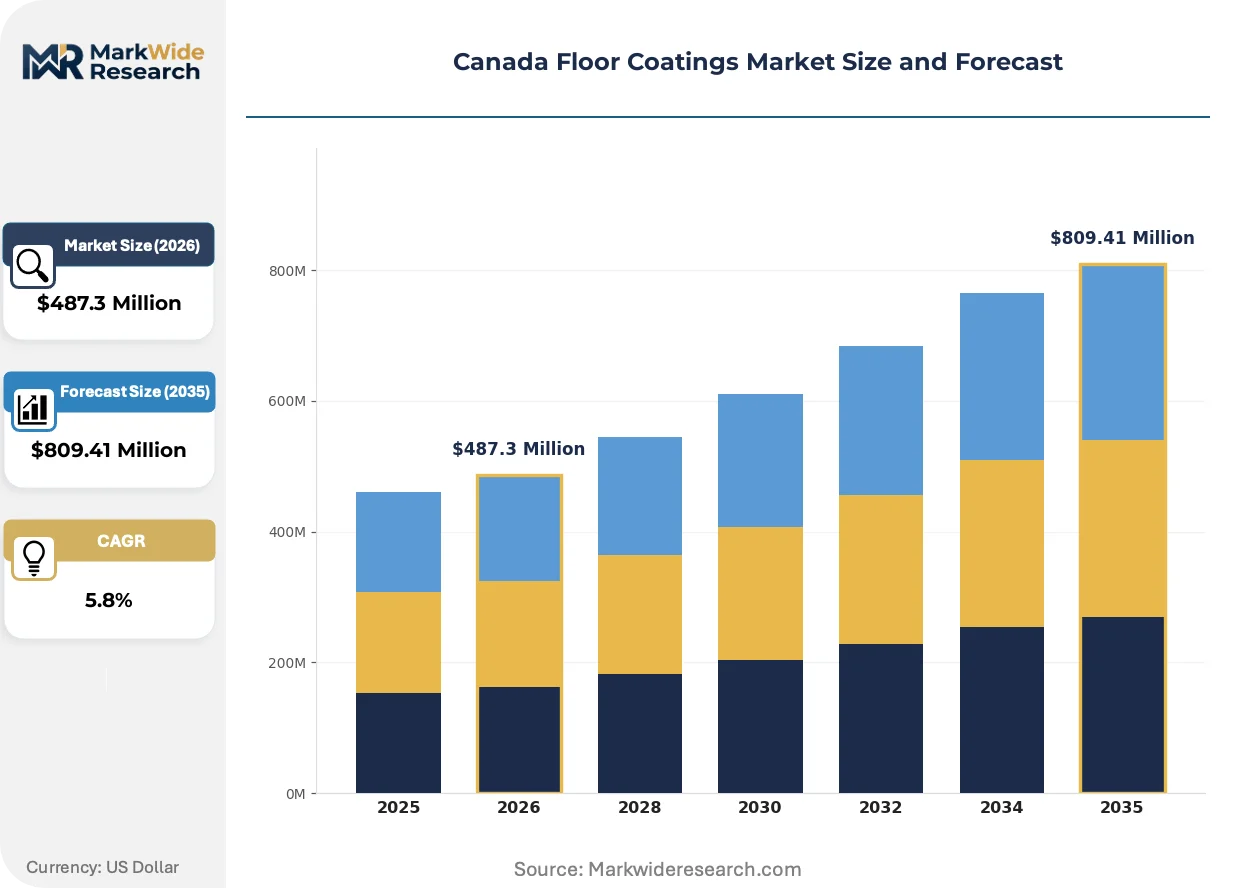
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Polyaspartic Application: Commercial, Industrial, Residential, Automotive Form: Liquid, Powder, Solvent-Based, Water-Based End User: Manufacturers, Retailers, Contractors, Facility Managers |
| Companies Covered | RPM International Inc, BASF SE, The Sherwin-Williams Company, Teknos Group, Jotun, PPG Industries Inc., AkzoNobel NV, LATICRETE INTERNATIONAL INC., Sika AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Floor Coatings Market Strategic Shifts
Formulation chemistry and application methods are converging around speed, sustainability, and service integration. Manufacturers are racing to compress cure cycles while eliminating hazardous air pollutants from resin systems.
Polyaspartic aliphatic polyurea technology is electrifying project economics in time-sensitive environments. These systems achieve full cure in 6-8 hours versus 72 hours for conventional epoxies. Automotive manufacturers in Oshawa and Alliston are specifying polyaspartic topcoats for assembly line floors to minimize production downtime. The technology is electrifying contractor bidding behavior, compressing project timelines from weeks to days and reshaping labor cost calculations.
Health Canada's PMRA is accelerating VOC regulatory timelines under the Canadian Environmental Protection Act. The 2025 proposed amendments would slash allowable solvent content in architectural coatings by 25 percent from current limits. Industrial formulators are responding by shifting R&D investment toward waterborne epoxy dispersions and hybrid acrylic-urethane systems. Ontario-based manufacturers face the steepest compliance curve due to the province's concentration of heavy-duty industrial demand.
Facility managers in Toronto and Vancouver are consolidating vendor relationships around technical service capabilities rather than unit pricing. Approved-vendor lists now privilege contractors with moisture-testing equipment, warranty-backed installation, and predictive maintenance software. This buyer behavior shift is squeezing independent applicators without capital for diagnostic tooling. The trend is most visible in retail and food-processing verticals where floor failure carries operational liability.
Canada Floor Coatings Market Segmentation
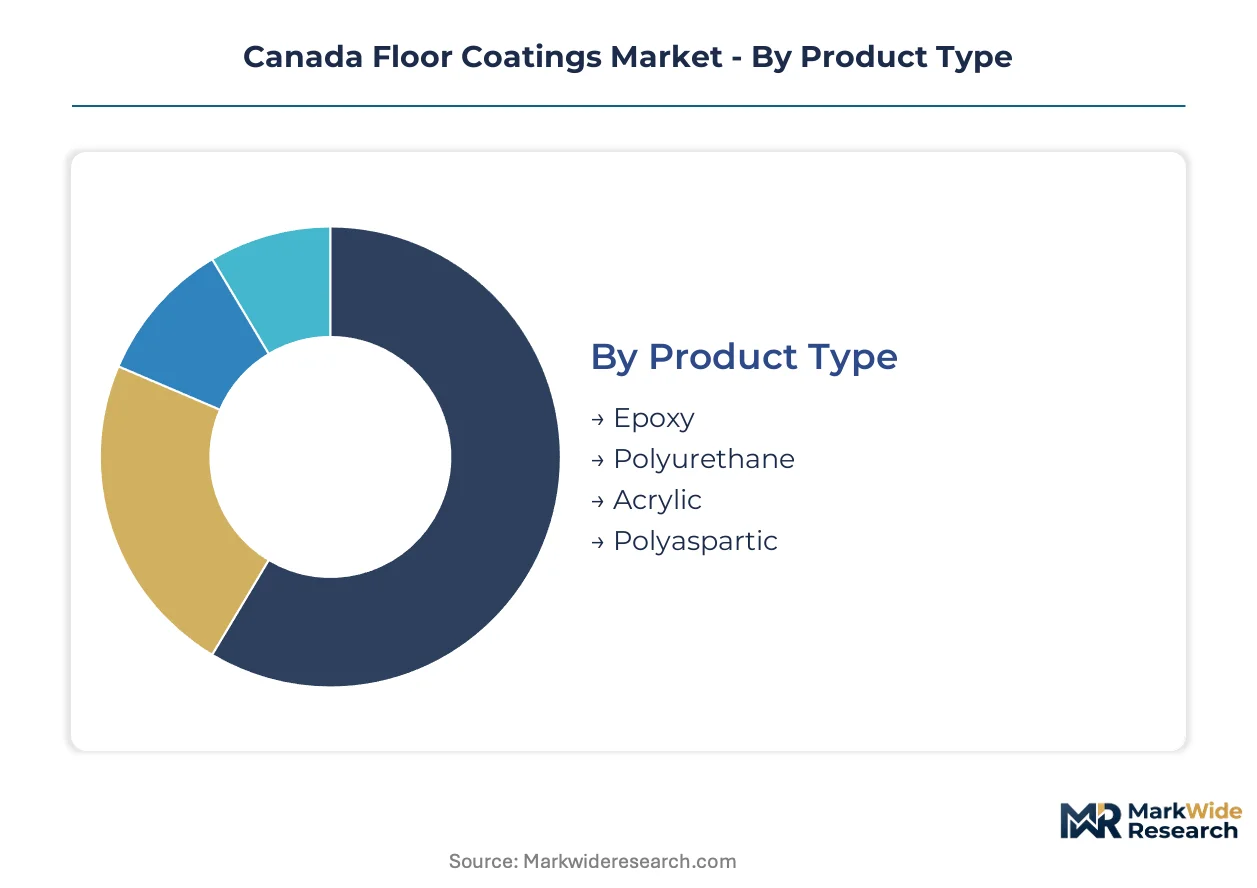
Floor coatings in Canada stratify across resin chemistry, application environment, and procurement channel. Each dimension governs specification behavior, regulatory exposure, and margin structure differently across the country's industrial corridors.
Product Type:
Epoxy systems function as standalone heavy-duty protection in manufacturing floors, while polyurethane and acrylic formulations embed as topcoat layers over base systems.
- Epoxy:Two-part thermosetting systems deliver chemical resistance and compressive strength at 10-250 mils thickness. Demand concentrates in Ontario's manufacturing corridor where automotive and food processing facilities specify solvent-free novolac variants for acid resistance. Refurbishment cycles compressing from seven to four years pull volume upward in Hamilton and Windsor industrial parks.
- Polyurethane:Aliphatic and aromatic formulations provide UV stability and abrasion resistance as topcoats over epoxy primers. Toronto and Vancouver commercial builders specify these for retail and office lobbies where aesthetic retention matters. Health Canada PMRA VOC limits are accelerating waterborne polyurethane R&D among domestic formulators.
- Acrylic:Single-component waterborne systems serve light-duty commercial and residential applications with lower capital cost. Quebec contractors favor these for occupied facility renovations where odor minimization drives specification.
- Polyaspartic:Rapid-cure aliphatic polyurea technology achieves full cure in 6-8 hours versus 72 hours for conventional epoxies. Oshawa automotive assembly plants and Calgary cold-storage warehouses specify these where production downtime carries steep economic penalties.
Volume placements concentrate in epoxy systems; the faster expansion belongs to polyaspartic formulations.
Application:
Cost tiers separate capital-intensive industrial specifications from operational-budget commercial maintenance and discretionary residential spending.
- Commercial:Retail, healthcare, and institutional floors balance durability with aesthetic requirements. Toronto and Vancouver municipal green building codes mandate low-VOC materials, filtering specification toward waterborne systems. LEED v4.1 compliance operates as a gatekeeper for new build projects in these markets.
- Industrial:Manufacturing, warehousing, and logistics floors prioritize chemical resistance and load-bearing capacity. Ontario's manufacturing corridor generates concentrated demand for heavy-duty epoxy and polyurethane systems with shortened refurbishment cycles driving recurring revenue.
- Residential:Basement, garage, and decorative concrete coatings represent discretionary expenditure sensitive to housing market conditions. Prairie province applications face seasonal constraints as water-based epoxies require minimum 10°C substrate temperatures.
- Automotive:Assembly line floors, showrooms, and service bays demand rapid return-to-service and chemical resistance. Polyaspartic penetration is deepest here where 24-hour cure cycles justify premium formulation costs.
Commercial and industrial applications dominate current placements; automotive specifications are climbing the fastest as production uptime economics intensify.
Form:
Regulatory pressure and application constraints are displacing solvent-based systems, with waterborne and powder formulations gaining specification share.
- Liquid:Roll and spray-applied coatings constitute the majority of field-installed volume. Ontario contractors maintain extensive inventories of two-part liquid epoxies for industrial maintenance contracts.
- Powder:Thermosetting powders serve factory-applied OEM components and precast concrete elements. Limited field applicability constrains this form to captive manufacturing environments.
- Solvent-Based:Traditional high-VOC formulations retain niche use in unheated outdoor applications where waterborne cure kinetics fail. Health Canada PMRA regulatory compression is forcing formulators to abandon these products and rebuild supply chains.
- Water-Based:Low-odor, low-VOC dispersions are outpacing solvent alternatives in residential and occupied commercial facilities. British Columbia's stricter workplace exposure limits for isocyanates accelerate specification toward these systems.
Liquid formulations anchor current volume; water-based systems are expanding most quickly as provincial compliance tightens.
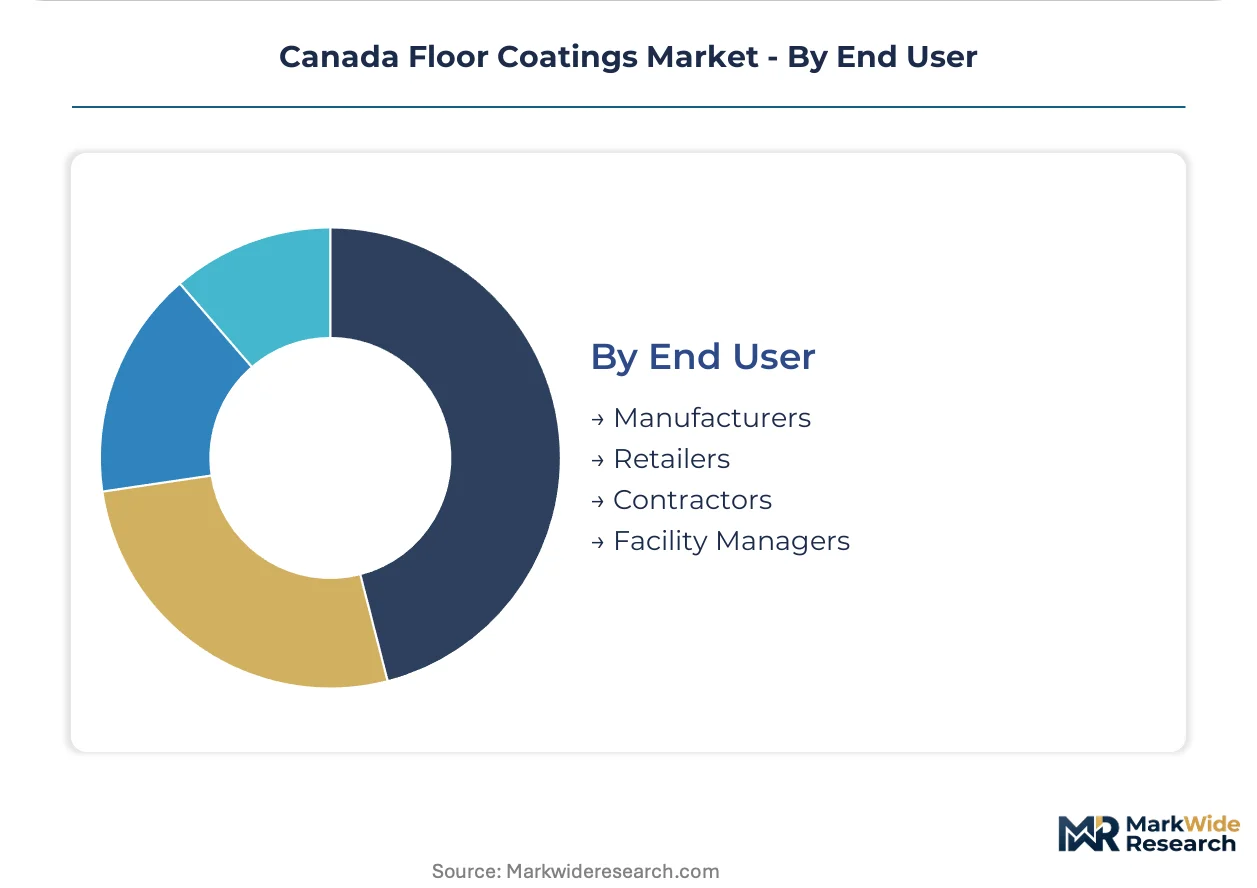
End User:
Procurement authority separates capital-budget manufacturers from operational-budget facility managers and specification-influencing contractors.
- Manufacturers:Automotive, food processing, and pharmaceutical producers specify coatings for new construction and scheduled maintenance. These buyers prioritize warranty-backed installation and predictive maintenance software over unit pricing.
- Retailers:Big-box and grocery chains manage floor maintenance through national facility management contracts. Approved-vendor lists privilege contractors with moisture-testing equipment and multi-location service capability.
- Contractors:Independent and national applicators serve as specification gatekeepers in project-driven markets. Certified applicators for moisture-tolerant epoxy and polyaspartic systems cluster in Toronto, Montreal, and Calgary, creating bottlenecks in secondary markets.
- Facility Managers:Industrial and institutional building operators are consolidating vendor relationships around technical service capabilities. Subscription-based maintenance programs convert capital expenditure into predictable operational budgets, restructuring procurement behavior across Ontario and Quebec.
Contractor channel volume dominates project flow; facility manager direct procurement is gaining share fastest as service-contract bundling proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian formulators consume resin systems produced in the United States and Europe, while domestic demand concentrates in Ontario's industrial corridor. Regional coating consumption patterns diverge sharply between manufacturing-intensive provinces and resource-dependent economies.
Ontario
Automotive assembly plants in Oshawa and Alliston specify polyaspartic systems for rapid return-to-service. Health Canada PMRA VOC limits are accelerating waterborne epoxy R&D among Toronto-area formulators. The manufacturing corridor from Hamilton to Windsor generates concentrated demand for heavy-duty novolac epoxy variants.
Quebec
Healthcare facilities in Montreal and Quebec City specify antimicrobial coatings with silver-ion additives. The province's workplace exposure limits for isocyanates exceed federal guidelines, filtering specification toward low-odor systems. Food processing plants in the Montérégie region are compressing refurbishment cycles to four years.
British Columbia
Vancouver commercial construction mandates LEED v4.1 compliance for new build projects. The province's stricter workplace exposure limits for isocyanates accelerate water-based polyurethane adoption. Port modernization in Vancouver and Prince Rupert specifies heavy-duty marine-terminal coatings.
Alberta
Calgary cold-storage warehouses specify rapid-cure polyaspartic systems to minimize production downtime. Water-based epoxy cure temperature limitations constrain outdoor applications across the province for 4-5 months annually. The petrochemical sector in Fort McMurray generates demand for chemical-resistant industrial floors.
Atlantic Canada
Halifax and St. John's port infrastructure renewal programs specify heavy-duty coatings for marine-terminal floors. This geography remains underpenetrated by national distributors. Provincial green building standards in Nova Scotia are tightening VOC limits for commercial construction.
Canada Floor Coatings Market Competitive Environment
Top-tier vendors anchor specification-driven commercial projects, while mid-tier formulators compete on service bundling and regional coverage. The vendor base stratifies across multinational chemical conglomerates, specialty coating manufacturers, and regional applicator networks. Three archetypes dominate: resin system innovators, distribution-integrated service providers, and certified-applicator aggregators. Consolidation pressures are intensifying through M&A activity and strategic distribution partnerships.
Among multinational coating suppliers, RPM International Inc., PPG Industries Inc., and The Sherwin-Williams Company occupy positions across the tier structure. RPM International Inc. exemplifies the service-contract bundling archetype through subscription-based maintenance programs. PPG Industries Inc. anchors distribution-integrated positioning across Ontario and Quebec commercial projects. The Sherwin-Williams Company represents specification-influence capabilities through color-matching software and contractor loyalty programs.
| Leading Market Players |
|---|
| RPM International Inc |
| BASF SE |
| The Sherwin-Williams Company |
| Teknos Group |
| Jotun |
| PPG Industries Inc. |
| AkzoNobel NV |
| LATICRETE INTERNATIONAL INC. |
| Sika AG |
| Others |
Value Chain & Pricing Dynamics
Facility manager consolidation around approved-vendor lists in Ontario and Quebec is compressing contractor margins and forcing formulators to absorb diagnostic equipment costs into bundled service pricing. This procurement shift elevates technical service capabilities over unit pricing, reshaping how coating suppliers structure customer relationships and recover margin through recurring maintenance contracts rather than transactional product sales.
Pricing Analysis
Margin tightening in waterborne epoxy formulations reflects Health Canada PMRA compliance investments and raw material substitution costs. Three-tier pricing structure across premium polyaspartic, standard polyurethane, and economy acrylic systems separates specification-driven automotive plants from budget-sensitive residential renovators. Price differentiation hinges on cure speed certification and warranty-backed installation coverage. Cost-down pressure on solvent-based alternatives accelerates as provincial VOC limits disqualify these products from municipal projects in Toronto and Vancouver.
Supply Chain Analysis
Single-source vulnerability sits with United States Gulf Coast epoxy resin production and European specialty isocyanate suppliers. Canadian formulators draw from American benzene derivatives, German aliphatic polyurea precursors, and Chinese titanium dioxide feedstocks. Tariff exposure on cross-border chemical shipments threatens margin stability for Ontario-based manufacturers serving Quebec and Atlantic Canada. Distribution runs through PPG Industries and Sherwin-Williams national networks, with independent applicators in secondary markets facing 6-8 week inventory lead times during peak construction seasons.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada floor coatings market sits in a formulation-transition phase as waterborne and polyaspartic technologies displace legacy solvent-based epoxy systems. Rapid-cure chemistry is rewriting project economics and contractor procurement behavior across the manufacturing corridor.
For Market Incumbents: To counter specialty chemical entrants capturing polyaspartic specification share, RPM International and PPG Industries must deepen backward integration into waterborne resin production and expand certified-applicator training capacity in Halifax and St. John's. Channel control through subscription maintenance bundling remains the priority defensive lever against independent contractors consolidating into regional service networks. For New Entrants and Emerging Players: The price-point gap between premium polyaspartic systems and economy acrylic alternatives creates entry space for mid-tier hybrid formulations targeting Quebec healthcare and British Columbia commercial verticals. Atlantic Canada port infrastructure renewal offers the most penetrable geography, with antimicrobial coating registration at Health Canada PMRA providing a differentiated go-to-market angle against established Ontario-based competitors. For Investors and Strategic Acquirers: The window for entry favors vertically integrated coating applicators with captive moisture-testing and warranty capabilities. Long-term viability rests on service-contract revenue predictability rather than cyclical product sales. Watch for provincial green building code acceleration in Nova Scotia and New Brunswick as the signal indicating specification inflection toward low-VOC systems.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Formulation R&D Investment | Health Canada PMRA VOC compliance deadlines in Ontario force accelerated solvent-free product development cycles. |
| Certified Applicator Network Expansion | Halifax and St. John's port projects face contractor shortages, rewarding early training investments in Atlantic Canada. |
| Antimicrobial Coating Registration | Silver-ion and copper-additive formulations unlock Quebec healthcare specification through PMRA biocide compliance. |
| Subscription Service Contract Bundling | RPM International's maintenance programs convert capital expenditure to operational budgets, locking out transactional competitors. |
| Moisture-Tolerant System Development | Prairie province cold-weather application constraints create first-mover advantage for low-temperature cure chemistry. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with coating plant managers, facility management procurement leads, certified applicator contractors, and Health Canada PMRA regulatory affairs specialists. Bottom-up volume modeling triangulated against top-down value estimates derived from resin import statistics and distributor revenue disclosures across Ontario, Quebec, and British Columbia.
Data-stream reconciliation connected field-installed volume tracking with specification-driven project databases across the projection horizon. Segmentation dimensions encompassed resin chemistry tier, application environment, formulation type, and end-user procurement channel. CAGRs were derived from trend extrapolation of refurbishment cycle compression and regulatory compliance timelines, with polyaspartic adoption curves and waterborne substitution rates serving as industry-specific forecast inputs.
Underlying measurement precision varies by segment; industrial and commercial applications carry tighter precision than residential discretionary spending. Forecasts reflect assumptions about regulatory implementation pacing and petrochemical feedstock stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
UV Coatings Market
Coatings
2K Coatings Market
Coatings
Leisure Boat Marine Coatings Market
Coatings
Africa Automotive Refinish Coatings Market
Coatings
Can Coatings Market
Coatings
Russia Architectural Coatings Market
Coatings
Coating Pigments Market
Coatings
Anti-Microbial Coatings Market
Coatings
Global Plastic Coatings Market
Coatings
Bio-Based Coatings Market
Coatings
OEM Coatings Market
Coatings
Global PET Film Coated Steel Coil Market
Coatings
Global Battery Coating Market
Coatings
Morocco Automotive OEM Coatings Market
Coatings
Liquid-Applied Roof Coating Market
Coatings
South Korea Automotive OEM Coatings Market