
 Marine Deck Coatings Market | 2026-2036
Marine Deck Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Deck Coatings Market Outlook
Marine coatings distribution through shipyard direct-supply agreements is reconfiguring procurement patterns across major building regions. PPG Industries leverages its integrated supply chain to sustain bulk contracts with Korean and Chinese yards. Hempel A/S anchors its position through specialized technical service teams embedded at key dry-dock facilities. Jotun competes via differentiated anti-slip and UV-resistant formulations targeting superyacht segments.
Marine deck coatings are polymer-based protective systems, typically formulated from polyurethane, epoxy, or acrylic resins with functional additives, applied at dry film thicknesses of 150-500 microns to withstand mechanical abrasion, saltwater exposure, and thermal cycling on vessel walking surfaces. Epoxy systems dominate new-build applications for cargo ships and ferries due to superior adhesion to steel substrates and chemical resistance. Polyurethane coatings represent the fastest-growing product category, driven by yacht and military end-user demand for color retention and flexible film properties under dynamic load conditions.
IMO marine environment regulations, REACH chemical restrictions in Europe, and China's MEE volatile organic compound emission standards collectively constrain solvent-based technology formulations while accelerating water-based and two-part system development. Compliance with these frameworks shapes product registration requirements, raw material sourcing decisions, and manufacturing facility locations. Stakeholders must monitor evolving biocide regulations for anti-fouling additives and assess dual-carbon policy trajectories in major shipbuilding nations to anticipate formulation investment priorities.
Market Dynamics
Fleet lifecycle extension mandates from IMO decarbonization frameworks are forcing vessel operators to prioritize refurbishment over replacement, concentrating demand for high-durability deck coating systems at Asian dry-dock clusters.
Growth Catalysts
- IMO Sulfur Cap Extensions:Stricter enforcement of maritime emission standards compels cargo fleet operators to extend vessel service lives, driving recurring recoating cycles at major shipyard facilities.
- Epoxy-Polyurethane Hybrid Systems:Advanced resin formulations combining chemical resistance with flexible film properties capture preference from military and offshore platform operators facing extreme mechanical loads.
- Shanghai-Zhoushan Shipyard Concentration:China's dominant new-build and repair capacity generates sustained bulk procurement volumes for anti-slip and UV-stable coating specifications.
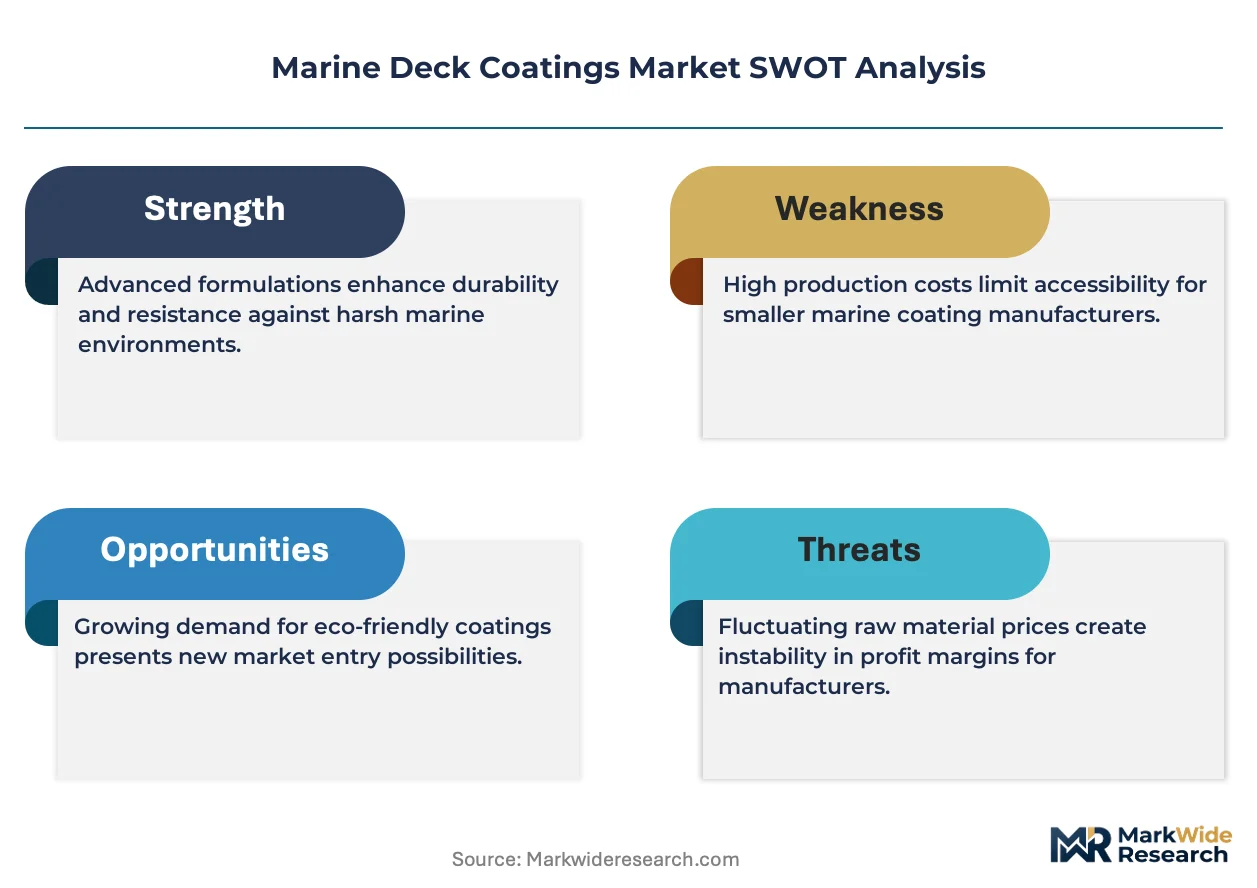
Market Restraints
- Bisphenol A Feedstock Volatility:Epoxy resin precursor costs fluctuate with petrochemical pricing cycles, compressing formulation margins for water-based system producers.
- South Korean Supplier Concentration:Specialty polyisocyanate hardener production clusters among three domestic chemical groups, creating single-source vulnerability for polyurethane coating manufacturers.
- Biocide Registration Delays:ECHA's REACH authorization procedures for anti-fouling additives extend product commercialization timelines by 18-24 months.
Strategic Opportunities
- India Ship Repair Expansion:Cochin and Visakhapatnam yard modernization under the country's Maritime India Vision 2030 creates untapped demand for high-performance deck systems.
- Arctic Route Vessel Traffic:Northern Sea Route commercialization drives specification for extreme low-temperature flexibility in polyurethane formulations.
- EU Green Deal Procurement Incentives:Public ferry operator tenders now weight lifecycle carbon footprint, advantaging water-based and bio-content coating suppliers.
Industry Challenges
- Coating Inspector Certification Bottlenecks:NACE/SSPC qualification backlogs delay project commissioning at peak dry-dock seasons.
- Legacy Solvent System Retrofit Complexity:Yard infrastructure designed for conventional high-VOC application requires capital-intensive ventilation upgrades to handle water-based alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Deck Coatings Market |
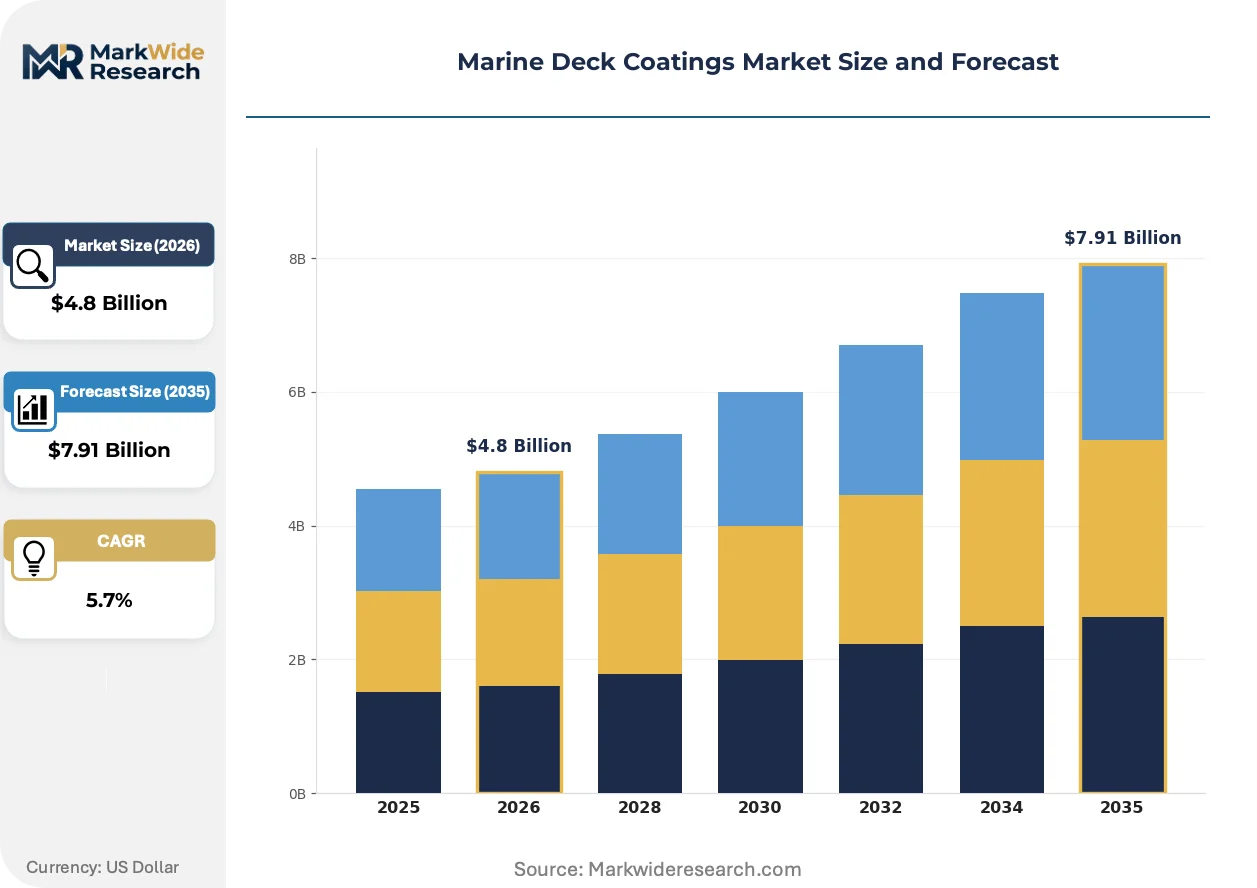
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Alkyd Application: Yachts, Cargo Ships, Ferries, Fishing Vessels End User: Commercial, Residential, Government, Military Technology: Water-Based, Solvent-Based, Two-Part, Single-Part |
| Companies Covered | PPG Industries Inc, Akzo Nobel NV, Hempel A/S, Jotun, The Sherwin Williams Company, Chugoku Marine Paints, Kansai Paint Co., Ltd., Nippon Paint Holdings Co., Ltd., RPM International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Deck Coatings Market Strategic Shifts
Formulation chemistry and application protocols are converging around sustainability compliance and operational efficiency, with regulatory pressure accelerating technology substitution cycles across marine coating procurement.
Waterborne two-part epoxy systems are hybridizing with silicone-modified acrylic segments to achieve salt-spray resistance comparable to solvent-based predecessors while satisfying MEE VOC emission thresholds. Chinese military vessel operators have adopted these systems for surface combatant deck refurbishment, compressing the technology validation timeline from five years to eighteen months. The hybridization is collapsing the traditional performance gap between regulatory-compliant and legacy formulations.
REACH restriction proposals for microplastic release from coating abrasion are compelling reformulation of anti-slip aggregates across European-flagged fleets. ECHA's 2023 restriction roadmap threatens existing quartz and polymer bead additives, forcing suppliers to validate bio-based alternatives including crushed walnut shell and volcanic pumice. Ferry operators in the Baltic Sea basin face the most immediate specification uncertainty as classification societies develop new testing protocols.
Shipyard direct-supply agreements are displacing traditional distributor networks for large fleet operators, with procurement teams embedding technical specifications into multi-year maintenance contracts. Korean container line operators pioneered this model, and Chinese state-owned yards now replicate the structure for domestic cargo fleet accounts. The channel compression is most visible at Zhoushan repair facilities serving Yangtze River delta traffic.
Marine Deck Coatings Market Segmentation
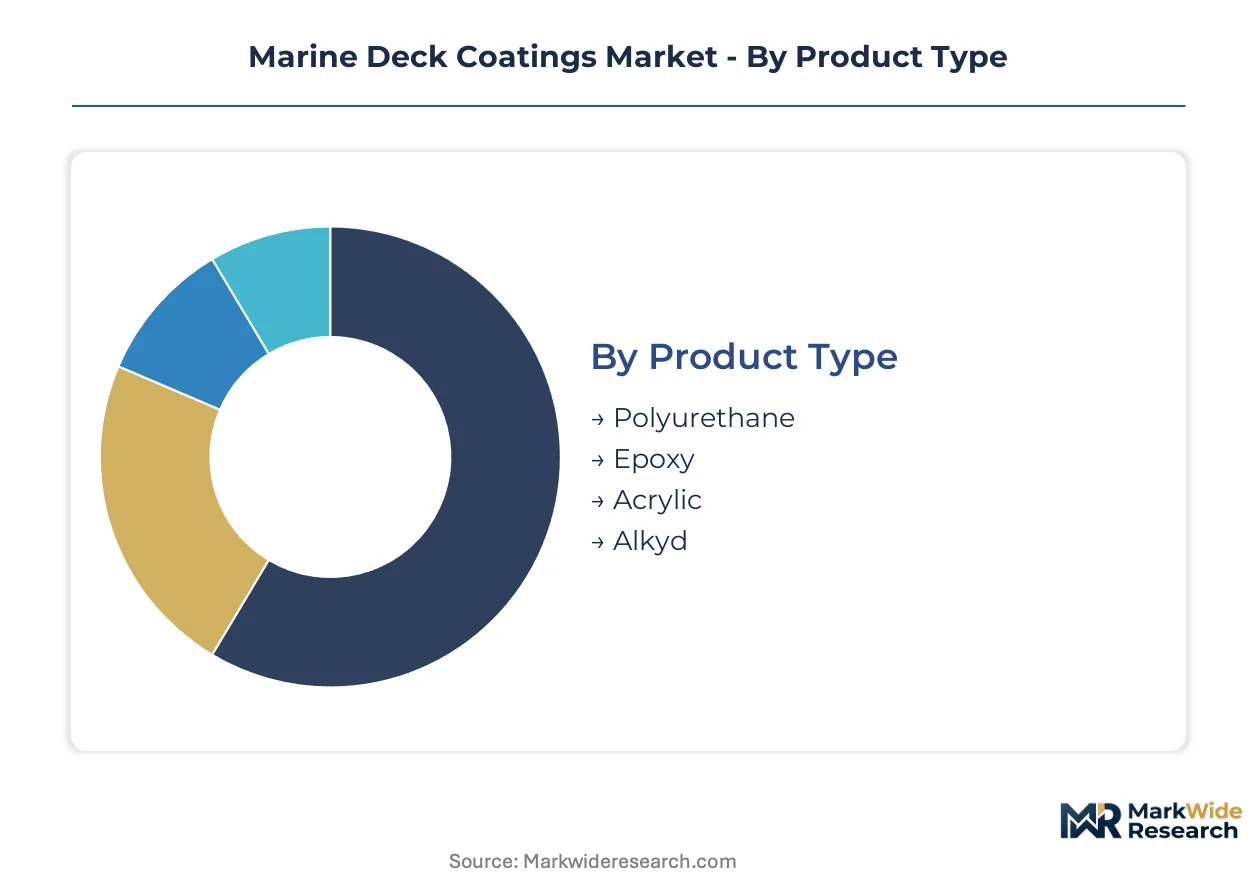
Segmentation in marine deck coatings reveals how formulation chemistry, vessel specifications, and regulatory compliance intersect to create distinct procurement patterns across shipyard channels. Understanding these divisions exposes where technical service intensity and specification authority concentrate.
Product Type:
After-sales technical support requirements vary dramatically by resin chemistry, with polyurethane systems demanding the most intensive application supervision and epoxy formulations requiring substrate-specific troubleshooting.
- Polyurethane:Flexible aliphatic and aromatic resin systems deliver superior UV stability and color retention under dynamic mechanical loads. Yacht builders in Italy and military vessel operators in the United States specify these coatings for superstructure decks where aesthetic performance and thermal cycling resistance justify premium formulation costs. Demand concentrates where vessel operators prioritize extended maintenance intervals over initial material expenditure.
- Epoxy:Bisphenol-A and novolac-based systems bond aggressively to prepared steel substrates, offering chemical resistance against fuel spills and hydraulic fluids. Cargo ship operators at Zhoushan and Korean dry-dock facilities favor these formulations for tanker and bulker refurbishment cycles where adhesion failure carries catastrophic operational consequences. The segment dominates new-build procurement at Asian shipyards.
- Acrylic:Water-dispersible and solvent-borne acrylics serve quick-turnaround repair applications where rapid recoat windows matter more than ultimate durability.
- Alkyd:Traditional oil-modified polyester resins persist in small-craft maintenance where cost sensitivity overrides performance specifications.
Epoxy holds the largest share; momentum sits with polyurethane as yacht and military specifications expand.
Application:
Vessel type determines deck geometry, traffic intensity, and exposure severity, creating divergent specification requirements that shape formulation selection and application protocol complexity.
- Yachts:Superyacht and luxury vessel decks demand anti-slip finishes with customizable color palettes and gloss retention under intense solar exposure. Mediterranean and Caribbean refit yards drive specification for UV-stable polyurethane systems with embedded quartz aggregates. The segment commands the highest per-square-meter coating expenditure in the marine category.
- Cargo Ships:Container vessels, tankers, and bulk carriers require high-build epoxy systems capable of withstanding fork-lift traffic, container lashings, and chemical splash exposure. Shanghai and Singapore dry-dock clusters generate volume demand for rapid-cure formulations that compress lay-up schedules during scheduled maintenance windows.
- Ferries:Passenger vessel operators prioritize rapid-cure water-based systems that minimize volatile emissions during in-service refurbishment cycles.
- Fishing Vessels:Trawler and processing ship decks face organic matter abrasion and salt-spray saturation that favors sacrificial coating strategies with frequent recoating intervals.
Cargo ships anchor volume demand; ferries are climbing the fastest as emission regulations accelerate water-based system adoption.
End User:
Procurement authority and specification control distribute unevenly across customer categories, with government and military buyers wielding the most rigid technical requirements and commercial operators optimizing for lifecycle cost.
- Commercial:Container lines, bulk operators, and cruise companies negotiate multi-year supply agreements with direct shipyard delivery clauses. Korean and Chinese state-owned shipping groups consolidate purchasing power through fleet-wide coating specifications that lock in formulation suppliers for entire vessel classes. Price sensitivity intensifies as freight rate volatility compresses maintenance budgets.
- Government:Coast guard and maritime authority fleets operate under public procurement frameworks that weight domestic content and environmental compliance alongside technical performance. European ferry operators under EU Green Deal procurement guidelines now mandate lifecycle carbon footprint disclosure in coating tenders.
- Military:Naval specification authorities enforce rigorous qualification protocols that extend product validation timelines but secure long-term supply relationships.
- Residential:Private yacht owners rely on yard recommendations and broker referrals with limited independent technical assessment capacity.
Commercial end users dominate procurement volume; military specifications set the performance ceiling that trickles down to adjacent segments.
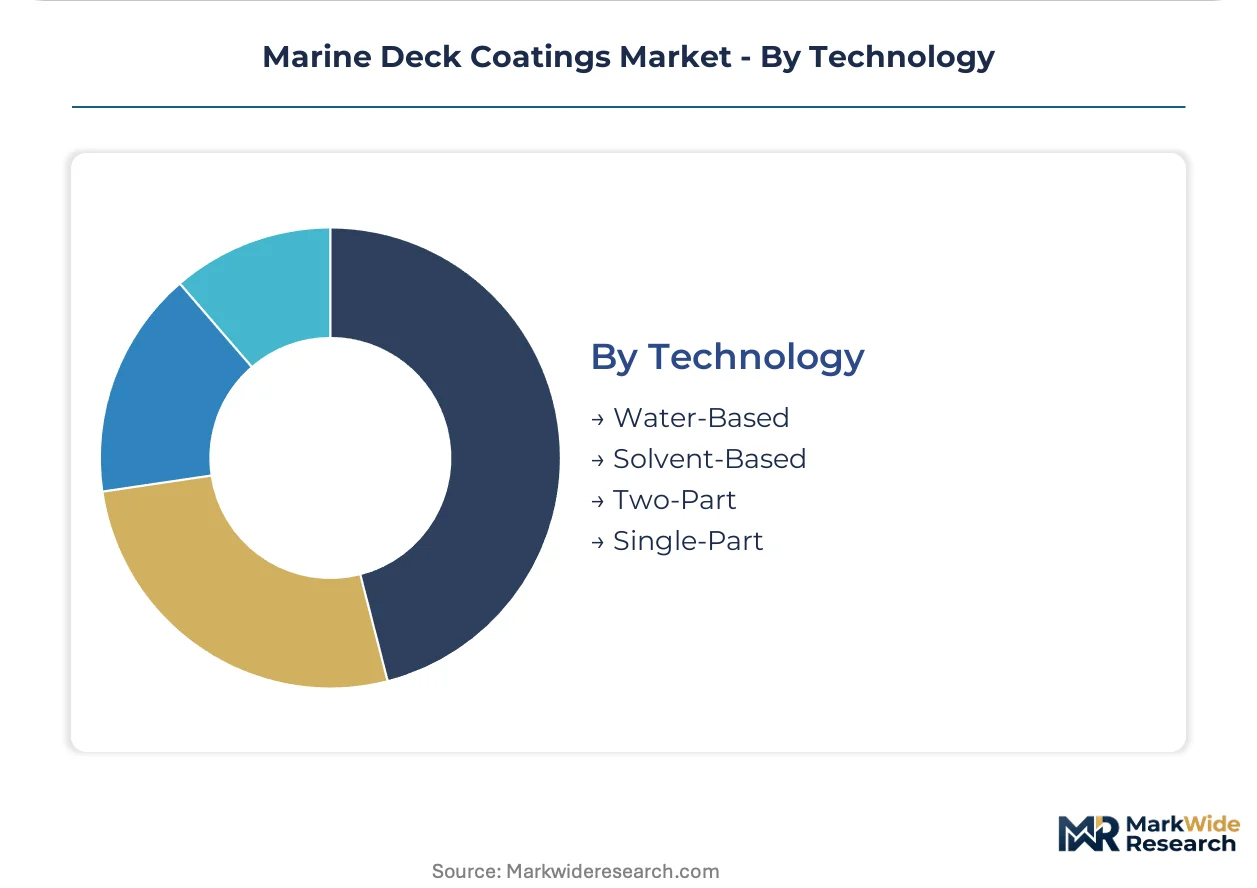
Technology:
Application infrastructure investment and environmental compliance burden divide the technology landscape, with water-based systems requiring capital-intensive spray booth modifications that concentrate adoption at larger yard facilities.
- Water-Based:Acrylic-epoxy hybrid dispersions and polyurethane dispersions satisfy MEE and ECHA emission thresholds while approaching solvent-based performance in salt-spray resistance. Chinese military yards have compressed validation timelines for these systems, accelerating adoption across surface combatant refurbishment programs. The technology commands premium pricing during transition periods as supply capacity constraints persist.
- Solvent-Based:Conventional high-VOC alkyd and epoxy formulations retain cost advantage and application familiarity at smaller repair facilities lacking ventilation infrastructure upgrades. Regulatory phase-out timelines vary by jurisdiction, creating geographic pockets of continued demand.
- Two-Part:Catalyzed epoxy and polyurethane systems dominate high-performance applications where pot life management and mixing accuracy determine coating integrity.
- Single-Part:Moisture-cure and oxidative-dry formulations serve touch-up and spot repair applications where on-site mixing logistics prove impractical.
Solvent-based technology retains the largest installed base; water-based formulations are gaining share fastest as Asian and European emission standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Zhoushan shipyard corridor anchors Asia-Pacific coating demand through its integrated new-build and repair infrastructure serving Yangtze River delta traffic.
China
Shanghai and Zhoushan shipyards generate concentrated procurement volumes for epoxy and polyurethane systems serving container vessel new-build programs. MEE volatile organic compound emission standards accelerate water-based formulation adoption at military refurbishment facilities. The Yangtze River delta cluster processes the highest annual dry-dock throughput globally.
South Korea
Ulsan and Geoje shipyards drive specification for rapid-cure epoxy systems compressing vessel lay-up schedules. Korean container lines pioneered direct-supply procurement models embedding technical specifications into multi-year maintenance contracts. Three domestic chemical groups control specialty polyisocyanate hardener production, creating feedstock concentration.
United States
Military vessel operators at Norfolk and San Diego naval facilities enforce rigorous qualification protocols extending product validation timelines. EPA emission guidelines constrain solvent-based application at commercial yards. Gulf Coast repair facilities serving offshore platform traffic specify hybrid epoxy-polyurethane systems for extreme mechanical load conditions.
Germany
Hamburg and Bremerhaven ferry operators under EU Green Deal procurement guidelines mandate lifecycle carbon footprint disclosure in coating tenders. ECHA REACH authorization procedures for anti-fouling additives extend product commercialization timelines. Baltic Sea basin classification societies develop new testing protocols for bio-based anti-slip aggregates.
India
Cochin and Visakhapatnam yard modernization under Maritime India Vision 2030 creates demand for high-performance deck systems. DGFT import regulations shape raw material sourcing decisions for domestic formulation producers. The country's ship repair expansion targets capture of Middle East tanker refurbishment traffic.
Marine Deck Coatings Market Competitive Environment
On the supply side, the industry is consolidated among integrated coating manufacturers with embedded shipyard technical service capabilities. Tiered competitive positioning separates global formulators with captive resin production from regional specialists dependent on merchant chemical supply. Strategic archetypes include integrated resin-coating manufacturers, shipyard-embedded technical service providers, and specialty formulation developers. Dominant competitive moves center on direct-supply agreement capture at Asian dry-dock clusters and water-based technology portfolio expansion.
Within the integrated manufacturer tier, PPG Industries exemplifies supply chain consolidation through bulk contract structures at Korean and Chinese yards. Hempel A/S occupies a position as the technical service-intensive archetype with embedded application support teams. Jotun represents the specialty formulation anchor targeting differentiated performance specifications in yacht and military segments where UV stability and anti-slip properties command premium positioning.
| Leading Market Players |
|---|
| PPG Industries Inc |
| Akzo Nobel NV |
| Hempel A/S |
| Jotun |
| The Sherwin Williams Company |
| Chugoku Marine Paints |
| Kansai Paint Co., Ltd. |
| Nippon Paint Holdings Co., Ltd. |
| RPM International |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Zhoushan shipyard corridor concentrates global coating demand through integrated new-build and repair infrastructure, translating vessel operator procurement consolidation into asymmetric pricing power for resin suppliers with captive production.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates marine deck coatings, separating military-grade qualified systems from commercial fleet specifications and small-craft maintenance grades. Price differentiation centers on ISO 12944 corrosion protection certification tier and volume-scale procurement commitments under multi-year dry-dock contracts. Pricing pressure stems from bisphenol-A feedstock volatility compressing epoxy formulation margins. Commercial cargo operators exhibit highest price sensitivity due to freight rate cyclicality, while military specifications remain least elastic given qualification rigor.
Supply Chain Analysis
Contract manufacturing concentration rests with PPG Industries, Hempel A/S, and Jotun operating integrated resin-coating production facilities across China, South Korea, and Germany. Raw material dependencies draw from specialty polyisocyanate hardeners, bisphenol-A epoxy precursors, and titanium dioxide pigments. Single-source vulnerability concentrates in South Korean polyisocyanate production among three domestic chemical groups. Distribution runs through direct-supply agreements embedding technical specifications into multi-year maintenance contracts at Asian dry-dock clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine deck coatings represent an early-cycle expansion story as IMO decarbonization mandates force fleet lifecycle extension, accelerating refurbishment demand at Asian dry-dock facilities.
For Market Incumbents: Harden technical service embedding at Zhoushan and Ulsan shipyard clusters to defend against emerging water-based specialists capturing EU Green Deal procurement. Deepen backward integration into epoxy resin production to offset bisphenol-A feedstock volatility compressing formulation margins. Prioritize NACE/SSPC inspector certification pipeline investment to resolve commissioning bottlenecks during peak dry-dock seasons.
For New Entrants and Emerging Players: Pursue untapped specification authority at Cochin and Visakhapatnam yards modernizing under Maritime India Vision 2030, where incumbent technical service presence remains thin. Target Arctic Route vessel traffic demanding extreme low-temperature polyurethane flexibility as the most penetrable application segment. Lead with bio-based anti-slip aggregate formulations addressing ECHA microplastic restriction proposals.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because emission standard tightening creates irreversible technology substitution tailwinds favoring water-based and bio-content suppliers. Acquisition candidates include regional formulators with MEE-compliant portfolios and embedded military yard relationships. Monitor ECHA REACH authorization timelines for anti-fouling biocides as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Formulation Scale-Up | MEE VOC compliance unlocks Chinese military refurbishment contracts at compressed validation timelines. |
| Direct-Shipyard Technical Service Embedding | Hempel's dry-dock team model captures multi-year maintenance contract specification authority. |
| Bio-Based Anti-Slip Aggregate Development | Crushed walnut shell alternatives preempt ECHA microplastic restrictions on quartz additives. |
| Arctic Route Polyurethane Qualification | Extreme low-temperature flexibility specifications capture Northern Sea Route commercialization demand. |
| Inspector Certification Pipeline Investment | NACE/SSPC qualification capacity resolves peak-season commissioning bottlenecks at Asian yards. |
Study Parameters
Cross-validation between shipyard procurement director interviews and customs trade data anchors the qualitative findings across resin chemistry and application protocol evolution. Primary fieldwork engaged coating application supervisors, fleet maintenance managers at container lines, technical service directors, and shipyard supply chain officers. Secondary sources incorporated MEE emission filings, ECHA REACH registration databases, Korean customs export statistics, and SEC 10-K disclosures from listed coating manufacturers. Bottom-up vessel fleet analysis triangulates against top-down chemical consumption estimates.
Calibration against historical coating consumption per deadweight tonnage and dry-dock cycle frequency shapes the analytical framework across the projection horizon. Segmentation dimensions span resin chemistry, vessel type, application technology, and end-user procurement authority. CAGRs derive from regression against fleet age distribution, regulatory phase-in schedules, and shipyard capacity utilization. Forecast inputs include IMO decarbonization mandate enforcement intensity and MEE VOC standard adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-owned chemical groups or accelerated EU Green Deal procurement weighting would shift outcomes. Quarterly review of ECHA restriction proposal advancement, Zhoushan dry-dock throughput statistics, and bisphenol-A spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
High Temperature Coatings Market
Coatings
Polyurethane Powder Coatings Market
Coatings
Soft Touch Polyurethane Coatings Market
Coatings
Europe Coil Coatings Market
Coatings
US Industrial Coatings Market
Coatings
Mexico Industrial Wood Coatings Market
Coatings
Electrically Conductive Coating Market
Coatings
Breathable Antimicrobial Coatings Market
Coatings
Fillers and Coating Market
Coatings
Global Low Temperature Powder Coatings Market
Coatings
Diamond-Like Carbon Coatings Market
Coatings
Middle East and Africa Super Hydrophobic Coatings Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
Asia-Pacific Flat Glass Coating Market
Coatings
PACVD-Based Coatings Market
Coatings
Global Anti-Corrosion Coating Market