
 Paper Coating Materials Market | 2026-2036
Paper Coating Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Coating Materials Market Intelligence
Demand from packaging manufacturers is rotating share away from traditional publication producers. This shift prioritizes coatings that enhance durability and barrier properties for e-commerce and food-grade applications. BASF SE leverages its extensive polymer chemistry portfolio to develop advanced functional coatings. Dow Inc. competes on the performance of its synthetic latex binders, while Omya AG dominates the supply of ground calcium carbonate for bulk applications.
Paper coating materials are functional formulations applied to the surface of paper or paperboard to improve aesthetic and physical characteristics. These coatings, often composed of pigments, binders, and additives, enhance properties like gloss, smoothness, and printability. Calcium carbonate remains the dominant product type by volume due to its cost-effectiveness. However, synthetic polymers and latex are gaining share in high-performance packaging board applications where moisture and grease resistance are critical.
The market operates within strict regulatory boundaries for material safety and environmental impact. The US FDA sets guidelines for food-contact substances, while the EU's REACH regulation governs the use of chemicals in coatings. These frameworks compel producers to validate material composition and limit certain hazardous substances. Stakeholder success will depend on aligning product development with the rising demand for recyclable and compostable coating solutions.
Market Dynamics
The central structural force shaping the paper coating materials market is the regulatory and consumer-led push for sustainability. This pressure compels a fundamental shift away from single-use plastics and towards recyclable, compostable, and bio-based coating formulations, particularly for food packaging and e-commerce applications.
Growth Catalysts
- Single-Use Plastic Directives:Regulations like the EU Green Deal are creating powerful substitution mandates, forcing brand owners to seek paper-based packaging solutions with advanced barrier coatings as alternatives to plastic containers and films.
- E-commerce Expansion:The growth of online retail, especially in China, requires durable and moisture-resistant packaging, stimulating demand for functional coatings that protect goods during transit without compromising the recyclability of the paperboard substrate.
- Bio-based Material Innovation:Advances in developing binders and barrier polymers from renewable sources like starches, proteins, and PLA are enabling new product categories that meet performance requirements and sustainability goals for food-contact applications.
Market Restraints
- Input Cost Volatility:The pricing of synthetic latex and polymer binders is directly tied to volatile petrochemical feedstock markets, creating margin pressure and forecasting uncertainty for coating formulators and paper mills.
- Technical Performance Gaps:Many emerging bio-based coatings struggle to match the high-performance barrier properties, particularly against oil and grease, offered by conventional petroleum-derived coatings at a comparable cost.
- Regulatory Compliance Hurdles:Securing food-contact approvals from bodies like the US FDA or Europe's EFSA is a lengthy and costly process, slowing the commercialization of novel coating chemistries and creating barriers for new entrants.
Strategic Opportunities
- Coatings for Molded Fiber:The rising adoption of molded fiber products as a replacement for plastic clamshells and containers creates a significant opportunity for specialized coatings that enhance water resistance and food-safe barriers.
- Functional Additives for Recyclability:There is an unmet need for additives that help coating materials break down more easily during the repulping process, improving the yield and quality of recycled paper fibers.
- Underpenetrated Asian Markets:Outside of China, developing economies in Southeast Asia present growth potential as their consumer packaging and food service industries formalize and adopt higher-quality coated paper and paperboard products.
Industry Challenges
- Coating and Paper Mill Integration:Applying new, sensitive bio-based formulations often requires significant capital investment to upgrade or retrofit existing paper machine coaters, which can be a barrier for older mills with tight capital budgets.
- End-of-Life Infrastructure Mismatch:A lack of standardized collection and processing infrastructure for coated paper products leads to consumer confusion and high contamination rates in recycling streams, undermining sustainability claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Coating Materials Market |
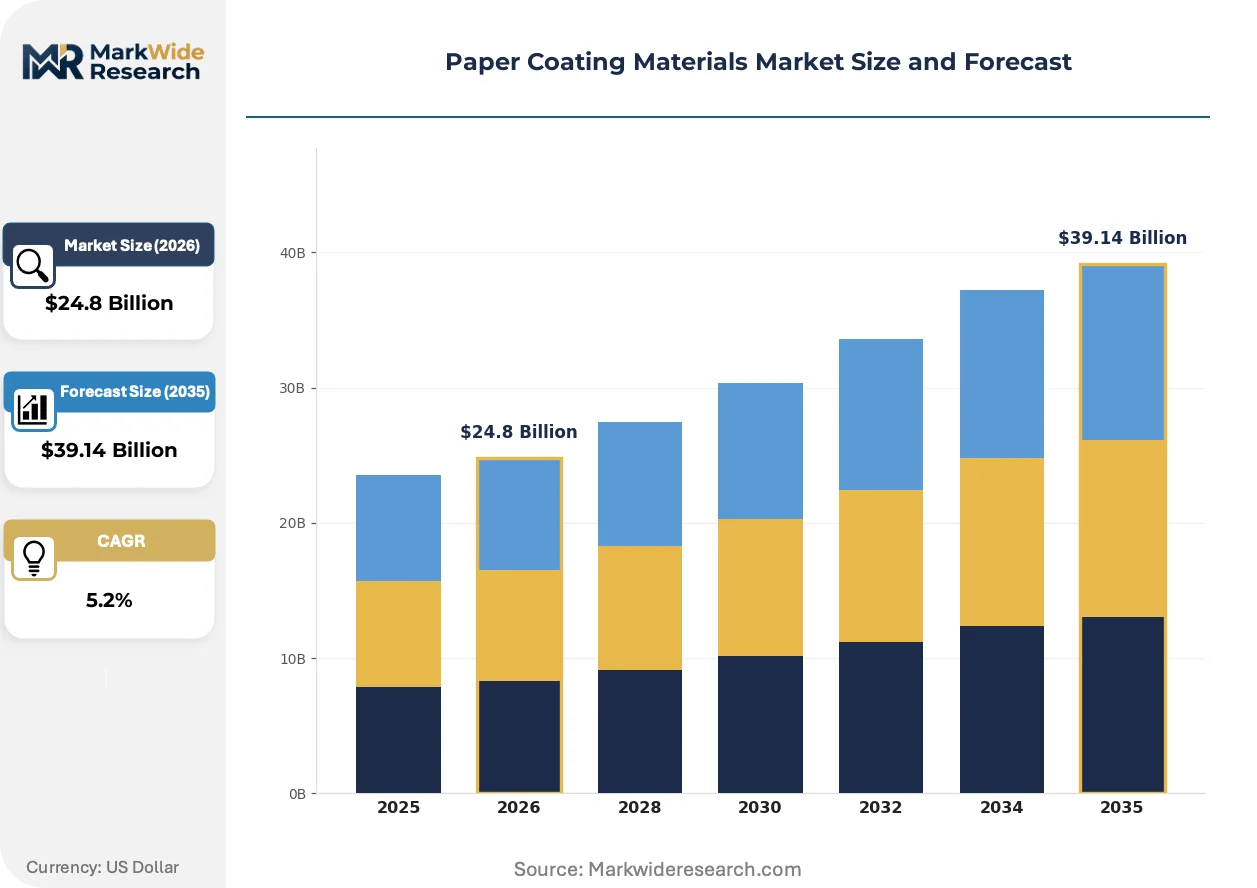
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $39.14 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clay Coating, Latex, Calcium Carbonate, Titanium Dioxide, Synthetic Polymers, Starch Application: Printing Paper, Packaging Board, Tissue Paper, Label Stock, Specialty Papers, Decorative Paper End User Industry: Publication Producers, Packaging Manufacturers, Paper Converters, Stationery Producers, Art Supplies, Industrial Printers Coating Technology: Blade Coating, Curtain Coating, Roll Coating, Air Knife, Size Press, Spray Coating |
| Companies Covered | Omya AG, Michelman, Inc., BASF SE, Nippon Paper Industries Co., Ltd., Asia Pulp & Paper, Dow Inc., Eastman Chemical Company, Stora Enso Oyj, Imerys S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Coating Materials Market Strategic Shifts & Innovations
Material science is advancing to meet the dual mandate of enhanced functional performance and improved environmental profiles. Innovation is focused on creating coatings that provide effective barriers against moisture, grease, and oxygen while ensuring the final paper product remains recyclable or compostable.
Bio-polymer formulations serve to replace petroleum-derived barrier materials like polyethylene. Food and beverage packaging producers are the primary adopters, responding to regulatory pressure and consumer demand for plastic-free alternatives. This development is bifurcating the market between high-value, functional bio-coatings for specialized applications and traditional mineral-based coatings used in commodity graphic and printing papers.
The EU's REACH regulation governs the chemical substances used within coatings, requiring rigorous documentation on safety and environmental impact. This framework compels formulators to validate every component and find alternatives for any materials designated as Substances of Very High Concern (SVHC). Manufacturers targeting the European market are most impacted, accelerating research into greener solvents and additives to ensure compliance.
Brand owners are increasingly making procurement decisions based on the certified end-of-life pathway of coated packaging. This shift prioritizes coatings with validated credentials for recyclability in standard paper mills or compostability in industrial facilities, displacing suppliers who cannot provide such verification. This behavior is most pronounced in the consumer-packaged goods and quick-service restaurant sectors across North America and Europe.
Paper Coating Materials Market Segmentation
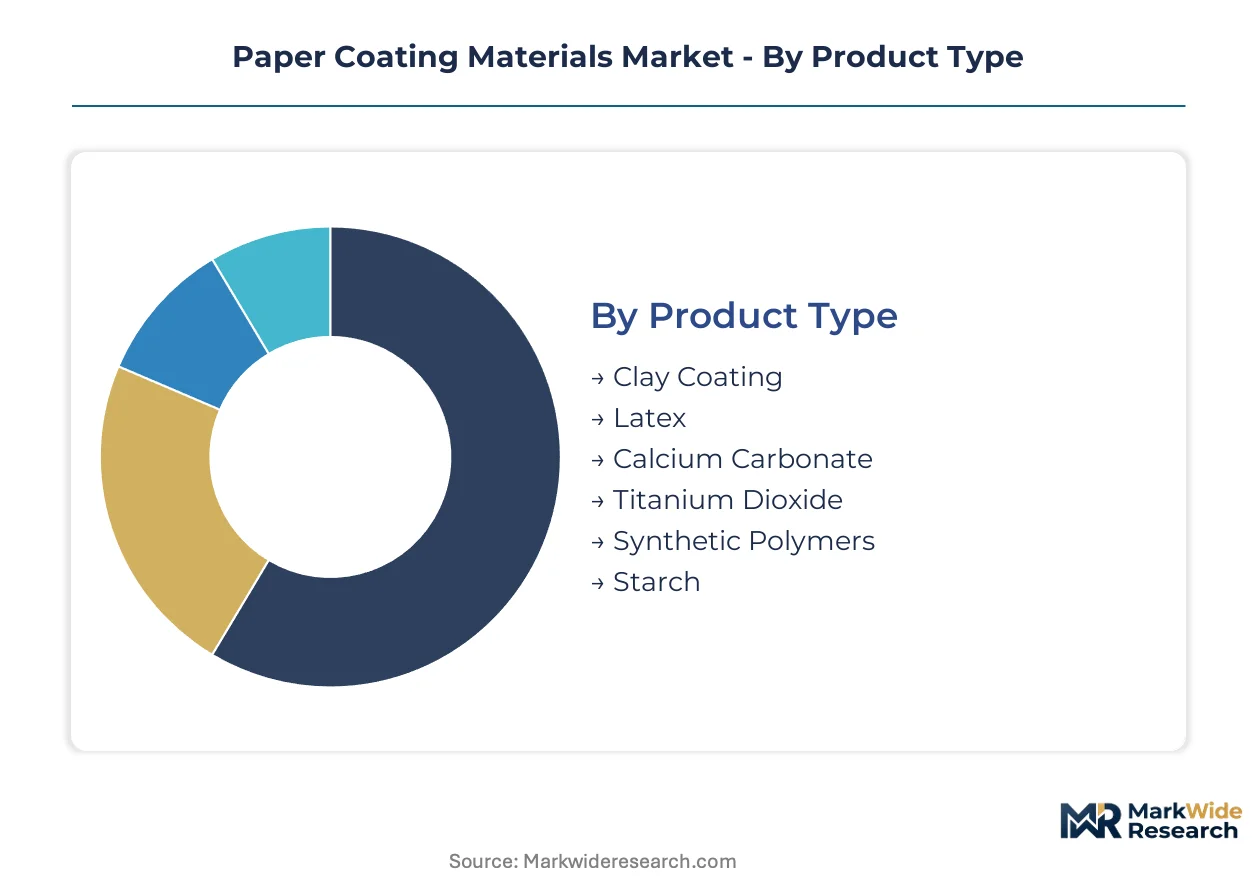
Segmentation of the paper coating materials market reveals diverse functional requirements across various paper and paperboard applications. Understanding these distinct segments helps manufacturers tailor product formulations and optimize production processes. This granular analysis highlights where specific material innovations deliver the most significant performance and commercial advantages.
Product Type:
Margin pools within the product type segment are influenced by material performance and cost-effectiveness for bulk versus specialized high-barrier needs.
- Calcium Carbonate:
This mineral pigment is widely used for its brightness, opacity, and cost-effectiveness in paper and board coatings. Demand concentrates in graphic papers and commodity packaging.
- Synthetic Polymers:
These petroleum-derived binders provide superior water resistance, flexibility, and adhesion. Demand concentrates in high-performance packaging board for food and beverage applications.
- Clay Coating:
Kaolin clay enhances paper smoothness, brightness, and ink receptivity for various printing applications.
- Latex:
Polymer emulsions like synthetic latex improve binding strength, water resistance, and printability in coated papers.
- Titanium Dioxide:
This high-opacity pigment boosts brightness and whiteness, primarily for premium graphic and decorative papers.
- Starch:
Bio-based starch polymers are cost-effective binders enhancing paper strength and surface properties, often blended with other materials.
The dominant share belongs to Calcium Carbonate due to its volume, while Synthetic Polymers is closing the gap fastest in high-performance segments.
Application:
Application segments differentiate by the sheer volume of paper processed and the specific functional demands placed on the coating.
- Packaging Board:
This segment includes corrugated boxes and folding cartons, requiring coatings for barrier properties and printability. Demand is driven by e-commerce and plastic alternatives for food and beverage.
- Label Stock:
Coatings for label stock enhance adhesion, print quality, and moisture resistance for various product labeling. Demand is strong in consumer goods and logistics, requiring durable surfaces.
- Printing Paper:
Coated printing papers are used for magazines and catalogs, prioritizing smoothness, gloss, and ink holdout for sharp images.
- Tissue Paper:
Coatings on tissue paper can add softness, strength, or absorbency, primarily for hygiene and sanitary products.
- Specialty Papers:
These include release liners and thermal papers, where coatings impart unique functional properties for niche industrial uses.
- Decorative Paper:
Decorative papers use coatings to achieve specific textures, patterns, and finishes for laminates and furniture surfaces.
Packaging Board applications represent the largest volume, with Label Stock showing consistent expansion.
End User Industry:
End user industries are defined by their primary application focus, which dictates the performance characteristics required from paper coating materials.
- Packaging Manufacturers:
These manufacturers create cartons and flexible packaging, requiring coatings for barrier protection, printability, and sustainability. Demand is surging due to e-commerce and plastic alternatives.
- Publication Producers:
This segment includes publishers of magazines and books, where coatings enhance print quality, gloss, and readability. Demand is declining due to digital media shifts.
- Paper Converters:
Paper converters transform large paper rolls into finished products, often applying coatings in-house to add specific functionalities.
- Stationery Producers:
This group uses coated papers for notebooks and office supplies, where surface smoothness and ink compatibility are essential.
- Art Supplies:
Manufacturers of art papers utilize specialized coatings to optimize paint adhesion, texture, and archival properties.
- Industrial Printers:
These printers use coated papers for commercial printing, labels, and specialized industrial applications, requiring high-speed compatibility.
Packaging Manufacturers remain the primary growth engine, while Publication Producers face structural headwinds.
Coating Technology:
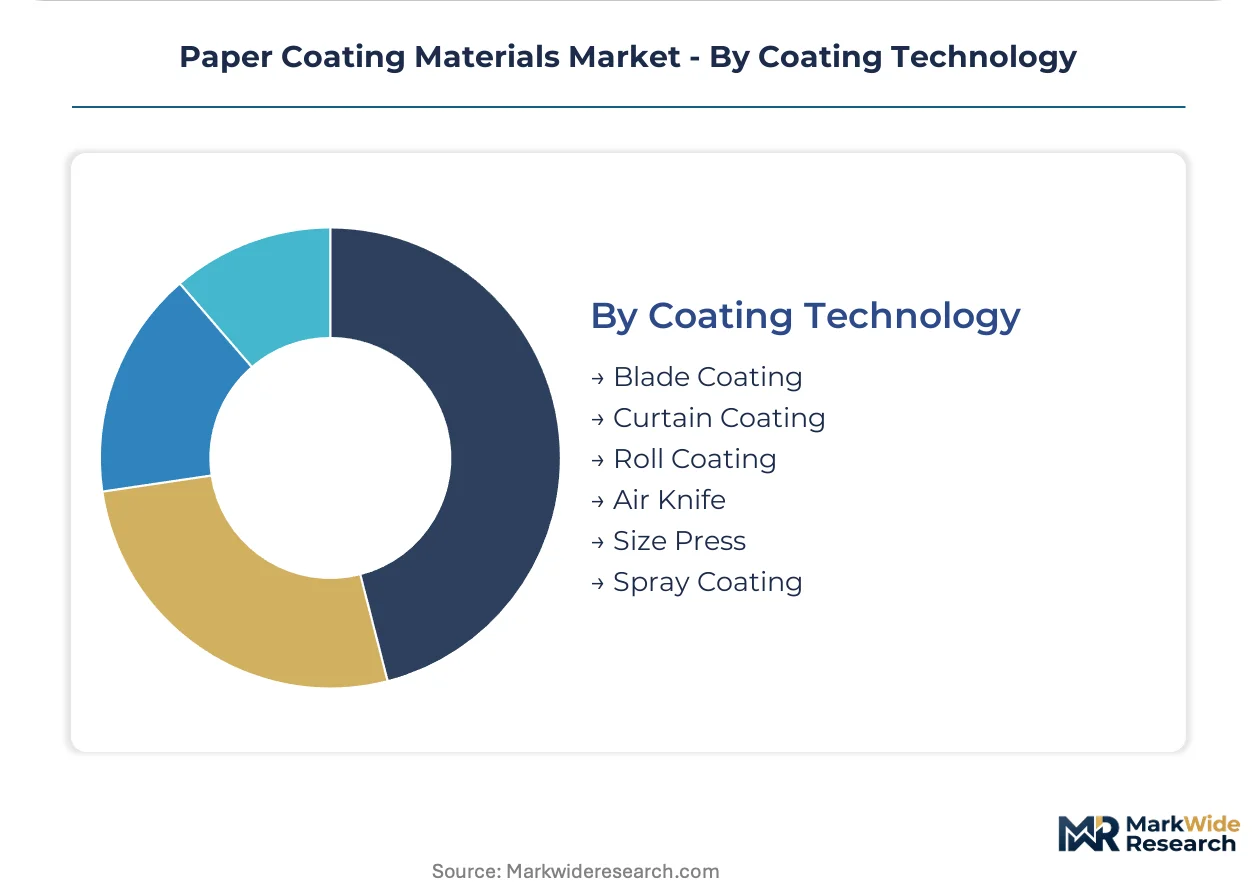
Coating technologies vary significantly in their maturity, precision, and suitability for different paper types and functional requirements.
- Blade Coating:
This widely used method applies coating slurry with a flexible blade, producing high-quality, smooth, and glossy surfaces. It is prevalent in graphic paper and general packaging board.
- Size Press:
Integrated into the paper machine, the size press applies a thin layer of coating or sizing solution, improving paper strength and printability. It is cost-effective for bulk paper grades.
- Curtain Coating:
This advanced method involves a free-falling curtain of coating liquid, offering precise, uniform application for high-barrier packaging.
- Roll Coating:
Roll coaters transfer coating material directly onto the paper surface, suitable for various paper grades and simpler coating applications.
- Air Knife:
An air knife removes excess coating, achieving smooth, uniform layers, particularly for heavier coat weights and board applications.
- Spray Coating:
Spray coating applies fine droplets of coating material, suitable for selective application or adding functional layers to complex shapes.
Blade Coating handles the majority of volume, as advanced techniques like Curtain Coating gain traction for specialized barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturing exports to European and North American consumer markets drive significant demand for advanced paper coating materials. This trade flow emphasizes the need for durable and sustainable packaging solutions, influencing material innovation across continents. Regional regulatory frameworks and economic expansion patterns significantly shape market development.
China
The extensive e-commerce sector and export-oriented manufacturing in China stimulate demand for high-performance packaging coatings. China's dual carbon goals promote the adoption of bio-based and recyclable coating solutions for paperboard. The Yangtze River Delta region, a major manufacturing hub, sees concentrated activity in packaging material production and application.
Germany
Germany's focus on sustainable packaging and high-performance industrial applications generates demand for advanced barrier coatings. The EU Green Deal and REACH regulation compel formulators to develop environmentally compliant and safe coating chemistries. North Rhine-Westphalia, with its strong chemical and paper industries, remains a key center for coating material innovation.
United States
Demand in the United States centers on food-contact packaging and consumer packaged goods, requiring coatings with specific barrier properties. The US FDA sets stringent guidelines for food-contact substances, influencing material composition and approval processes. The Southeast region, home to numerous pulp and paper mills, represents a significant area for coating material consumption.
Japan
Japanese industries prioritize premium graphic papers, specialized packaging, and hygiene products, driving demand for high-quality, functional coatings. METI initiatives support research into sustainable materials and circular economy principles within the packaging sector. The Kanto region, encompassing Tokyo, hosts major manufacturing and consumer goods companies requiring advanced coated paper products.
India
India's growing consumer base and organized retail sector contribute to expanding demand for coated packaging materials and hygiene products. BIS standards govern product quality and safety for paper and paperboard applications, influencing coating formulations. Maharashtra, with its large industrial base, serves as a primary hub for packaging manufacturers and paper converters.
Paper Coating Materials Market Key Industry Players
Listed leaders compete with private specialists across the paper coating materials value chain, driving innovation and market share. The competitive structure features a mix of large chemical conglomerates and specialized mineral suppliers. Strategic archetypes include integrated material producers, niche barrier solution providers, and bulk pigment suppliers. Dominant competitive moves include portfolio diversification into sustainable offerings and strategic partnerships for technology co-development.
On the integrated material production vector, Germany-based BASF SE and US-based Dow Inc. anchor significant market share with their extensive polymer chemistry portfolios. These companies supply synthetic latex binders critical for high-performance packaging applications. Switzerland-based Omya AG exemplifies the specialized mineral supplier archetype, dominating the supply of ground calcium carbonate for bulk paper and board coatings.
| Leading Market Players |
|---|
| Omya AG |
| Michelman, Inc. |
| BASF SE |
| Nippon Paper Industries Co., Ltd. |
| Asia Pulp & Paper |
| Dow Inc. |
| Eastman Chemical Company |
| Stora Enso Oyj |
| Imerys S.A. |
| Others |
Cost & Logistics Intelligence
Extended lead times for novel bio-based coating chemistries directly influence their market pricing power and reshape supply chain investments. This dynamic creates distinct cost structures for traditional and sustainable paper coating materials, impacting producer margins.
Pricing Analysis
The pricing gap between conventional petroleum-derived coatings and novel bio-based formulations remains substantial. Commodity spot pricing often applies to mineral-based products like calcium carbonate, while specialized bio-coatings command value-based pricing due to their enhanced barrier properties and sustainability credentials. Input cost volatility for synthetic latex and polymer binders creates margin pressure for formulators. Packaging manufacturers demonstrate lower price sensitivity for high-performance solutions compared to publication producers who prioritize cost-effectiveness.
Supply Chain Analysis
Days-of-inventory for critical polymer binders fluctuate with petrochemical feedstock availability, directly impacting coating material supply. Supply concentrates in chemical manufacturing hubs like Germany and China, alongside major mineral extraction sites for calcium carbonate. The supply chain depends on raw materials such as synthetic latex, polymer binders, and bio-based starches. Input cost volatility for petrochemicals represents a significant structural risk for formulators. Distribution primarily runs through direct sales from large chemical companies and mineral suppliers to paper mills and paper converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
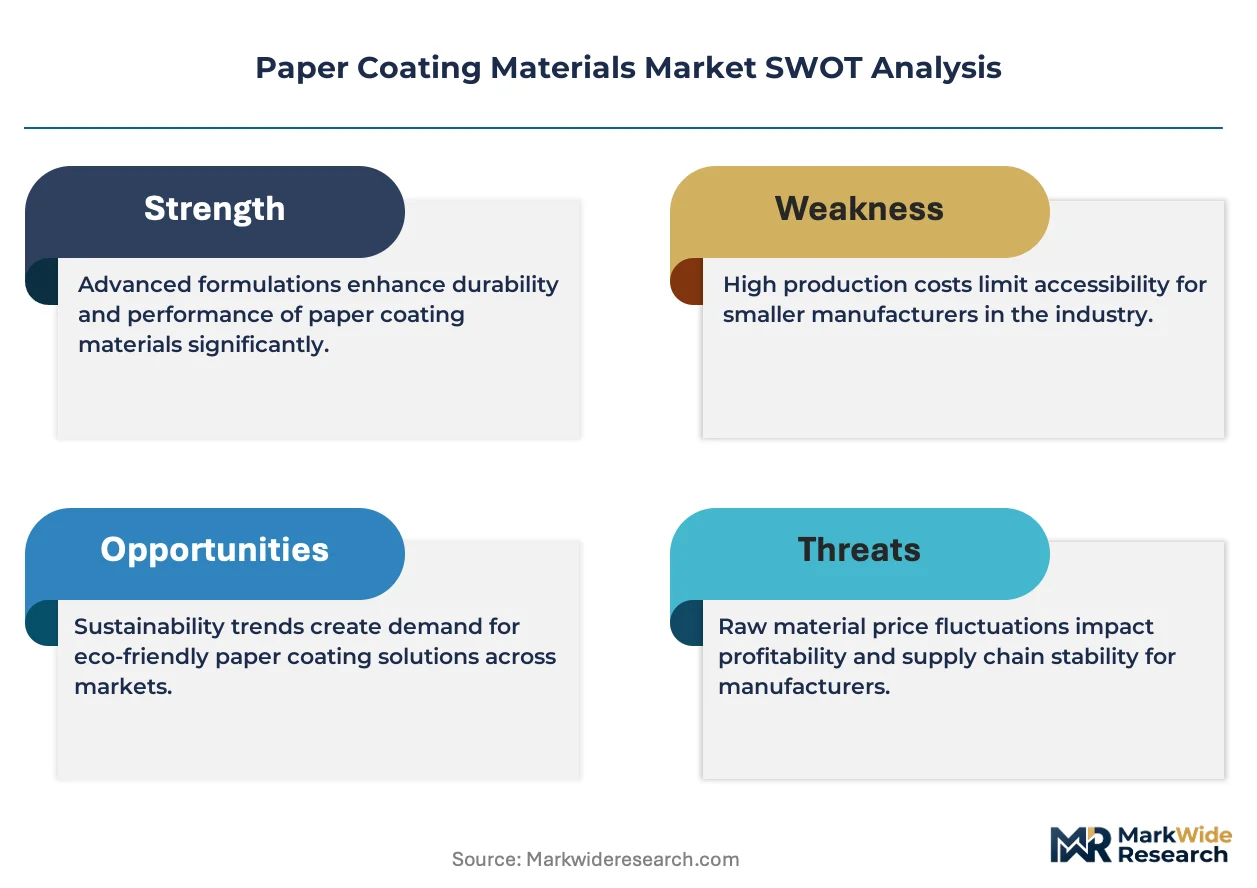
The paper coating materials market faces a significant gap in integrated bio-coating application capabilities. Bridging the performance and processability divide for sustainable formulations requires specialized engineering expertise and capital investment.
For Market Incumbents: Secure long-term supply agreements for bio-based feedstocks to mitigate input cost volatility. Diversify polymer chemistry portfolios into advanced compostable and recyclable solutions, anticipating stricter EU Green Deal regulations. Invest in certification processes for food-contact substances, validating new chemistries for specific applications. Strategic partnerships with specialized bio-material developers can counter emerging entrant archetypes in high-performance barrier coatings.
For New Entrants and Emerging Players: Application-specific formulation support for novel bio-based barriers represents an underserved segment. Target specialized coatings for molded fiber products, which replace plastic clamshells in food service. Focus on developing functional additives that improve recyclability during repulping, addressing a critical unmet need. Southeast Asian markets present a penetrable geography through localized technical support.
For Investors and Strategic Acquirers: Carve-out targets emerge from large chemical conglomerates seeking to divest non-core polymer divisions. The market exhibits long-term viability, driven by the global sustainability transition over the next decade. Seek niche barrier solution providers with validated food-contact approvals and strong intellectual property in bio-based chemistries. Increased venture capital funding into bio-polymer startups serves as a key signal to watch for acquisition opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Shifts production processes to align with stringent EU REACH regulations for chemical substances. |
| Long-term Supply Agreement | Secures consistent access to bio-based feedstocks, mitigating input cost volatility for formulators. |
| Joint Venture | Accelerates co-development of advanced bio-based barrier polymers with specialized material science firms. |
| Capacity Expansion | Addresses the expanding demand for durable e-commerce packaging in the Chinese market. |
| Product Launch | Introduces novel compostable and recyclable coating solutions, meeting brand owner sustainability demands. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during primary interviews to gather granular market insights. Discussions engaged coating formulators, paper mill managers, packaging manufacturers, and regulatory affairs specialists. Secondary validation utilized data from US FDA guidelines, EU REACH documents, and relevant trade association reports. Analysts applied both bottom-up and top-down triangulation.
The analytical framework projected market trajectories across the analysis window using a robust quantitative model. Segmentation dimensions included product type, application, end-user industry, coating technology, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical data analysis and future trend projections. Key inputs included e-commerce growth rates and plastic ban implementation timelines.
Forecasts assume regulatory continuity in the EU, US, and China; material policy shifts would require re-modeling. Unforeseen raw material price spikes or accelerated bio-material breakthroughs represent key risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Recovered Paper Market
Paper Products
Paper and Board Technologies Market
Paper Products
GCC Stone Paper Market
Paper Products
Medium Density Fiberboard Market
Paper Products
Wood-Based Panel Market
Paper Products
Middle East and Africa Decor Paper Market
Paper Products
Specialty Paper Market
Paper Products
Uncoated Fine Paper Market
Paper Products
Reprographic Paper Market
Paper Products
Office Printing Papers Market
Paper Products
Chemical Pulp Market
Paper Products
Overlay Paper Market
Paper Products
Paper Core Market
Paper Products
Compressed Fiberboard Market
Paper Products
Global Kraft Paper Market
Paper Products
Decorative Plastic and Paper Laminates Market