
 Global Sputter Coatings Market | 2026-2036
Global Sputter Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sputter Coatings Market Foresight
Japanese target materials suppliers is rebalancing capacity toward high-purity metals for EUV lithography nodes. Umicore leverages integrated refining-to-target manufacturing to secure rare metal supply chains for semiconductor clients. Heraeus anchors European demand through precious metal recycling and thin-film expertise in optical coatings.
Sputter coatings are thin films deposited by ion bombardment of a solid target, typically achieving thicknesses from nanometers to micrometers with precise stoichiometric control. The process operates under vacuum conditions where inert gas ions dislodge target atoms that condense on substrates, serving primarily to enhance hardness, corrosion resistance, electrical conductivity, or optical properties in precision components. Titanium nitride and diamond-like carbon coatings dominate tool manufacturing applications where wear resistance commands premium pricing. Magnetron sputtering equipment occupies the largest installed base, while ion beam sputtering captures niche optical fabrication segments requiring atomic-scale surface precision.
EPA regulations in the United States restrict hexavalent chromium emissions from conventional electroplating, redirecting demand toward compliant physical vapor deposition alternatives. REACH and RoHS frameworks in Europe mandate substitution of hazardous substances in electronics, accelerating qualification of aluminum oxide and silicon carbide barrier layers for electronic packaging. Japan's METI enforces energy efficiency standards that favor sputtered coatings over thermal processes in precision manufacturing. Stakeholders must evaluate deposition technology roadmaps against evolving substance restrictions and regional clean-energy incentives to align capacity investments with compliant demand pools.
Market Dynamics
Semiconductor node shrinkage below 7nm is forcing deposition equipment upgrades across East Asian fabrication clusters, as EUV lithography requires ultra-high-purity target materials with sub-ppm contamination thresholds.
Growth Catalysts
- EPA Emissions Rules:United States restrictions on hexavalent chromium electroplating redirect automotive and aerospace finishing contracts toward compliant physical vapor deposition processes.
- Semiconductor Fabrication:EU chip subsidies under the European Chips Act accelerate capacity builds in Dresden and Leuven, pulling demand for advanced sputtering targets.
- Japan METI Efficiency Standards:Energy consumption mandates favor sputtered coatings over thermal spray in precision component manufacturing, tightening process specifications.
Market Restraints
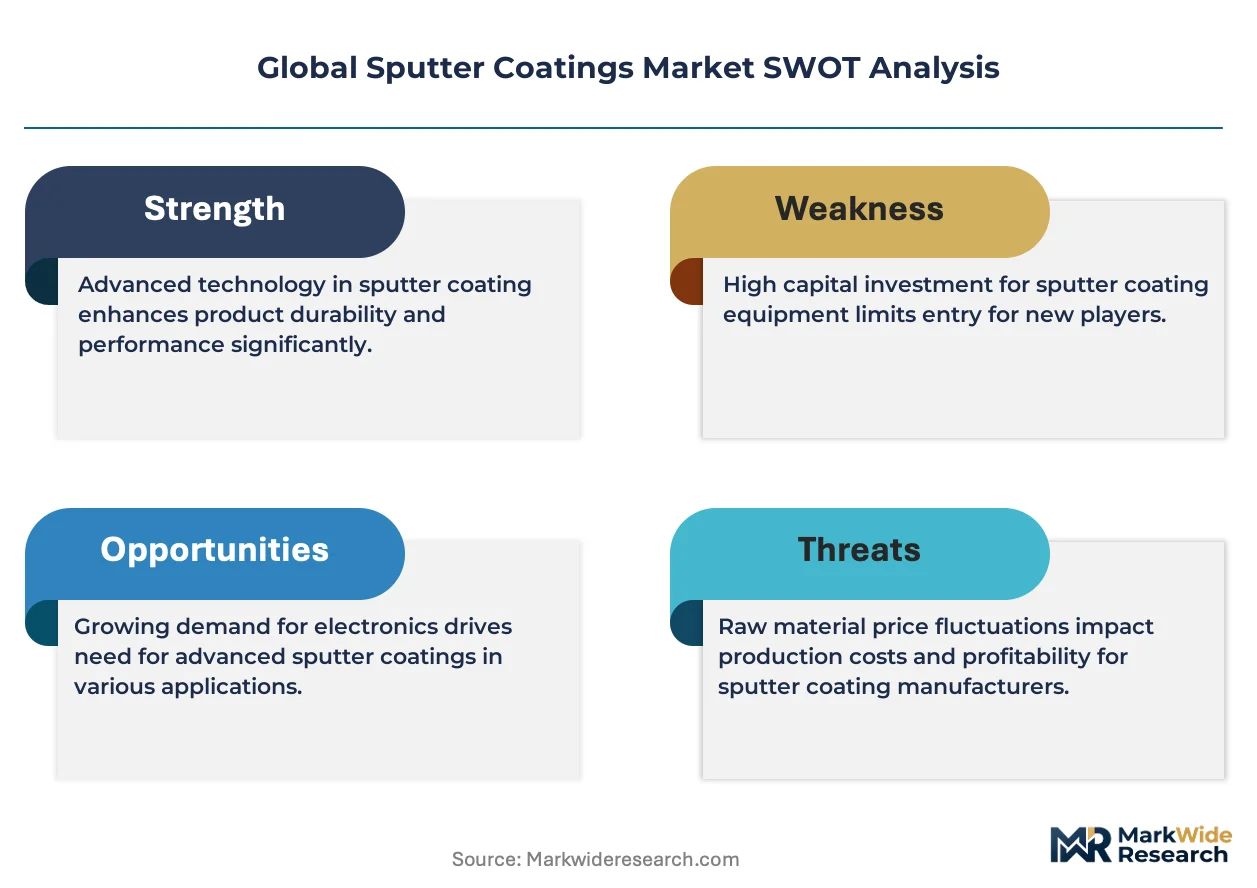
- Rare Metal Supply Concentration:High-purity tantalum and ruthenium refining capacity clusters in Chinese and Russian feedstock channels, creating single-source vulnerability for semiconductor target producers.
- Capital Intensity:Magnetron sputtering systems require vacuum chambers, power supplies, and gas handling infrastructure exceeding $2 million per deposition line.
- Technical Limitation:Conventional DC magnetron sputtering struggles with insulating oxide targets, forcing expensive RF power supply retrofits or alternative process qualification.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging and display fabrication create first-mover advantage for deposition equipment suppliers establishing local service networks.
- Battery Solid-State Electrolytes:Sulfide and oxide ceramic thin-film deposition for next-generation lithium-metal batteries opens qualification pathways outside traditional electronics.
- EU Green Deal Funding:Horizon Europe grants for hydrogen economy infrastructure specify corrosion-resistant coatings for electrolyzer bipolar plates, redirecting R&D budgets.
Industry Challenges
- Vacuum Technician Shortage:Specialized skills for leak detection, gas purity management, and plasma diagnostics face generational attrition in mature manufacturing economies.
- Multi-Site Qualification Burden:Automotive and medical device OEMs require identical coating properties across geographically dispersed production lines, complicating process transfer.
- Legacy Equipment Integration:Retrofitting 1990s-era batch coaters with modern gas flow controllers and thickness monitoring creates control architecture incompatibilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sputter Coatings Market |
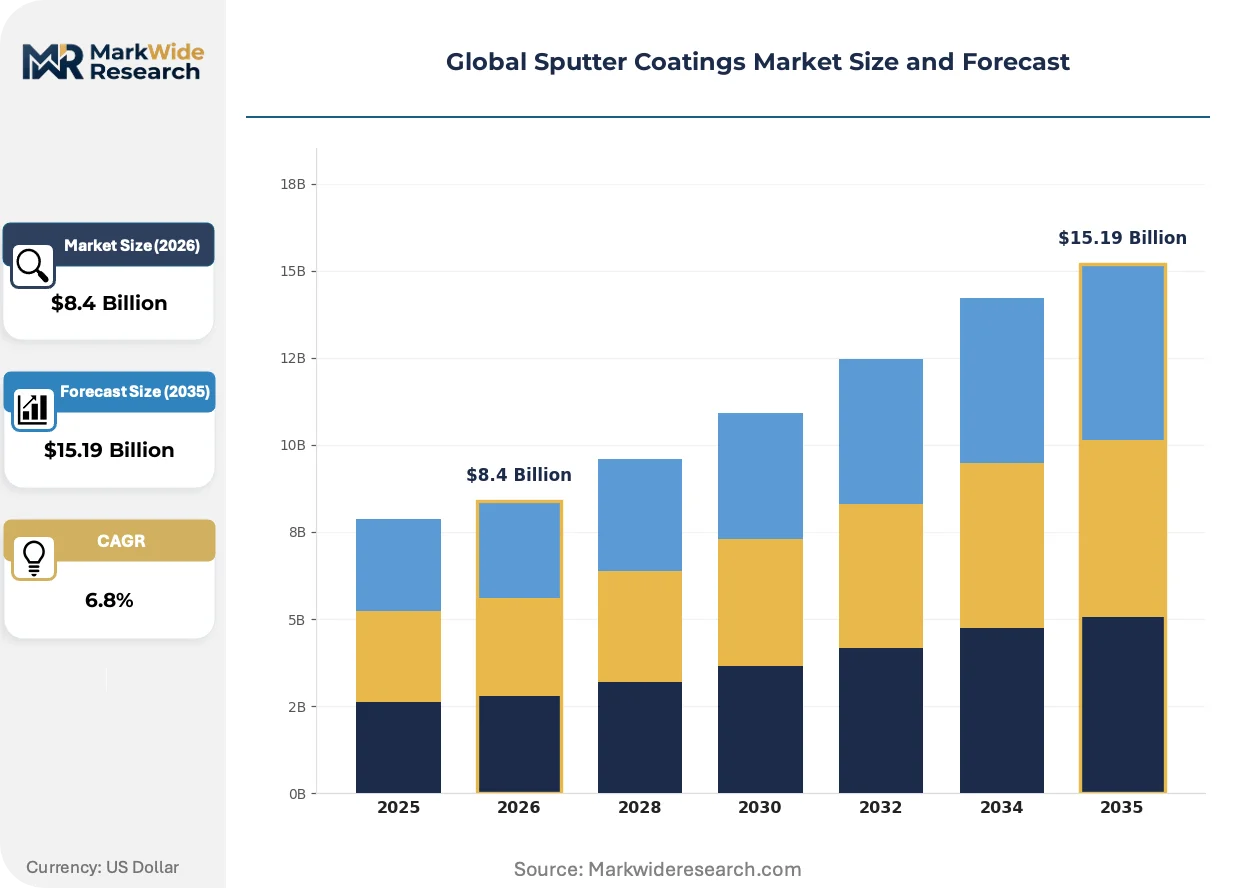
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Material Type: Titanium Nitride, Chromium Nitride, Zirconium Oxide, Diamond-Like Carbon, Aluminum Oxide, Silicon Carbide Application: Cutting Tools, Decorative Surfaces, Semiconductor Devices, Optical Components, Aerospace Parts, Electronic Packaging Deposition Technology: Magnetron Sputtering, Reactive Sputtering, Radio Frequency Sputtering, Direct Current Sputtering, Pulsed DC Sputtering, Ion Beam Sputtering End User Industry: Tool Manufacturing, Consumer Electronics, Aerospace Engineering, Optical Fabrication, Packaging Solutions, Semiconductor Fabrication |
| Companies Covered | Umicore, Oerlikon Balzers, Materion Corporation, Veeco Instruments Inc., Kurt J. Lesker Company, JX Nippon Mining & Metals Corporation, Heraeus, Tosoh SMD, Inc., ULVAC, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sputter Coatings Market Shifts & Advancements
Deposition technology roadmaps are converging on atomic-scale precision as end-users specify functional properties rather than thickness tolerances alone.
High-entropy alloy targets are absorbing qualification momentum in wear-resistant tooling applications. Cutting insert manufacturers in Germany and Japan specify these multi-principal-element compositions for thermal stability beyond 800°C. The technology is absorbing market share from conventional titanium nitride in high-speed machining segments.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer-based corrosion barriers in European food processing equipment. Coating houses in Italy and the Netherlands pivot toward ceramic oxide alternatives for compliance. Medical device packaging in Ireland faces the tightest substitution timelines.
Consolidated procurement through tier-one semiconductor equipment OEMs is compressing target supplier margins. Applied Materials and Lam Research now specify annual price-down trajectories and consignment inventory models. Japanese and Korean sputtering target vendors absorb the working capital burden most acutely.
Global Sputter Coatings Market Segmentation
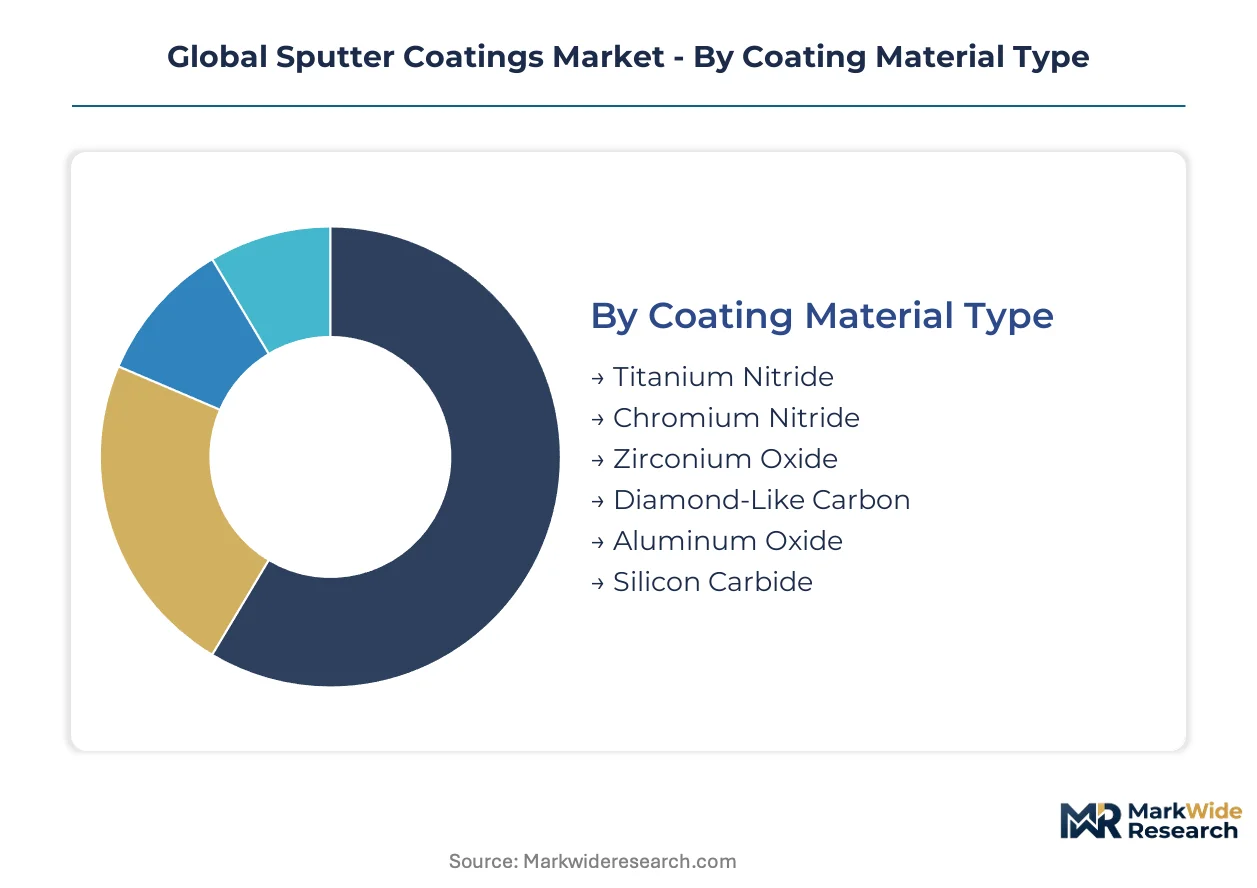
Sputter coatings demand fragments across material chemistries, deposition physics, and end-use specifications. Each segmentation axis carries distinct margin profiles and qualification barriers that reshape supplier positioning.
Coating Material Type:
Standardization dominates commodity nitrides while oxide and carbide formulations require custom stoichiometry for semiconductor clients.
- Titanium Nitride:Golden-yellow ceramic coating deposited from metallic titanium targets in nitrogen atmosphere. Cutting tool manufacturers in Germany and Japan specify TiN for its balance of hardness and low coefficient of friction against ferrous workpieces.
- Diamond-Like Carbon:Amorphous carbon films combining sp2 and sp3 bonding achieve superlubricity below 0.1 friction coefficient. Automotive component suppliers specify DLC for fuel injector needles and valve train parts where boundary lubrication fails.
- Chromium Nitride:Gray-silver coating offering superior corrosion resistance versus TiN in marine environments. Decorative applicators favor CrN for faucet and hardware finishes requiring salt spray endurance.
- Zirconium Oxide:Thermal barrier properties suit turbine blade applications. Aerospace repair stations specify yttria-stabilized variants for oxidation protection.
- Aluminum Oxide:Dielectric barrier layers in electronic packaging substitute for fluoropolymer coatings under REACH restrictions. Irish medical device packaging houses drive qualification timelines.
- Silicon Carbide:Wide bandgap semiconductor applications and extreme environment wear protection. Limited installed capacity constrains volume expansion.
Most installed capacity flows through Titanium Nitride. Expansion is steepest in Diamond-Like Carbon.
Application:
Volume concentration sits in tooling while value concentration shifts toward semiconductor and optical segments demanding atomic-scale precision.
- Semiconductor Devices:Interconnect barrier layers, gate electrodes, and hard masks for EUV lithography. Sub-ppm contamination thresholds force target material suppliers into integrated refining operations.
- Cutting Tools:Inserts, drills, and end mills for high-speed machining. German and Japanese tool manufacturers specify high-entropy alloy variants for thermal stability beyond 800°C.
- Optical Components:Anti-reflection and filter coatings for laser systems and imaging equipment. Ion beam sputtering dominates where surface roughness must stay below 0.5nm.
- Electronic Packaging:Hermetic seals and thermal management layers. Lead-free solder compatibility drives aluminum oxide substitution.
- Aerospace Parts:Erosion-resistant turbine coatings and corrosion barriers for landing gear. FAA certification cycles extend qualification timelines.
- Decorative Surfaces:Architectural hardware and luxury goods finishing. Price pressure from electroplating alternatives compresses margins.
Cutting Tools absorbs the largest equipment footprint. Semiconductor Devices commands the steepest expansion trajectory.
Deposition Technology:
Capital intensity separates batch-scale magnetron systems from precision ion beam installations requiring cleanroom infrastructure.
- Magnetron Sputtering:Magnetic confinement of plasma enables deposition rates exceeding 100nm per minute. The largest installed base serves automotive and tooling applications where throughput dominates economics.
- Ion Beam Sputtering:Separate ion source eliminates target poisoning and achieves stoichiometric precision for optical multilayers. German precision optics houses specify IBS for laser mirror fabrication.
- Reactive Sputtering:Process gas introduction during metallic target erosion forms compound coatings in situ. Titanium nitride production relies on nitrogen injection control.
- Radio Frequency Sputtering:AC power delivery overcomes charge accumulation on insulating oxide targets. RF retrofit costs burden legacy DC system operators.
- Pulsed DC Sputtering:Microsecond polarity reversal reduces arcing on reactive processes. Emerging preference for aluminum oxide barrier deposition.
- Direct Current Sputtering:Simplest power architecture limited to conductive targets. Lowest equipment cost sustains presence in commodity coating operations.
Magnetron Sputtering carries the dominant equipment base. Ion Beam Sputtering is gaining share fastest in precision segments.
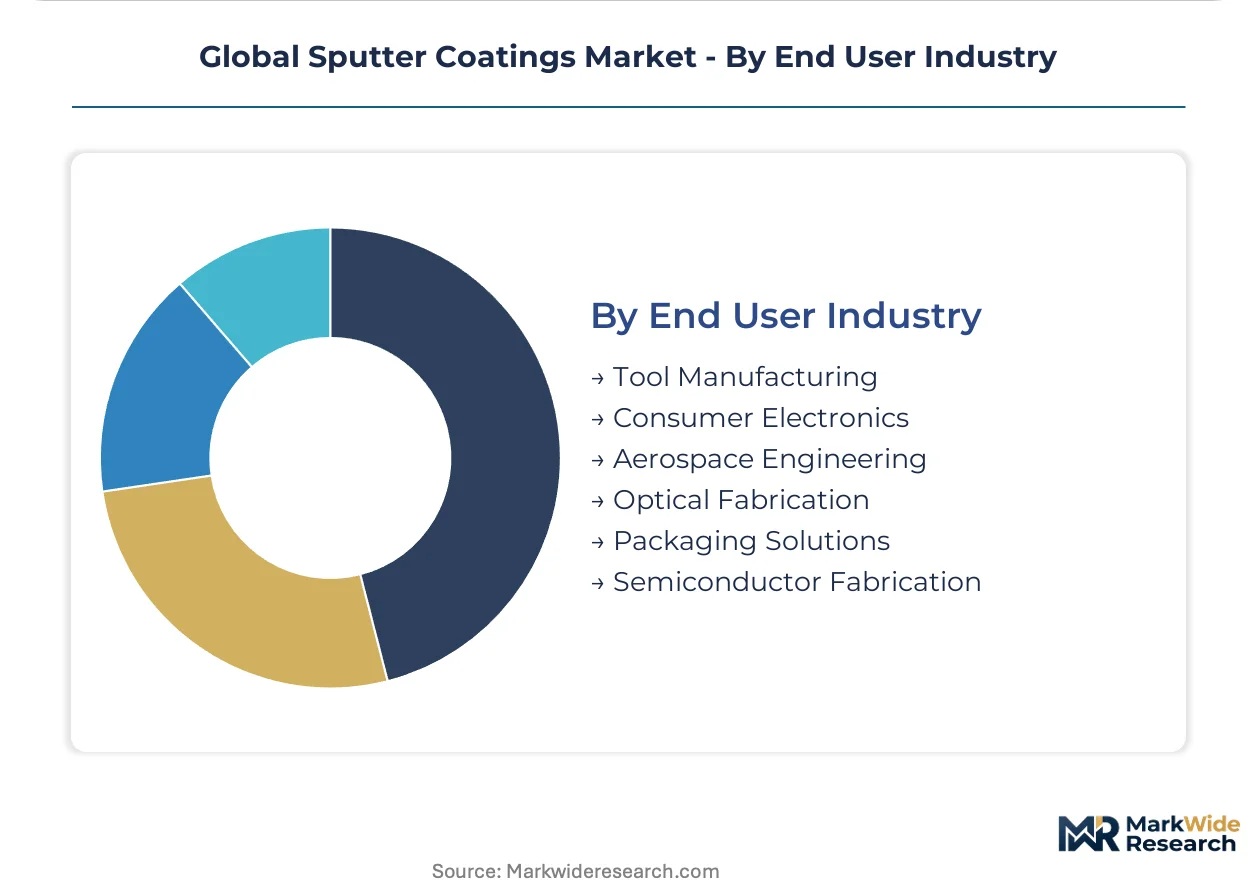
End User Industry:
Procurement sophistication varies from consolidated semiconductor equipment OEMs to fragmented job shop networks in tooling.
- Semiconductor Fabrication:EUV lithography nodes below 7nm drive target purity requirements. Applied Materials and Lam Research specify annual price-down trajectories and consignment inventory models.
- Tool Manufacturing:High-entropy alloy qualification absorbs R&D investment from German and Japanese cutting insert producers. Volume concentration in East Asian machining clusters.
- Consumer Electronics:Display panel electrodes and smartphone component finishing. Korean and Chinese device assemblers drive coating specification standardization.
- Aerospace Engineering:FAA and EASA certification requirements for flight-critical components. Repair station networks concentrate demand in Dallas, Toulouse, and Singapore.
- Optical Fabrication:Laser system manufacturers and telescope mirror coaters. German and Japanese precision optics houses maintain captive deposition capacity.
- Packaging Solutions:Food processing equipment corrosion barriers under REACH fluoropolymer restrictions. Italian and Dutch coating houses pivot toward ceramic oxide alternatives.
Tool Manufacturing represents the largest addressable equipment base. Semiconductor Fabrication shows the most rapid capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands the highest purity standards for EUV lithography targets, while the United States redirects automotive finishing demand through EPA emissions enforcement. Germany anchors European optical fabrication capacity.
United States
EPA restrictions on hexavalent chromium electroplating redirect aerospace and automotive finishing contracts toward compliant physical vapor deposition processes. The FAA maintains certification requirements for flight-critical coated components. Dallas repair stations and Pacific Northwest machining clusters absorb upgraded magnetron sputtering capacity.
Germany
High-entropy alloy qualification absorbs R&D investment from cutting insert producers in Stuttgart and Solingen. REACH substance restrictions on fluoropolymers eliminate corrosion barriers in food processing equipment. Bavarian and North Rhine-Westphalian coating houses pivot toward ceramic oxide alternatives for compliance.
Japan
METI energy efficiency standards favor sputtered coatings over thermal spray in precision component manufacturing. Sub-ppm contamination thresholds for EUV lithography nodes force target material suppliers into integrated refining operations. Tokyo-Osaka manufacturing corridors feed global electronics supply chains with advanced deposition capacity.
South Korea
Display panel electrode fabrication and smartphone component finishing drive coating specification standardization. Samsung and LG device assemblers consolidate procurement through captive supplier networks. Seoul-Incheon manufacturing clusters concentrate reactive sputtering capacity for titanium nitride production.
Taiwan
TSMC-led semiconductor fabrication below 7nm nodes pulls demand for ultra-high-purity tantalum and ruthenium targets. Consignment inventory models compress supplier margins for Japanese and Korean target vendors. Hsinchu Science Park anchors the densest concentration of EUV lithography deposition equipment globally.
Global Sputter Coatings Market Competitive Landscape
Japanese producers anchor the high-purity target tier; German and Belgian specialists hold integrated refining-to-coating positions. The vendor base separates into three strategic archetypes: captive refiners controlling rare metal supply chains, equipment-integrated coating houses, and independent target material suppliers. Consolidated procurement through Applied Materials and Lam Research forces annual price-down trajectories. Backward integration into rare metal refining represents the dominant competitive move alongside regional service network expansion.
Within the integrated refiner archetype, Umicore and Heraeus exemplify European upstream control over rare metal supply chains for semiconductor clients. Japanese specialists JX Nippon Mining & Metals Corporation and Tosoh SMD occupy positions within the high-purity target tier, while Veeco Instruments represents equipment-integrated coating technology. These named entities anchor industry-level commentary on supply chain configuration and customer consolidation pressures without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| Umicore |
| Oerlikon Balzers |
| Materion Corporation |
| Veeco Instruments Inc. |
| Kurt J. Lesker Company |
| JX Nippon Mining & Metals Corporation |
| Heraeus |
| Tosoh SMD, Inc. |
| ULVAC, Inc. |
| Others |
Supply & Pricing Matrix
Vacuum technician concentrations in Stuttgart and Osaka widen labor-cost spreads between precision optical coating tiers and commodity tooling finishes. METI-mandated energy efficiency standards in Japan compress process economics for thermal spray alternatives, while EPA emissions enforcement in the United States redirects automotive finishing contracts toward compliant physical vapor deposition channels.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for high-purity tantalum targets as consignment inventory models compress supplier margins. Three-tier pricing structure across premium, standard, and economy levels separates EUV-grade sub-ppm targets from display panel electrodes and decorative hardware finishes. Price differentiation hinges on certification grade and volume scale, with semiconductor equipment OEMs extracting annual price-down trajectories. Cost compression in the standard tier intensifies because Japanese and Korean vendors absorb working capital burdens. Automotive job shops exhibit highest price sensitivity; semiconductor fabrication commands lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Applied Materials and Lam Research, while independent coating houses serve fragmented tooling networks. Geographic supply concentrates in Japan, South Korea, and Taiwan for advanced deposition capacity. Raw material dependencies draw from high-purity tantalum, ruthenium, and rare metal feedstocks. Single-source vulnerability clusters in Chinese and Russian refining channels for critical semiconductor targets. Distribution runs through tier-one equipment OEMs with consignment models, captive supplier networks in Korean display fabrication, and regional service hubs for automotive finishing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in sputter coatings rests on backward integration into rare metal refining and premium-tier qualification for EUV lithography nodes below 7nm. Semiconductor fabrication's contamination thresholds create pricing power insulation unavailable in commodity tooling segments.
For Market Incumbents: Anchor high-purity target supply through integrated refining-to-target manufacturing as Umicore and Heraeus demonstrate in European rare metal channels. Defend against emerging Indian deposition equipment suppliers by establishing local service networks ahead of PLI scheme maturation. Prioritize certification investment for REACH-compliant aluminum oxide barrier layers as fluoropolymer substitutes face elimination timelines. For New Entrants and Emerging Players: Launch via equipment-integrated coating partnerships targeting India's semiconductor packaging and display fabrication incentives. White-space concentration sits in solid-state battery electrolyte deposition for sulfide and oxide ceramic thin-films outside traditional electronics. The most penetrable segment is European hydrogen economy infrastructure under EU Green Deal funding for electrolyzer bipolar plate coatings. For Investors and Strategic Acquirers: Semiconductor equipment OEMs are the most active acquirer in this space, consolidating target supplier networks through annual price-down specifications and consignment inventory mandates. Long-term viability favors integrated refiners controlling rare metal supply chains over independent target material vendors exposed to procurement compression. Watch for inflection in India's electronics manufacturing PLI scheme uptake as deposition capacity localization signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Metal Refining | Umicore secures tantalum supply chains for semiconductor target clients through captive refining capacity. |
| Regional Service Network Expansion | First-mover deposition equipment suppliers capture India's PLI scheme incentives for semiconductor packaging. |
| REACH-Compliant Coating Qualification | Italian and Dutch coating houses pivot toward ceramic oxide alternatives as fluoropolymer barriers face elimination. |
| EUV Lithography Target Purity Investment | JX Nippon Mining and Tosoh SMD occupy sub-ppm contamination tier for nodes below 7nm. |
| Solid-State Battery Electrolyte Deposition | Sulfide and oxide ceramic thin-film pathways open qualification outside traditional electronics applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with vacuum technicians, plant managers at deposition facilities, procurement leads at semiconductor equipment OEMs, and technical R&D directors at target material suppliers with secondary validation. Sources included customs and trade data for rare metal feedstocks, SEC filings from coating equipment manufacturers, METI efficiency standard documentation, and EPA emissions rulemaking records. Bottom-up capacity assessments and top-down demand modeling triangulated across segmentation dimensions.
Segment-weighting across material chemistry, deposition technology, and end-use industry shaped the analytical framework throughout the projection horizon. Coating material type splits between commodity nitrides and custom-stoichiometry oxides for semiconductor clients. Application segmentation separates volume-driven tooling from value-concentrated semiconductor and optical fabrication. End-user industry dimension captures procurement sophistication variance from consolidated equipment OEMs to fragmented job shop networks. CAGRs derived from equipment installation rates, target consumption intensity per deposition line, and purity-grade pricing trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare metal supply disruption scenarios or accelerated EUV lithography node transitions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Process Pipe Coating Market
Coatings
Sol Gel Nanocoating Market
Coatings
Phosphate Conversion Coatings Market
Coatings
US Protective Coatings Market
Coatings
Conductive Coatings Market
Coatings
Vinyl Surface Coatings Market
Coatings
Anti-Adhesion Coatings Market
Coatings
Japan Protective Coatings Market
Coatings
Coated Casing Market
Coatings
Asia-Pacific Anti-Friction Coatings Market
Coatings
Global Metal Coatings Market
Coatings
Cladding Coatings Market
Coatings
Hard Coating Market
Coatings
Transparent Conductive Coatings Market
Coatings
North America Anti-Friction Coatings Market
Coatings
Global Surface Protection Films Market