
 North America Polyimide Coating Market | 2026-2036
North America Polyimide Coating Market Size, Share, and Industry Trends Forecast 2026-2036
North America Polyimide Coating Market Insights
EPA volatile organic compound rules for industrial coatings is repositioning the cost-of-entry calculus for new suppliers across the region. DuPont leverages its backward integration into polyimide resin synthesis to sustain margin resilience. Kaneka Corporation anchors its North American position through specialized film coating grades for electronics substrates. Toray Industries competes on thermal barrier performance specifications in aerospace procurement cycles.
North America polyimide coating comprises aromatic heterocyclic polymer formulations applied as thin-film barriers, typically processed through thermal imidization at temperatures exceeding 300°C to achieve dielectric strength above 150 kV/mm and continuous service ratings near 200°C. The primary commercial purpose centers on protecting electronic substrates, wire insulation, and engine components from thermal degradation and corrosive environments. Liquid coating formulations dominate current volume flows due to their compatibility with precision spray and dip application methods in semiconductor packaging operations. Film coating segments command premium positioning where dimensional stability and dielectric performance justify higher unit economics in flexible circuit manufacturing.
FAA airworthiness directives and NHTSA material flammability standards shape product qualification requirements for aerospace and automotive applications respectively, while EPA emission regulations govern solvent-based formulation chemistry across manufacturing facilities. OSHA workplace exposure limits for aromatic amine precursors further constrain process design choices in coating operations. Stakeholders must monitor evolving state-level chemical disclosure mandates in California and New York that could accelerate waterborne formulation transitions.
Market Dynamics
EPA volatile organic compound emission limits for industrial coatings are forcing reformulation investments across the supply base, compressing margins for solvent-dependent producers while advantaging waterborne chemistry specialists.
Growth Catalysts
- Aerospace thermal management demand:FAA airworthiness directives for engine compartment insulation are expanding procurement of high-temperature barrier systems in United States manufacturing corridors.
- Semiconductor packaging miniaturization:California's fabrication corridor requires dielectric coatings with continuous service ratings near 200°C for advanced substrate protection.
- REACH-aligned chemistry transitions:ECHA substance restrictions on aromatic amine precursors are accelerating adoption of modified polyimide resin synthesis pathways in cross-border supply chains.
Market Restraints
- Feedstock concentration risk:Aromatic dianhydride precursors depend on concentrated petrochemical supply from Texas Gulf Coast infrastructure vulnerable to hurricane disruption.
- Thermal imidization energy costs:Processing temperatures exceeding 300°C impose natural gas cost exposure that tracks Henry Hub volatility.
- Ceramic coating substitution:Plasma-sprayed thermal barrier ceramics compete in aerospace applications above 400°C service thresholds.
Strategic Opportunities
- Texas energy infrastructure expansion:LNG export terminal construction and hydrogen pipeline projects require corrosion-resistant high-temperature wire insulation in coastal processing facilities.
- Waterborne formulation penetration:EPA VOC limits create white space for aqueous polyimide dispersions in semiconductor dip-coating operations historically dependent on N-methyl-2-pyrrolidone solvents.
- Flexible circuit manufacturing reshoring:CHIPS Act incentives are repositioning film coating demand toward domestic substrate producers in Arizona and New York.
Industry Challenges
- Specialized polymer synthesis expertise scarcity:Thermal imidization process engineering requires skill sets concentrated among aging workforce cohorts in legacy aerospace coatings facilities.
- FAA qualification timeline compression:New formulation approvals for engine compartment applications face 18-24 month certification cycles that mismatch semiconductor customer ramp schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Polyimide Coating Market |
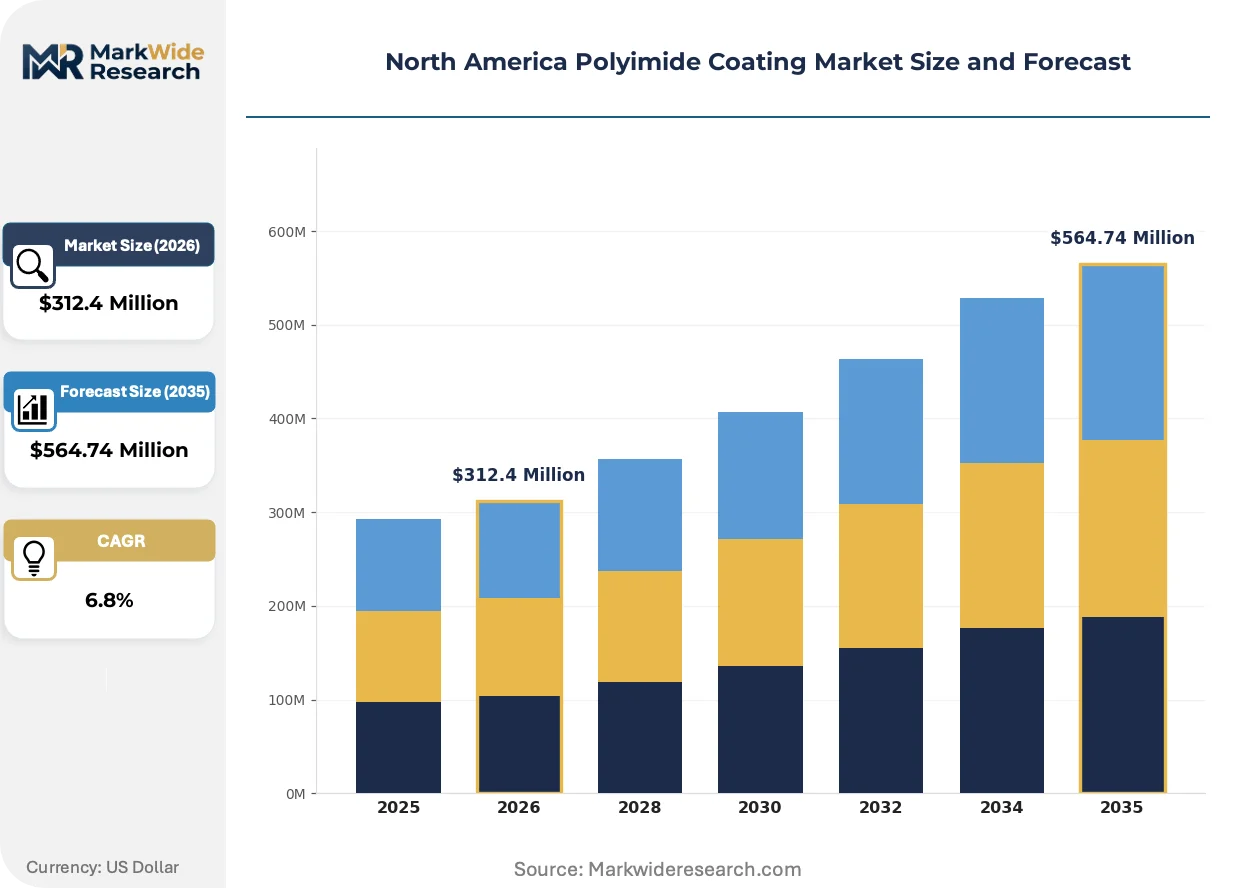
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Coating, Powder Coating, Film Coating, Solution Coating End User Industry: Aerospace, Electronics, Automotive Components, Industrial Equipment Application: Insulation, Adhesives, Anti-Corrosion, Thermal Barriers Form: Spray, Brush, Dip, Roll |
| Companies Covered | DuPont, Kaneka Corporation, Toray Industries, PI Advanced Materials, Saint-Gobain, Ube Industries, FLEXcon Company, UBE Corporation, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Polyimide Coating Market Trends and Innovations
Formulation chemistry, regulatory compliance architecture, and procurement specifications are converging to redefine competitive positioning across the value chain.
Non-fluorinated waterborne polyimide dispersions are electrifying coating application methods in semiconductor packaging operations. Wafer fabrication facilities in California and Arizona are adopting spray-compatible aqueous formulations at pilot scale. This chemistry transition is compressing solvent recovery capital requirements while elevating dielectric performance consistency in thin-film barrier applications.
OSHA workplace exposure limits for aromatic amine precursors are tightening process design constraints in coating operations. Manufacturers must engineer closed-system thermal imidization to maintain OSHA permissible exposure limits below 10 ppm. Aerospace wire insulation producers in the Southeast United States are retrofitting facilities with negative-pressure curing ovens and real-time air monitoring systems.
Specification-driven procurement is consolidating vendor qualification lists across defense electronics programs. Prime contractors in Texas and California are mandating MIL-PRF-46146 certification for all polyimide coating suppliers, displacing commercial-grade alternatives in satellite and avionics applications. This certification compression is visible most acutely in radiation-hardened electronic substrate manufacturing for space systems.
North America Polyimide Coating Market Segmentation
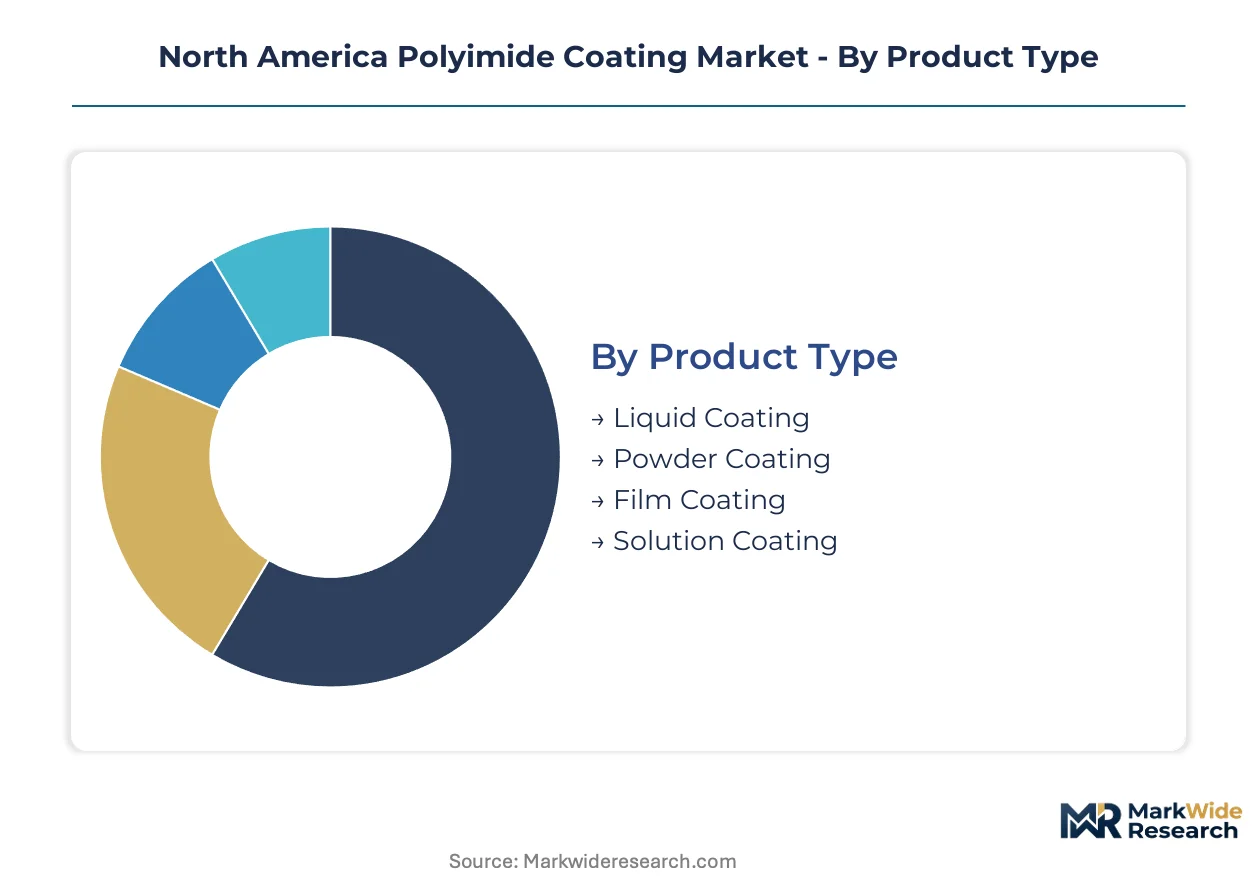
Polyimide coating segmentation in North America reflects divergent technical requirements across precision electronics and heavy industrial applications. Each dimension—product chemistry, end-use sector, functional purpose, and application method—carries distinct margin profiles and qualification barriers that reshape supplier economics.
Product Type:
Liquid formulations dominate standalone coating operations where precision thickness control matters, while film and powder grades embed into integrated manufacturing systems for substrate protection.
- Liquid Coating:Aromatic polyimide precursors dissolved in polar aprotic solvents enable spray and dip application with film thickness precision below 25 micrometers. California semiconductor packaging facilities specify liquid grades for wafer-level dielectric protection where thermal imidization integrates with cleanroom protocols.
- Film Coating:Cast polyimide films with pre-cured imide rings deliver dimensional stability for flexible circuit laminates without solvent exposure. Arizona substrate manufacturers reshoring under CHIPS Act incentives are expanding procurement of film-coated copper clad laminates for high-density interconnect boards.
- Powder Coating:Thermoplastic polyimide particles suit thick-film industrial applications requiring abrasion resistance above 300°C.
- Solution Coating:Low-viscosity polyamic acid solutions target brush and roll application in field repair of aerospace wire insulation.
Liquid coating leads volumes today; film coating is gaining share fastest.
End User Industry:
Cost tier segmentation separates qualification-intensive aerospace programs from price-sensitive industrial equipment procurement.
- Aerospace:FAA airworthiness directives mandate MIL-PRF-46146 certified coatings for engine compartment wire bundles and thermal blankets. Texas and Southeast US manufacturing corridors concentrate demand for high-temperature insulation systems in commercial and defense aircraft programs.
- Electronics:Semiconductor packaging miniaturization requires dielectric coatings with continuous service ratings near 200°C for advanced substrate protection in California's fabrication corridor.
- Automotive Components:NHTSA material flammability standards govern polyimide coating selection for electric vehicle battery thermal management and motor insulation.
- Industrial Equipment:LNG export terminals and hydrogen pipeline projects along the Texas Gulf Coast specify corrosion-resistant wire insulation for coastal processing infrastructure.
Electronics commands premium pricing; aerospace is expanding most quickly.
Application:
Functional purpose determines whether coatings operate as primary protection or auxiliary system components.
- Insulation:Dielectric barrier systems for wire and substrate protection constitute the foundational use case across all end-use sectors.
- Adhesives:Polyimide-based bonding layers enable high-temperature laminate construction in multilayer flexible circuits.
- Anti-Corrosion:Chemical-resistant barrier coatings protect instrumentation in Texas energy infrastructure exposed to sour gas environments.
- Thermal Barriers:Plasma-spray competitive pressure limits polyimide thermal barrier use to sub-400°C aerospace applications.
Insulation anchors current demand; anti-corrosion is climbing the fastest.
Form:
Application method segmentation tracks automation compatibility and labor intensity across manufacturing scales.
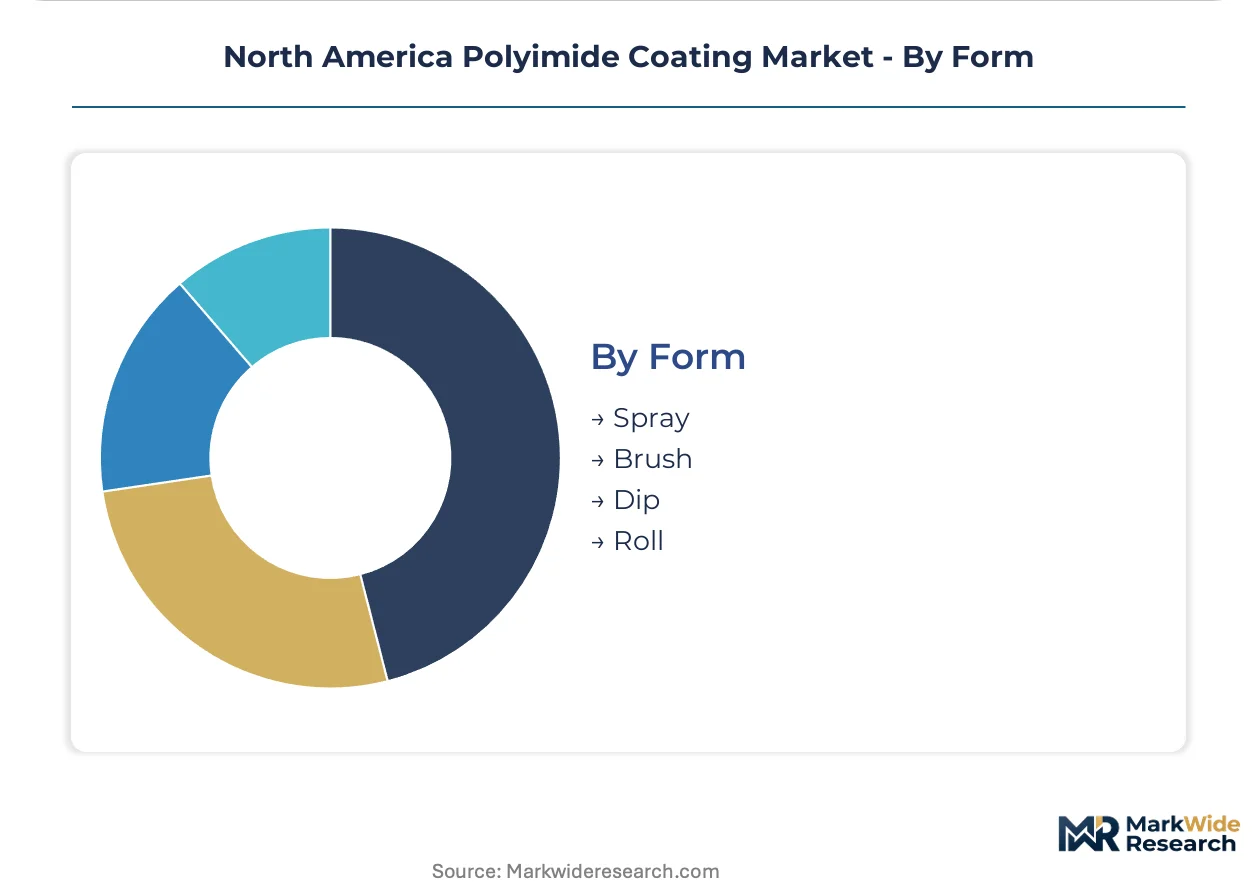
- Spray:Automated spray systems dominate semiconductor packaging operations where throughput and thickness uniformity justify capital investment.
- Dip:Batch immersion coating suits wire harness and small component processing with lower equipment barriers.
- Brush:Manual application persists in aerospace MRO field operations for localized repair and touch-up.
- Roll:Continuous roll-to-roll coating enables high-volume film laminate production for flexible circuit manufacturers.
Spray leads adoption today; dip methods are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer synthesis expertise concentrates in legacy aerospace coatings facilities across the southeastern United States, with thermal imidization process engineering skills becoming scarcer as workforce cohorts age.
United States
California's semiconductor fabrication corridor drives dielectric coating procurement for wafer-level substrate protection, while EPA volatile organic compound limits compel reformulation investments. FAA airworthiness directives expand high-temperature insulation procurement in Texas and Southeast manufacturing corridors for commercial and defense aircraft programs.
Canada
Ontario's automotive wire harness suppliers specify polyimide coatings for electric vehicle battery thermal management systems. Health Canada's chemical substance regulations align with REACH restrictions on aromatic amine precursors. Quebec's aerospace subcontracting cluster near Montreal processes MIL-PRF-46146 certified coatings for satellite avionics applications.
Mexico
Nuevo León's expanding electronics manufacturing services sector imports liquid coating formulations for semiconductor packaging operations. The country's environmental regulator enforces industrial emissions standards tightening solvent-based chemistry constraints. Mexico City Metro area flexible circuit assemblers source film-coated copper clad laminates from US suppliers.
North America Polyimide Coating Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across qualification-intensive segments. The vendor base stratifies into three tiers: integrated resin producers commanding backward integration advantages, specialized coating formulators serving electronics substrates, and regional applicators focused on aerospace wire harness processing. Dominant competitive moves include capacity expansion in waterborne formulation lines and strategic partnerships with semiconductor packaging facilities.
Within the integrated resin producer tier, DuPont and Kaneka Corporation exemplify archetypes leveraging captive polyimide synthesis capabilities. Toray Industries occupies a position representing thermal barrier performance specialization in aerospace procurement cycles. These three anchors illustrate how geographic origin and corporate structure—American, Japanese, and Japanese respectively—map to distinct strategic positioning without determining specific market share outcomes.
| Leading Market Players |
|---|
| DuPont |
| Kaneka Corporation |
| Toray Industries |
| PI Advanced Materials |
| Saint-Gobain |
| Ube Industries |
| FLEXcon Company |
| UBE Corporation |
| Evonik Industries |
| Others |
Pricing and Supply Chain Analysis
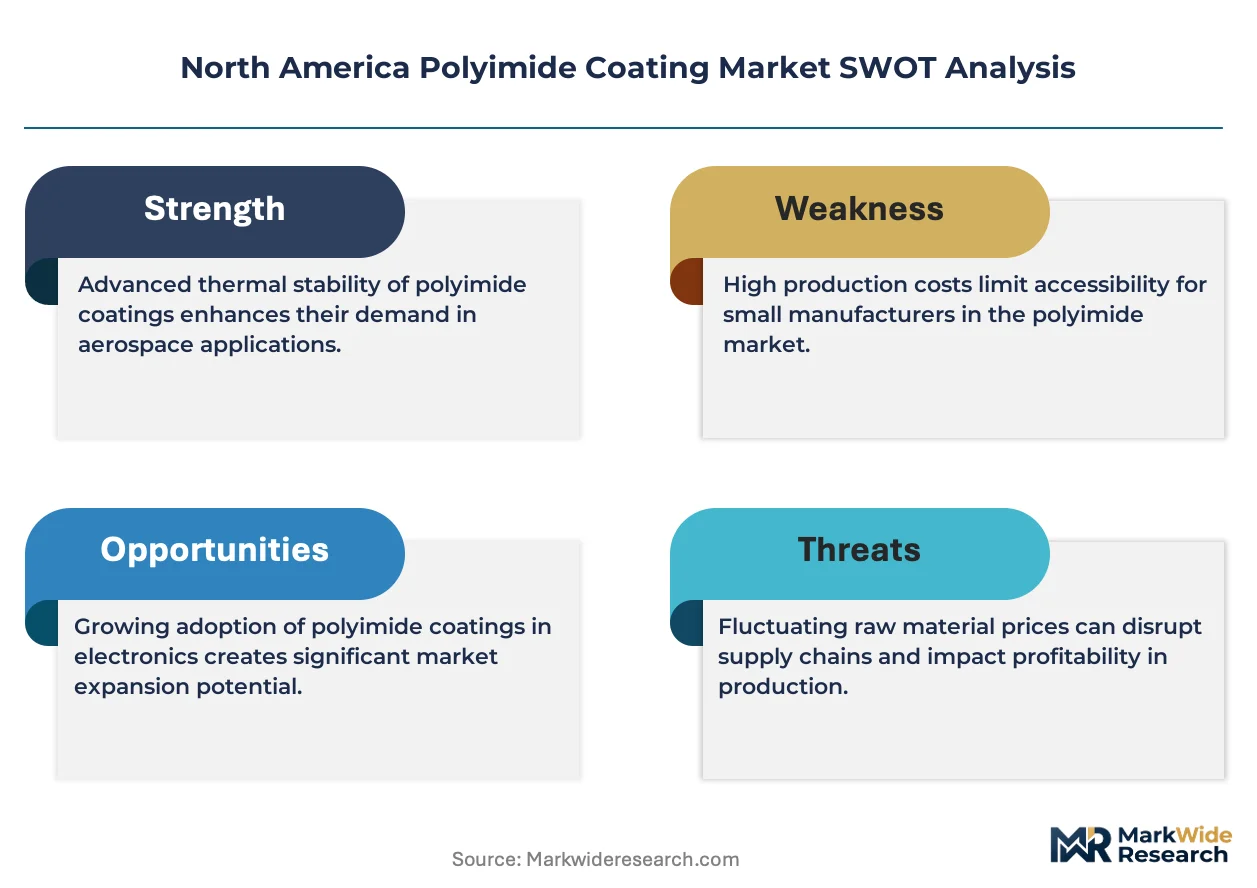
Family-owned mid-cap coating formulators in the southeastern United States anchor supply-side discipline through generational ownership structures that resist cyclical price-cutting. Their captive relationships with legacy aerospace wire harness producers insulate margin structures from commodity volatility while EPA compliance investments selectively pressure solvent-dependent competitors.
Pricing Analysis
Bundled technical service and qualification support separates premium-grade suppliers from unbundled commodity coating vendors. Three-tier pricing structure across MIL-PRF-46146 certified, commercial-grade, and field-repair formulations reflects FAA certification investment recovery. Pricing pressure stems from waterborne formulation R&D amortization costs that solvent-dependent producers must absorb rapidly. Semiconductor packaging buyers exhibit lowest price sensitivity due to dielectric performance specifications; industrial equipment procurement shows highest sensitivity to unit coating costs.
Supply Chain Analysis
FAA and MIL-PRF-46146 qualification gating restricts vendor lists to established resin synthesis operations in the United States, Japan, and Germany. Aromatic dianhydride precursors draw from Texas Gulf Coast petrochemical infrastructure, pyromellitic dianhydride from Japanese specialty chemical producers, and polar aprotic solvents from domestic bulk chemical distributors. Single-source vulnerability concentrates in hurricane-exposed Texas feedstock corridors. Distribution runs through qualified applicator networks serving aerospace OEMs and direct sales channels for semiconductor packaging facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America polyimide coating market functions as a stable compounder where regulatory compliance creates predictable replacement demand cycles. FAA airworthiness directives and EPA emission rules generate non-discretionary procurement that smooths revenue volatility across economic cycles.
For Market Incumbents: To counter ceramic thermal barrier substitution above 400°C service thresholds, deepen backward integration into polyimide resin synthesis to sustain margin resilience against feedstock volatility. Prioritize capacity expansion in waterborne formulation lines to capture EPA-driven solvent transition demand from California semiconductor packaging corridors. For New Entrants and Emerging Players: Texas LNG export terminal contractors represent an underserved buyer archetype requiring corrosion-resistant wire insulation without legacy aerospace qualification burdens. Target hydrogen pipeline infrastructure projects along the Gulf Coast with field-applicable solution coating grades. Pursue direct technical sales engagement bypassing established applicator networks. For Investors and Strategic Acquirers: Valuations sit cheapest among regional aerospace wire harness applicators facing workforce succession pressure. Five-to-ten-year viability hinges on CHIPS Act reshoring sustaining domestic flexible circuit substrate demand. Monitor ECHA aromatic amine precursor restriction alignment as signal for accelerated chemistry transition capital requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Formulation Capacity Expansion | EPA VOC compliance deadlines in California and Texas create first-mover positioning for aqueous dispersion specialists. |
| Backward Integration into Resin Synthesis | Captive polyimide precursor production insulates margins from Texas Gulf Coast aromatic dianhydride supply disruptions. |
| MIL-PRF-46146 Certification Investment | FAA qualification compression in defense electronics programs displaces commercial-grade suppliers from satellite avionics procurement. |
| Flexible Circuit Substrate Partnership | CHIPS Act reshoring incentives reposition film coating demand toward Arizona and New York manufacturing corridors. |
| Closed-System Thermal Imidization Retrofit | OSHA aromatic amine exposure limits below 10 ppm mandate negative-pressure curing infrastructure in Southeast US facilities. |
Research Methodology
Bottom-up electronics and aerospace procurement modeling reconciled against top-down resin production capacity tracking forms the analytical core of this study. Primary interviews with coating formulator technical directors, semiconductor packaging procurement leads, aerospace wire harness quality managers, and EPA compliance officers combined with secondary validation from FAA airworthiness directive filings, EPA emission regulation dockets, SEC 10-K disclosures from listed chemical producers, and customs trade data on aromatic dianhydride imports. Triangulation across these sources grounds volume estimates in actual procurement patterns and production constraints.
Input-output matrices map polyimide precursor availability through thermal imidization capacity to end-use application demand across the projection horizon. Segmentation dimensions include product chemistry grade, end-use industry qualification tier, functional application purpose, and regional manufacturing cluster. CAGRs derive from curve-fitting historical procurement cycles against regulatory compliance timelines and capacity expansion announcements. Forecast inputs incorporate Henry Hub natural gas volatility for thermal processing cost modeling and CHIPS Act incentive disbursement pacing for domestic substrate reshoring projections.
Inputs from FAA certification databases and EPA enforcement records were available through the study window; gaps in real-time semiconductor packaging facility coating procurement introduce uncertainty bands around electronics segment projections. Forecasts reflect documented assumptions regarding regulatory compliance pacing and feedstock supply continuity. A model refresh is warranted upon material change in ECHA aromatic amine precursor restriction alignment or Texas Gulf Coast hurricane disruption frequency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Anti Soiling Coating Market
Coatings
United Kingdom Protective Coatings Market
Coatings
Asia-Pacific Automotive Refinish Coatings Market
Coatings
Coating Binders Market
Coatings
Coating Equipment Market
Coatings
BRIC Performance Coatings Market
Coatings
Global Low Temperature Powder Coatings Market
Coatings
Japan Architectural Coatings Market
Coatings
Soft Touch Polyurethane Coatings Market
Coatings
Yacht Coatings Market
Coatings
Global Coil Coatings Market
Coatings
Compound Coating Market
Coatings
Radiation Curable Coatings Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Fluid Bed and Coating System Market
Coatings
Urethane Surface Coatings Market