
 Tablet and Pellet Coating Systems Market | 2026-2036
Tablet and Pellet Coating Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Tablet and Pellet Coating Systems Market Analytics
Polysaccharide-based coatings are broadening formulation possibilities for moisture-sensitive APIs. L.B. Bohle leverages its German engineering base to dominate high-containment coating system supply. ACG Pharma Technologies anchors its position through integrated tablet press and coater offerings across South Asian markets.
Tablet and pellet coating systems apply functional layers onto solid oral dosage forms using atomized spray deposition in perforated drums or fluidized beds, typically operating at batch temperatures between 35°C and 60°C depending on substrate sensitivity. The equipment enables controlled release, taste masking, and moisture protection for pharmaceutical and nutraceutical products. Drum coaters occupy the largest installed base due to proven scalability for batch sizes exceeding 500 kg. Water-based technology leads new system procurement as solvent recovery costs and environmental compliance intensify. Functional coating for modified-release profiles commands premium pricing relative to aesthetic or moisture-barrier applications.
The US FDA enforces Current Good Manufacturing Practice through process validation requirements that directly determine coating system qualification timelines and capital deployment schedules. India's CDSCO aligns with ICH Q8-Q12 guidelines, compelling domestic manufacturers to adopt automated coating process control for export eligibility. Europe's EMA MDR framework extends quality system expectations to coating equipment suppliers serving contract development organizations. Stakeholders must weigh equipment standardization against application-specific flexibility as regulatory convergence accelerates across major pharmaceutical manufacturing jurisdictions.
Market Dynamics
Pharmaceutical contract manufacturers are consolidating coating capacity around integrated process analytical technology suites to meet FDA Quality by Design validation timelines. This capital concentration is compressing equipment procurement cycles and favoring vendors with turnkey qualification packages.
Growth Catalysts
- Biologics pipeline expansion:Monoclonal antibody and peptide formulations require specialized moisture-barrier coatings, pulling investment into high-containment drum systems.
- CDSCO ICH Q12 alignment:India's export eligibility rules now mandate automated process control, forcing domestic API producers to install qualified coating lines.
- Water-based formulation advances:Polysaccharide coating materials eliminate solvent recovery infrastructure, reducing facility capital requirements for emerging market entrants.
Market Restraints
- Stainless steel input volatility:Grade 316L drum fabrication costs fluctuate with nickel pricing, squeezing margin on standard equipment configurations.
- High-containment component concentration:Isolator and glovebox subsystems depend on a narrow German and Swiss supplier base, creating delivery risk for qualified pharmaceutical projects.
- Solvent coating regulatory friction:EPA National Emission Standards for Hazardous Air Pollutants impose extended permitting timelines on organic solvent-based installations.
Strategic Opportunities
- CDMO captive integration:Indian API manufacturers are backward-integrating into finished dosage, creating first-time coating equipment demand among former pure-play chemical suppliers.
- Continuous processing convergence:Twin-screw granulation-coating integration enables real-time release testing, compressing batch cycle times for high-volume generics.
- Nutraceutical channel expansion:Direct-to-consumer supplement brands are bypassing traditional toll manufacturers, sourcing small-batch coating capacity through equipment-as-a-service models.
Industry Challenges
- Process analytical technology skill scarcity:PAT implementation requires chemometricians and automation engineers that pharmaceutical engineering programs are not producing at sufficient scale.
- Legacy system integration complexity:Brownfield sites face mechanical and software incompatibility when retrofitting modern coating controls onto 1990s-vintage drum infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tablet and Pellet Coating Systems Market |
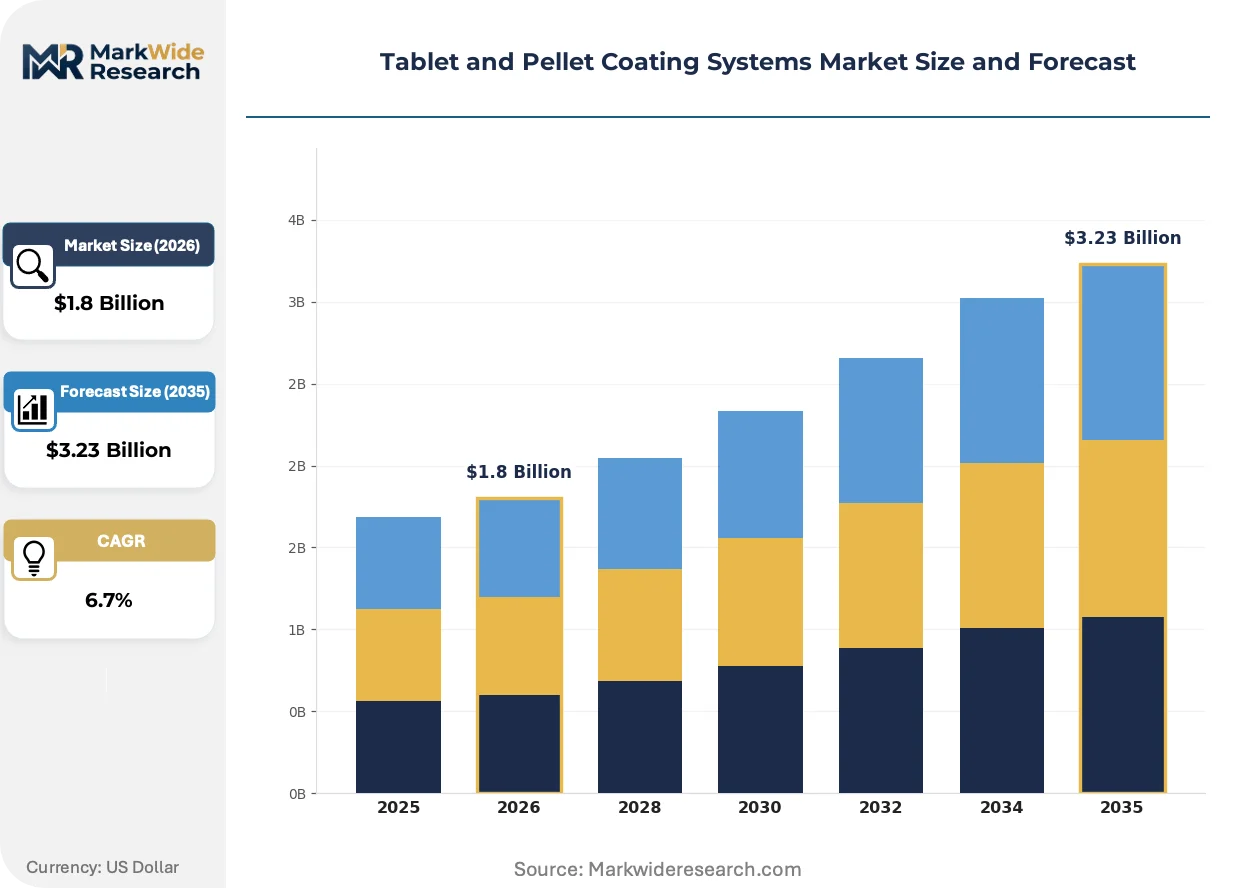
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluid Bed Coaters, Spray Coaters, Drum Coaters, Film Coaters Technology: Solvent-Based, Water-Based, Hot-Melt, Electrostatic End User: Pharmaceuticals, Nutraceuticals, Biotechnology, Research Institutions Application: Controlled Release, Taste Masking, Functional Coating, Moisture Protection |
| Companies Covered | L.B. Bohle, Key International, ACG Pharma Technologies, O'Hara Technologies, Freund-Vector Corporation, IMA Group, Thomas Processing, ACG Worldwide, Syntegon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tablet and Pellet Coating Systems Market Evolving Landscape
Process analytical technology is migrating from laboratory validation to real-time release, collapsing the traditional distinction between manufacturing and quality control functions. Equipment vendors are embedding spectroscopic sensors and multivariate algorithms directly into coating drum controls.
Near-infrared spectroscopy is unifying coating endpoint detection across moisture, organic solvent, and aqueous processes. Mid-size generic manufacturers in Eastern Europe are adopting NIR-equipped coaters faster than expected, compressing the technology's price premium from five years to eighteen months. This unifying sensor platform is eliminating separate laboratory testing workflows, enabling real-time batch release that shortens production cycles by multiple days.
EMA's Medical Device Regulation framework now extends quality system expectations to coating equipment suppliers serving contract development organizations. European CDMOs must document equipment supplier audits in their technical files, forcing coaters to maintain ISO 13485-aligned quality manuals. German and Swiss equipment vendors are responding by pre-qualifying documentation packages that accelerate customer regulatory submissions.
Buyer concentration among the top twenty global CDMOs is consolidating procurement leverage, compressing vendor margins on standard configurations. These buyers are unbundling after-sales service contracts from equipment purchases, sourcing spare parts and technical support through third-party maintenance providers. This disintermediation is most advanced in North American and Western European markets, where CDMOs operate dedicated internal engineering teams capable of independent system validation.
Tablet and Pellet Coating Systems Market Segmentation
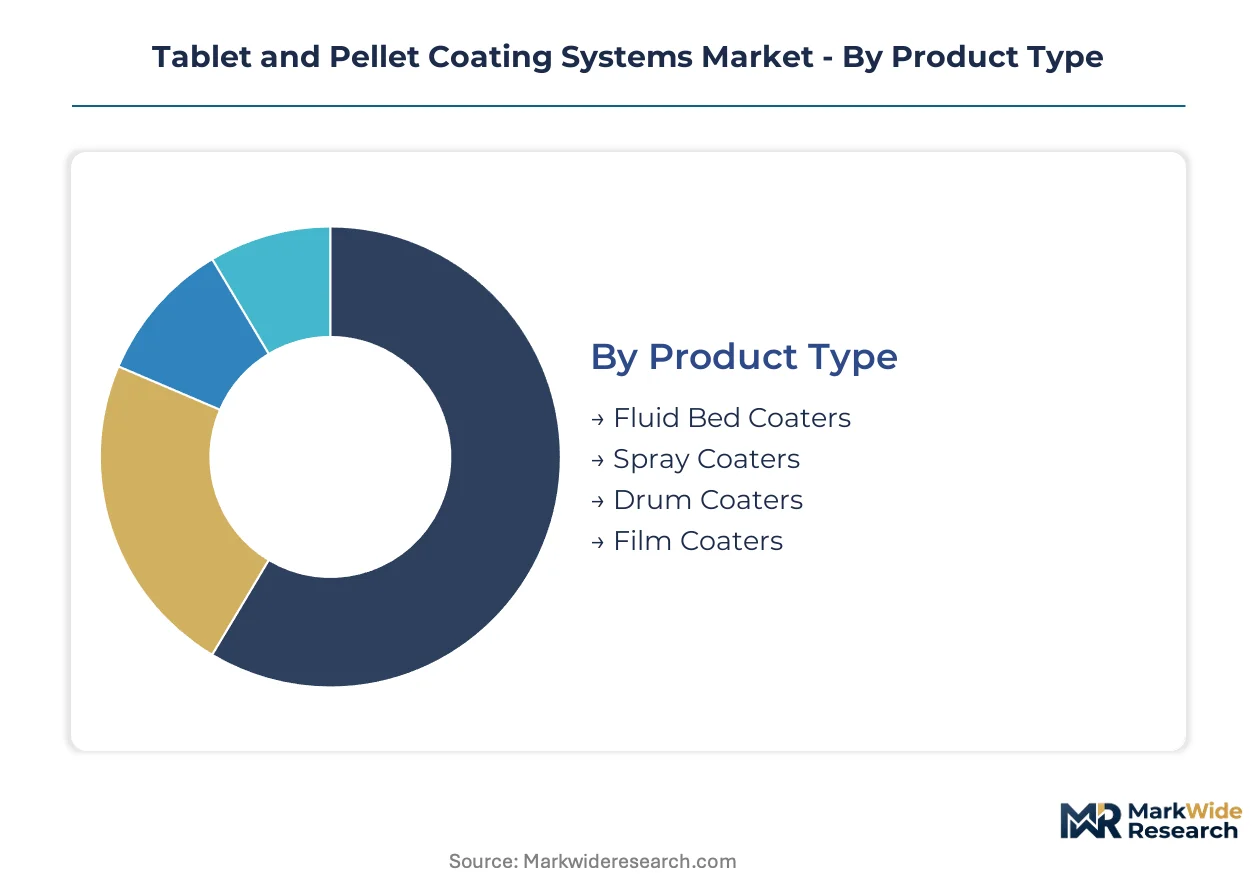
Coating system procurement patterns diverge sharply across equipment scale, formulation chemistry, and regulatory maturity of end-user facilities. Segmentation reveals where capital concentrates and which technology transitions are compressing replacement cycles.
Product Type:
Buyers differentiate primarily by batch scale and containment requirements rather than coating mechanism alone.
- Drum Coaters:Perforated cylindrical drums with atomized spray deposition dominate installations above 500 kg batch size. Demand concentrates among Indian API producers integrating downstream into finished dosage, driven by CDSCO export eligibility mandates for automated process control.
- Fluid Bed Coaters:Air-suspension systems enable simultaneous drying and coating for moisture-sensitive substrates. European CDMOs favor these for high-potency biologics, constrained by EMA MDR documentation requirements for equipment supplier audits.
- Spray Coaters:Precision nozzle arrays suit small-batch nutraceutical and clinical trial manufacturing.
- Film Coaters:Specialized units for thin, uniform aesthetic or barrier layers on tablets.
Volume sits with drum configurations; growth tilts toward fluid bed systems for biologics containment.
Technology:
Formulation chemistry determines facility capital intensity and environmental compliance burden.
- Water-Based:Aqueous polysaccharide and polymer dispersions eliminate solvent recovery infrastructure. Indian and Southeast Asian entrants prefer these for reduced facility capital, though drying energy costs persist.
- Solvent-Based:Organic solvent systems deliver superior moisture barriers for hygroscopic APIs. North American adoption faces EPA National Emission Standards permitting delays, compressing project timelines.
- Hot-Melt:Molten polymer application without liquid carriers suits heat-stable actives.
- Electrostatic:Charged particle deposition enables uniform coating on irregular pellet geometries.
Procurement is shifting toward water-based platforms; solvent systems retain share in moisture-critical applications.
End User:
Facility validation depth and PAT capability separate customer tiers.
- Pharmaceuticals:FDA-regulated manufacturers demand integrated process analytical technology suites with real-time release capability. Contract manufacturers consolidate procurement among top twenty global CDMOs, compressing vendor margins.
- Biotechnology:Peptide and monoclonal antibody formulators require high-containment drum systems with isolator integration. German and Swiss component suppliers constrain delivery capacity for qualified projects.
- Nutraceuticals:Direct-to-consumer brands source small-batch capacity through equipment-as-a-service models.
- Research Institutions:Academic and CRO facilities prioritize flexibility over throughput.
Pharmaceuticals anchor installed base; biotechnology is expanding most quickly on biologics pipeline growth.
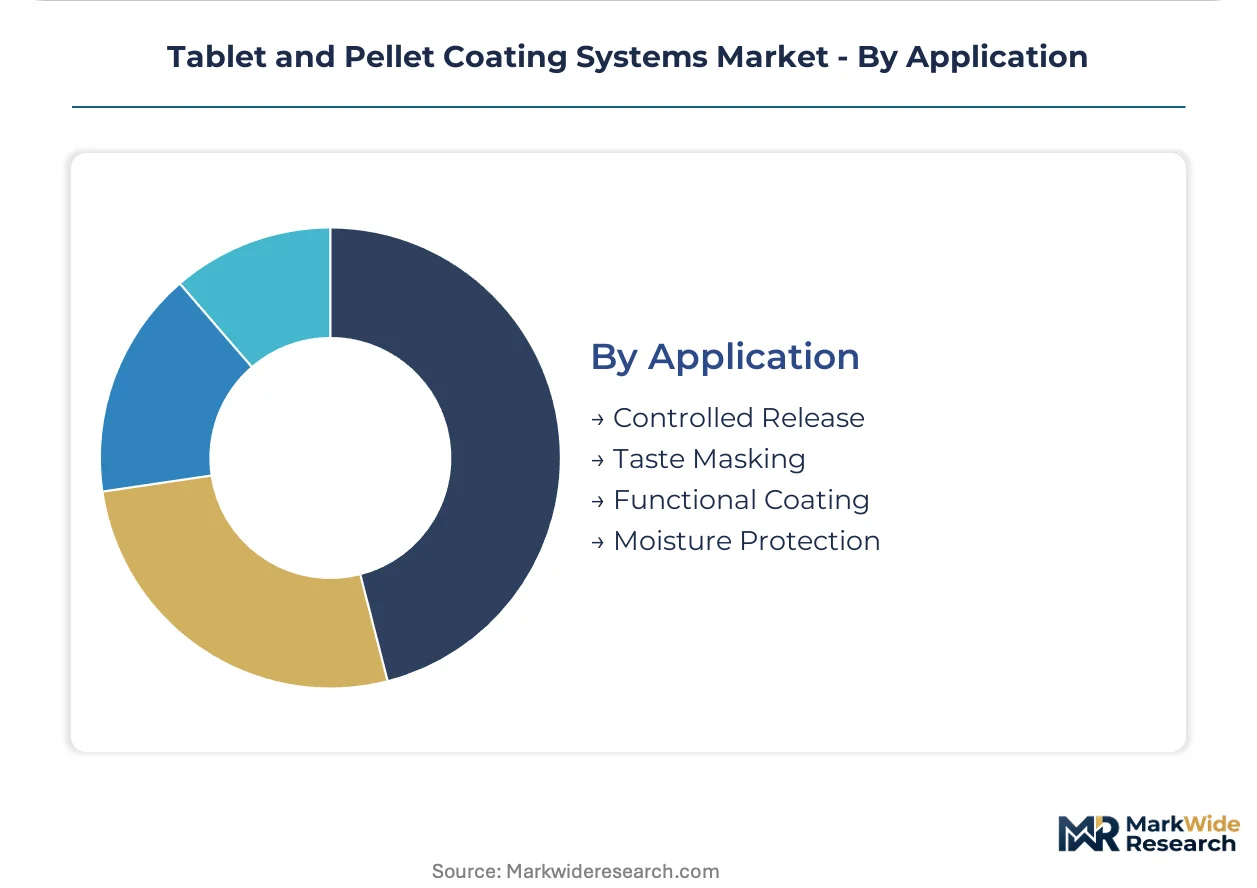
Application:
Pricing power correlates with functional complexity and regulatory scrutiny.
- Controlled Release:Multilayer coatings with dissolution-rate engineering command premium pricing. Generic manufacturers in Eastern Europe adopt NIR-equipped coaters for endpoint detection, collapsing technology price premiums.
- Functional Coating:Enteric, colon-targeted, and bioadhesive layers require validated deposition control. Indian domestic API producers invest here to capture finished-dosage value.
- Taste Masking:Bitter API encapsulation for pediatric and geriatric compliance.
- Moisture Protection:Barrier layers for hygroscopic and effervescent formulations.
Functional coating drives margin; moisture protection represents volume foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates coating equipment procurement among domestic API producers integrating downstream into finished dosage forms. German and Swiss engineering clusters supply high-containment systems for biologics manufacturers. The United States anchors process analytical technology adoption through FDA validation requirements.
United States
Contract development and manufacturing organizations consolidate procurement among the top twenty global CDMOs, compressing vendor margins on standard configurations. The FDA enforces Current Good Manufacturing Practice through process validation requirements that determine capital deployment schedules. The Boston-Cambridge biotech corridor drives demand for high-containment drum systems with isolator integration.
Germany
Engineering-intensive fabricators dominate supply of perforated drum coaters for batch sizes exceeding 500 kg. The EMA Medical Device Regulation framework extends quality system expectations to equipment suppliers serving European CDMOs. The Rhine-Ruhr industrial basin anchors production of stainless steel 316L drum components and process control systems.
India
Domestic API producers are backward-integrating into finished dosage, creating first-time coating equipment demand among former pure-play chemical suppliers. The CDSCO aligns with ICH Q8-Q12 guidelines, compelling automated process control adoption for export eligibility. The Hyderabad-Bengaluru pharmaceutical cluster leads installation of water-based coating lines for polysaccharide formulations.
Switzerland
Precise component fabrication for glovebox and isolator subsystems supports qualified pharmaceutical projects across Europe. Swissmedic maintains stringent equipment supplier audit requirements that pre-qualify documentation packages for regulatory submissions. The Basel-Zurich corridor concentrates high-containment engineering expertise for peptide and monoclonal antibody formulators.
China
Domestic equipment manufacturers scale production of fluid bed coaters for moisture-sensitive substrates in the generics sector. The NMPA harmonizes with ICH guidelines, accelerating automated coating process control adoption for export-oriented facilities. The Yangtze River Delta pharmaceutical manufacturing base expands coating capacity to serve both domestic and contract export demand.
Tablet and Pellet Coating Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with equipment vendors facing concentrated procurement leverage from top-tier CDMOs. The vendor base organizes into three tiers: German and Swiss engineering houses commanding premium positioning for high-containment systems, Indian and Chinese fabricators competing on standard drum configurations, and integrated pharmaceutical technology groups bundling coating with upstream unit operations. Consolidation concentrates around turnkey qualification packages and after-sales service unbundling, while geographic expansion targets Indian API producer integration into finished dosage.
Within the European engineering tier, L.B. Bohle and Syntegon occupy positions anchored by German precision manufacturing heritage and integrated process analytical technology capabilities. ACG Pharma Technologies represents the South Asian integrated model, bundling tablet press and coater offerings across domestic and export markets. Freund-Vector Corporation exemplifies the North American specialist archetype, serving biotechnology formulators with containment-engineered systems. These three anchors illustrate how geographic engineering traditions translate into differentiated competitive positioning across regulatory maturity levels and batch scale requirements.
| Leading Market Players |
|---|
| L.B. Bohle |
| Key International |
| ACG Pharma Technologies |
| O'Hara Technologies |
| Freund-Vector Corporation |
| IMA Group |
| Thomas Processing |
| ACG Worldwide |
| Syntegon |
| Others |
Value Network & Pricing Analysis
Nickel price volatility on the London Metal Exchange cascades directly through Grade 316L stainless steel drum fabrication costs, fragmenting equipment pricing into containment-tiered brackets that separate German-engineered isolator-integrated systems from standard Indian and Chinese drum configurations.
Pricing Analysis
Volume concentrates in standard drum coaters while margins accrue to high-containment isolator-integrated systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA-validated PAT suites commanding substantial premiums over basic automated configurations. Cost compression in standard equipment is intensifying because Indian and Chinese fabricators scale production for domestic API producer demand. Emerging market entrants exhibit highest price sensitivity, while biotechnology formulators prioritize containment performance over capital expenditure.
Supply Chain Analysis
Direct-to-CDMO channels handle hyperscale buyer demand among the top twenty global contract manufacturers, while regional distributors serve mid-tier generic producers. Component fabrication concentrates in Germany, Switzerland, and China, with glovebox and isolator subsystems drawing from a narrow Rhine-Ruhr and Basel-Zurich supplier base. Raw material inputs hinge on nickel, stainless steel 316L, and precision-machined spray nozzle arrays. Single-source vulnerability in qualified pharmaceutical component supply creates delivery risk for projects requiring EMA MDR documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement leverage concentration among top-tier CDMOs is accelerating vendor consolidation, forcing smaller equipment suppliers toward niche containment specialization or exit.
For Market Incumbents: Cement market position through captive PAT software development and pre-qualified documentation packages that compress customer FDA validation timelines. Threat substitution from equipment-as-a-service models in nutraceutical channels demands defensive service bundling. Priority lever rests on backward integration into spectroscopic sensor production to secure supply chain control over real-time release testing components. For New Entrants and Emerging Players: Capture white-space in small-batch clinical trial coating capacity and equipment-as-a-service deployment for direct-to-consumer nutraceutical brands. India's domestic API producer integration into finished dosage represents the most penetrable geography, with CDSCO export eligibility mandates forcing first-time equipment procurement. Go-to-market angle should emphasize water-based polysaccharide formulation expertise to reduce facility capital barriers for emerging market entrants. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier German engineering houses with isolator integration capabilities but strained working capital from extended CDMO payment terms. Long-term viability over the next decade hinges on continuous processing convergence and twin-screw granulation-coating integration. Signal to watch is NIR-equipped coater price premium collapse timelines, indicating technology commoditization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Turnkey Qualification Packaging | Pre-validated documentation accelerates CDMO FDA submission timelines and reduces deployment risk. |
| PAT Software Captive Development | In-house chemometric algorithms differentiate vendors as NIR hardware commoditizes. |
| Isolator Component Backward Integration | Vertical control over glovebox supply mitigates Swiss and German supplier concentration risk. |
| Water-Based Formulation Partnership | Polysaccharide coating alliances reduce facility capital requirements for Indian market entrants. |
| Equipment-as-a-Service Launch | Subscription models unlock nutraceutical direct-to-consumer brands bypassing traditional toll manufacturers. |
Research Methodology
Document review covered FDA 483 inspection observations, EMA MDR technical file requirements, and CDSCO export eligibility guidelines, complemented by interviews with coating equipment engineering directors, pharmaceutical manufacturing heads, contract manufacturing procurement leads, and process analytical technology implementation specialists. Secondary validation drew from SEC equipment vendor filings, ICH Q8-Q12 guideline documentation, and stainless steel commodity trade data. Bottom-up equipment installation tracking and top-down pharmaceutical capital expenditure analysis were triangulated against regional regulatory filing patterns.
Installed base projections and revenue estimates were generated across the analysis window using segmentation by equipment type, containment tier, formulation chemistry, and end-user facility validation depth. CAGRs were derived from equipment procurement cycle analysis and replacement rate modeling tied to PAT adoption curves. Industry-specific inputs included CDSCO ICH alignment enforcement timelines, EPA National Emission Standards permitting velocity, and biologics pipeline moisture-barrier coating demand.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nickel price volatility, high-containment component supplier consolidation, and continuous processing technology disruption. Forecasts reflect documented assumptions regarding regulatory convergence pace and CDMO procurement centralization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Conductive Polymer Coatings Market
Coatings
Egypt Automotive OEM Coatings Market
Coatings
Biopolymer Coatings Market
Coatings
In-Mold Coatings Market
Coatings
Color-Shifting Coating Market
Coatings
China Marine Coatings Market
Coatings
Saudi Arabia Floor Coatings Market
Coatings
Fillers and Coating Market
Coatings
Coating Pigments Market
Coatings
Europe Metal Finishing Market
Coatings
Global Anti-Smudge Coatings Market
Coatings
E-Coat Market
Coatings
Concrete Floor Coatings Market
Coatings
Epoxy Coating Market
Coatings
Italy Automotive OEM Coatings Market
Coatings
Vacuum Coating Machine Market