
 Cladding Coatings Market | 2026-2036
Cladding Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Cladding Coatings Market Intelligence
Fluoropolymer alternatives is broadening the addressable market for polyurethane and acrylic cladding coatings as architects seek comparable weathering performance at reduced material cost. AkzoNobel leverages its coil coatings heritage to dominate premium metal cladding specifications across European infrastructure projects. PPG Industries sustains R&D intensity in UV-cured technologies for factory-applied architectural panels. Sherwin-Williams anchors North American distribution through contractor-direct channels that control specification flow in commercial construction.
Cladding coatings are formulated systems applied to exterior building envelopes, typically comprising binders, pigments, and functional additives that achieve film thicknesses of 50-150 microns to resist moisture ingress, thermal cycling, and ultraviolet degradation. Their primary purpose is to protect structural substrates while enabling aesthetic customization of facades across building typologies. Polyurethane formulations command the largest share of specification activity due to balanced elasticity and color retention in variable climates. Water-based technology represents the fastest-expanding technology category as environmental compliance tightens across jurisdictions. Powder coating occupies a mature position in industrial and pre-fabricated panel segments where factory application controls quality and waste.
REACH restricts solvent-based formulations through VOC emission thresholds, while the EU Green Deal mandates embodied carbon disclosure in construction products, redirecting procurement toward water-based and bio-based alternatives. EPA regulations in the United States parallel this trajectory through architectural coating VOC limits under 40 CFR Part 59. BIS certification requirements in India enforce minimum performance standards for exterior durability, creating market access barriers for uncertified imports. Stakeholders must monitor evolving carbon accounting rules and material passport requirements that will determine specification eligibility in public procurement frameworks.
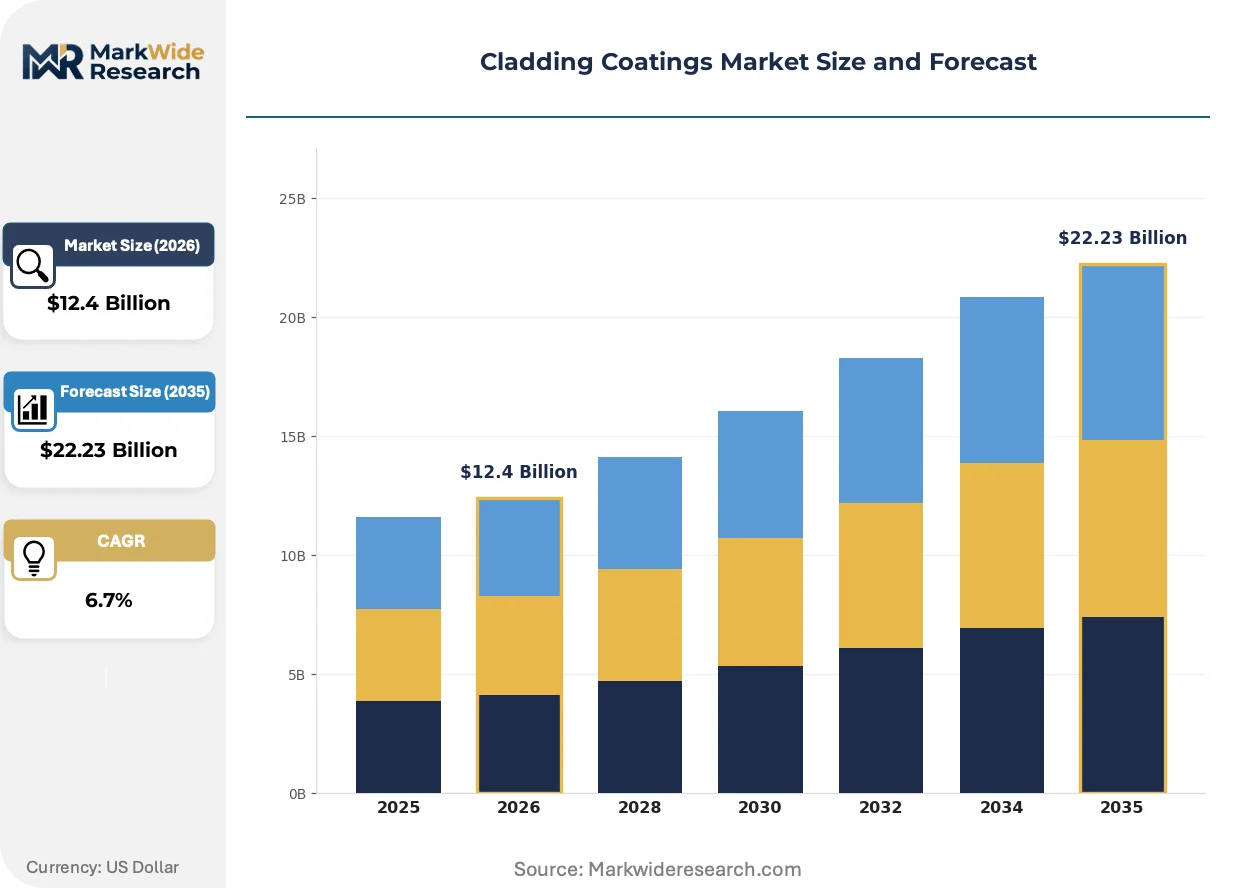
Market Dynamics
Building energy retrofit mandates across Germany, France, and the United Kingdom are compressing specification cycles for high-performance cladding systems as aging commercial stock faces mandatory efficiency upgrades.
Growth Catalysts
- EU Green Deal carbon disclosure:Embodied carbon reporting requirements redirect public procurement toward water-based and bio-based coating formulations.
- Commercial facade refurbishment:Aging building stock across German cities accelerates replacement demand for weather-resistant exterior systems.
- Fluoropolymer alternatives:Polyurethane and acrylic formulations capture specification share from premium fluoropolymer systems through comparable durability at reduced material cost.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane resin costs fluctuate with crude oil and isocyanate supply constraints.
- REACH VOC compliance costs:Solvent-based formulation reformulation demands capital-intensive R&D and testing cycles.
- Powder coating substitution:Factory-applied powder systems displace field-applied liquid coatings in pre-fabricated panel segments.
Strategic Opportunities
- India BIS certification gap:Uncertified import barriers create first-mover advantage for compliant domestic and foreign producers meeting exterior durability standards.
- UV-cured technology convergence:Factory-applied architectural panels integrate UV-cured coatings with automated production lines for throughput gains.
- Contractor-direct channels:North American specification flow control through distributor bypass models captures margin and relationship ownership.
Industry Challenges
- Formulation chemist scarcity:Low-VOC water-based system development requires specialized expertise in resin-pigment compatibility.
- Material passport integration:EU digital product tracking mandates force supply chain data architecture investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cladding Coatings Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Polyester Application: Residential, Commercial, Industrial, Institutional Technology: Water-Based, Solvent-Based, Powder Coating, UV-Cured End User: Contractors, Architects, Builders, Property Developers |
| Companies Covered | AkzoNobel, PPG Industries, Sherwin-Williams, BASF, Nippon Paint, Kansai Paint, Jotun, Beckers Group, Hempel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cladding Coatings Market Strategic Shifts & Innovations
Formulation chemistry and application methods are evolving under regulatory pressure and performance demands. Water-based technology gains specification share. Factory-applied systems compress field labor dependency. Carbon accounting tools reshape procurement evaluation.
Photocatalytic self-cleaning coatings are absorbing specification interest from commercial developers seeking reduced maintenance burden on high-rise facades. Property managers in London and Frankfurt specify these systems for traffic-exposed elevations. The technology is absorbing maintenance budget allocations that previously flowed to periodic cleaning contracts.
REACH Annex XVII restrictions on solvent-based architectural coatings tighten VOC emission thresholds across EU member states. Manufacturers reformulate product lines toward water-based and bio-based alternatives to maintain market access. German coating producers face the steepest compliance timeline given their concentration of metal cladding specification activity.
Specification authority is migrating from general contractors to facade engineering consultants who control technical submittal approval. Large commercial developments in Paris and Milan now route coating selection through specialist envelope designers. This shift concentrates influence among firms with demonstrated high-performance building credentials.
Cladding Coatings Market Segmentation
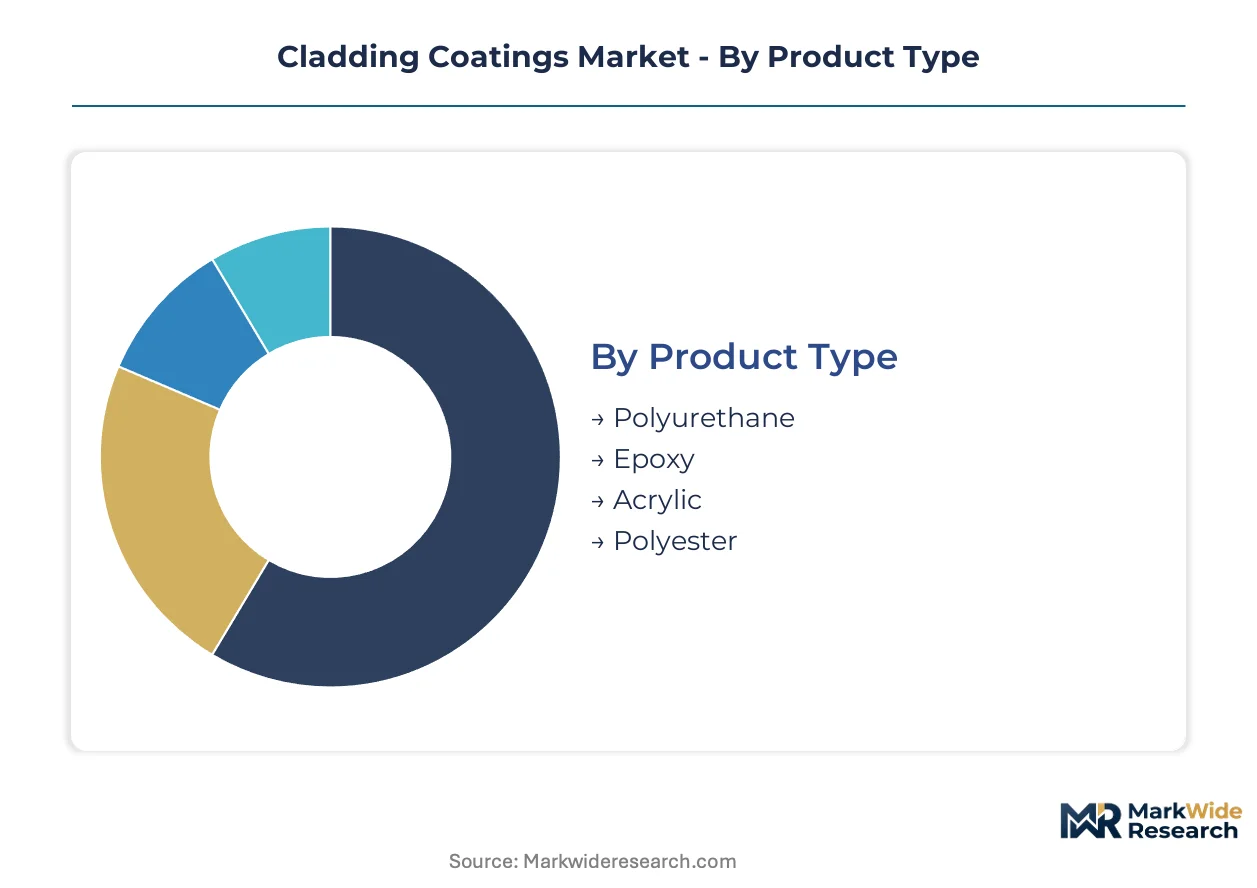
Cladding coatings specification diverges sharply across building typologies and regulatory environments. Product chemistry, application setting, and procurement channel each impose distinct compliance burdens and performance thresholds. Understanding these segment boundaries enables targeted formulation development and channel strategy.
Product Type:
REACH Annex XVII and EPA 40 CFR Part 59 impose divergent certification timelines across resin chemistries, with polyurethane and epoxy facing the steepest VOC reformulation deadlines.
- Polyurethane:Balanced elasticity and UV resistance dominate commercial facade specifications in Germany and France. Building energy retrofit mandates across aging European stock compress specification cycles for high-performance systems with proven 15-year color retention warranties.
- Epoxy:Superior chemical resistance and substrate adhesion anchor industrial cladding applications. Factory-applied panel manufacturers in the United Kingdom specify epoxy primers for steel substrates exposed to coastal atmospheric corrosion.
- Acrylic:Water-borne acrylic formulations satisfy tightened VOC thresholds in residential refurbishment segments. BIS certification requirements in India favor acrylic systems for exterior durability compliance in tropical monsoon climates.
- Polyester:Powder coating compatibility positions polyester resins in pre-fabricated metal panel production. Continuous coil coating lines in Italy and Spain utilize saturated polyester chemistries for architectural aluminum.
Leading the category by volume: polyurethane. Growing fastest: water-borne acrylic variants gaining specification share from solvent-based alternatives.
Application:
End-use setting determines film thickness requirements, warranty terms, and maintenance liability structures.
- Residential:Single-family and multi-family housing drive specification of cost-optimized water-based systems. German KfW efficiency programs subsidize high-performance cladding retrofits in owner-occupied housing stock.
- Commercial:Office towers and retail facades absorb premium fluoropolymer alternatives and photocatalytic self-cleaning formulations. London and Frankfurt property managers specify these systems to displace periodic cleaning contracts.
- Industrial:Manufacturing facilities and warehouses demand chemical-resistant epoxy and polyurethane systems. UK industrial parks specify 100-micron dry film thickness for steel substrate protection in coastal exposure zones.
- Institutional:Schools, hospitals, and government buildings face mandatory embodied carbon disclosure under EU Green Deal procurement rules. French public procurement frameworks now require Environmental Product Declarations for exterior coating systems.
Commercial applications command the highest specification authority. Institutional segments are climbing the fastest as public procurement carbon rules tighten.
Technology:
Application method determines capital intensity, waste generation, and field labor dependency.
- Water-Based:Low-VOC formulations capture specification share from solvent systems across EU member states. German coating producers face accelerated reformulation timelines given concentration of metal cladding specification activity.
- Solvent-Based:REACH Annex XVII restrictions compress market access for traditional alkyd and urethane solvent systems. Remaining demand concentrates in industrial maintenance applications where ambient cure requirements exclude water-borne alternatives.
- Powder Coating:Factory-applied systems eliminate field application variability and VOC emissions entirely. Pre-fabricated panel manufacturers in Italy integrate powder coating with automated production lines.
- UV-Cured:Instant cure kinetics enable high-throughput factory application on engineered wood and fiber cement panels. PPG Industries sustains R&D intensity in UV-cured technologies for architectural panel segments.
Water-based technology leads current specification volume. UV-cured systems are expanding most quickly in factory-applied panel manufacturing.
End User:
Procurement authority migration from general contractors to specialized consultants reshapes channel strategy requirements.
- Contractors:Field application crews influence coating selection through established supplier relationships and spray equipment compatibility. Sherwin-Williams anchors North American distribution through contractor-direct channels controlling specification flow.
- Architects:Facade engineering consultants in Paris and Milan now control technical submittal approval for large commercial developments. Specification authority concentrates among firms with demonstrated high-performance building credentials.
- Builders:Production homebuilders prioritize cost certainty and application speed in volume residential construction. Water-based acrylic systems dominate this segment through contractor familiarity and ambient cure schedules.
- Property Developers:Commercial developers evaluate lifecycle cost including maintenance burden reduction. Photocatalytic self-cleaning coatings absorb capital budget allocations previously reserved for periodic cleaning contracts.
Contractors retain the largest procurement volume by project count. Architects are gaining influence fastest as envelope engineering specialization deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German KfW efficiency programs and the EU Green Deal carbon disclosure rules concentrate specification authority in European industrial zones. Tax incentives for building energy retrofits accelerate coating replacement cycles across aging commercial stock.
Germany
Commercial facade refurbishment in Berlin, Frankfurt, and Munich drives polyurethane specification for high-performance weathering warranties. REACH Annex XVII tightens VOC thresholds for solvent-based systems. The Rhine-Ruhr industrial corridor hosts coil coating lines supplying architectural aluminum to infrastructure projects.
United States
EPA 40 CFR Part 59 architectural coating limits redirect procurement toward water-based alternatives in commercial construction. Contractor-direct distribution channels control specification flow in Texas, California, and Florida markets. Sherwin-Williams anchors this channel structure through field application crew relationships.
France
Public procurement frameworks mandate Environmental Product Declarations for institutional building envelopes under EU Green Deal rules. Paris and Lyon facade engineering consultants now control technical submittal approval for large developments. The Île-de-France region concentrates specification activity for premium self-cleaning coating systems.
India
BIS certification requirements for exterior durability create market access barriers for uncertified imports in Mumbai and Delhi-NCR construction markets. Water-borne acrylic formulations satisfy tropical monsoon climate performance standards. Domestic producers gain first-mover advantage in residential refurbishment segments.
United Kingdom
Industrial cladding applications in coastal zones specify epoxy primers for atmospheric corrosion protection under factory-applied panel standards. Building energy retrofit mandates compress specification cycles for high-performance systems. The Midlands and Northern England host pre-fabricated panel manufacturers integrating powder coating with automated production.
Cladding Coatings Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with premium formulations consolidating around heritage coating houses and volume applications fragmenting among regional blenders. The vendor base organizes into three tiers: multinational chemical conglomerates with coil coating heritage, mid-cap specialists focused on water-based technology migration, and regional distributors controlling contractor relationships. M&A activity concentrates on water-borne formulation capabilities and geographic expansion into BIS-regulated markets. Strategic partnerships between resin suppliers and panel manufacturers reshape factory-applied coating specifications.
Among heritage chemical conglomerates, AkzoNobel and PPG Industries occupy positions defined by coil coating lineage and UV-cured technology portfolios respectively. AkzoNobel represents the premium metal cladding specification archetype across European infrastructure. PPG Industries exemplifies factory-applied architectural panel convergence with automated production line integration. Sherwin-Williams anchors the contractor-direct distribution archetype in North American commercial construction through specification flow control relationships.
| Leading Market Players |
|---|
| AkzoNobel |
| PPG Industries |
| Sherwin-Williams |
| BASF |
| Nippon Paint |
| Kansai Paint |
| Jotun |
| Beckers Group |
| Hempel |
| Others |
Cost & Logistics Intelligence
Polyurethane resin feedstock volatility cascades through coating pricing tiers as petrochemical input costs fluctuate with crude oil and isocyanate supply constraints, compressing margins for field-applied liquid systems while factory-applied powder coatings capture cost stability through captive resin supply.
Pricing Analysis
Short lead-time premiums dominate coating procurement as project contractors pay markups for expedited delivery of certified water-based formulations. Three-tier pricing structure across premium fluoropolymer, standard polyurethane, and economy acrylic levels reflects certification grade and warranty duration differentiation. Cost compression in economy tiers intensifies because domestic producers in India exploit BIS certification gaps to undercut import pricing. Volume residential builders exhibit highest price sensitivity, while institutional procurement teams prioritize embodied carbon disclosure compliance over unit cost.
Supply Chain Analysis
Freight cost escalation from German Rhine-Ruhr industrial corridor to UK pre-fabricated panel manufacturers reshapes procurement geography as buyers seek regional blending capacity. Production concentrates in Germany, Italy, and the United Kingdom for coil coating lines supplying architectural aluminum. Supply chains rest on titanium dioxide pigments, isocyanate resins, and specialty additives as critical inputs. Single-source vulnerability in isocyanate supply creates exposure to petrochemical disruption. Distribution runs through contractor-direct channels in North America and facade engineering consultant networks in France and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based technology migration is displacing solvent-based formulations across EU member states as REACH Annex XVII compliance deadlines compress reformulation timelines for incumbent producers.
For Market Incumbents: Deploy backward integration into specialty resin production to secure supply chain control against isocyanate price volatility and powder coating substitution threats. Accelerate water-based R&D capacity in German technical centers to defend specification share as REACH VOC thresholds tighten. Capture facade engineering consultant relationships in Paris and Milan to secure technical submittal influence before specification authority fully migrates from general contractors. For New Entrants and Emerging Players: Residential refurbishment contractors in Indian tier-2 cities represent the most penetrable buyer archetype as BIS certification barriers filter out uncertified imports. Exploit compliance gaps by establishing domestic blending capacity in Mumbai and Delhi-NCR construction corridors. Pursue KfW efficiency program alignment in German owner-occupied housing stock to access subsidized retrofit demand. For Investors and Strategic Acquirers: UV-cured technology patent filings by factory-applied panel manufacturers are the leading indicator that automated production integration will reshape architectural coating specifications. Long-term viability favors mid-cap specialists with demonstrated water-borne formulation expertise and BIS-certified production assets. Watch for consolidation signals as resin suppliers form strategic partnerships with pre-fabricated panel manufacturers to reshape factory-applied coating standards.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Formulation Migration | REACH Annex XVII compliance secures EU market access for reformulated product lines. |
| Backward Integration into Resin Supply | Captive isocyanate production hedges petrochemical feedstock volatility exposure. |
| Facade Engineering Consultant Engagement | Technical submittal approval control in Paris and Milan secures specification influence. |
| BIS Certification Investment | Domestic production qualification in India filters import competition from uncertified producers. |
| UV-Cured Technology R&D Expansion | Factory-applied panel integration with automated lines captures throughput gains in architectural segments. |
Research Approach
Document review covered EU regulatory filings, EPA 40 CFR Part 59 guidance documents, and BIS certification standards, complemented by interviews with coating formulation chemists, facade engineering consultants, and procurement managers at commercial developers. Primary fieldwork engaged plant managers at German coil coating facilities, distribution channel partners in North American contractor-direct networks, and technical R&D directors at water-based technology specialists. Secondary validation drew from customs trade data, SEC 10-K disclosures from heritage chemical conglomerates, and Cefic industry reports. Bottom-up demand modeling triangulated against top-down market sizing from production capacity assessments.
Cross-referencing historical specification patterns against expert panel input anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include resin chemistry tier, application setting, technology type, and procurement channel authority. CAGRs were derived through trend extrapolation moderated by regulatory compliance timeline impacts. Key inputs encompassed building energy retrofit mandate acceleration curves and material passport integration cost assumptions for EU public procurement frameworks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock volatility and REACH carbon accounting rule evolution. Projections reflect assumptions about regulatory enforcement consistency and technology adoption curves without guaranteeing specific compliance timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Europe Thermal Spray Market
Coatings
South Africa Automotive OEM Coatings Market
Coatings
Global Anti Slip Coatings Market
Coatings
Fillers and Coating Market
Coatings
Noise and Vibration Coatings Market
Coatings
Italy Protective Coatings Market
Coatings
Carpet Back Coatings Market
Coatings
Conductive Coatings Market
Coatings
Thailand Architectural Coatings Market
Coatings
Global PET Film Coated Steel Coil Market
Coatings
Asia-Pacific Thermal Spray Market
Coatings
US Concrete Floor Coatings Market
Coatings
Global Graphite Coatings Market
Coatings
Global Smart Coating Market
Coatings
Canada Industrial Wood Coatings Market
Coatings
Clear Coatings Market