
 Global Inorganic Antimicrobial Coatings Market | 2026-2036
Global Inorganic Antimicrobial Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inorganic Antimicrobial Coatings Market Foresight
Medical-grade certification tiers are bifurcating the competitive landscape into validated suppliers and commodity producers. AkzoNobel N.V. leverages its marine and protective coatings heritage to transfer corrosion-resistant binder technologies into antimicrobial formulations for HVAC infrastructure. BASF SE anchors its position through captive silver-nanoparticle synthesis and direct supply to European pharmaceutical manufacturers seeking REACH-compliant surface treatments. PPG Industries differentiates via plasma-sprayed ceramic antimicrobial layers developed for food processing equipment in North American dairy operations.
Inorganic antimicrobial coatings constitute surface-functionalized films incorporating metallic biocides—principally silver ions, copper oxides, zinc oxide, or titanium dioxide—deposited through sol-gel, chemical vapor deposition, or thermal spraying processes to achieve sustained microbial kill rates on substrates. These coatings serve critical industrial purposes where organic biocide leaching or antibiotic resistance renders conventional approaches inadequate, particularly in medical device sterilization and potable water system protection. Silver-based formulations occupy the dominant value share given established efficacy against gram-positive and gram-negative pathogens, while copper-based alternatives are gaining structural ground in HVAC condensate pans where humidity accelerates ion release. Sol-gel technology leads application-method volumes due to ambient-temperature processing compatibility with heat-sensitive medical polymers, though plasma spraying commands premium positioning for ceramic-based coatings in water treatment membrane housings.
FDA 510(k) clearance pathways and EPA antimicrobial pesticide registrations govern market access for coatings deployed in US medical and food-contact applications, creating multi-year validation barriers that favor incumbents with established toxicology dossiers. EMA biocompatibility standards and REACH substance restrictions in Europe further constrain formulation flexibility, compelling reformulation investments as zinc oxide faces scrutiny under updated hazard classifications. Stakeholders must monitor evolving ISO 22196 test method revisions and national transpositions of the EU Medical Device Regulation to anticipate which biocide-load thresholds will define next-generation compliance benchmarks.
Market Dynamics
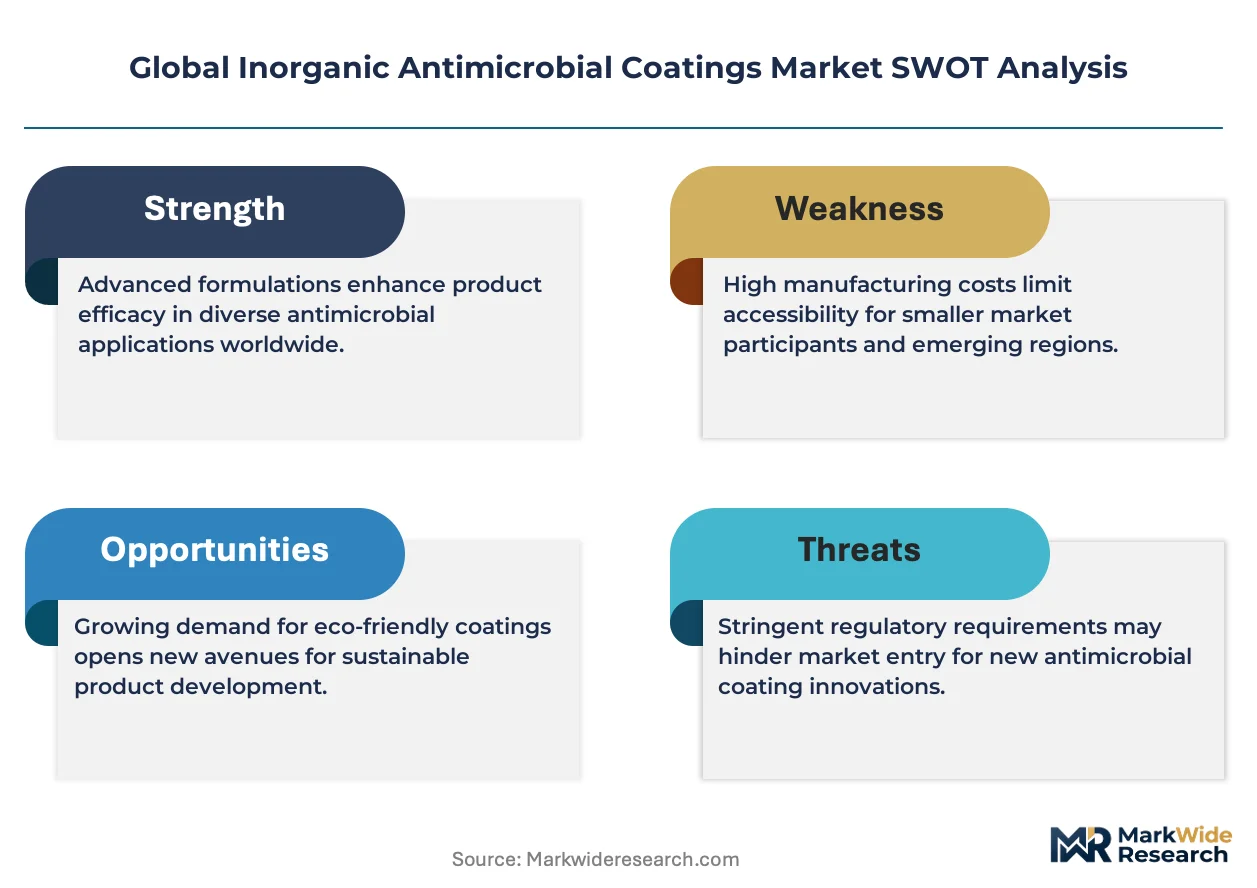
REACH substance restrictions and EMA biocompatibility standards are forcing manufacturers to reformulate zinc oxide and silver-ion loadings, compressing formulation flexibility while elevating compliance costs for REACH-certified suppliers.
Growth Catalysts
- Sol-gel deposition:Ambient-temperature processing compatibility with heat-sensitive medical polymers enables coating integration into surgical instrument polymers and implantable device housings without thermal degradation.
- EU Medical Device Regulation:MDR biocompatibility verification mandates for surface-contacting medical devices are pulling procurement toward certified antimicrobial treatments in German and Italian medical device clusters.
- HVAC infrastructure corrosion:Humidity-accelerated microbial colonization in condensate pans and ductwork is driving specification of copper-oxide formulations for ion-release durability in climate control systems.
Market Restraints
- Silver price volatility:Precious metal commodity swings directly compress margin structures for silver-ion dominant formulations, forcing hedging costs onto coating manufacturers.
- German supply concentration:Captive silver-nanoparticle synthesis capabilities concentrate among three chemical conglomerates, creating procurement bottlenecks for independent coating formulators.
- Antimicrobial resistance screening:ISO 22196 test method limitations in capturing biofilm formation kinetics create validation gaps that delay EPA antimicrobial pesticide registrations.
Strategic Opportunities
- Water treatment membrane housings:Plasma-sprayed ceramic antimicrobial layers for reverse osmosis and ultrafiltration systems remain underpenetrated relative to medical and food-contact applications.
- Japanese pharmaceutical manufacturing:METI cleanroom standards and PMDA surface contamination protocols create a regulatory tailwind for verified antimicrobial surface treatments in active pharmaceutical ingredient production facilities.
- Photocatalytic titanium dioxide:Convergence with UV-LED activation systems enables self-sanitizing surfaces for transit infrastructure and public building interiors without continuous biocide replenishment.
Industry Challenges
- Toxicology dossier assembly:Multi-year EPA and ECHA data requirements for novel biocide loadings strain smaller formulators lacking dedicated regulatory affairs functions.
- Legacy HVAC retrofit integration:Existing ductwork geometries and polymer compatibility constraints complicate application of sol-gel coatings onto installed infrastructure without system downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inorganic Antimicrobial Coatings Market |
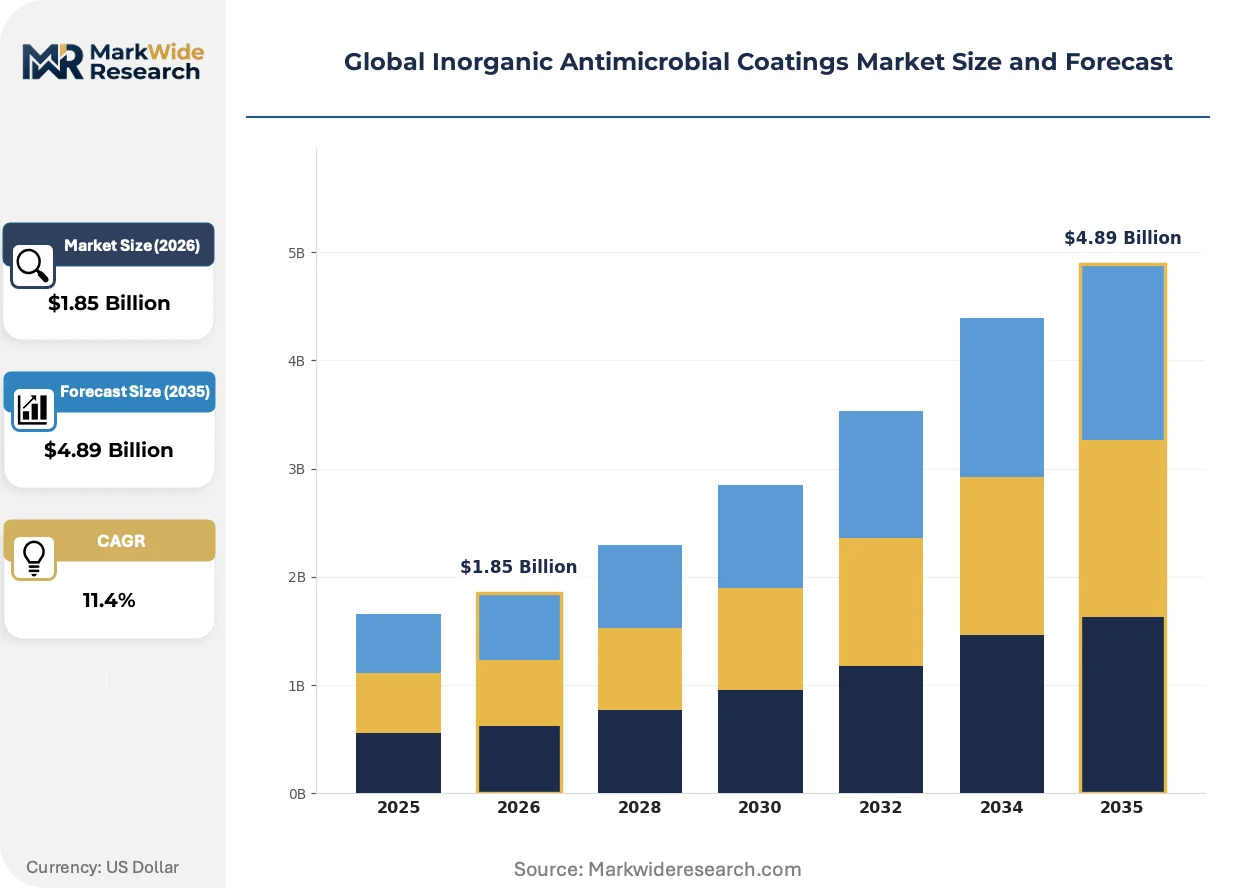
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver-Based, Copper-Based, Zinc Oxide-Based, Titanium Dioxide-Based, Ceramic-Based Technology: Sol-Gel, Chemical Vapor Deposition, Plasma Spraying, Electrochemical Deposition, Thermal Spraying Application: Medical Devices, Food Processing Equipment, HVAC Systems, Water Treatment, Packaging End User: Pharmaceutical Manufacturers, Food & Beverage Facilities, HVAC Contractors, Water Utilities, Packaging Companies |
| Companies Covered | AkzoNobel N.V., PPG Industries, Sherwin-Williams Company, BASF SE, Axalta Coating Systems, Nippon Paint Holdings, RPM International Inc., Lonza, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inorganic Antimicrobial Coatings Market Shifts & Advancements
Coating functionality is decomposing into substrate-specific performance tiers, with application-method selection now determining antimicrobial efficacy durability more than biocide chemistry alone.
Photocatalytic titanium dioxide is decomposing the traditional silver-ion dominance in ambient-light activated applications. Japanese building materials manufacturers and Dutch architectural glass producers are specifying TiO2-silica nanocomposites for facade and interior surface treatments. The technology is decomposing premium pricing power for silver-based formulations in non-medical ambient environments where UV or visible-light exposure is reliable.
EMA's updated biocompatibility evaluation endpoints and ECHA's revised zinc oxide hazard classifications are compressing formulation portfolios. Coating manufacturers must now maintain parallel REACH-compliant and legacy formulations, doubling regulatory maintenance overhead. German medical device clusters in Baden-Württemberg are responding fastest, with captive toxicology testing capabilities accelerating reformulation cycles.
Hospital procurement departments are consolidating vendor lists around certified antimicrobial surface treatment suppliers with verified ISO 22196 performance data. Group purchasing organizations in US healthcare systems are displacing spot-buying of commodity coatings with multi-year sole-source agreements. This concentration is most visible in California and Texas hospital networks, where infection control liability exposure drives preference for validated supplier relationships over unit-cost minimization.
Global Inorganic Antimicrobial Coatings Market Segmentation
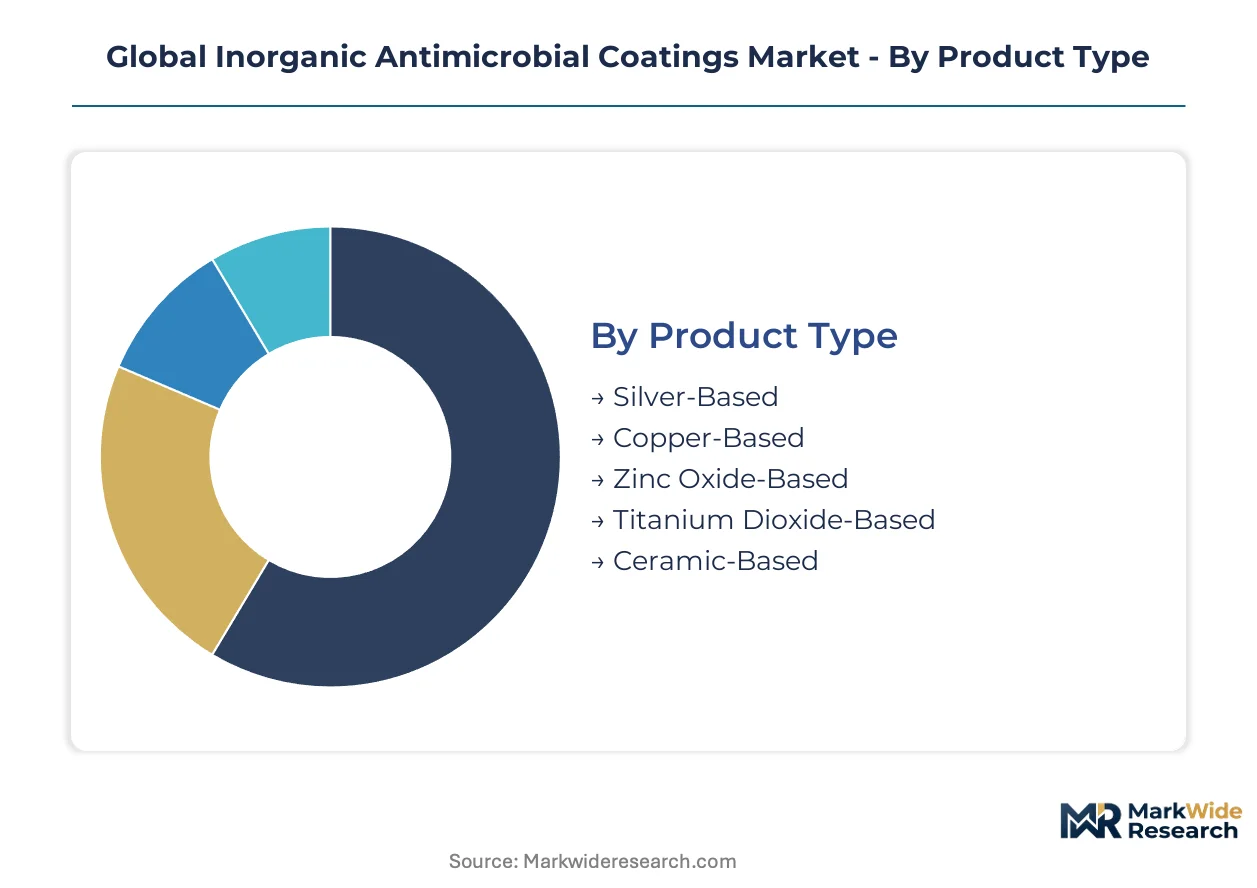
Segmentation in inorganic antimicrobial coatings reveals how formulation chemistry, application method, and end-use requirements channel procurement decisions across distinct regulatory and performance tiers. Channel concentration varies sharply: medical device OEMs route through certified coating formulators with FDA 510(k) or EMA dossiers, while HVAC contractors purchase through regional distributors prioritizing ion-release durability specifications.
Product Type:
Silver-based formulations dominate pharmaceutical and medical device channels where REACH-compliant biocompatibility verification commands premium positioning, while copper-oxide alternatives penetrate HVAC and water utility procurement through corrosion-resistant ion-release specifications.
- Silver-Based:Incorporates silver ions or nanoparticles in sol-gel or polymer matrices, delivering broad-spectrum efficacy against gram-positive and gram-negative pathogens. German medical device clusters in Baden-Württemberg anchor procurement volumes for surgical instrument coatings requiring EMA biocompatibility clearance.
- Copper-Based:Deploys copper oxide or metallic copper in ceramic or organic binders, optimized for humidity-accelerated ion release in climate control infrastructure. US HVAC contractors in Texas and Florida specify these formulations for condensate pan applications where moisture drives microbial colonization.
- Zinc Oxide-Based:Faces ECHA hazard classification scrutiny under REACH, compressing formulation flexibility for European pharmaceutical manufacturers.
- Titanium Dioxide-Based:Photocatalytic activation under UV-LED systems enables self-sanitizing surfaces for Japanese transit infrastructure and Dutch architectural glass.
- Ceramic-Based:Plasma-sprayed alumina or zirconia matrices with embedded biocides serve water treatment membrane housings requiring mechanical durability.
By volume, Silver-Based formulations lead. By growth pace, Titanium Dioxide-Based coatings are expanding most quickly as UV-LED activation systems mature.
Technology:
Application-method selection now determines antimicrobial efficacy durability more than biocide chemistry alone, with cost tiers separating ambient-temperature sol-gel deposition from capital-intensive plasma spraying equipment.
- Sol-Gel:Ambient-temperature hydrolysis and condensation of metal alkoxides enables coating integration into heat-sensitive medical polymers without thermal degradation. Italian medical device manufacturers leverage this compatibility for implantable device housings requiring MDR biocompatibility verification.
- Plasma Spraying:High-velocity thermal deposition of ceramic-biocide composites creates dense, adherent layers for water treatment membrane housings. German water utilities specify these coatings for reverse osmosis pressure vessels where mechanical abrasion resistance outweighs unit cost premiums.
- Chemical Vapor Deposition:Gas-phase precursor reactions yield conformal thin films for precision medical instruments.
- Electrochemical Deposition:Anodic or cathodic processes suit conductive substrates in food processing equipment.
- Thermal Spraying:Combustion or electric arc methods deposit thicker ceramic layers for industrial infrastructure.
Sol-Gel commands the widest installed base. Plasma Spraying captures the steepest expansion trajectory in water treatment applications.
Application:
End-use maturity separates established medical device coatings with multi-decade toxicology dossiers from emerging packaging applications facing evolving FDA food-contact notification requirements.
- Medical Devices:Surface-functionalized films on surgical instruments, implantable housings, and diagnostic equipment require ISO 22196 validation and FDA 510(k) or EMA clearance. California and Texas hospital networks consolidate procurement around certified suppliers with verified performance data.
- HVAC Systems:Condensate pan, ductwork, and heat exchanger coatings combat humidity-accelerated microbial colonization. US commercial building operators specify copper-oxide formulations for ion-release durability in climate control infrastructure.
- Food Processing Equipment:Dairy and meat processing surfaces demand EPA antimicrobial pesticide registration for direct food contact.
- Water Treatment:Membrane housings and distribution system components require ceramic-biocide composites for mechanical durability.
- Packaging:Active and intelligent packaging surfaces face evolving regulatory frameworks for food-contact biocide migration.
Medical Devices generates the highest value concentration. Packaging is climbing the fastest as active barrier technologies penetrate pharmaceutical and perishable food segments.
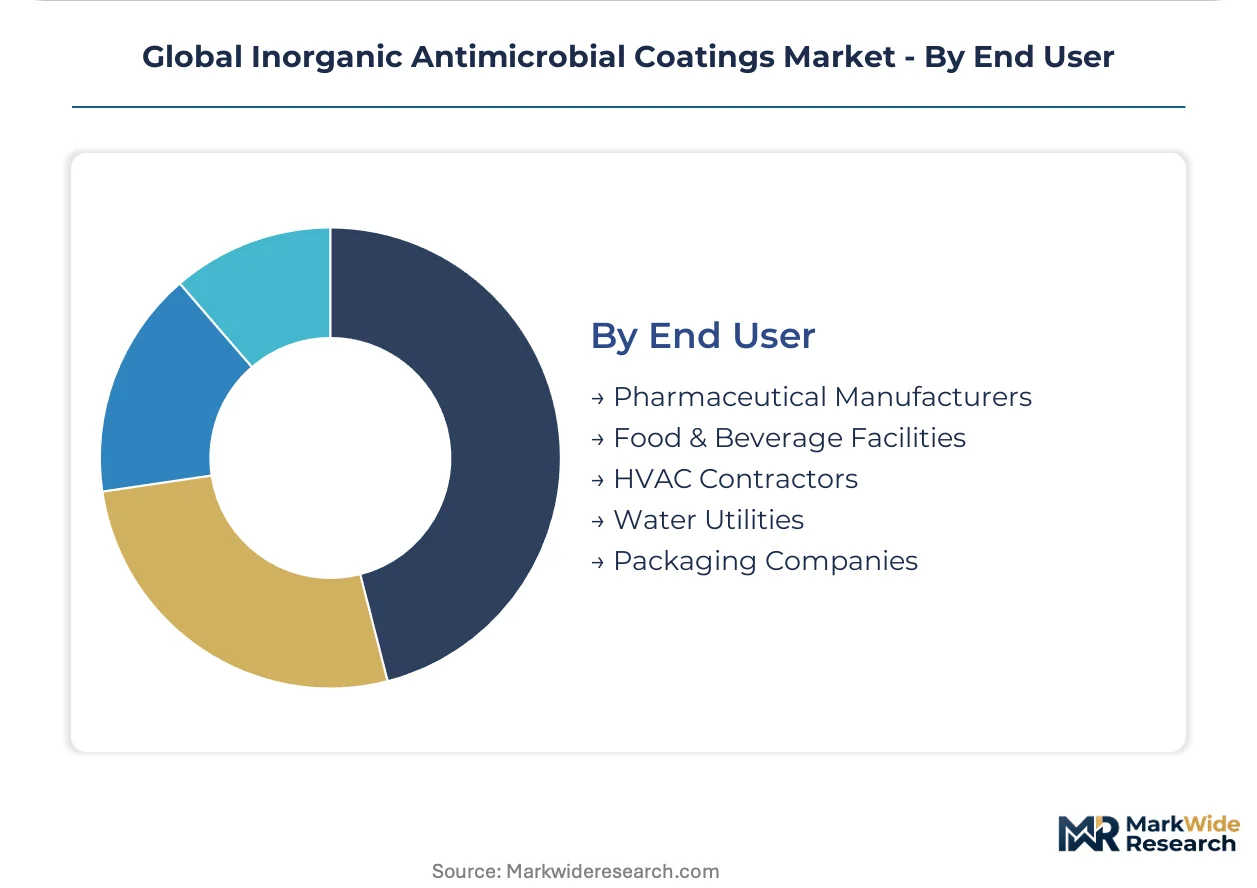
End User:
Customer-type procurement sophistication bifurcates between pharmaceutical manufacturers with captive toxicology testing capabilities and HVAC contractors relying on distributor specification sheets.
- Pharmaceutical Manufacturers:Active pharmaceutical ingredient producers in Japan and Europe drive demand for verified antimicrobial surface treatments under METI cleanroom standards and EMA contamination protocols. These end users maintain parallel REACH-compliant and legacy formulation inventories.
- Food & Beverage Facilities:North American dairy operations specify plasma-sprayed ceramic antimicrobial layers for processing equipment requiring USDA and EPA dual compliance.
- HVAC Contractors:Regional installation and maintenance providers purchase through distributor channels prioritizing ion-release durability specifications over biocompatibility certification.
- Water Utilities:Municipal and industrial treatment operators specify ceramic-biocide composites for membrane housing protection.
- Packaging Companies:Flexible and rigid packaging converters face evolving FDA food-contact notification requirements for active antimicrobial layers.
Pharmaceutical Manufacturers anchor premium pricing. Packaging Companies are gaining share fastest as active barrier technologies commercialize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Captive silver-nanoparticle synthesis capabilities concentrate among German chemical conglomerates, creating procurement bottlenecks that ripple through coating formulators worldwide. Supply chain configuration dictates competitive access to REACH-certified raw materials.
United States
California and Texas hospital networks consolidate procurement around certified antimicrobial surface treatment suppliers with verified ISO 22196 performance data. FDA 510(k) clearance pathways and EPA antimicrobial pesticide registrations govern market access for medical and food-contact applications. Group purchasing organizations displace spot-buying with multi-year sole-source agreements.
Germany
Medical device clusters in Baden-Württemberg and Bavaria anchor procurement volumes for certified antimicrobial surface treatments requiring EMA biocompatibility verification. REACH substance restrictions and updated ECHA zinc oxide hazard classifications compress formulation flexibility. Captive toxicology testing capabilities accelerate reformulation cycles among integrated chemical producers.
Japan
Building materials manufacturers specify TiO2-silica nanocomposites for facade and interior surface treatments in transit infrastructure and public buildings. METI cleanroom standards and PMDA surface contamination protocols drive demand for verified antimicrobial treatments in active pharmaceutical ingredient production. Photocatalytic titanium dioxide converges with UV-LED activation systems.
Italy
Medical device manufacturers leverage sol-gel ambient-temperature processing compatibility for implantable device housings requiring MDR biocompatibility verification. EU Medical Device Regulation biocompatibility mandates pull procurement toward certified antimicrobial treatments. Northern industrial districts concentrate coating integration expertise for surgical instrument polymers.
Netherlands
Architectural glass producers specify photocatalytic titanium dioxide-silica nanocomposites for exterior and interior surface treatments. REACH compliance requirements push manufacturers toward silver-ion and copper-oxide formulations with verified biocompatility profiles. Dutch building materials innovation clusters accelerate TiO2 coating commercialization for ambient-light activated applications.
Global Inorganic Antimicrobial Coatings Market Competitive Landscape
Concentration sits with diversified chemical conglomerates possessing captive biocide synthesis and integrated toxicology testing capabilities. The competitive landscape bifurcates between validated suppliers with multi-year regulatory dossiers and commodity producers lacking certification depth. Three archetypes dominate: integrated chemical majors with backward control over silver-nanoparticle production, specialized coating formulators with FDA 510(k) clearance expertise, and regional distributors serving HVAC contractor channels. Dominant competitive moves include strategic partnerships with medical device OEMs for co-development of MDR-compliant formulations and portfolio diversification into photocatalytic titanium dioxide for non-medical applications.
Within the integrated chemical tier, BASF SE anchors European supply through its Ludwigshafen-based operations, while AkzoNobel N.V. and PPG Industries occupy positions bridging marine coatings heritage with antimicrobial surface treatment diversification. These three exemplify how corrosion-resistant binder technology transfer and plasma-sprayed ceramic expertise create defensible positioning across regulated end-use segments.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| PPG Industries |
| Sherwin-Williams Company |
| BASF SE |
| Axalta Coating Systems |
| Nippon Paint Holdings |
| RPM International Inc. |
| Lonza |
| DuPont |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between German silver-nanoparticle producers and REACH-certified coating formulators lock in raw material access while constraining price visibility for independent competitors. These contracts concentrate procurement leverage among integrated chemical conglomerates, forcing smaller formulators into spot-market exposure for silver-ion feedstocks.
Pricing Analysis
REACH and EMA biocompatibility standards dictate the pricing tier structure across the Global Inorganic Antimicrobial Coatings Market. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared medical-grade formulations from commodity HVAC treatments. Certification grade and volume scale drive price differentiation, with pharmaceutical manufacturers absorbing premium positioning for verified toxicology dossiers. Cost compression in standard-tier copper-oxide formulations is intensifying because humidity-accelerated ion-release specifications are commoditizing. HVAC contractors exhibit the highest price sensitivity, while pharmaceutical manufacturers prioritize certification depth over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate among German medical device clusters, while just-in-time inventory governs North American HVAC contractor procurement. Silver nanoparticle synthesis concentrates in Germany, South Korea, and Japan, with ceramic biocide feedstock anchored in China and the United States. The supply chain draws from silver bullion, copper oxide powder, and titanium dioxide nanoparticles as critical inputs. Single-source vulnerability from German captive production creates structural exposure for independent formulators lacking backward integration. Distribution runs through certified coating formulators for medical channels and regional distributors for climate control infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photocatalytic titanium dioxide formulations present a credible substitution threat to silver-ion dominance in ambient-light applications, compelling incumbents to defend positioning through chemistry portfolio diversification.
For Market Incumbents: Consolidate regulatory dossier depth by accelerating EMA biocompatibility verification for next-generation copper-oxide formulations. Deepen backward integration into silver-nanoparticle synthesis to offset German supply concentration and secure margin control against commodity price volatility. For New Entrants and Emerging Players: Differentiate on plasma-sprayed ceramic expertise for water treatment membrane housings, a segment showing structural underpenetration relative to medical applications. Target Japanese pharmaceutical manufacturing facilities under METI cleanroom standards, leveraging PMDA surface contamination protocols as the go-to-market entry mechanism. For Investors and Strategic Acquirers: Capital is best deployed toward specialized coating formulators with FDA 510(k) clearance expertise and captive toxicology testing capabilities. Over a multi-year horizon, acquisition value accrues to firms bridging medical-grade certification with photocatalytic diversification. Watch ISO 22196 test method revisions as the signal for which biocide-load thresholds will trigger reformulation cycles and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver-Nanoparticle Synthesis | Captive production insulates margin structures from precious metal commodity swings. |
| EMA Biocompatibility Certification Investment | MDR compliance verification secures sole-source positioning in German medical device clusters. |
| Photocatalytic Titanium Dioxide R&D Expansion | UV-LED convergence enables self-sanitizing surfaces for Japanese transit infrastructure. |
| Plasma-Sprayed Ceramic Capacity Buildout | Water treatment membrane housing demand outpaces current specialized coating supply. |
| Long-term Supply Agreement with HVAC OEMs | Multi-year contracts lock in copper-oxide volume for climate control system specifications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with coating formulator R&D directors, hospital procurement managers, and HVAC contractor specification engineers; and secondary validation against ECHA REACH filings, EPA antimicrobial pesticide registrations, and SEC 10-K disclosures from diversified chemical producers. Bottom-up triangulation across application-method volumes and top-down reconciliation against end-use expenditure patterns anchored value estimates.
Across the analysis window, the forecasting framework modeled biocide chemistry, application technology, end-use segment, and regional regulatory cluster dimensions. CAGRs were derived from regression analysis of historical adoption curves and projected compliance-driven replacement cycles. Silver price volatility assumptions and ISO 22196 test method revision timelines served as industry-specific sensitivity inputs.
Material uncertainties — ECHA hazard classification updates, EPA registration pathway delays, and antimicrobial resistance screening standard changes — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory stability and raw material supply continuity. Revision becomes warranted when titanium dioxide photocatalytic efficacy claims cross independent validation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Fillers and Coating Market
Coatings
Waterproof Coating Market
Coatings
Mexico Industrial Wood Coatings Market
Coatings
United States Automotive OEM Coatings Market
Coatings
Cool Roof Coatings Market
Coatings
United States Floor Coatings Market
Coatings
Anti-Microbial Powder Coatings Market
Coatings
Water-Based Alkyd Coatings Market
Coatings
Global Abrasion Resistant Coatings Market
Coatings
Sol-Gel Coatings Market
Coatings
Anti-Graffiti Coatings Market
Coatings
Asia-Pacific Superhydrophobic Coating Market
Coatings
Bio-Based Coatings Market
Coatings
Global Coil Coatings Market
Coatings
FBE Coatings Market
Coatings
Cladding Coatings Market