
 Pallets Market | 2026-2036
Pallets Market Size, Share, and Industry Trends Forecast 2026-2036
Pallets Market Intelligence
The capital-intensity divergence between pallet pooling networks and standalone manufacturers is rotating competitive dynamics across the supply chain. CHEP leverages its closed-loop rental infrastructure across multiple continents. Cabka Group GmbH sustains leadership in recycled plastic pallet technology through dedicated R&D facilities. PalletOne anchors North American production scale with integrated sawmill and recycling operations.
Pallets are portable horizontal platforms constructed from wood, plastic, metal, or composite materials, designed with standardized dimensions—typically 1200 mm × 800 mm or 48 in × 40 in—to enable mechanical handling by forklifts, pallet jacks, and conveyor systems. Their primary function is unitizing goods for storage, transport, and distribution while protecting product integrity through load-bearing structural design. Wood pallets occupy the largest volume share due to low material cost and repairability, though plastic pallets represent the fastest-expanding material category as hygiene-sensitive industries mandate washable, non-porous surfaces. Block pallets lead in international trade compatibility because four-way entry reduces handling time in containerized shipping. Heavy-duty load capacity segments capture disproportionate margin pools from automotive and chemical end users requiring engineered durability.
The EPA regulates wood treatment chemicals under the Toxic Substances Control Act, while the USDA enforces phytosanitary standards through ISPM-15 heat-treatment requirements for international wood pallet movement. The EU's REACH framework restricts hazardous substances in plastic pallet formulations, and the F-Gas Regulation indirectly shapes insulated pallet demand for temperature-controlled logistics. Stakeholders must monitor how evolving extended producer responsibility laws across multiple jurisdictions reshape material recovery obligations and pooling economics.
Market Dynamics
Closed-loop rental economics are compressing ownership models as pooling operators scale reverse logistics networks and capture margin from idle asset monetization.
Growth Catalysts
- E-commerce fulfillment density:Last-mile distribution centers in Germany and China are deploying plastic pallets for automated sortation compatibility and washdown sanitation protocols.
- REACH substance restrictions:The EU's chemical framework is accelerating recycled polymer formulation R&D as virgin resin costs fluctuate and circularity mandates tighten.
- ISPM-15 harmonization:Heat-treatment certification requirements for cross-border wood pallet movement are standardizing quarantine protocols and reducing customs friction at major ports.
Market Restraints
- Lumber input volatility:Softwood price swings in North American sawmill regions compress margin predictability for wooden pallet manufacturers without backward integration into timber assets.
- Pooling network concentration:Four-way entry block pallet supply concentrates among operators with captive repair depots, creating barriers for standalone producers seeking rental market entry.
- Composite material cost floors:Engineered fiber-reinforced platforms require resin and fiber inputs that resist scale economies below threshold production volumes.
Strategic Opportunities
- India manufacturing corridors:The PLI scheme for logistics infrastructure is creating pallet demand clusters around automotive and electronics export zones in Tamil Nadu and Gujarat.
- RFID-embedded tracking convergence:Sensor-equipped plastic pallets are enabling real-time location and condition monitoring for pharmaceutical cold chains.
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are forcing brand owners toward rental pooling models that externalize recovery and recycling obligations.
Industry Challenges
- Repair technician scarcity:Wood pallet refurbishment requires skilled labor for nail extraction and stringer replacement that competing logistics wages are absorbing.
- Multi-jurisdiction certification lag:ISPM-15 heat-treatment stamps must be renewed across bilateral trade agreements, creating documentation bottlenecks for exporters serving multiple destination markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallets Market |
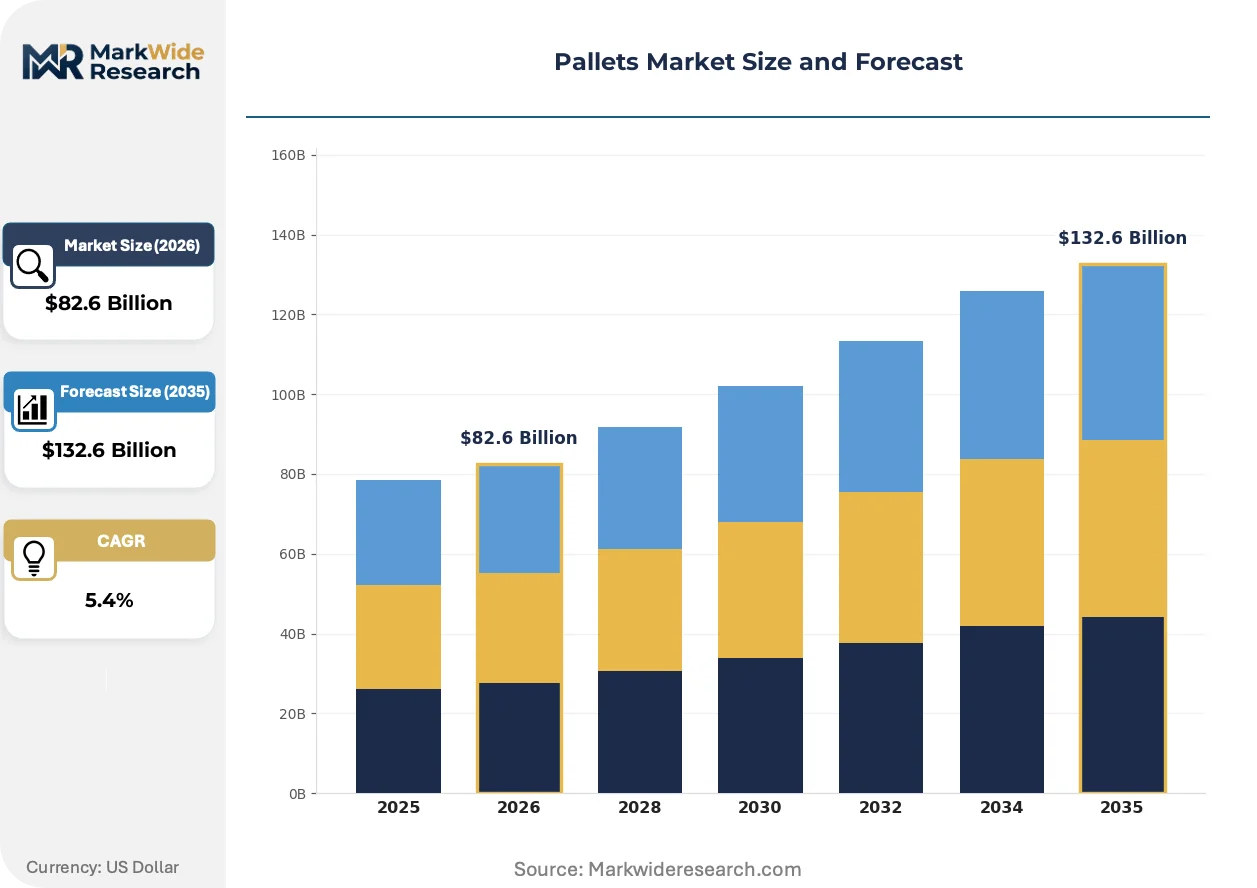
| Market Size in 2026 | $82.6 Billion |
| Market Size in 2035 | $132.6 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Plastic, Metal, Composite, Corrugated Fiberboard Type: Stringer, Block, Reversible, Four-Way, Double-Face, Single-Face Load Capacity: Light Duty, Medium Duty, Heavy Duty, Extra Heavy Duty End User Industry: Manufacturing, Logistics Providers, Agriculture, Food Processing, Construction |
| Companies Covered | PGS Group, PECO Pallet, CHEP, Cabka Group GmbH, Craemer GmbH, PalletOne, ORBIS Corporation, Falkenhahn AG, Loscam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallets Market Strategic Shifts & Innovations
Material science advances and regulatory pressure on circularity are converging to transform pallet economics from disposable commodity toward managed asset service models.
Recycled high-density polyethylene formulations are supplanting virgin plastic in hygiene-critical applications. Pharmaceutical distributors and fresh produce packers are adopting washdown-compatible platforms at accelerated replacement cycles. This material shift is compressing virgin resin demand while expanding closed-loop recovery infrastructure investment.
REACH substance restrictions on hazardous additives are reshaping polymer compounding practices across European manufacturing. Formulators must eliminate legacy flame retardants and plasticizers from pallet grades intended for food contact and healthcare logistics. German and Dutch chemical converters are leading reformulation timelines to maintain CE marking compliance.
Rental pooling contracts are displacing spot purchase arrangements among multinational consumer goods manufacturers. Procurement functions are consolidating pallet spend under multi-year service agreements that bundle supply, retrieval, and sanitation. This behavioral pivot is most pronounced in Benelux distribution networks where CHEP and LPR maintain dense depot coverage.
Pallets Market Segmentation
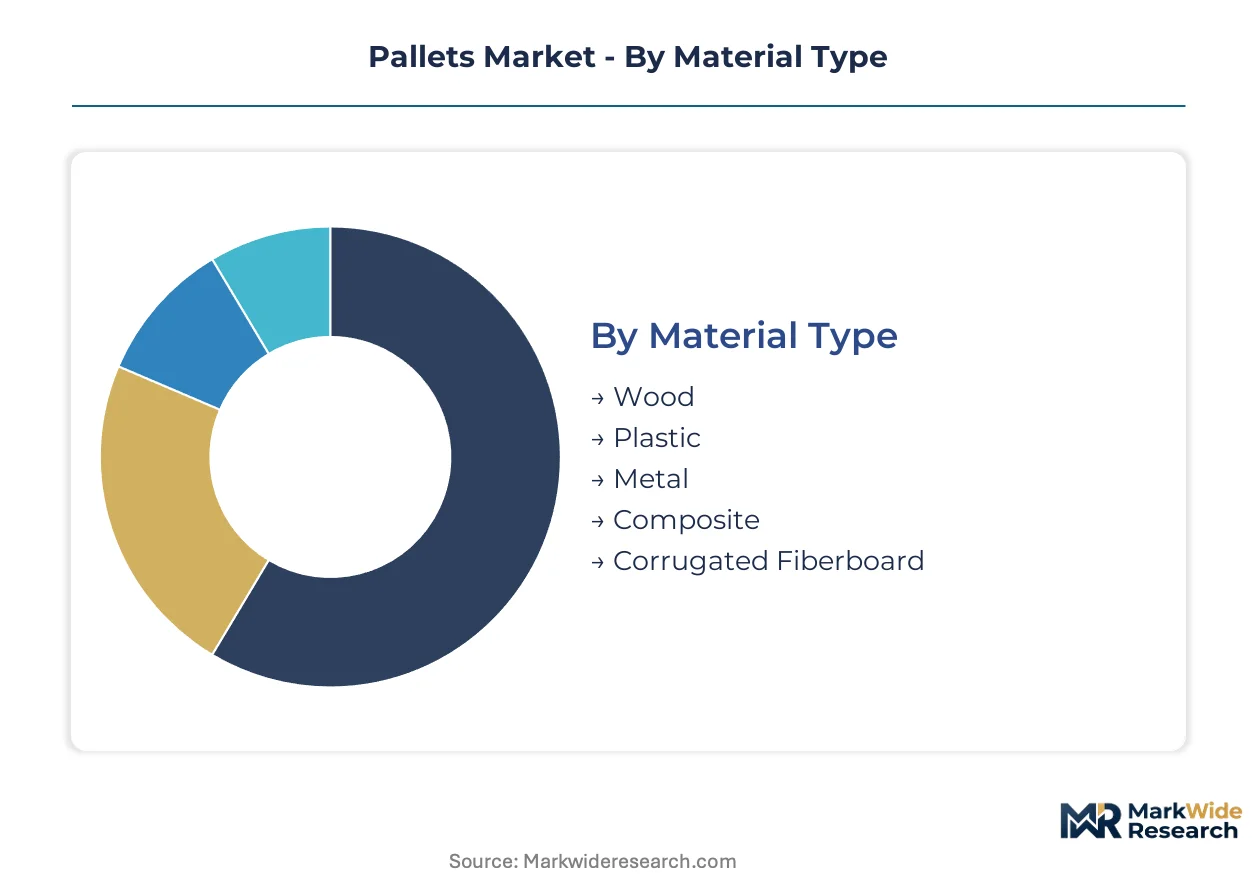
Pallet procurement patterns diverge sharply across material grades and handling specifications. Channel economics favor rental pooling for high-turnover plastic platforms while spot purchasing persists for commodity wood units in fragmented manufacturing bases.
Material Type:
Wood pallets flow through independent distributors and direct mill sales to cost-sensitive bulk buyers. Plastic and metal platforms concentrate in closed-loop rental channels serving hygiene-regulated industries.
- Wood:Softwood and hardwood slats assembled with nails or staples form the dominant installed base. German automotive suppliers and Chinese electronics exporters specify heat-treated grades for ISPM-15 compliance in cross-border movement. Lumber price volatility compresses margin predictability for non-integrated producers.
- Plastic:Injection-molded high-density polyethylene platforms withstand repeated washdown cycles without moisture absorption. Fresh produce packers in the Netherlands and pharmaceutical distributors in India specify these for automated handling systems and sanitation protocols. REACH substance restrictions are accelerating recycled polymer formulation R&D.
- Metal:Steel and aluminum constructions tolerate extreme load cycling in chemical and heavy machinery logistics. Fire safety regulations in German chemical parks drive specification over wood alternatives.
- Composite:Engineered fiber-reinforced platforms blend resin matrices with recycled materials for niche durability applications. Cost floors resist scale economies below threshold production volumes.
- Corrugated Fiberboard:Single-use paper-based platforms serve lightweight export shipments where return logistics are uneconomical. E-commerce fulfillment networks in China deploy these for one-way consumer goods distribution.
Wood dominates installed base. Plastic is where expansion concentrates.
Type:
Structural configuration determines forklift entry geometry and stacking efficiency. Block pallets command rental premiums while stringer designs anchor spot-purchase volume.
- Stringer:Two or three parallel longitudinal boards support the deck from beneath. These occupy the highest production volume in North American sawmill regions due to simple repairability and low material input.
- Block:Nine columnar blocks connect top and bottom decks, enabling four-way entry. International container shipping lanes between Germany and China standardize on these for reduced handling time.
- Reversible:Identical top and bottom deck construction permits double-sided loading. Chemical processors specify these for uniform load distribution in racked storage.
- Four-Way:Notched stringer or block designs allow forklift access from all sides. Automated warehouse systems in Benelux distribution centers require these for omnidirectional retrieval.
- Double-Face:Deck boards cover both top and bottom surfaces for balanced strength. Heavy machinery manufacturers in the United States deploy these for concentrated point loads.
- Single-Face:Deck boards on one side only reduce weight and material cost. Lightweight consumer goods distribution favors these for one-way shipping applications.
Stringer pallets anchor production scale. Block configurations capture rental network premiums.
Load Capacity:
Duty ratings segment margin pools by engineering complexity and end-use criticality. Heavy-duty specifications concentrate in automotive and chemical supply chains where failure costs exceed platform price multiples.
- Light Duty:Rated below 500 kg for consumer goods and retail display applications. E-commerce sortation centers in China deploy these for parcel aggregation where unit loads remain small.
- Medium Duty:500-1500 kg ratings serve general manufacturing and distribution. Food processing plants in India specify these for ingredient storage and internal movement.
- Heavy Duty:1500-3000 kg engineered platforms tolerate concentrated automotive component loads. German OEM supply chains mandate these for engine and transmission shipping.
- Extra Heavy Duty:Exceeding 3000 kg for steel coil, machinery, and bulk chemical transport. Chemical producers in the United States require these for hazardous material containment and stability.
Medium-duty ratings dominate transaction volume. Heavy-duty segments capture disproportionate margin pools.
End User Industry:
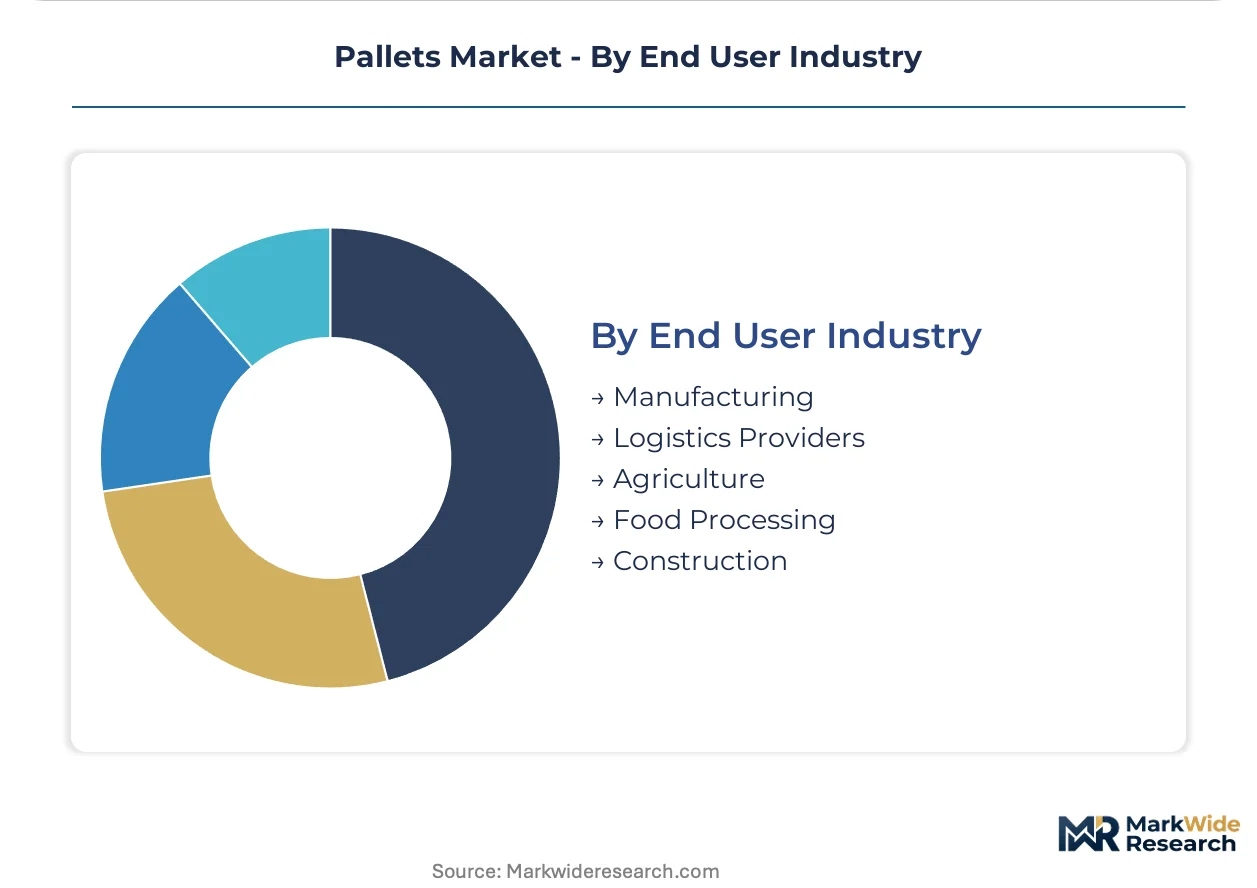
Industry-specific regulations and handling intensity reshape specification requirements. Food contact and pharmaceutical applications drive plastic adoption while construction maintains wood preference for rough handling tolerance.
- Manufacturing:Automotive, electronics, and industrial equipment producers specify grade-mixed pallet fleets. Just-in-time delivery networks in Germany and China require four-way entry and dimensional precision for automated handling.
- Logistics Providers:Third-party warehousing and transportation operators balance asset utilization across heterogeneous customer requirements. Rental pooling contracts with CHEP and LPR consolidate spend for multinational consumer goods manufacturers.
- Agriculture:Fresh produce packers and grain handlers prioritize ventilation and moisture resistance. USDA phytosanitary standards govern wood pallet movement for export shipments.
- Food Processing:Meat, dairy, and beverage facilities mandate washdown-compatible plastic platforms. FDA food contact regulations and HACCP protocols drive specification away from porous wood surfaces.
- Construction:Building materials distributors tolerate rough handling and outdoor exposure. Low unit cost and repairability sustain wood dominance despite load inconsistency.
Manufacturing anchors specification diversity. Food processing is where material upgrade concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and China exhibit low price elasticity for plastic pooling platforms, while North American sawmill regions face acute margin pressure from lumber volatility. This demand-elasticity contrast shapes diverging investment patterns across major pallet-consuming economies.
United States
Food processing and pharmaceutical cold chains drive specification toward washdown-compatible plastic platforms. FDA food contact regulations and USDA phytosanitary standards govern material selection for cross-border shipments. Chicago-Midwest distribution corridors concentrate automated warehouse deployments requiring four-way entry block pallets.
Germany
Automotive OEM supply chains mandate heavy-duty engineered platforms for just-in-time component delivery. REACH substance restrictions from ECHA accelerate recycled polymer formulation timelines for CE-marked products. Bavarian chemical parks specify metal pallets under fire safety protocols that exclude wood alternatives.
China
E-commerce fulfillment density in Yangtze River Delta cities propels plastic pallet adoption for automated sortation systems. GB standards from SAMR and MIIT shape domestic manufacturing specifications. Shenzhen electronics export zones cluster demand for ISPM-15 compliant heat-treated wood platforms.
India
PLI scheme incentives for logistics infrastructure concentrate pallet demand around Tamil Nadu and Gujarat manufacturing corridors. FSSAI food safety regulations push food processors toward washable plastic surfaces. Mumbai-Pune automotive clusters specify medium-duty plastic platforms for component assembly lines.
Netherlands
Fresh produce packers in Rotterdam-Antwerp port hinterlands prioritize ventilation and moisture resistance for perishable exports. EU Packaging and Packaging Waste Regulation extended producer responsibility mandates accelerate rental pooling adoption. Benelux distribution networks maintain dense CHEP and LPR depot coverage for multinational consumer goods manufacturers.
Pallets Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the pallet supply chain. Pooling network operators with captive repair depots and reverse logistics infrastructure dominate rental economics, while sawmill-integrated manufacturers anchor spot-purchase wood volume. Three archetypes define competitive positioning: closed-loop rental specialists, recycled polymer technology developers, and vertically integrated wood producers. M&A activity concentrates repair depot networks, while strategic partnerships embed tracking technology into plastic platform fleets.
Among German-based technology developers, Cabka Group GmbH and Craemer GmbH exemplify the recycled polymer formulation archetype. CHEP occupies a position as the archetypal closed-loop rental operator with multi-continental depot infrastructure. PalletOne anchors North American production scale through in-house sawmill and recycling operations.
| Leading Market Players |
|---|
| PGS Group |
| PECO Pallet |
| CHEP |
| Cabka Group GmbH |
| Craemer GmbH |
| PalletOne |
| ORBIS Corporation |
| Falkenhahn AG |
| Loscam |
| Others |
Cost & Logistics Intelligence
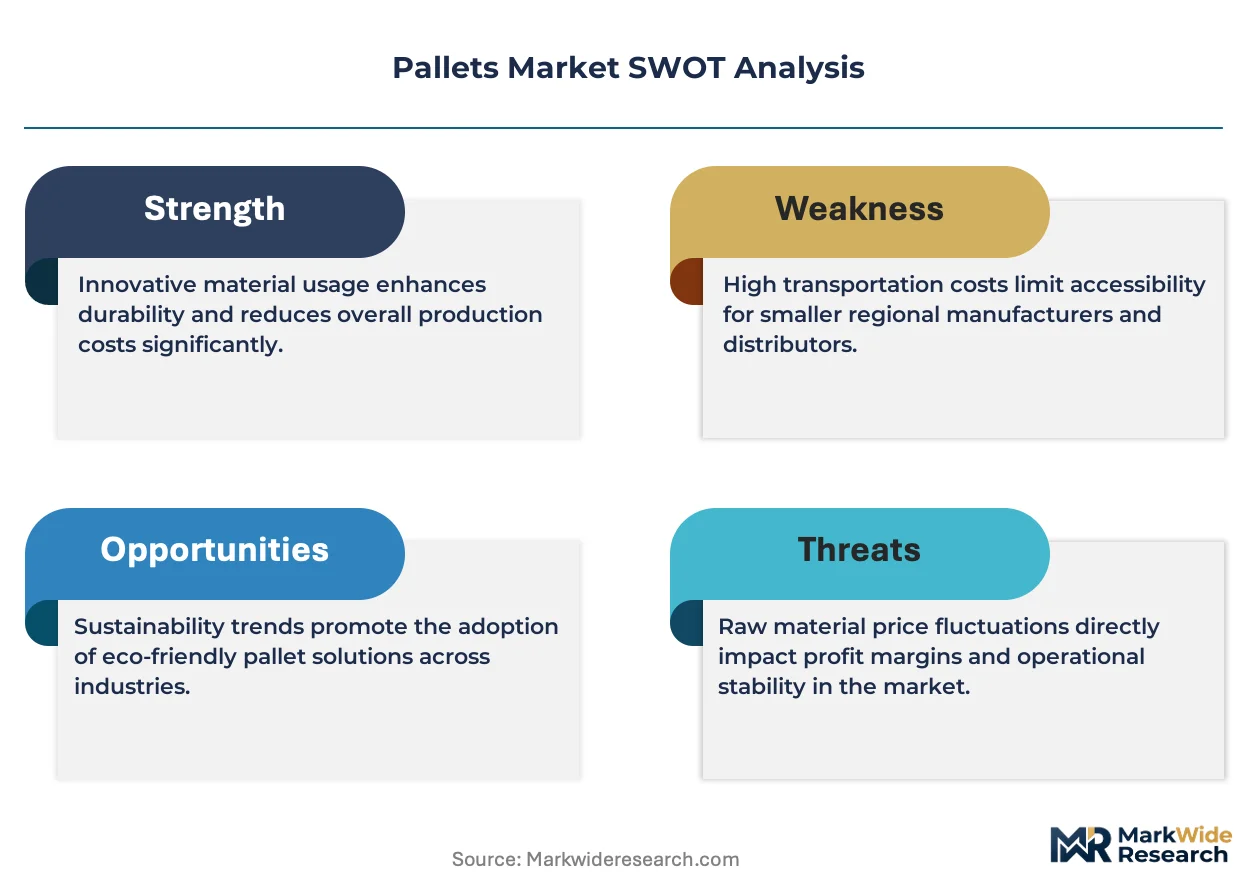
Capacity utilization gaps between pooling networks and standalone manufacturers compress price floors for commodity wood platforms while elevating rental premiums for tracked plastic assets. This divergence concentrates margin capture among operators with reverse logistics density across Germany, China, and the United States.
Pricing Analysis
After-sales service revenue from sanitation, repair, and retrieval contracts drives lifetime value for plastic pallet pooling operators. Three-tier pricing structure across premium rental, standard lease, and economy spot-purchase levels segments buyer segments by handling intensity and compliance requirements. Price differentiation hinges on ISPM-15 certification grade and embedded RFID tracking capability. Cost compression in economy wood tiers intensifies because softwood price volatility erodes non-integrated producer margins. Small-scale manufacturers exhibit highest price sensitivity; pharmaceutical cold chain operators demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Inbound logistics costs on Asia-Europe container lanes fluctuate with port congestion at Rotterdam and Hamburg, altering landed cost structures for Chinese-manufactured plastic platforms. Geographic supply concentration centers on China for injection-molded resin pallets, Germany for engineered composite formulations, and the United States for softwood stringer production. Raw material dependencies encompass high-density polyethylene resin, southern yellow pine lumber, and glass fiber reinforcement. Single-source vulnerability in specialized polymer compounding creates chokepoints for REACH-compliant formulations. Distribution runs through captive depot networks for rental operators and independent distributors for spot-purchase wood volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect toward interoperability standards as RFID-embedded pallets enable cross-operator tracking and pharmaceutical cold chain verification.
For Market Incumbents: Consolidate repair depot networks in Benelux and Yangtze River Delta corridors to defend pooling margins against emerging regional operators. Acquire recycled polymer formulation capabilities to offset virgin resin cost volatility and meet REACH substance restrictions. Backward integration into sawmill assets anchors wood platform cost structures against lumber input swings. For New Entrants and Emerging Players: ISPM-15 certification fast-track programs unlock white-space opportunity in Indian electronics export corridors and Vietnamese manufacturing zones. Target medium-duty plastic specifications for food processing applications where FSSAI regulations displace wood surfaces. Pursue sensor-embedded platform partnerships with pharmaceutical 3PLs as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors recycled polymer specialists with REACH-compliant formulation libraries and captive R&D facilities. Long-term viability rests on circularity infrastructure ownership rather than commodity manufacturing scale. Acquisition targets should demonstrate depot network density or proprietary material science. Monitor EU Packaging and Packaging Waste Regulation enforcement timelines as pooling adoption inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Depot Network Expansion | Reverse logistics density in Germany and China captures idle asset monetization pools. |
| Recycled Polymer R&D Investment | REACH-compliant formulations from Cabka Group GmbH reduce virgin resin exposure. |
| RFID Tracking Integration | Sensor-equipped platforms from ORBIS Corporation enable pharmaceutical cold chain verification. |
| Sawmill Backward Integration | PalletOne's captive timber supply insulates margin from softwood price volatility. |
| Rental Pooling Contract Consolidation | CHEP multi-year service agreements bundle sanitation and retrieval for Benelux consumer goods manufacturers. |
Research Approach
Desk research of trade flow databases, customs records, and regulatory filings preceded structured interviews with pallet pooling operations directors, polymer formulation chemists, sawmill procurement managers, and pharmaceutical logistics executives. Secondary validation drew from EPA treatment chemical registrations, ECHA REACH substance databases, USDA phytosanitary inspection records, and SEC filings from publicly traded logistics operators. Bottom-up volume estimates triangulated against top-down industry association data.
Variance decomposition across material type, load capacity tier, and end-use industry segments shaped the analytical framework over the projection horizon. Modeled dimensions encompassed wood versus plastic versus metal material splits, stringer versus block structural configurations, and regional regulatory cluster adoption patterns. CAGRs derived from logistic curve fitting to historical replacement cycle data and pooling penetration rates. Industry-specific inputs included ISPM-15 heat-treatment capacity expansion timelines and EU extended producer responsibility implementation schedules.
Decision-makers should treat outputs as directional under assumptions of continued e-commerce fulfillment density growth and REACH substance restriction enforcement; material deviation would warrant model refresh. Specific risks that could revise forecasts encompass lumber price spike persistence, pooling network consolidation acceleration, and alternative unitization technology displacement. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
North America Lumber Pallet Market
Pallets Packaging
Pallet Displays Market
Pallets Packaging
Foldable Plastic Pallet Boxes Market
Pallets Packaging
Corrugated Pallet Wrap Market
Pallets Packaging
Japan Pallets Market
Pallets Packaging
Indonesia Pallets Market
Pallets Packaging
Presswood Pallets Market
Pallets Packaging
Pallet Shippers Market
Pallets Packaging
Pallet Boxes Market
Pallets Packaging
Single Use Pallet Market
Pallets Packaging
Disposable Plastic Pallet Market
Pallets Packaging
PUR Shippers Market
Pallets Packaging
Wire Cage Pallet Collar Market
Pallets Packaging
Global Crates and Pallets Packaging Market
Pallets Packaging
Wooden Pallet Collars Market
Pallets Packaging
Germany Pallets Market